
 Refrigeration Gauge Market | 2026-2036
Refrigeration Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigeration Gauge Market Analytics
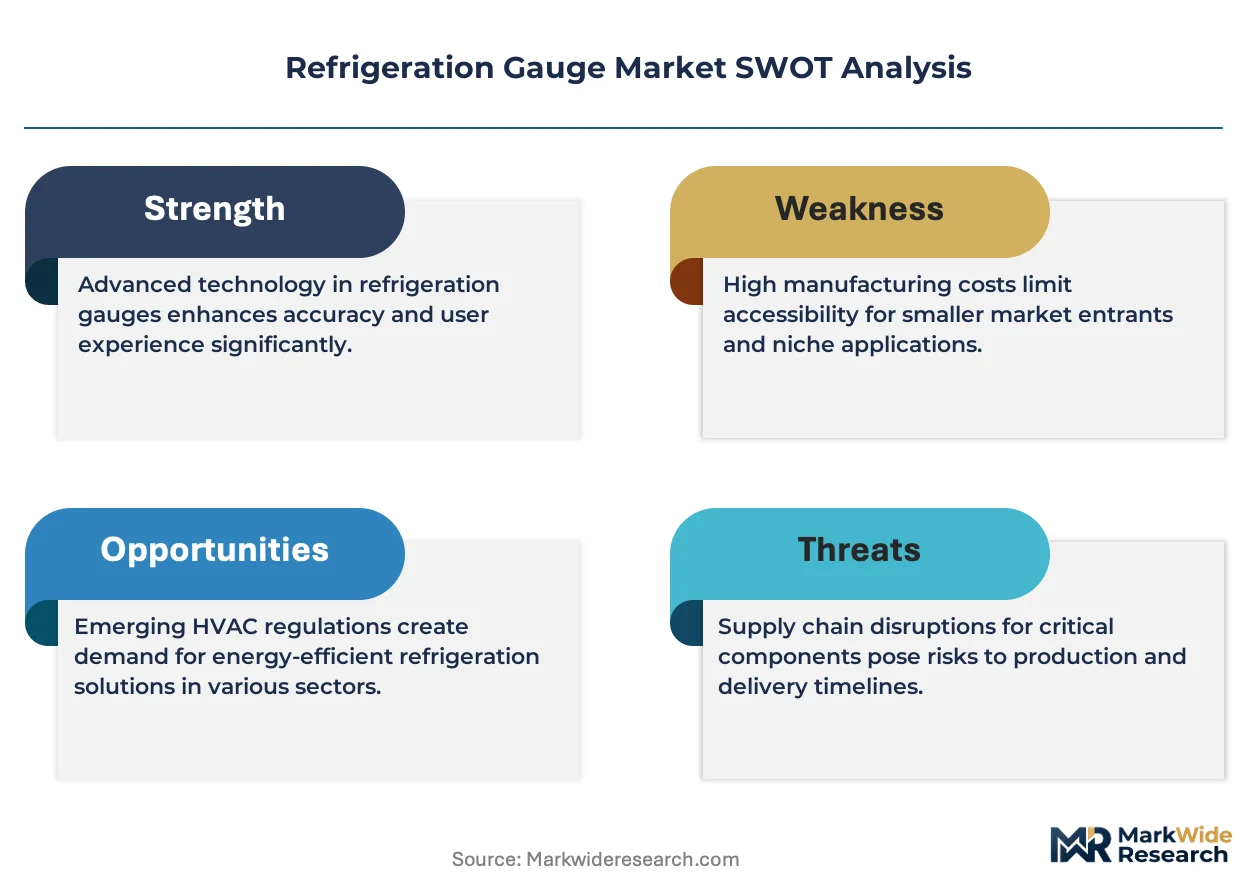
F-Gas Regulation is consolidating the cost-of-entry calculus for gauge manufacturers serving European refrigeration service channels. WIKA Group leverages its calibration infrastructure to sustain premium positioning across industrial cold storage installations. Parker Hannifin Corp anchors its presence through distribution depth in North American commercial HVAC channels. Emerson Electric differentiates via integrated system offerings that bundle gauges with compressor controls.
Refrigeration gauges are pressure measurement instruments, typically constructed with brass or stainless steel bourdon tubes and rated for refrigerant-specific pressure ranges from vacuum to 800 psi, designed to monitor system charge status and detect leaks in vapor-compression cycles. Digital gauges now lead product type dynamics as technicians prioritize data-logging and Bluetooth diagnostics over analog dial readability. Smart technology applications are expanding fastest where predictive maintenance contracts require remote pressure monitoring, though mechanical technology still occupies the price-sensitive residential service tier.
EPA Section 608 certification requirements in the United States mandate leak detection protocols that directly sustain gauge replacement demand, while REACH compliance in Europe restricts mercury-containing instruments and accelerates digital migration. India's BIS certification for pressure instruments creates a formal barrier for unbranded imports entering the commercial services segment. Stakeholders must weigh refrigerant transition timelines against gauge compatibility portfolios when allocating R&D budgets.
Market Dynamics
F-Gas Regulation phase-downs across Europe are compressing gauge replacement cycles as cold chain operators retrofit systems for lower-GWP refrigerants, forcing simultaneous instrumentation upgrades to maintain measurement accuracy across incompatible pressure ranges.
Growth Catalysts
- Cold chain logistics expansion:Pharmaceutical distribution networks in Germany and the Netherlands require continuous monitoring infrastructure, driving gauge turnover in industrial freezer installations.
- REACH compliance deadlines:The European Chemicals Agency's mercury restrictions accelerate digital gauge adoption as service technicians phase out analog dial instruments containing restricted substances.
- Bluetooth-enabled diagnostics:Wireless pressure logging allows predictive maintenance contracts to replace reactive service calls, creating pull from facility management providers.
Market Restraints
- Brass alloy cost volatility:Bourdon tube manufacturing depends on copper and zinc price stability, squeezing margin for mechanical gauge producers serving price-sensitive residential tiers.
- Calibration infrastructure concentration:Germany hosts the majority of accredited pressure instrument laboratories in Europe, creating geographic dependency for certification-dependent buyers.
- Refrigerant fragmentation:R-32, R-454B, and R-290 operate at incompatible pressure ranges, forcing gauge manufacturers to proliferate SKU counts without volume concentration.
Strategic Opportunities
- India commercial services segment:BIS certification requirements for pressure instruments create a formal barrier against unbranded imports, opening space for compliant suppliers.
- Remote monitoring integration:Convergence of IoT pressure sensors with building management systems enables subscription-based gauge-as-a-service models for multi-site retail operators.
- EPA Section 608 enforcement:Leak detection protocol mandates in the United States sustain replacement demand as certified technicians must maintain calibrated instrumentation.
Industry Challenges
- Technician certification bottlenecks:EPA Section 608 and F-Gas certification requirements create skilled labor scarcity, slowing installation velocity for digital gauge systems requiring training.
- Legacy system integration:Analog gauge replacement in existing refrigeration circuits demands compatibility verification with aged Schrader valve configurations and copper line sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigeration Gauge Market |
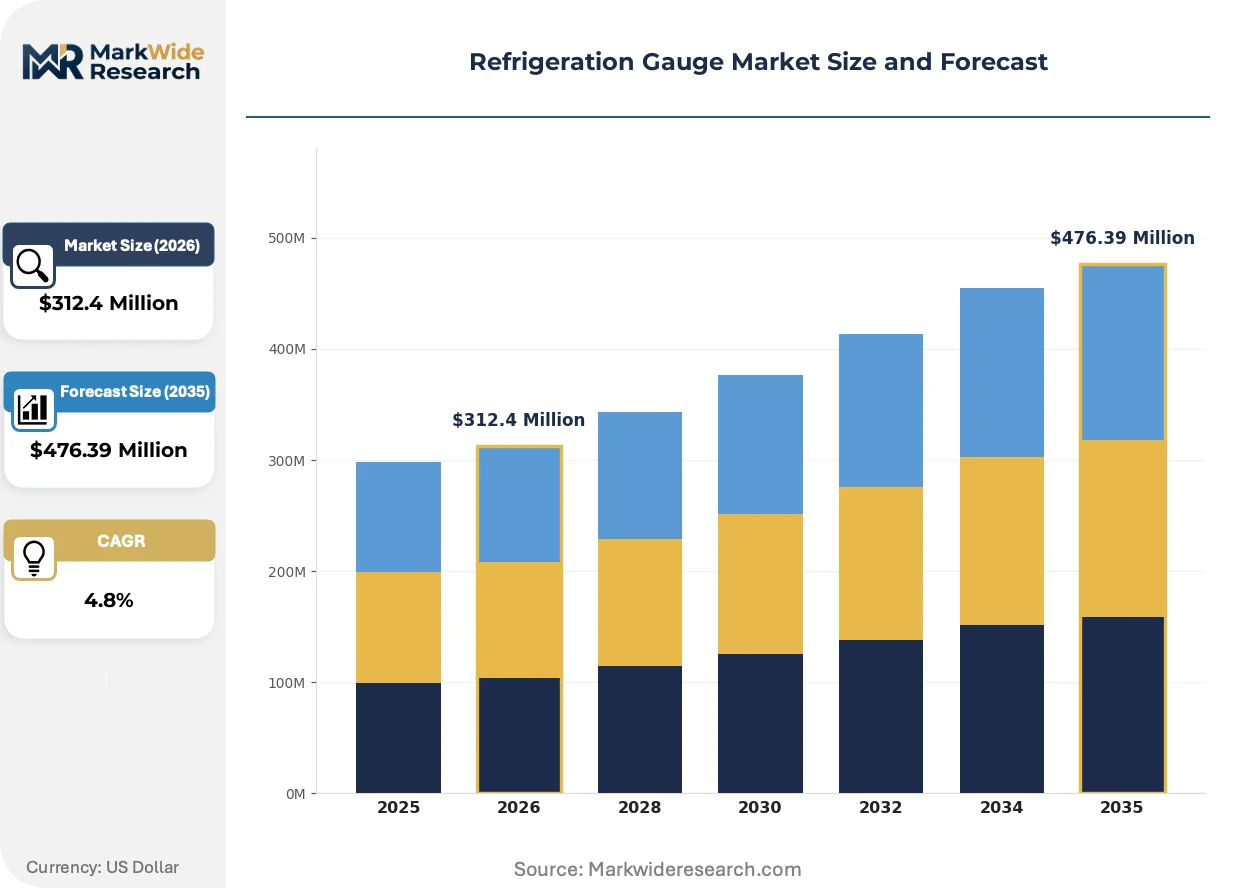
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Gauges, Analog Gauges, Manifold Gauges, Vacuum Gauges End User: Commercial Services, Residential Services, Automotive Services, Industrial Applications Application: HVAC Systems, Refrigeration Units, Automotive Air Conditioning, Cryogenic Equipment Technology: Wireless Technology, Standard Technology, Smart Technology, Mechanical Technology |
| Companies Covered | WIKA Group, Omega Engineering, Parker Hannifin Corp, WINTERS INSTRUMENTS, Emerson Electric, Honeywell International, Testo AG, Fluke Corporation, Fieldpiece Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigeration Gauge Market Evolving Landscape
Digital pressure instrumentation is compressing the mechanical gauge installed base as technicians prioritize data-logging capabilities over dial readability, while refrigerant transition timelines force simultaneous compatibility upgrades across service fleets.
Digital manifold gauge sets with integrated vacuum measurement and refrigerant-specific pressure-temperature charts are overtaking analog counterparts in commercial HVAC service channels. Large facility management contractors in Germany and the United States are standardizing on Bluetooth-equipped models to enable remote diagnostic access. This technology compression is collapsing the premium tier for mechanical instrumentation while expanding software subscription revenue streams.
REACH Annex XVII restrictions on mercury-containing instruments are accelerating digital migration across European service fleets. The regulation forces wholesale replacement of analog dial thermometers and pressure gauges in commercial refrigeration applications. Industrial cold storage operators in Germany face the tightest compliance deadlines, driving above-average instrumentation turnover compared to residential service markets.
Service contract unbundling is fragmenting gauge procurement authority away from OEM system sales. Independent refrigeration contractors now specify instrumentation separately from compressor packages, creating direct manufacturer relationships. This purchasing pattern shift is most visible in North American commercial HVAC channels where distributor loyalty programs face pressure from direct digital sales platforms.
Refrigeration Gauge Market Segmentation
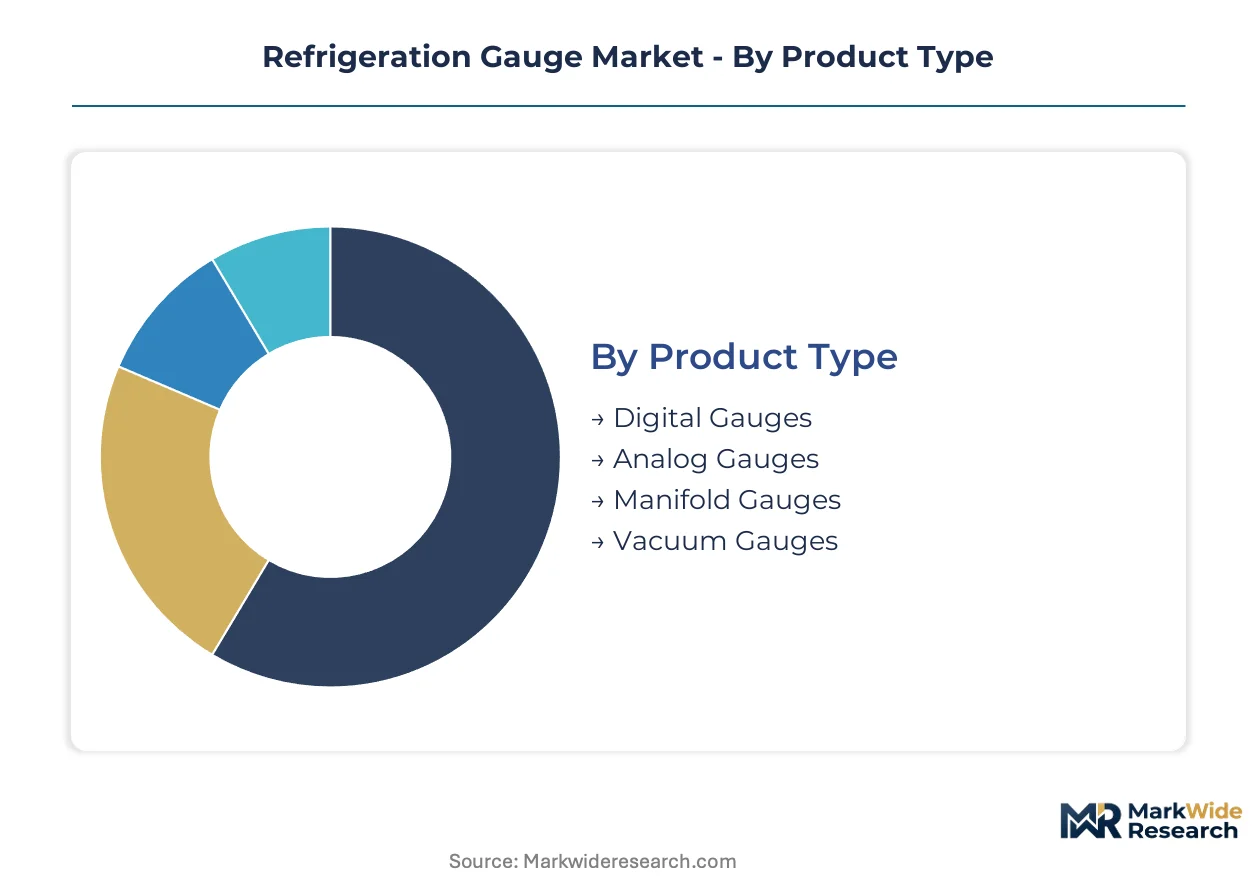
Refrigeration gauge procurement patterns diver sharply between standalone service tools and embedded system instrumentation. Understanding where each segment sits on this integration spectrum reveals which manufacturers control direct customer relationships versus OEM-dependent revenue streams.
Product Type:
Digital gauges dominate standalone technician toolkits where Bluetooth data logging justifies premium pricing, while analog and manifold configurations persist as embedded components within OEM system packages.
- Digital Gauges:Pressure transducers with LCD displays and onboard memory for refrigerant-specific PT charts. Demand clusters in Germany where F-Gas compliance audits require documented calibration trails for industrial cold storage contracts.
- Analog Gauges:Bourdon tube instruments with dial faces, typically brass-cased for cost containment. Residential service channels in the United States sustain volumes through EPA Section 608 certification requirements that mandate leak detection instrumentation.
- Manifold Gauges:Dual-valve assemblies combining high and low side measurement in portable sets.
- Vacuum Gauges:Micron-range sensors for dehydration verification during system commissioning.
Digital gauges lead volumes today; manifold configurations are gaining share fastest through HVAC service fleet standardization.
End User:
Commercial service contractors specify instrumentation independently from system purchases, while industrial buyers bundle gauges into capital equipment procurement cycles with longer replacement horizons.
- Commercial Services:Independent refrigeration contractors performing maintenance and retrofit work across multi-site retail and foodservice accounts. India's BIS certification requirements are reshaping procurement toward documented traceability as unbranded imports face formal exclusion.
- Industrial Applications:Cold storage operators and pharmaceutical distribution facilities requiring continuous monitoring infrastructure. German pharmaceutical logistics networks drive above-average gauge turnover through compliance-driven replacement cycles.
- Residential Services:Single-technician operations serving homeowner HVAC systems.
- Automotive Services:Vehicle air conditioning specialists handling R-1234yf and R-134a transitions.
Commercial services anchor current demand; industrial applications are expanding most quickly through cold chain infrastructure investment.
Application:
Application segmentation tracks refrigerant pressure regime compatibility, with HVAC and refrigeration units operating at distinct ranges that force gauge specialization.
- HVAC Systems:Split-system and packaged unit servicing across commercial and residential buildings. REACH Annex XVII mercury restrictions are accelerating digital migration as service technicians phase out analog dial instruments containing restricted substances.
- Refrigeration Units:Commercial freezer and cooler installations spanning food retail and pharmaceutical storage. Bluetooth-enabled diagnostics allow predictive maintenance contracts to replace reactive service calls, pulling demand from facility management providers.
- Automotive Air Conditioning:Mobile A/C system servicing with refrigerant recovery requirements.
- Cryogenic Equipment:Ultra-low temperature systems requiring specialized pressure measurement protocols.
Refrigeration units dominate installed base; HVAC systems show the steepest expansion trajectory through building stock electrification.
Technology:
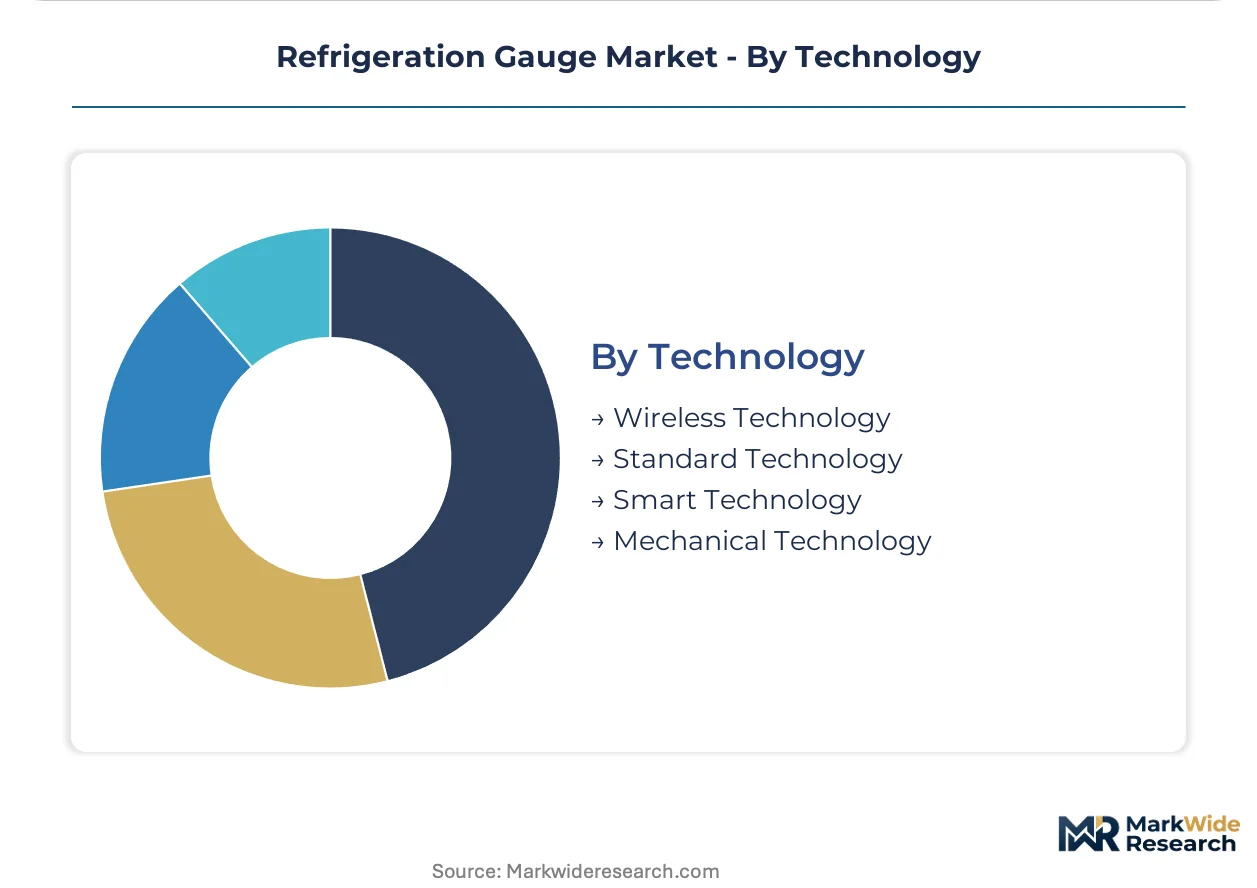
Technology tiers separate connected instrumentation with remote monitoring capability from purely mechanical measurement without electronic augmentation.
- Smart Technology:IoT-integrated sensors with cloud connectivity and predictive analytics capability. Large facility management contractors in Germany and the United States are standardizing on these models to enable remote diagnostic access.
- Wireless Technology:Bluetooth-equipped gauges enabling smartphone-based data logging without full cloud integration. This tier is collapsing the premium positioning of mechanical instrumentation while expanding software subscription revenue streams.
- Standard Technology:Electronic gauges with digital displays but no connectivity features.
- Mechanical Technology:Purely analog bourdon tube instruments without electronic components.
Mechanical technology retains the largest installed base; smart technology is climbing the fastest through building management system convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified technician concentrations in Germany and the United States anchor instrumentation demand as regulatory enforcement tightens calibration requirements across commercial refrigeration service channels.
United States
EPA Section 608 enforcement sustains gauge replacement cycles as certified technicians must maintain calibrated leak detection instrumentation. The agency's refrigerant management protocols directly mandate pressure measurement accuracy in commercial HVAC service calls. Texas and Florida host the densest concentrations of independent refrigeration contractors upgrading to Bluetooth-enabled diagnostic sets.
Germany
F-Gas Regulation phase-downs compress replacement timelines as cold chain operators retrofit systems for lower-GWP refrigerants. ECHA compliance deadlines force wholesale digital migration across industrial cold storage installations. Bavaria's pharmaceutical logistics corridors drive above-average instrumentation turnover through audit-driven procurement cycles.
India
BIS certification requirements for pressure instruments reshape commercial services procurement toward documented traceability as unbranded imports face formal exclusion. The Bureau of Indian Standards mandates calibration infrastructure that compliant suppliers must maintain. Maharashtra and Gujarat concentrate cold storage expansion projects requiring continuous monitoring infrastructure.
China
Domestic cold chain infrastructure investment accelerates gauge demand as pharmaceutical distribution networks expand temperature-controlled capacity. NMPA oversight of medical product storage conditions elevates instrumentation specifications in licensed facilities. Yangtze River Delta logistics hubs standardize on digital pressure monitoring for compliance documentation.
Netherlands
Pharmaceutical distribution networks require continuous monitoring infrastructure that sustains above-average gauge turnover in industrial freezer installations. REACH Annex XVII mercury restrictions accelerate service fleet digitalization as technicians phase out analog dial instruments. Rotterdam's port-centric cold storage cluster enforces stringent calibration protocols for cross-border pharmaceutical transit.
Refrigeration Gauge Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered instrumentation markets. The vendor base spans multinational industrial conglomerates with calibration infrastructure investments and regional specialists serving price-sensitive service tiers. Three archetypes dominate: diversified measurement technology groups, HVAC-focused system integrators, and regional gauge fabricators. Competitive moves concentrate on strategic partnerships for distribution depth and portfolio diversification across refrigerant compatibility ranges.
Among diversified measurement technology groups, WIKA Group and Emerson Electric exemplify archetypes leveraging calibration infrastructure and system integration capabilities respectively. Parker Hannifin Corp anchors the industrial distribution-focused tier. These three occupy positions that span premium industrial installations through commercial service channels, with each representing distinct strategic postures around technical service depth versus geographic coverage breadth.
| Leading Market Players |
|---|
| WIKA Group |
| Omega Engineering |
| Parker Hannifin Corp |
| WINTERS INSTRUMENTS |
| Emerson Electric |
| Honeywell International |
| Testo AG |
| Fluke Corporation |
| Fieldpiece Instruments |
| Others |
Value Network & Pricing Analysis
REACH Annex XVII mercury restrictions gate qualified supply for European refrigeration gauge manufacturers while simultaneously segmenting premium-tier pricing access for digital instrumentation with documented calibration trails. Cold chain operators in Germany and the Netherlands face compliance-driven procurement cycles that compress replacement timelines and sustain above-average price realization for certified suppliers.
Pricing Analysis
The bundled-vs-unbundled service split separates OEM system-integrated gauge pricing from independent contractor procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and Bluetooth connectivity features. Price differentiation stems from ECHA calibration documentation and refrigerant compatibility breadth. Cost compression in mechanical brass-cased tiers is intensifying because copper and zinc alloy volatility squeezes margin for residential service channels. Residential HVAC technicians in the United States exhibit highest price sensitivity, while German pharmaceutical logistics operators show lowest sensitivity due to audit-driven compliance requirements.
Supply Chain Analysis
Freight cost escalation from Asian component hubs to European calibration centers compresses margin for gauge assemblers without regional manufacturing presence. Bourdon tube fabrication concentrates in Germany, China, and India, with brass alloy sourcing tethered to copper mining corridors in Chile and Peru. Raw material dependencies span copper-zinc alloys, stainless steel for high-pressure applications, and electronic components for transducer assemblies. Single-source vulnerability in accredited pressure instrument laboratories creates geographic concentration risk for certification-dependent buyers. Distribution runs through HVAC wholesale distributors in North America and direct manufacturer relationships with facility management contractors in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Refrigeration Gauge Market functions as a stable compounder where regulatory compliance mandates across multiple geographies generate steady replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Anchor calibration infrastructure investments in Germany to defend premium positioning against emerging digital specialists. Deepen backward integration into brass alloy sourcing to offset commodity volatility squeezing mechanical gauge margins. Expand refrigerant compatibility portfolios for R-32, R-454B, and R-290 pressure ranges to capture retrofit cycles accelerating under F-Gas Regulation phase-downs.
For New Entrants and Emerging Players: Capture India's commercial services segment where BIS certification requirements exclude unbranded imports and create formal procurement barriers. Target Maharashtra and Gujarat cold storage expansion projects requiring continuous monitoring infrastructure with documented traceability. Pursue direct digital sales platforms to bypass entrenched distributor loyalty programs in North American HVAC channels.
For Investors and Strategic Acquirers: Roll-up economics work for regional gauge fabricators with captive calibration capabilities because technician certification bottlenecks create sticky customer relationships and recurring revenue streams. Focus acquisition screening on mid-scale specialists with EPA Section 608 or F-Gas certification infrastructure. Watch Bluetooth-enabled diagnostic adoption rates in German facility management contracts as the inflection signal for subscription revenue scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Expansion | ECHA-accredited laboratories in Germany capture audit-driven procurement from pharmaceutical cold chain operators. |
| Refrigerant Compatibility Portfolio Diversification | SKU proliferation for R-290 and R-454B pressure ranges secures retrofit cycle participation under F-Gas Regulation timelines. |
| Direct Digital Sales Platform Launch | Bypassing HVAC wholesale distributors captures margin from independent contractors standardizing on Bluetooth-equipped sets. |
| Backward Integration into Alloy Sourcing | Captive brass supply hedges copper-zinc price volatility squeezing mechanical gauge producers serving residential tiers. |
| IoT Sensor Cloud Integration | Building management system convergence enables gauge-as-a-service subscription models for multi-site retail operators. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with refrigeration service technicians, HVAC distributor procurement managers, cold storage facility engineers, and calibration laboratory directors combined with secondary validation from EPA refrigerant management filings, ECHA restriction substance databases, BIS certification registries, and customs trade data for pressure instrument imports. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Input-output matrices map refrigerant transition timelines, technician certification concentrations, and cold chain infrastructure investment flows across the projection horizon. Segmentation dimensions modeled include product type tier, end-use procurement authority, application pressure regime, and technology connectivity level. CAGRs derive from installation base turnover rates and replacement cycle compression under regulatory compliance deadlines. Forecast inputs incorporate F-Gas Regulation phase-down schedules and REACH Annex XVII enforcement timelines.
Refrigerant transition delays, alloy price spikes, and technician certification bottlenecks are the dominant revision risks that could compress or extend modeled replacement cycles. Forecasts reflect assumptions about regulatory enforcement consistency and calibration infrastructure expansion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Acoustic Respiration Sensors Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
Global Smartphone Sensors Market
Sensors and Controls
Sensor Screwdrivers Market
Sensors and Controls
Smart Flow Meter Market
Sensors and Controls
MEMS Accelerometer and Gyroscope Market
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
Solid Flow Rate Valve Control Market
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
Tip Location Devices Market
Sensors and Controls
Timing Device Market
Sensors and Controls
Biomedical Pressure Sensors Market