
 Europe Nano Sensors Market | 2026-2036
Europe Nano Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nano Sensors Market Foresight
Industrial automation buyers are gaining share as healthcare diagnostics demand is bifurcating between centralized hospital systems and decentralized point-of-care networks. Bosch Sensortec leverages its MEMS manufacturing depth to anchor supply relationships with German automotive OEMs. STMicroelectronics sustains R&D intensity across nanostructured material platforms for environmental monitoring applications. Infineon Technologies AG dominates industrial-grade physical sensor modules through captive fab capacity in Austria and Germany.
Nano sensors are transduction devices engineered at sub-micron scale, typically incorporating nanostructured materials such as metal oxide semiconductors or carbon nanotubes to achieve detection thresholds in parts-per-billion for chemical, physical, or biological analytes. Their primary commercial purpose is enabling real-time, minimally invasive monitoring in environments where conventional sensors lack resolution or response speed. Chemical sensors lead product-type revenue pools due to gas-detection mandates in industrial safety, while optical sensors represent the fastest-expanding category driven by photonic integration in healthcare diagnostics. Carbon nanotube technology commands premium positioning in aerospace end-user applications where weight reduction intersects with electromagnetic shielding requirements.
REACH governs nanomaterial registration and hazard classification across EU member states, compelling reformulation of sensor substrates to eliminate restricted substances. The EU AI Act and CE marking under MDR shape product-access pathways for diagnostic nano sensors deployed in clinical settings. ECHA's evolving guidance on nano-specific hazard profiles will determine which material platforms retain market authorization through the forecast horizon. Stakeholders must monitor regulatory divergence between EU harmonized standards and emerging national transpositions in France and Italy.
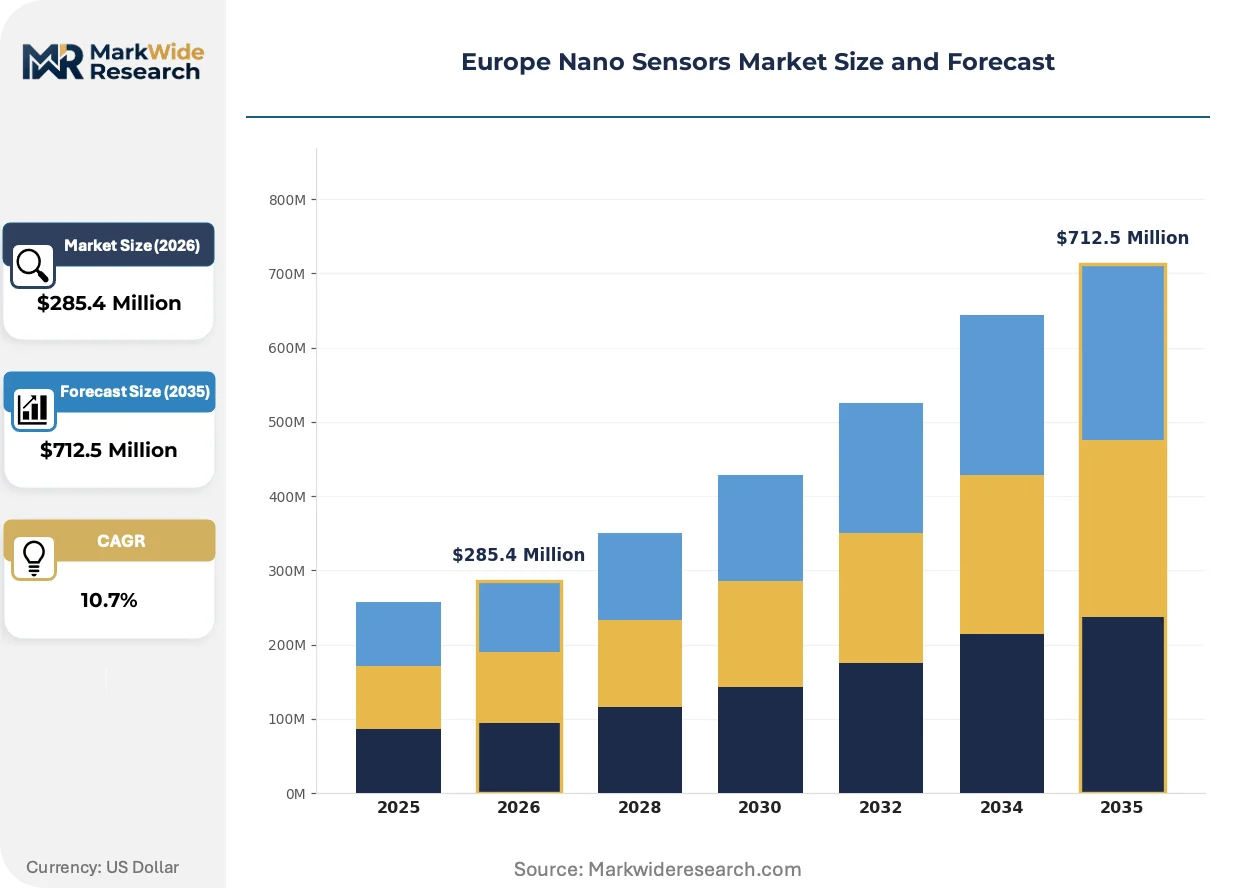
Market Dynamics
REACH compliance deadlines and the EU Green Deal are forcing material substitution across nanostructured substrates, compressing formulation cycles while opening premium positioning for green-certified sensor platforms in German industrial automation clusters.
Growth Catalysts
- EU Green Deal mandates:Carbon-neutrality targets for 2050 accelerate procurement of low-emission nano sensor substrates in automotive and industrial verticals.
- Healthcare diagnostics decentralization:Point-of-care networks in France and Italy drive volume for portable chemical and optical sensor modules.
- Carbon nanotube integration:Weight-critical aerospace applications in Germany and the UK adopt nanotube-based electromagnetic shielding solutions.
Market Restraints
- Precious metal input volatility:Palladium and platinum price swings destabilize cost structures for metal oxide semiconductor formulations.
- Fab capacity concentration:Captive production in Austria and eastern Germany creates supply vulnerability for non-integrated sensor vendors.
- REACH registration friction:ECHA's evolving nano-specific hazard guidance delays market authorization for novel substrate materials.
Strategic Opportunities
- Italian industrial IoT lag:Underpenetrated factory automation in northern Italy offers first-mover positioning for environmental monitoring nano sensors.
- EU AI Act alignment:Diagnostic sensor vendors embedding AI inference at the edge gain accelerated CE marking pathways under MDR harmonization.
- Photonic-biological convergence:Optical nano sensors interfacing with microfluidic cartridges capture emerging demand in decentralized clinical workflows.
Industry Challenges
- Nanofabrication talent scarcity:Cleanroom process engineering expertise concentrates in German and Dutch technical universities, constraining scale-up capacity elsewhere.
- MDR certification timelines:Clinical-grade sensor platforms face 18-24 month conformity assessment delays, compressing revenue recognition windows.
- Legacy system integration:Brownfield industrial sites in France and Spain require protocol bridging hardware, adding deployment complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nano Sensors Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $712.5 Million |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Sensors, Physical Sensors, Biochemical Sensors, Optical Sensors Application: Environmental Monitoring, Healthcare Diagnostics, Industrial Automation, Food Safety Technology: Nanostructured Materials, Quantum Dots, Carbon Nanotubes, Metal Oxide Semiconductors End User: Aerospace, Healthcare, Manufacturing, Automotive |
| Companies Covered | Bosch Sensortec, STMicroelectronics, Siemens AG, Analog Devices Inc, OMRON Corporation, Honeywell International Inc, Texas Instruments Incorporated, Infineon Technologies AG, NanoSENSORS GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nano Sensors Market Shifts & Advancements
Material science advances and regulatory precision are fragmenting the competitive landscape into specialized technology platforms, with photonic integration and green chemistry emerging as the dominant innovation vectors.
Optical nano sensor architectures are bifurcating between silicon photonics for high-volume healthcare diagnostics and plasmonic nanostructures for specialized chemical detection. German automotive OEMs favor silicon-based platforms for emissions monitoring, while French environmental agencies specify plasmonic arrays for water quality surveillance. This split is compressing R&D budgets for mid-tier vendors attempting dual-platform coverage.
REACH substance restrictions are eliminating legacy hexavalent chromium coatings from sensor housings, compelling stainless steel and polymer substitutions. ECHA's 2024 nanoform guidance adds registration burdens for carbon-based substrates. German industrial safety sensor suppliers are responding fastest, with reformulated product lines already securing SCIP database compliance.
Hospital procurement departments now unbundle sensor hardware from service contracts, favoring unit-price purchasing with third-party calibration support. This disintermediation pressures integrated vendors in the UK and Netherlands, where group purchasing organizations consolidate diagnostic equipment tenders. Independent sensor specialists capture share by certifying compatibility across multiple analyzer platforms.
Europe Nano Sensors Market Segmentation
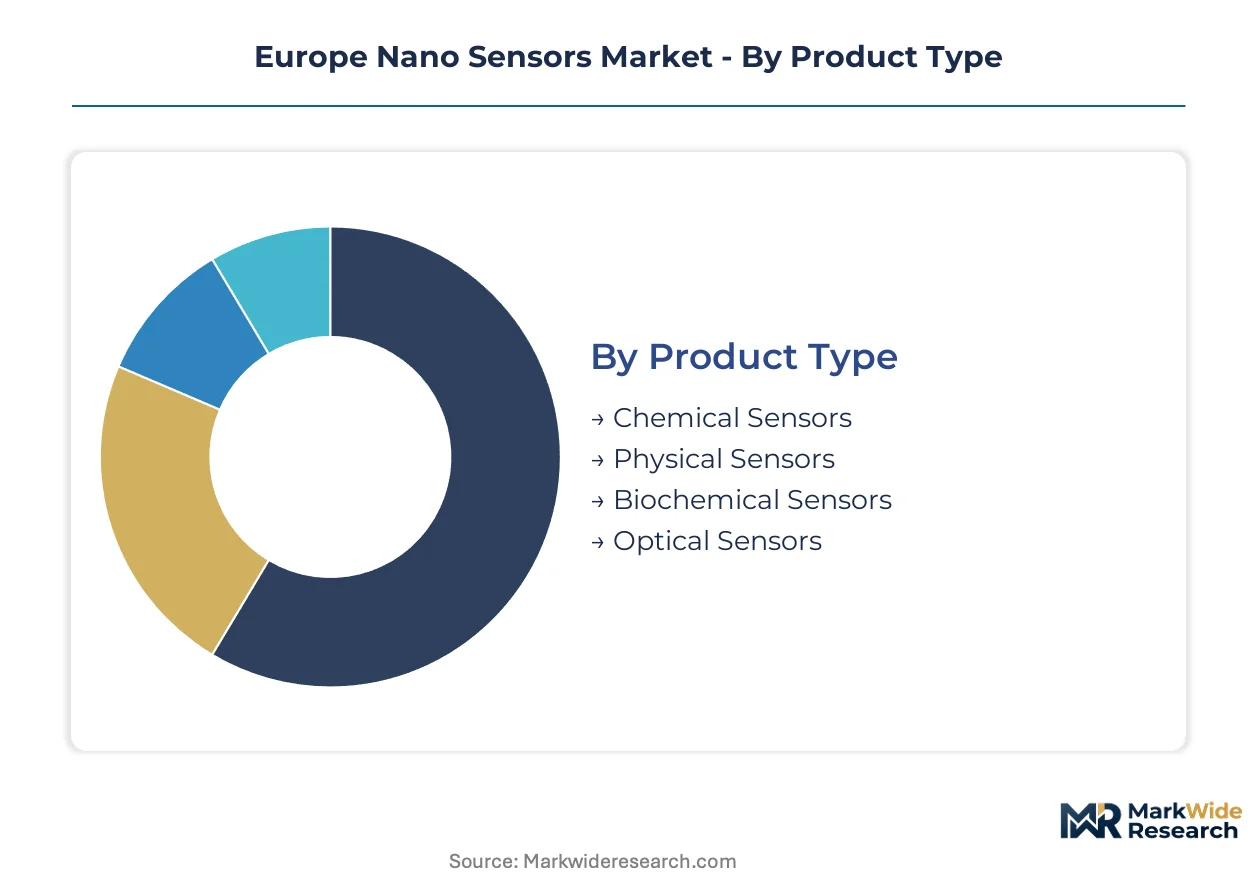
Segmentation in Europe's nano sensors market reveals how regulatory pressure and application-specific performance requirements fragment procurement patterns. Buyers prioritize detection thresholds, substrate compliance, and integration complexity differently across verticals, creating distinct competitive arenas for vendors.
Product Type:
Substitution pressure from alternative detection technologies varies sharply by transduction mechanism, with electrochemical methods threatening legacy platforms in cost-sensitive industrial segments.
- Chemical Sensors:Metal oxide semiconductor and polymer-absorption architectures detect gas-phase analytes at parts-per-billion resolution. German automotive OEMs and industrial safety clusters in the Ruhr region anchor procurement volumes for emissions and workplace hazard monitoring.
- Optical Sensors:Photonic transduction employing plasmonic nanostructures or silicon waveguides enables label-free biological detection. Point-of-care networks in France and Italy drive expansion for fluorescence-based diagnostic cartridges requiring minimal sample preparation.
- Physical Sensors:Piezoresistive and capacitive nano-mechanical devices measure force, pressure, and acceleration. MEMS foundries in Germany and Austria supply automotive inertial measurement units.
- Biochemical Sensors:Enzyme-functionalized or aptamer-coated interfaces target specific biomolecular recognition. Clinical laboratories in the Netherlands and Switzerland specify these for high-complexity immunoassay workflows.
Chemical sensors retain volume leadership; optical sensors hold the steepest expansion curve.
Application:
Margin structures diverge by deployment environment, with regulated clinical settings commanding premium pricing over industrial monitoring contracts.
- Healthcare Diagnostics:Centralized hospital laboratories and decentralized point-of-care networks require distinct form factors. French and Italian procurement consolidation favors portable optical modules, while German university hospitals specify high-throughput integrated systems.
- Industrial Automation:Predictive maintenance and process control applications demand ruggedized physical and chemical sensors. Automotive production lines in Stuttgart and Wolfsburg specify vibration and gas-detection arrays for smart factory deployments.
- Environmental Monitoring:Water quality surveillance in France and air quality networks in the UK specify plasmonic chemical sensors for heavy metal and particulate detection.
- Food Safety:Pathogen and contaminant screening in processing facilities employs biochemical and optical platforms. Italian dairy and meat processing clusters drive regional demand for rapid bacterial detection.
Healthcare diagnostics captures the highest unit margins; industrial automation generates the largest procurement volumes.
Technology:
Material platform selection determines REACH registration burden and fabrication cost structure, with carbon-based substrates facing escalating regulatory scrutiny.
- Metal Oxide Semiconductors:Tin dioxide and zinc oxide films operate at elevated temperatures for selective gas detection. German industrial safety vendors dominate formulation expertise for combustible and toxic gas monitoring.
- Carbon Nanotubes:Single-walled and multi-walled structures provide exceptional conductivity-to-weight ratios. Aerospace applications in Germany and the UK specify these for electromagnetic interference shielding in satellite and aircraft systems.
- Nanostructured Materials:Engineered porosity and surface area enhancement improve analyte capture efficiency. Environmental monitoring agencies in France specify these for persistent organic pollutant detection.
- Quantum Dots:Size-tunable fluorescence emission enables multiplexed biological assays. Swiss and Dutch diagnostic developers integrate these into high-sensitivity immunoassay platforms.
Metal oxide semiconductors retain volume leadership; carbon nanotubes hold the steepest expansion curve.
End User:
Customer concentration and certification requirements create tiered supply relationships, with aerospace and healthcare demanding captive technical support.
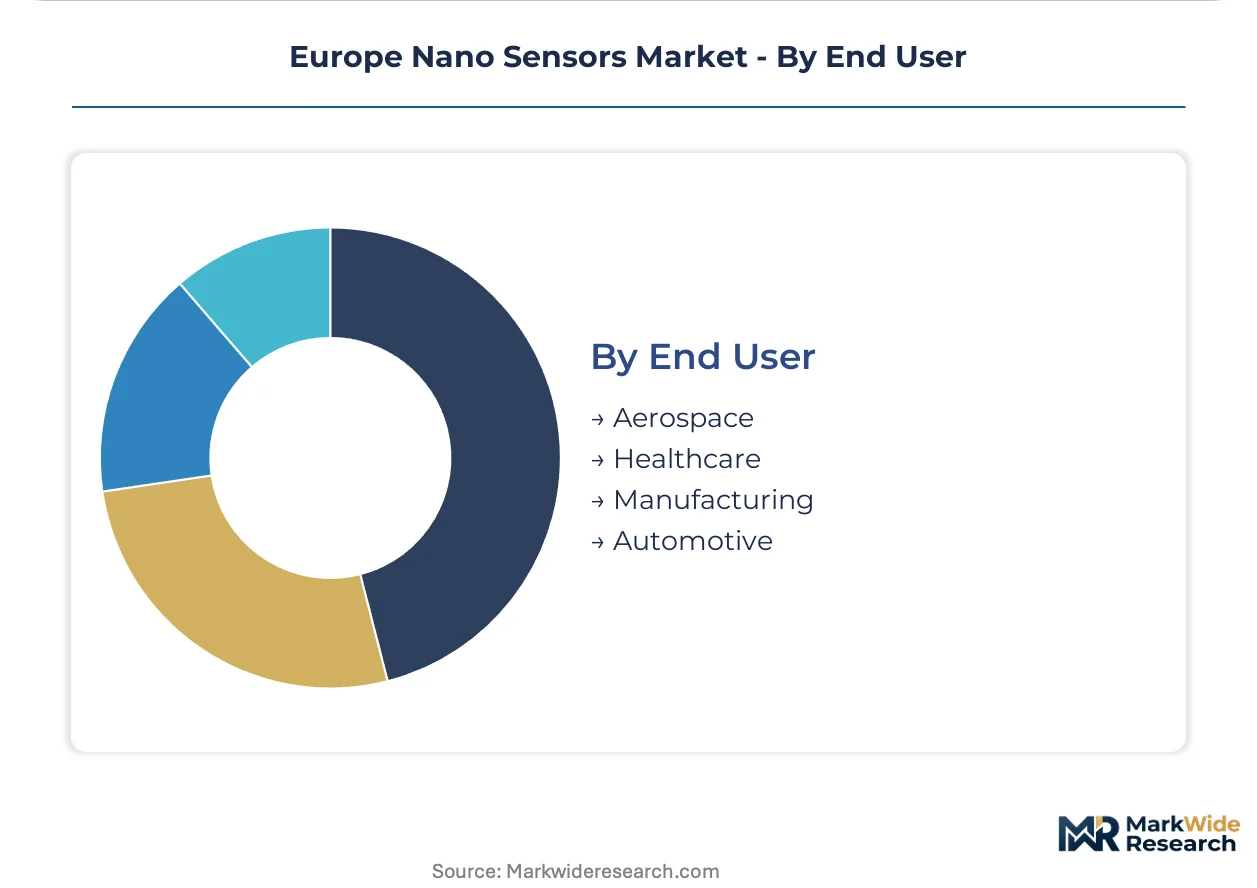
- Automotive:Emissions monitoring and battery management systems require chemical and physical sensors with automotive-grade reliability. German OEM integration programs in Munich and Stuttgart specify MEMS-based pressure and gas sensors.
- Healthcare:Clinical diagnostics and wearable monitoring demand biocompatibility and MDR conformity. Hospital procurement departments in France and the Netherlands unbundle hardware from service contracts.
- Manufacturing:Factory automation and quality control employ diverse physical and chemical sensing modalities. Northern Italian industrial IoT lag creates first-mover opportunities for environmental monitoring vendors.
- Aerospace:Weight-critical applications specify carbon nanotube electromagnetic shielding and structural health monitoring. UK satellite manufacturers and German aircraft suppliers drive specialized procurement.
Automotive retains volume leadership; aerospace holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive fab capacity clusters in Austria and eastern Germany concentrate supply-side leverage for industrial-grade physical sensor modules. German automotive OEM integration programs and REACH compliance deadlines are redrawing procurement geography across the continent.
Germany
Automotive OEMs in Stuttgart and Wolfsburg specify MEMS-based pressure and gas sensors for emissions monitoring and battery management systems. The EU Green Deal carbon-neutrality targets for 2050 accelerate procurement of low-emission nano sensor substrates. Industrial automation clusters in the Ruhr region anchor procurement volumes for workplace hazard monitoring applications.
United Kingdom
Air quality networks specify plasmonic chemical sensors for particulate detection in urban monitoring deployments. ECHA's evolving nano-specific hazard guidance adds registration burdens for carbon-based substrates entering UK supply chains. Satellite manufacturers drive specialized procurement of carbon nanotube electromagnetic shielding for weight-critical aerospace applications.
France
Point-of-care networks drive volume for portable chemical and optical sensor modules in decentralized clinical workflows. ANSM and CNIL oversight shapes data governance for connected diagnostic devices alongside CE marking under MDR. Environmental agencies specify plasmonic arrays for water quality surveillance in municipal monitoring infrastructure.
Italy
Underpenetrated factory automation in northern Italy offers first-mover positioning for environmental monitoring nano sensors. Dairy and meat processing clusters drive regional demand for rapid bacterial detection using biochemical and optical platforms. Procurement consolidation favors portable optical modules compatible with third-party calibration support.
Netherlands
Hospital procurement departments unbundle sensor hardware from service contracts, favoring unit-price purchasing across diagnostic equipment tenders. Group purchasing organizations consolidate tenders for high-throughput integrated systems in university medical centers. Swiss and Dutch diagnostic developers integrate quantum dots into high-sensitivity immunoassay platforms for clinical laboratory workflows.
Europe Nano Sensors Market Competitive Landscape
Concentration sits with diversified electronics conglomerates possessing captive semiconductor fabrication capacity. MEMS foundries in Germany and Austria supply automotive inertial measurement units while environmental monitoring specialists capture share through compatibility certification. Three archetypes dominate: integrated semiconductor manufacturers with sensor divisions, pure-play MEMS foundries, and diagnostic-focused optical specialists. Competitive moves center on backward integration into nanostructured material supply and strategic partnerships for REACH-compliant substrate reformulation.
Among Germany-based diversified technology groups, Bosch Sensortec and Siemens AG exemplify the integrated archetype with depth across automotive and industrial verticals. STMicroelectronics occupies a position bridging European MEMS manufacturing with nanostructured material R&D for environmental monitoring. Infineon Technologies AG anchors the industrial-grade physical sensor segment through captive fab presence in Austria and eastern Germany.
| Leading Market Players |
|---|
| Bosch Sensortec |
| STMicroelectronics |
| Siemens AG |
| Analog Devices Inc |
| OMRON Corporation |
| Honeywell International Inc |
| Texas Instruments Incorporated |
| Infineon Technologies AG |
| NanoSENSORS GmbH |
| Others |
Supply & Pricing Matrix
Twenty-four week lead times for REACH-compliant nanostructured substrates concentrate pricing power with German and Austrian MEMS foundries while compressing margin buffers for non-integrated sensor vendors dependent on spot-market palladium procurement.
Pricing Analysis
REACH substance registration dictates the pricing tier structure across Europe's nano sensors market, separating MDR-certified diagnostic platforms from industrial safety modules and uncertified component supply. Premium-mid-economy pricing differentiation rests on CE marking tier and captive fab ownership, with hospital procurement departments in France and the Netherlands driving cost compression through unbundled hardware tenders. Pricing pressure stems from precious metal input volatility in metal oxide semiconductor formulations. Automotive OEMs in Germany exhibit lowest price sensitivity due to integration program lock-ins, while northern Italian manufacturing buyers prioritize unit-cost minimization over certification grade.
Supply Chain Analysis
Just-in-time inventory strategies dominate among German automotive OEMs, whereas environmental monitoring agencies in France and the UK maintain strategic stockpiles of plasmonic sensor arrays for water quality surveillance networks. Supply concentration centers on Austria and eastern Germany for MEMS fabrication, with nanostructured material substrates sourced from Dutch specialty chemical suppliers and Swiss quantum dot developers. Palladium, platinum, and high-purity silicon wafers constitute critical input dependencies. Single-source vulnerability in captive fab capacity creates supply risk for non-integrated vendors. Distribution runs through direct OEM integration programs for automotive and industrial verticals, with diagnostic equipment tenders consolidated via group purchasing organizations in the Netherlands and UK hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's nano sensors market is recovering from cyclical compression in industrial automation procurement, with EU Green Deal carbon-neutrality mandates reactivating capital expenditure cycles across German automotive and Ruhr region manufacturing clusters.
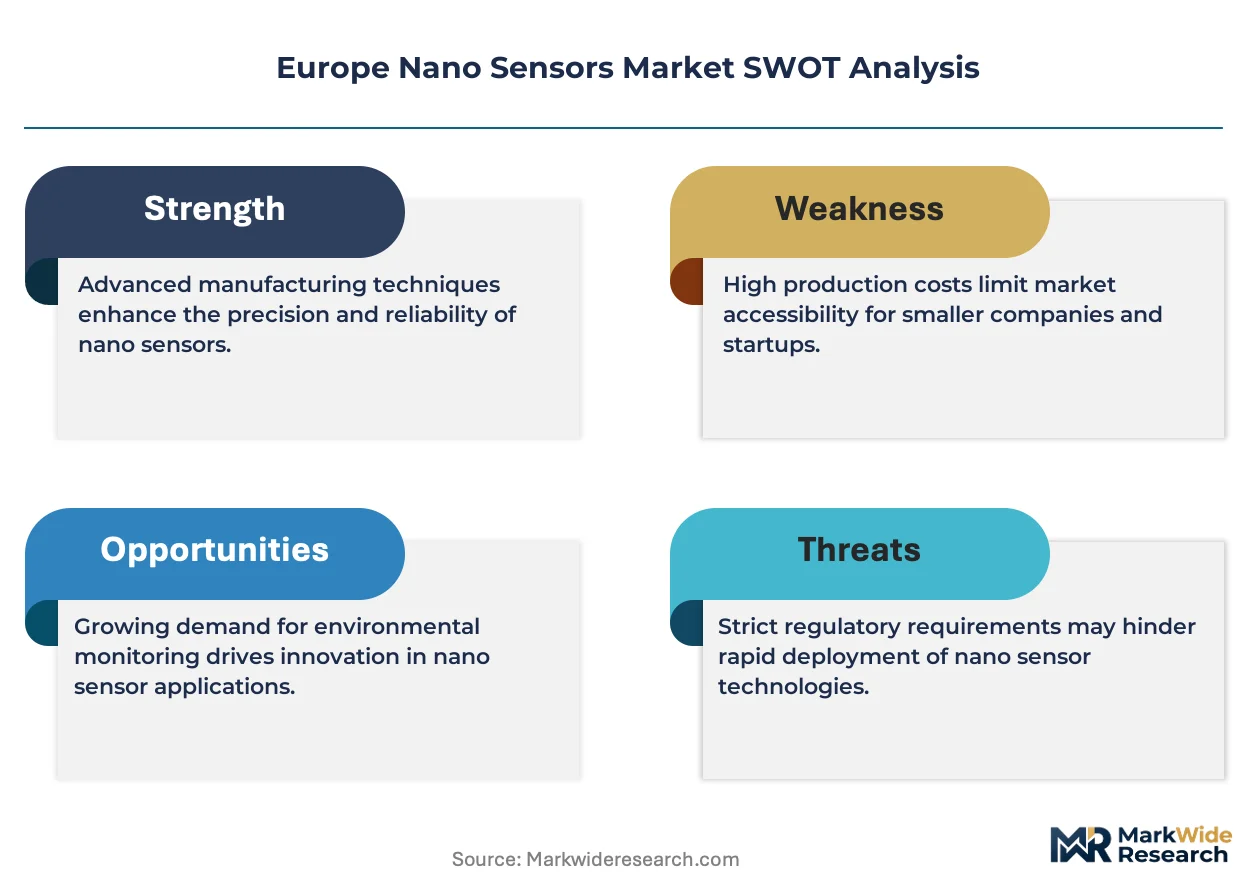
For Market Incumbents: Compound defensive positioning by deepening backward integration into REACH-compliant nanostructured material supply and expanding captive fab capacity in Austria to offset single-source vulnerability. Accelerate SCIP database compliance for reformulated product lines ahead of ECHA's evolving nanoform guidance. Prioritize MDR certification investment to defend margin position against disintermediation from third-party calibration specialists. For New Entrants and Emerging Players: Anchor in northern Italy's underpenetrated factory automation sector, where environmental monitoring nano sensors face limited incumbent saturation. Target dairy and meat processing clusters with portable optical modules compatible with third-party calibration support. Pursue compatibility certification across multiple analyzer platforms to bypass integrated vendor relationships in consolidated procurement environments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates seeking to divest non-core sensor divisions amid R&D budget compression from dual-platform coverage attempts. Five-to-ten year viability hinges on photonic-biological convergence capabilities and REACH-compliant substrate reformulation expertise. Watch for inflection when ECHA's nano-specific hazard guidance triggers material platform authorization withdrawals, consolidating market share among pre-compliant vendors.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Substrate Reformulation | ECHA registration deadlines force material substitution, rewarding early SCIP compliance in German industrial safety supply. |
| Photonic-Biological Platform Convergence | Optical nano sensors interfacing with microfluidic cartridges capture point-of-care network expansion in France and Italy. |
| Captive Fab Capacity Expansion | Austria and eastern Germany MEMS foundries secure automotive OEM integration programs against supply vulnerability. |
| MDR Harmonization Alignment | Diagnostic sensor vendors embedding AI inference gain accelerated CE marking pathways under EU AI Act integration. |
| Carbon Nanotube Electromagnetic Shielding | Aerospace applications in Germany and UK specify weight-critical solutions for satellite and aircraft system procurement. |
Research Methodology
Desk research of ECHA regulatory filings, EU trade statistics, and semiconductor industry association reports preceded structured interviews with MEMS foundry operations directors, automotive OEM sensor procurement leads, hospital biomedical engineers, and environmental monitoring agency technical specifications officers. Primary fieldwork combined with secondary validation from SEC 10-K disclosures of listed sensor manufacturers and customs data on nanomaterial import flows. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Variance decomposition across product type, application, technology platform, and end-user concentration shaped the analytical framework for volume and value projections throughout the forecast period. CAGRs derived from regression against industrial automation capital expenditure cycles, healthcare diagnostics procurement patterns, and REACH compliance timeline impacts. Modeled inputs included automotive production forecasts for Stuttgart and Wolfsburg OEM programs, point-of-care network expansion rates in France and Italy, and aerospace procurement trajectories for UK satellite manufacturers.
Material uncertainties — ECHA nanoform guidance revisions, palladium price volatility spikes, and MDR certification timeline extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions on regulatory stability and supply chain continuity. Revision becomes warranted when REACH substance restriction scope crosses thresholds triggering widespread substrate reformulation failure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Air Pressure Sensor Market
Sensors and Controls
Barometer Market
Sensors and Controls
Submarine Sensor Market
Sensors and Controls
Control Knobs for Panel Potentiometer Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
Pressure Transmitter and Transducer Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
Battery Free Wireless Sensor Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Thermometer Market
Sensors and Controls
Automation Control Components and Devices Market
Sensors and Controls
VOC Sensors and Monitors Market
Sensors and Controls
Biometric Sensors Market
Sensors and Controls
Home Automation Sensors Market