
 Germany Non-Contact Infrared Thermometer Market | 2026-2036
Germany Non-Contact Infrared Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Non-Contact Infrared Thermometer Market Insights
Modular sensor-head configurations paired with wireless data-logging modules is restructuring how German clinics evaluate procurement options. Braun Healthcare leverages its established distribution through Hartmann AG's medical supply channels to sustain shelf presence across ambulatory care networks. WIKA anchors the industrial temperature-monitoring segment with precision-engineered infrared sensors that compete on calibration traceability. Optris GmbH specializes in compact OEM thermal modules that extend into veterinary diagnostic equipment, while Testo SE & Co. KGaA dominates the portable segment through direct-to-technician digital platforms.
A non-contact infrared thermometer measures surface or body temperature by detecting infrared radiation emitted by an object, typically employing thermopile sensors with spectral sensitivity bands between 8 and 14 micrometers for clinical applications and achieving response times under 500 milliseconds. These devices serve fever screening, industrial process control, and veterinary diagnostics without physical contact, reducing cross-contamination risk in hygiene-critical environments. Handheld units lead the product type landscape due to their flexibility across hospital wards and home settings, while wall-mounted installations represent the fastest-growing configuration as German healthcare facilities automate patient intake workflows. The thermopile technology category captures the dominant share of production volume, though laser-assisted targeting systems command margin premiums in precision industrial applications.
The Medical Devices Regulation (MDR) and DIN EN 12470-5 standards govern clinical accuracy requirements, while the CE marking process under EU framework dictates market access timelines for new entrants. KBA does not regulate this sector; rather, the German Institute for Medical Documentation and Information (DIMDI) maintains the national database of certified medical devices that shapes procurement eligibility for public hospital tenders. Stakeholders must monitor how the EU AI Act classification criteria will treat infrared thermometers with embedded algorithmic fever-detection thresholds, as this determination will reshape software validation obligations and competitive differentiation strategies.
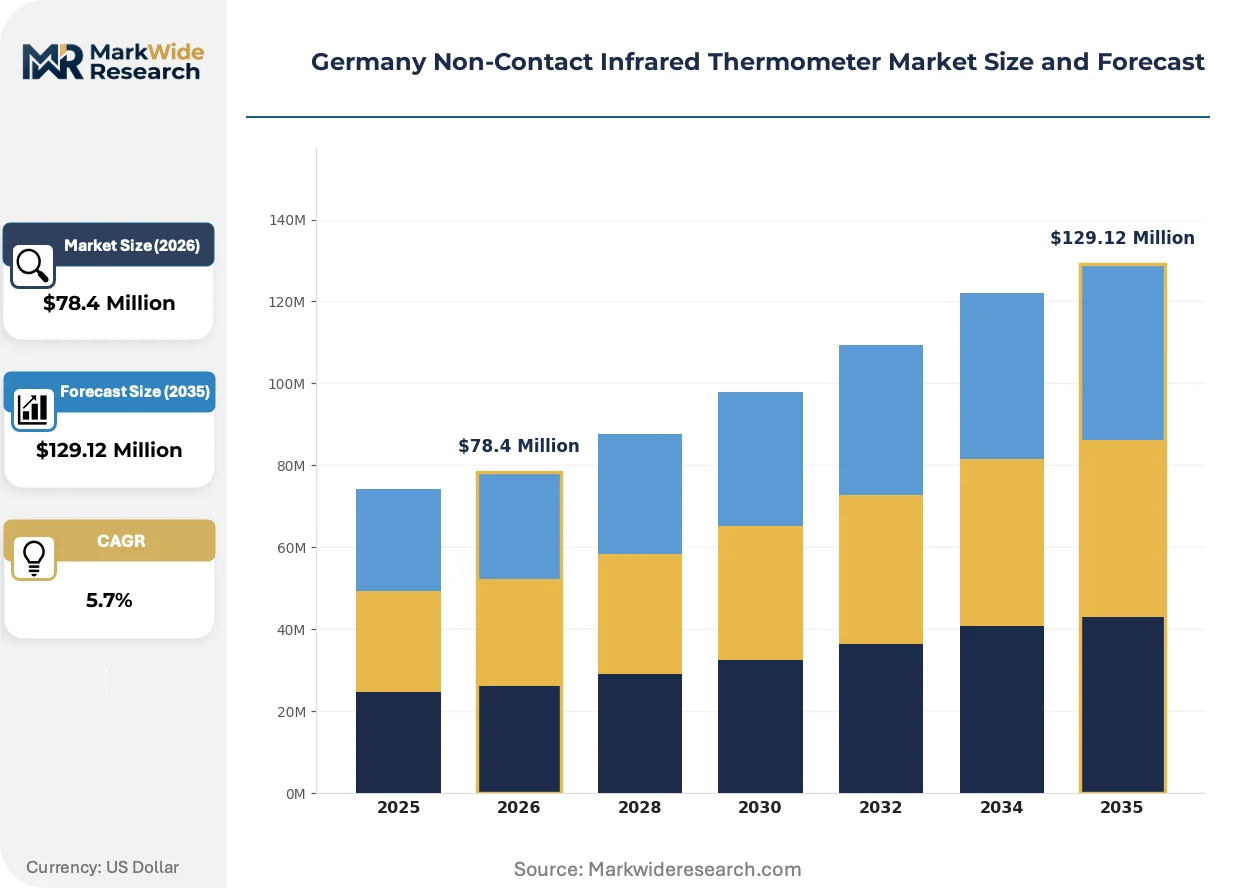
Market Dynamics
The MDR transition and DIN EN 12470-5 accuracy mandates are compressing certification timelines while wall-mounted automation demand accelerates across German hospital networks. Procurement officers now weight calibration traceability and wireless integration equally in tender evaluations.
Growth Catalysts
- Hospital automation mandates:German university hospital networks in Bavaria and North Rhine-Westphalia are standardizing wall-mounted infrared units for patient intake workflows. Triage zone throughput requirements drive volume procurement.
- DIN EN 12470-5 compliance:Tightened clinical accuracy standards are filtering out uncertified imports and elevating premium device categories in public tenders.
- Thermopile sensor advancement:Response time improvements below 500 milliseconds are expanding viable use cases from fever screening to continuous patient monitoring.
Market Restraints
- Calibration infrastructure concentration:Precision reference standards for clinical-grade verification depend on a limited network of German metrology institutes.
- Thermopile wafer supply:MEMS sensor substrate production concentrates in Asian foundries, creating input cost volatility for domestic assemblers.
- Contact thermometer substitution:Tympanic and axillary probe devices retain preference in pediatric wards due to familiarity and lower unit cost.
Strategic Opportunities
- Veterinary diagnostic expansion:Optris GmbH's OEM thermal module architecture extends into livestock health monitoring, opening agricultural procurement channels.
- EU AI Act classification clarity:Algorithmic fever-detection thresholds embedded in next-generation devices will trigger software validation requirements that favor established German manufacturers.
- Industrial process convergence:WIKA's precision-engineered sensors bridge clinical and manufacturing applications, enabling cross-sector calibration service bundling.
Industry Challenges
- MDR technical documentation:Clinical evaluation report preparation consumes 14-18 months for novel sensor configurations, delaying market entry.
- Wireless security integration:Hospital IT departments demand IEC 62304-compliant software lifecycle documentation for data-logging modules, complicating vendor qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Non-Contact Infrared Thermometer Market |
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $129.12 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Fixed, Portable, Wall-mounted End User: Hospitals, Clinics, Laboratories, Home Usage Technology: Laser, Thermopile, Optical, Digital Application: Fever Screening, Medical Diagnosis, Industrial Use, Veterinary |
| Companies Covered | Braun Healthcare, WIKA (Alexander Wiegand SE & Co. KG), PCE Deutschland Gmbh, Geratherm Medical AG, Testo SE & Co. KGaA, Optris GmbH, Paul Hartmann AG, Amarell GmbH & Co. KG, AFRISO-EURO-INDEX GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Non-Contact Infrared Thermometer Market Trends and Innovations
Modular sensor-head configurations paired with wireless data-logging modules are restructuring how German clinics evaluate procurement options. Three distinct shifts are compressing traditional hardware margins while opening software-defined revenue streams.
Multi-spectral infrared arrays with embedded ambient temperature compensation are overtaking single-point thermopile sensors in precision-critical applications. Bavarian university hospitals are piloting these configurations for continuous ward monitoring. The technology is overtaking legacy handheld units by enabling unattended measurement cycles that reduce nursing staff contact exposure.
The EU AI Act classification criteria for algorithmic fever-detection thresholds are reshaping software validation obligations for manufacturers targeting German healthcare procurement. Devices with embedded decision-support algorithms face heightened conformity assessment requirements. Wall-mounted installations with cloud-connected analytics are most affected, driving partnerships between hardware OEMs and notified bodies.
Direct-to-technician digital platforms are compressing traditional medical supply distribution margins in the portable segment. Testo SE & Co. KGaA's field service portals demonstrate how manufacturer-controlled channels bypass Hartmann AG's wholesale networks. Bavarian ambulatory care networks show the strongest platform adoption, with procurement officers prioritizing calibration-as-a-service bundling over upfront hardware pricing.
Germany Non-Contact Infrared Thermometer Market Segmentation
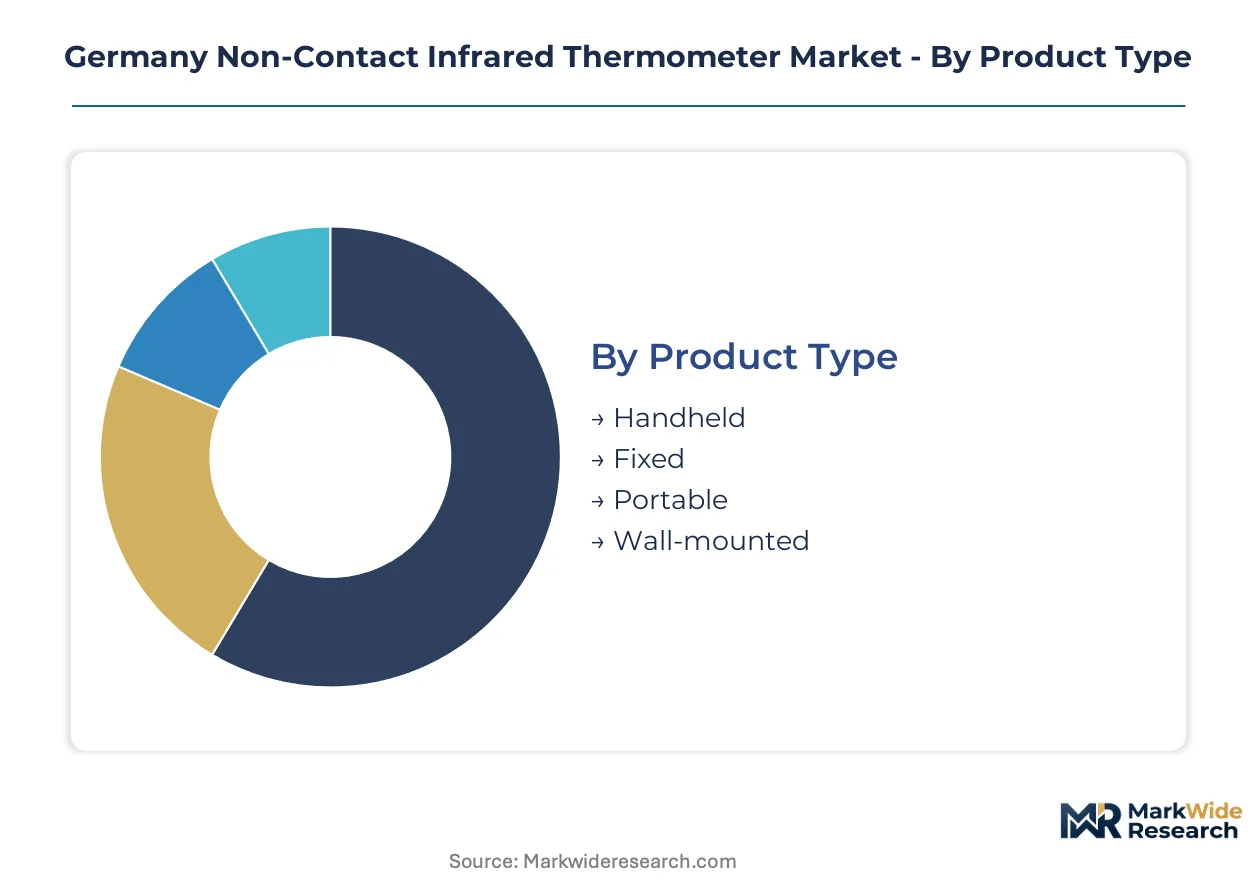
German procurement patterns fragment sharply across clinical, industrial, and consumer channels. Each segment carries distinct certification burdens and margin profiles that reshape vendor positioning.
Product Type:
Manufacturing concentration in Bavaria and North Rhine-Westphalia tilts supply toward hospital-grade configurations with traceable calibration chains.
- Handheld:Battery-powered units with thermopile sensors dominate ward flexibility. Bavarian university hospitals prioritize these for nursing staff mobility across triage zones, though DIN EN 12470-5 compliance costs squeeze mid-tier suppliers.
- Wall-mounted:Automated intake installations with wireless data-logging expand fastest across German hospital networks. North Rhine-Westphalia's university hospital procurement mandates drive volume, with MDR technical documentation requirements filtering out smaller vendors.
- Fixed:Permanent industrial monitoring stations anchor WIKA's precision sensor production. Calibration traceability to German metrology institutes commands premium positioning.
- Portable:Compact field-service units target veterinary and ambulatory applications. Testo SE's direct-to-technician platforms bypass traditional Hartmann AG distribution channels.
Today's leader: Handheld. Tomorrow's challenger: Wall-mounted.
End User:
Public tender eligibility under DIMDI certification databases concentrates volume in institutional channels with documented calibration protocols.
- Hospitals:Wall-mounted automation for patient intake workflows. Bavaria and North Rhine-Westphalia university networks standardize procurement, with IEC 62304 software documentation requirements complicating vendor qualification.
- Home Usage:Consumer-grade handheld units with simplified interfaces. Retail shelf presence depends on CE marking speed rather than clinical accuracy tier.
- Clinics:Ambulatory care networks favor modular sensor-head configurations with wireless integration. Testo's field service portals gain share in Bavaria through calibration-as-a-service bundling.
- Laboratories:Precision reference devices requiring metrology-grade verification. Limited German calibration infrastructure creates supply bottlenecks for clinical-grade units.
Institutional procurement anchors current revenue. Consumer channels offer volume scale at compressed margins.
Technology:
Sensor substrate sourcing from Asian MEMS foundries introduces input cost volatility that favors domestic assemblers with locked supply agreements.
- Thermopile:Dominant production volume with spectral sensitivity bands between 8 and 14 micrometers. Response times below 500 milliseconds enable continuous patient monitoring pilots in Bavarian hospitals.
- Laser:Assisted targeting systems command margin premiums in precision industrial applications. WIKA leverages calibration traceability to anchor this tier.
- Digital:Embedded algorithmic processing for fever-detection thresholds. EU AI Act classification uncertainty delays software validation timelines for next-generation devices.
- Optical:Multi-spectral infrared arrays with ambient temperature compensation. Bavarian university hospital pilots test unattended measurement cycles for ward monitoring.
Thermopile sensors hold production scale. Multi-spectral optical configurations gain precision-critical share.
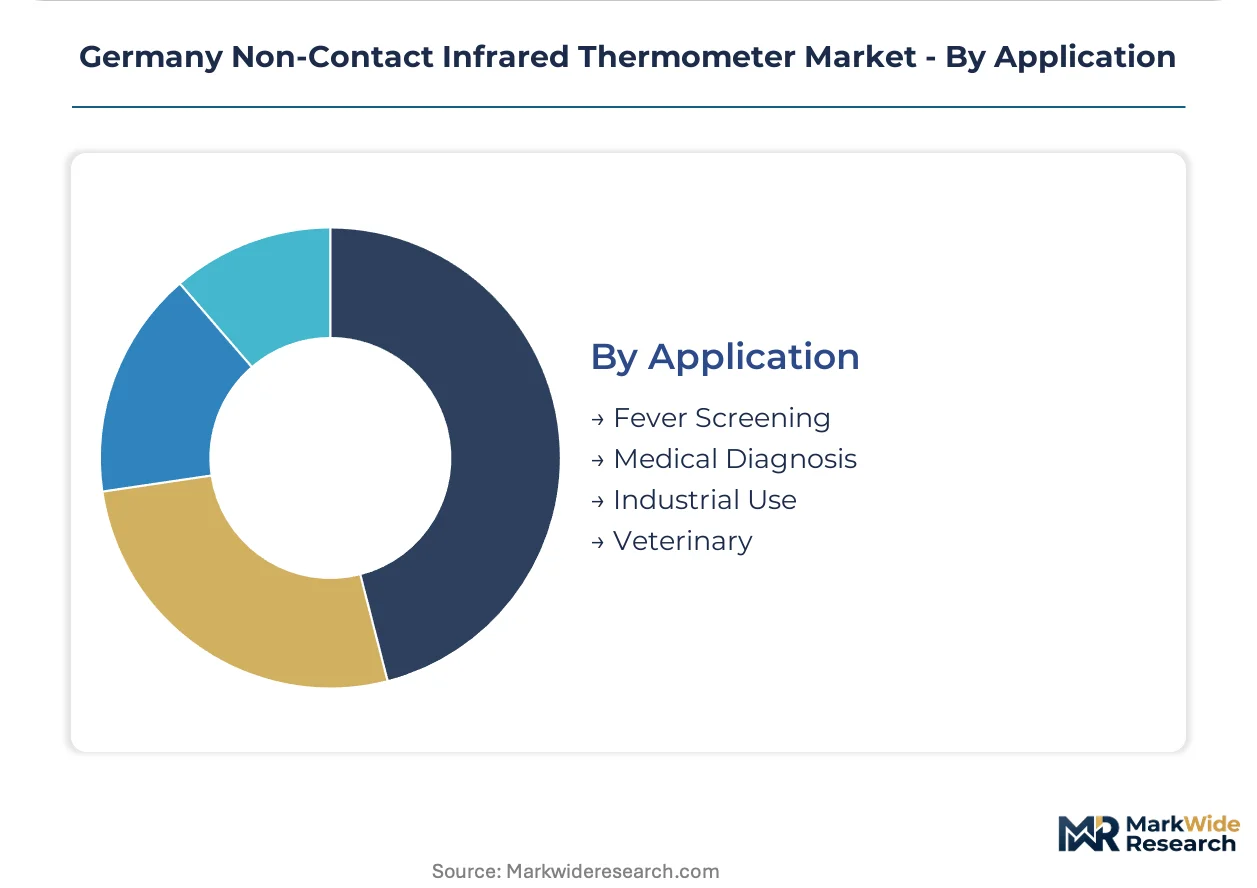
Application:
Cross-sector demand from clinical, manufacturing, and agricultural channels creates divergent certification pathways and pricing bands.
- Fever Screening:Mass triage deployment in hospital intake zones. Wall-mounted automation reduces nursing staff contact exposure while MDR compliance elevates device categories in public tenders.
- Industrial Use:Process control monitoring bridging clinical and manufacturing calibration services. WIKA's precision sensors enable cross-sector bundling strategies.
- Medical Diagnosis:Clinical-grade accuracy under DIN EN 12470-5 standards. Tympanic and axillary probe devices retain pediatric preference due to familiarity.
- Veterinary:Livestock health monitoring through OEM thermal module architecture. Optris GmbH extends compact sensor platforms into agricultural procurement channels.
Clinical fever screening commands premium pricing. Veterinary and industrial segments expand addressable market scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German non-contact infrared thermometer manufacturing traces its precision-engineering lineage to post-war optical instrument clusters in Thuringia and Bavaria. These foundations established metrology-grade calibration protocols that now differentiate domestic suppliers from import competitors. Contemporary procurement concentrates in university hospital networks and industrial automation corridors.
Bavaria
University hospital networks in Munich and Erlangen standardize wall-mounted infrared automation for patient intake workflows. DIN EN 12470-5 compliance mandates filter tender eligibility through DIMDI certification databases. The Munich-Planegg medical device corridor anchors thermopile sensor assembly operations serving clinical-grade demand.
North Rhine-Westphalia
Rhineland university hospitals drive volume procurement for triage zone throughput optimization. MDR technical documentation requirements compress vendor qualification timelines for wireless data-logging modules. The Cologne-Düsseldorf industrial belt concentrates precision metrology institutes supporting calibration traceability chains.
Baden-Württemberg
Stuttgart's industrial automation sector bridges clinical fever screening with manufacturing process control applications. CE marking timelines under EU framework dictate market access for embedded algorithmic processing modules. The Neckar-Alb region hosts sensor-head configuration specialists serving veterinary diagnostic OEM channels.
Lower Saxony
Hanover's veterinary equipment manufacturers extend thermal module platforms into livestock health monitoring procurement. IEC 62304 software lifecycle documentation requirements complicate hospital IT department vendor approvals. The Braunschweig-Wolfsburg corridor integrates infrared sensors into automotive supplier quality control systems.
Hesse
Frankfurt's ambulatory care networks prioritize direct-to-technician digital platforms over traditional medical supply distribution. EU AI Act classification uncertainty delays software validation for next-generation fever-detection algorithms. The Rhine-Main logistics hub accelerates calibration-as-a-service bundling for portable field-service units.
Germany Non-Contact Infrared Thermometer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across calibration traceability and MDR certification completion timelines. The vendor base stratifies into three tiers: precision metrology specialists with locked hospital supply agreements, modular OEM sensor suppliers extending into adjacent diagnostics, and portable device assemblers competing through digital distribution bypass. Dominant competitive moves include backward integration into thermopile wafer sourcing partnerships and calibration service bundling to defend recurring revenue streams.
Among German-based precision engineering groups, WIKA anchors the industrial-clinical convergence tier through metrology-grade sensor production. Braun Healthcare and Testo SE & Co. KGaA occupy distinct positioning vectors—Braun represents established medical supply channel presence, while Testo exemplifies direct-to-technician platform disruption. Optris GmbH sits within the compact OEM module specialization tier, with Geratherm Medical AG and Paul Hartmann AG representing diversified health technology conglomerate structures. PCE Deutschland GmbH, Amarell GmbH & Co. KG, and AFRISO-EURO-INDEX GmbH populate the mid-market instrumentation segment.
| Leading Market Players |
|---|
| Braun Healthcare |
| WIKA (Alexander Wiegand SE & Co. KG) |
| PCE Deutschland Gmbh |
| Geratherm Medical AG |
| Testo SE & Co. KGaA |
| Optris GmbH |
| Paul Hartmann AG |
| Amarell GmbH & Co. KG |
| AFRISO-EURO-INDEX GmbH |
| Others |
Pricing and Supply Chain Analysis
Family-owned precision-engineering mid-caps in Bavaria and North Rhine-Westphalia anchor German production, locking in calibration traceability premiums while Asian MEMS foundry dependencies compress margins on economy-tier handheld units.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates wall-mounted hospital automation systems from portable field-service units and consumer-grade handheld devices. DIN EN 12470-5 certification tier and calibration-as-a-service bundling drive price differentiation, with MDR compliance costs elevating clinical-grade premiums. Cost compression in the economy handheld tier intensifies because Asian import competition floods retail channels. Home usage segments exhibit highest price sensitivity; Bavarian university hospital procurement committees show lowest sensitivity when wireless data-logging integration reduces total cost of ownership.
Supply Chain Analysis
Refurbishment flows for thermopile sensor modules remain underdeveloped, creating stranded asset risk for hospitals upgrading to multi-spectral optical arrays. MEMS wafer substrate production concentrates in China, Taiwan, and South Korea, feeding German assembly operations. Thermopile sensors, laser targeting components, and wireless data-logging modules constitute critical input dependencies. Single-source vulnerability in Asian MEMS foundries threatens input cost stability for domestic assemblers lacking locked supply agreements. Distribution runs through Hartmann AG's medical supply wholesale networks for established hospital procurement, while Testo SE's direct-to-technician platforms bypass traditional channels in the portable segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German MDR compliance timelines and DIN EN 12470-5 certification costs create a geographic-arbitrage window against faster CE-marking pathways in neighboring EU jurisdictions, rewarding manufacturers with dual-notification-body strategies.
For Market Incumbents: Lock in thermopile wafer sourcing partnerships with Asian MEMS foundries to defend against input cost volatility from substitute technology displacement. Secure IEC 62304-compliant software documentation for wireless modules before EU AI Act classification clarifies algorithmic fever-detection validation obligations. Calibration service bundling represents the priority defensive lever against direct-to-technician platform erosion. For New Entrants and Emerging Players: Multi-spectral infrared array technology with embedded ambient temperature compensation offers entry wedge into Bavarian university hospital pilot programs for continuous ward monitoring. Veterinary diagnostic OEM channels through livestock health monitoring procurement show lowest incumbent saturation. Target agricultural equipment distributors in Lower Saxony with compact thermal module architectures as the specific go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market instrumentation specialists lacking MDR technical documentation completion. Long-term viability over the next decade hinges on software-defined revenue streams from algorithmic fever-detection thresholds rather than hardware margins alone. Watch EU AI Act classification criteria for infrared thermometers with embedded decision-support algorithms as the specific inflection signal triggering consolidation premiums for validated-device portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Completion | DIMDI certification database eligibility determines public hospital tender participation in Bavaria and North Rhine-Westphalia. |
| Wireless Data-Logging Module Development | IEC 62304-compliant software lifecycle documentation satisfies hospital IT department vendor qualification requirements. |
| Calibration-as-a-Service Bundling | Recurring revenue streams defend against direct-to-technician platform compression in the portable segment. |
| Thermopile Wafer Sourcing Partnership | Locked supply agreements with Asian MEMS foundries mitigate input cost volatility for domestic assemblers. |
| Veterinary Diagnostic OEM Channel Expansion | Livestock health monitoring procurement in Lower Saxony extends addressable market beyond clinical fever screening. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement officers, biomedical engineers, GPO contracts managers, and veterinary equipment manufacturers with secondary validation against DIMDI certification databases, EU MDR guidance documents, DIN standards publications, and customs trade records. Bottom-up segment sizing and top-down macroeconomic anchoring provided cross-check triangulation.
Comparable historical reference periods anchored the projection horizon across product type, end user, technology, and application dimensions, with specific modeling of hospital automation adoption curves and thermopile sensor response time improvements. CAGRs derived from segment-level volume trajectories and value-per-unit trends incorporated MDR transition timeline assumptions and wireless integration penetration rates as industry-specific forecast inputs.
The model holds under stable MDR implementation schedules and continued DIN EN 12470-5 enforcement; deviation in EU AI Act classification timelines or Asian MEMS foundry supply disruptions would shift volume and value trajectories. Practitioners should monitor notified body capacity constraints and thermopile wafer spot pricing for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Electric Vehicle Sensor Market
Sensors and Controls
Silicon Photomultiplier (Sipm) Market
Sensors and Controls
Global Battery Free RFID Sensor Market
Sensors and Controls
Barometer Market
Sensors and Controls
Magnetoresistive Sensors Market
Sensors and Controls
Antenna Transducer and Radome Market
Sensors and Controls
Asia-Pacific Bulk Acoustic Wave Sensors Market
Sensors and Controls
Reservoir Monitoring System Market
Sensors and Controls
Africa Robotic Sensors Market
Sensors and Controls
United States Pressure Transmitter Market
Sensors and Controls
Smartphone Biometric Sensors Market
Sensors and Controls
RTD Temperature Sensors Market
Sensors and Controls
Machine Control System Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Millimeter Wave Sensors Market