
 Ultrafast Rectifiers Market | 2026-2036
Ultrafast Rectifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrafast Rectifiers Market Analytics
Buyer concentration among automotive OEMs and tier-one inverter manufacturers is restructuring procurement dynamics across the ultrafast rectifier supply base. Vishay Intertechnology leverages its broad silicon and silicon carbide portfolio to serve multiple voltage classes simultaneously. Infineon Technologies anchors European supply chains through captive fab capacity and automotive qualification depth. STMicroelectronics competes by integrating ultrafast devices with gate-driver ICs in system-in-package formats.
Ultrafast rectifiers are semiconductor diodes engineered for reverse recovery times below 50 nanoseconds, typically fabricated on silicon, silicon carbide, or gallium nitride substrates using epitaxial growth and platinum doping to minimize stored charge and switching losses. Their primary purpose is to convert alternating current to direct current in high-frequency power conversion systems where standard rectifiers would generate excessive heat and electromagnetic interference. Silicon carbide ultrafast rectifiers command premium positioning in electric vehicle onboard chargers and traction inverters where thermal budgets are tight. Gallium nitride variants represent the fastest-growing product category as telecom server power supplies push switching frequencies beyond 500 kilohertz. Silicon-based devices retain volume dominance in consumer electronics adapters where cost floors matter more than incremental efficiency gains.
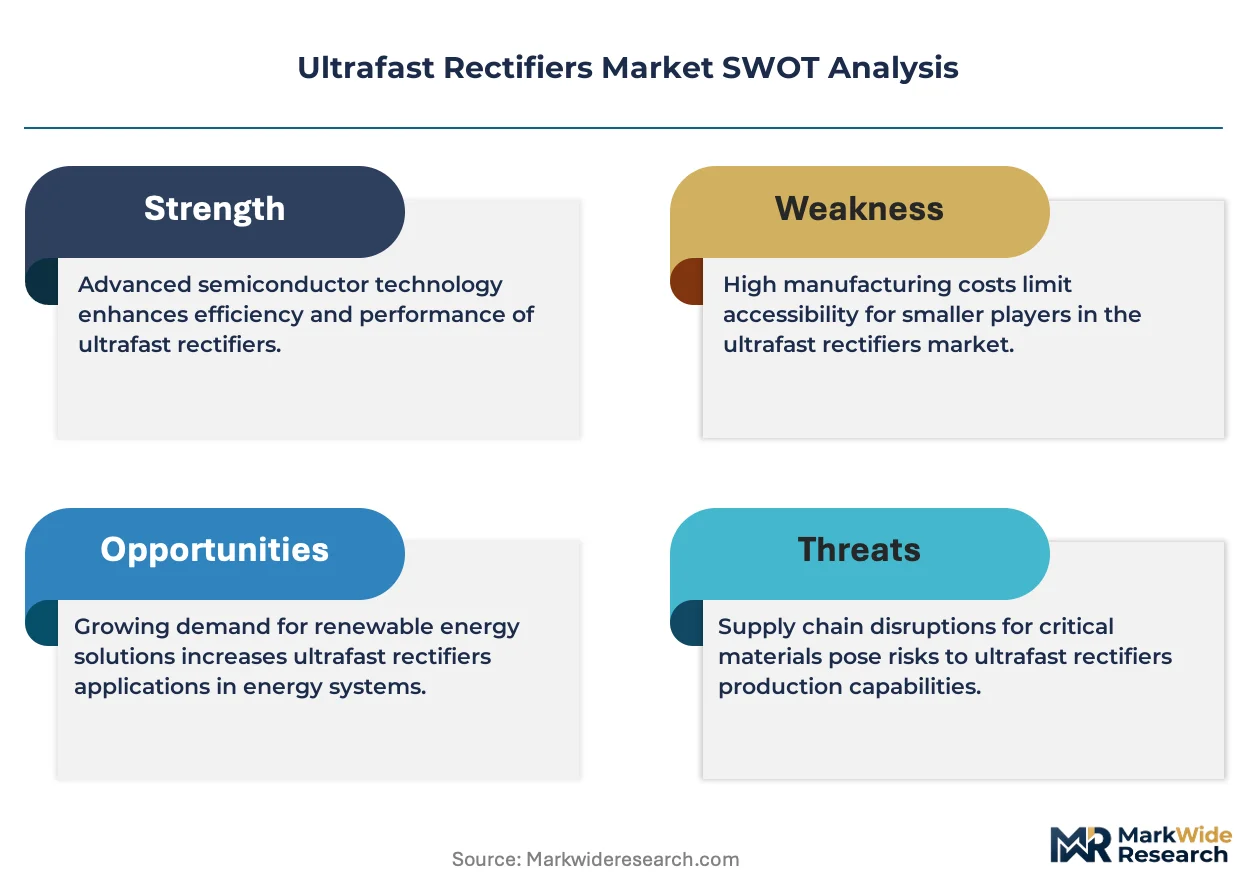
FDA medical-device power-supply regulations, EPA energy-efficiency standards for external power supplies, and EU Green Deal carbon-border adjustments collectively tighten compliance thresholds for rectifier efficiency and material traceability. CE marking under RoHS and REACH restricts heavy-metal content in packaging and substrate metallization, pushing manufacturers toward gold-free barrier metallization schemes. Stakeholders must monitor how automotive ISO 26262 functional-safety requirements propagate from power modules down to discrete rectifier qualification protocols.
Market Dynamics
Powertrain electrification across automotive OEMs is compressing qualification timelines and forcing rectifier suppliers to synchronize roadmaps with tier-one inverter manufacturers.
Growth Catalysts
- EU Green Deal efficiency mandates:Tighter carbon-border adjustments are accelerating design upgrades in onboard chargers and traction inverters across European automotive supply chains.
- Gallium nitride substrate migration:Telecom server power supplies pushing beyond 500 kilohertz switching frequencies are pulling demand for the fastest recovery devices.
- China:Domestic EV OEMs and renewable inverter manufacturers are sourcing directly from qualified suppliers, concentrating procurement volume in the Yangtze River Delta cluster.
Market Restraints
- Epitaxial wafer supply concentration:Six-inch silicon carbide substrate output remains captive to a handful of Japanese and US suppliers, creating allocation bottlenecks.
- Platinum doping cost volatility:Noble metal price swings in barrier metallization layers compress margin buffers for mid-tier device fabricators.
- ISO 26262 propagation delays:Functional-safety qualification protocols for discrete rectifiers lag behind power module timelines, freezing automotive design-ins.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for semiconductor packaging are attracting rectifier assembly investments to Gujarat and Karnataka.
- Gate-driver integration:System-in-package formats combining ultrafast diodes with driver ICs open premium positioning in space-constrained industrial motor drives.
- US IRA domestic content credits:Clean energy manufacturing tax incentives are reshaping sourcing calculus for solar inverter builders in Arizona and Texas.
Industry Challenges
- Gold-free barrier metallization:REACH-compliant RoHS alternatives require process requalification that extends automotive approval cycles by 12-18 months.
- EMI suppression integration:Higher switching frequencies demand co-design of rectifier snubber networks with magnetics, straining legacy power supply engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrafast Rectifiers Market |
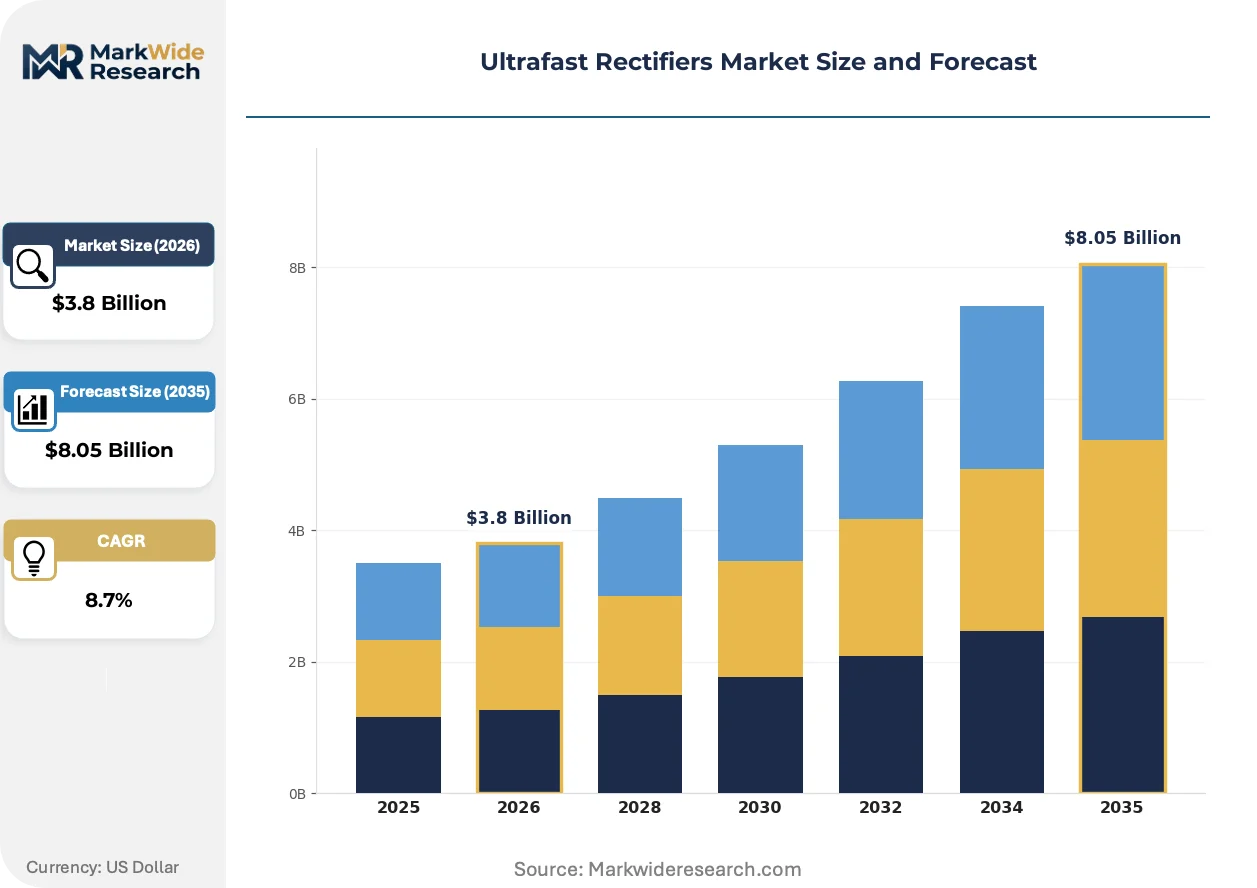
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Carbide, Gallium Nitride, Silicon, Hybrid Application: Power Supplies, Electric Vehicles, Renewable Energy, Consumer Electronics End User: Industrial Automation, Telecommunications, Automotive, Aerospace Technology: Switching Devices, Converter Design, Control Architecture, Energy Harvesting |
| Companies Covered | Vishay Intertechnology, Diodes Incorporated, Infineon Technologies, Nexperia, Littelfuse, ON Semiconductor, ROHM Semiconductor, IXYS, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrafast Rectifiers Market Evolving Landscape
Silicon carbide and gallium nitride substrates are fragmenting the traditional silicon-dominant supply base while regulatory pressure on efficiency and traceability tightens design constraints.
Silicon carbide ultrafast rectifiers are consolidating their position in electric vehicle onboard chargers and traction inverters where thermal budgets are tight. Automotive OEMs in Germany and the United States are qualifying these devices for 800-volt architectures at compressed timelines. This substrate shift is consolidating procurement decisions around suppliers with captive SiC crystal growth and automotive qualification depth.
EPA energy-efficiency standards for external power supplies are forcing adapter manufacturers to abandon standard recovery diodes in favor of sub-50-nanosecond devices. The regulations mandate minimum active-mode efficiency thresholds that legacy rectifier topologies cannot meet without excessive heat sinking. Consumer electronics OEMs in China and Taiwan are redesigning 65-watt and above adapters to comply, pushing silicon-based ultrafast variants into volume dominance.
Direct sourcing contracts between automotive OEMs and qualified rectifier suppliers are disintermediating traditional distribution channels for high-reliability grades. Tier-one inverter manufacturers in the United States and Germany now require material traceability and lot-specific reliability data that distributors cannot provide. This channel compression is most visible in traction inverter procurement, where buyers negotiate multi-year supply agreements with substrate-level visibility.
Ultrafast Rectifiers Market Segmentation
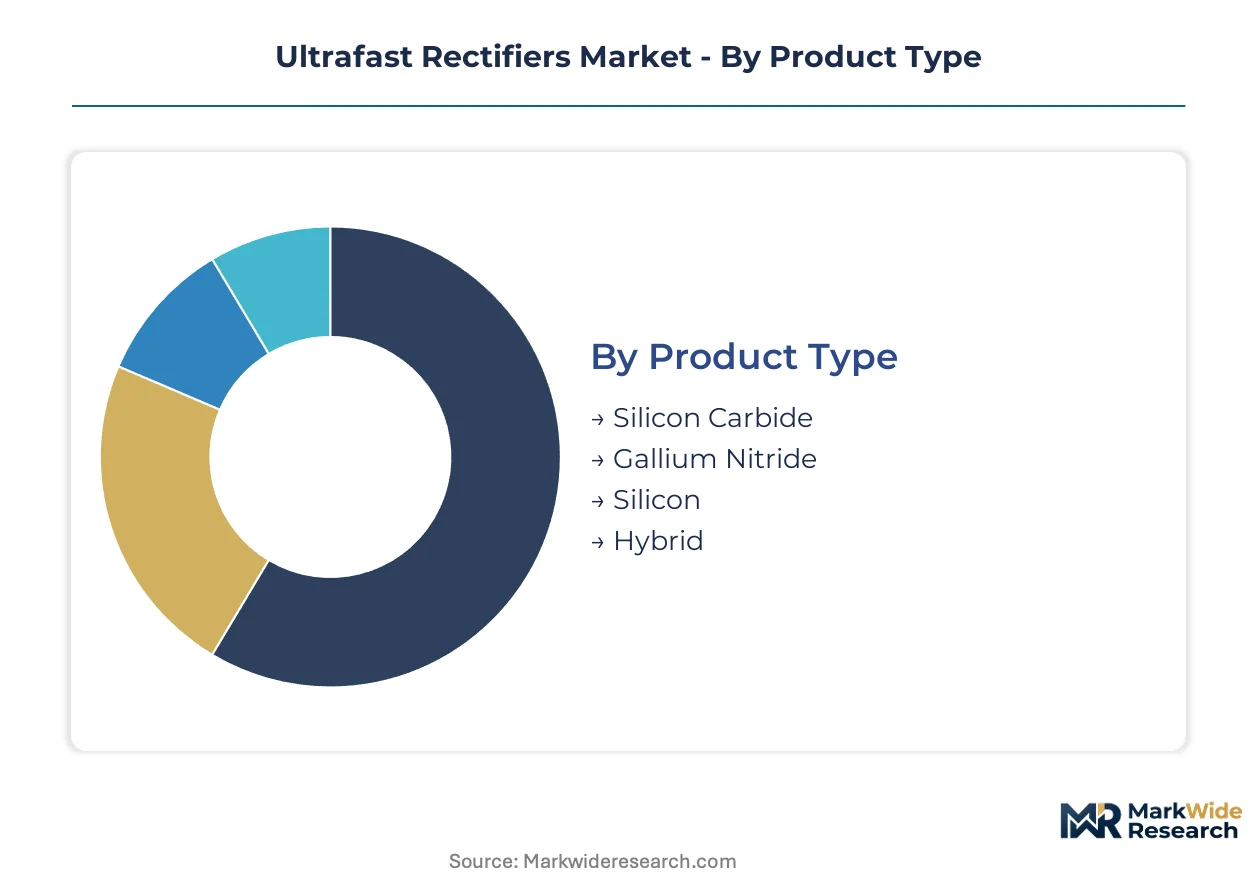
Ultrafast rectifier procurement diverges sharply across substrate technologies and end-use thermal budgets. Product selection hinges on switching frequency requirements, voltage class, and qualification depth for automotive or industrial safety standards.
Product Type:
Silicon retains volume dominance while compound semiconductors capture premium positioning in high-frequency, high-temperature applications.
- Silicon:Epitaxial silicon devices with platinum-doped junctions deliver reverse recovery times of 25-50 nanoseconds. Consumer electronics adapter manufacturers in China and Taiwan source these for 65-watt and above designs under EPA energy-efficiency mandates.
- Silicon Carbide:Wide-bandgap substrates enable operation above 175°C with recovery times below 25 nanoseconds. German and US automotive OEMs qualify these for 800-volt traction inverters where thermal budgets are tight.
- Gallium Nitride:Highest switching frequencies beyond 500 kilohertz suit telecom server power supplies.
- Hybrid:Multi-die packages combining silicon control with SiC rectification target cost-sensitive industrial motor drives.
Mature deployment sits with Silicon. Newer deployment is concentrated in Silicon Carbide.
Application:
End-use thermal constraints and regulatory efficiency floors determine substrate selection and device architecture.
- Power Supplies:External adapter manufacturers redesign around sub-50-nanosecond devices to meet EPA active-mode efficiency thresholds. Gallium nitride variants are expanding most quickly in datacenter server racks.
- Electric Vehicles:Onboard chargers and traction inverters demand automotive-qualified devices with lot-specific reliability data. 800-volt architectures favor silicon carbide for reduced switching losses.
- Renewable Energy:Solar inverters in Arizona and Texas source devices qualifying for US IRA domestic content credits.
- Consumer Electronics:Cost floors dominate; silicon ultrafast devices retain share in smartphone and laptop adapters.
Volume procurement centers on Power Supplies. Technology migration is fastest in Electric Vehicles.
End User:
Qualification depth and supply chain visibility requirements vary dramatically across customer categories.
- Automotive:ISO 26262 functional-safety protocols propagate from power modules to discrete rectifier qualification. Direct sourcing contracts disintermediate distribution for traction inverter procurement.
- Telecommunications:Base station power supplies and hyperscale datacenters drive gallium nitride adoption above 500 kilohertz switching frequencies.
- Industrial Automation:Space-constrained motor drives favor system-in-package formats integrating ultrafast diodes with gate-driver ICs.
- Aerospace:Radiation-hardened variants with extended temperature ranges serve satellite power conditioning.
Qualification rigor peaks with Automotive. Procurement velocity is highest in Telecommunications.
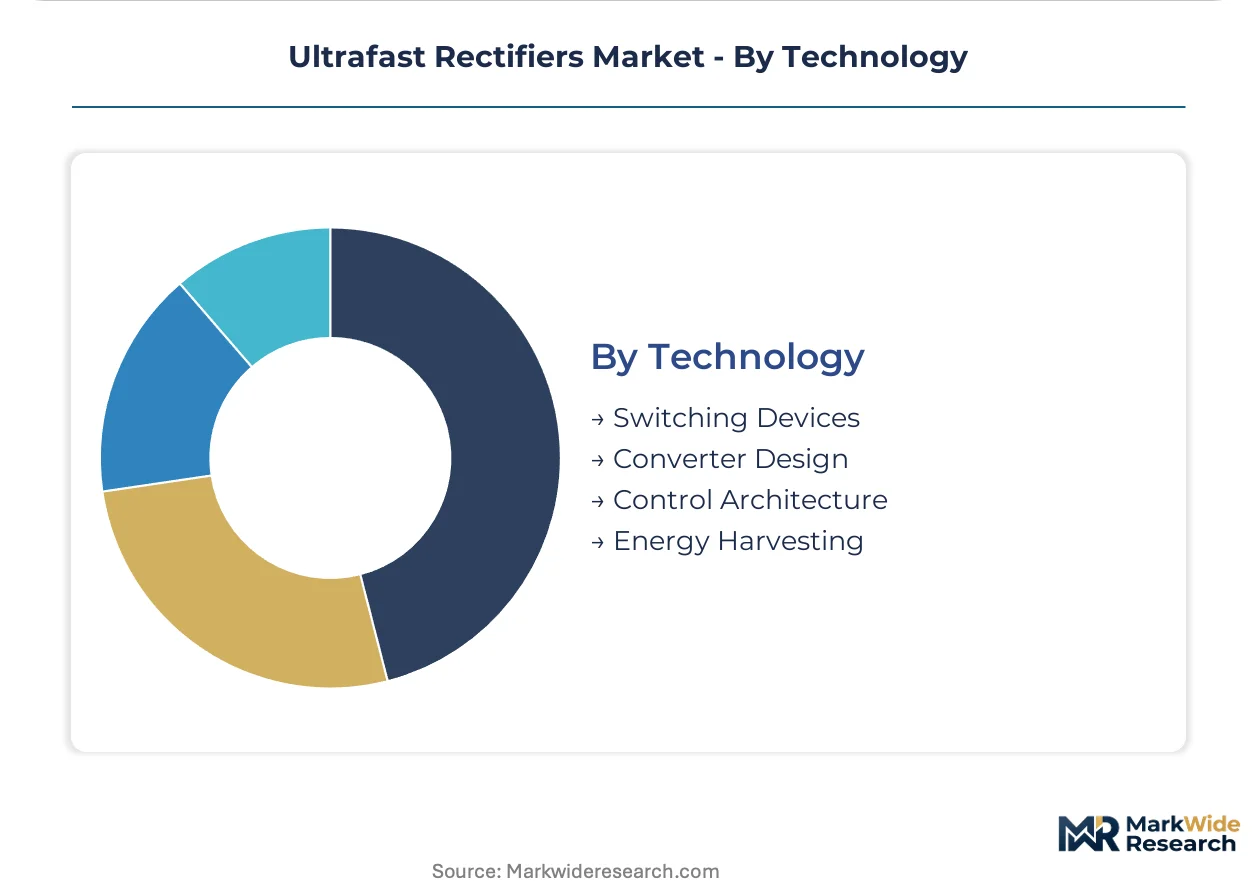
Technology:
Device-level innovation increasingly co-depends on system-level integration and control architecture.
- Switching Devices:Discrete ultrafast diodes remain the baseline, though module integration is accelerating.
- Converter Design:Resonant and soft-switching topologies reduce rectifier stress, enabling higher frequency operation.
- Control Architecture:Digital power management ICs synchronize rectifier switching with synchronous FETs for loss reduction.
- Energy Harvesting:Low-leakage ultrafast devices capture ambient vibration and thermal gradients in industrial IoT sensors.
Commercial maturity rests with Switching Devices. Architectural innovation is concentrated in Control Architecture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in China, Germany, and the United States concentrate procurement of ultrafast rectifiers, with renewable inverter manufacturers in Arizona and Texas and the Yangtze River Delta adding industrial volume.
China
Domestic EV OEMs and renewable inverter manufacturers source directly from qualified suppliers, bypassing traditional distribution channels. MIIT dual carbon goals accelerate onboard charger efficiency mandates. Procurement concentrates in the Yangtze River Delta cluster where tier-one inverter manufacturers negotiate multi-year supply agreements.
Germany
Automotive OEMs qualify silicon carbide devices for 800-volt traction inverters at compressed timelines. EU Green Deal carbon-border adjustments force design upgrades across European supply chains. Bavaria-based power module manufacturers propagate ISO 26262 functional-safety requirements down to discrete rectifier qualification protocols.
United States
Solar inverter builders in Arizona and Texas reshape sourcing calculus around US IRA domestic content credits. EPA energy-efficiency standards for external power supplies mandate sub-50-nanosecond devices in consumer electronics adapters. Greater Phoenix and Austin metro areas attract clean energy manufacturing investments with tax incentives.
Japan
Six-inch silicon carbide substrate output remains captive to a handful of Japanese suppliers, creating allocation bottlenecks for device fabricators. METI industrial policy supports wide-bandgap semiconductor supply chain security. Kyushu-based crystal growth facilities anchor substrate supply for automotive qualification programs.
India
Production-linked incentives for semiconductor packaging attract rectifier assembly investments to Gujarat and Karnataka. BIS standards alignment with RoHS and REACH pushes manufacturers toward gold-free barrier metallization schemes. Ahmedabad and Bengaluru industrial corridors host emerging backend facilities serving domestic automotive and industrial demand.
Ultrafast Rectifiers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue gallium nitride substrate migration and system-in-package integration. The supplier base stratifies across captive substrate growers, fabless device designers, and integrated power module builders. Three archetypes dominate: silicon carbide substrate specialists with automotive qualification depth, silicon legacy players serving cost-sensitive consumer electronics, and compound semiconductor innovators targeting telecom frequencies. Competitive moves center on backward integration into epitaxial wafer supply and strategic partnerships for gate-driver co-design.
Within the integrated device manufacturer tier, Vishay Intertechnology and Infineon Technologies exemplify scale-driven positioning across multiple voltage classes. STMicroelectronics occupies a position emphasizing system-level integration. Among Japan-based substrate suppliers, ROHM Semiconductor anchors the silicon carbide supply chain. These named entities represent archetype diversity rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Vishay Intertechnology |
| Diodes Incorporated |
| Infineon Technologies |
| Nexperia |
| Littelfuse |
| ON Semiconductor |
| ROHM Semiconductor |
| IXYS |
| STMicroelectronics |
| Others |
Value Network & Pricing Analysis
Automotive OEM mandates for lot-specific reliability data and material traceability are compressing procurement channels and forcing suppliers to absorb qualification costs, which stratifies pricing power across captive substrate growers and fabless device designers.
Pricing Analysis
Volume procurement of silicon-based devices for consumer electronics adapters runs on thin margins, while silicon carbide variants for 800-volt traction inverters capture premium positioning through automotive qualification depth. Price differentiation hinges on ISO 26262 certification tier and captive six-inch substrate supply. Cost compression in silicon tiers is intensifying because EPA efficiency mandates are forcing redesign cycles. Consumer electronics OEMs in China exhibit highest price sensitivity; German automotive OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
Specialized epitaxial growth technicians in Japan, Germany, and the United States constrain capacity expansion for silicon carbide substrate production. The supply chain draws from platinum-doped barrier metallization, six-inch SiC wafers, and gold-free packaging materials. Single-source vulnerability concentrates in Kyushu-based crystal growth facilities. Distribution runs through direct long-term contracts for automotive grades, with spot market fragmentation in consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where backward integration into epitaxial wafer supply separates price-setters from price-takers.
For Market Incumbents: To counter gallium nitride substrate migration by telecom power supply designers, lock in six-inch SiC wafer offtake agreements with Japanese suppliers and accelerate gate-driver IC co-design partnerships with tier-one inverter manufacturers.
For New Entrants and Emerging Players: US IRA domestic content credits in Arizona and Texas open a window for solar inverter-focused device qualification without automotive ISO 26262 burden. Target renewable energy procurement in Greater Phoenix and Austin metro areas. Lead with US-origin material traceability as your go-to-market wedge.
For Investors and Strategic Acquirers: The window for entry favors compound semiconductor packaging specialists with existing automotive qualification infrastructure. Five-to-ten year viability rests on substrate-level backward integration or exclusive gate-driver integration IP. Watch silicon carbide substrate allocation announcements from Japanese suppliers as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Supply | Captive six-inch wafer supply insulates margin buffers against Japanese supplier allocation decisions. |
| Gate-Driver IC Co-Design Partnership | System-in-package integration with STMicroelectronics or Infineon anchors premium positioning in motor drives. |
| Automotive ISO 26262 Certification Investment | Functional-safety qualification depth unlocks 800-volt traction inverter procurement with German OEMs. |
| Gold-Free Barrier Metallization Process Shift | REACH-compliant RoHS alternatives preempt regulatory disqualification from EU automotive supply chains. |
| India PLI Scheme Assembly Investment | Gujarat and Karnataka packaging capacity captures cost advantages for industrial automation segments. |
Research Methodology
Document review covered SEC 10-K filings, ECHA REACH substance registrations, and MIIT dual carbon policy documents, complemented by interviews with tier-one inverter procurement managers, automotive platform engineers, epitaxial wafer process engineers, and power supply design leads. Secondary validation drew from EPA energy-efficiency rulemaking dockets, EU Green Deal carbon-border adjustment proposals, and customs trade data for semiconductor device categories. Bottom-up and top-down triangulation reconciled device shipment estimates with end-use application demand.
Segment-level value outputs across the projection horizon reflect substrate technology, voltage class, end-use thermal budget, and automotive qualification tier. CAGRs were derived from regression analysis of historical procurement patterns against regulatory mandate implementation timelines. Forecast inputs incorporated MIIT dual carbon goal acceleration curves and US IRA domestic content credit qualification thresholds.
The model assumes a particular technology adoption path; alternative pathways for gallium nitride substrate migration in telecom server power supplies would alter the outlook. Forecasts reflect assumptions about silicon carbide substrate supply expansion and ISO 26262 propagation timelines. Material deviation in Japanese substrate allocation announcements or EPA efficiency mandate enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
USB Power Adapters Market
Power Systems
Global Pin Fin Heat Sink for IGBT Market
Power Systems
High Voltage Ceramic Zinc Oxide Surge Arrester Market
Power Systems
Vehicle Inverter Market
Power Systems
Transformer Tap Changers and Voltage Control Relay Market
Power Systems
Solid State Transformer Market
Power Systems
AC DC Power Adapter Market
Power Systems
Gan-Powered Chargers Market
Power Systems
Buck-Boost Controller Market
Power Systems
DC-DC Converter Market
Power Systems
US Variable Frequency Drive Market
Power Systems
South America Battery Management System Market
Power Systems
Shunt Reactor Market
Power Systems
Integrated UPS Market
Power Systems
North America Micro Inverter Market
Power Systems
Series Reactor Market