
 Camera Battery Charger Market | 2026-2036
Camera Battery Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Camera Battery Charger Market Insights
Market Context
Lithium iron phosphate is repositioning product economics in charger power management circuits, offering thermal stability that reduces enclosure material costs. Canon leverages captive battery ecosystems to sustain aftermarket charger attachment rates. Sony anchors premium positioning through proprietary fast-charging protocols that lock in professional user bases. Neewer competes on cross-brand compatibility, dominating the third-party replacement segment through aggressive channel control on marketplace platforms.
Technical Definition and Segment Structure
A camera battery charger is an electronic device designed to restore electrochemical energy to lithium-ion or lithium-polymer cells through controlled voltage and current delivery, typically operating at 4.2V per cell with CC-CV charging profiles to prevent thermal runaway. Its primary commercial purpose is to support continuous image capture workflows by minimizing downtime between battery depletion cycles. Dual chargers lead product type revenue pools by serving professionals running multi-body rigs, while solar chargers represent the fastest-growing category as expedition videographers seek off-grid power autonomy. Smart charging technology commands margin concentration through microcontroller-based battery health monitoring that extends cell cycle life.
Regulatory Environment
The EU Green Deal and REACH chemical restrictions are reshaping charger material compliance, specifically limiting halogenated flame retardants in plastic housings sold across member states. The USB Implementers Forum Power Delivery specification, alongside China's GB standards for lithium-ion safety, is converging to standardize input architectures and reduce proprietary adapter proliferation. Stakeholders must monitor whether regulatory momentum behind universal charging mandates forces proprietary connector abandonment in premium product tiers.
Market Dynamics
USB-C Power Delivery standardization is dissolving proprietary charging protocols that locked users into OEM ecosystems, forcing incumbents to open architectures or cede aftermarket share to cross-compatible rivals.
Growth Catalysts
- Mirrorless camera refresh cycles:Professional content creators operating multi-body rigs require redundant charging infrastructure, expanding addressable charger volumes per user.
- EU Green Deal material mandates:Halogen-free flame retardant requirements are accelerating redesigns toward recyclable enclosures that reduce long-term compliance costs.
- Lithium iron phosphate thermal stability:This chemistry enables simplified power management circuits that cut enclosure engineering expenses and improve safety margins.
Market Restraints
- Lithium-ion cell supply concentration:China's dominance over cathode active material refining creates input cost volatility and geopolitical exposure for non-domestic charger manufacturers.
- REACH chemical registration burdens:European substance compliance timelines extend product launch cycles and raise fixed regulatory costs for smaller participants.
- Smartphone imaging substitution:Computational photography advances in flagship handsets reduce casual camera ownership, compressing entry-level charger demand.
Strategic Opportunities
- Expedition videography off-grid demand:Solar-integrated chargers address Antarctic, Patagonian, and Himalayan production crews seeking autonomous power.
- India PLI scheme localization:Domestic assembly incentives for electronics manufacturing attract charger OEMs to establish regional production bases.
- USB-IF PD 3.1 convergence:240W universal power contracts enable single-cable workflows across cameras, lighting, and laptops, consolidating accessory ecosystems.
Industry Challenges
- GB 31241 certification timelines:China's lithium-ion safety standard requires extended testing protocols that delay product market entry.
- Legacy proprietary connector inventory:Manufacturers holding obsolete SKUs face write-down pressure as USB-C adoption accelerates across professional segments.
- Microcontroller firmware validation:Smart charging health monitoring algorithms demand specialized embedded engineering talent that concentrates in Shenzhen and Taipei.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camera Battery Charger Market |
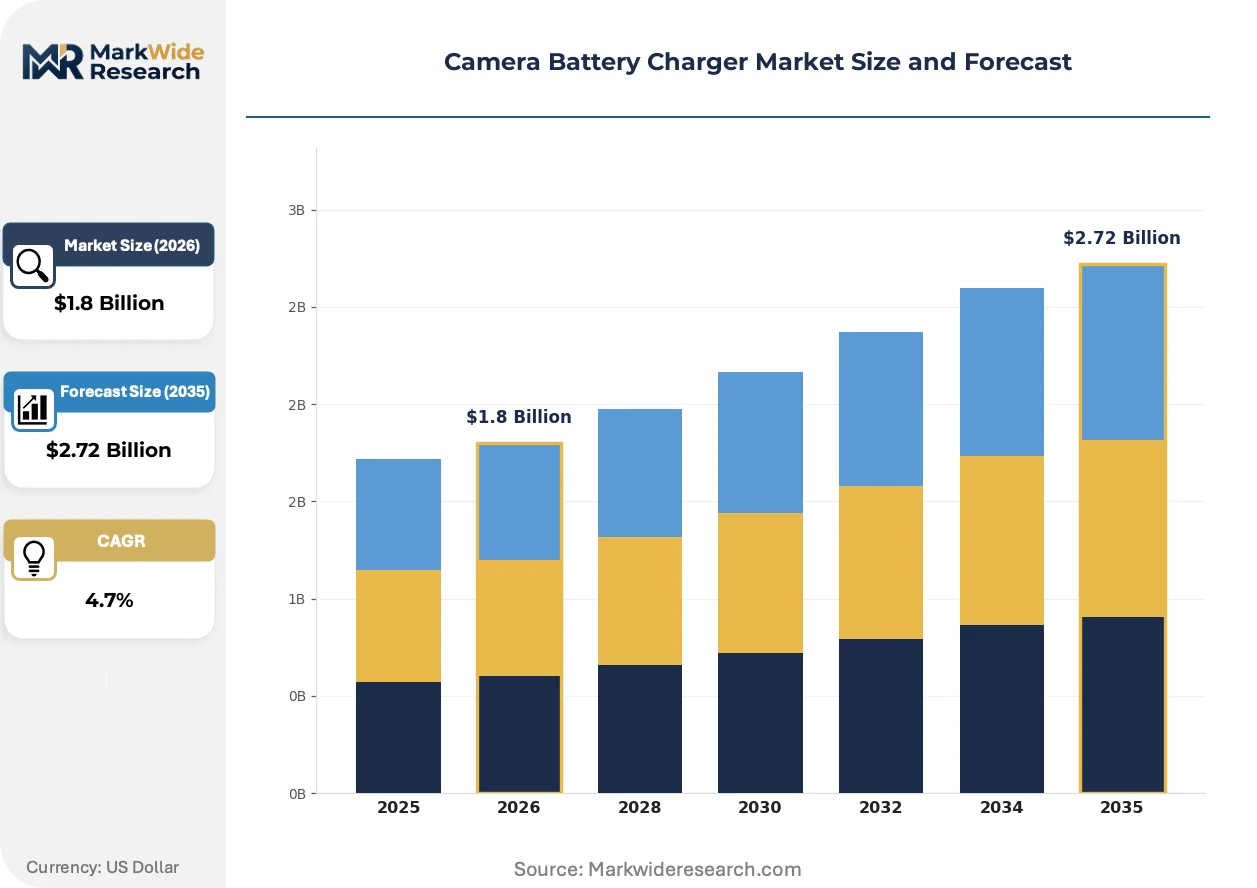
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual Chargers, Multi Chargers, Solar Chargers, Portable Chargers Technology: Smart Charging, Quick Charge, Pulse Charging, Conventional Charging End User: Photography Professionals, Enthusiasts, Videographers, Retailers Distribution Channel: Online Retail, Electronic Stores, Specialty Shops, Supermarkets |
| Companies Covered | Canon, Sony, Nikon, FUJIFILM, Panasonic, Olympus, Neewer, Sigma, hahnel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camera Battery Charger Market Trends and Innovations
Gallium nitride power semiconductors and universal charging mandates are compressing charger form factors while dissolving ecosystem lock-ins that structured historical profit pools.
GaN transistors are absorbing switching losses that previously demanded bulky heatsinks and ventilation channels. Expedition videographers and wedding cinematographers now pack 100W chargers into pocketable dimensions. This compression is absorbing the premium that OEMs historically commanded through proprietary fast-charging protocols.
REACH chemical restrictions and RoHS substance limits are forcing halogenated flame retardant replacement with phosphorus-based alternatives. Housing material reformulation extends supplier qualification cycles by months. Professional-tier manufacturers with captive polymer engineering capabilities absorb these delays faster than contract-dependent competitors.
Direct-to-operator sales through marketplace platforms are unbundling traditional distributor markups. Independent content creators now compare third-party compatibility specifications before purchase. This channel shift concentrates in China and Southeast Asia where domestic brands control lithium cell supply and price aggressively for export markets.
Camera Battery Charger Market Segmentation
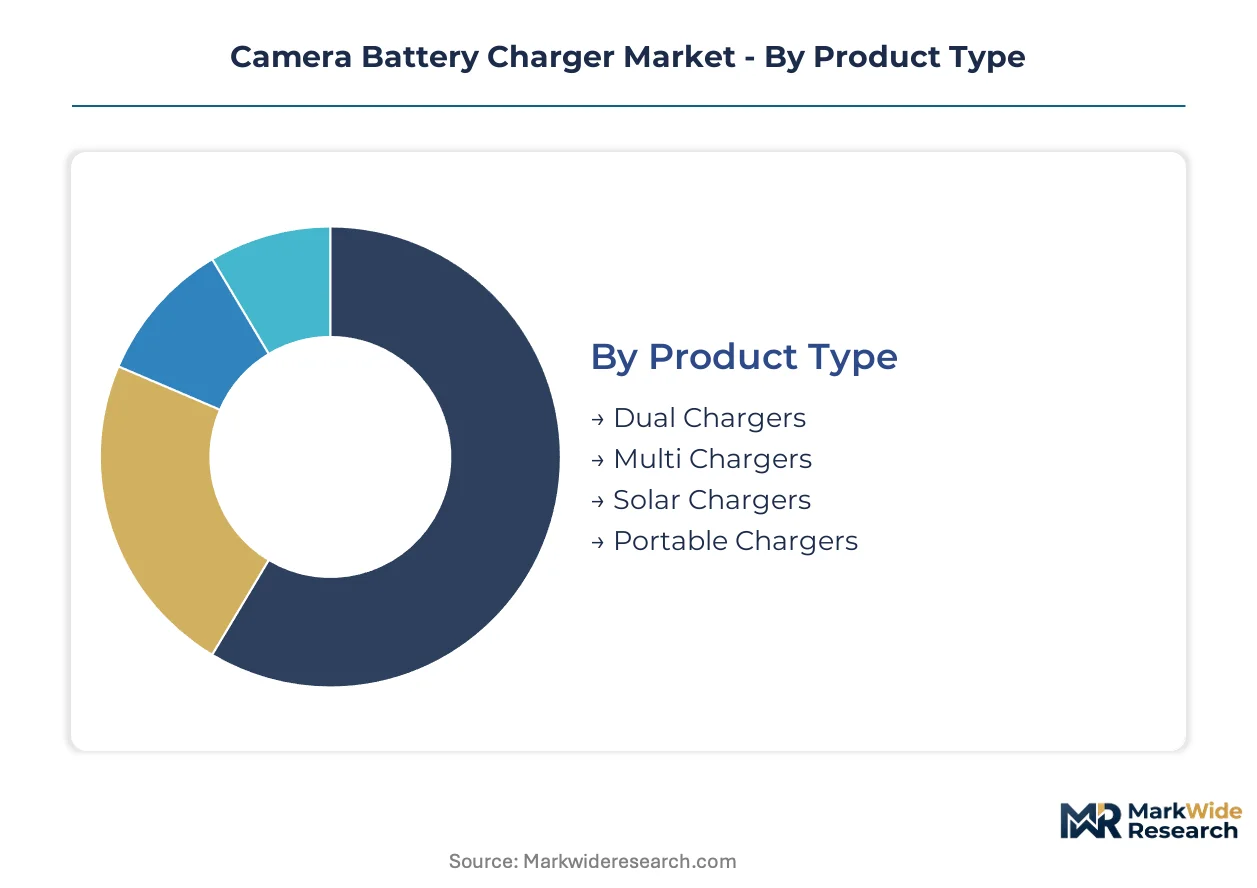
Segmentation in camera battery chargers reveals how capital deployment, technical sophistication, and channel economics fragment addressable demand. Each dimension exposes distinct margin structures and competitive entry barriers that shape manufacturer positioning.
Product Type:
Capital intensity peaks in multi-charger configurations requiring complex power distribution architectures and thermal management systems.
- Dual Chargers:Two-bay designs dominate professional workflows, enabling simultaneous charging of redundant battery sets for multi-body mirrorless rigs. Wedding cinematographers in the United States and commercial studios in Germany concentrate procurement here, driven by downtime minimization requirements during high-value shoots.
- Solar Chargers:Photovoltaic-integrated units with MPPT controllers and weatherproof enclosures serve Antarctic documentary crews and Himalayan expedition videographers seeking off-grid autonomy. Demand climbs fastest in Patagonian and Alaskan production markets where generator weight penalties prove prohibitive.
- Multi Chargers:Four-to-eight bay rack systems with sequential charging logic address rental houses and broadcast fleet operators.
- Portable Chargers:Compact single-bay units with USB-C PD input target travel photographers prioritizing luggage weight constraints.
Most installed capacity flows through Dual Chargers. Expansion is steepest in Solar Chargers.
Technology:
Margin stratification follows firmware complexity, with microcontroller-dependent tiers commanding premium positioning against analog baseline products.
- Smart Charging:Microcontroller-based CC-CV profiles with temperature-compensated voltage termination and cycle count logging extend lithium-ion cell longevity. Professional content creators in Japan and South Korea absorb price premiums for health monitoring that protects battery investments exceeding charger costs by 10x.
- Quick Charge:Elevated current delivery protocols reduce charge intervals by 40-60% for deadline-pressed news photographers and sports videographers. Thermal engineering requirements and GaN semiconductor costs concentrate supply among Shenzhen and Taipei engineering clusters with embedded firmware expertise.
- Pulse Charging:Intermittent current modulation claims sulfation reduction benefits for nickel-chemistry legacy compatibility.
- Conventional Charging:Fixed-voltage linear regulators serve price-sensitive replacement markets with minimal feature differentiation.
Revenue concentrates in Smart Charging. Volume expansion runs strongest in Quick Charge.
End User:
Customer archetypes diverge sharply in price sensitivity, technical specification engagement, and replacement frequency.
- Photography Professionals:Full-time commercial shooters operating Canon, Sony, and Nikon systems demand OEM protocol compatibility and warranty preservation. Studios in California and Bavaria maintain redundant charger inventories per camera body, multiplying per-user addressable volume.
- Videographers:Cinema production crews with Blackmagic and RED rigs prioritize 240W USB-PD convergence for lighting and monitor consolidation. Documentary specialists in New Zealand and Norway drive solar-integrated demand for remote location autonomy.
- Enthusiasts:Serious amateurs with single-body mirrorless setups balance aftermarket price savings against compatibility risk tolerance.
- Retailers:Camera store chains and rental houses stock breadth SKUs for walk-in replacement demand with minimal technical consultation.
Photography Professionals anchor revenue per user. Videographers drive technology migration fastest.
Distribution Channel:
Channel economics determine margin capture, with direct-to-operator platforms compressing traditional distributor markups.
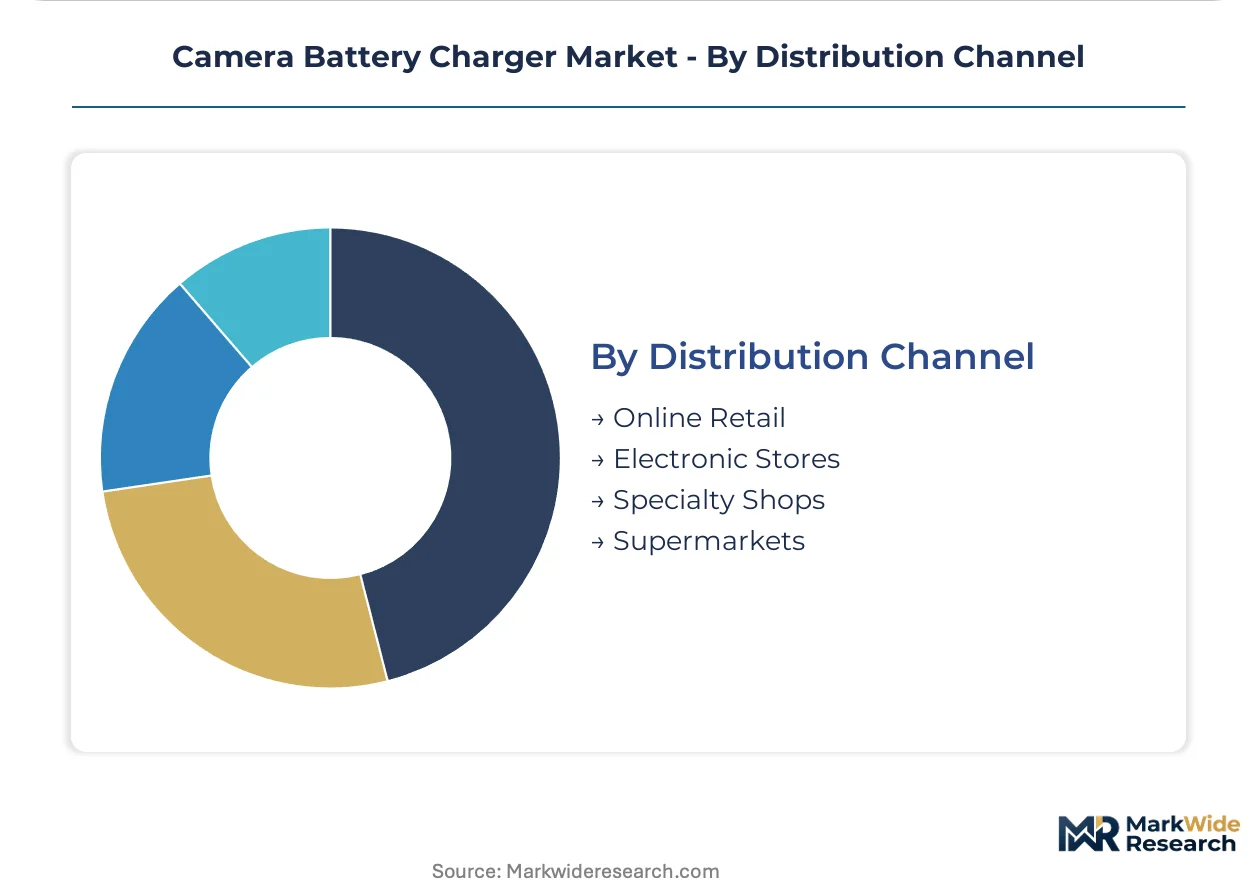
- Online Retail:Marketplace platforms and direct-brand storefronts enable specification comparison across compatibility databases. Independent content creators in China and Southeast Asia concentrate here, where domestic manufacturers control lithium cell supply and price aggressively for export markets.
- Electronic Stores:Big-box retailers with dedicated camera departments provide immediate replacement for failed chargers during critical shoots. Staff technical knowledge varies, pushing informed buyers toward online research.
- Specialty Shops:Independent camera retailers with repair services bundle charger sales with battery health diagnostics.
- Supermarkets:Mass-merchandise incidental placement captures emergency replacement demand from casual users.
Transaction volume concentrates in Online Retail. Specialty Shops retain premium-tier attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor anchors global charger production, with lithium-ion cell supply chains and GaN semiconductor fabrication clustering in the Pearl River Delta. Professional content creators in Los Angeles, Munich, and Tokyo drive differentiated demand across three distinct regulatory environments.
United States
Wedding cinematographers in California and commercial studios in New York Metro sustain dual-charger procurement for multi-body mirrorless rigs. FCC equipment authorization requirements govern RF emissions from smart charging microcontrollers. Austin and Seattle engineering hubs concentrate firmware talent for USB-PD protocol implementation.
China
Domestic manufacturers control cathode active material refining and drive cost-efficient production for export markets. GB 31241 lithium-ion safety standards mandate extended testing protocols that filter out smaller participants. Dongguan and Shenzhen assembly plants supply cross-compatible chargers to marketplace platforms serving Southeast Asia.
Germany
Bavarian broadcast fleet operators and Berlin rental houses demand rack-system multi-chargers with sequential charging logic. REACH chemical restrictions and RoHS substance limits accelerate halogen-free flame retardant adoption in housing materials. Stuttgart polymer engineering clusters absorb supplier qualification delays faster than contract-dependent competitors.
Japan
Professional content creators in Tokyo and Osaka absorb price premiums for health monitoring that protects battery investments exceeding charger costs. METI energy efficiency guidelines shape standby power requirements for charging systems. Nagoya industrial corridors host precision molding operations for compact GaN-based enclosures.
India
PLI scheme localization incentives attract charger OEMs to establish regional assembly bases for domestic and export markets. BIS certification requirements create compliance timelines that favor established participants with regulatory affairs capabilities. Tamil Nadu electronics manufacturing zones attract component suppliers from Shenzhen ecosystems.
Camera Battery Charger Market Competitive Landscape
Global majors compete with regional champions across ecosystem lock-in versus cross-compatibility vectors. The vendor base stratifies into three tiers: OEMs with captive battery protocols, third-party specialists with aggressive marketplace pricing, and component-integrated assemblers serving private-label demand. Strategic moves concentrate on USB-C PD convergence adoption and GaN semiconductor integration for form factor compression.
Among Japanese imaging OEMs, Canon and Sony exemplify contrasting ecosystem strategies, while Neewer occupies a position within the cross-brand compatibility tier. Canon represents the proprietary fast-charging protocol archetype that locks in professional user bases through warranty preservation requirements. Sony anchors premium positioning through microcontroller-dependent smart charging implementations. Neewer exemplifies the marketplace-native competitor dominating third-party replacement segments through channel control and aggressive export pricing from Shenzhen supply bases.
| Leading Market Players |
|---|
| Canon |
| Sony |
| Nikon |
| FUJIFILM |
| Panasonic |
| Olympus |
| Neewer |
| Sigma |
| hahnel |
| Others |
Pricing and Supply Chain Analysis
Embedded firmware engineering talent clustering in Shenzhen and Taipei compresses labor-cost differentials between premium smart-charging tiers and economy-grade analog alternatives. This workforce concentration enables OEMs to maintain margin separation across product tiers despite component commoditization.
Pricing Analysis
Input-cost pass-through from lithium-ion cell cathode materials and GaN semiconductor substrates drives tiered pricing stratification across premium, standard, and economy levels. Price differentiation rests on microcontroller firmware complexity and USB-PD certification grade, with smart-charging implementations commanding substantial premiums over conventional linear regulators. Pricing pressure stems from direct-to-operator marketplace channels unbundling traditional distributor markups. Enthusiast segments exhibit highest price sensitivity, while professional videographers absorb premiums for health-monitoring features that protect battery investments.
Supply Chain Analysis
Single-source vulnerability sits with China's dominance over cathode active material refining and lithium-ion cell production. Manufacturing draws from concentrated inputs including lithium carbonate, cobalt sulfate, and gallium nitride wafers. Supply chain risk centers on geopolitical exposure to export restriction scenarios affecting non-domestic charger manufacturers. Distribution runs through marketplace platforms and direct-brand storefronts serving independent content creators, with specialty camera retailers retaining premium-tier attachment for warranty-sensitive professional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camera battery charger demand functions as a stable compounder, with mirrorless camera refresh cycles among professional content creators generating predictable replacement revenue regardless of macroeconomic volatility.
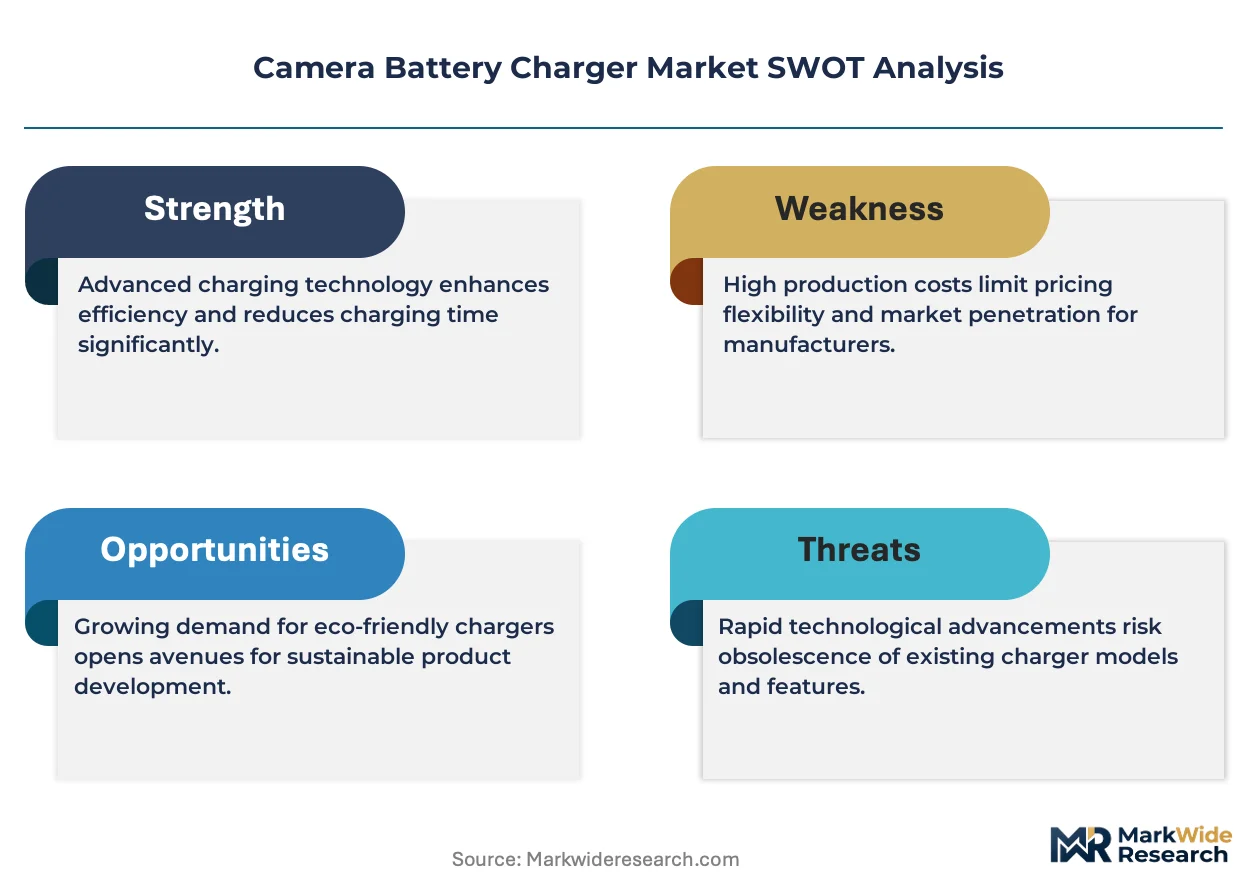
For Market Incumbents: Anticipate accelerated proprietary protocol abandonment as USB-IF PD 3.1 convergence dissolves ecosystem lock-ins that historically protected margin pools. Defensive positioning requires GaN semiconductor integration for form factor compression and captive polymer engineering capabilities to absorb REACH chemical compliance delays faster than contract-dependent rivals. Channel control investments on marketplace platforms become essential as direct-to-operator sales unbundle traditional distributor economics. For New Entrants and Emerging Players: EU Green Deal material mandates in Europe open a window for halogen-free flame retardant housing formulations that established OEMs must retrofit. White-space targets concentrate in solar-integrated chargers for Antarctic and Himalayan expedition videography, plus India PLI scheme localization for regional assembly bases. Go-to-market execution should leverage Shenzhen supply chain proximity for aggressive export pricing on cross-compatible SKUs. For Investors and Strategic Acquirers: Valuations sit cheapest among component-integrated assemblers serving private-label demand with minimal brand equity. Long-term viability over a multi-year horizon favors participants with backward integration into lithium cell supply or captive GaN semiconductor sourcing. The signal to watch is USB-C PD 3.1 adoption velocity across professional camera tiers, indicating when universal charging mandates force proprietary connector abandonment.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Integration | Enables pocketable 100W chargers that absorb premium fast-charging protocol margins. |
| REACH-Compliant Housing Reformulation | Phosphorus-based flame retardant adoption filters out contract-dependent competitors in Europe. |
| Direct-to-Operator Channel Expansion | Marketplace platform control captures specification-comparison behavior among independent creators. |
| Solar-Integrated Product Development | MPPT controller and weatherproof enclosure capabilities address Patagonian and Alaskan production markets. |
| India PLI Localization | Regional assembly bases exploit domestic electronics manufacturing incentives for export market supply. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with camera OEM product managers, third-party charger brand founders, marketplace platform category leads, and rental house procurement directors. Secondary validation draws from USB-IF certification databases, GB standards filings, REACH substance registrations, and customs trade records. Bottom-up demand modeling triangulates against top-down market sizing across professional, enthusiast, and retailer segments.
Granularity-level modeling operates at product type, charging technology, end-user archetype, and distribution channel dimensions, with additional disaggregation by regional regulatory cluster. CAGRs derive from segment-level volume projections and value-per-unit assumptions across the projection horizon. Industry-specific forecast inputs include mirrorless camera shipment trajectories, USB-C PD adoption curves, and lithium-ion cell capacity expansion timelines.
Revisions become necessary when universal charging mandates accelerate beyond current regulatory momentum, lithium supply disruptions alter input cost structures, or computational photography advances compress entry-level camera ownership faster than projected. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Robotic Flat Cable Market
Electronic Components
Stretchable Conductors in Electronics Market
Electronic Components
High Density Interconnect (HDI) PCB Market
Electronic Components
Electromechanical Timers Market
Electronic Components
Circuit Protection Kits Market
Electronic Components
High Temperature Capacitor Market
Electronic Components
Solder Paste for Mini LED Market
Electronic Components
Fixed Capacitor Market
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
Display Port Adapters Market
Electronic Components
Digital Potentiometer Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
Digital Isolator Market
Electronic Components
Global Circuit Protection Market
Electronic Components
North America USB Retimer Market