
 Voltage Regulators Market | 2026-2036
Voltage Regulators Market Size, Share, and Industry Trends Forecast 2026-2036
Voltage Regulators Market Intelligence
Modular regulator architectures paired with integrated gate drivers is broadening buyer choice across voltage classes and thermal envelopes. Texas Instruments leverages its analog foundry scale to sustain cost leadership in LDO portfolios for mobile and IoT endpoints. Infineon Technologies anchors its position through in-house production of wide-bandgap driver circuits for automotive traction inverters. STMicroelectronics differentiates via process technology leadership in silicon-on-insulator regulators for aerospace and defense channels.
A voltage regulator is an electromechanical or solid-state device that maintains a constant output voltage despite variations in input voltage or load current, typically operating within tolerance bands of one to five percent and switching frequencies from hundreds of kilohertz to several megahertz in modern implementations. Its primary purpose is to protect sensitive downstream circuitry from power fluctuations in applications ranging from microprocessor cores to grid-scale renewable inverters. Switching regulators command the largest value share due to superior thermal efficiency in data center and electric vehicle powertrains, while digital control architectures represent the fastest-expanding technology segment as firmware-configurable loop compensation replaces discrete compensation networks. The automotive end-user segment carries the highest margin pool because AEC-Q100 qualification requirements and functional safety standards create substantial barriers to supplier entry.
The US FAA and NHTSA impose electromagnetic compatibility and functional safety requirements on avionics and automotive voltage regulation subsystems, while the EU Ecodesign Framework and F-Gas Regulation indirectly shape efficiency benchmarks for power conversion equipment deployed in HVAC and industrial motor drives. China's MIIT enforces GB standards for grid-connected inverter efficiency that cascade into regulator specifications for solar and wind installations. Stakeholders must monitor divergence between regional efficiency certification regimes when configuring global product platforms.
Market Dynamics
Automotive electrification programs across Germany, Japan, and South Korea are compressing development cycles for wide-bandgap switching regulators while tightening thermal efficiency requirements for power management subsystems.
Growth Catalysts
- EU Green Deal efficiency mandates:The framework tightens minimum performance standards for power conversion equipment deployed in industrial motor drives and HVAC systems, forcing upgrades across installed bases.
- Silicon carbide MOSFET adoption:Traction inverter manufacturers in automotive supply chains are procuring matching gate-driver regulators capable of operating at higher switching frequencies with reduced switching losses.
- East Asian semiconductor clusters:Concentrated fab capacity in Taiwan and South Korea generates captive demand for precision voltage regulation in lithography and ion implantation equipment.
Market Restraints
- Wide-bandgap substrate costs:Silicon carbide and gallium nitride wafer prices remain elevated versus silicon alternatives, compressing margins in cost-sensitive consumer applications.
- Foundry concentration risk:Advanced analog process capacity concentrates at TSMC and GlobalFoundries, creating single-source vulnerability for fabless regulator designers.
- AEC-Q100 qualification timelines:Automotive functional safety certification cycles extend 18-24 months, delaying revenue recognition for new entrants targeting EV powertrains.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor assembly and test facilities create localized demand for industrial-grade regulators in captive power supplies.
- Digital control firmware:Configurable loop compensation via software-defined architectures enables single-SKU platforms serving multiple voltage classes and load profiles.
- Direct-to-OEM distribution:Automotive tier-one suppliers are bypassing traditional distributor channels for high-volume regulator procurement, compressing channel margins but deepening supplier relationships.
Industry Challenges
- Mixed-signal design talent scarcity:Expertise in analog-digital boundary optimization for digital LDOs concentrates at a handful of semiconductor design centers.
- Legacy 12V infrastructure integration:Data center and automotive 48V bus architectures must coexist with established 12V subsystems, complicating regulator portfolio rationalization.
- IP licensing fragmentation:Patent thickets around adaptive voltage scaling and dynamic frequency control create negotiation complexity for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voltage Regulators Market |
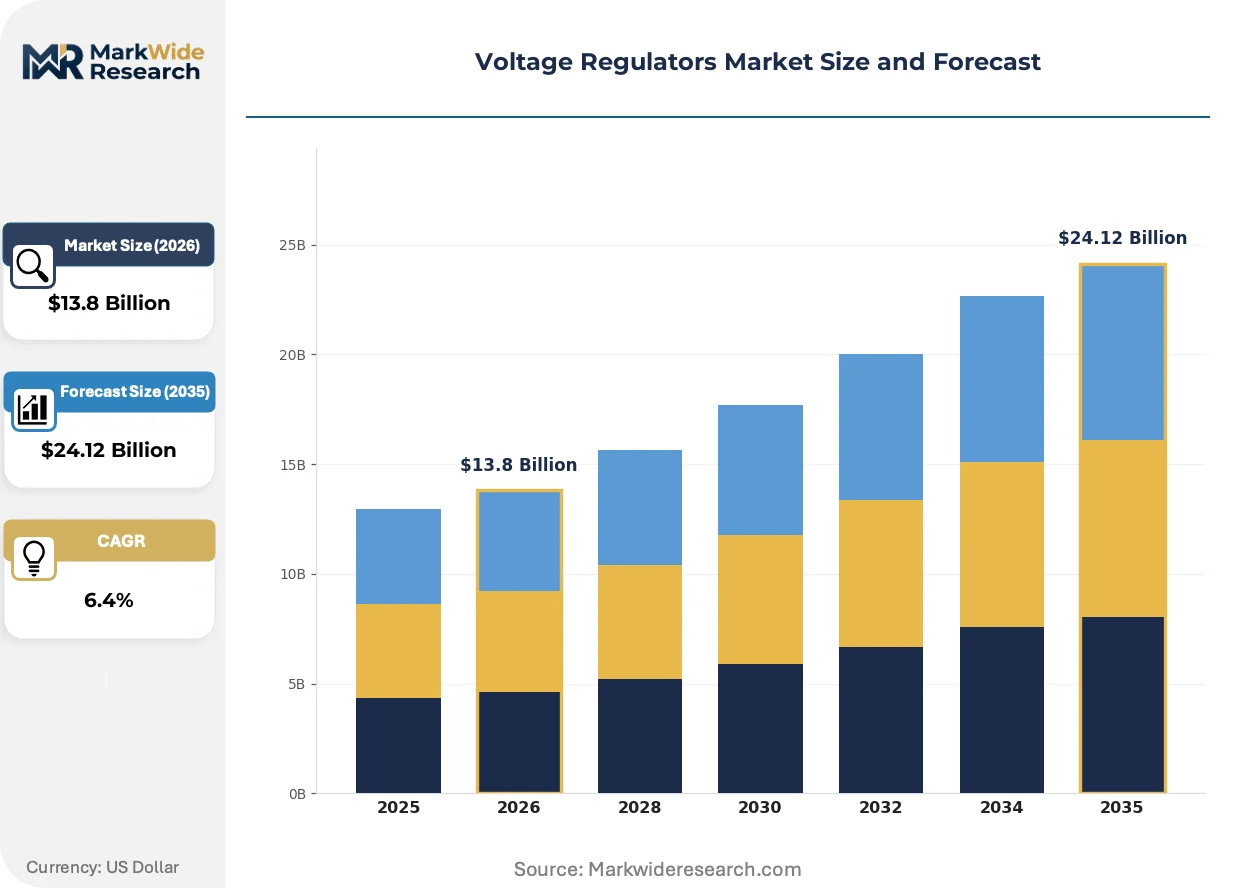
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LDO Regulators, Switching Regulators, Series Regulators, Buck-Boost Converters Technology: Linear, Digital, Analog, Hybrid End User: Consumer Electronics, Automotive Sector, Industrial Equipment, Renewable Energy Application: Power Supply, Signal Processing, Battery Management, Voltage Regulation |
| Companies Covered | Texas Instruments, Infineon Technologies, ON Semiconductor, NXP Semiconductors, STMicroelectronics, Analog Devices, ABB Ltd., Eaton Corporation, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voltage Regulators Market Strategic Shifts & Innovations
Power management architectures are fragmenting across application-specific optimization paths, with thermal envelope constraints and functional safety requirements driving divergence between consumer, automotive, and industrial implementations.
Digital LDO architectures with firmware-configurable load-line regulation are decentralizing voltage control from centralized PMICs to point-of-load stages in multi-rail processor subsystems. Mobile SoC designers in South Korea and Taiwan are adopting these distributed regulators to manage transient response requirements in AI accelerator cores. The shift is compressing the addressable market for discrete multi-output PMICs while expanding unit volumes for single-rail digital LDOs.
China's MIIT enforcement of GB standards for grid-connected inverter efficiency is cascading into regulator specifications for solar and wind installations, mandating higher conversion efficiency across input voltage ranges. Domestic inverter manufacturers are redesigning DC-link voltage regulation stages to meet these thresholds, accelerating obsolescence of legacy linear regulator designs in renewable applications. The regulatory pressure is most acute in utility-scale solar deployments where inverter efficiency directly impacts project economics.
Automotive OEMs are consolidating supplier relationships for AEC-Q100 qualified regulators, reducing qualified vendor lists from 15-20 to 5-8 strategic partners per voltage class. German and Japanese electrification programs favor suppliers with in-house wide-bandgap fabrication and integrated functional safety documentation. The concentration is visible in traction inverter procurement where single-source agreements for gate-driver regulators now span multi-year vehicle platform lifecycles.
Voltage Regulators Market Segmentation
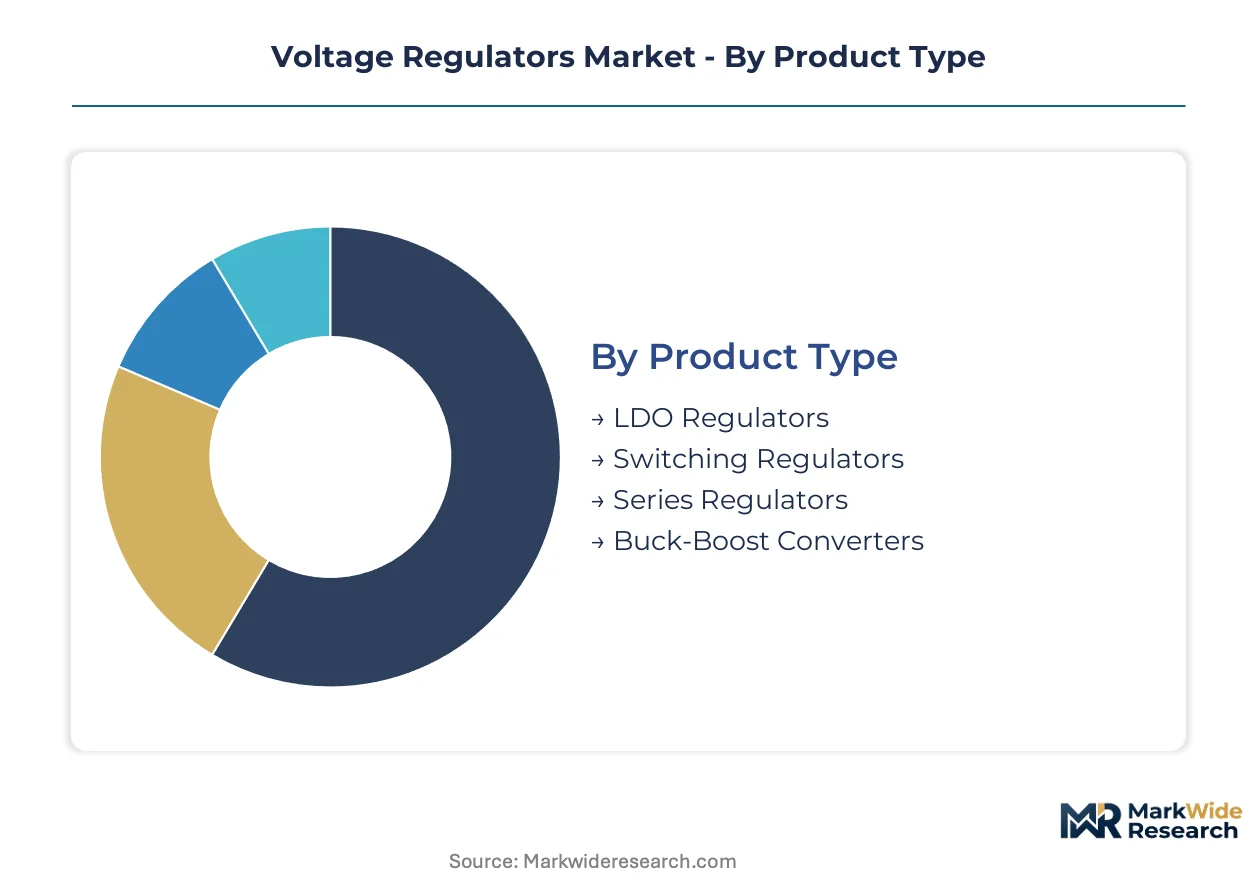
Voltage regulator architectures diverge sharply across thermal envelopes and switching frequency requirements. Product positioning depends on matching efficiency profiles to specific load transient demands in automotive traction systems, mobile SoCs, and industrial motor drives.
Product Type:
Supply concentration in wide-bandgap substrates favors suppliers with captive silicon carbide capacity for high-frequency switching variants.
- LDO Regulators:Low-dropout architectures deliver sub-100mV headroom operation for noise-sensitive analog rails in mobile camera modules and RF subsystems. Texas Instruments and STMicroelectronics dominate procurement for IoT endpoints where quiescent current below 1µA extends battery life in wearable devices from South Korean OEMs.
- Switching Regulators:Buck, boost, and buck-boost topologies achieve 90-95% efficiency through PWM control at frequencies exceeding 2MHz. Demand concentrates in German automotive 48V mild-hybrid systems and Taiwanese server power supplies where thermal density mandates synchronous rectification.
- Series Regulators:Discrete pass-element designs persist in legacy industrial 24V control systems requiring minimal EMI signature.
- Buck-Boost Converters:Seamless mode-transition architectures stabilize output across battery voltage collapse in portable medical devices and drone avionics.
Today's leader: Switching Regulators. Tomorrow's challenger: Buck-Boost Converters.
Technology:
Process node differentiation separates cost-optimized consumer solutions from automotive-qualified implementations requiring AEC-Q100 documentation.
- Linear:Simple voltage divider and pass-transistor configurations eliminate switching noise for precision instrumentation amplifiers in German factory automation. Infineon maintains foundry partnerships for 40V automotive-qualified linear portfolios serving KBA-certified engine control modules.
- Digital:Firmware-configurable loop compensation enables dynamic voltage scaling for AI accelerator cores in Samsung and TSMC-fabricated mobile SoCs. South Korean designers are displacing analog PMICs with distributed digital LDOs at point-of-load stages.
- Analog:Discrete compensation networks dominate cost-sensitive LED driver applications in Chinese consumer lighting.
- Hybrid:Mixed-signal architectures combine analog fast loops with digital supervisory control for aerospace MIL-STD-704 power quality compliance.
Digital technology is climbing the fastest as software-defined power management displaces fixed-function PMICs in advanced processor subsystems.
End User:
Margin structures vary by qualification burden, with automotive functional safety documentation commanding 40-60% price premiums over consumer equivalents.
- Automotive Sector:AEC-Q100 Grade 0 qualification and ISO 26262 ASIL-D documentation requirements restrict qualified suppliers to Infineon, NXP, and Renesas for traction inverter gate drivers. German electrification programs under KBA oversight are consolidating supplier lists to 5-8 strategic partners per voltage class.
- Consumer Electronics:High-volume smartphone and tablet procurement from Foxconn and Pegatron drives aggressive cost-down cycles for sub-1A LDOs in 5nm and 3nm processor companion chips.
- Industrial Equipment:Extended temperature range (-40°C to +125°C) specifications serve Siemens and Schneider Electric programmable logic controllers.
- Renewable Energy:China's MIIT GB standards for grid-connected inverter efficiency mandate 98.5% minimum conversion efficiency, forcing redesign of DC-link regulation stages in Sungrow and Huawei string inverters.
Automotive Sector captures the steepest margin expansion trajectory. Renewable Energy represents the fastest volume acceleration as solar and wind installations scale.
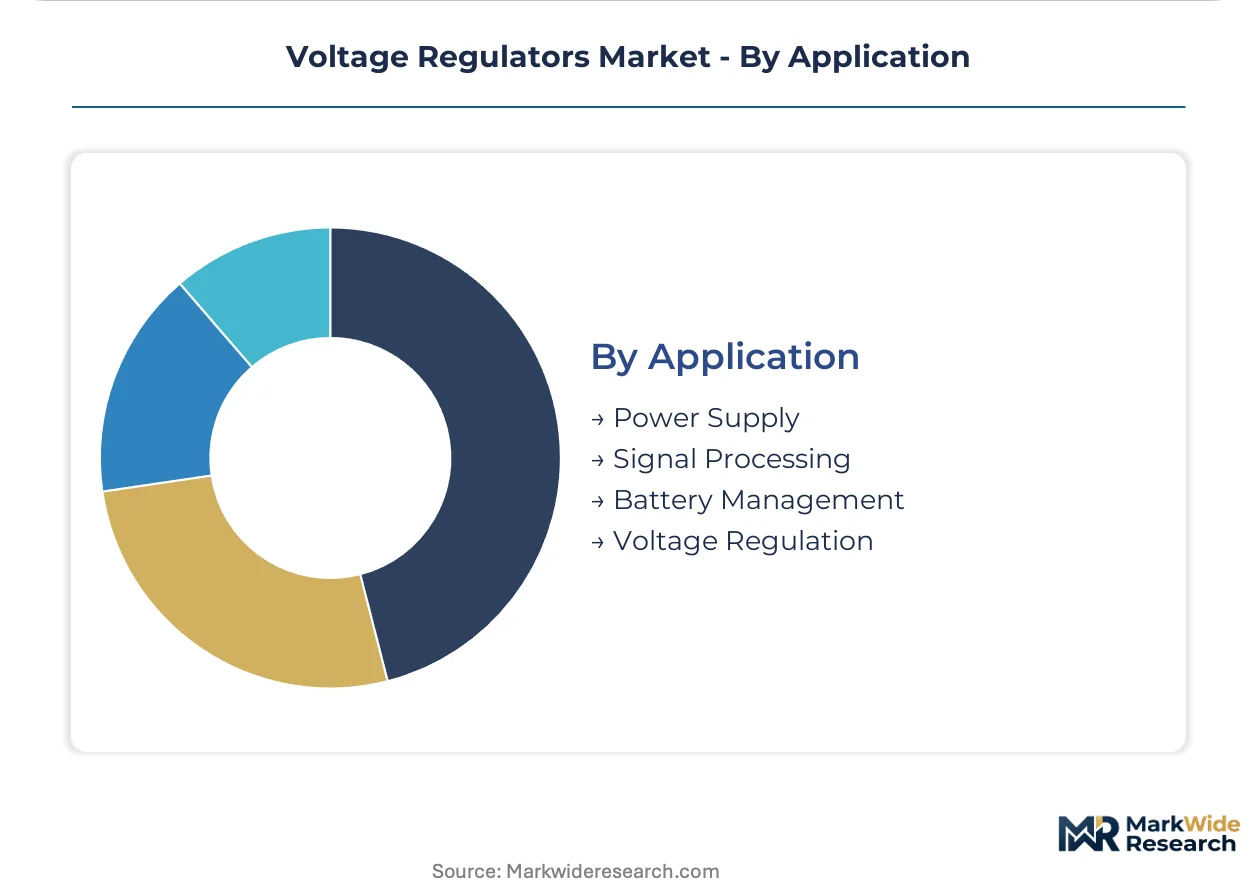
Application:
Application-specific optimization paths fragment as thermal constraints and transient response requirements diverge across end-use environments.
- Power Supply:AC-DC and DC-DC conversion stages in data center hyperscale facilities require 80 PLUS Titanium efficiency certification. Taiwanese ODMs including Delta Electronics and Lite-On procure GaN-based switching regulators for 3kW server power supplies.
- Battery Management:Cell balancing and charge termination circuits in NMC and LFP battery packs demand precision voltage references within ±0.5% tolerance across automotive temperature extremes.
- Signal Processing:Low-noise regulation for ADC reference voltages in medical imaging and test equipment.
- Voltage Regulation:General-purpose line and load regulation for distributed industrial sensor networks.
Power Supply applications anchor current procurement volumes. Battery Management is gaining share fastest as electrification expands addressable regulator content per vehicle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Voltage regulator manufacturing originated in post-war American electronics and German automotive supplier networks, then migrated to East Asian semiconductor clusters as consumer electronics scaled. Today's demand geography reflects this lineage: precision regulation for lithography equipment concentrates in Taiwan and South Korea, while automotive-grade components cluster in Germany and Japan.
Germany
KBA-certified traction inverter programs under the national electrification roadmap are absorbing wide-bandgate driver regulators at volume. The EU Green Deal's Ecodesign Framework tightens efficiency benchmarks for industrial motor drives manufactured in Bavaria and Baden-Württemberg. Stuttgart's automotive supplier corridor hosts concentrated procurement offices for AEC-Q100 qualified power management components.
China
MIIT enforcement of GB standards for grid-connected inverter efficiency is cascading into regulator specifications for utility-scale solar installations. Dual carbon goals mandate higher conversion efficiency across renewable power conversion equipment deployed in the Yangtze River Delta and Pearl River Delta. Shenzhen and Hangzhou host domestic inverter manufacturers redesigning DC-link voltage regulation stages to meet these thresholds.
United States
FAA electromagnetic compatibility requirements for avionics subsystems sustain demand for MIL-STD-704 compliant hybrid regulators. NHTSA functional safety standards compress supplier qualification timelines for automotive voltage regulation in Michigan and Ohio manufacturing corridors. Phoenix and Austin semiconductor clusters generate captive demand for precision regulation in ion implantation and lithography equipment.
Japan
METI industrial efficiency programs accelerate replacement of legacy linear regulators in factory automation systems across Kansai and Chubu manufacturing belts. JIS standards for power quality in precision instrumentation shape procurement specifications for low-noise regulation architectures. Nagoya's automotive electronics corridor concentrates tier-one supplier engineering centers for electrified powertrain development.
South Korea
MFDS medical device regulations and national semiconductor self-sufficiency initiatives are expanding domestic regulator fabrication capacity. Samsung and SK Hynix AI accelerator programs drive point-of-load digital LDO adoption in Seoul Capital Area design centers. Busan-Ulsan's packaging and test facilities generate captive demand for industrial-grade voltage regulation in process equipment power supplies.
Voltage Regulators Market Key Industry Players
Premium-margin players sit above commodity-margin players across automotive qualification burden and wide-bandgap fabrication capability. The market structures around three tiers: IDMs with captive silicon carbide capacity, analog specialists with AEC-Q100 documentation depth, and fabless designers dependent on concentrated foundry capacity. Strategic moves cluster on backward integration into substrate supply and consolidation of functional safety engineering teams for ISO 26262 certification.
Within the automotive-qualified tier, Infineon Technologies and NXP Semiconductors exemplify suppliers with in-house wide-bandgap fabrication and integrated safety documentation. Texas Instruments anchors the analog specialist position through scale in LDO portfolios for mobile and IoT endpoints. STMicroelectronics occupies a hybrid position spanning automotive traction inverters and aerospace silicon-on-insulator regulators.
| Leading Market Players |
|---|
| Texas Instruments |
| Infineon Technologies |
| ON Semiconductor |
| NXP Semiconductors |
| STMicroelectronics |
| Analog Devices |
| ABB Ltd. |
| Eaton Corporation |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
Automotive-grade AEC-Q100 certification creates a three-tier pricing structure across premium, standard, and economy levels that separates qualified suppliers from commodity competitors while concentrating supply chain control among IDMs with captive silicon carbide fabrication. This divergence manifests in 40-60% price premiums for automotive-qualified components and single-source procurement agreements spanning multi-year vehicle platform lifecycles, whereas consumer-grade LDOs compete on foundry scale and wafer cost arbitrage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with AEC-Q100 Grade 0 certification and ISO 26262 ASIL-D documentation commanding substantial premiums over consumer equivalents. Price differentiation rests on functional safety qualification burden and wide-bandgap fabrication capability, with automotive traction inverter gate drivers carrying the highest margins. Cost compression in consumer IoT LDOs is intensifying because Texas Instruments and STMicroelectronics leverage analog foundry scale for sub-1µA quiescent current portfolios. Smartphone OEMs exhibit the greatest price sensitivity, while German automotive tier-ones prioritize supplier consolidation over unit cost.
Supply Chain Analysis
End-of-life regulator refurbishment and AEC-Q100 requalification flows remain underdeveloped, creating asset recovery opportunities for specialized distributors serving industrial maintenance channels. Geographic supply concentration centers on Taiwan and South Korea for advanced analog process capacity, with Germany and Japan anchoring automotive-qualified production. Raw material dependencies include silicon carbide substrates from Wolfspeed and Coherent, gallium nitride wafers from Sumitomo Electric, and 300mm silicon wafers from Shin-Etsu and SUMCO. Single-source vulnerability at TSMC and GlobalFoundries for BCD analog processes creates foundry concentration risk. Distribution runs through Arrow and Avnet for broad-market components, while direct-to-OEM agreements dominate automotive procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's MIIT-mandated efficiency upgrades and India's PLI scheme for electronics manufacturing creates procurement cost differentials for industrial-grade regulators, with localized assembly and test facilities in Gujarat and Tamil Nadu offering 15-20% landed cost advantages over imported European alternatives.
For Market Incumbents: To counter fabless designer encroachment in digital LDO architectures, Infineon and NXP should deepen backward integration into silicon carbide substrate supply while consolidating ISO 26262 functional safety engineering teams for streamlined ASIL-D certification. Capacity addition in Dresden and Villach strengthens captive wide-bandgate driver production for German KBA-certified traction inverter programs. For New Entrants and Emerging Players: Firmware-configurable loop compensation via software-defined power management offers the most penetrable wedge against entrenched analog PMIC suppliers in South Korean AI accelerator design centers. White-space targets include point-of-load digital LDOs for Samsung and SK Hynix multi-rail processor subsystems, plus AEC-Q100 Grade 1 components for Indian automotive electrification programs. A direct engagement model with Seoul Capital Area SoC designers bypasses established distributor channels. For Investors and Strategic Acquirers: Consolidation pressure builds where mixed-signal design talent scarcity concentrates at a handful of semiconductor design centers, favoring acquisition of analog-digital boundary optimization specialists in Taiwan and South Korea. Long-term viability hinges on in-house wide-bandgap fabrication or exclusive foundry partnerships. The signal to watch is automotive OEM qualified vendor list consolidation from 15-20 to 5-8 strategic partners per voltage class, indicating which suppliers have secured multi-year platform agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Capacity Expansion | Captive substrate supply secures margin control for German automotive traction inverter procurement. |
| Digital Control Firmware Development | Software-defined loop compensation displaces fixed-function PMICs in Samsung AI accelerator cores. |
| AEC-Q100 Certification Acceleration | Compressed 12-month qualification timelines capture Indian PLI scheme incentives for local assembly. |
| Direct-to-OEM Distribution Partnership | Bypassing Arrow and Avnet deepens supplier relationships with Stuttgart automotive procurement offices. |
| Wide-Bandgap Driver Integration | Gate-driver regulator consolidation reduces BOM complexity for 48V mild-hybrid systems under KBA oversight. |
Research Approach
Multiple input streams — primary interviews with power management IC design leads, automotive tier-one procurement officers, and semiconductor foundry planning executives, plus secondary validation through SEC 10-K filings, MIIT GB standard enforcement notices, and KBA certification databases — were reconciled through bottom-up and top-down triangulation. Supply-side data drew from TSMC and GlobalFoundries capacity disclosures, while demand-side inputs incorporated Siemens and Schneider Electric programmable logic controller specifications. Cross-referencing across these sources identified divergence points between projected and actual AEC-Q100 qualification timelines.
Data-stream reconciliation anchored the analytical framework across the modeling period, with segmentation dimensions spanning product architecture, process technology, end-user qualification tier, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles for industrial motor drives under EU Ecodesign Framework mandates and electrified vehicle powertrain ramp rates in German and Japanese OEM programs. Industry-specific forecast inputs included silicon carbide MOSFET adoption curves and digital LDO penetration rates in mobile SoC designs.
The model holds under stable foundry capacity allocation and continued MIIT enforcement of grid-connected inverter efficiency standards; deviation in wide-bandgap substrate supply constraints or automotive platform delays would shift volume and value trajectories. Practitioners should monitor TSMC BCD process node allocation announcements and German KBA traction inverter procurement volumes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Power Supply Isolation Equipment Market
Power Systems
Transformer Tap Changers and Voltage Control Relay Market
Power Systems
Global Rectifier Market
Power Systems
Traction Inverter Market
Power Systems
North America Telecom Power Systems Market
Power Systems
Harmonic Generators Market
Power Systems
Global Plasma Generators Market
Power Systems
DC Stabilized Power Supply Market
Power Systems
Static VAR Compensator (SVC) Market
Power Systems
Digital Inverter Market
Power Systems
North America Micro Inverter Market
Power Systems
Global Power Semiconductor Switches Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
Modular Uninterrupted Power Supplies (UPS) Market
Power Systems
Bypass Thyristor Market
Power Systems
Surface Mounted Medium Voltage Distribution Panel Market