
 Charge Controller System Market | 2026-2036
Charge Controller System Market Size, Share, and Industry Trends Forecast 2026-2036
Charge Controller System Market Analysis
A capital-intensity divergence between vertically integrated power electronics manufacturers and assembly-focused competitors is unwinding competitive stability in charge controllers. Schneider Electric leverages captive semiconductor sourcing to sustain margin resilience across utility-scale deployments. Morningstar Corporation anchors its position through precision analog engineering for extreme-environment off-grid systems. Victron Energy competes via modular inverter-charger integration that extends product lifecycle value for marine and RV segments.
A charge controller system regulates voltage and current flow between power generation sources and battery storage, typically employing pulse-width modulation or maximum power point tracking algorithms to optimize energy harvest and prevent overcharge damage. MPPT controllers dominate value pools where array voltages exceed battery bank levels by significant margins, while PWM controllers occupy cost-sensitive residential installations with matched voltages. Off-grid installation categories concentrate margin in remote telecommunications and rural electrification projects across Africa and South Asia, whereas on-grid commercial segments navigate net-metering policy volatility in deregulated utility territories.
The IEC 62109 safety standard for power conversion equipment shapes product certification requirements across export-oriented manufacturing bases, while India's BIS mandates local testing for solar charge controllers deployed under government subsidy programs. The EU Green Deal's renewable hydrogen linkage and F-Gas Regulation phase-down are forcing controller manufacturers to architect compatibility with emerging electrolyzer DC coupling architectures. Stakeholders must monitor how battery chemistry diversification toward lithium iron phosphate and sodium-ion formats reshapes voltage regulation algorithms and thermal management specifications.
Market Dynamics
MPPT algorithm sophistication and lithium-ion battery chemistry diversification are compressing controller design cycles while forcing firmware architecture overhauls across the supply base.
Growth Catalysts
- IEC 62109-1 Safety Mandate:Export-oriented manufacturers in India and China face accelerated certification timelines to access European renewable hydrogen coupling projects under the EU Green Deal framework.
- Off-Grid Rural Electrification:India's BIS local testing requirements for solar charge controllers deployed under government subsidy programs are standardizing procurement specifications across state-level distribution companies.
- Telecommunications Infrastructure:Remote tower operators in sub-Saharan Africa are specifying MPPT controllers with wide voltage input ranges to accommodate mixed solar-diesel hybrid architectures.
Market Restraints
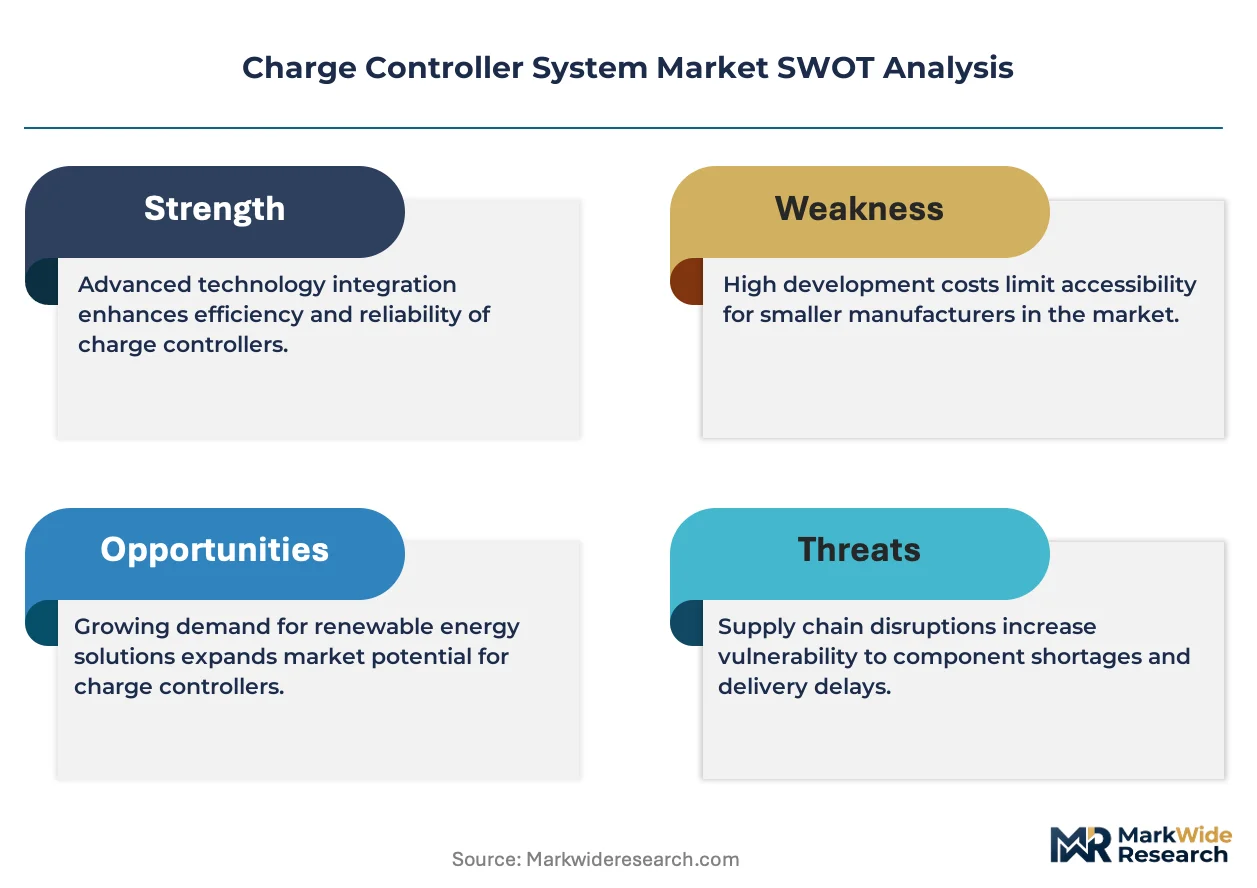
- Semiconductor Input Volatility:Power MOSFET and gate driver IC lead times from Taiwanese foundries create inventory mismatches for assembly-focused controller manufacturers lacking captive sourcing.
- Technical Voltage Ceiling Constraints:Conventional MPPT topologies face thermal dissipation limits when processing array voltages above 600VDC in utility-scale installations.
- Substitution by Integrated Inverters:String inverter manufacturers are absorbing charge control functions into hybrid units, eroding standalone controller attach rates in residential retrofit segments.
Strategic Opportunities
- Electrolyzer DC Coupling Architectures:The EU F-Gas Regulation phase-down is forcing compatibility engineering for direct battery-to-electrolyzer DC bus configurations in green hydrogen pilot plants.
- Sodium-Ion Battery Integration:Voltage regulation algorithms optimized for lithium iron phosphate require recalibration for sodium-ion's flatter discharge curves, creating firmware differentiation potential.
- Marine and RV Channel Expansion:Modular inverter-charger integration is extending product lifecycle value in recreational vehicle aftermarket distribution through specialized marine electronics retailers.
Industry Challenges
- Firmware Talent Scarcity:Embedded systems engineers with power electronics and battery management algorithm expertise command premium compensation, constraining mid-tier manufacturer R&D scaling.
- Multi-Chemistry Certification Burden:Separate thermal validation protocols for lead-acid, lithium iron phosphate, and sodium-ion battery pairings extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Charge Controller System Market |
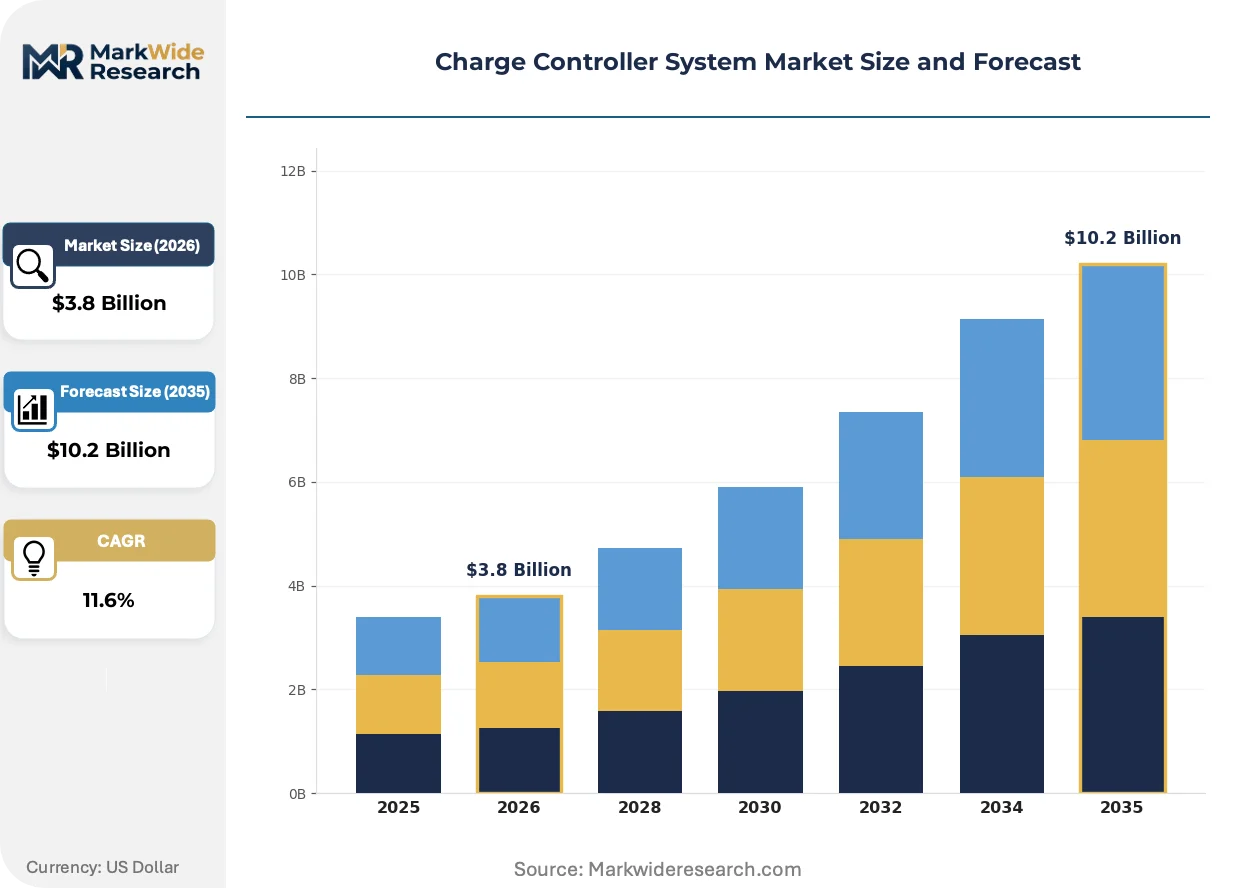
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MPPT Controllers, PWM Controllers, Hybrid Controllers, Smart Controllers Technology: Solar, Wind, Hydro, Battery Management End User: Residential, Commercial, Industrial, Automotive Installation: On-Grid, Off-Grid, Portable, Stationary |
| Companies Covered | Schneider Electric, Morningstar Corporation, Victron Energy, OutBack Power, Phocos Group, Steca Elektronik, Genasun, Blue Sky Energy, EPSolar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Charge Controller System Market Emerging Trajectories
Silicon carbide power semiconductors and adaptive MPPT tracking algorithms are collapsing thermal management footprints while enabling higher switching frequencies across residential and commercial controller tiers.
GaN-based power stages are miniaturizing magnetic component requirements in 48V and 400V nominal controllers. Marine electronics installers in Nordic coastal regions are specifying these compact units for space-constrained sailboat battery compartments. The technology is miniaturizing enclosure volumes by 40-60% versus silicon MOSFET equivalents, compressing bill-of-materials costs for premium-tier products.
The EU F-Gas Regulation's hydrofluorocarbon phase-down timeline is forcing refrigerant system manufacturers to specify charge controllers compatible with emerging electrolyzer DC coupling architectures. Industrial heat pump OEMs in Germany and the Netherlands are procuring controllers with expanded voltage input ranges to support reversible DC bus configurations. Battery storage integrators are responding by pre-certifying controllers for hydrogen production facility deployments.
Telecommunications tower operators in India are consolidating procurement through national-level framework agreements rather than state-by-state tendering. This buyer concentration is compressing pricing negotiation cycles and favoring manufacturers with BIS-certified testing laboratory partnerships. The shift is most visible in Rajasthan and Gujarat, where tower infrastructure companies are specifying 5-year warranty terms as standard procurement conditions.
Charge Controller System Market Segmentation
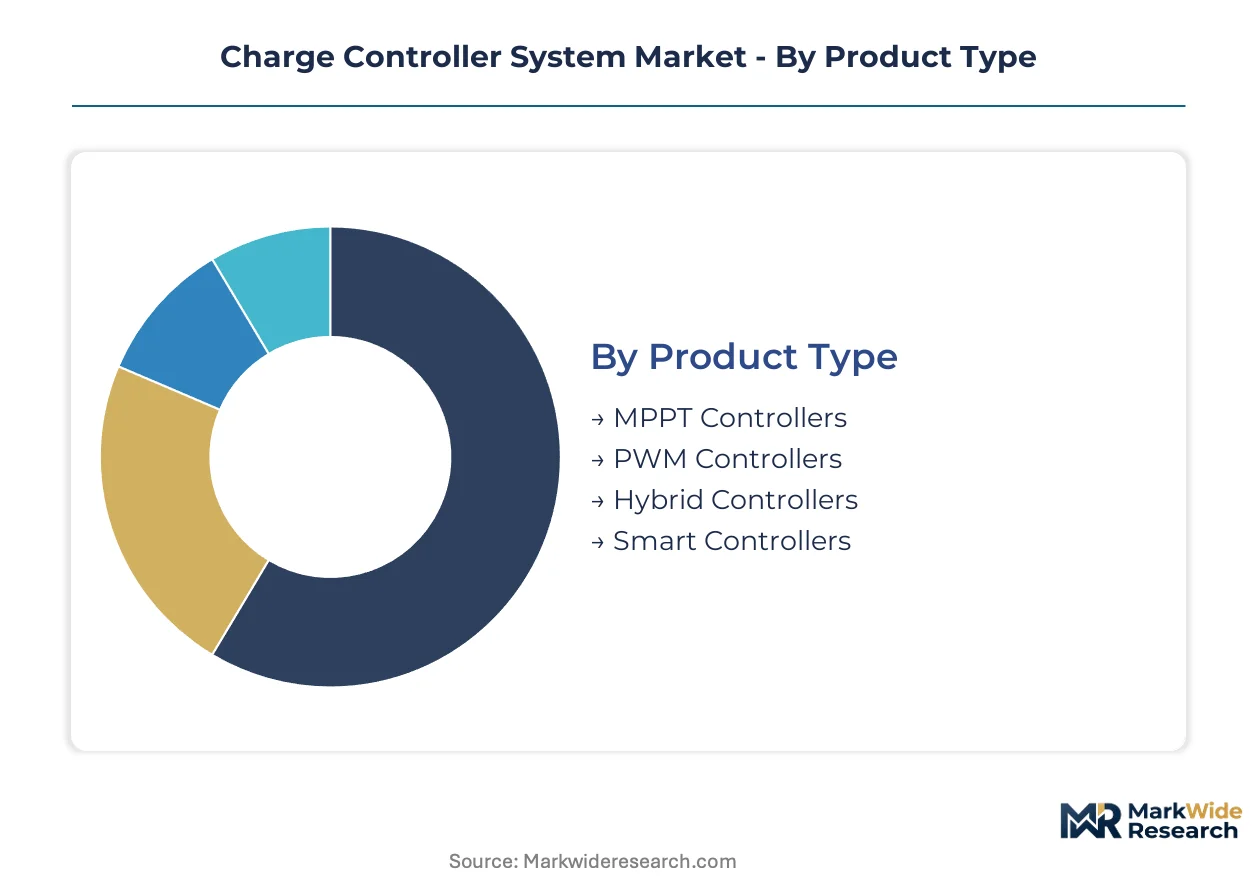
Charge controller segmentation reveals distinct margin architectures across power conversion topologies and installation contexts. Product type and technology categories concentrate value in MPPT algorithms and solar harvesting systems, while end-user and installation dimensions expose divergent certification burdens and channel economics.
Product Type:
Margin pools concentrate in MPPT and hybrid architectures where semiconductor content and firmware complexity justify premium positioning.
- MPPT Controllers:Maximum power point tracking algorithms dynamically adjust electrical operating points to extract optimal energy from photovoltaic arrays under variable irradiance conditions. Utility-scale deployments in India and utility deregulated territories in Germany specify these units for array voltages exceeding battery banks by significant margins, with IEC 62109 certification serving as a procurement gate.
- PWM Controllers:Pulse-width modulation topologies switch power at battery voltage levels, offering simpler architectures with lower semiconductor counts. Residential installations across cost-sensitive emerging economies favor these controllers where panel and battery voltages match, particularly in rural electrification projects under India's state-level distribution company programs.
- Hybrid Controllers:Integrated inverter-charger architectures consolidate power conversion stages for marine and RV aftermarket channels through specialized distribution partnerships.
- Smart Controllers:Network-connected units with remote monitoring capabilities serve telecommunications tower operators in sub-Saharan Africa requiring centralized fleet management.
The dominant share belongs to MPPT Controllers, while Hybrid Controllers are closing the gap fastest through marine and RV channel expansion.
Technology:
Cost tier stratification separates mature solar harvesting from emerging hydro and battery management integration plays.
- Solar:Photovoltaic charge regulation dominates volume through DC coupling architectures optimized for crystalline and thin-film module characteristics. India's BIS local testing mandates for solar charge controllers deployed under government subsidy programs standardize procurement specifications across Rajasthan and Gujarat state tenders.
- Battery Management:Multi-chemistry voltage regulation algorithms accommodate lithium iron phosphate and sodium-ion discharge curves, requiring firmware recalibration that extends product launch timelines.
- Wind:Turbine-specific controllers manage variable input frequencies from small-scale rotors, serving off-grid installations with mixed renewable sources.
- Hydro:Micro-hydro charge regulation addresses consistent baseload generation from run-of-river installations, concentrated in mountainous terrain with reliable water flows.
Solar technology commands the installed base, though Battery Management integration is expanding most quickly through lithium chemistry diversification.
End User:
Application-driven specification divergence creates distinct certification and warranty requirement clusters across customer types.
- Residential:Single-family and small multi-family installations specify cost-optimized PWM or entry MPPT units with standardized 5-year warranty terms. India's residential solar adoption acceleration under government targets drives procurement volume through state-level subsidy frameworks.
- Industrial:Manufacturing facilities and processing plants demand ruggedized controllers with wide temperature operating ranges and extended service intervals.
- Commercial:Retail, office, and institutional buildings navigate net-metering policy volatility in deregulated utility territories, requiring flexible grid-interactive capabilities.
- Automotive:Electric vehicle auxiliary power systems and charging infrastructure integration specify automotive-grade reliability standards.
Residential end users represent the volume anchor, while Industrial applications are gaining share fastest through reliability premium capture.
Installation:
Geography and mobility requirements reshape enclosure specifications, voltage input ranges, and channel access economics.
- Off-Grid:Remote telecommunications towers and rural electrification projects across Africa and South Asia concentrate margin in extreme-environment reliability specifications. Sub-Saharan African tower operators specify wide voltage input ranges to accommodate mixed solar-diesel hybrid architectures.
- On-Grid:Net-metered commercial and utility-scale installations require grid-synchronization capabilities and utility interconnection standards compliance.
- Portable:Recreational vehicle and marine applications prioritize compact enclosures and modular integration through specialized aftermarket retailers.
- Stationary:Fixed industrial and residential installations optimize for thermal management and long-term durability in permanent mounting configurations.
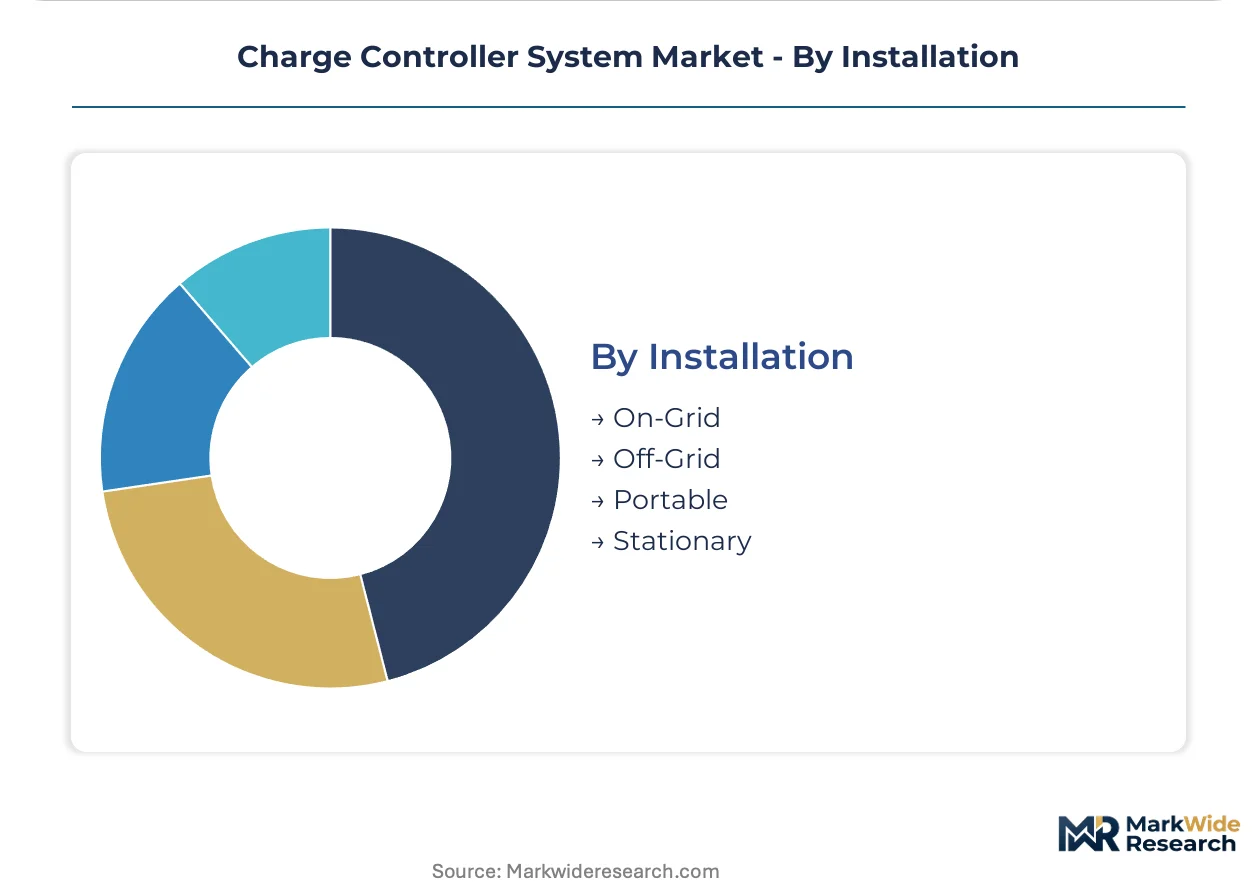
Off-Grid installations hold the margin concentration, while Portable systems are climbing the fastest through marine and RV channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in rural electrification projects across South Asia exhibit extreme price elasticity, while European industrial procurement tolerates substantial premiums for hydrogen-coupled DC architectures. This demand-elasticity contrast concentrates margin capture in divergent geographies.
India
Rajasthan and Gujarat tower infrastructure operators consolidate procurement through national framework agreements with standardized 5-year warranty terms. BIS local testing mandates for solar charge controllers deployed under government subsidy programs reshape supplier qualification requirements. State-level distribution companies in Maharashtra and Karnataka accelerate residential solar adoption through targeted subsidy disbursements.
Germany
Industrial heat pump OEMs in the Netherlands and Germany procure controllers with expanded voltage input ranges for reversible DC bus configurations. The EU F-Gas Regulation phase-down timeline forces compatibility engineering for electrolyzer DC coupling architectures in green hydrogen pilot plants. Manufacturing clusters in Baden-Württemberg and North Rhine-Westphalia concentrate controller pre-certification activity for hydrogen facility deployments.
United States
String inverter manufacturers absorb charge control functions into hybrid units, eroding standalone controller attach rates in residential retrofit segments across deregulated utility territories. FERC interconnection standards and state-level net-metering policy volatility reshape grid-interactive capability requirements. Solar deployment concentrates in California, Texas, and Florida metros where commercial building codes accelerate smart controller specification.
China
Export-oriented manufacturers face accelerated IEC 62109-1 certification timelines to access European renewable hydrogen coupling projects. Power MOSFET and gate driver IC lead times from Taiwanese foundries create inventory mismatches for assembly-focused controller manufacturers. Manufacturing clusters in Guangdong and Jiangsu provinces dominate export production for cost-sensitive PWM controller segments.
South Africa
Remote telecommunications tower operators specify MPPT controllers with wide voltage input ranges to accommodate mixed solar-diesel hybrid architectures. Off-grid installation demand concentrates in sub-Saharan African markets where extreme-environment reliability specifications command margin premiums. Distribution partnerships through Johannesburg-based industrial suppliers channel premium-tier products to rural electrification projects.
Charge Controller System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the charge controller system market. Vertically integrated power electronics manufacturers with captive semiconductor sourcing sustain margin resilience against assembly-focused competitors dependent on Taiwanese foundry supply. Three archetypes dominate: precision analog engineering specialists for extreme-environment applications, modular integration providers for marine and RV aftermarket channels, and utility-scale deployment specialists with certification depth. Competitive moves concentrate on backward integration into power semiconductor supply and firmware architecture differentiation for multi-chemistry battery management.
Within the precision analog tier, Morningstar Corporation exemplifies engineering-intensive positioning for off-grid reliability specifications. Schneider Electric anchors the utility-scale deployment archetype through certification depth and captive sourcing advantages. Victron Energy occupies the modular integration position for marine and RV lifecycle value extension. These three companies represent the strategic archetype divergence reshaping competitive stability across residential, commercial, and industrial installation segments.
| Leading Market Players |
|---|
| Schneider Electric |
| Morningstar Corporation |
| Victron Energy |
| OutBack Power |
| Phocos Group |
| Steca Elektronik |
| Genasun |
| Blue Sky Energy |
| EPSolar |
| Others |
Supply Flow & Price Mechanics
Silicon carbide power semiconductor substitution for silicon MOSFETs is simultaneously redrawing manufacturing geography toward captive wafer fabrication in Germany and Japan while compressing premium-tier pricing spreads as GaN-based alternatives enter volume production. This materials transition rewards vertically integrated power electronics manufacturers with in-house semiconductor sourcing while stranding assembly-focused competitors dependent on Taiwanese foundry allocation.
Pricing Analysis
After-sales service contracts and extended warranty coverage drive lifetime value capture across telecommunications and utility-scale deployments. Three-tier pricing structure across premium, standard, and economy levels separates IEC 62109-certified units for European hydrogen projects from BIS-compliant domestic Indian supply and cost-optimized PWM controllers for rural electrification. Pricing pressure stems from string inverter hybrid integration absorbing standalone controller functions in residential retrofits. Rural electrification buyers in India exhibit extreme price elasticity, while German industrial heat pump OEMs tolerate substantial premiums for electrolyzer-compatible DC architectures.
Supply Chain Analysis
Strategic stockpiling of power MOSFETs and gate driver ICs dominates inventory strategy among manufacturers exposed to Taiwanese foundry lead time volatility. Semiconductor supply concentrates in Taiwan, South Korea, and China, while final assembly clusters in Guangdong and Jiangsu provinces. Controller production draws from silicon carbide substrates, lithium-ion battery management ICs, and aluminum thermal management housings. Single-source vulnerability around Taiwanese wafer fabrication creates procurement risk for assembly-focused competitors lacking captive sourcing. Distribution runs through industrial electrical distributors in Europe, national framework agreements in India, and specialized marine electronics retailers for RV aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Charge controller markets are approaching a platform-economics inflection where firmware-defined battery chemistry compatibility and cloud-connected fleet management reshape competitive boundaries around interoperability rather than hardware specifications alone.
For Market Incumbents: Secure backward integration into silicon carbide and GaN semiconductor supply to sustain margin resilience against assembly-focused competitors exposed to Taiwanese foundry allocation constraints. Defend utility-scale positioning through accelerated IEC 62109-1 certification for European renewable hydrogen coupling projects before export-oriented manufacturers in China and India close the compliance gap. Prioritize firmware architecture investment for sodium-ion battery voltage regulation algorithms to preempt chemistry diversification threats.
For New Entrants and Emerging Players: Anchor in marine and RV aftermarket channels where modular inverter-charger integration commands lifecycle value premiums through specialized distribution partnerships rather than price-competitive utility procurement. Target telecommunications tower operators in sub-Saharan Africa consolidating procurement through national framework agreements with 5-year warranty requirements that favor agile firmware specialists over legacy hardware incumbents. Pursue white-label manufacturing partnerships with Indian BIS-certified testing laboratories to access state-level subsidy program eligibility.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision analog engineering specialists serving extreme-environment off-grid specifications where talent scarcity and multi-chemistry certification burdens create durable competitive moats. Five-to-ten year viability hinges on firmware-defined differentiation rather than hardware cost position. Monitor sodium-ion battery chemistry commercialization timelines as the critical inflection signal for controller firmware recalibration demand and associated R&D investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Semiconductors | Captive sourcing of silicon carbide wafers insulates margin from Taiwanese foundry allocation volatility. |
| Multi-Chemistry Firmware Certification | Simultaneous lead-acid, lithium iron phosphate, and sodium-ion validation extends product launch timelines by 8-14 months. |
| Electrolyzer DC Coupling Compatibility | EU F-Gas Regulation phase-down forces controller architecture redesign for green hydrogen pilot plant deployments. |
| Marine Channel Distribution Partnerships | Specialized Nordic coastal retailer access captures RV aftermarket lifecycle value through modular integration. |
| BIS Testing Laboratory Pre-Certification | Indian state-level subsidy program eligibility requires local testing partnerships for government procurement access. |
Methodological Framework
The analysis maps MPPT algorithm architectures, PWM controller specifications, hybrid inverter-charger integrations, and smart network-connected units, each validated through power electronics design engineers, telecommunications infrastructure procurement officers, marine electronics installers, and utility-scale EPC contractors. Primary interview intelligence triangulates against IEC certification databases, BIS testing laboratory records, EU Green Deal hydrogen coupling project filings, and Indian state-level distribution company tender documents. Bottom-up unit economics and top-down market sizing converge through cross-referencing manufacturer production disclosures with import-export customs data.
Consistency checks validate volume and value outputs against external benchmarks including IEA renewable energy deployment statistics, FERC interconnection queue data, and telecommunications tower infrastructure investment disclosures across sub-Saharan Africa and South Asia. Segmentation modeling spans product type, technology, end user, and installation category with additional granularity for battery chemistry compatibility and regional regulatory framework clusters. CAGRs derive from weighted average of historical trajectory, policy mandate timelines, and technology substitution curves. Forecast inputs incorporate semiconductor supply lead time dynamics and electrolyzer DC coupling architecture adoption rates.
Decision-makers should treat outputs as directional under assumptions of sustained lithium-ion cost decline and IEC 62109 certification timeline stability; material deviation in sodium-ion commercialization pace or Taiwanese foundry capacity expansion would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Asia-Pacific Automotive DC-DC Converters Market
Power Systems
EV Power Module Market
Power Systems
Battery Charge Controller Market
Power Systems
Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Global Next Generation Power Semiconductors Market
Power Systems
Telecom Battery Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Battery Electronic Control Unit Market
Power Systems
Integrated UPS Market
Power Systems
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Global Frequency Converter Market
Power Systems
Asia-Pacific Shunt Reactors Market
Power Systems
Traction Inverter Market
Power Systems
Flyback Transformer Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
Medium Voltage Drives Market