
 High Voltage Direct Current Power Supply Market | 2026-2036
High Voltage Direct Current Power Supply Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Direct Current Power Supply Market Insights
Software-defined power management is repositioning how HVDC systems generate recurring revenue beyond hardware sales. ABB Ltd. leverages its digital platform architecture to anchor long-term service contracts across European converter installations. Siemens AG sustains competitive differentiation through deep specialization in modular converter topologies for offshore wind integration. Hitachi Energy dominates the Asia-Pacific project pipeline with integrated system offerings that bundle hardware, control software, and predictive maintenance subscriptions.
High Voltage Direct Current Power Supply refers to electrical conversion equipment that transforms alternating current into regulated direct current at potentials typically exceeding 100 kV, utilizing thyristor or insulated-gate bipolar transistor switching arrays for precise voltage control and minimal harmonic distortion in long-distance transmission and industrial processes. Converter products lead installed capacity due to their centrality in grid interconnection projects, while modular technology architectures are capturing expanding margin pools as utilities prioritize field-replaceable subsystems that reduce outage duration. Digital technology segments are accelerating fastest as embedded monitoring and adaptive control capabilities become standard procurement requirements for renewable energy developers seeking grid-code compliance.
FERC interconnection standards and the EPA's greenhouse gas performance benchmarks are reshaping procurement specifications for utility-scale HVDC installations across the United States, while China's GB standards and MIIT efficiency mandates are driving domestic converter replacement cycles. The EU Green Deal and F-Gas Regulation are simultaneously constraining insulating medium choices and accelerating SF6-free system development for European transmission operators. Stakeholders must monitor evolving grid-code harmonization between jurisdictions to anticipate where certification investments will unlock project access.
Market Dynamics
Semiconductor fabrication capacity expansion is compressing procurement cycles for precision HVDC systems as fabs prioritize voltage stability specifications over capital cost minimization. Converter station operators face simultaneous pressure from grid-code tightening and renewable interconnection mandates.
Growth Catalysts
- China's dual carbon goals:MIIT efficiency mandates are accelerating domestic converter replacement cycles and tightening procurement specifications for new grid interconnections.
- Offshore wind buildouts:European transmission operators are specifying modular HVDC architectures for North Sea and Baltic Sea collector platforms.
- Thyristor-to-IGBT migration:Insulated-gate bipolar transistor switching arrays are enabling finer voltage control for semiconductor lithography equipment manufacturers.
Market Restraints
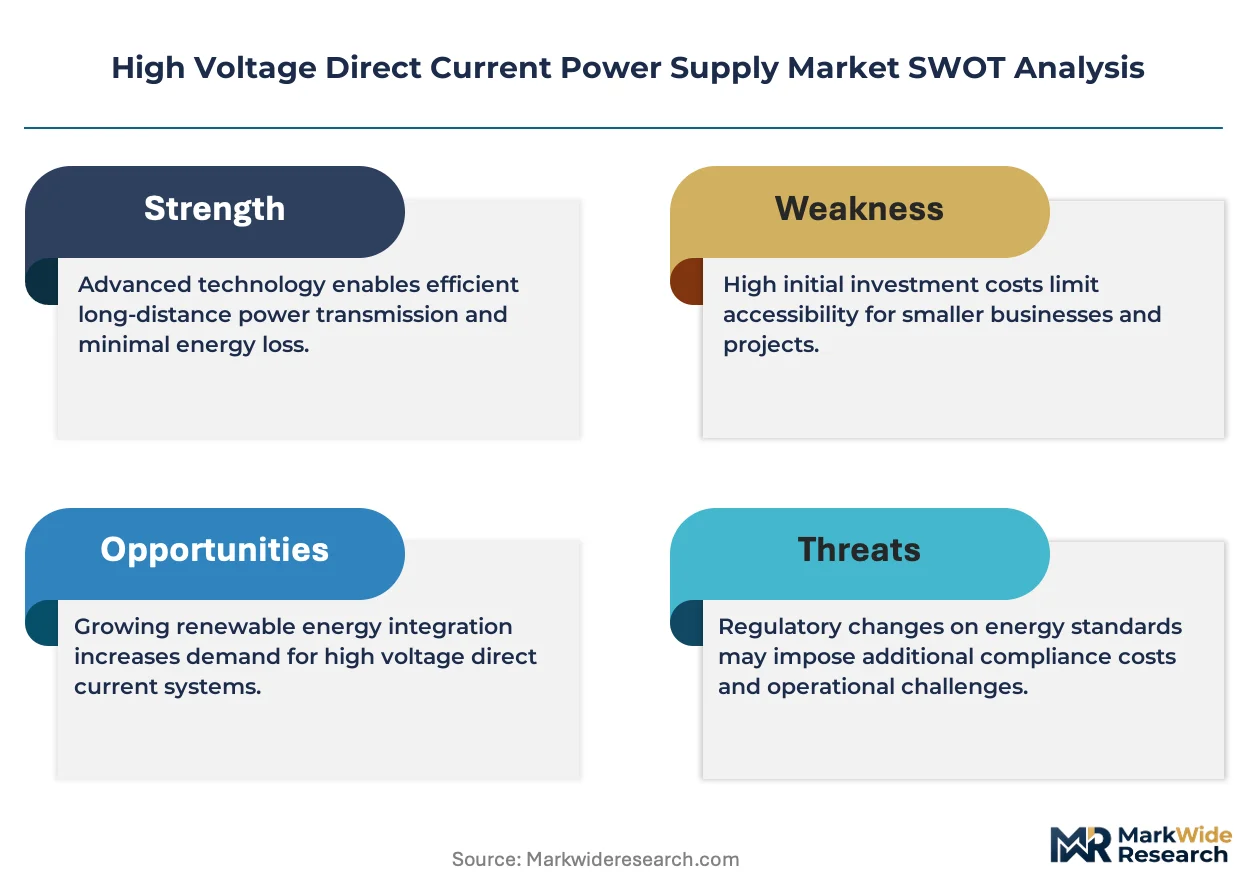
- SF6 insulating medium constraints:The EU F-Gas Regulation is limiting gas-insulated system availability and extending lead times for European converter station projects.
- Specialized magnetic core supply:Grain-oriented electrical steel production concentrates in a limited number of integrated steelworks, creating input cost volatility.
- Grid-code fragmentation:Divergent FERC interconnection standards across US ISO territories are multiplying certification burdens for equipment suppliers.
Strategic Opportunities
- India transmission expansion:CEA mandates for cross-border interconnections are opening procurement windows for converter station technology as the country scales renewable evacuation infrastructure.
- Predictive maintenance subscriptions:Software-defined power management platforms are creating recurring revenue streams alongside hardware sales in Japanese and South Korean manufacturing corridors.
- SF6-free system development:Vacuum interrupter and clean air insulation technologies are capturing premium positioning as European operators accelerate decarbonization commitments.
Industry Challenges
- Power electronics engineering scarcity:Converter control algorithm development and high-frequency magnetics design expertise remains concentrated among a narrow specialist workforce.
- Legacy thyristor system integration:Retrofitting digital monitoring capabilities into installed base converter stations requires custom interface engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Direct Current Power Supply Market |
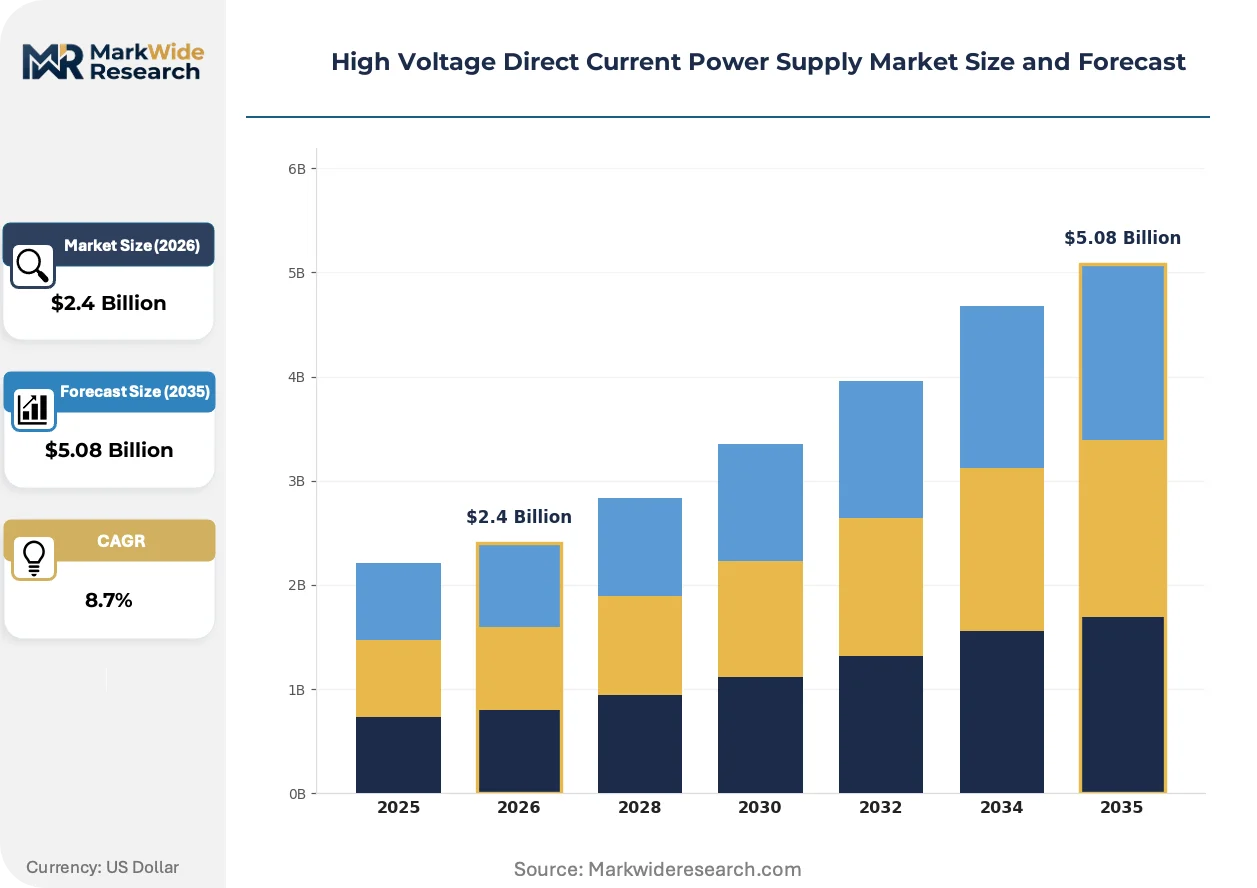
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Converter, Inverter, Rectifier, Charger Technology: Integrated, Modular, Hybrid, Digital End User: Telecommunications, Renewable Energy, Industrial Automation, Railways Installation: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | ABB Ltd., Siemens AG, General Electric, Hitachi Energy, Toshiba Corporation, Mitsubishi Electric Corporation, Excelitas Technologies Corp., XP Power, American Power Design, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Direct Current Power Supply Market Trends and Innovations
HVDC system architecture is pivoting from hardware-centric sales toward software-anchored service relationships. Three developments are compressing traditional competitive boundaries and repositioning value capture mechanisms across the supply chain.
Silicon carbide power semiconductors are electrifying converter efficiency benchmarks by reducing switching losses in high-voltage applications. Offshore wind developers are specifying SiC-based modular multilevel converters for collector platforms to minimize platform footprint and cooling requirements. This material transition is electrifying incumbent silicon IGBT market positions while compressing margin structures for suppliers without wide-bandgap fabrication partnerships.
The EU Green Deal's F-Gas Regulation is prohibiting sulfur hexafluoride deployment in new transmission equipment from 2030. European TSOs are accelerating pilot deployments of vacuum-interrupter and fluoronitrile-insulated systems to secure operational experience ahead of mandatory phase-out dates. Converter station OEMs with certified SF6-free portfolios are capturing disproportionate share of German and Nordic tender pipelines.
Semiconductor fabs are consolidating HVDC supplier relationships around integrated system offerings that bundle hardware, control software, and uptime guarantees. Lithography equipment manufacturers are displacing component sourcing models with multi-year service partnerships that transfer voltage stability risk to converter specialists. This preference compression is most visible in East Asian manufacturing corridors where fab concentration enables scale-based procurement leverage.
High Voltage Direct Current Power Supply Market Segmentation
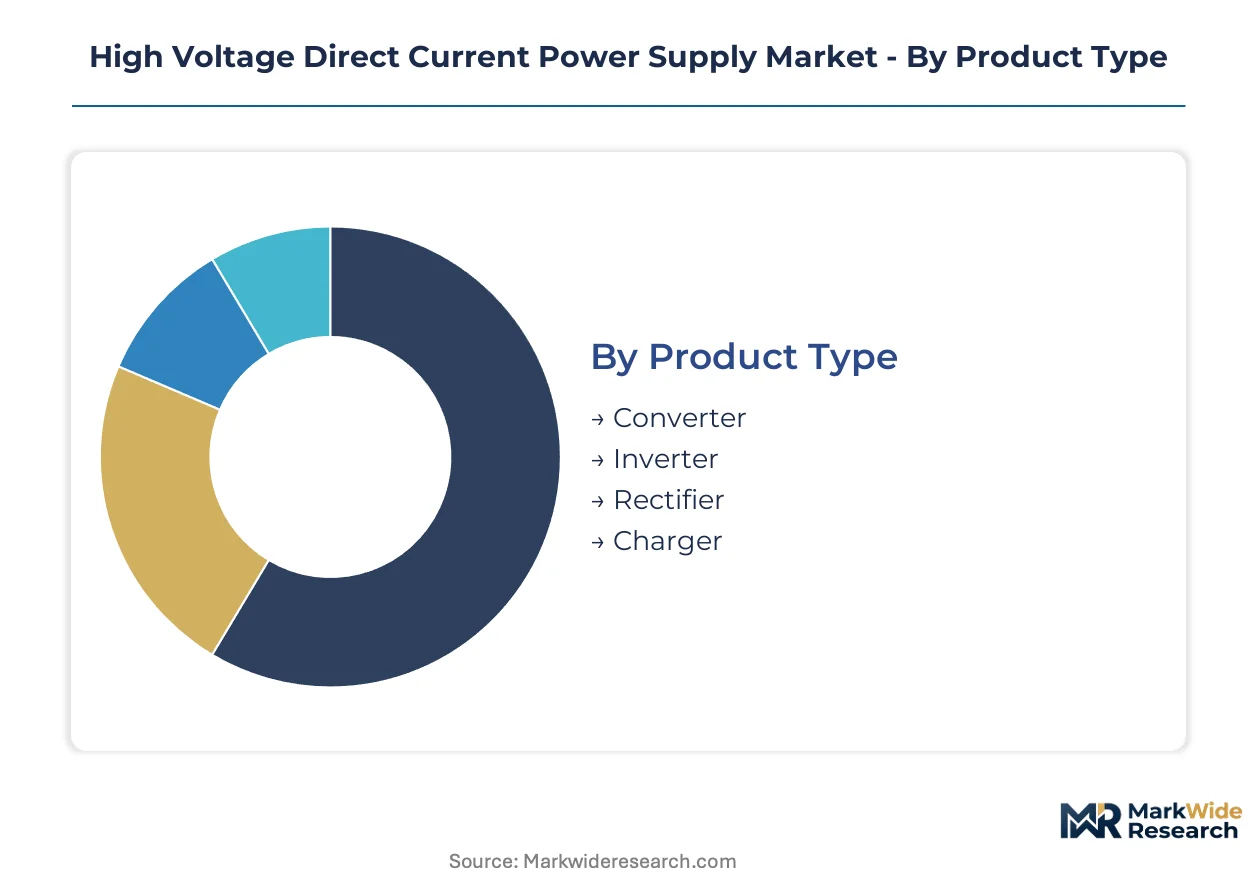
HVDC power supply segmentation reveals how voltage conversion architectures align with distinct technical requirements across grid interconnection, industrial process control, and renewable energy integration. Product specifications vary sharply between long-distance transmission infrastructure and precision manufacturing applications.
Product Type:
Voltage conversion topology determines harmonic performance, switching frequency tolerance, and thermal management requirements in high-potential DC applications.
- Converter:Thyristor and IGBT switching arrays transform AC to regulated DC above 100 kV for grid interconnection and long-distance transmission. Semiconductor fabrication facilities in Japan and eastern China specify these systems for lithography equipment voltage stability, prioritizing precision over capital cost minimization. Converter products anchor installed capacity due to their centrality in cross-border grid projects and industrial DC loads.
- Inverter:DC-to-AC conversion stages enable renewable energy integration and battery energy storage system grid connection. Offshore wind developers in the North Sea and Baltic Sea specify modular inverter architectures for collector platforms to minimize footprint and cooling requirements. Inverter systems are capturing expanding procurement volumes as renewable evacuation infrastructure scales across European transmission networks.
- Rectifier:AC-to-DC conversion without active voltage regulation serves electrolysis and electrochemical processing applications. Industrial automation corridors in South Korea deploy rectifier banks for heavy manufacturing DC loads.
- Charger:Battery charging systems with integrated power conditioning support railway electrification and grid-scale storage. Railway operators in India specify charger systems for cross-border interconnection corridors under CEA mandates.
Converter leads on scale; inverter leads on momentum.
Technology:
System architecture choices determine field serviceability, upgrade pathways, and lifetime cost structures for converter station operators.
- Integrated:Monolithic system designs with centralized control and cooling reduce commissioning complexity for greenfield installations. Chinese grid modernization projects under MIIT efficiency mandates favor integrated architectures for domestic converter replacement cycles.
- Modular:Field-replaceable subsystems with standardized interfaces reduce outage duration and enable capacity expansion without full replacement. European TSOs specify modular topologies for North Sea offshore platforms to minimize maintenance vessel dispatch frequency. Modular architectures are gaining procurement preference as utilities prioritize operational flexibility over upfront capital minimization.
- Hybrid:Combined thyristor and IGBT switching configurations balance cost and control precision in retrofit applications. Legacy system operators in Germany deploy hybrid architectures to extend installed base service life.
- Digital:Embedded monitoring, adaptive control, and predictive analytics capabilities embedded at the power electronics level. Renewable developers seeking grid-code compliance specify digital platforms as standard procurement requirements. Digital technology segments are climbing the fastest as software-defined power management creates recurring revenue alongside hardware sales.
Integrated dominates current installations; digital claims the steepest expansion trajectory.
End User:
Application voltage stability requirements and duty cycle profiles shape procurement specifications and supplier relationship structures.
- Telecommunications:DC power systems for data center and network infrastructure requiring high availability and minimal harmonic injection. Facilities in Singapore and Hong Kong specify precision HVDC rectification for submarine cable landing stations.
- Renewable Energy:Grid interconnection and collector platform systems for wind and solar evacuation. Offshore wind buildouts in European waters and solar parks in Rajasthan drive modular converter demand with strict grid-code compliance requirements.
- Industrial Automation:Precision voltage supply for semiconductor lithography, electrolysis, and electrochemical processing. East Asian manufacturing corridors spanning Japan, South Korea, and eastern China concentrate demand for integrated system offerings bundling hardware, control software, and uptime guarantees. Industrial automation commands premium positioning due to voltage stability specifications that supersede capital cost priorities.
- Railways:Traction power supply and cross-border interconnection infrastructure. Indian Railways and European corridor operators specify HVDC systems for 25 kV/50 Hz and 15 kV/16.7 Hz electrification standardization.
Industrial automation leads on margin capture; renewable energy leads on volume growth.
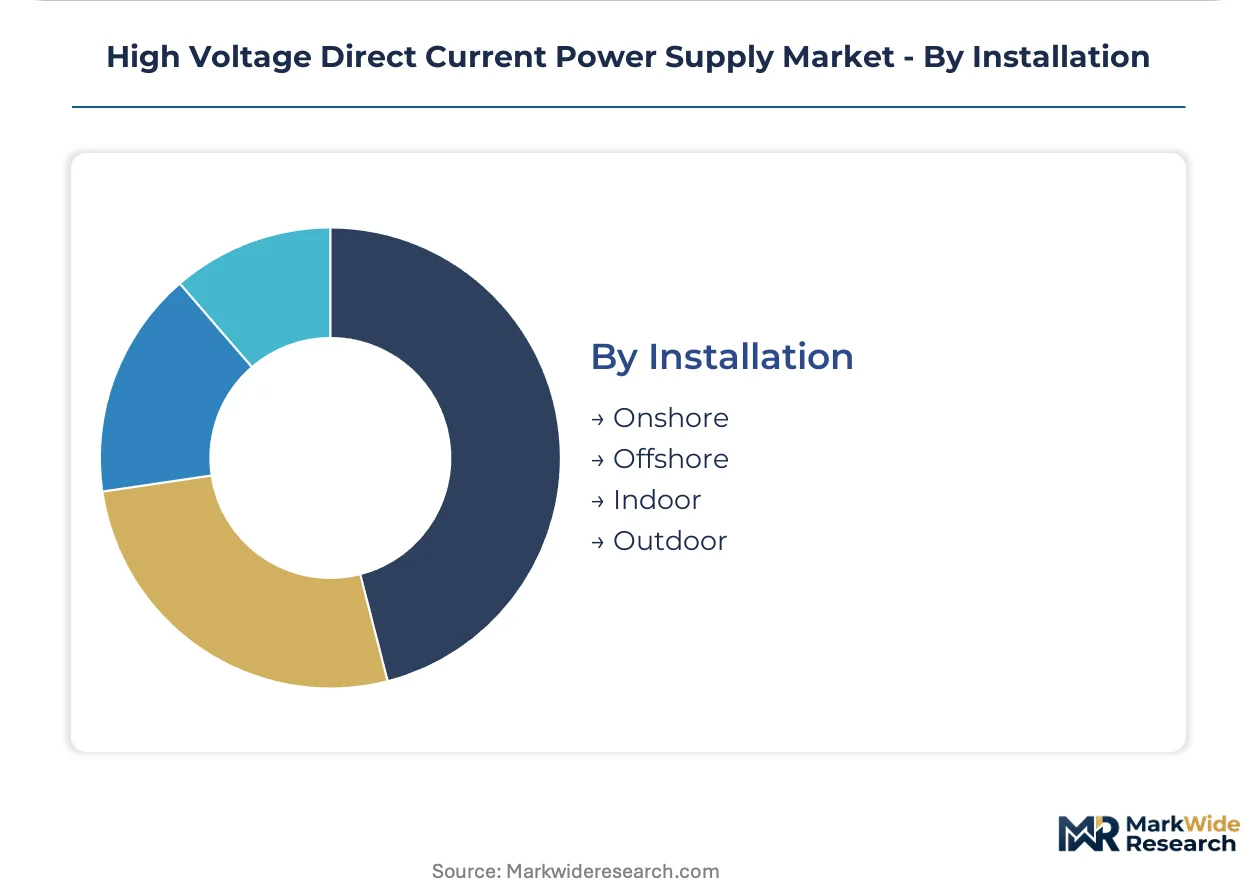
Installation:
Environmental exposure and accessibility constraints determine enclosure specifications, cooling system design, and maintenance logistics.
- Onshore:Ground-mounted converter stations with conventional air or liquid cooling for grid interconnection and industrial loads. China's dual carbon goals drive onshore replacement cycles across provincial grid operators.
- Offshore:Platform-mounted systems with marine-grade enclosures and salt corrosion protection. North Sea and Baltic Sea projects specify SF6-free insulation technologies ahead of EU F-Gas Regulation phase-out deadlines. Offshore installations command extended lead times due to specialized magnetic core supply constraints and marine certification requirements.
- Indoor:Climate-controlled environments for precision manufacturing and data center applications. Semiconductor fabs in Hsinchu and Pyeongtaek specify indoor HVDC systems with sub-percent voltage ripple tolerance.
- Outdoor:Weather-hardened enclosures for utility-scale renewable and railway infrastructure. Indian solar parks and railway corridors deploy outdoor systems with IP65 protection and passive cooling.
Onshore dominates installed base; offshore gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT efficiency mandates are accelerating converter replacement cycles faster than Germany's F-Gas Regulation is reshaping European procurement specifications, revealing how divergent policy instruments are compressing regional market timelines simultaneously.
China
Provincial grid operators are replacing legacy thyristor systems under dual carbon goals and MIIT efficiency mandates. GB standards are tightening procurement specifications for new interconnections. The Yangtze River Delta manufacturing corridor spanning Shanghai and Suzhou is absorbing integrated HVDC systems for semiconductor lithography voltage stability.
Germany
Transmission system operators are piloting SF6-free vacuum interrupter technologies ahead of EU F-Gas Regulation deadlines. The EU Green Deal is constraining insulating medium choices while accelerating clean air insulation development. Industrial clusters in Bavaria and Baden-Württemberg are retrofitting digital monitoring capabilities into installed base converter stations.
United States
Offshore wind developers are specifying modular converter architectures for Atlantic Coast collector platforms. FERC interconnection standards are reshaping procurement specifications across ISO territories. The Pacific Northwest corridor linking Oregon and Washington is deploying precision HVDC systems for semiconductor fabrication expansion.
Japan
Semiconductor fabs in Hsinchu-adjacent supply chains are consolidating supplier relationships around integrated system offerings with uptime guarantees. METI industrial policy is prioritizing voltage stability specifications over capital cost minimization. The Kyushu manufacturing belt is absorbing predictive maintenance subscriptions alongside hardware procurement.
India
Cross-border interconnection mandates from CEA are opening procurement windows for converter station technology. Railway electrification standards are specifying HVDC charger systems for 25 kV corridor standardization. The Gujarat-Rajasthan solar belt is deploying outdoor modular systems with IP65 protection for renewable evacuation infrastructure.
High Voltage Direct Current Power Supply Market Competitive Landscape
Top-tier vendors anchor integrated system offerings with bundled software and service contracts, while mid-tier specialists compete on modular architectures and geographic proximity to manufacturing corridors. The vendor base stratifies across three tiers: diversified electrical conglomerates with digital platforms, regional power electronics specialists with deep converter control expertise, and component-scale suppliers serving precision industrial applications. Two competitive moves dominate: technology licensing partnerships for silicon carbide power semiconductor access, and predictive maintenance subscription models that convert hardware sales into recurring revenue streams.
Within the diversified conglomerate tier, ABB Ltd. and Siemens AG occupy positions defined by digital platform depth and modular topology specialization respectively. Hitachi Energy anchors the Asia-Pacific project pipeline through integrated offerings that bundle hardware, control software, and service subscriptions. These three exemplify how competitive positioning increasingly depends on software-anchored service relationships rather than hardware specifications alone.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| General Electric |
| Hitachi Energy |
| Toshiba Corporation |
| Mitsubishi Electric Corporation |
| Excelitas Technologies Corp. |
| XP Power |
| American Power Design |
| Others |
Pricing and Supply Chain Analysis
Grain-oriented electrical steel price volatility cascades through converter station manufacturing costs, compressing margin structures for suppliers without captive magnetic core supply while amplifying pricing power for integrated steelworks serving East Asian manufacturing corridors.
Pricing Analysis
Capacity additions in China are reshaping price floors for thyristor and IGBT converter systems, with MIIT efficiency mandates accelerating domestic replacement cycles. Three-tier pricing structure across premium, standard, and economy levels separates SF6-free certified systems from conventional gas-insulated alternatives and legacy thyristor retrofits. Cost compression in standard-tier products is intensifying because silicon carbide power semiconductor partnerships concentrate among diversified conglomerates. Industrial automation buyers in semiconductor lithography exhibit the least price sensitivity, prioritizing sub-percent voltage ripple guarantees over capital cost minimization.
Supply Chain Analysis
Freight cost differentials between marine-grade enclosure suppliers in Germany and magnetic core producers in Japan are widening landed cost spreads for offshore platform projects. Converter station supply chains draw from China for power semiconductor packaging, Japan for precision control electronics, and South Korea for high-frequency magnetics. Single-source vulnerability concentrates in grain-oriented electrical steel production, with tariff exposure running through European customs classifications for SF6-free insulation technologies. Distribution runs through EPC contractors and transmission system operator procurement frameworks, with long-term service contracts displacing transactional hardware sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in India's CEA-mandated cross-border interconnections, where domestic manufacturing cost structures undercut European SF6-free system pricing by substantial margins without sacrificing grid-code compliance.
For Market Incumbents: Anticipate silicon carbide power semiconductor shortages by securing wide-bandgap fabrication partnerships ahead of offshore wind procurement waves. Defensive consolidation through predictive maintenance subscription platforms locks in recurring revenue against modular architecture specialists. Capacity addition in South Korea threatens integrated system margins; certification investment in F-Gas Regulation compliance preserves European tender access. For New Entrants and Emerging Players: Capture white-space in India's railway electrification corridor standardization, where CEA mandates for 25 kV systems outpace established vendor presence. The most penetrable segment sits in outdoor modular systems for Gujarat-Rajasthan solar evacuation, with IP65 protection specifications creating technical barriers surmountable through regional EPC partnerships. Go-to-market leverage concentrates on predictive maintenance subscriptions bundled with hardware procurement. For Investors and Strategic Acquirers: Asymmetric upside sits with regional power electronics specialists possessing deep converter control algorithm expertise but lacking digital platform scale. Long-term viability over the projection horizon favors acquisition targets with certified SF6-free portfolios and established relationships with European transmission system operators. The signal to watch is F-Gas Regulation enforcement acceleration triggering mandatory phase-out compliance purchases.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Partnership Formation | Wide-bandgap semiconductor access secures efficiency benchmarks for North Sea offshore platforms. |
| SF6-Free Certification Investment | Clean air insulation credentials unlock German and Nordic tender pipelines ahead of regulatory deadlines. |
| Predictive Maintenance Platform Launch | Software-defined power management converts Hitachi Energy's hardware sales into recurring revenue streams. |
| India Manufacturing Footprint Expansion | Domestic production addresses CEA cross-border mandates while capturing cost arbitrage against European imports. |
| Legacy Thyristor Retrofit Service Line | Digital monitoring integration extends installed base service life for German industrial cluster operators. |
Research Methodology
Coverage spans China, Germany, the United States, Japan, and India, with primary inputs from each market informing demand-side validation. Converter station procurement officers, power electronics engineering directors, transmission system operator planning leads, and semiconductor fab facility managers contributed structured interviews. Secondary validation drew from MIIT efficiency mandate filings, FERC interconnection standard dockets, EU Green Deal policy documentation, and CEA cross-border interconnection records. Bottom-up project pipeline analysis triangulated against top-down grid investment forecasts.
Granularity-level modeling addressed voltage conversion topology, system architecture choices, installation environment constraints, and end-user application requirements across the analysis window. Segment-level CAGRs derived from unit economics modeling of converter, inverter, rectifier, and charger product categories, with technology adoption curves calibrated against silicon carbide penetration rates and SF6-free deployment timelines. Grid-code harmonization indices and renewable interconnection queue data informed regional growth differentials.
Commodity price volatility in grain-oriented electrical steel, regulatory enforcement acceleration for F-Gas Regulation compliance, and offshore wind project development delays are the dominant revision risks. Forecasts reflect documented assumptions regarding policy continuity and technology cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
South Korea Battery Management Systems Market
Power Systems
Asia-Pacific Shunt Reactors Market
Power Systems
E-Axle Inverter and Control Unit Systems Market
Power Systems
Hybrid Inverters Market
Power Systems
Germany Rechargeable Battery Market
Power Systems
DC Power Supplies Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market
Power Systems
Three-Phase String Inverter Market
Power Systems
PV Inverter Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
BCD Power IC Market
Power Systems
Charge Controller System Market
Power Systems
Battery Equalizer Market
Power Systems
Voltage Regulators Market
Power Systems
Asia Pacific Transformer Monitoring System Market
Power Systems
Global Fault Current Limiter Market