
 Power Supply Isolation Equipment Market | 2026-2036
Power Supply Isolation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Power Supply Isolation Equipment Market Analytics
Silicon carbide is recalibrating cost-performance trade-offs across power supply isolation equipment as engineers substitute traditional silicon-based isolators in high-frequency applications. Infineon Technologies leverages its vertical integration into SiC wafer production to control supply of next-generation isolation components. Vishay Intertechnology anchors its position through specialized thick-film resistor isolators serving industrial automation customers. Texas Instruments competes by extending its portfolio of capacitive isolation devices with integrated gate drivers for renewable energy inverters.
Power supply isolation equipment encompasses transformers, isolators, capacitors, and filters engineered to block DC paths and suppress transient noise while maintaining signal integrity across galvanic boundaries, typically rated for isolation voltages from 500V to 5kV depending on application safety requirements. Magnetic isolation technology leads unit volume in industrial settings where EMI resilience matters, while optical isolation captures premium positioning in medical devices demanding patient-contact safety certifications. Ceramic isolation is displacing legacy materials in telecommunications base stations where temperature stability and miniaturization converge.
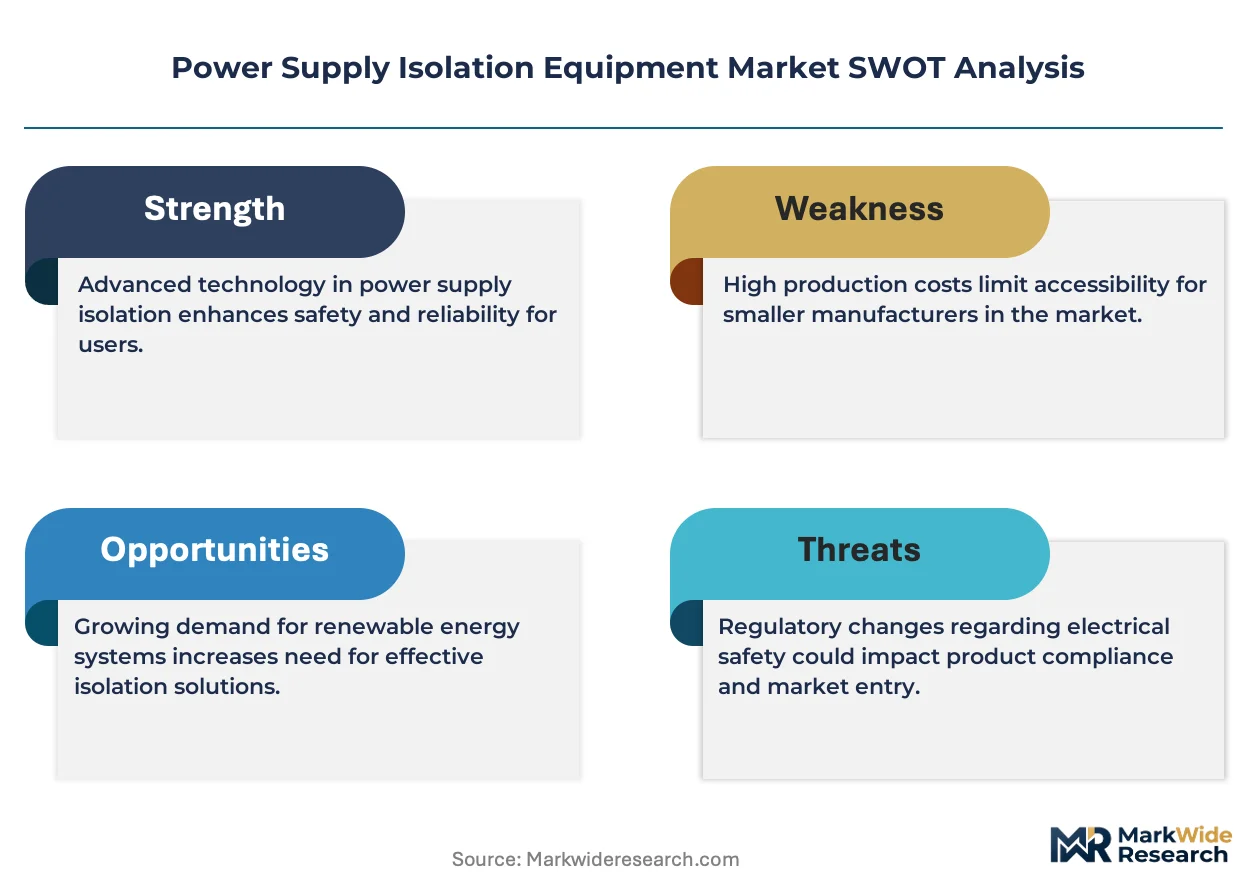
IEC 62368-1 safety standards for audio/video and IT equipment, combined with FDA electrical safety requirements for medical devices and China's GB 4943.1 national standard, collectively elevate barrier-to-entry for isolation component suppliers lacking certified testing infrastructure. The EU AI Act and CSRD disclosure rules will extend traceability requirements to power subsystem procurement decisions. Stakeholders must monitor how evolving efficiency mandates across multiple jurisdictions reshape material selection timelines and qualification cycles.
Market Dynamics
Silicon carbide substrates and ceramic dielectric materials are compressing isolation component footprints while elevating thermal performance thresholds, forcing incumbent magnetic isolation suppliers to accelerate material transitions or cede socket positions in high-frequency power electronics.
Growth Catalysts
- Data center power density requirements:Hyperscale operators in Northern Virginia, Frankfurt, and Singapore are specifying isolation components rated for 150°C ambient operation. This specification pull is accelerating ceramic and magnetic isolation technology qualification cycles.
- China's dual carbon policy framework:GB 4943.1 energy efficiency mandates and SAMR efficiency labeling requirements are disqualifying legacy silicon-based isolators from domestic server power supply tenders.
- Renewable energy inverter deployment:Grid-tied solar and wind installations require reinforced isolation barriers between high-voltage DC buses and control electronics. Capacitive isolation with integrated gate drivers is capturing these sockets.
Market Restraints
- SiC wafer supply concentration:Six-inch and eight-inch silicon carbide substrate production remains concentrated among three merchant suppliers. This concentration creates allocation risk for isolation component manufacturers lacking captive wafer supply.
- Certification timeline friction:IEC 62368-1 third edition testing and FDA 510(k) electrical safety reviews extend new product introduction cycles by 8-14 months for medical-grade isolation barriers.
- Copper and ferrite input volatility:Magnetic isolation transformers depend on high-permeability ferrite cores and heavy-gauge copper windings. LME copper price swings above 15% quarterly compress margin predictability for industrial-grade product lines.
Strategic Opportunities
- India manufacturing localization:PLI scheme incentives for electronics manufacturing and BIS certification requirements for power supplies are creating demand for locally qualified isolation component suppliers.
- EV onboard charger integration:Bidirectional charging and 800V architectures require reinforced isolation between battery management systems and grid interfaces. This application demands isolation voltage ratings above 3kV with sub-nanosecond propagation delay.
- EU CSRD supply chain disclosure:The Corporate Sustainability Reporting Directive mandates traceability for power subsystem procurement. Isolation component suppliers with certified carbon footprint data capture preferential supplier status with European industrial OEMs.
Industry Challenges
- Multi-physics simulation expertise scarcity:Isolation barrier design now requires coupled thermal-electromagnetic-structural modeling. Talent pools with ANSYS Maxwell and COMSOL Multiphysics proficiency command premium compensation in Shenzhen and Seoul labor markets.
- Legacy system integration complexity:Industrial automation customers operating 20-year equipment lifecycles demand pin-compatible isolation replacements. Forward and backward compatibility constraints limit architectural innovation in established sockets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Supply Isolation Equipment Market |
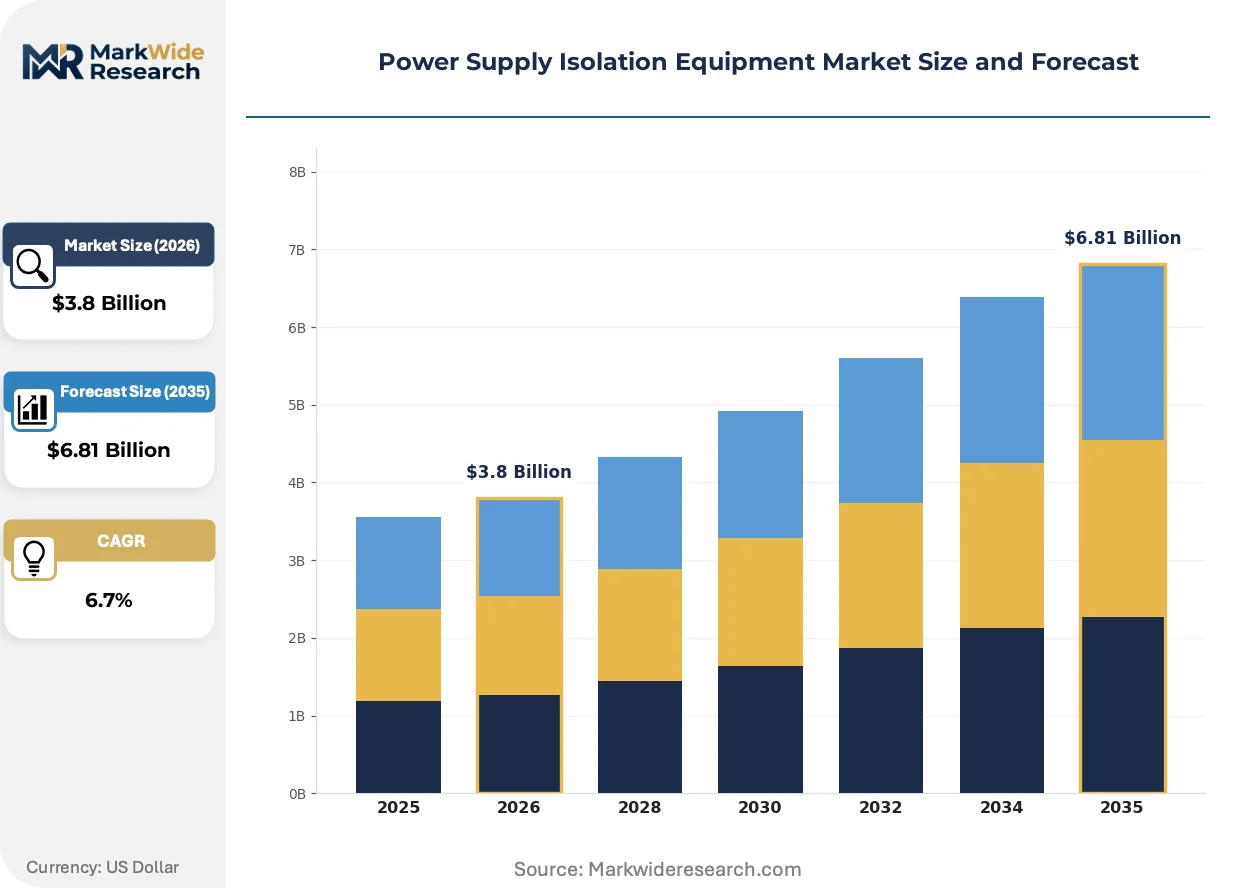
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transformers, Isolators, Capacitors, Filters Technology: Magnetic, Ceramic, Optical, RF End User: Telecommunications, Industrial Automation, Renewable Energy, Medical Devices Installation: Wall-Mounted, Rack-Mounted, Portable, Embedded |
| Companies Covered | Infineon Technologies, Vishay Intertechnology, STMicroelectronics, ON Semiconductor, Texas Instruments, Analog Devices, NXP Semiconductors, Microchip Technology, Maxim Integrated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Supply Isolation Equipment Market Evolving Landscape
Material science advances and regulatory disclosure mandates are compressing traditional isolation technology lifecycles. Component suppliers must now validate performance across wider temperature ranges while documenting supply chain provenance.
Capacitive isolation with integrated signal conditioning is consolidating socket share in renewable energy inverters and electric vehicle powertrains. Wind turbine manufacturers in Denmark and onshore solar developers in Texas are specifying these devices for their sub-picosecond jitter characteristics. The technology is consolidating what were previously discrete transformer-plus-optoisolator subassemblies into single-package solutions.
REACH substance restrictions and RoHS substance thresholds are forcing reformulation of epoxy encapsulants and solder alloys used in isolation barrier construction. German industrial OEMs and French medical device manufacturers are requiring full material declaration documentation from component suppliers. High-reliability automotive applications in Stuttgart and Wolfsburg are most affected, with qualification timelines extending to capture new chemistry validation.
Specification authority is migrating from component distributors to OEM direct engineering engagement. Procurement teams at Japanese automotive tier-ones and Korean semiconductor equipment builders are bypassing catalog distributors for isolation component selection. This pattern is most visible in Munich and Tokyo metropolitan areas, where field application engineers now participate in architecture decisions previously reserved for purchasing departments.
Power Supply Isolation Equipment Market Segmentation
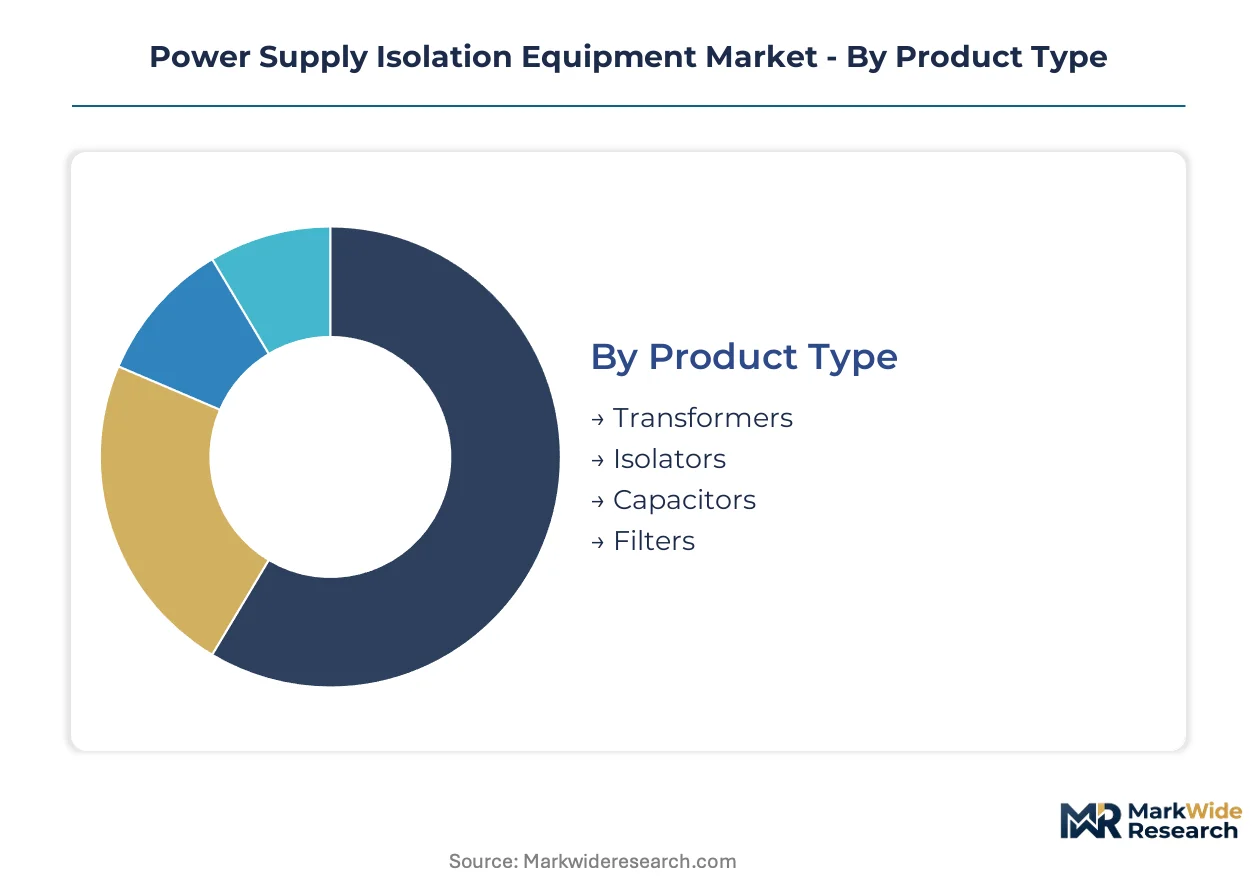
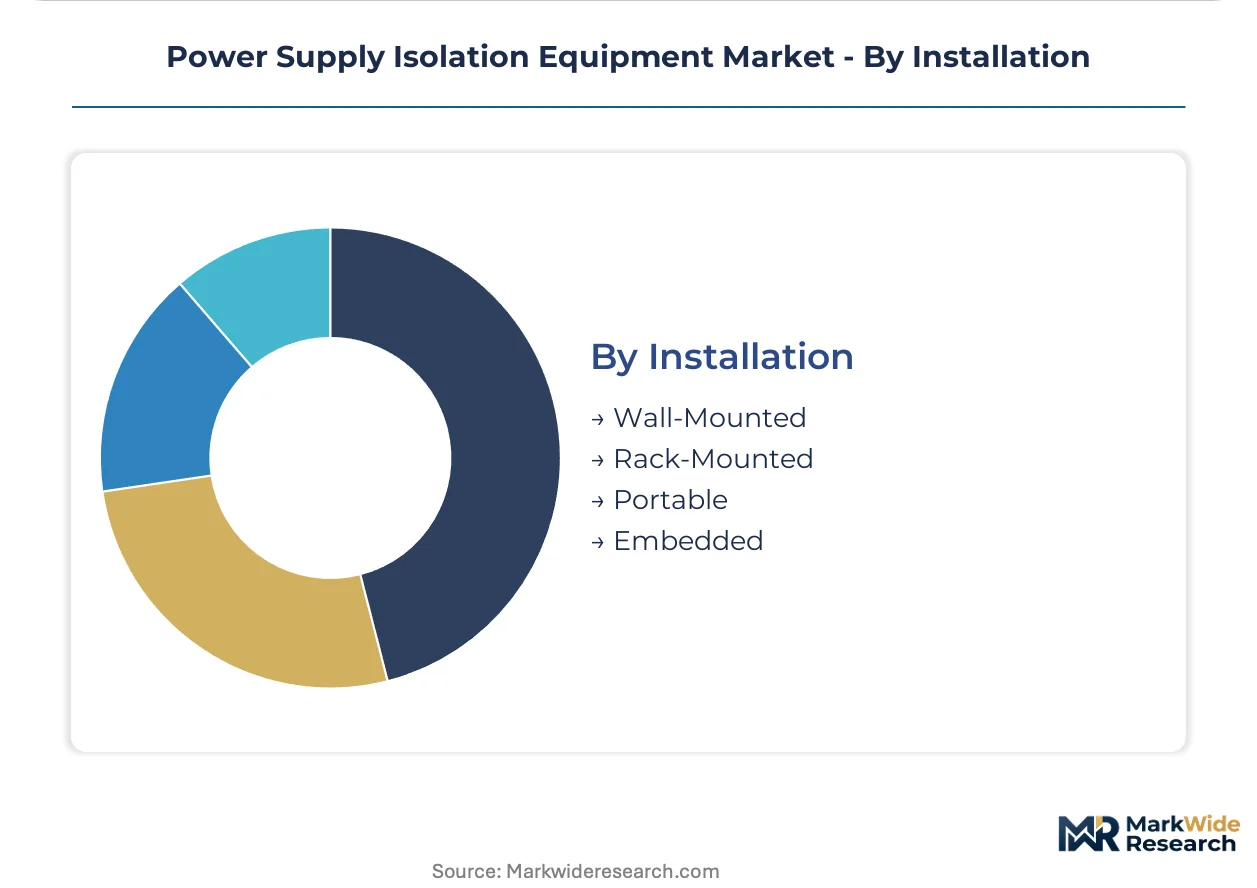
Segmentation in power supply isolation equipment reveals distinct procurement patterns across integration depths. Standalone wall-mounted and rack-mounted units serve infrastructure retrofits, while embedded configurations dominate next-generation system designs.
Product Type:
Integration depth varies sharply—transformers and isolators frequently embed directly into power supply modules, whereas capacitors and filters appear in both standalone and integrated configurations depending on noise suppression requirements.
- Transformers:Magnetic core assemblies rated for 500V to 5kV isolation block DC paths while transferring AC power across galvanic boundaries. Demand clusters in industrial automation retrofits across Germany's Ruhr Valley manufacturing belt, driven by IEC 62368-1 safety recertification deadlines.
- Isolators:Silicon-based and silicon carbide devices provide signal isolation with propagation delays below 50 nanoseconds. Data center operators in Northern Virginia and Frankfurt specify these for 150°C ambient operation in hyperscale power distribution units.
- Capacitors:Ceramic dielectric barriers suppress high-frequency transients in telecommunications base stations.
- Filters:EMI suppression networks protect sensitive control electronics in medical imaging equipment.
Volume placements concentrate in transformers; the faster expansion belongs to isolators.
Technology:
Cost tier stratification separates premium optical and ceramic solutions from standard magnetic implementations, with RF isolation occupying a specialized niche.
- Magnetic:Ferrite-core transformers and inductors deliver EMI resilience in heavy-industrial environments. Steel mills in Pittsburgh and chemical plants along the Houston Ship Channel maintain decades-old magnetic isolation architectures.
- Ceramic:Temperature-stable dielectric materials enable miniaturization in 5G base stations and EV onboard chargers. Shenzhen and Seoul manufacturing clusters drive qualification cycles for ceramic barriers rated above 125°C.
- Optical:LED-phototransistor pairs achieve patient-contact safety certifications for medical devices.
- RF:Isolation transformers for radio frequency applications serve broadcast and radar systems.
Magnetic technology holds the largest installed base; ceramic barriers are climbing the fastest.
End User:
Application-specific requirements dictate isolation voltage ratings, with medical and renewable energy demanding the highest certification burdens.
- Telecommunications:Base station power supplies require isolation components with sub-picosecond jitter for 5G signal integrity. Network equipment builders in Tokyo and Ericsson's Swedish supply base specify ceramic and magnetic solutions for outdoor cabinet deployments.
- Industrial Automation:Programmable logic controllers and motor drives need robust EMI immunity across 20-year equipment lifecycles. German automotive tier-ones in Stuttgart and Wolfsburg demand pin-compatible replacements for legacy magnetic isolators.
- Renewable Energy:Solar inverters and wind turbine power converters require reinforced isolation between high-voltage DC buses and control electronics.
- Medical Devices:Patient-contact equipment mandates FDA 510(k) electrical safety certifications for isolation barriers.
Industrial automation generates the highest unit volumes; renewable energy inverters show the steepest expansion trajectory.
Installation:
Customer type splits between infrastructure owners specifying standalone units and OEM engineers embedding isolation into subsystem designs.
- Wall-Mounted:Enclosed isolation transformers for facility power distribution serve commercial building retrofits. Electrical contractors in Texas and Florida specify these for hurricane-resistant backup power systems.
- Rack-Mounted:Standardized 19-inch chassis units integrate into data center power distribution architectures. Hyperscale operators in Singapore and Northern Virginia standardize on hot-swappable rack-mounted isolation for maintenance continuity.
- Portable:Mobile isolation transformers support temporary power in construction and event production.
- Embedded:Chip-scale and module-level isolation components integrate directly into printed circuit board assemblies.
Rack-mounted units dominate data center procurement; embedded configurations are gaining share fastest in automotive and telecommunications OEM programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for power supply isolation equipment concentrates in East Asian manufacturing corridors and German industrial zones. Hyperscale data center buildouts in Northern Virginia and renewable energy deployments across Texas create secondary demand poles. Regulatory divergence across jurisdictions is fragmenting qualification timelines and forcing suppliers to maintain multiple certification tracks.
China
Data center power infrastructure and EV onboard charger production drive procurement volumes in the Yangtze River Delta and Pearl River Delta. GB 4943.1 energy efficiency mandates and SAMR efficiency labeling requirements disqualify legacy silicon isolators from domestic server tenders. Shenzhen manufacturing clusters accelerate ceramic isolation qualification cycles for 5G base station deployments.
United States
Hyperscale operators in Northern Virginia specify isolation components rated for 150°C ambient operation in hyperscale power distribution units. FERC grid interconnection standards and FDA electrical safety requirements for medical devices elevate certification burdens for suppliers. Texas wind and solar developers deploy reinforced isolation barriers in grid-tied inverter installations across the ERCOT footprint.
Germany
Industrial automation retrofits across the Ruhr Valley manufacturing belt demand pin-compatible magnetic isolation replacements for legacy systems. REACH substance restrictions and RoHS thresholds force reformulation of epoxy encapsulants in isolation barrier construction. Stuttgart automotive tier-ones require full material declaration documentation from component suppliers for high-reliability applications.
Japan
Telecommunications base station builders in Tokyo specify ceramic and magnetic solutions with sub-picosecond jitter for 5G outdoor cabinet deployments. METI efficiency standards and JIS certification requirements shape procurement specifications for network equipment. Osaka-area semiconductor equipment manufacturers bypass catalog distributors for direct engineering engagement on isolation component selection.
South Korea
Semiconductor equipment builders in Seoul metropolitan area drive demand for isolation components with sub-nanosecond propagation delay. MFDS medical device regulations and KTL safety certifications create parallel qualification tracks for patient-contact applications. Busan-Ulsan manufacturing corridor concentrates production of thick-film resistor isolators serving regional industrial automation customers.
Power Supply Isolation Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with component suppliers holding pricing power in certified medical and automotive sockets while contract assemblers compete on cost in industrial retrofits. The vendor base arranges into three tiers: integrated semiconductor manufacturers with captive wafer supply, specialized isolation component houses with deep certification expertise, and regional contract manufacturers serving price-sensitive retrofit markets. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing six-inch SiC substrate allocations or partnering with testing laboratories to compress IEC 62368-1 qualification timelines.
Among European integrated semiconductor manufacturers, Infineon Technologies and STMicroelectronics occupy positions defined by upstream control over silicon carbide substrate production. Texas Instruments and Analog Devices represent the North American capacitive isolation archetype, while Vishay Intertechnology anchors the specialized thick-film resistor segment. These named entities exemplify how geographic origin and company structure correlate with competitive positioning: German and Swiss corporations emphasize vertical manufacturing depth, US-based firms prioritize integrated signal conditioning, and specialized houses maintain focus on narrow certification domains.
| Leading Market Players |
|---|
| Infineon Technologies |
| Vishay Intertechnology |
| STMicroelectronics |
| ON Semiconductor |
| Texas Instruments |
| Analog Devices |
| NXP Semiconductors |
| Microchip Technology |
| Maxim Integrated |
| Others |
Value Network & Pricing Analysis
Silicon carbide substrate production is compressing isolation component cost curves while concentrating supply leverage among wafer manufacturers with captive SiC crystal growth capabilities. This dual transformation simultaneously elevates performance premiums for ceramic and magnetic isolation barriers and tightens margin predictability for component houses lacking backward integration into substrate supply.
Pricing Analysis
Volume placements in industrial-grade magnetic transformers run at thin margins, while certified medical and automotive sockets command substantial premiums. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k) certified optical isolators from industrial-grade magnetic units and unqualified catalog components. Cost compression in standard magnetic tiers is intensifying because copper and ferrite input volatility above fifteen percent quarterly erodes contract profitability. Data center operators in Northern Virginia and Singapore exhibit the least price sensitivity, prioritizing 150°C ambient ratings over unit cost; contract manufacturers serving Southeast Asian industrial retrofits face the highest procurement pressure.
Supply Chain Analysis
Dual-sourcing requirements from German automotive tier-ones and Japanese telecommunications OEMs mandate multi-supplier qualification for SiC-based isolators and ceramic dielectric barriers. Production concentrates in China, Germany, and Japan, with Shenzhen and Seoul clusters feeding East Asian manufacturing demand. Supply chains draw from silicon carbide wafers, high-permeability ferrite cores, and ceramic dielectric substrates as critical inputs. Single-source vulnerability in six-inch and eight-inch SiC substrate supply creates allocation risk during capacity constraints. Distribution runs through direct OEM engineering engagement in premium sockets, with catalog distributors retaining share in price-sensitive industrial retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacitive isolation with integrated gate drivers is displacing legacy transformer-plus-optoisolator subassemblies across renewable energy and electric vehicle powertrains. Component suppliers must navigate this substitution cycle while managing certification timeline compression.
For Market Incumbents: Hedge SiC wafer supply exposure through long-term offtake agreements with substrate manufacturers or captive crystal growth investments. Accelerate IEC 62368-1 third edition pre-qualification testing to compress new product introduction cycles threatened by eight-to-fourteen month regulatory delays. Deepen backward integration into ceramic dielectric material production to defend margin position against ferrite core cost volatility.
For New Entrants and Emerging Players: Field application engineering teams represent the critical channel partner type for bypassing distributor control in data center and automotive procurement decisions. Target India's PLI scheme electronics manufacturing corridors, where BIS certification requirements for power supplies create demand for locally qualified isolation component suppliers. Pursue qualification partnerships with testing laboratories to compress regulatory approval timelines relative to established competitors.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated semiconductor manufacturers seeking isolation technology portfolios. Long-term viability favors specialists with certified medical and automotive safety expertise over undifferentiated industrial component houses. Watch SiC substrate allocation announcements as the inflection indicator for which isolation component suppliers can scale next-generation product lines.
| Strategic Initiative | Industry Significance |
|---|---|
| SiC Substrate Supply Agreement | Secures wafer allocation from Wolfspeed or Coherent for isolation component scaling. |
| IEC 62368-1 Pre-Certification Investment | Compresses eight-to-fourteen month testing timelines for medical and IT equipment sockets. |
| India Manufacturing Localization | Captures PLI scheme incentives and BIS certification requirements for domestic power supply tenders. |
| Integrated Gate Driver Development | Consolidates discrete subassemblies into single-package solutions for renewable energy inverters. |
| Carbon Footprint Certification Program | Meets EU CSRD disclosure mandates for preferential supplier status with European industrial OEMs. |
Research Methodology
Document review covered SEC 10-K filings, IEC standard committee drafts, and SAMR efficiency labeling databases, complemented by interviews with power electronics design engineers, data center facility managers, automotive tier-one procurement leads, and semiconductor equipment manufacturers. Primary fieldwork engaged isolation component suppliers in Shenzhen, Seoul, and Stuttgart manufacturing clusters. Secondary validation drew from customs trade data, hyperscaler capex disclosures, and FDA 510(k) submission records. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across product type, technology, and end-user segmentation dimensions.
Cross-referencing historical pricing elasticity against expert panel input shaped the analytical framework for volume and value projections across the analysis window. Segmentation modeling captured integration depth, isolation voltage rating tiers, thermal performance thresholds, and regional regulatory cluster variations. CAGRs derived from coupled growth rate analysis across technology substitution curves and end-market expansion patterns. Forecast inputs incorporated SiC substrate capacity buildout schedules, GB 4943.1 enforcement timelines, and data center power density specification trajectories.
Caveats apply where SiC wafer supply concentration, IEC 62368-1 third edition implementation delays, or copper and ferrite commodity price spikes could materially shift the outlook. Forecasts reflect assumptions regarding technology transition rates and regulatory enforcement consistency. Deviation in substrate allocation priority or certification timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Automotive Power Electronics Market
Power Systems
Thermal Management Systems Market
Power Systems
PV Inverter Market
Power Systems
Asia Pacific Low Voltage Drives Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market
Power Systems
AC Voltage Transducer Market
Power Systems
Asia-Pacific IGBT and Super Junction MOSFET Market
Power Systems
Embedded Power Generation Market
Power Systems
PV Micro Inverters Market
Power Systems
Power Electronics Equipment Cooling System Market
Power Systems
High Voltage Ceramic Zinc Oxide Surge Arrester Market
Power Systems
Smart Junction Box and Power Distribution Box Systems Market
Power Systems
High Current Power Supply for Electrophoresis Market
Power Systems
DC-DC Converter Market
Power Systems
Voltage Regulators Market