
 Radio Frequency Test Equipment Market | 2026-2036
Radio Frequency Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Radio Frequency Test Equipment Market Analytics
Millimeter-wave integration into commercial test workflows is reconfiguring how semiconductor and telecom manufacturers validate radio performance. Keysight Technologies leverages extensive calibration IP to dominate high-frequency bench solutions. Anritsu Corporation anchors field-portable 5G test portfolios for network deployment crews. Rohde & Schwarz sustains European defense and automotive radar test leadership through deep R&D investment.
Radio frequency test equipment comprises instruments that characterize electromagnetic signal behavior across specified frequency ranges, typically employing vector analysis, spectral decomposition, or synthesized stimulus generation to measure parameters including power, distortion, phase noise, and spurious emissions for component and system validation. Spectrum analyzers capture the largest installed base due to their ubiquity across cellular, aerospace, and broadcast compliance workflows, while software-defined architectures represent the fastest-expanding technology segment as programmable instrumentation replaces discrete hardware for multi-standard flexibility. Network analyzers command premium pricing in millimeter-wave bands where s-parameter characterization demands precision metrology, and manufacturing testing applications absorb the highest instrument volume as production lines automate pass-fail screening.
The FCC in the United States, ETSI across Europe, and MIIT in China each enforce distinct emission mask and spurious limit regimes that compel manufacturers to maintain geographically calibrated test capabilities. REACH and RoHS frameworks further constrain material compositions in probe assemblies and connector plating, adding compliance cost layers to hardware refresh cycles. Stakeholders must weigh spectrum auction timelines against instrument depreciation schedules when committing capital to next-generation test floors.
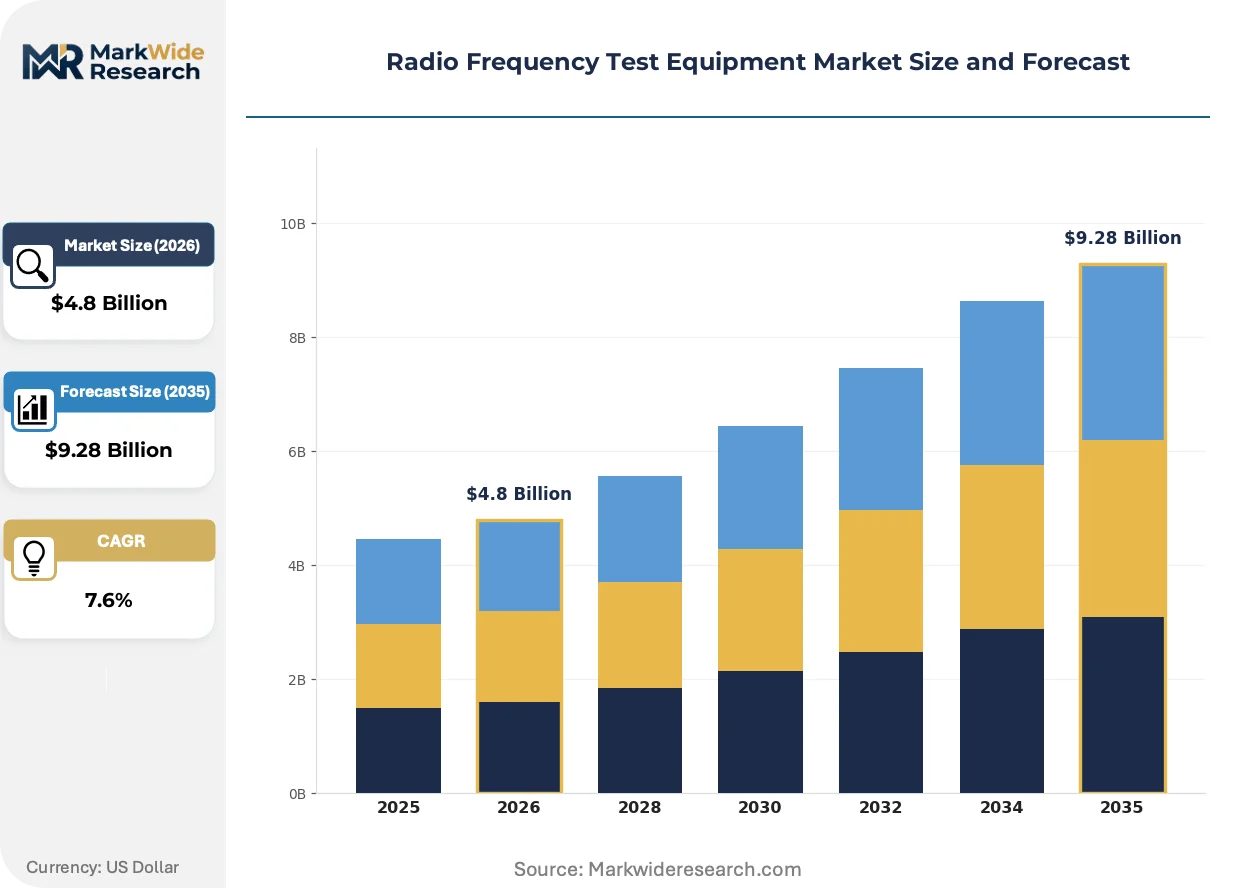
Market Dynamics
Millimeter-wave test requirements are compressing refresh cycles as 5G-Advanced and 6G research push frequency boundaries beyond 100 GHz, forcing capital redeployment toward multi-band capable instrumentation.
Growth Catalysts
- FCC spectrum reallocation mandates:Auctions of C-band and 3.45 GHz spectrum in the United States compel broadcast and satellite operators to upgrade emission test suites, sustaining replacement demand through 2030.
- China base station manufacturing scale:Domestic production of 5G massive MIMO arrays by Huawei and ZTE concentrates procurement of vector signal analyzers in Shenzhen and Chengdu test corridors.
- Automotive radar validation:77-81 GHz frequency-modulated continuous-wave sensors for adaptive cruise control require compact over-the-air test chambers, expanding semiconductor foundry metrology budgets.
Market Restraints
- Precision connector supply concentration:2.4 mm and 1.85 mm test port components rely on Japanese and German specialty manufacturers, creating 16-20 week lead time vulnerability during capacity constraints.
- RoHS material restrictions:REACH and RoHS frameworks in Europe constrain cadmium-free plating alternatives for coaxial probe assemblies, elevating component costs and qualification timelines.
- Skilled metrologist scarcity:Calibration expertise for thermal drift compensation in mmWave bands concentrates among retiring specialists in aerospace and defense laboratories, constraining service expansion.
Strategic Opportunities
- India telecom infrastructure buildout:Reliance Jio and Bharti Airtel 5G network densification creates demand for field-portable spectrum monitors in Mumbai, Delhi, and Bangalore deployment zones.
- AI-driven test automation:Machine learning algorithms for anomaly detection in production line screening reduce operator intervention, enabling subscription-based software revenue streams alongside hardware sales.
- Open RAN interoperability mandates:European and US carrier requirements for multi-vendor base station validation expand protocol test system procurement beyond traditional integrated equipment suppliers.
Industry Challenges
- Multi-standard firmware complexity:Simultaneous support for 5G NR, Wi-Fi 7, and UWB test modes strains embedded software teams, delaying feature release schedules against competitor roadmaps.
- Traceability audit burden:ISO/IEC 17025 accreditation requirements for calibration laboratories impose documentation overhead that consumes 15-20% of technical staff capacity in mid-sized service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radio Frequency Test Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Signal Generators, Spectrum Analyzers, Network Analyzers, Oscilloscopes Technology: Analog, Digital, Software-Defined, Microwave End User: Aerospace, Telecommunications, Automotive, Electronics Application: Research & Development, Manufacturing Testing, Compliance Testing, Field Testing |
| Companies Covered | Keysight Technologies, Anritsu Corporation, Rohde & Schwarz, Tektronix, Teledyne Technologies, National Instruments, Yokogawa Electric Corporation, VIAVI Solutions, EXFO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radio Frequency Test Equipment Market Evolving Landscape
Software-defined instrumentation architectures are compressing hardware replacement cycles while expanding remote test capabilities across distributed manufacturing networks and field service operations.
Direct digital synthesis and FPGA-based real-time processing are rendering obsolete discrete local oscillator chains in mid-range spectrum analyzers. Semiconductor fabs in South Korea and Taiwan now specify software-upgradeable platforms for 5G and 6G protocol validation, compressing capital expenditure amortization from seven years to four.
ETSI's harmonized standards for 6 GHz Wi-Fi and 5G NR unlicensed operation in Europe mandate updated spurious emission test masks. Test house laboratories in Germany and France must acquire new vector signal generators capable of 8 GHz carrier aggregation, redirecting investment from legacy cellular-only equipment.
Leasing and managed service contracts now displace outright purchase for tier-two contract manufacturers in Mexico and Vietnam. These arrangements bundle hardware, calibration, and software maintenance into per-test-unit pricing, transferring obsolescence risk from capital-constrained buyers to original equipment vendors seeking recurring revenue stability.
Radio Frequency Test Equipment Market Segmentation
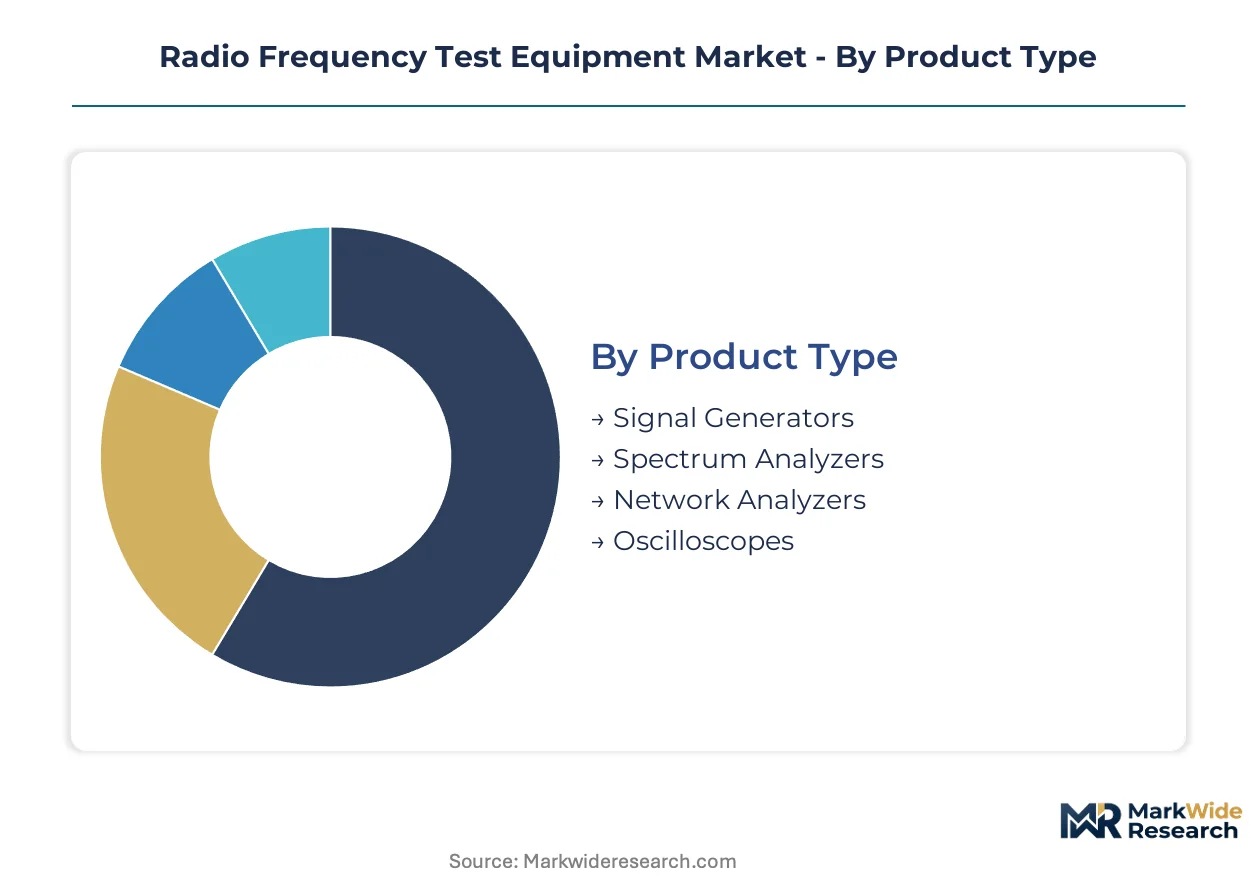
Radio frequency test equipment segments diverge sharply in service intensity and calibration cadence. Spectrum analyzers demand annual metrology recertification, while software-defined platforms shift service revenue toward firmware subscription models.
Product Type:
After-sales service intensity varies dramatically across instrument categories, with precision microwave units requiring quarterly drift compensation and field-portable gear demanding rapid depot turnaround.
- Spectrum Analyzers:Capture spurious emissions and harmonic distortion across cellular, aerospace, and broadcast compliance workflows. Demand concentrates in Shenzhen test corridors where Huawei and ZTE massive MIMO production lines require swept-frequency validation at volume. Calibration protocols here consume 15-20% of total cost of ownership.
- Network Analyzers:Characterize s-parameters for antenna and filter design with precision metrology at millimeter-wave bands. Procurement clusters among German automotive radar developers and South Korean semiconductor foundries validating 77-81 GHz sensor substrates. These units command premium service contracts due to thermal stability requirements.
- Signal Generators:Provide synthesized stimulus for receiver sensitivity and intermodulation testing across R&D benches.
- Oscilloscopes:Capture time-domain transients in power amplifier and digital baseband verification workflows.
By volume, Spectrum Analyzers leads. By growth pace, Network Analyzers is ahead.
Technology:
Cost tier stratification separates legacy analog architectures from FPGA-based platforms that compress hardware refresh cycles through programmable upgrades.
- Software-Defined:FPGA-based real-time processing replaces discrete local oscillator chains, enabling multi-standard flexibility through firmware updates. Semiconductor fabs in Taiwan and South Korea specify these platforms for 5G and 6G protocol validation, compressing capital amortization from seven years to four. Subscription revenue models are displacing outright purchase among tier-two contract manufacturers.
- Microwave:Addresses frequency-modulated continuous-wave radar and satellite communication test requirements above 40 GHz. Demand anchors in European defense laboratories and US aerospace contractors validating phased array architectures. Lead times for precision connectors create 16-20 week procurement vulnerability.
- Analog:Sustains installed base in budget-constrained education and maintenance repair operations.
- Digital:Dominates mid-range production line screening with deterministic processing for pass-fail automation.
By installed base, Analog dominates. By expansion trajectory, Software-Defined is climbing the fastest.
End User:
Application maturity dictates procurement sophistication, with aerospace demanding traceable calibration chains and automotive emphasizing compact over-the-air chamber integration.
- Telecommunications:5G base station deployment and Open RAN interoperability mandates drive vector signal analyzer procurement. FCC spectrum reallocation compels US operators to upgrade emission test suites, while Reliance Jio and Bharti Airtel densification in Mumbai and Delhi creates field-portable monitor demand. This segment absorbs the highest instrument volume through automated manufacturing lines.
- Automotive:77-81 GHz adaptive cruise control sensors require compact over-the-air test chambers, expanding semiconductor foundry metrology budgets. German Tier-1 suppliers and US EV manufacturers specify multi-target simulation capabilities for radar cross-section validation. Validation timelines here are compressing with each new NCAP safety rating cycle.
- Aerospace:Defense contractors maintain geographically calibrated test floors for ITAR-controlled program compliance.
- Electronics:Consumer device manufacturers prioritize throughput over precision for Wi-Fi and UWB module screening.
By revenue concentration, Telecommunications leads. By investment intensity per test station, Aerospace is gaining share fastest.
Application:
Customer type separation distinguishes capital-intensive R&D benches from high-throughput manufacturing floors where per-test-unit pricing models are displacing ownership.
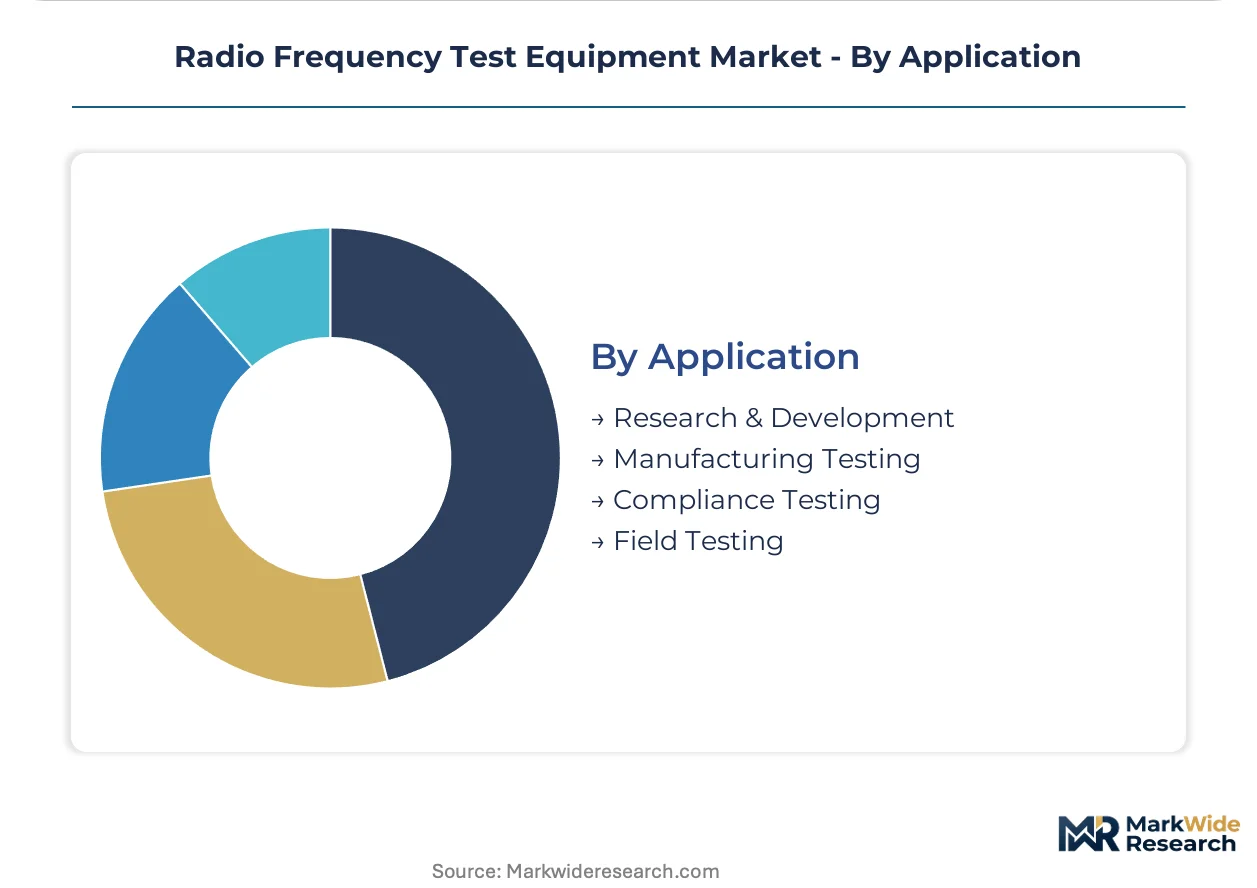
- Manufacturing Testing:Automated pass-fail screening absorbs the highest instrument volume as production lines scale for 5G massive MIMO and automotive radar module output. Leasing and managed service contracts now dominate tier-two contract manufacturers in Mexico and Vietnam, bundling hardware, calibration, and software maintenance into operational expenditure. Machine learning algorithms for anomaly detection reduce operator intervention.
- Compliance Testing:ETSI harmonized standards for 6 GHz Wi-Fi and 5G NR unlicensed operation mandate updated spurious emission masks. Test houses in Germany and France must acquire vector signal generators capable of 8 GHz carrier aggregation, redirecting investment from legacy cellular-only equipment. ISO/IEC 17025 accreditation imposes documentation overhead consuming technical staff capacity.
- Research & Development:Millimeter-wave boundaries beyond 100 GHz for 5G-Advanced and 6G research force capital redeployment toward multi-band capable instrumentation.
- Field Testing:Network deployment crews prioritize battery endurance and ruggedized packaging over laboratory precision.
By deployment scale, Manufacturing Testing leads. By specification advancement rate, Research & Development shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German test equipment exports flow into automotive radar validation centers across South Korea and Taiwan, while Shenzhen manufacturing corridors absorb the highest instrument volume for 5G massive MIMO production lines.
United States
FCC spectrum reallocation mandates for C-band and 3.45 GHz auctions compel broadcast and satellite operators to upgrade emission test suites. The FCC enforces distinct emission mask regimes that require geographically calibrated test capabilities. Test floor investments concentrate in Dallas-Fort Worth and San Diego defense corridors where phased array validation drives multi-band instrumentation procurement.
China
Domestic base station manufacturing by Huawei and ZTE concentrates vector signal analyzer demand in Shenzhen and Chengdu test corridors. MIIT enforces spectrum allocation frameworks that accelerate equipment refresh cycles for 5G-Advanced deployment. Semiconductor foundries in Shanghai and Beijing specify software-defined platforms for protocol validation, compressing capital amortization schedules.
Germany
Automotive Tier-1 suppliers validate 77-81 GHz frequency-modulated continuous-wave sensors for adaptive cruise control systems. ETSI harmonized standards for spurious emission test masks redirect investment from legacy cellular-only equipment. Test house laboratories in Munich and Stuttgart acquire vector signal generators capable of 8 GHz carrier aggregation for 6 GHz Wi-Fi compliance.
South Korea
Semiconductor fabs specify software-upgradeable platforms for 5G and 6G protocol validation, compressing capital expenditure amortization timelines. The country's national telecommunications regulator enforces emission standards that align with ETSI frameworks for equipment interoperability. Foundry metrology budgets expand in Hwaseong and Pyeongtaek clusters where automotive radar substrate validation commands premium service contracts.
India
Reliance Jio and Bharti Airtel 5G network densification creates demand for field-portable spectrum monitors in Mumbai, Delhi, and Bangalore deployment zones. TRAI spectrum auction timelines force operators to commit capital against instrument depreciation schedules. Manufacturing test corridors in Pune and Chennai absorb automated pass-fail screening equipment for contract electronics production.
Radio Frequency Test Equipment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where calibration IP and firmware ecosystems determine pricing power. The market consolidates around three strategic archetypes: precision metrology incumbents with deep R&D investment, software-defined platform vendors seeking subscription revenue, and field-portable specialists targeting network deployment crews. Dominant competitive moves include technology licensing for multi-standard firmware and geographic expansion through managed service contracts.
Within the precision metrology tier, Keysight Technologies and Rohde & Schwarz exemplify archetypes anchored in extensive calibration IP and European defense laboratory relationships respectively. Anritsu Corporation occupies a position among field-portable specialists. These three entities represent the spectrum from bench-dominated high-frequency solutions to ruggedized deployment equipment, with each anchoring distinct service intensity models across telecommunications and aerospace validation workflows.
| Leading Market Players |
|---|
| Keysight Technologies |
| Anritsu Corporation |
| Rohde & Schwarz |
| Tektronix |
| Teledyne Technologies |
| National Instruments |
| Yokogawa Electric Corporation |
| VIAVI Solutions |
| EXFO |
| Others |
Value Network & Pricing Analysis
Shenzhen manufacturing corridors concentrate precision connector fabrication capacity for 2.4 mm and 1.85 mm test port assemblies, creating asymmetric pricing power for Japanese and German specialty suppliers who command 16-20 week lead time premiums during capacity constraints. This geographic concentration compresses margins for mid-range instrument vendors while amplifying returns for incumbents with captive calibration IP.
Pricing Analysis
Current-generation software-defined platforms command 40-60% premiums over prior-generation analog architectures, while next-generation millimeter-wave instrumentation above 100 GHz sustains further markups through scarcity of thermal drift compensation expertise. Three-tier pricing structure across premium metrology-grade, standard production-test, and economy education-tier levels stratifies procurement budgets, with certification-grade ISO/IEC 17025 traceability driving the widest spreads. Pricing pressure stems from tier-two contract manufacturers in Mexico and Vietnam demanding per-test-unit operational expenditure models that transfer obsolescence risk upstream. Automotive radar validation labs show least price sensitivity due to NCAP safety cycle compression, while education and maintenance repair operations exhibit highest elasticity.
Supply Chain Analysis
Export-control regimes under ITAR and EAR classifications restrict millimeter-wave synthesizer and FPGA-based real-time processing technology flows to defense-aerospace end users, fragmenting procurement channels between commercial and controlled segments. Component supply concentrates in Japan for precision coaxial assemblies, Germany for thermal-stable metrology-grade hardware, and Taiwan for high-volume semiconductor test integration. Raw material dependencies span beryllium-copper alloy substrates, cadmium-free plating alternatives constrained by REACH frameworks, and synthetic sapphire for low-loss dielectric applications. Single-source vulnerability concentrates in sub-2.0 mm precision connector manufacturing. Distribution runs through direct OEM relationships for tier-one accounts and authorized distributor networks for mid-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radio frequency test equipment sits in early-cycle expansion as 5G-Advanced deployment and 6G research programs accelerate instrument refresh timelines beyond traditional seven-year amortization schedules.
For Market Incumbents: Entrench calibration IP moats through automated drift compensation algorithms that reduce skilled metrologist dependency, while acquiring field-portable specialists to preempt Anritsu-class competitors from consolidating network deployment crew relationships. Vertical integration into precision connector manufacturing mitigates 16-20 week lead time vulnerability from Japanese and German suppliers. Priority investment in software-defined firmware ecosystems captures subscription revenue displacement of outright purchase models. For New Entrants and Emerging Players: Pursue India telecom infrastructure buildout where Reliance Jio and Bharti Airtel densification creates field-portable spectrum monitor demand without incumbent channel saturation. Target Open RAN interoperability validation as the most penetrable segment, where European and US carrier multi-vendor mandates expand procurement beyond traditional integrated equipment suppliers. Go-to-market leverage through managed service contracts bundles hardware, calibration, and software maintenance into operational expenditure pricing that appeals to capital-constrained tier-two manufacturers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined platform vendors with recurring firmware revenue over hardware-dependent legacy analog incumbents. Long-term viability across the projection horizon hinges on 5G-Advanced and 6G frequency boundary expansion sustaining multi-band instrumentation demand. Acquisition target archetype: field-portable specialists with ruggedized deployment equipment and network crew channel relationships. Signal to watch: FCC spectrum auction timelines against carrier capital commitment schedules as inflection indicator for replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration IP Acquisition | Automated thermal drift compensation reduces dependency on retiring aerospace metrologists. |
| Software-Defined Platform Launch | FPGA-based architectures enable 5G and 6G protocol validation through firmware subscriptions. |
| Managed Service Contract Expansion | Per-test-unit pricing transfers obsolescence risk to vendors while securing recurring revenue. |
| Precision Connector Backward Integration | In-house production of 2.4 mm assemblies mitigates 16-20 week lead time vulnerability. |
| Open RAN Validation Partnership | Multi-vendor base station interoperability mandates expand protocol test system procurement. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Semiconductor test engineers, network deployment crew supervisors, calibration laboratory technical directors, and procurement managers at tier-one telecommunications operators provided operational perspective. Secondary sources include FCC spectrum auction records, ETSI harmonized standards documentation, MIIT equipment certification databases, and customs trade data for precision connector import flows. Bottom-up instrumentation shipment analysis triangulates against top-down capital expenditure modeling across telecommunications, automotive, and aerospace end-use segments.
Calibration against historical replacement cycles and spectrum reallocation timelines validates the analytical framework across the projection horizon. Segmentation dimensions span product type, technology architecture, end-user industry, and application workflow intensity. CAGRs derive from instrument volume elasticity to base station deployment rates and semiconductor fab capacity expansion schedules. Forecast inputs incorporate Open RAN interoperability mandate adoption curves and automotive radar sensor production scaling.
Macroeconomic conditions sit as an overlay; deviation in carrier capital expenditure commitments or spectrum auction delays would shift the trajectory. Forecasts reflect documented assumptions regarding 5G-Advanced deployment pacing and skilled metrologist availability for millimeter-wave calibration. Cross-checking against semiconductor capital equipment spending benchmarks and telecommunications infrastructure investment surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
Semiconductor Curve Tracer Market
Test and Measurement
RF Test Equipment Market
Test and Measurement
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market
Test and Measurement
Failure Analysis Equipment Market
Test and Measurement
Temperature Humidity Chambers Market
Test and Measurement
Liquid Immersion Cooling Fluid Compatibility Test Equipment Market
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
North America Electronic Test and Measurement Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
Optical Wafer Inspection Systems Market
Test and Measurement
North America Electrical Testing Services Market
Test and Measurement
Heat Deformation Tester Market
Test and Measurement
Curve Tracer Market
Test and Measurement
In-Process Composite Layup Monitoring Sensors and Test Equipment Market
Test and Measurement
Latin America Measurement and Test Equipment Market