
 Solid State Power Controller Market | 2026-2036
Solid State Power Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Solid State Power Controller Market Analytics
Defense prime contractors is rotating procurement priority toward integrated solid state power controller architectures for electric propulsion and directed-energy weapon platforms. ABB dominates marine and grid integration applications through its medium-voltage power electronics portfolio. Siemens leads traction and rail electrification segments with silicon carbide-based controller platforms. Honeywell specializes in aerospace-grade solid state controllers, leveraging its vertical integration into thermal management and packaging.
A solid state power controller is an electronic switching device that replaces electromechanical relays and contactors to manage electrical power distribution through semiconductor-based switching, typically handling voltages from 28VDC to 270VDC in aerospace and 480VAC in industrial settings with response times under 100 microseconds. Its primary purpose is to eliminate moving parts, arc faults, and mechanical wear while enabling precise programmable protection against overload, short circuit, and thermal runaway. Modular product types command the widest addressable market footprint by allowing scalable configuration across voltage and current ratings, though integrated architectures capture margin concentration in defense and aerospace programs where volume and weight constraints override cost sensitivity. Gallium nitride technology is displacing silicon MOSFETs in high-frequency applications below 650V, while silicon carbide anchors medium-voltage industrial and traction segments above 1.2kV where thermal performance determines reliability.
FAA airworthiness standards and MIL-STD-704F shape aerospace controller specifications for voltage transients and power quality, while EU F-Gas Regulation and REACH constrain thermal interface material selection for European industrial deployments. IEC 61800-5-1 and UL 508C establish safety and performance baselines for variable speed drives and motor controllers across commercial and industrial end users. Stakeholders must monitor wide-bandgap semiconductor supply chain concentration and qualification timelines for defense-grade die sourcing.
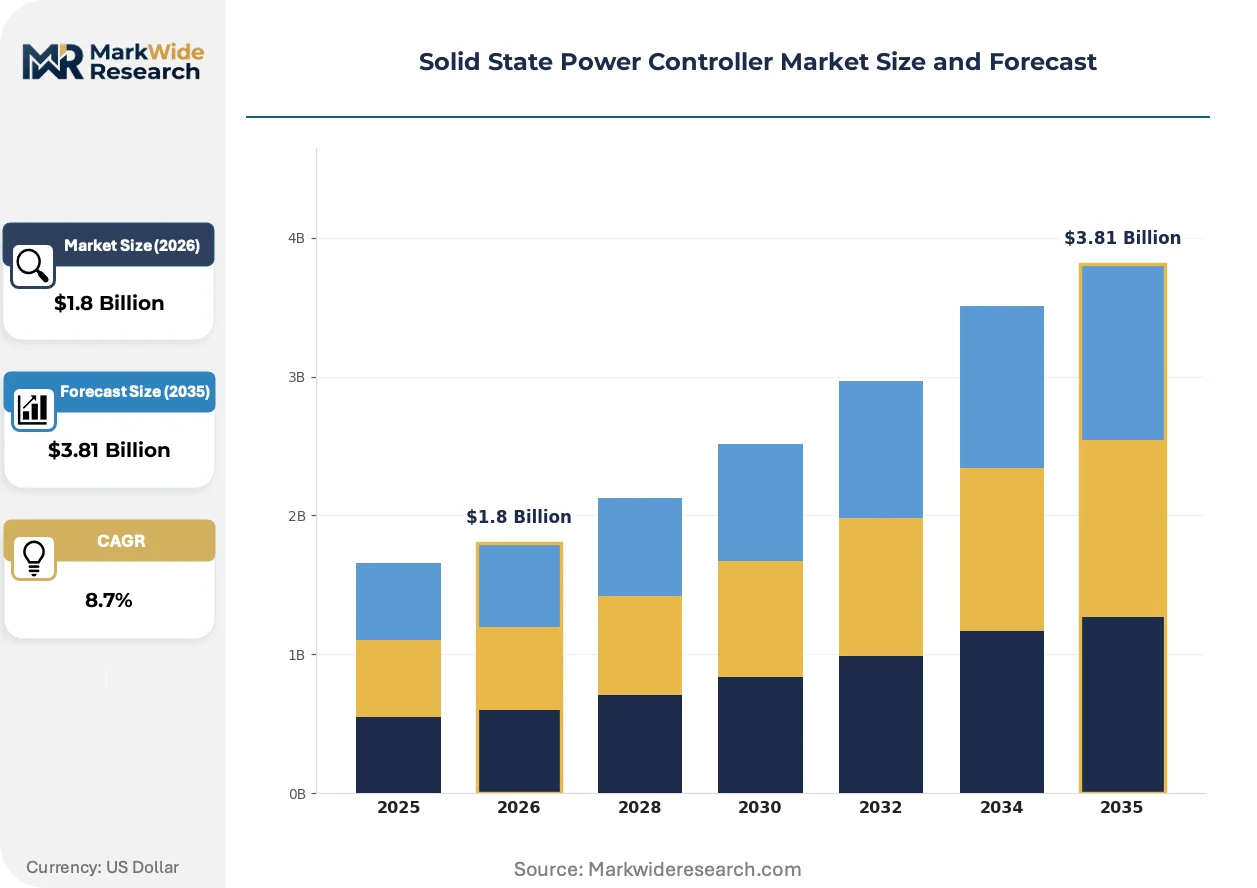
Market Dynamics
Wide-bandgap semiconductor supply concentration is compressing qualification timelines for defense-grade die sourcing, forcing tier-two aerospace suppliers into long-term offtake agreements with SiC foundries in Germany and Japan.
Growth Catalysts
- MIL-STD-704F Power Quality Mandates:US defense procurement now requires solid state controllers for all new electric propulsion platforms, eliminating electromechanical alternatives from qualified vendor lists.
- Silicon Carbide Thermal Performance:Naval integrated power systems specify SiC-based controllers for medium-voltage distribution above 1.2kV, where traditional silicon thyristors fail under thermal cycling.
- China Dual Carbon Goals:Industrial automation investments in Jiangsu and Guangdong provinces specify solid state controllers for motor drives, displacing contactors in high-frequency switching applications.
Market Restraints
- Gallium Nitride Wafer Supply Bottleneck:Six-inch GaN-on-SiC substrate production concentrates in two Japanese foundries, creating 18-month lead times for aerospace qualification batches.
- EU F-Gas Thermal Interface Constraints:REACH restrictions on fluorinated compounds limit TIM selection for European industrial deployments, forcing redesign of cooling architectures.
- Electromechanical Relay Cost Floor:Mature contactor technology in 480VAC industrial motor control maintains 60-70% cost advantage below 100A ratings, blocking solid state penetration in price-sensitive maintenance markets.
Strategic Opportunities
- Directed-Energy Weapon Power Conditioning:Pulsed power applications for laser and microwave platforms require sub-50 microsecond fault isolation, creating specification pull for integrated controller-gate driver architectures.
- Urban Air Mobility Certification Pathway:FAA SC-VTOL special conditions for electric vertical takeoff aircraft mandate solid state distribution systems, opening new airframe integration contracts.
- India PLI Scheme for Power Electronics:Production-linked incentives for semiconductor packaging attract controller assembly investments targeting railway electrification and renewable integration.
Industry Challenges
- Wide-Bandgap Device Characterization Expertise Gap:Fewer than 200 engineers globally possess combined SiC/GaN qualification experience for aerospace thermal cycling profiles, constraining OEM hiring.
- IEC 61800-5-1 Certification Timeline Compression:Variable speed drive safety testing now requires 14-18 months for modified controller platforms, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid State Power Controller Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Integrated, Modular, Hybrid Application: Manufacturing, Transportation, Defense, Renewable Energy End User: Industrial, Commercial, Residential, Military Technology: Silicon Carbide, Gallium Nitride, Thyristor, MOSFET |
| Companies Covered | Advanced Energy Industries, Watlow, Gefran, ABB, Honeywell, Schneider Electric, Siemens, Rockwell Automation, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid State Power Controller Market Evolving Landscape
Controller architectures are fragmenting between modular building-block designs for industrial scalability and highly integrated custom assemblies for aerospace weight constraints. This divergence is reshaping R&D allocation and supplier qualification pathways.
Gallium nitride power semiconductors is bifurcating the sub-650V controller segment. GaN HEMTs enable switching frequencies above 100kHz in 28VDC aerospace bus applications, cutting magnetics mass by 40% compared to silicon MOSFETs. Defense prime contractors now specify GaN for directed-energy weapon modulators and radar power supplies, while industrial motor drives below 480VAC resist adoption due to gate driver complexity and EMI certification costs.
EU F-Gas Regulation phase-down is forcing thermal management redesigns for European industrial controller deployments. Restrictions on perfluorinated compounds eliminate conventional phase-change materials from power module interfaces, pushing suppliers toward graphene-enhanced greases and sintered silver attachments. German rail electrification programs and French nuclear maintenance contracts now specify F-Gas-compliant TIMs in procurement tenders, compressing margins for legacy product lines.
Long-term power-by-the-hour contracts are displacing unit sales in marine and offshore wind applications. ABB and Siemens now offer 15-year availability guarantees for integrated controller-inverter systems, transferring operational risk from vessel operators to OEM service networks. This shift concentrates in North Sea offshore wind installations and Norwegian electric ferry fleets, where downtime penalties exceed equipment capital costs.
Solid State Power Controller Market Segmentation
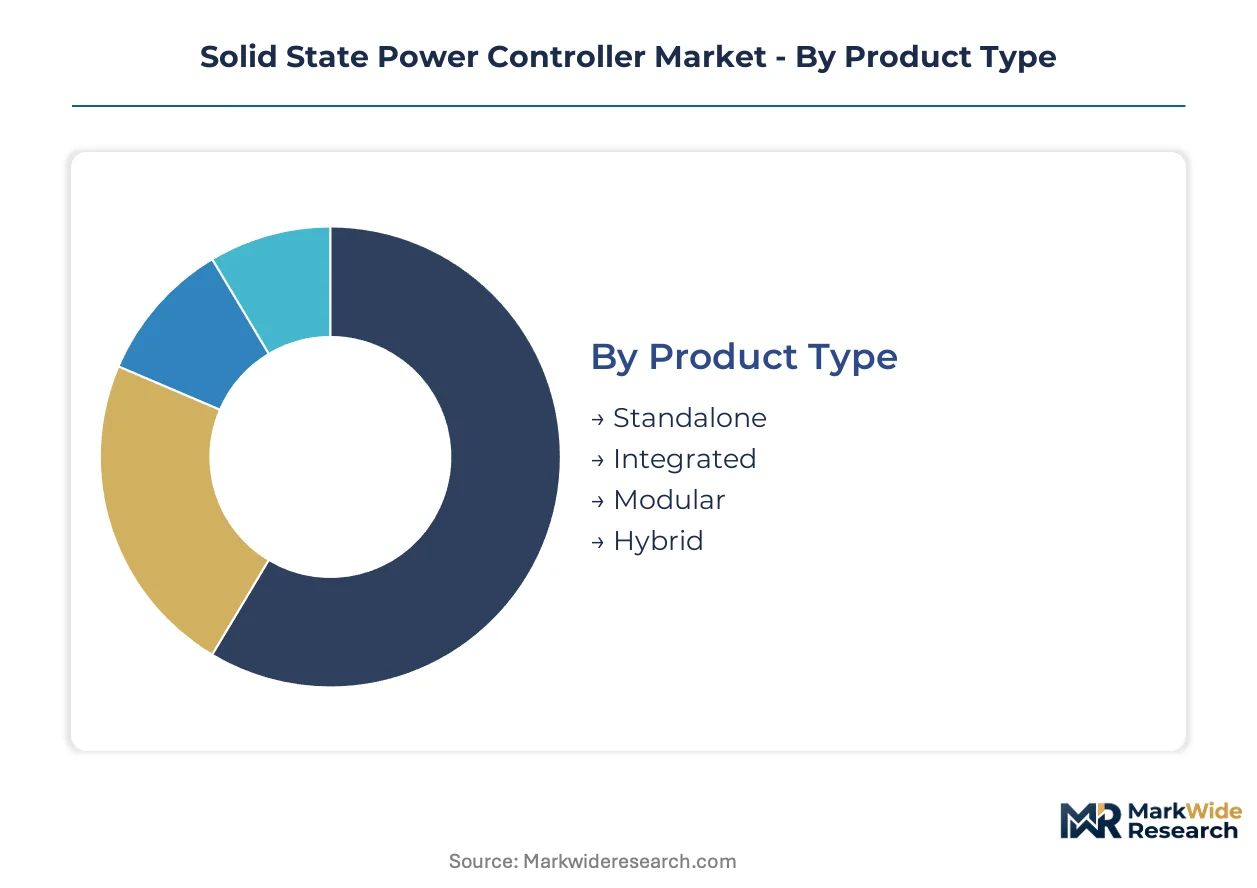
Solid state power controller architectures diverge sharply between industrial scalability and aerospace integration requirements. Semiconductor technology choices and packaging configurations determine qualification pathways, cost structures, and addressable end-use markets across each segment category.
Product Type:
Margin pools concentrate in integrated architectures where defense and aerospace programs prioritize volume and weight reduction over unit cost.
- Modular:Scalable building-block designs allow voltage and current rating reconfiguration through standardized power stages. Demand concentrates in German industrial automation and Chinese motor drive applications where facility managers require field-serviceable components without full system replacement.
- Integrated:Custom assemblies combine gate drivers, protection logic, and thermal management in single enclosures. US defense prime contractors specify these for electric propulsion platforms under MIL-STD-704F mandates, accepting 3-5x cost premiums for space and reliability gains.
- Standalone:Discrete switching units for retrofit applications in mature industrial motor control systems.
- Hybrid:Mixed electromechanical-solid state architectures bridging legacy infrastructure upgrades.
The dominant share belongs to Modular configurations, while Integrated designs are gaining share fastest through defense procurement acceleration.
Application:
Application selection tracks directly with voltage tier and switching frequency requirements across end-use environments.
- Defense:Directed-energy weapons and electric propulsion systems demand sub-50 microsecond fault isolation. Naval integrated power programs in the United States and United Kingdom specify silicon carbide controllers above 1.2kV for thermal cycling resilience in combat environments.
- Transportation:Rail electrification and emerging electric aircraft applications drive qualification of wide-bandgap devices under FAA and EU safety frameworks. Siemens and ABB dominate traction controller supply for German high-speed rail and Chinese metro expansion.
- Manufacturing:Industrial motor drives and variable speed controllers for factory automation systems.
- Renewable Energy:Grid-tie inverters and offshore wind power conversion systems.
Defense applications command premium pricing tiers, while Transportation is climbing the fastest on electrification investment cycles.
End User:
End user segmentation reflects divergent procurement authority structures and technical specification complexity.
- Military:Long-term offtake agreements and sole-source qualification pathways dominate. US Navy shipbuilding programs and UK defense modernization contracts lock suppliers into 10-15 year availability guarantees with stringent change control protocols.
- Industrial:Volume procurement through system integrators and OEM channel partners. German automotive manufacturing and Chinese heavy industry drive specification standardization around IEC 61800-5-1 safety baselines.
- Commercial:Data center power distribution and building automation systems.
- Residential:Distributed solar and smart home energy management applications.
Military end users anchor contract value concentration, with Industrial volume expanding most quickly through automation retrofits.
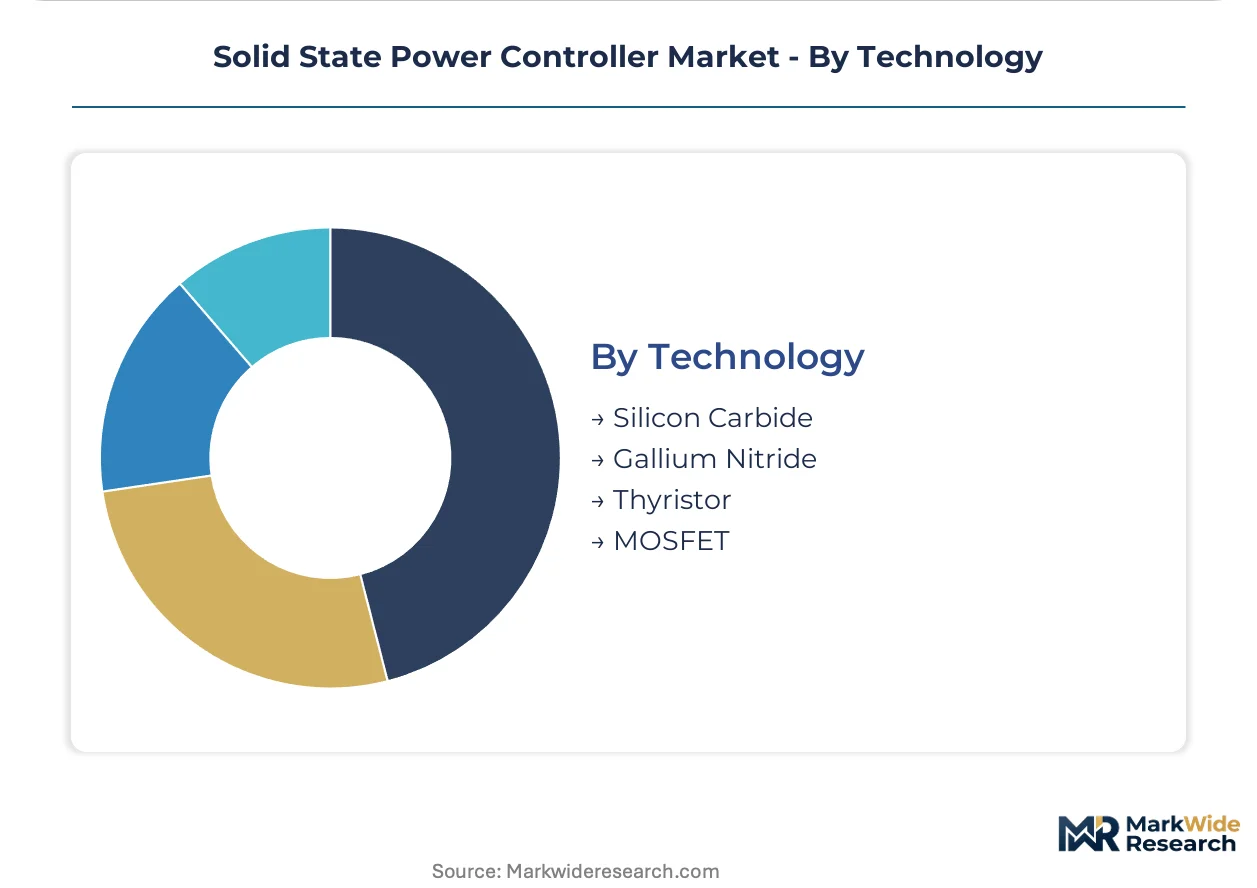
Technology:
Technology selection determines thermal performance ceilings, switching frequency capability, and defense qualification viability.
- Silicon Carbide:Wide-bandgap devices enable medium-voltage operation above 1.2kV with superior thermal conductivity. Naval power distribution and railway traction systems in Japan, Germany, and China specify SiC for reduced cooling system mass and extended reliability under thermal cycling.
- Gallium Nitride:High-electron-mobility transistors switch above 100kHz, cutting magnetics mass by 40% in 28VDC aerospace bus applications. Defense radar and directed-energy weapon modulators drive demand, constrained by six-inch GaN-on-SiC wafer supply concentration in Japanese foundries.
- Thyristor:Mature silicon technology for legacy high-power industrial installations.
- MOSFET:Cost-optimized silicon devices for sub-100A industrial motor control below 480VAC.
Silicon Carbide holds the dominant technology position, while Gallium Nitride shows the steepest expansion trajectory in aerospace and defense platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation suppliers export solid state power controllers to US defense prime contractors and Chinese railway electrification programs, establishing the dominant trade-flow corridor in this market.
United States
Defense modernization programs and FAA certification pathways for electric aircraft anchor procurement volume. MIL-STD-704F mandates eliminate electromechanical alternatives from qualified vendor lists for naval electric propulsion. The Greater Boston aerospace cluster and Seattle-Tacoma defense manufacturing base concentrate specification authority for next-generation controller architectures.
Germany
Railway electrification and industrial automation drive medium-voltage silicon carbide adoption. EU F-Gas Regulation constraints on thermal interface materials force cooling architecture redesigns for European deployments. The Ruhr industrial belt and Bavarian automotive manufacturing corridors specify IEC 61800-5-1 compliant controllers for motor drive retrofits.
China
Dual carbon goals and industrial automation investments in Jiangsu and Guangdong provinces displace contactors in high-frequency switching applications. MIIT standards and GB certification frameworks shape domestic procurement specifications. The Yangtze River Delta manufacturing cluster and Pearl River Delta electronics assembly bases concentrate controller demand for renewable integration and metro expansion.
Japan
Six-inch GaN-on-SiC wafer production concentrates in domestic foundries, creating supply bottlenecks for aerospace qualification batches. METI industrial policy supports wide-bandgap semiconductor manufacturing scale-up. The Kyushu semiconductor fabrication corridor and Nagoya aerospace supply chain anchor qualification expertise for defense-grade die sourcing.
India
Production-linked incentive schemes for power electronics attract controller assembly investments targeting railway electrification. CEA grid standards and BIS certification requirements shape product specifications for renewable integration. The Delhi-NCR industrial corridor and Gujarat manufacturing clusters concentrate procurement for smart grid and metro rail applications.
Solid State Power Controller Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive semiconductor packaging capabilities, creating tiered competition between integrated system suppliers and specialized controller fabricators. Market structure concentrates margin capture in defense-aerospace qualified vendors with decade-long sole-source agreements, while industrial segments fragment across regional automation distributors. Strategic archetypes include wide-bandgap semiconductor foundry partners, thermal management specialists, and power electronics system integrators. Dominant competitive moves encompass long-term offtake agreements with SiC foundries and vertical integration into gate driver ASIC design.
Within the diversified conglomerate tier, ABB and Siemens occupy positions spanning marine grid integration through traction electrification, while Honeywell exemplifies the aerospace-qualified specialist archetype with vertical integration into thermal packaging. These three anchors represent distinct competitive vectors: ABB concentrates medium-voltage marine and offshore wind applications, Siemens leads rail electrification with silicon carbide-based platforms, and Honeywell captures defense-aerospace programs through MIL-STD qualification pathways.
| Leading Market Players |
|---|
| Advanced Energy Industries |
| Watlow |
| Gefran |
| ABB |
| Honeywell |
| Schneider Electric |
| Siemens |
| Rockwell Automation |
| Eaton |
| Others |
Value Network & Pricing Analysis
Wide-bandgap semiconductor substitution for silicon thyristors simultaneously redraws supply geography toward Japanese and German foundries while compressing pricing premiums for defense-grade qualification batches. Aerospace buyers now absorb 3-5x cost multiples for integrated architectures as SiC and GaN die sourcing concentrates in a handful of qualified fabrication facilities.
Pricing Analysis
SiC-to-GaN-to-silicon generational pricing gaps stratify controller markets into three performance-cost tiers. Three-tier pricing structure across aerospace-qualified, industrial-standard, and maintenance-retrofit levels reflects MIL-STD certification burden and volume scale. Cost compression in sub-100A industrial segments stems from persistent electromechanical relay cost floors. Maintenance-retrofit buyers exhibit highest price sensitivity, while defense prime contractors accept premium positioning for weight-constrained integrated assemblies.
Supply Chain Analysis
Six-inch GaN-on-SiC wafer chokepoints in Japanese foundries constrain aerospace qualification throughput and extend procurement timelines. Raw material dependencies center on silicon carbide substrates, gallium nitride epitaxy services, and F-Gas-compliant thermal interface materials. Single-source vulnerability pervades defense-grade die sourcing as tier-two suppliers lock into long-term offtake agreements. Distribution runs through defense prime contractor qualification pathways, industrial automation system integrators, and rail electrification OEM channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solid state power controller market sits at a wide-bandgap inflection driven by MIL-STD-704F mandates eliminating electromechanical alternatives from defense procurement. FAA electric aircraft certification pathways and naval integrated power programs accelerate specification upgrades across aerospace and marine applications.
For Market Incumbents: Fortify captive semiconductor packaging capabilities through backward integration into SiC foundry partnerships or long-term offtake agreements with German and Japanese wafer suppliers. Deepen gate driver ASIC design expertise to defend against emerging fabless competitors exploiting GaN HEMT supply bottlenecks. Prioritize thermal management qualification under EU F-Gas constraints to maintain European industrial access.
For New Entrants and Emerging Players: Differentiate on directed-energy weapon power conditioning specialization, where sub-50 microsecond fault isolation requirements exceed incumbent radar power supply capabilities. Target urban air mobility certification support services as the most penetrable aerospace segment, leveraging FAA SC-VTOL special conditions to bypass entrenched defense qualification barriers. Pursue India PLI scheme assembly investments for railway electrification localization.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors wide-bandgap qualification specialists with aerospace thermal cycling expertise. Long-term viability hinges on decade-long defense sole-source agreements and power-by-the-hour marine service contracts. Monitor GaN-on-SiC wafer supply expansion announcements as the critical inflection signal for aerospace pricing normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term SiC Foundry Offtake Agreement | Secures defense-grade die sourcing from German and Japanese fabrication facilities against allocation risk. |
| Gate Driver ASIC Design Investment | Captures margin concentration in integrated aerospace architectures through in-house semiconductor design. |
| F-Gas-Compliant TIM Certification | Unblocks German rail electrification and French nuclear maintenance procurement under EU thermal regulations. |
| Urban Air Mobility SC-VTOL Qualification | Opens FAA certification pathway for electric vertical takeoff aircraft power distribution contracts. |
| India PLI Scheme Assembly Localization | Accesses production-linked incentives for railway electrification and renewable integration controller manufacturing. |
Research Methodology
A standing panel of defense prime contractor procurement officers, wide-bandgap semiconductor foundry engineering directors, rail electrification system integrators, and aerospace thermal management specialists provided ongoing calibration. Primary interviews combined with secondary validation against SEC 10-K filings, IEC certification registries, FAA airworthiness directives, and customs trade data. Bottom-up segment sizing triangulated against top-down defense budget appropriations and industrial automation capex surveys.
Consistency checks validated volume and value outputs against external benchmarks including semiconductor wafer shipment data and power electronics system revenue disclosures. The analytical framework modeled technology type, product architecture, application voltage tier, and end-user procurement authority across the projection horizon. CAGRs derived from segment-level growth rate synthesis applied to baseline qualification batch volumes and electrification investment cycles.
Material uncertainties — defense program delay, GaN substrate supply disruption, REACH thermal material restriction expansion — sit outside the modeled envelope. Forecasts reflect assumptions regarding qualification timeline compression and wide-bandgap adoption curves. Practitioners should keep alternative scenarios live as MIL-STD revision cycles and EU F-Gas phase-down schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Global Flexible Batteries Market
Power Systems
Asia-Pacific Shunt Reactors Market
Power Systems
DC-DC Converter Market
Power Systems
Laptop Battery Market
Power Systems
Power Semiconductor Market
Power Systems
Charge Controller System Market
Power Systems
Global Chip Power Inductor Market
Power Systems
Low Voltage AC Drive Market
Power Systems
Gan-Powered Chargers Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market
Power Systems
Thyristor Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Power Electronics Equipment Cooling System Market
Power Systems
Three Phase Micro Inverters Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market