
 Asia-Pacific IGBT and Super Junction MOSFET Market | 2026-2036
Asia-Pacific IGBT and Super Junction MOSFET Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific IGBT and Super Junction MOSFET Market Insights
Software-defined thermal management and predictive maintenance subscriptions is restructuring how power semiconductor vendors capture lifetime value. Infineon Technologies AG leverages its European-Australian design heritage to anchor premium industrial contracts across Southeast Asia. Rohm Co., Ltd. specializes in silicon carbide-adjacent process know-how that differentiates its super junction offerings for Japanese automotive tier ones. Mitsubishi Electric Corporation dominates traction-grade IGBT module assembly from its Nagoya operations, supplying Chinese rail and Korean shipbuilding programs.
IGBT and super junction MOSFET devices are bipolar and unipolar power transistors respectively, engineered for switching frequencies between 1 kHz and 100 kHz and blocking voltages from 600 V to 6.5 kV, serving motor drives, inverters, and power conversion systems. Silicon carbide technology within the technology segment commands widening design wins at voltage thresholds above 1.2 kV where silicon-based super junction structures face thermal limitations. Electric vehicles within the application segment absorbs disproportionate engineering attention as OEMs specify 750 V and 800 V architectures that strain conventional IGBT switching losses.
China's MIIT enforces GB/T energy efficiency tiers that disqualify older IGBT generations from new inverter installations, while Japan's METI mandates JIS-certified standby loss ceilings that push super junction MOSFET refresh cycles. India's BIS adoption of IEC 60747 test protocols for imported power modules tightens market access for uncertified suppliers. Stakeholders must track how Australia's CEA grid interconnection standards and South Korea's KEMCO efficiency labels reshape procurement specifications for renewable energy inverters and EV charging infrastructure.
Market Dynamics
China's dual carbon goals and Japan's METI efficiency mandates are forcing synchronous technology transitions across power semiconductor supply chains, compressing refresh cycles for 600V-1.7kV devices while elevating silicon carbide-adjacent process investments.
Growth Catalysts
- EV powertrain voltage escalation:Chinese OEMs specify 750V and 800V architectures that strain conventional IGBT switching losses, creating immediate demand for super junction MOSFET refreshes in onboard chargers and DC-DC converters.
- GB/T energy efficiency tiers:China's MIIT enforces standards that disqualify older IGBT generations from new inverter installations, mandating technology upgrades across industrial motor drive fleets.
- Rail and shipbuilding electrification:Korean shipyards and Chinese rail programs specify traction-grade IGBT modules, concentrating procurement in Nagoya and Shanghai manufacturing corridors.
Market Restraints
- Epitaxial wafer supply concentration:150mm and 200mm silicon substrates for super junction structures depend on Japanese and Korean suppliers, creating input cost volatility during capacity allocation cycles.
- Silicon carbide substitution above 1.2kV:SiC MOSFETs capture design wins at voltage thresholds where silicon-based super junction structures face thermal limitations, compressing addressable market for legacy technologies.
- BIS certification timelines:India's adoption of IEC 60747 test protocols for imported power modules extends market access timelines for uncertified suppliers by 8-14 months.
Strategic Opportunities
- Southeast Asia industrial motorization:Vietnam and Indonesia manufacturing expansion creates underpenetrated demand for 600V-1.2kV IGBT modules in variable frequency drives without entrenched supplier relationships.
- Software-defined thermal management:Predictive maintenance subscriptions enable power semiconductor vendors to capture lifetime value beyond hardware shipment, restructuring revenue models toward recurring service streams.
- Australia CEA grid interconnection:Renewable energy inverter procurement specifications under evolving utility standards create design-win opportunities for certified super junction suppliers in solar and storage integration.
Industry Challenges
- Traction-grade module assembly expertise:Specialized packaging capabilities for rail and EV applications concentrate in Nagoya and Shanghai, creating talent scarcity for expansion programs elsewhere.
- JIS-certified standby loss compliance:Japanese METI mandates compress development timelines for super junction MOSFET refresh cycles, straining R&D allocation across multiple voltage classes simultaneously.
- Legacy system integration friction:Industrial customers in China's eastern manufacturing corridor face switching costs when retrofitting 400V-class motor drives to accommodate higher-efficiency IGBT generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific IGBT and Super Junction MOSFET Market |
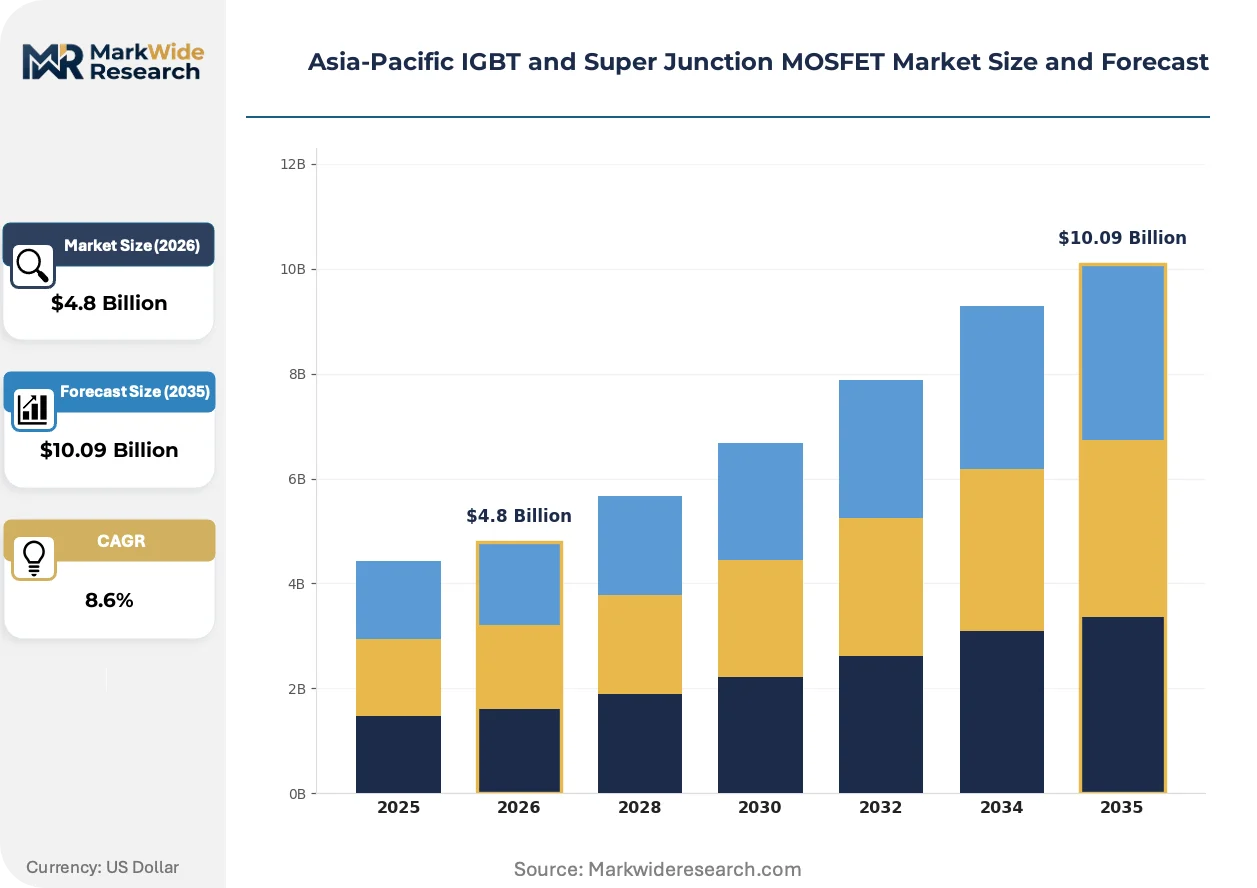
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IGBT, Super Junction MOSFET, GaN, SiC Application: Renewable Energy, Electric Vehicles, Consumer Electronics, Industrial Drives End User: Automotive, Telecommunications, Power Utilities, Manufacturing Installation: Onshore, Offshore, Stationary, Mobile |
| Companies Covered | Infineon Technologies AG, Mitsubishi Electric Corporation, Rohm Co., Ltd., Fuji Electric Co., Ltd., STMicroelectronics N.V., Toshiba Corporation, ON Semiconductor Corporation, Renesas Electronics Corporation, NXP Semiconductors N.V., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific IGBT and Super Junction MOSFET Market Trends and Innovations
Power semiconductor architectures are restructuring around thermal performance envelopes and predictive service models, displacing pure hardware competition with integrated system-level value propositions.
Silicon carbide process know-how is converging with super junction MOSFET design methodologies, enabling hybrid device architectures that bridge silicon cost structures with enhanced thermal performance. Japanese automotive tier ones adopt these convergent approaches fastest, specifying 750V-class devices that compress switching losses without full SiC cost premiums. This convergence is enabling mid-tier suppliers to defend position in 600V-1.2kV segments against pure-play silicon carbide entrants.
METI's JIS-certified standby loss ceilings are mandating super junction MOSFET refresh cycles across Japanese industrial equipment fleets, forcing component suppliers to accelerate development timelines. The regulation's industrial consequence is a compression of product lifecycle revenue, as earlier-generation devices face disqualification from new installations. Chinese inverter manufacturers serving Japanese export markets are responding by pre-certifying next-generation devices to avoid procurement exclusion.
Subscription-based thermal monitoring services are displacing traditional hardware-only procurement in Southeast Asian industrial contracts, unbundling lifetime performance guarantees from initial capital expenditure. System integrators in Thailand and Malaysia now specify predictive maintenance clauses as standard contract terms, favoring vendors with software-defined service capabilities. This pattern is most visible in semiconductor fabrication and precision manufacturing verticals where downtime costs dominate total cost of ownership calculations.
Asia-Pacific IGBT and Super Junction MOSFET Market Segmentation
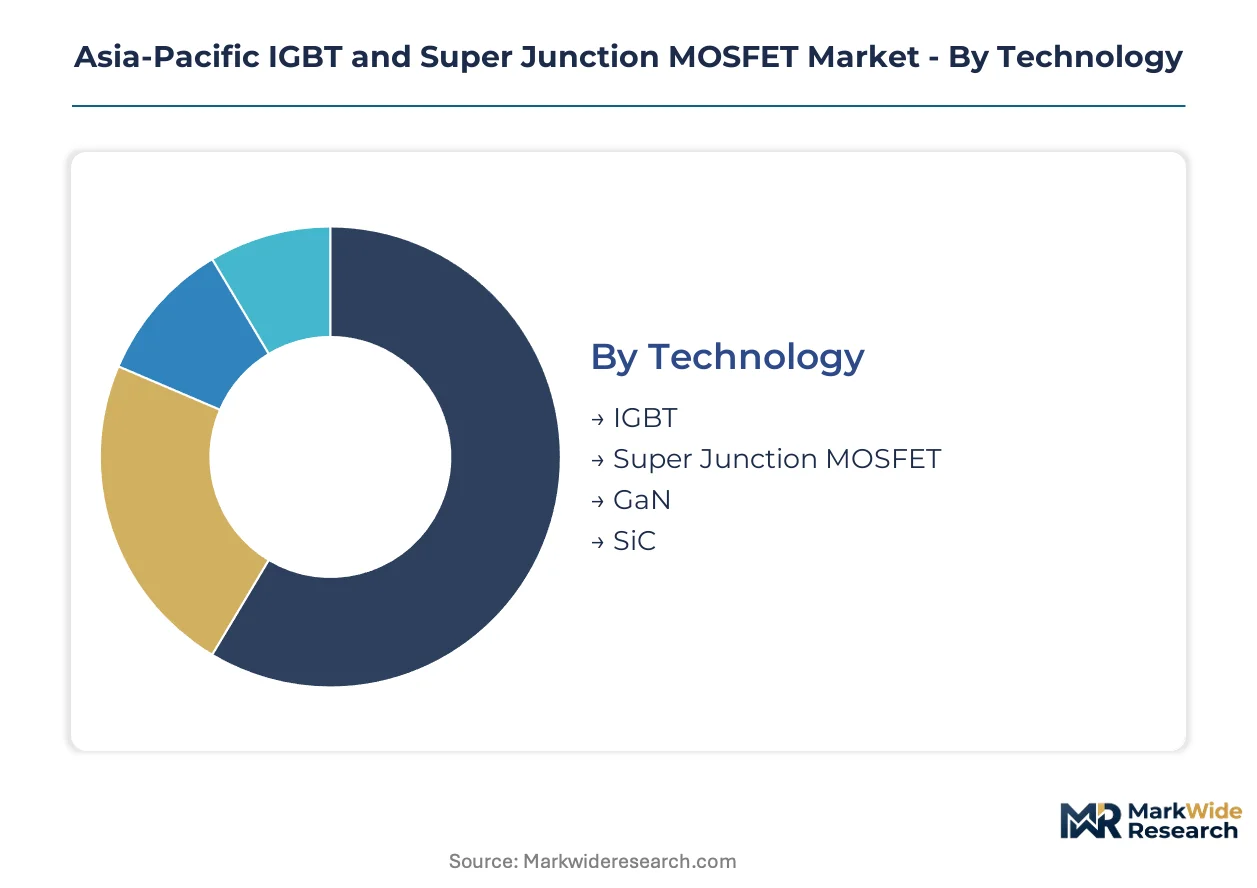
Power semiconductor procurement in the Asia-Pacific region follows distinct technical and application logics that reshape vendor priorities. Upgrade cycles for 600V-1.7kV devices differ sharply across technology generations, end-use verticals, and installation environments, forcing suppliers to align roadmaps with heterogeneous replacement timelines.
Technology:
Replacement urgency varies by voltage threshold and thermal envelope, with legacy silicon technologies facing accelerated refresh cycles under efficiency mandates.
- IGBT:Bipolar power transistors engineered for 600V-6.5kV blocking voltages and 1-50kHz switching frequencies dominate traction-grade applications. Chinese rail programs and Korean shipbuilding fleets concentrate procurement in Nagoya and Shanghai assembly corridors, where Mitsubishi Electric and Infineon anchor supply relationships.
- Super Junction MOSFET:Unipolar devices with optimized charge-compensation structures deliver reduced on-resistance at 600V-900V thresholds. Japanese automotive tier ones specify these for 750V onboard chargers to compress switching losses without full silicon carbide cost premiums, accelerating refresh cycles under METI standby loss mandates.
- GaN:Gallium nitride lateral devices serve sub-650V applications with switching frequencies exceeding 100kHz.
- SiC:Silicon carbide vertical MOSFETs capture design wins above 1.2kV where silicon super junction structures face thermal limitations.
IGBT sits at the top of the volume ranking, with SiC climbing the fastest.
Application:
End-use concentration patterns determine margin structures and certification requirements across the regional supply base.
- Electric Vehicles:Powertrain inverters, onboard chargers, and DC-DC converters absorb disproportionate engineering attention as Chinese OEMs specify 750V and 800V architectures. GB/T efficiency tiers disqualify older IGBT generations from new installations, mandating synchronous technology transitions across supplier portfolios.
- Renewable Energy:Solar inverters and energy storage power conversion systems demand 1.2kV-1.7kV devices with extended thermal cycling reliability. Australia's CEA grid interconnection standards reshape procurement specifications for utility-scale installations, favoring certified super junction suppliers.
- Industrial Drives:Variable frequency motor controls in China's eastern manufacturing corridor face switching costs when retrofitting 400V-class systems.
- Consumer Electronics:Compact adapters and power supplies utilize 600V-class super junction MOSFETs for standby loss compliance.
Electric Vehicles commands the largest revenue share, while Renewable Energy expands most quickly.
End User:
Customer sophistication and procurement scale create tiered access patterns for module suppliers across the region.
- Automotive:Tier one suppliers and OEM powertrain divisions specify devices with AEC-Q101 qualification and 15-year lifetime guarantees. Japanese and Korean automotive programs drive adoption of hybrid silicon-silicon carbide architectures at 750V thresholds.
- Power Utilities:Grid operators and renewable project developers procure under evolving interconnection standards that elevate certification burdens.
- Manufacturing:Industrial motor drive fleets in Vietnam and Indonesia present underpenetrated demand without entrenched supplier relationships.
- Telecommunications:Data center power supplies and base station rectifiers require high-efficiency 48V-400V conversion stages.
Automotive leads procurement volume, with Manufacturing gaining share fastest.
Installation:
Environmental exposure and mobility requirements differentiate reliability specifications and service model structures.
- Stationary:Fixed industrial drives, solar inverters, and grid infrastructure operate in controlled environments with predictable thermal management. Predictive maintenance subscriptions now standard in Southeast Asian semiconductor fabrication contracts restructure revenue toward recurring service streams.
- Mobile:Electric vehicle powertrains and construction equipment face vibration, humidity, and temperature cycling stressors that demand enhanced packaging expertise.
- Onshore:Land-based renewable and industrial installations follow established logistics and service networks.
- Offshore:Marine and subsea applications impose hermetic sealing and corrosion resistance requirements that concentrate supply among specialized packaging houses.
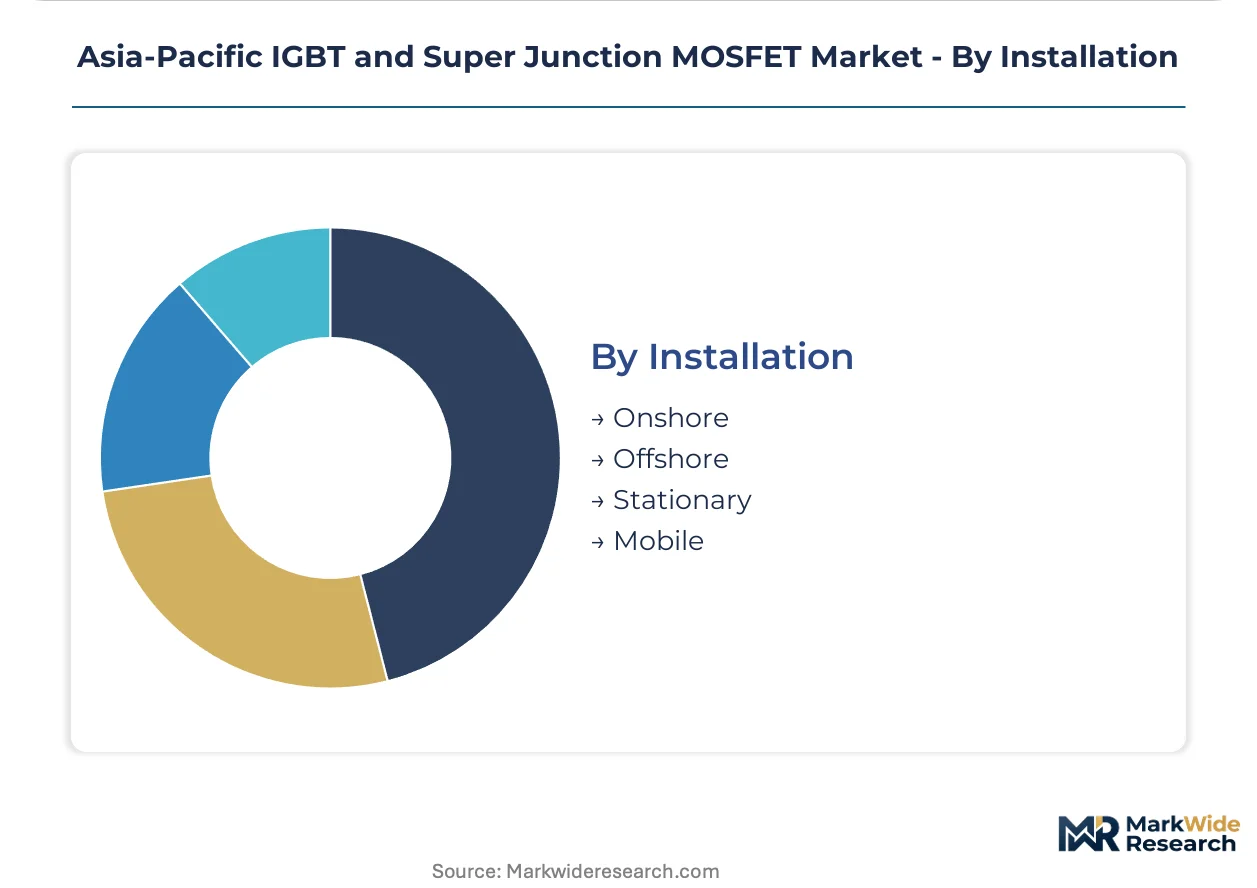
Stationary dominates installed base, with Mobile showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
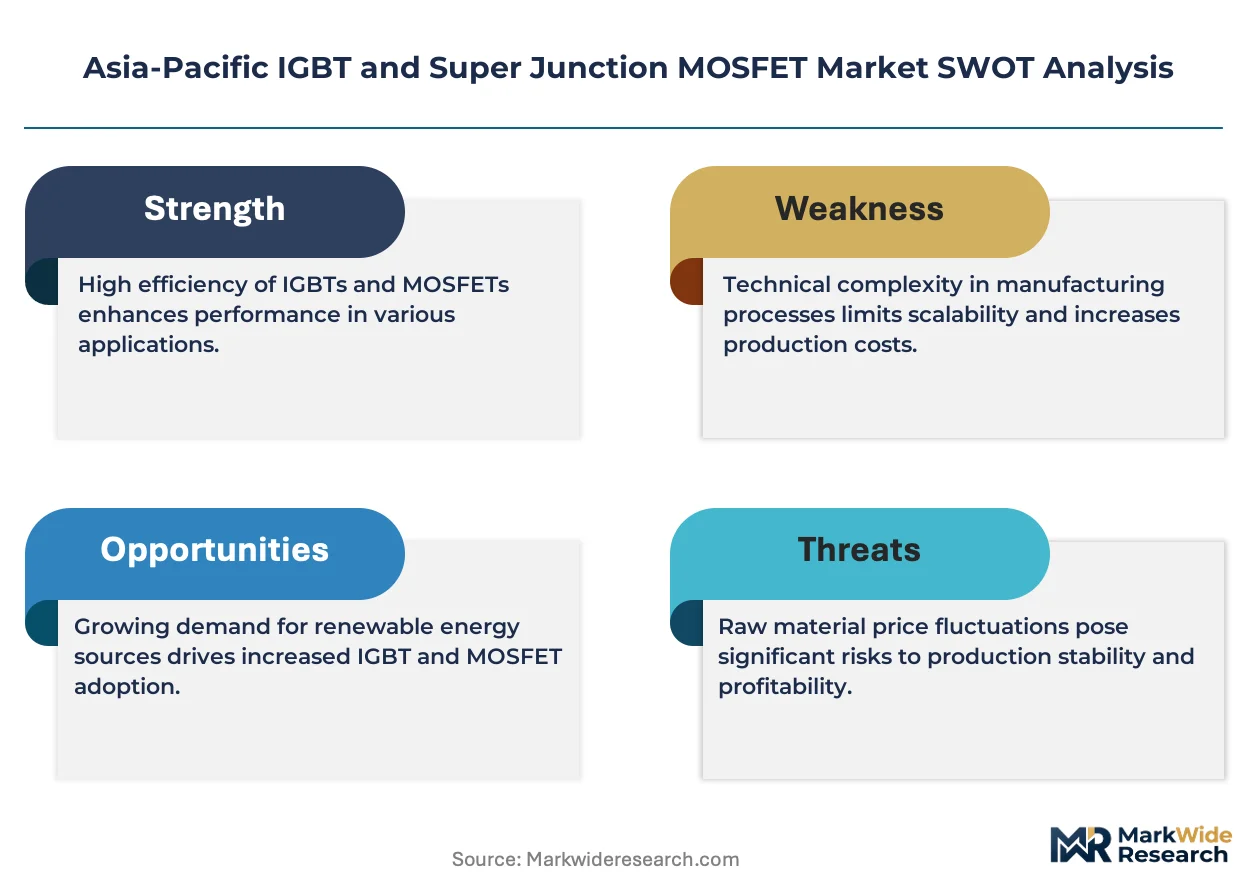
Cost-of-compliance gaps between national efficiency regimes are redirecting module assembly investments across the Asia-Pacific. Suppliers migrate production to jurisdictions with phased regulatory timelines while pre-certifying devices for stricter adjacent markets.
China
MIIT's GB/T energy efficiency tiers disqualify older IGBT generations from new inverter installations, forcing synchronous refreshes across industrial motor drive fleets. The dual carbon goals accelerate technology transitions in power semiconductor supply chains. Manufacturing concentrates in the eastern corridor spanning Shanghai, Suzhou, and Shenzhen, where module assembly serves domestic EV and rail programs.
Japan
METI mandates JIS-certified standby loss ceilings that compress super junction MOSFET development timelines across multiple voltage classes. Automotive tier ones specify hybrid silicon-silicon carbide architectures at 750V thresholds to manage switching losses. Nagoya anchors traction-grade IGBT module assembly, supplying Chinese rail and Korean shipbuilding procurement.
South Korea
KEMCO efficiency labels reshape procurement specifications for renewable energy inverters and EV charging infrastructure, elevating certification burdens for imported power modules. Korean shipyards specify traction-grade IGBT modules for vessel electrification programs. Daegu-Gyeongbuk and Busan-Ulsan manufacturing zones concentrate packaging expertise for marine and industrial applications.
India
BIS adoption of IEC 60747 test protocols for imported power modules extends market access timelines for uncertified suppliers by 8-14 months. Manufacturing expansion in Gujarat and Maharashtra creates underpenetrated demand for 600V-1.2kV IGBT modules without entrenched supplier relationships. Industrial motorization across Tamil Nadu and Karnataka drives variable frequency drive procurement.
Australia
CEA grid interconnection standards reshape procurement specifications for utility-scale renewable installations, favoring certified super junction suppliers in solar and storage integration. Predictive maintenance subscriptions now standard in Southeast Asian contracts are penetrating Australian semiconductor fabrication and precision manufacturing verticals. New South Wales and Victoria concentrate demand for high-reliability power conversion systems.
Asia-Pacific IGBT and Super Junction MOSFET Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated device manufacturers dominating traction-grade applications and fabless designers capturing consumer electronics volumes. The vendor base organizes around three strategic archetypes: European-Japanese heritage suppliers with premium industrial positioning, Korean-Taiwanese scale players serving consumer tiers, and emerging Chinese vertically integrated challengers. M&A activity concentrates on packaging expertise acquisition, while capacity expansion focuses on 200mm epitaxial wafer supply.
Among European-heritage suppliers, Infineon Technologies AG and STMicroelectronics N.V. occupy positions anchoring premium industrial contracts across Southeast Asia. Rohm Co., Ltd. exemplifies the Japanese specialist archetype with process know-how differentiation for automotive tier ones. Mitsubishi Electric Corporation represents the integrated industrial conglomerate model, dominating traction-grade module assembly from established manufacturing corridors.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Mitsubishi Electric Corporation |
| Rohm Co., Ltd. |
| Fuji Electric Co., Ltd. |
| STMicroelectronics N.V. |
| Toshiba Corporation |
| ON Semiconductor Corporation |
| Renesas Electronics Corporation |
| NXP Semiconductors N.V. |
| Others |
Pricing and Supply Chain Analysis
Captive epitaxial wafer production in Japan and South Korea anchors supply security for super junction MOSFET manufacturers while insulating tier-one suppliers from spot-market volatility. This integration pattern concentrates pricing power among established IGBT module assemblers in Nagoya and Shanghai, who negotiate long-term offtake agreements that lock in margin structures across refresh cycles.
Pricing Analysis
Distributor margins for 600V-1.7kV IGBT modules compress as direct OEM contracts expand across Chinese EV powertrain programs. Three-tier pricing structure across AEC-Q101 automotive, industrial-grade, and uncertified economy levels reflects certification investment recovery timelines. Cost compression in 750V onboard charger segments intensifies because silicon carbide-adjacent hybrid devices force silicon-only suppliers to absorb R&D amortization across shrinking volumes. Automotive tier ones exhibit lowest price sensitivity due to 15-year lifetime guarantees, while Southeast Asian industrial integrators drive hardest bargain on upfront capital expenditure.
Supply Chain Analysis
Regional distribution centers in Singapore and Hong Kong coordinate hub-and-spoke patterns for Japanese and Korean-sourced epitaxial wafers. Manufacturing concentrates in China, Japan, and South Korea, where 150mm and 200mm silicon substrates feed super junction fabrication lines. Raw material dependencies include high-purity polysilicon, specialized epitaxial reactor gases, and ceramic substrate materials for traction-grade packaging. Single-source vulnerability around Japanese 200mm wafer supply creates procurement risk during capacity allocation cycles. Distribution runs through authorized component distributors serving industrial motor drive and automotive tier one accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on silicon carbide process know-how commanding premium positioning in 750V-1.2kV hybrid architectures, while cost-down pressure on pure silicon IGBTs forces suppliers to extract value through predictive maintenance subscriptions.
For Market Incumbents: Cement traction-grade module assembly relationships with Chinese rail and Korean shipbuilding programs through Nagoya and Shanghai corridor investments. Acquire 200mm epitaxial wafer capacity or secure captive supply agreements to defend against silicon carbide substitution above 1.2kV. Deepen software-defined thermal management capabilities to capture recurring service revenue as hardware margins compress under GB/T efficiency tier compliance costs. For New Entrants and Emerging Players: Industrial distributors in Vietnam and Indonesia offer channel access without entrenched supplier relationships for 600V-1.2kV variable frequency drive applications. Target underpenetrated manufacturing motorization across Gujarat and Maharashtra where BIS certification timelines have delayed established competitors. Pursue Australia CEA grid interconnection pre-certification to capture solar inverter design wins before utility-scale procurement specifications harden. For Investors and Strategic Acquirers: Consolidation pressure builds where packaging expertise for traction-grade modules concentrates in Nagoya and Shanghai, creating acquisition premiums for specialized assembly houses. Packaging capability scarcity in rail and EV applications supports 5-10 year viability for mid-tier suppliers with module assembly know-how. Watch METI JIS-certified standby loss mandate enforcement velocity as signal for super junction MOSFET refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Epitaxial Wafer Capacity Expansion | Captive 200mm supply secures input cost stability against Japanese and Korean allocation volatility. |
| Software-Defined Thermal Management Launch | Predictive maintenance subscriptions restructure revenue toward recurring streams in Southeast Asian contracts. |
| GB/T Efficiency Tier Pre-Certification | Early compliance with MIIT mandates prevents procurement exclusion from Chinese inverter installations. |
| Automotive Tier One Partnership | AEC-Q101 qualification unlocks 750V onboard charger specifications for Japanese hybrid architectures. |
| Australia CEA Certification Pathway | Grid interconnection approval enables utility-scale solar and storage inverter design wins. |
Research Methodology
Coverage spans China, Japan, South Korea, India, and Australia, with primary inputs from each market cluster combining interviews with power semiconductor procurement managers, automotive tier one platform engineers, industrial motor drive maintenance directors, and renewable project EPC contractors. Secondary validation draws from MIIT GB/T filings, METI JIS certification registries, BIS IEC 60747 test protocol documentation, and customs trade data for epitaxial wafer flows. Bottom-up segment sizing triangulates against top-down regional demand aggregation.
Granularity-level modeling extends to voltage class, technology generation, application vertical, and end-user tier across the projection horizon. Segmentation dimensions include 600V-6.5kV blocking voltage thresholds, IGBT versus super junction MOSFET versus silicon carbide technology, and stationary versus mobile installation environments. CAGRs derive from replacement cycle analysis under efficiency mandate compliance deadlines and EV powertrain voltage escalation trajectories. Forecast inputs incorporate rail and shipbuilding electrification procurement schedules alongside solar inverter deployment pipelines under evolving grid interconnection standards.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silicon carbide cost reduction curves and Chinese dual carbon policy enforcement intensity. Outputs reflect documented assumptions around technology transition velocities and regulatory compliance timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Marine Variable Frequency Drives Market
Power Systems
Global DC Power Supply Module Market
Power Systems
Global Battery Thermal Management System Market
Power Systems
Battery Balancer Market
Power Systems
Silicon-Controlled Rectifier (SCR) Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
Power Diode Market
Power Systems
APAC Variable Frequency Drives Market
Power Systems
Global Telecom Tower Power System Market
Power Systems
Low Voltage Drives Market
Power Systems
Asia Pacific Battery Management System Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Asia Pacific Solid State Transformers Market
Power Systems
Grid Forming Inverters Market
Power Systems
Pulse Generator Market
Power Systems
Digital Inverter Market