
 Taiwan Data Center Storage Market | 2026-2036
Taiwan Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Data Center Storage Market Insights
All-flash array bundling with software-defined management is consolidating buyer preference toward integrated performance tiers. Dell Inc. leverages its PowerStore architecture to anchor high-throughput workloads for Taiwan's foundry operators. Pure Storage Inc. differentiates through cloud-operating-model subscriptions that reduce capital intensity for mid-size enterprises. Huawei Technologies Co. Ltd. navigates procurement restrictions by positioning through local system integrators in Kaohsiung.
Taiwan data center storage encompasses solid-state, magnetic, and tape-based media systems engineered for capacities from terabyte-scale edge nodes to petabyte-class enterprise arrays, with latency specifications ranging from sub-millisecond flash to archival tape retrieval measured in minutes. These systems serve semiconductor fabrication, financial transaction processing, and telecommunications infrastructure by ensuring data persistence, availability, and regulatory compliance across distributed compute environments. SSD deployments command premium positioning as AI training clusters proliferate across northern Taiwan, while hybrid cloud configurations capture the fastest expansion as enterprises distribute workloads between Hsinchu Science Park facilities and hyperscaler regions. Colocation deployment models sustain margin pools through long-term power and cross-connect contracts with Chunghwa Telecom and Far EasTone.
Taiwan's Ministry of Digital Affairs imposes cybersecurity resilience standards on critical infrastructure operators, compelling storage architecture investments with encrypted-at-rest and air-gapped backup capabilities. The National Communications Commission mandates data retention frameworks for telecom providers that extend tape and archival tier requirements. BIS certification requirements for imported encryption modules shape vendor qualification timelines and product localization strategies. Stakeholders must weigh sovereign data requirements against cloud elasticity as edge AI inference expands through Taoyuan and Tainan industrial corridors.
Market Dynamics
AI training clusters across Hsinchu Science Park and Taoyuan industrial corridors are compressing storage procurement cycles from annual refresh to quarterly capacity expansions, forcing architecture decisions that prioritize throughput density over cost-per-gigabyte optimization.
Growth Catalysts
- Data Localization Mandates:Taiwan's National Communications Commission requires critical infrastructure operators to maintain sovereign data residency, compelling domestic storage capacity builds for financial and telecom sectors.
- Semiconductor Supply Chain Analytics:Foundry operators generate petabyte-scale metrology and yield data that demand low-latency flash tiers for real-time process control.
- Edge AI Inference Expansion:Taoyuan and Tainan industrial corridors are deploying terabyte-scale edge nodes to support manufacturing quality inspection with sub-10ms response requirements.
Market Restraints
- NAND Flash Supply Concentration:Taiwan's storage integrators depend on concentrated upstream NAND supply from Korean and Japanese fabs, exposing procurement to geopolitical disruption and allocation volatility.
- BIS Certification Timelines:Imported encryption modules face extended qualification periods under Bureau of Industry and Security protocols, delaying product launches by 6-12 months.
- Power Density Constraints:Taipei and Taichung colocation facilities face physical limits on rack-level power draw, capping all-flash array density below theoretical maximums.
Strategic Opportunities
- Kaohsiung Port Digital Infrastructure:Southern Taiwan's underdeveloped data center capacity offers first-mover positioning for providers serving maritime logistics and cross-border trade analytics.
- Software-Defined Storage Convergence:Container-native orchestration with NVMe-oF fabrics is enabling disaggregated architectures that separate compute scaling from storage procurement decisions.
- Cybersecurity Resilience Incentives:Taiwan's Ministry of Digital Affairs subsidizes encrypted-at-rest and air-gapped backup deployments for critical infrastructure, creating procurement tailwinds for compliant vendors.
Industry Challenges
- Legacy Tape Migration Complexity:Telecom providers face decade-long retention mandates under National Communications Commission frameworks, forcing parallel operations of archival tape and modern object storage.
- Specialized Talent Scarcity:Enterprise demand for storage architects fluent in both mainframe-era hierarchical storage management and cloud-native S3 APIs exceeds available workforce supply in northern Taiwan.
- Hyperscaler Co-location Tension:Enterprises distributing workloads between Hsinchu Science Park facilities and AWS or Azure regions encounter data gravity conflicts that complicate backup and disaster recovery orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Data Center Storage Market |
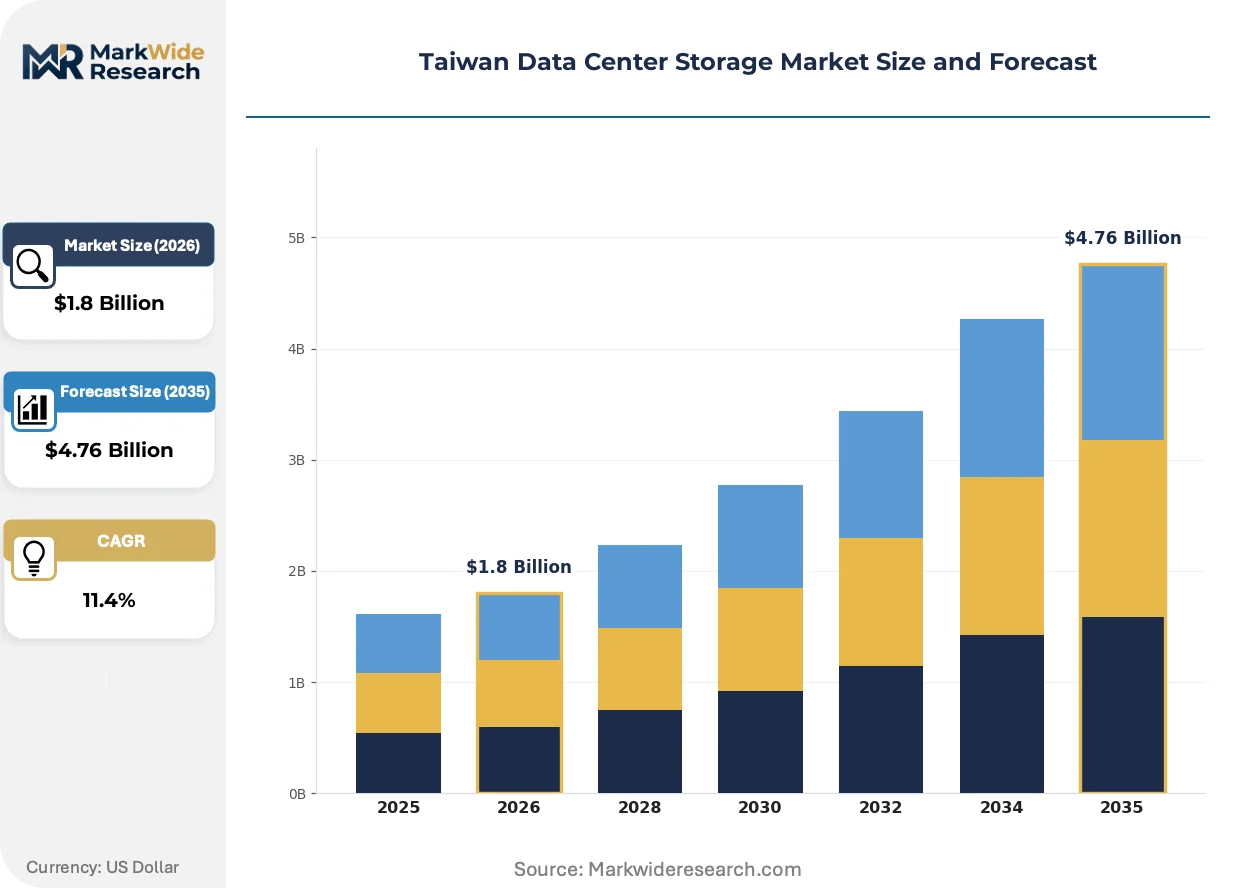
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: SSD, HDD, Hybrid, Tape Deployment Model: On-Premises, Cloud-Based, Hybrid Cloud, Colocation End User: Enterprise, SMBs, Government, Telecom Data Management: Backup, Archival, Disaster Recovery, Tiered Storage |
| Companies Covered | Dell Inc., Hewlett Packard Enterprise, NetApp Inc., Hitachi Vantara LLC, Kingston Technology Company Inc., Pure Storage Inc., Huawei Technologies Co. Ltd., Lenovo Group Limited, Fujitsu Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Data Center Storage Market Trends and Innovations
Storage architecture in Taiwan is pivoting from capacity-centric procurement to performance-optimized infrastructure that serves AI inference and sovereign data requirements simultaneously.
Computational storage drives with embedded processing capabilities are unifying data reduction and encryption functions at the device level. Foundry operators in Hsinchu are deploying these drives to compress metrology data before network transmission, reducing east-west traffic in AI training clusters. This unification is collapsing the traditional separation between storage hardware and data services software layers.
Taiwan's Ministry of Digital Affairs cybersecurity resilience standards mandate encrypted-at-rest capabilities and documented backup isolation for critical infrastructure operators. Financial services and semiconductor supply chain enterprises must demonstrate air-gapped recovery capabilities during regulatory audits. Compliance investments are accelerating replacement of legacy SAN architectures with software-defined alternatives that offer immutable snapshot features.
Consumption-based financing models are displacing capital-intensive storage purchases among mid-size Taiwanese enterprises. System integrators in Taichung and Taipei now bundle hardware, software licensing, and operational support into per-terabyte monthly arrangements. This shift is most visible in pharmaceutical and precision manufacturing verticals where CFOs prioritize opex predictability over depreciation schedules.
Taiwan Data Center Storage Market Segmentation
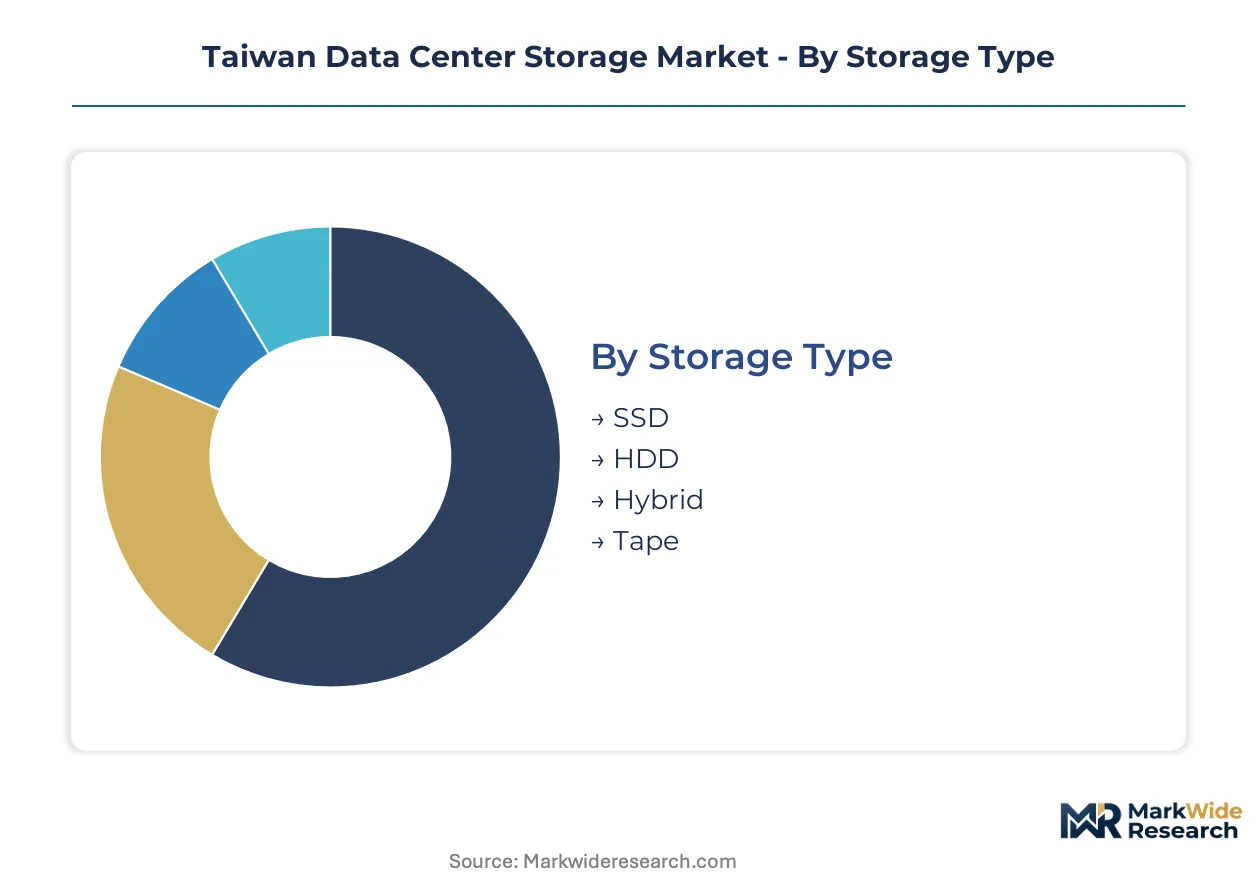
Storage procurement in Taiwan fragments across performance requirements, sovereignty constraints, and workload distribution patterns. Buyers prioritize latency specifications for AI training clusters while balancing compliance mandates for financial and telecom sectors.
Storage Type:
Cost-per-gigabyte tolerance separates hyperscaler deployments from enterprise flash investments.
- SSD:NAND-based solid-state arrays deliver sub-millisecond latency for Hsinchu foundry metrology pipelines. Taoyuan industrial corridors deploy NVMe-oF fabrics to support AI inference clusters with throughput density exceeding 100GBps per rack.
- HDD:Magnetic disk systems anchor warm-tier economics for mid-size enterprises in Taichung. Procurement concentrates in 16TB+ helium-sealed drives for backup consolidation projects where petabyte-scale capacity outweighs access speed requirements.
- Hybrid:Tiered flash-disk architectures automate data placement between performance and capacity pools. Taipei financial services deploy these systems to satisfy encrypted-at-rest mandates without sacrificing transaction processing speed.
- Tape:LTO-9 cartridges serve National Communications Commission retention frameworks requiring decade-long archival persistence. Telecom providers maintain parallel tape libraries alongside object storage for regulatory audit trails.
Volume sits with HDD; growth tilts toward SSD.
Deployment Model:
Control over encryption key custody drives architecture selection across regulated industries.
- On-Premises:Dedicated arrays within Hsinchu Science Park facilities satisfy Ministry of Digital Affairs cybersecurity resilience standards. Semiconductor supply chain operators mandate physical air-gaps for yield data protection.
- Cloud-Based:Hyperscaler object storage from AWS and Azure regions absorbs burst capacity for seasonal analytics workloads. Migration friction persists where data gravity conflicts with sovereignty requirements.
- Hybrid Cloud:Policy-driven tiering distributes hot data to local flash while archiving cold datasets to cloud. This configuration climbs fastest among pharmaceutical manufacturers seeking opex predictability.
- Colocation:Chunghwa Telecom and Far EasTone facilities in Taipei and Taichung offer cross-connect contracts with guaranteed power density. Rack-level constraints cap all-flash deployments below theoretical maximums.
On-premises claims current spend; hybrid cloud is expanding most steeply.
End User:
Regulatory exposure determines investment urgency and compliance feature requirements.
- Enterprise:Foundry operators and financial institutions command premium flash tiers for real-time process control. These buyers negotiate multi-year capacity reservations with direct vendor relationships.
- SMBs:Mid-size manufacturers in Tainan adopt consumption-based financing to avoid capital-intensive procurement cycles. System integrators bundle hardware, software, and operational support into per-terabyte monthly arrangements.
- Government:Critical infrastructure operators face mandatory encrypted-at-rest and documented backup isolation. Ministry of Digital Affairs audits drive replacement of legacy SAN architectures.
- Telecom:National Communications Commission frameworks compel extended retention infrastructure. Providers juggle parallel tape and modern object storage for subscriber metadata compliance.
Enterprise dominates installed base; government procurement shows steepest expansion trajectory.
Data Management:
Recovery time objectives separate mission-critical workloads from archival compliance.
- Backup:Immutable snapshot capabilities replace traditional tape rotation for ransomware resilience. Financial services in Taipei prioritize isolated recovery environments with sub-hour restoration guarantees.
- Archival:Cold storage tiers serve decade-long retention without primary array performance overhead. Telecom providers face decade-long mandates forcing investment in both tape libraries and cloud glacier alternatives.
- Disaster Recovery:Synchronous replication between Hsinchu and Taoyuan facilities protects against seismic and power disruption. Latency constraints limit synchronous distances to sub-100km fiber routes.
- Tiered Storage:Automated data placement algorithms balance cost and access patterns across flash, disk, and tape pools. Foundry operators deploy these systems to compress metrology data before network transmission.
Backup captures current volume; tiered storage is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan produces the majority of the world's advanced NAND flash memory yet consumes a fraction domestically, creating a production-consumption asymmetry that shapes regional storage procurement patterns. Foundry operators in Hsinchu and Taichung absorb high-performance tiers while mid-market demand concentrates in Taipei financial services.
Taipei Metropolitan Area
Financial institutions and telecom headquarters drive encrypted-at-rest storage procurement for transaction processing and subscriber metadata compliance. The National Communications Commission mandates data retention frameworks that extend archival infrastructure requirements. Chunghwa Telecom and Far EasTone colocation facilities in Neihu and Nangang districts face physical power density constraints capping all-flash array deployments.
Hsinchu Science Park
Semiconductor foundry operators generate petabyte-scale metrology and yield data demanding sub-millisecond flash tiers for real-time process control. The Ministry of Digital Affairs imposes cybersecurity resilience standards compelling air-gapped backup investments. TSMC and supply chain analytics clusters anchor the densest concentration of NVMe-oF fabric deployments in Taiwan.
Taichung Industrial Corridor
Precision machinery and pharmaceutical manufacturers adopt consumption-based storage financing to prioritize opex predictability over capital-intensive procurement cycles. System integrators bundle hardware, software, and operational support into per-terabyte monthly arrangements. The Taichung Port expansion is attracting logistics operators evaluating hybrid cloud configurations for trade analytics.
Taoyuan Industrial Zone
Edge AI inference deployments for manufacturing quality inspection require terabyte-scale nodes with sub-10ms response capabilities. Taoyuan International Airport's cargo operations generate data gravity pulling storage capacity northward from Taipei. Industrial automation clusters are compressing procurement cycles from annual refresh to quarterly capacity expansions.
Kaohsiung Port District
Southern Taiwan's underdeveloped data center capacity offers first-mover positioning for providers serving maritime logistics and cross-border trade analytics. Local system integrators facilitate vendor navigation of procurement restrictions for international equipment suppliers. The Kaohsiung Free Trade Zone is emerging as an alternative deployment location for enterprises seeking geographic diversification from northern Taiwan concentration.
Taiwan Data Center Storage Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Taiwan's data center storage market, with procurement decisions splitting between integrated IT infrastructure bundles and best-of-breed performance tiers. The vendor ecosystem organizes into three strategic archetypes: global technology conglomerates with broad infrastructure portfolios, storage-focused specialists with cloud-operating-model subscriptions, and Asia-Pacific hardware integrators leveraging local system integrator relationships. Competitive positioning hinges on BIS certification timelines for encryption modules and long-term power contracts with dominant telecom carriers.
Among global infrastructure providers, Dell Inc. and Hewlett Packard Enterprise occupy positions anchoring enterprise refresh cycles through direct relationships with foundry operators and financial institutions. Pure Storage Inc. exemplifies the subscription-based specialist archetype, reducing capital intensity for mid-size manufacturers in Taichung and Tainan through consumption-oriented arrangements. Huawei Technologies Co. Ltd. represents the Asia-Pacific integrator model, navigating procurement complexities through Kaohsiung-based system integrator partnerships.
| Leading Market Players |
|---|
| Dell Inc. |
| Hewlett Packard Enterprise |
| NetApp Inc. |
| Hitachi Vantara LLC |
| Kingston Technology Company Inc. |
| Pure Storage Inc. |
| Huawei Technologies Co. Ltd. |
| Lenovo Group Limited |
| Fujitsu Limited |
| Others |
Pricing and Supply Chain Analysis
Enterprise foundry operators and financial institutions command the dominant procurement volumes in Taiwan data center storage, anchoring contract-based pricing with multi-year capacity reservations that compress margins for mid-tier vendors serving price-sensitive SMB manufacturers.
Pricing Analysis
Margin tightening in mid-market flash arrays reflects Korean and Japanese NAND supply concentration that limits Taiwanese integrators' bargaining leverage. Pricing stratifies across performance-optimized NVMe tiers, encrypted compliance-grade systems, and economy-focused HDD backup pools. Cost-down pressure on standard-tier hybrid configurations accelerates as Taichung pharmaceutical manufacturers prioritize opex predictability over capital depreciation schedules. SMBs in Tainan industrial corridors exhibit highest price sensitivity, while Hsinchu foundry operators absorb premium positioning for sub-millisecond latency guarantees.
Supply Chain Analysis
Dual-sourcing requirements from Taiwan's Ministry of Digital Affairs compel storage integrators to qualify NAND supply from South Korea, Japan, and domestic packaging facilities simultaneously. Raw material dependencies center on 3D NAND wafers, NVMe controller ASICs, and encryption modules subject to BIS certification protocols. Single-source vulnerability persists where advanced node flash fabrication concentrates in Korean fabs. Distribution runs through Taipei and Taichung system integrators that bundle hardware, software licensing, and operational support for end-user deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan data center storage is transitioning from capacity-centric procurement to performance-optimized infrastructure, with software-defined architectures and NVMe-oF fabrics displacing legacy SAN investments across Hsinchu and Taoyuan deployments.
For Market Incumbents: Deepen backward integration into NAND packaging capabilities to secure supply allocation during Korean fab allocation volatility. Anchor high-throughput PowerStore architectures with direct foundry relationships while accelerating BIS certification timelines for encryption modules to defend against Pure Storage subscription models eroding mid-market share.
For New Entrants and Emerging Players: The price-point gap between premium NVMe-oF fabrics and economy HDD backup tiers offers white-space positioning for container-native storage software vendors. Target Kaohsiung Port District maritime logistics operators seeking geographic diversification from northern Taiwan concentration, with consumption-based financing bundled through local system integrator partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor software-defined storage specialists with established Ministry of Digital Affairs compliance certifications in Taipei and Taichung. Long-term viability hinges on sovereign data mandate enforcement durability rather than hyperscaler co-location expansion. Watch National Communications Commission retention framework extensions as the signal indicating archival infrastructure procurement inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| NVMe-oF Fabric Deployment | TSMC metrology pipelines demand throughput density exceeding 100GBps per rack. |
| Consumption-Based Financing Launch | Taichung pharmaceutical CFOs prioritize opex predictability over depreciation schedules. |
| BIS Certification Acceleration | Encryption module qualification delays compress product launch windows by 6-12 months. |
| Kaohsiung System Integrator Partnership | Local relationships navigate procurement restrictions for international equipment suppliers. |
| Air-Gapped Backup Architecture | Ministry of Digital Affairs audits mandate documented isolation for critical infrastructure. |
Research Methodology
Independent corroboration across storage architect interviews, system integrator fieldwork, and hyperscaler procurement disclosures underwrites the qualitative findings. Primary sources span data center infrastructure directors at Hsinchu Science Park foundries, IT procurement officers at Taipei financial institutions, and channel partners at Chunghwa Telecom colocation facilities. Secondary validation draws from Bureau of Industry and Security certification databases, National Communications Commission regulatory filings, and hyperscaler capex disclosure patterns. Bottom-up capacity deployment tracking triangulates against top-down market sizing across the analysis window.
Comparable-period anchoring to historical refresh cycles grounds the projection framework across the modeling period. Segmentation dimensions include storage media type, deployment model, end-user vertical, and data management function. CAGRs derive from vendor shipment disclosures, foundry capacity expansion announcements, and colocation power contract trajectories. Forecast inputs incorporate AI training cluster density requirements and Ministry of Digital Affairs cybersecurity resilience standard enforcement timelines.
Underlying measurement precision varies by segment; on-premises enterprise flash deployments carry tighter precision than emerging edge AI inference node configurations. Forecasts reflect assumptions regarding NAND supply allocation stability and BIS certification processing efficiency. Deviation in National Communications Commission data retention mandate extensions would shift the archival infrastructure outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Middle East Data Center Storage Market
Data Storage
Holographic Versatile Disc (HVD) Market
Data Storage
Japan Data Center Storage Market
Data Storage
HDD Head Assembly Market
Data Storage
Blu-Ray Drive Market
Data Storage
APAC Next Generation Storage Market
Data Storage
Recordable Optical Disc Market
Data Storage
Digital Recording System Market
Data Storage
Electrochromic Storage Devices Market
Data Storage
All Flash Storage Market
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Substrates for Magnetic Disks Market
Data Storage
North America Next Generation Storage Market
Data Storage
USB Key Market