
 Global Rectifier Market | 2026-2036
Global Rectifier Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rectifier Market Foresight
Modular rectifier packaging is rebalancing procurement patterns across power electronics buyers. Infineon Technologies AG leverages its integrated silicon carbide modules to capture premium positioning in electric vehicle charging infrastructure. Vishay Intertechnology anchors discrete rectifier supply through extensive foundry partnerships and automotive qualification depth. ON Semiconductor specializes in intelligent power modules that combine rectification with active control, reducing bill-of-material complexity for industrial OEMs.
A rectifier is an electrical device that converts alternating current to direct current through semiconductor junction behavior, typically achieving forward voltage drops between 0.3V and 1.1V depending on material composition. Silicon diode rectifiers remain the volume foundation for consumer power supplies and battery chargers due to mature cost structures and established reliability data. Silicon carbide rectifiers represent the fastest-expanding technology segment as data center operators and renewable energy system integrators prioritize thermal efficiency and switching speed over upfront cost. Bridge rectifier configurations dominate welding equipment and motor drive applications where full-wave conversion eliminates transformer center-tap requirements.
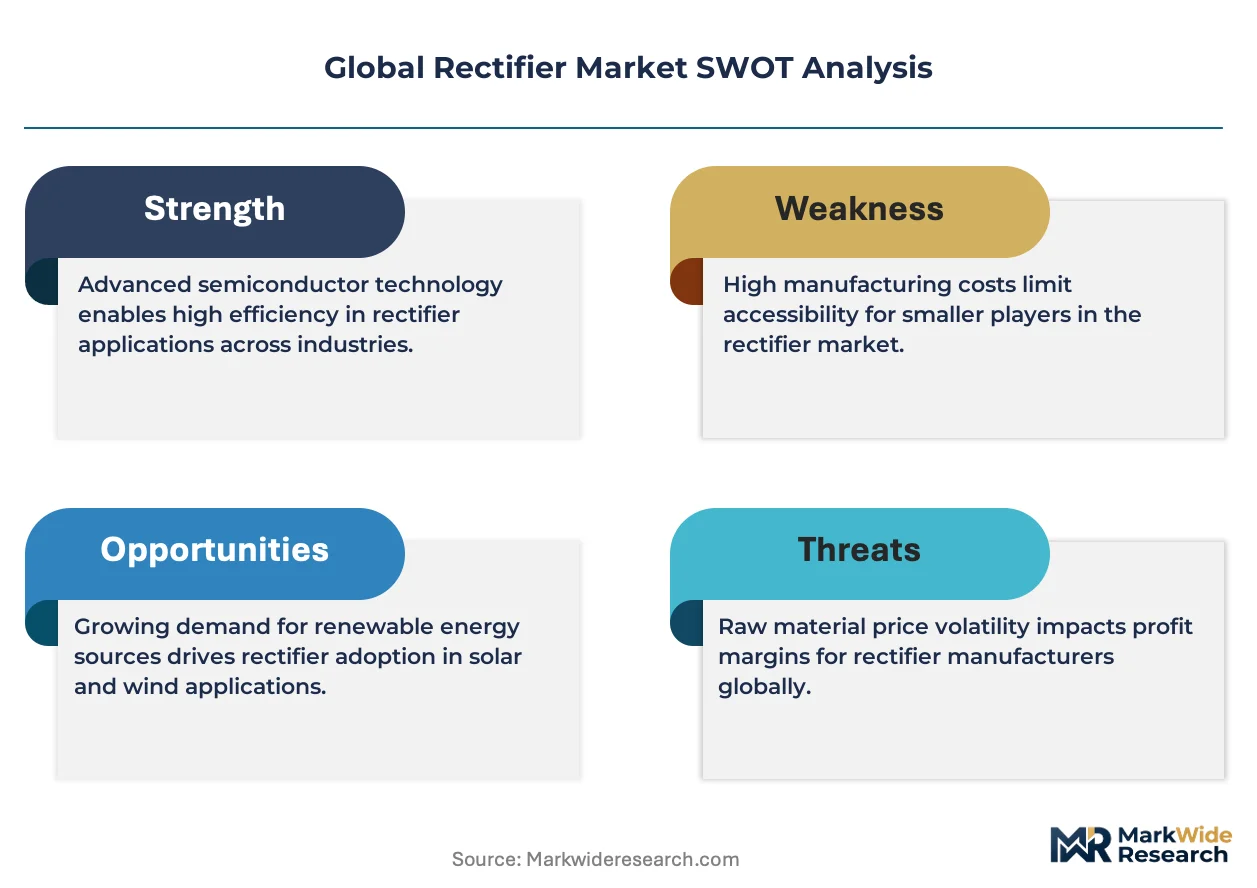
The EU Green Deal and F-Gas Regulation constrain fluorinated gas use in power semiconductor manufacturing, pushing European suppliers toward dry etching and alternative dielectric processes. China's MIIT enforces GB standards for rectifier efficiency in telecommunications infrastructure, directly shaping product roadmaps for equipment serving that procurement base. India's BIS certification requirements for power electronics create formal entry barriers that favor suppliers with established testing relationships. Stakeholders must monitor how carbon border adjustments and semiconductor subsidy programs redistribute manufacturing cost advantages across competing supply regions.
Market Dynamics
Silicon carbide rectifiers are compressing forward voltage drop tolerances across data center power supplies, forcing procurement committees to rewrite supplier scorecards around thermal efficiency rather than unit cost alone.
Growth Catalysts
- EU F-Gas Regulation:Fluorinated gas restrictions in semiconductor etching processes accelerate dry etching adoption, creating procurement preference for European suppliers with certified alternative processes.
- Data center efficiency mandates:Hyperscale operators in Northern Virginia and Frankfurt are specifying silicon carbide rectifiers for server power supplies, prioritizing heat dissipation over silicon diode economics.
- India's PLI scheme:Production-linked incentives for electronics manufacturing concentrate assembly capacity in Noida and Sri City, generating localized demand for bridge rectifier modules in welding equipment.
Market Restraints
- Silicon carbide substrate scarcity:Wolfspeed and II-VI dominate 150mm SiC wafer supply, constraining module output expansion regardless of design capacity.
- China's dual carbon enforcement:MIIT power efficiency audits for telecommunications infrastructure force immediate product redesigns, compressing development cycles for serving that procurement base.
- Gallium nitride substitution threat:GaN transistors encroach on sub-600V rectification applications in consumer adapters, threatening silicon diode volume foundations.
Strategic Opportunities
- Indonesia electronics manufacturing:Relocation of consumer electronics assembly from coastal China to Batam and Jakarta creates demand for discrete rectifier supply localized to ASEAN customs zones.
- Vehicle-to-grid integration:Bidirectional charging infrastructure requires intelligent rectifier modules with active switching control, opening premium positioning for semiconductor suppliers with firmware integration capabilities.
- EU Green Deal carbon border adjustments:CBAM implementation on imported power electronics creates first-mover advantage for European foundries with certified low-carbon production processes.
Industry Challenges
- Wide bandgap packaging thermal management:SiC and GaN die attachment requires silver sintering expertise scarce in traditional silicon diode assembly facilities, creating bottlenecks during technology transitions.
- BIS certification timeline compression:India's mandatory testing for power electronics imports extends procurement cycles by 14-18 weeks, disadvantaging suppliers without established Bengaluru laboratory relationships.
- Legacy motor drive retrofit compatibility:Bridge rectifier replacements in installed welding and industrial automation equipment must match obsolete mechanical footprints, fragmenting SKU requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rectifier Market |
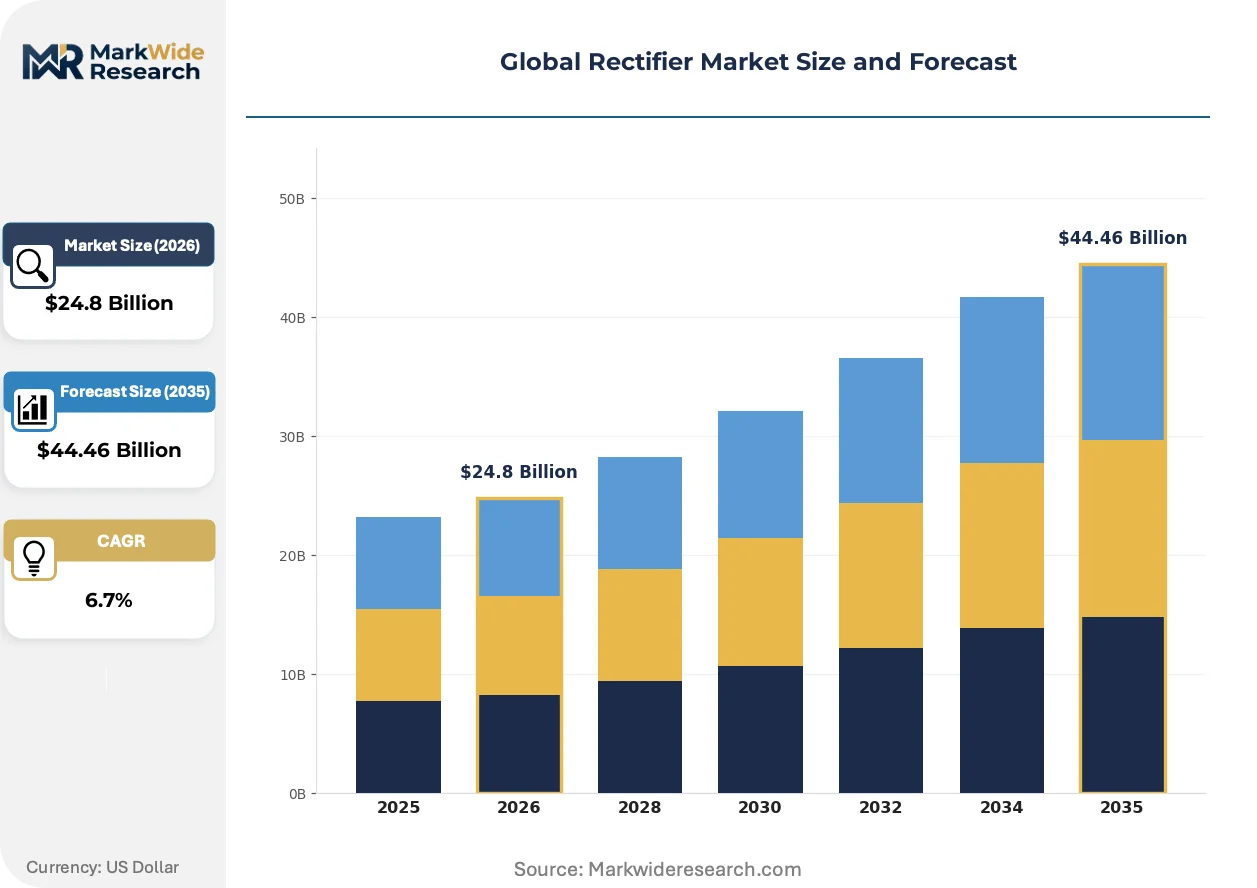
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $44.46 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Selenium Rectifiers, Silicon Diode Rectifiers, Silicon Controlled Rectifiers, Bridge Rectifiers, Schottky Rectifiers Technology: Discrete Semiconductor, Integrated Circuit, Thyristor-Based, Silicon Carbide, Gallium Nitride Application: Power Supplies, Welding Equipment, Motor Drives, Battery Chargers, Renewable Energy Systems End User: Consumer Electronics Manufacturers, Telecommunications Providers, Industrial Manufacturing Firms, Aerospace & Defense Contractors, Data Center Operators |
| Companies Covered | Vishay Intertechnology, Diodes Incorporated, Infineon Technologies AG, Renesas Electronics Corporation, NXP Semiconductors, ON Semiconductor, Toshiba Corporation, Mitsubishi Electric Corporation, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rectifier Market Shifts & Advancements
Rectifier technology trajectories center on material transitions that reconfigure thermal budgets and switching frequencies simultaneously, with packaging architectures racing to accommodate die-level capabilities.
Silicon carbide Schottky rectifiers is absorbing the high-frequency rectification load previously assigned to silicon ultrafast diodes in server power supplies. Data center operators in Ashburn and Amsterdam are specifying 650V SiC devices for power factor correction stages, accepting 40% higher unit costs to recover cooling infrastructure savings. This material transition is absorbing engineering resources across power semiconductor divisions, compressing R&D attention on silicon superjunction alternatives.
REACH substance restrictions on lead-bearing solders and hexavalent chromium platings force metallurgical redesigns in rectifier terminal finishes. European suppliers are migrating to pure tin and nickel-palladium-gold systems ahead of enforcement deadlines, adding 8-12% to packaging costs. Automotive rectifier modules for electric vehicle onboard chargers face the most acute compliance pressure, with German OEMs requiring full material disclosure back to mine origin.
Hyperscale buyers are consolidating power supply procurement through direct semiconductor supplier relationships, bypassing traditional distributor inventory buffers. Amazon Web Services and Microsoft Azure negotiate annual silicon carbide rectifier allocations directly with Infineon and Wolfspeed, leaving tier-two server OEMs competing for residual foundry capacity. This concentration is most visible in Northern California and Singapore, where procurement teams maintain dedicated supplier development engineers on-site at wafer fabrication facilities.
Global Rectifier Market Segmentation
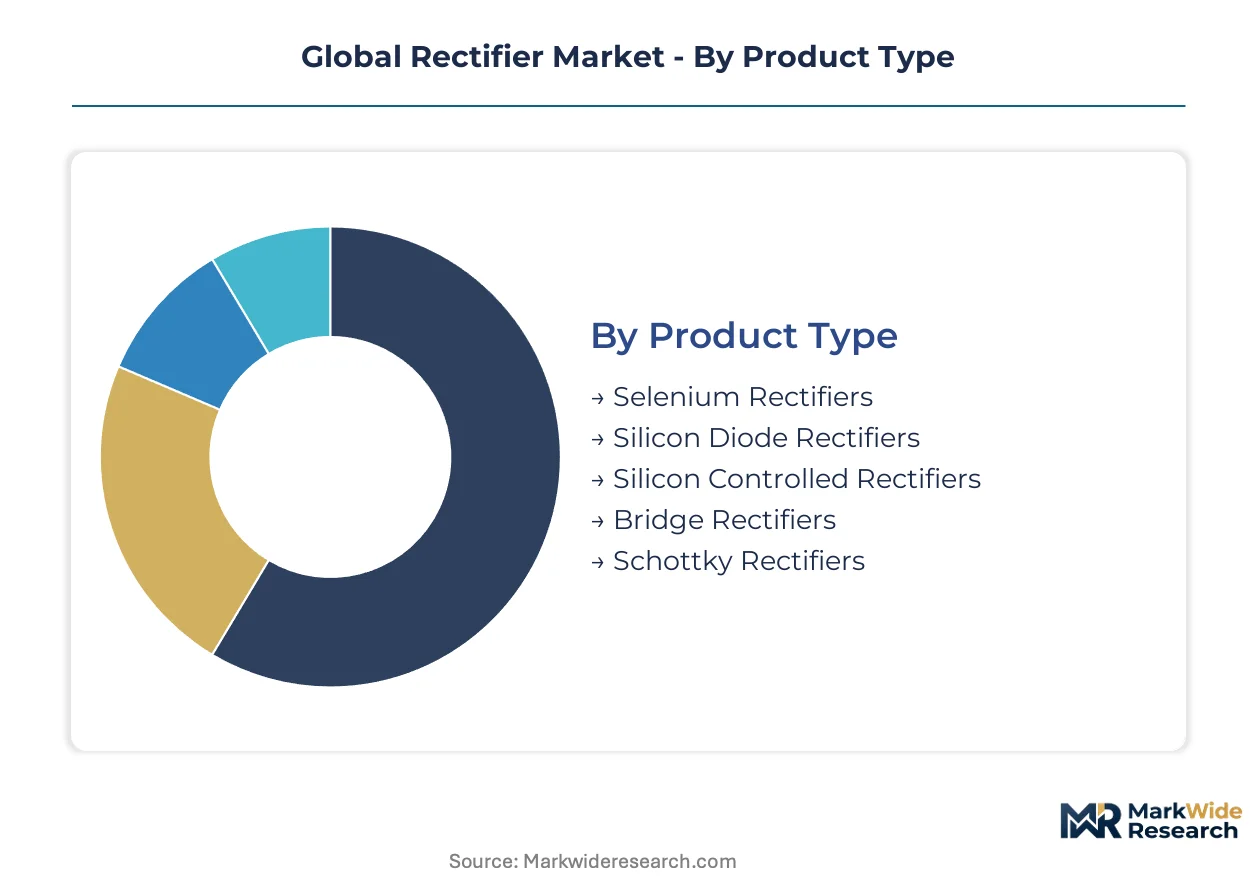
Rectifier procurement committees evaluate suppliers across four distinct decision hierarchies: material efficiency for data center operators, thermal ruggedness for industrial welders, cost minimization for consumer electronics, and qualification depth for defense contractors. Each segmentation axis reveals divergent margin structures and technology roadmaps.
Product Type:
Cost tier determines supplier selection more than any other factor in this category.
- Silicon Diode Rectifiers:These junction-based devices achieve forward voltage drops between 0.6V and 1.1V using mature silicon fabrication. Consumer power supply manufacturers in Shenzhen and Hanoi specify these for smartphone chargers and laptop adapters where unit economics dominate thermal performance.
- Silicon Carbide Rectifiers:Wide bandgap substrates enable switching frequencies above 100kHz with negligible reverse recovery losses. Data center operators in Ashburn and Frankfurt specify 650V SiC Schottky devices for server power supplies, accepting premium pricing to recover cooling infrastructure savings.
- Selenium Rectifiers:Legacy metal-disk assemblies survive in antique equipment maintenance and educational demonstrations where semiconductor replacement is impractical.
- Silicon Controlled Rectifiers:Thyristor-based phase control dominates industrial motor soft-starting and lighting dimmer circuits requiring precise AC power modulation.
- Bridge Rectifiers:Four-diode full-wave configurations eliminate transformer center-tap requirements in welding equipment and battery charger assemblies across India's PLI-subsidized manufacturing zones.
- Schottky Rectifiers:Metal-semiconductor junctions deliver sub-0.5V forward drops for high-frequency DC-DC converters in telecommunications rectifier modules.
Silicon diode rectifiers lead on scale; silicon carbide rectifiers lead on momentum.
Technology:
Application voltage and switching frequency requirements determine which technology layer procurement teams specify.
- Silicon Carbide:3.26eV bandgap substrates withstand junction temperatures exceeding 175°C while switching at frequencies silicon cannot achieve. Renewable energy inverter manufacturers in Germany's industrial automation corridor specify SiC for solar string converters and wind turbine power conditioning.
- Discrete Semiconductor:Individual die packaging dominates consumer electronics where board-level flexibility and repairability outweigh integration benefits.
- Integrated Circuit:Multi-function power management ICs incorporate rectification alongside voltage regulation and protection logic for space-constrained mobile devices.
- Thyristor-Based:Phase-controlled silicon switches manage megawatt-scale industrial drives and traction power systems requiring precise AC waveform manipulation.
- Gallium Nitride:3.4eV bandgap devices encroach on sub-600V rectification applications in consumer adapters, threatening silicon diode volume foundations with superior switching speed.
Discrete semiconductor technology leads on installed base; silicon carbide leads on design win velocity.
Application:
End-use thermal environment and duty cycle dictate material selection and packaging investment.
- Power Supplies:Server and telecommunications rectifiers prioritize efficiency certification compliance over upfront component cost. Hyperscale operators negotiate direct allocations with foundries, bypassing distributor inventory buffers.
- Renewable Energy Systems:Solar inverters and wind converters demand 20-year reliability under thermal cycling stress. European system integrators specify SiC rectification to minimize cooling system maintenance in remote installations.
- Welding Equipment:Bridge rectifier configurations handle high-current pulsed loads in manual and robotic welding systems across India's electronics manufacturing clusters.
- Motor Drives:Variable frequency drives require rectification front-ends capable of withstanding grid voltage transients and regenerative braking energy return.
- Battery Chargers:Consumer and industrial charging systems span silicon diodes for cost-sensitive applications to active rectification for bidirectional vehicle-to-grid integration.
Power supply applications lead on revenue concentration; renewable energy systems lead on technology upgrade intensity.
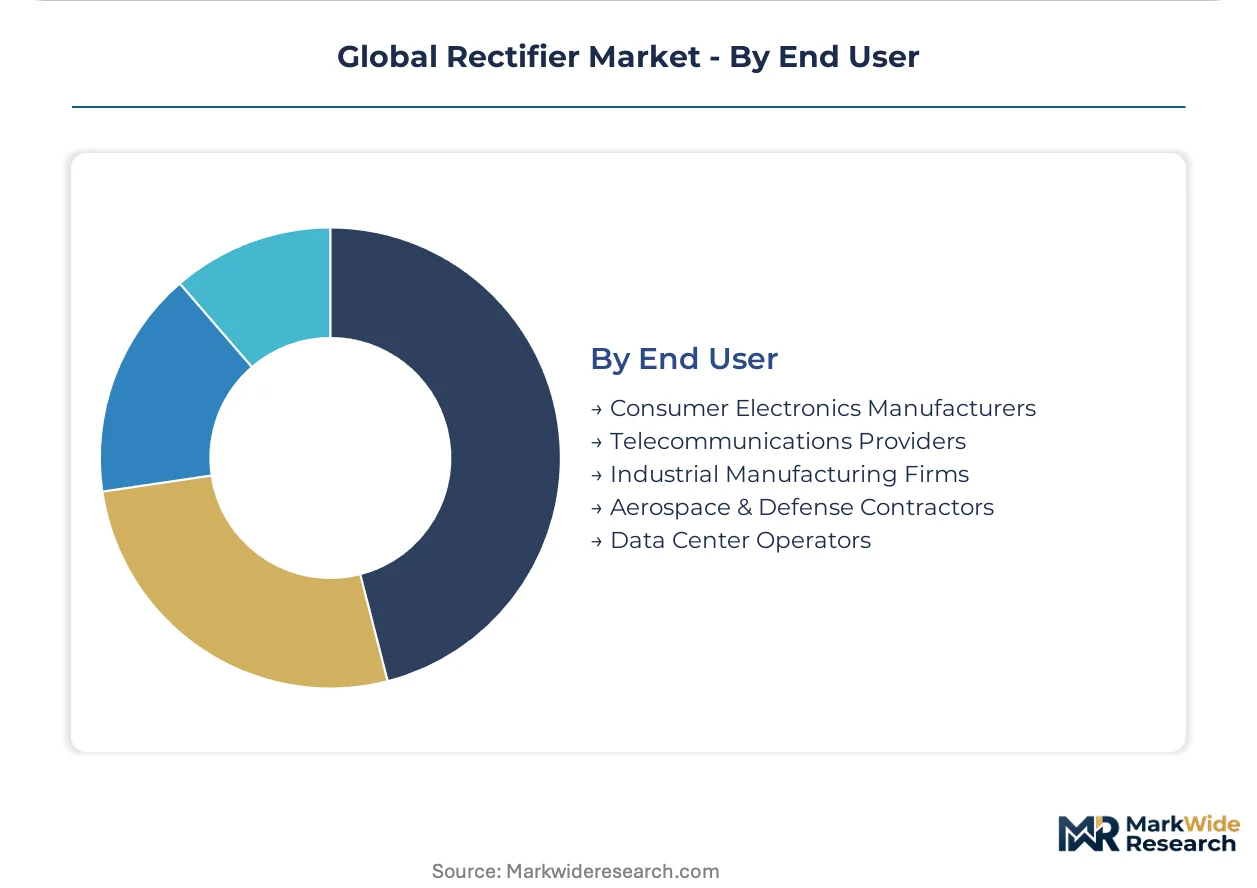
End User:
Qualification burden and procurement scale separate these buyer categories.
- Data Center Operators:Hyperscale facilities in Northern Virginia and Singapore specify silicon carbide rectifiers for power usage effectiveness targets, maintaining on-site supplier development engineers at wafer fabrication facilities.
- Industrial Manufacturing Firms:Motor drive and welding equipment OEMs prioritize bridge rectifier module availability and legacy footprint compatibility over cutting-edge efficiency.
- Consumer Electronics Manufacturers:Smartphone and laptop assemblers in Batam and Jakarta drive discrete silicon diode volume through consolidated procurement tenders.
- Telecommunications Providers:China's MIIT enforces GB standards for rectifier efficiency in base station power supplies, directly shaping product roadmaps for equipment serving that procurement base.
- Aerospace & Defense Contractors:United States defense contractor networks demand extended temperature range qualification and supply chain traceability documentation exceeding commercial standards.
Consumer electronics manufacturers lead on unit volume; data center operators lead on specification influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The rectifier industry traces its modern scaling to post-war German industrial electrification and subsequent Japanese semiconductor manufacturing expansion, with contemporary demand clustering around data center corridors and renewable energy manufacturing zones across five major economies.
United States
Defense contractor networks and hyperscale data center operators drive specification-grade demand for wide bandgap rectifiers. The Department of Defense maintains traceability requirements exceeding commercial standards for power electronics in aerospace applications. Northern Virginia's data center corridor specifies silicon carbide devices for power usage effectiveness compliance, with procurement teams embedding engineers directly at wafer fabrication facilities.
Germany
Industrial automation OEMs and automotive suppliers anchor European demand for bridge rectifier modules and intelligent power systems. The EU F-Gas Regulation accelerates dry etching adoption across semiconductor fabrication, creating preference for domestic suppliers with certified alternative processes. Bavaria's industrial automation corridor concentrates rectifier procurement for motor drives and welding equipment, with system integrators prioritizing 20-year reliability under thermal cycling stress.
China
Telecommunications infrastructure deployment and dual carbon enforcement reshape product roadmaps for equipment manufacturers. MIIT enforces GB standards for rectifier efficiency in base station power supplies, compressing development cycles for serving that procurement base. Shenzhen and Dongguan electronics manufacturing clusters drive discrete silicon diode volume for consumer power supplies and battery charger assemblies.
India
Electronics manufacturing incentives and telecommunications expansion concentrate assembly capacity in specific industrial zones. The PLI scheme for electronics manufacturing generates localized demand for bridge rectifier modules in welding equipment across Noida and Sri City. BIS certification requirements for power electronics imports extend procurement cycles, favoring suppliers with established Bengaluru laboratory relationships.
Japan
Automotive electrification and industrial machinery export markets sustain demand for high-reliability rectification components. METI standards for power semiconductor efficiency shape product development priorities for equipment serving domestic and Southeast Asian markets. Kyushu's semiconductor manufacturing base supplies discrete rectifiers for automotive onboard chargers, with OEMs requiring full material disclosure back to mine origin for compliance.
Global Rectifier Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material technology and thermal efficiency specifications. The vendor base organizes into three tiers: integrated device manufacturers with captive silicon carbide substrate supply, fabless specialists leveraging foundry partnerships for cost positioning, and discrete component assemblers serving consumer electronics volume. Strategic differentiation concentrates on M&A activity targeting wide bandgap packaging expertise and capacity expansion in ASEAN customs zones to serve relocated electronics assembly.
Among European integrated device manufacturers, Infineon Technologies AG and STMicroelectronics occupy positions at the premium-tier intersection of silicon carbide modules and automotive qualification depth. ON Semiconductor represents the North American archetype combining intelligent power modules with active control integration. Vishay Intertechnology anchors the discrete component tier through extensive foundry partnerships and automotive qualification breadth.
| Leading Market Players |
|---|
| Vishay Intertechnology |
| Diodes Incorporated |
| Infineon Technologies AG |
| Renesas Electronics Corporation |
| NXP Semiconductors |
| ON Semiconductor |
| Toshiba Corporation |
| Mitsubishi Electric Corporation |
| STMicroelectronics |
| Others |
Supply & Pricing Matrix
Silver sintering paste and high-purity silicon carbide substrates flow from Japanese and German chemical suppliers through three distinct pricing tiers before reaching data center procurement teams in Ashburn and Frankfurt. This input-cost cascade separates premium SiC module suppliers from commodity silicon diode assemblers serving consumer electronics manufacturers in Batam and Jakarta.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates rectifier procurement, with certification grade under EU F-Gas Regulation and volume scale driving differentiation between tiers. Cost compression in the economy tier is intensifying because gallium nitride substitution threatens silicon diode volume foundations. Consumer electronics manufacturers in ASEAN customs zones exhibit the highest price sensitivity, while data center operators prioritize thermal efficiency over unit economics.
Supply Chain Analysis
Freight costs from Wolfspeed's North Carolina substrate facilities and II-VI's Pennsylvania wafer operations to European module assembly plants add meaningful landed cost premiums for silicon carbide rectifiers. Supply concentrates in the United States, Germany, and China, with raw material dependencies on high-purity silicon carbide boules, silver sintering materials, and nickel-palladium-gold plating systems. Single-source vulnerability in 150mm SiC wafer supply constrains output expansion. Distribution runs through direct foundry relationships for hyperscale buyers and traditional electronics distributors for smaller OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global rectifier market represents a late-cycle quality story as data center efficiency mandates force procurement committees toward silicon carbide specifications despite 40% unit cost premiums over silicon alternatives.
For Market Incumbents: Deepen captive silicon carbide substrate supply through backward integration into wafer production or long-term offtake agreements with Wolfspeed and II-VI. Expand silver sintering assembly capacity in ASEAN customs zones to serve relocated consumer electronics manufacturing. Defend against gallium nitride encroachment by accelerating R&D investment in integrated intelligent power modules that combine rectification with active firmware control. For New Entrants and Emerging Players: Direct e-commerce platforms and specialized distributor partnerships offer lower-friction entry paths than direct OEM qualification. Target bridge rectifier replacement demand in India's PLI-subsidized welding equipment sector, where legacy footprint compatibility requirements fragment incumbent SKU portfolios. Emphasize rapid BIS certification turnaround through established Bengaluru laboratory relationships as a differentiated service layer. For Investors and Strategic Acquirers: Consolidation pressure builds where wide bandgap packaging expertise remains scarce relative to design capacity expansion announcements. The five-to-ten-year viability window favors suppliers with demonstrated silver sintering thermal management capabilities and certified low-carbon production processes under EU Green Deal carbon border adjustments. Acquisition target archetypes include mid-cap discrete component assemblers with automotive qualification depth and established foundry partnerships. Monitor silicon carbide substrate utilization rates at major wafer fabrication facilities as the primary inflection indicator for module output constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Silver Sintering Assembly Capacity Expansion | Addresses thermal management bottlenecks in SiC module production for data center power supplies. |
| Backward Integration into SiC Substrate Supply | Secures wafer allocation priority amid Wolfspeed and II-VI supply constraints. |
| BIS Certification Fast-Track Investment | Compresses 14-18 week procurement cycles for power electronics imports into India. |
| EU Green Deal Low-Carbon Process Certification | Creates first-mover advantage under carbon border adjustments on imported power electronics. |
| Intelligent Power Module Firmware Integration | Differentiates against commodity rectifiers through active switching control capabilities. |
Research Methodology
Direct dialogue with power semiconductor procurement managers, data center infrastructure engineers, automotive electronics sourcing leads, and industrial welding equipment OEMs grounded this analysis in operational reality. Secondary validation drew from SEC 10-K filings of major integrated device manufacturers, EU F-Gas Regulation implementation documents, India's PLI scheme administrative records, and customs data tracking silicon carbide wafer trade flows. Bottom-up and top-down triangulation reconciled component-level demand estimates with end-use application forecasts.
Bottom-up modeling of unit shipments across product type, technology layer, application, and end-user segments generated volume foundations, while top-down macroeconomic and regulatory scenario analysis shaped growth trajectory bounds across the projection horizon. Segmentation dimensions included material composition, packaging architecture, voltage rating, and regional regulatory cluster. CAGRs were derived from regression analysis of historical procurement patterns against efficiency mandate implementation timelines and substrate supply expansion announcements.
Substrate supply disruption, gallium nitride substitution acceleration, and carbon border adjustment enforcement timing are the dominant revision risks that could alter forecast trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Space DC-DC Converters Market
Power Systems
Three-Phase String Inverter Market
Power Systems
Grid Tie Inverter Market
Power Systems
Global Excitation Systems Market
Power Systems
Thyristor Market
Power Systems
DC Power Supplies Market
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
North America Electric Vehicle Power Inverter Market
Power Systems
Global Fault Current Limiter Market
Power Systems
Asia-Pacific Uninterruptible Power Supply (UPS) Market
Power Systems
North America Telecom Power Systems Market
Power Systems
PV Inverter Market
Power Systems
Grid Forming Inverters Market
Power Systems
Embedded Power Generation Market
Power Systems
Global Plasma Generators Market