
 Pressure Switch Market | 2026-2036
Pressure Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Switch Market Analysis
A capital-intensity divergence between integrated sensor manufacturers and component assemblers is redrawing competitive boundaries in the pressure switch industry. ABB leverages its factory automation ecosystem to bundle smart pressure switches with distributed control systems. Danfoss sustains dominance in refrigeration and HVAC applications through captive production of electromechanical diaphragm mechanisms. Bosch Rexroth anchors its position in hydraulic power units by controlling specification standards for mobile machinery pressure controls.
A pressure switch is an electromechanical or solid-state device that actuates an electrical contact when a fluid pressure crosses a predetermined setpoint, typically calibrated in pounds per square inch or bar with hysteresis bands of three to ten percent to prevent chatter. Its primary industrial purpose is to protect pumps, compressors, and process vessels from overpressure or underpressure conditions by triggering alarms, shutdowns, or control loop interventions. Electronic and solid-state variants are capturing margin pools in precision applications where vibration immunity and million-cycle longevity justify premium positioning, while mechanical types retain volume leadership in cost-sensitive utility and agricultural equipment. Smart technology installations are expanding fastest in water treatment and oil and gas sectors, where IO-Link connectivity enables predictive maintenance integration with SCADA architectures.
EPA mandates on methane emissions monitoring in US oil and gas infrastructure are compelling operators to specify digital pressure switches with data-logging capabilities for leak detection programs. EU machinery directives and CE marking requirements enforced by national market surveillance authorities are elevating documentation burdens for mechanical switch exporters seeking European industrial access. China's GB standards administered by SAMR are tightening accuracy classes for pressure controls used in boiler safety systems. Stakeholders must monitor how regional certification fragmentation affects platform standardization strategies and service network economics.
Market Dynamics
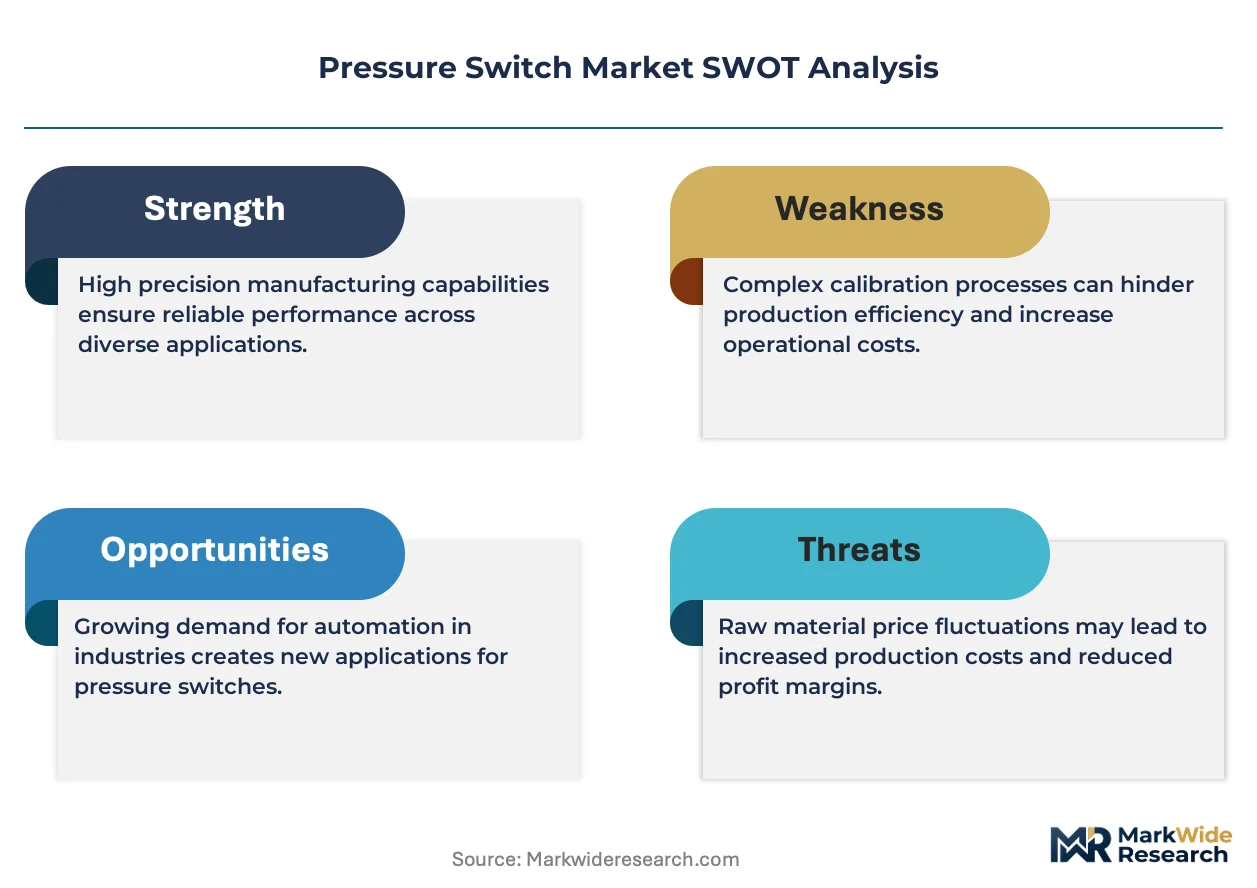
Mechanical pressure switch architectures face systematic replacement as electronic variants with IO-Link connectivity capture specification authority in process industries, compressing the addressable market for diaphragm-actuated electromechanical units and redistributing margin pools toward semiconductor-based sensing platforms.
Growth Catalysts
- Water treatment infrastructure modernization:Municipal utilities in the United States are specifying electronic pressure switches with data-logging capabilities for SCADA integration in distribution networks. Procurement volumes concentrate in states with aging pipe infrastructure.
- EU F-Gas Regulation Phase-Down:Refrigeration system OEMs in Germany must retrofit or replace legacy mechanical controls to meet tighter leak-detection mandates for fluorinated gases. This compels specification upgrades across commercial cold chain equipment.
- Automotive paint shop automation:China's eastern manufacturing corridor is accelerating replacement cycles for legacy mechanical units as BYD and Tesla supplier parks demand vibration-immune solid-state pressure monitoring in robotic spray booths.
Market Restraints
- Silicon wafer supply concentration:Taiwan Semiconductor Manufacturing and Samsung Foundry control advanced MEMS fabrication capacity, exposing electronic pressure switch producers to allocation risk during geopolitical disruptions.
- Stainless steel input volatility:316L diaphragm material costs fluctuate with nickel pricing on the London Metal Exchange, compressing margins for electromechanical switch assemblers locked into annual supply agreements.
- Mechanical longevity in benign environments:Agricultural irrigation systems in India continue specifying bimetallic strip pressure switches because million-cycle durability offers no operational advantage against seasonal usage patterns.
Strategic Opportunities
- Boiler safety system upgrades in China:SAMR's tightened GB standards for pressure control accuracy create specification windows for precision electronic switches in industrial steam generation facilities across Jiangsu and Zhejiang provinces.
- Hydrogen refueling infrastructure:Germany's KBA certification requirements for 700-bar dispensing systems favor solid-state pressure monitoring with embedded safety shutoff logic, opening a nascent application vertical.
- Convergence of pressure sensing and edge computing:Integration of ARM Cortex-M4 microcontrollers directly into switch housings enables localized anomaly detection without PLC dependency, appealing to oil and gas operators with remote wellhead assets.
Industry Challenges
- Embedded firmware certification timelines:IEC 61508 functional safety validation for programmable pressure switches extends development cycles by 14-18 months, delaying revenue recognition for product line refreshes.
- Legacy 4-20mA integration complexity:Brownfield process plants in the United States require signal conditioning hardware to bridge IO-Link-native switches to existing DCS architectures, inflating installed cost and complicating vendor selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Switch Market |
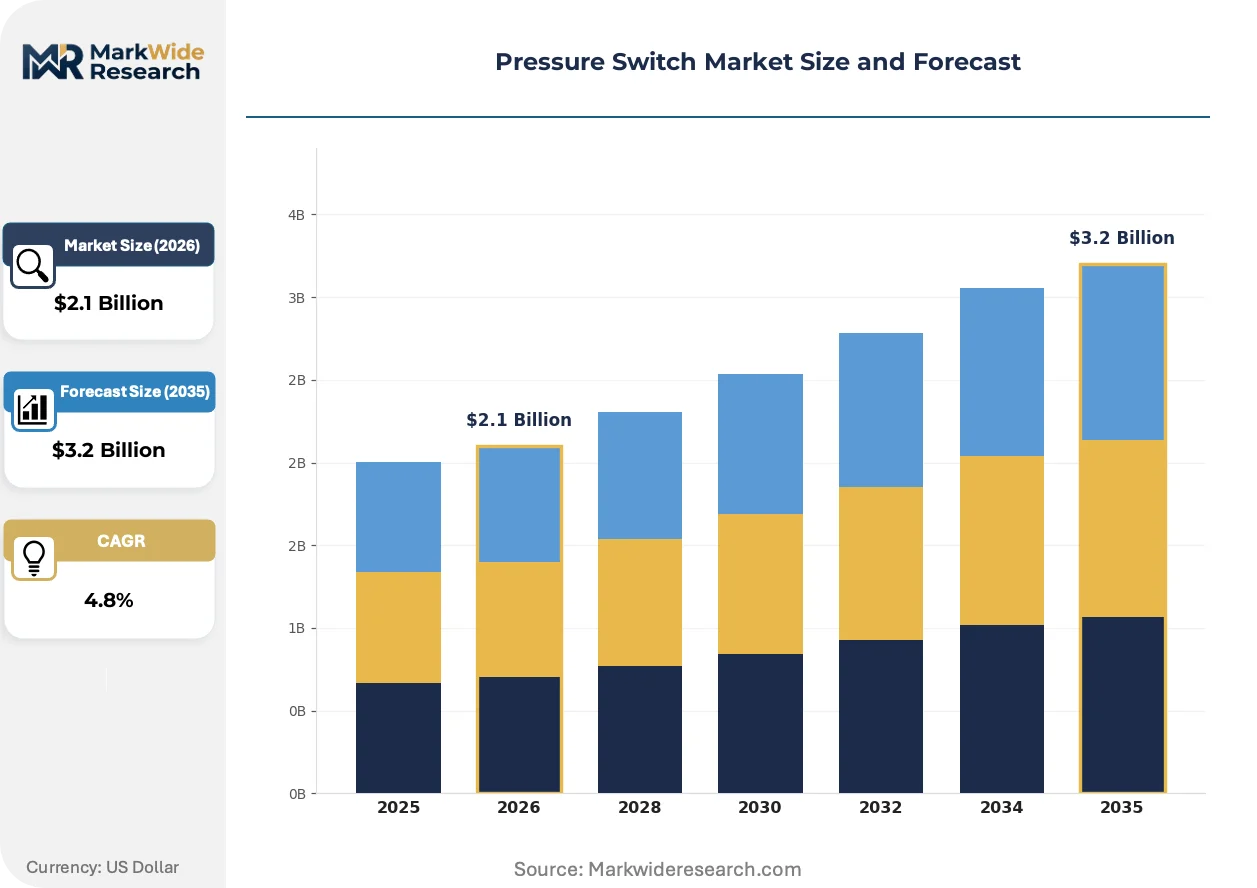
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electronic, Solid State, Variants End User: Oil & Gas, Automotive, Manufacturing, Water Treatment Technology: Analog, Digital, Smart, Hybrid Installation: Panel Mount, Pipe Mount, Direct Mount, Remote Mount |
| Companies Covered | ABB, Danfoss, Eaton, Parker Hannifin, Emerson, Honeywell, Bosch Rexroth, Schneider Electric, Barksdale Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Switch Market Emerging Trajectories
Solid-state MEMS pressure sensing is systematically capturing specification authority from electromechanical architectures, while regulatory mandates on emissions monitoring and machinery safety accelerate documentation burdens and reshape competitive positioning around certification depth.
Silicon carbide MEMS pressure transducers with integrated ASIC signal conditioning are displacing welded-diaphragm Bourdon tube mechanisms in high-cycle hydraulic power unit applications. Mobile machinery OEMs in Germany and Japan are specifying these variants for million-cycle longevity in excavator and loader implement circuits. The displacement is compressing aftermarket revenue pools for mechanical switch rebuild services while concentrating margin capture with semiconductor-integrated platform suppliers.
The EU Machinery Directive 2006/42/EC and subsequent CE marking enforcement by German market surveillance authorities now require pressure switches to carry notified body certification for safety-related control functions. This elevates documentation burdens for Asian exporters seeking European industrial access. Mechanical switch producers without EU-based technical file management capabilities are ceding specification authority to competitors with captive notified body relationships.
Specification authority is migrating from maintenance departments to central engineering procurement functions as predictive maintenance platforms require standardized IO-Link data structures across instrument populations. Water treatment operators in California and Texas are consolidating vendor lists to three approved platforms to simplify SCADA integration. This concentration is marginalizing regional distributors who lack field application engineering depth for protocol configuration and diagnostic support.
Pressure Switch Market Segmentation
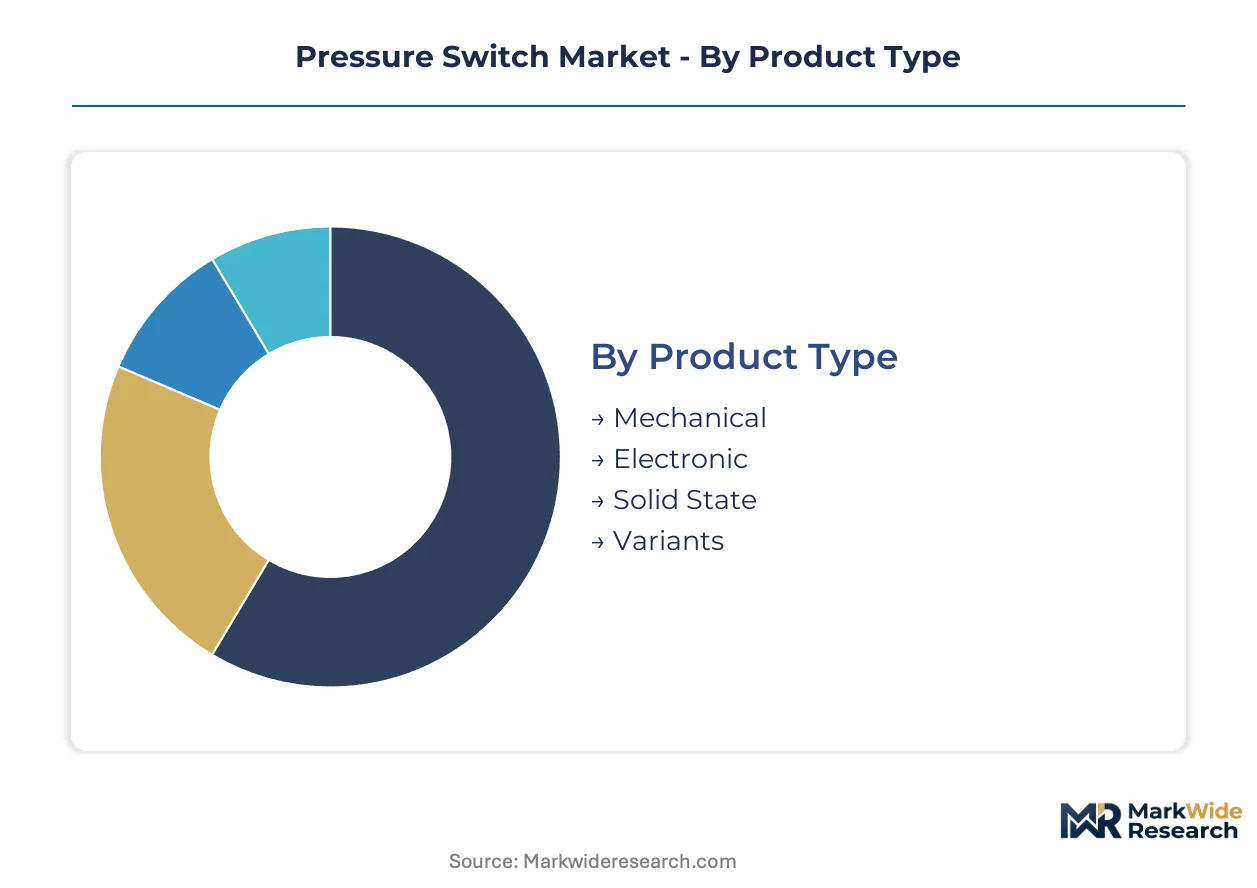
Pressure switch procurement patterns diverge sharply across product architectures and end-use environments. Specification authority migrates toward electronic and smart variants where regulatory mandates demand data traceability, while mechanical units retain volume in cost-constrained utility applications.
Product Type:
EU F-Gas Regulation leak-detection mandates and EPA methane monitoring rules split certification requirements between electromechanical and solid-state platforms.
- Mechanical:Diaphragm-actuated electromechanical designs with welded Bourdon tube mechanisms serve agricultural irrigation and legacy HVAC systems. India's seasonal irrigation networks specify bimetallic strip variants where million-cycle durability offers no operational advantage against intermittent usage patterns.
- Electronic:MEMS-based sensing elements with ASIC signal conditioning capture specification authority in process industries. Germany's refrigeration OEMs retrofit commercial cold chain equipment with these units to satisfy tighter fluorinated gas controls.
- Solid State:Silicon carbide pressure transducers with embedded microcontrollers enable localized anomaly detection without PLC dependency. Oil and gas operators with remote wellhead assets in Texas and North Dakota specify these for predictive maintenance integration.
- Variants:Specialized electropneumatic and piezoelectric configurations address niche aerospace and medical oxygen system applications.
Established volume favors Mechanical; emerging adoption favors Electronic.
End User:
Capital intensity and regulatory exposure concentrate margin pools in hydrocarbon extraction and automotive paint shop automation.
- Oil & Gas:Digital pressure switches with data-logging capabilities satisfy EPA mandates for methane emissions monitoring across US pipeline infrastructure. Leak detection programs in the Permian Basin and Bakken formation drive procurement of IO-Link-native units with SCADA integration.
- Automotive:BYD and Tesla supplier parks in China's eastern manufacturing corridor specify vibration-immune solid-state monitoring for robotic spray booths. Solid-state variants displace legacy mechanical units as automation upgrades accelerate replacement cycles.
- Manufacturing:Hydraulic power unit OEMs in Germany and Japan specify million-cycle silicon carbide variants for excavator implement circuits.
- Water Treatment:Municipal utilities in California and Texas consolidate vendor lists to three approved platforms for simplified SCADA integration in distribution networks.
Procurement scale concentrates in Oil & Gas; specification complexity climbs fastest in Automotive.
Technology:
Signal protocol architecture determines integration economics in brownfield versus greenfield installations.
- Smart:ARM Cortex-M4 microcontrollers embedded directly into switch housings enable edge computing without PLC dependency. Water treatment infrastructure operators specify these for predictive maintenance platforms requiring standardized IO-Link data structures.
- Digital:Native IO-Link connectivity with diagnostic parameter transmission captures specification authority in process industries. Brownfield plants require signal conditioning hardware to bridge these units to existing 4-20mA DCS architectures.
- Analog:Conventional 4-20mA output signals retain installed base in legacy process plants with decade-old distributed control systems.
- Hybrid:Dual-output configurations combining analog and digital protocols ease transition paths for utilities with mixed-generation instrumentation.
Deployment breadth favors Analog; capability expansion favors Smart.
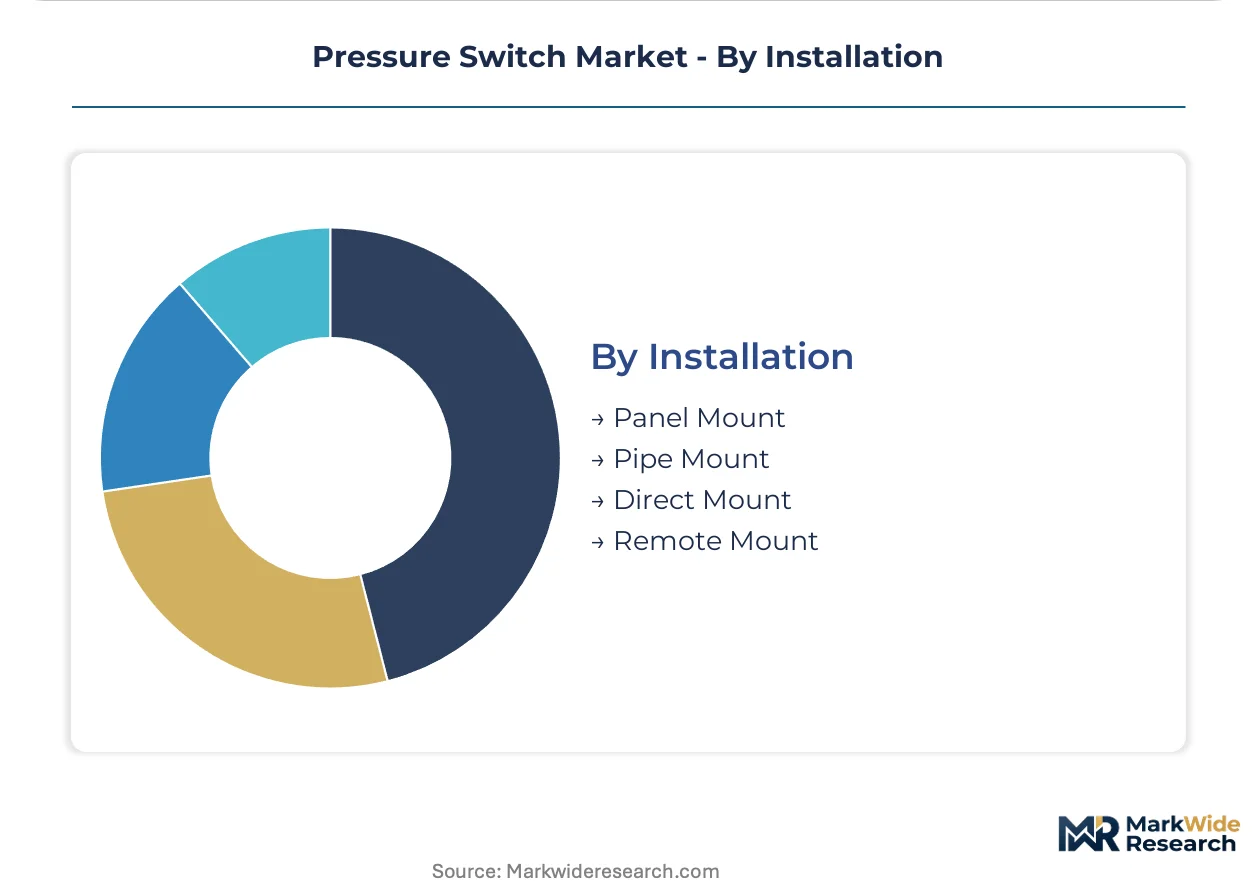
Installation:
Mounting geometry constrains material selection and sealing specifications for environmental exposure.
- Panel Mount:Enclosed switch housings with terminal block connections dominate control cabinet installations in manufacturing facilities. Stainless steel 316L diaphragm material costs fluctuate with London Metal Exchange nickel pricing.
- Pipe Mount:Inline threaded configurations with NPT or BSP process connections serve hydraulic power units and compressor packages. Mobile machinery OEMs in Germany specify these for excavator and loader implement circuits.
- Direct Mount:Compact designs with integral sensor elements address space-constrained boiler safety systems in China's Jiangsu and Zhejiang provinces.
- Remote Mount:Separated sensing heads with cable-connected electronics tolerate high-temperature or high-vibration process environments.
Application flexibility favors Pipe Mount; environmental tolerance favors Remote Mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in pressure switches tilt toward manufacturing economies with captive sensor fabrication capacity, while import dependency concentrates in regions lacking MEMS foundry infrastructure. Trade patterns track regulatory divergence on machinery safety and emissions monitoring protocols.
United States
EPA methane monitoring mandates drive specification upgrades across Permian Basin pipeline infrastructure. Municipal water utilities in California and Texas consolidate vendor lists for SCADA-integrated electronic switches. Houston and Dallas-Fort Worth clusters anchor procurement for oil and gas leak detection programs.
Germany
KBA certification requirements for 700-bar hydrogen refueling systems favor solid-state pressure monitoring with embedded safety logic. EU F-Gas Regulation phase-down compels refrigeration OEMs in Bavaria to retrofit commercial cold chain equipment. Stuttgart and Munich automotive supplier parks specify vibration-immune variants for robotic paint applications.
China
SAMR's tightened GB standards for boiler safety systems create specification windows in Jiangsu and Zhejiang provinces. BYD and Tesla supplier parks in the eastern manufacturing corridor accelerate replacement cycles for legacy mechanical units. Shanghai and Suzhou industrial clusters concentrate demand for automation-grade solid-state switches.
Japan
METI industrial decarbonization programs elevate accuracy requirements for process control systems in chemical and steel plants. Mobile machinery OEMs in the Chubu region specify silicon carbide variants for excavator implement circuits. Nagoya and Osaka manufacturing belts sustain procurement for million-cycle hydraulic power unit applications.
India
Seasonal irrigation networks in Maharashtra and Gujarat specify bimetallic strip mechanical switches where intermittent usage patterns negate electronic durability advantages. Central Electricity Authority boiler safety directives tighten accuracy classes for industrial steam generation. Ahmedabad and Pune industrial corridors concentrate procurement for cost-sensitive utility equipment.
Pressure Switch Market Vendor Landscape
Concentration sits with diversified industrial conglomerates controlling factory automation ecosystems and captive electromechanical component production. The vendor base stratifies across three tiers: integrated sensor manufacturers bundling smart switches with distributed control systems, electromechanical specialists dominating refrigeration and HVAC applications through diaphragm mechanism expertise, and hydraulic power unit suppliers anchoring mobile machinery segments via specification standard control. Dominant competitive moves include backward integration into MEMS fabrication capacity and strategic partnerships with semiconductor foundries to secure wafer allocation.
Within the integrated automation tier, ABB and Schneider Electric exemplify platform bundling strategies that capture specification authority through distributed control system relationships. Danfoss occupies a position among electromechanical specialists with captive diaphragm production capabilities. Bosch Rexroth anchors the hydraulic power unit segment, representing manufacturers that control mobile machinery specification standards. These archetypes illustrate how competitive positioning depends on vertical scope rather than product specialization alone.
| Leading Market Players |
|---|
| ABB |
| Danfoss |
| Eaton |
| Parker Hannifin |
| Emerson |
| Honeywell |
| Bosch Rexroth |
| Schneider Electric |
| Barksdale Inc. |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation certification gates both supply qualification and price differentiation simultaneously, forcing refrigeration OEMs to source only from vendors with notified body relationships while compressing margins for uncertified mechanical switch exporters. This regulatory filter stratifies the vendor base into premium-certified and economy-excluded tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on IEC 61508 functional safety certification grade and volume scale commitments. Cost compression in the economy tier is intensifying because stainless steel 316L diaphragm material costs fluctuate with London Metal Exchange nickel pricing. Agricultural irrigation operators in India exhibit the highest price sensitivity, while oil and gas leak detection programs in the Permian Basin tolerate premium positioning for data-logging capabilities.
Supply Chain Analysis
Taiwan Strait transit underwrites semiconductor-dependent supply flows for MEMS-based electronic pressure switches. Advanced MEMS fabrication concentrates in Taiwan, South Korea, and Japan, drawing from silicon wafer feedstock and ASIC signal conditioning components. Single-source vulnerability sits with TSMC and Samsung Foundry controlling advanced fabrication capacity. Distribution runs through authorized industrial distributors with field application engineering capabilities for IO-Link protocol configuration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pressure switch market sits in early-cycle expansion as EPA methane monitoring mandates and EU F-Gas Regulation phase-downs accelerate specification upgrades from mechanical to electronic architectures.
For Market Incumbents: Secure captive MEMS fabrication capacity or foundry allocation agreements to insulate against Taiwan semiconductor supply disruptions. Deepen backward integration into silicon carbide transducer production to capture margin pools in hydraulic power unit applications. Invest in notified body certification infrastructure to defend European market access against Asian mechanical switch competitors lacking EU technical file management capabilities. For New Entrants and Emerging Players: Differentiate on edge-computing integration by embedding ARM Cortex-M4 microcontrollers directly into switch housings for localized anomaly detection. Target hydrogen refueling infrastructure in Germany as the most penetrable vertical, where KBA certification requirements for 700-bar systems favor solid-state monitoring with embedded safety shutoff logic. Pursue direct OEM relationships with mobile machinery manufacturers rather than distributor-dependent channel strategies. For Investors and Strategic Acquirers: EU Machinery Directive enforcement reshapes the acquisition landscape by elevating documentation burdens that mechanical switch producers cannot meet. Long-term viability favors semiconductor-integrated platform suppliers with captive sensing element production over electromechanical assemblers exposed to stainless steel input volatility. Watch for SAMR's progressive tightening of GB standards accuracy classes as the signal indicating specification windows for precision electronic switches in Chinese boiler safety systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Captures margin pools and insulates supply from TSMC allocation risk during geopolitical disruptions. |
| Notified Body Certification Investment | Secures European industrial access as EU Machinery Directive elevates documentation burdens for safety-related controls. |
| IO-Link Protocol Platform Standardization | Enables predictive maintenance integration with SCADA architectures in water treatment and oil and gas sectors. |
| Hydrogen Refueling System Partnership | Positions for KBA-certified 700-bar dispensing applications as Germany expands hydrogen infrastructure. |
| Edge Computing Switch Development | Appeals to remote wellhead operators seeking localized anomaly detection without PLC dependency. |
Methodological Framework
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this study. Plant engineers, OEM procurement teams, aftermarket service heads, and water treatment SCADA integration specialists provided operational perspective. Secondary sources include EPA enforcement actions, EU F-Gas Regulation implementation guidance, SAMR GB standard updates, SEC 10-K filings from diversified industrial conglomerates, and customs trade data for pressure switch import flows. Bottom-up demand modeling triangulates against top-down macroeconomic indicators.
Sensitivity analysis across the projection horizon tests forecast robustness against nickel price volatility and semiconductor supply disruption scenarios. Segmentation dimensions include product architecture, end-use environment, signal protocol technology, and mounting geometry. CAGRs derive from regression analysis of replacement cycle acceleration rates and regulatory mandate compliance timelines. Industry-specific inputs incorporate MEMS foundry capacity utilization rates and municipal water infrastructure capital expenditure patterns.
Material uncertainties — geopolitical disruption of Taiwan semiconductor supply, nickel price spikes on the London Metal Exchange, and regulatory enforcement intensity variations — sit outside the modeled envelope. Forecasts reflect assumptions about continued EPA methane monitoring rule implementation and EU F-Gas Regulation phase-down adherence. Practitioners should keep alternative scenarios live as SAMR standard revision timelines and hydrogen infrastructure buildout rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Argentina Automotive Reed Sensors Switches Market
Switches
Asia-Pacific Low Voltage Switchgear Market
Switches
UAE Switchgear Market
Switches
APAC Push Buttons and Signaling Devices Market
Switches
Power Load Switches Market
Switches
Tactile Switch Keyboard Market
Switches
Matrix Switches Market
Switches
Molded Case Circuit Breaker Market
Switches
Europe Switchgear Market
Switches
Vibration Level Switch Market
Switches
Global High Voltage Switchgear Market
Switches
Australia and New Zealand Medium Voltage Switchgear Market
Switches
Electric Switch Market
Switches
Contactor-based Transfer Switch Market
Switches
Smart Dimmer Switch Market
Switches
Level Switches Market