
 APAC Semiconductor Device in Aerospace and Defense Market | 2026-2036
APAC Semiconductor Device in Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Semiconductor Device in Aerospace and Defense Market Insights
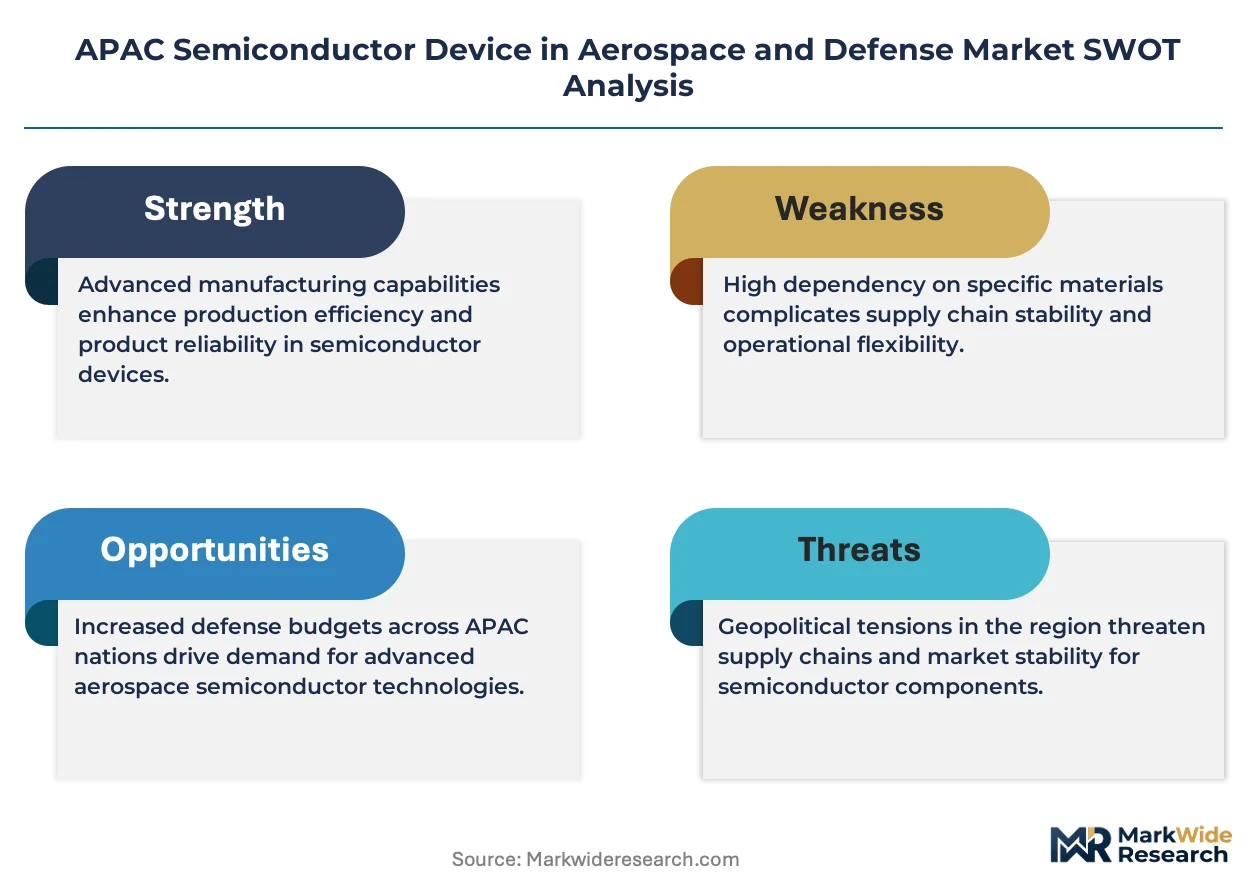
Project finance tied to sovereign defense offsets is narrowing the field of viable competitors across APAC. TSMC leverages government-backed foundry partnerships in Taiwan to sustain dedicated aerospace wafer lines. Samsung Electronics anchors South Korean defense procurement through captive silicon carbide capacity. Infineon Technologies differentiates via its gallium nitride roadmap for radar and electronic warfare systems.
APAC semiconductor devices for aerospace and defense comprise engineered electronic components—integrated circuits, discrete semiconductors, and power devices—fabricated to withstand extreme temperatures, radiation exposure, and mechanical shock across operational lifetimes exceeding fifteen years. These devices process signal, power, and control functions in platforms where failure tolerance approaches zero. Integrated circuits dominate current procurement volumes due to their ubiquity in navigation and communication payloads, while gallium nitride power devices represent the fastest-expanding margin pool as radar systems transition to higher-frequency operation. Silicon carbide traction is accelerating in motor control and power distribution architectures for next-generation military aviation.
Japan's METI coordinates national semiconductor strategy with defense qualification pathways, while India's PLI scheme and CEA grid-integration standards shape where fabrication investment lands. Australia's TGA-equivalent defense materiel certification adds a third compliance layer for subsystem exporters. Stakeholders must track which regulatory framework—METI's technology roadmaps, India's production-linked incentives, or Australia's sovereign capability mandates—ultimately governs access to the highest-reliability tier of APAC defense semiconductor demand.
Market Dynamics
Defense procurement offsets are compressing vendor eligibility across APAC, as sovereign capability mandates in Japan, South Korea, and Australia require domestic fabrication or technology transfer as contract conditions.
Growth Catalysts
- Gallium Nitride Transition:Radar and electronic warfare systems are migrating from gallium arsenide to gallium nitride power amplifiers, expanding addressable device value per platform.
- India's PLI Scheme:Production-linked incentives for semiconductor manufacturing are redirecting foundry investment toward defense-qualified domestic capacity.
- Radiation-Hardened Demand:Satellite constellation deployments and high-altitude aviation programs are accelerating procurement of rad-hard integrated circuits.
Market Restraints
- Specialized Substrate Costs:Silicon carbide and gallium nitride wafers command 5-10x silicon pricing, compressing margins on fixed-price defense contracts.
- Foundry Concentration:Defense-qualified advanced node production clusters in Taiwan and South Korea create single-source vulnerability for non-aligned buyers.
- Dual-Use Export Controls:Multilateral technology transfer restrictions fragment equipment and design tool access across national boundaries.
Strategic Opportunities
- India's Fab Ecosystem:Greenfield semiconductor manufacturing zones in Gujarat and Assam offer first-mover positioning for defense-qualified supply chains.
- Hypersonic Thermal Management:Extreme-temperature semiconductor packaging for hypersonic vehicle guidance represents unmet specification demand.
- Japan-METI Roadmap Alignment:National semiconductor strategy coordination creates preferential qualification pathways for domestic subsystem integrators.
Industry Challenges
- Radiation Effects Engineering Talent:Specialized workforce for single-event upset modeling and total dose hardening remains concentrated in a handful of national laboratories.
- Defense Qualification Timelines:Military environmental stress screening and lot acceptance testing extend product introduction cycles to 24-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Semiconductor Device in Aerospace and Defense Market |
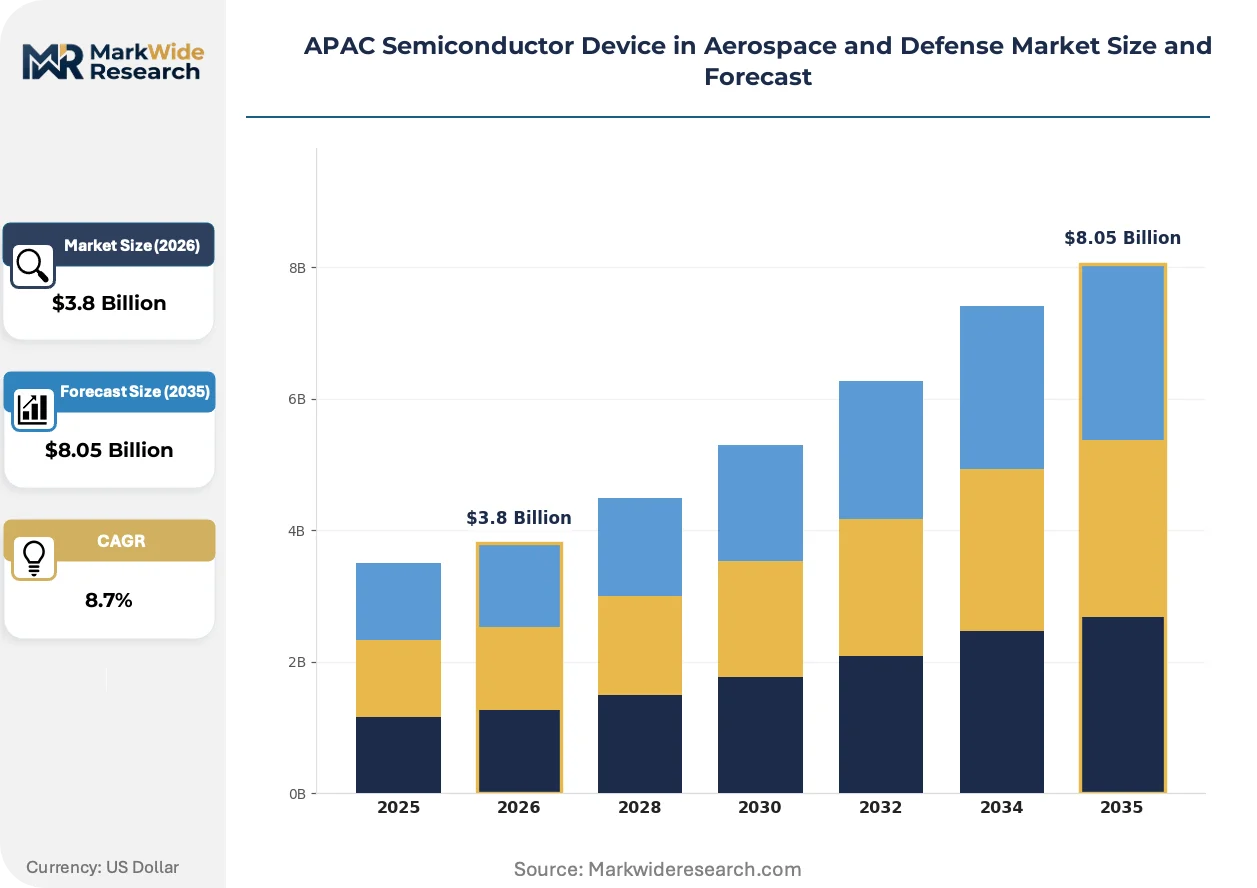
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Circuits, Discrete Semiconductors, LED Devices, Power Devices Application: Navigation Systems, Communication Devices, Control Systems, Surveillance Equipment End User: Military Aviation, Space Exploration, Defense Contractors, Commercial Aviation Technology: Silicon, Gallium Nitride, Silicon Carbide, MEMS |
| Companies Covered | Intel Corporation, TSMC, Samsung Electronics, STMicroelectronics, NXP Semiconductors, Toshiba Corporation, Renesas Electronics Corporation, Infineon Technologies, SK Hynix, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Semiconductor Device in Aerospace and Defense Market Trends and Innovations
Material science advances and sovereign industrial policy are converging to reshape how defense-grade semiconductors are specified, sourced, and integrated across APAC aerospace platforms.
Silicon carbide power modules are hybridizing discrete and integrated functionality for next-generation military aviation motor drives and power distribution systems. Japanese and South Korean airframe integrators are specifying these devices for variable frequency starter-generator applications. The technology is hybridizing previously separate power conversion stages, reducing component count and thermal management complexity in confined airframe volumes.
Australia's defense materiel certification framework is tightening subsystem traceability requirements for semiconductor provenance. The country's sovereign capability mandates now require documented wafer origin and foundry qualification status for critical flight systems. Australian platform integrators are responding by pre-qualifying dual-source supply chains across Japan and South Korea rather than sole-sourcing from Taiwan.
Platform primes are consolidating semiconductor procurement under long-term availability agreements rather than spot purchasing. Japanese and Indian defense contractors are shifting from transactional component buying to multi-year supply commitments with foundry partners. This pattern is most visible in satellite payload procurement, where radiation-hardened device lifetime buy strategies are displacing annual replenishment cycles.
APAC Semiconductor Device in Aerospace and Defense Market Segmentation
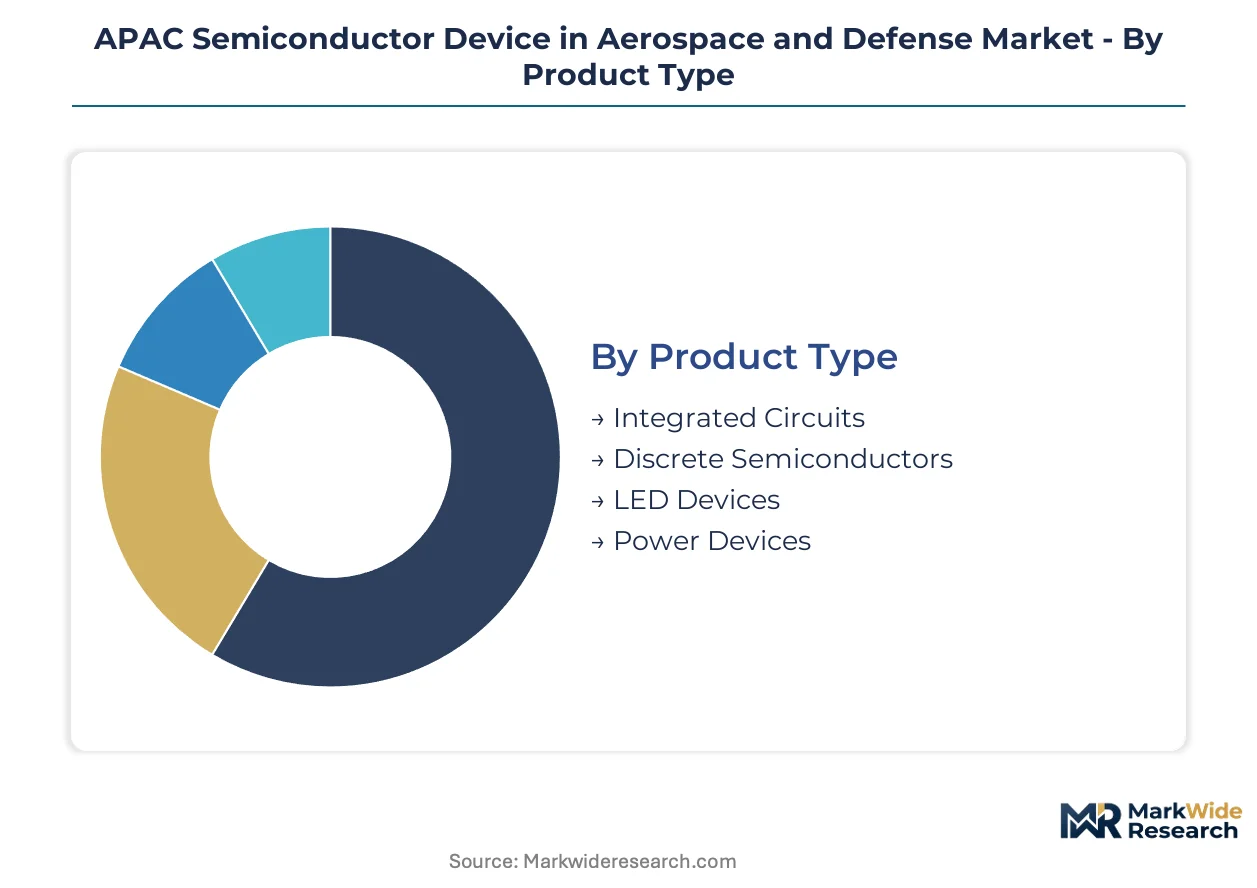
Defense procurement specifications in APAC diverge sharply across product generations and threat environments, forcing suppliers to maintain parallel qualification tracks for mature silicon platforms and emerging wide-bandgap technologies.
Product Type:
Mature silicon-based categories dominate current defense procurement volumes, while emerging compound semiconductor platforms capture the steepest technology transition premiums.
- Integrated Circuits:These devices combine multiple electronic functions on monolithic substrates, with radiation-hardened variants commanding specialized design rules for total dose immunity. Procurement concentrates in satellite navigation payloads across Japan and South Korea, driven by sovereign constellation deployments requiring fifteen-year operational lifetimes.
- Power Devices:Discrete switching components and modules handle energy conversion in motor drives and radar transmitters. Demand clusters in South Korean military aviation programs transitioning to silicon carbide-based variable frequency starter-generators, where higher switching frequencies reduce thermal management mass.
- Discrete Semiconductors:Individual transistor and diode components serve protection and signal conditioning roles in legacy platform retrofits.
- LED Devices:Solid-state emitters provide cockpit illumination and status indication in next-generation crew stations.
Integrated circuits retain volume leadership; power devices hold the steepest expansion curve.
Application:
Cost tier differentiation separates mission-critical flight systems from support electronics, with qualification overhead driving tiered pricing structures.
- Navigation Systems:Inertial measurement units and GPS receivers depend on precision signal processing with zero-failure tolerance. Japanese defense contractors source these subsystems through METI-coordinated qualification pathways, where domestic fabrication mandates add compliance layers but reduce supply chain exposure.
- Communication Devices:Tactical radios and satellite terminals require wide-bandwidth amplification with spectral efficiency. Gallium nitride power amplifiers are displacing gallium arsenide in Australian defense procurement, where sovereign capability mandates now require documented wafer provenance.
- Control Systems:Fly-by-wire and engine management electronics execute real-time control loops with deterministic latency.
- Surveillance Equipment:Electro-optical and signals intelligence payloads integrate sensor fusion processing at the edge.
Navigation systems anchor procurement value; communication devices are climbing the fastest on platform modernization cycles.
End User:
Customer type determines specification stringency, with military aviation and space exploration imposing the most demanding environmental stress screening protocols.
- Military Aviation:Fighter, transport, and rotary-wing platforms subject electronics to vibration, altitude cycling, and electromagnetic interference. India's defense procurement offsets now require domestic semiconductor content in avionics upgrades, redirecting subsystem integrators toward Gujarat-based fabrication zones.
- Space Exploration:Satellite buses and launch vehicles demand single-event upset hardened devices with guaranteed performance across radiation belts. Procurement in Japan and South Korea favors lifetime buy strategies over annual replenishment to mitigate foundry concentration risk.
- Defense Contractors:Tier-one system integrators consolidate component sourcing under long-term availability agreements.
- Commercial Aviation:Dual-use platforms with military derivatives require traceable supply chains but accept reduced qualification scope.
Military aviation commands procurement volume; space exploration shows the steepest technology premium expansion.
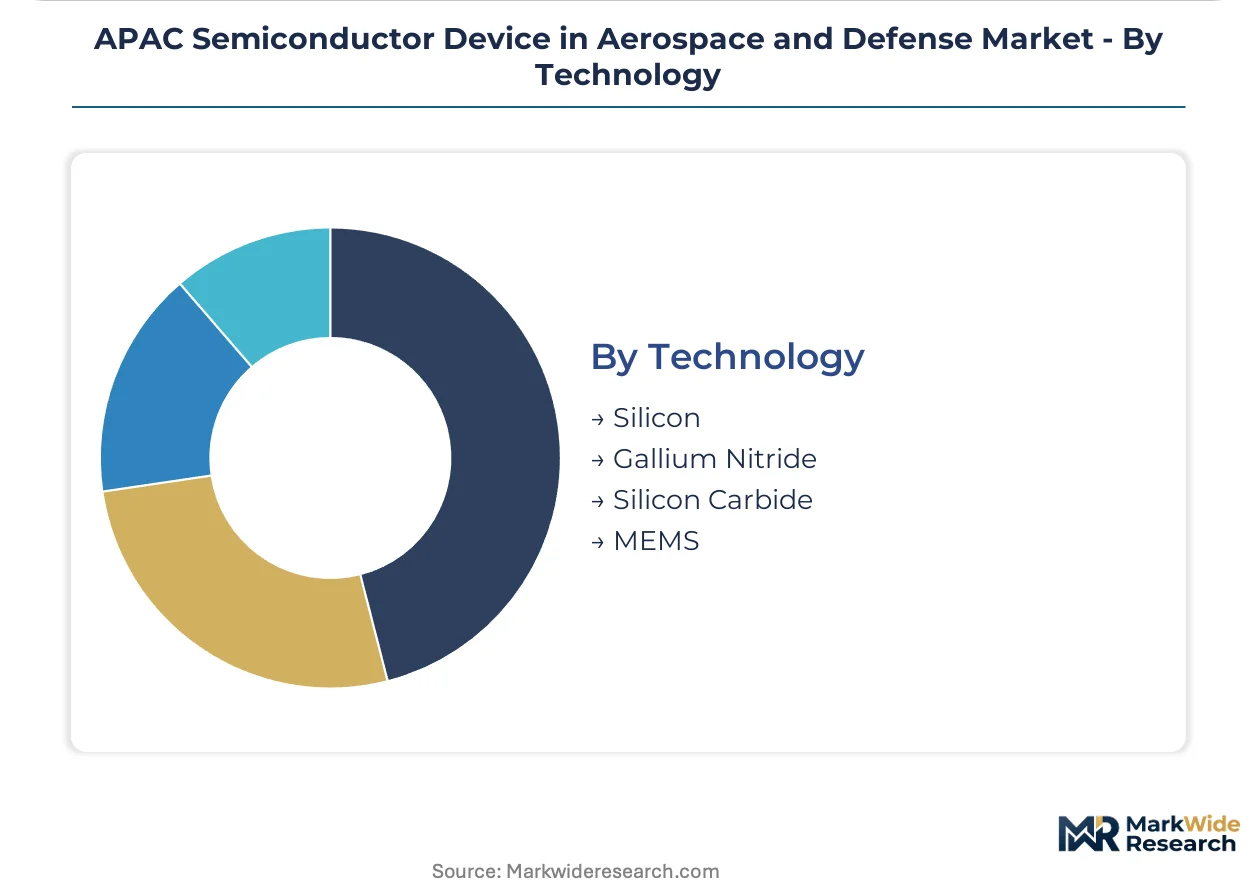
Technology:
Supply concentration in wide-bandgap substrates creates sourcing bottlenecks that favor vertically integrated device manufacturers with captive wafer capacity.
- Silicon:Mature CMOS and bipolar platforms deliver cost-effective performance for digital processing and analog functions. South Korean foundries anchor defense-qualified silicon output, with Samsung Electronics sustaining dedicated aerospace wafer lines through government-backed partnerships.
- Gallium Nitride:Wide-bandgap properties enable higher-frequency, higher-power operation in radar and electronic warfare transmitters. Infineon Technologies differentiates via GaN roadmaps for Australian and Japanese defense contractors seeking next-generation spectral dominance.
- Silicon Carbide:Superior thermal conductivity supports high-temperature operation in power conversion applications.
- MEMS:Micro-electromechanical systems enable miniaturized sensors for inertial navigation and pressure measurement.
Silicon maintains volume dominance; gallium nitride represents the fastest-growing trajectory as radar architectures migrate to higher frequencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement across APAC concentrates among sovereign platform integrators in Japan, South Korea, and Australia, with India's emerging domestic capacity redirecting supply chain investment toward Gujarat-based fabrication zones.
Japan
Military aviation and satellite constellation programs drive radiation-hardened integrated circuit demand. METI coordinates national semiconductor strategy with defense qualification pathways, creating preferential access for domestic subsystem integrators. The Kanto region around Tokyo anchors defense-qualified foundry partnerships and aerospace wafer line operations.
South Korea
Silicon carbide power devices for next-generation military aviation motor drives represent the steepest demand expansion. Government-backed foundry partnerships sustain dedicated aerospace wafer lines through Samsung Electronics and SK Hynix. The Seoul Capital Area concentration enables captive supply of defense-qualified advanced node production.
India
Defense procurement offsets now require domestic semiconductor content in avionics upgrades. The PLI scheme redirects foundry investment toward defense-qualified domestic capacity in Gujarat and Assam. Subsystem integrators are pre-qualifying supply chains within these greenfield manufacturing zones.
Australia
Sovereign capability mandates tighten subsystem traceability requirements for semiconductor provenance. The defense materiel certification framework requires documented wafer origin for critical flight systems. Platform integrators respond by dual-sourcing across Japan and South Korea rather than sole-sourcing from Taiwan.
Taiwan
TSMC leverages government-backed foundry partnerships to sustain dedicated aerospace wafer lines. Defense-qualified advanced node production creates single-source vulnerability for non-aligned buyers. The Hsinchu Science Park anchors the highest-reliability tier of radiation-hardened device output.
APAC Semiconductor Device in Aerospace and Defense Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around sovereign defense offsets and foundry concentration. Three archetypes dominate: vertically integrated device manufacturers with captive wafer capacity, pure-play foundries with government-backed defense lines, and subsystem integrators consolidating procurement under long-term availability agreements. Competitive moves center on backward integration into specialized substrates and strategic partnerships securing qualification pathway access.
Among Taiwan-based fabricators, TSMC occupies a position exemplifying the channel-controlling archetype through government-backed foundry partnerships. Samsung Electronics and SK Hynix represent the vertically integrated tier within South Korea's defense procurement ecosystem, anchoring captive silicon carbide capacity for military aviation applications. Infineon Technologies sits within the product-specialist tier, with its geographic origin signaling European-rooted compound semiconductor expertise applicable to radar and electronic warfare system roadmaps.
| Leading Market Players |
|---|
| Intel Corporation |
| TSMC |
| Samsung Electronics |
| STMicroelectronics |
| NXP Semiconductors |
| Toshiba Corporation |
| Renesas Electronics Corporation |
| Infineon Technologies |
| SK Hynix |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Taiwan's defense-qualified foundry lines is driving suppliers toward multi-year availability agreements and hardening pricing postures across APAC aerospace procurement. This utilization squeeze concentrates bargaining power with wafer fabricators while forcing subsystem integrators into fixed-price commitments that transfer substrate cost volatility downstream.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate defense semiconductor procurement across Japan and South Korea. Price differentiation separates radiation-hardened integrated circuits with METI qualification pathways from commercial-grade alternatives lacking military environmental stress screening. Pricing pressure stems from gallium nitride substrate shortages compressing margins on fixed-price radar system contracts. Defense contractors show highest price sensitivity in legacy platform retrofits, while space exploration programs accept premium positioning for guaranteed lot acceptance testing.
Supply Chain Analysis
Dual-use export controls under multilateral technology transfer regimes fragment equipment and design tool access across national boundaries. Geographic supply concentration centers on Taiwan, South Korea, and Japan for defense-qualified advanced node production. Raw material dependencies encompass silicon carbide wafers, gallium nitride substrates, and specialized packaging ceramics. Single-source vulnerability in Taiwan's Hsinchu Science Park creates procurement risk for non-aligned buyers. Distribution runs through tier-one defense contractors consolidating component sourcing under long-term availability agreements rather than spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against silicon carbide power modules displacing legacy silicon in military aviation motor drives. Incumbents must navigate this technology transition while preserving qualification pathway access.
For Market Incumbents: Pre-empt silicon carbide substitution by accelerating captive substrate capacity in South Korea's foundry corridor. Secure METI-coordinated qualification pathways for gallium nitride roadmaps before domestic Japanese integrators lock in preferred supplier status. Backward integration into specialized wafer production represents the critical defensive lever against margin compression from substrate cost inflation. For New Entrants and Emerging Players: India's Gujarat-based greenfield fabrication zones offer the most penetrable entry point for defense-qualified supply chain positioning. Pre-qualification with Australia's dual-source procurement mandates provides a secondary wedge for subsystem traceability compliance. Target foundry partnerships with PLI scheme beneficiaries rather than competing directly against Samsung Electronics' captive capacity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gallium nitride device manufacturing due to specialized epitaxy equipment requirements. Long-term viability over the next decade rests on securing wafer-level integration capabilities rather than remaining at the packaging tier. Acquisition targets should display proven defense qualification timelines under 24 months. Watch for India's CEA grid-integration standards tightening as the signal for domestic fabrication preference inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrates | Samsung Electronics anchors South Korean defense procurement through captive silicon carbide wafer supply. |
| Defense Qualification Pathway Investment | Japan's METI coordination creates preferential access for domestic subsystem integrators meeting JIS standards. |
| Long-term Availability Agreement | Japanese satellite payload contractors displace annual replenishment with lifetime buy strategies. |
| Greenfield Fab Partnership in Gujarat | India's PLI scheme redirects foundry investment toward defense-qualified domestic capacity zones. |
| Dual-source Supply Chain Pre-qualification | Australian platform integrators respond to sovereign capability mandates by diversifying across Japan and South Korea. |
Research Methodology
Cross-validation between primary interviews with defense procurement officers and secondary validation through customs filings anchors the qualitative findings. Semiconductor device engineering directors, foundry operations managers, subsystem integration leads, and defense materiel certification specialists contributed perspective across Japan, South Korea, India, and Australia. Secondary sources encompassed METI technology roadmaps, India's PLI scheme disclosures, CEA grid-integration standards, and Australia's defense materiel certification framework documentation. Bottom-up segment sizing and top-down macro constraint triangulation ensured analytical coherence.
Calibration against historical defense procurement cycles and foundry capacity utilization patterns shaped the projection framework. Segmentation dimensions encompassed product type, application, end user, technology, and country-level regulatory cluster. CAGRs were derived through trend extrapolation moderated by substrate supply constraints and qualification timeline bottlenecks. Forecast inputs included gallium nitride device adoption curves in radar systems and silicon carbide penetration rates in military aviation power distribution.
Stress conditions across gallium nitride substrate availability, defense budget allocation shifts, and export control enforcement stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding foundry concentration persistence and sovereign capability mandate trajectory. Material shifts in India's PLI scheme incentive structure or Australia's defense materiel certification requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
APAC Semiconductor Device for Industrial Applications Market
Semiconductor Devices
Printed Circuit Board (PCB) Laminate Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
High Speed Data Converters Market
Semiconductor Devices
Programmable Logic Device (PLD) Market
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
Gan and Sic Power Semiconductor Market
Semiconductor Devices
APAC Semiconductor Device for Processing Applications Market
Semiconductor Devices
ADC & DAC In Quantum Computing Market
Semiconductor Devices
Asia-Pacific Semiconductor Device Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Thin Wafer Market