
 Selenium Sulphide Market | 2026-2036
Selenium Sulphide Market Size, Share, and Industry Trends Forecast 2026-2036
Selenium Sulphide Market Intelligence
Customer concentration in the selenium sulphide market is shifting towards large, multinational cosmetic and pharmaceutical firms, diminishing the influence of smaller, regional buyers. Wockhardt Ltd leverages its pharmaceutical manufacturing base to secure a strong position in medicated treatments. BASF SE competes on the basis of its extensive chemical production scale and global distribution network. GlaxoSmithKline plc specializes in consumer healthcare products that incorporate the compound for specific dermatological applications.
Selenium sulphide is an inorganic compound with the chemical formula SeS2, recognized for its potent antifungal and cytostatic properties. It is typically produced as a bright orange to reddish-brown powder or suspension for formulation into topical treatments. The anti-dandruff application in personal care remains the primary demand driver for the market. Powder and suspension forms dominate the product landscape, with pharmaceutical-grade material commanding higher value due to stringent purity requirements for active ingredients.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) govern its use in pharmaceutical and cosmetic products. In China, the National Medical Products Administration (NMPA) sets standards for active pharmaceutical ingredients, which impacts market access. Future success will depend on navigating evolving regulations on active ingredient safety and securing supply chains for high-purity selenium.
Market Dynamics
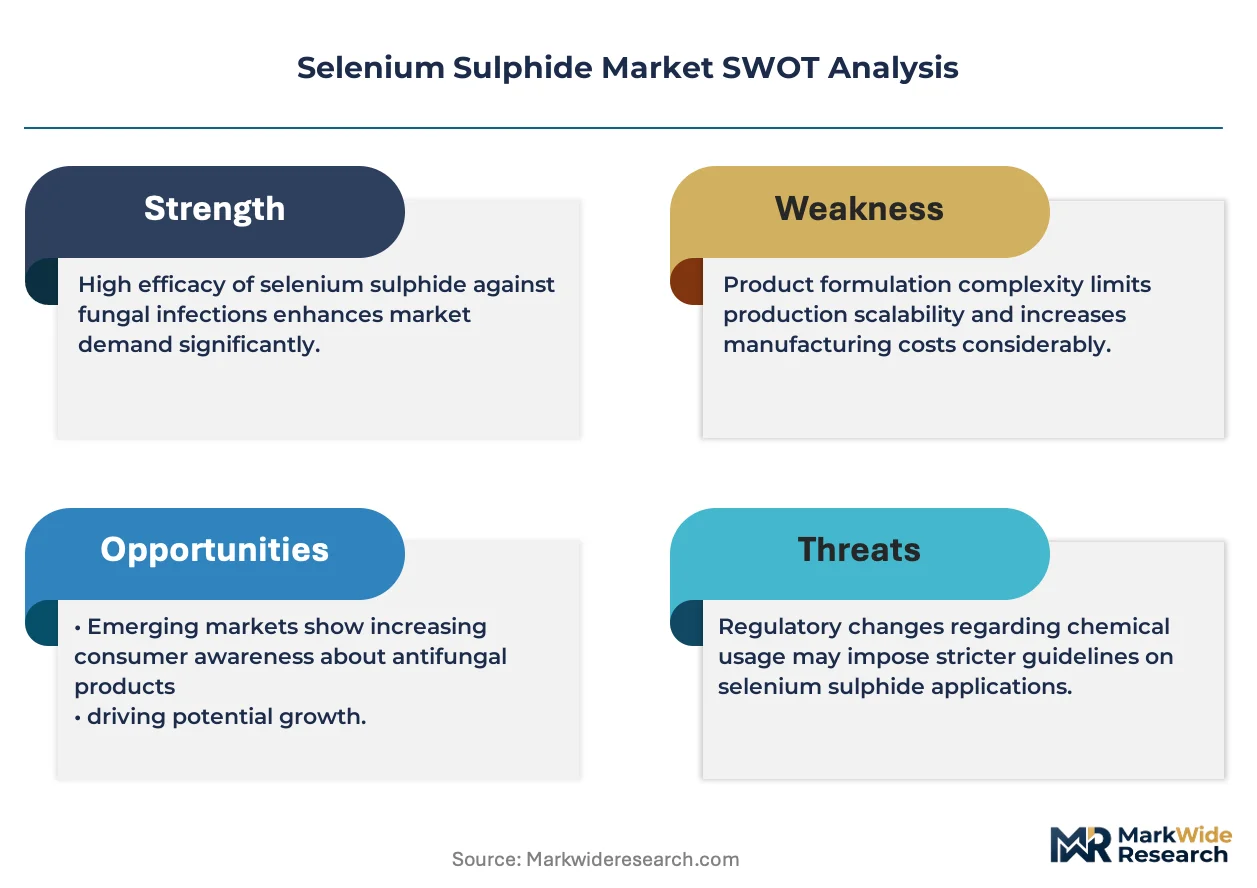
The selenium sulphide market is defined by the tension between its primary role in high-volume, price-sensitive personal care products and the increasing regulatory pressure for pharmaceutical-grade purity, driven by frameworks like the EU's REACH and FDA guidelines.
Growth Catalysts
- Expanding Consumer Markets:Rising disposable incomes and greater health awareness in populous nations like India and China are fueling demand for anti-dandruff shampoos and medicated skin treatments, the primary end-uses for selenium sulphide.
- Dermatological Applications:The compound's proven efficacy as a cytostatic and antifungal agent sustains its use in prescription and over-the-counter treatments for conditions like seborrheic dermatitis and tinea versicolor, creating a stable medical demand segment.
- Ingredient Purity Standards:Regulations from bodies like the European Chemicals Agency (ECHA) mandate stringent purity and safety data for cosmetic ingredients, solidifying the market position of suppliers who can consistently meet these high-grade specifications.
Market Restraints
- Raw Material Volatility:The production cost of selenium sulphide is directly tied to the fluctuating price and availability of high-purity selenium metal, creating margin pressure for manufacturers.
- Regulatory Divergence:Navigating the disparate requirements of regulatory bodies such as the US FDA, China's NMPA, and the European EMA for product registration and active ingredient claims complicates global product launches.
- Alternative Ingredients:Competition from other antifungal agents used in anti-dandruff formulations, including ketoconazole and zinc pyrithione, presents a constant substitution threat, particularly in mass-market product segments.
Strategic Opportunities
- Veterinary Formulations:There is an opportunity to develop and market specialized selenium sulphide-based treatments for fungal skin infections in companion animals and livestock, a relatively untapped application.
- Geographic Penetration:Markets in Southeast Asia, such as Indonesia and Vietnam, represent significant growth potential due to their large populations and nascent but growing demand for specialized personal care products.
- Novel Delivery Systems:Developing advanced formulations like micro-encapsulated suspensions or leave-on lotions can improve product stability, enhance user experience, and create differentiated, higher-value product offerings.
Industry Challenges
- Supply Chain Verification:A significant operational challenge involves ensuring a consistent and verifiable supply of high-purity raw selenium, free from contaminants that could affect final product safety and regulatory compliance.
- Compliance Timelines:The lengthy and costly process of securing and maintaining certifications from pharmaceutical and cosmetic regulators like the FDA and EMA creates a substantial operational burden and barrier to entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Selenium Sulphide Market |
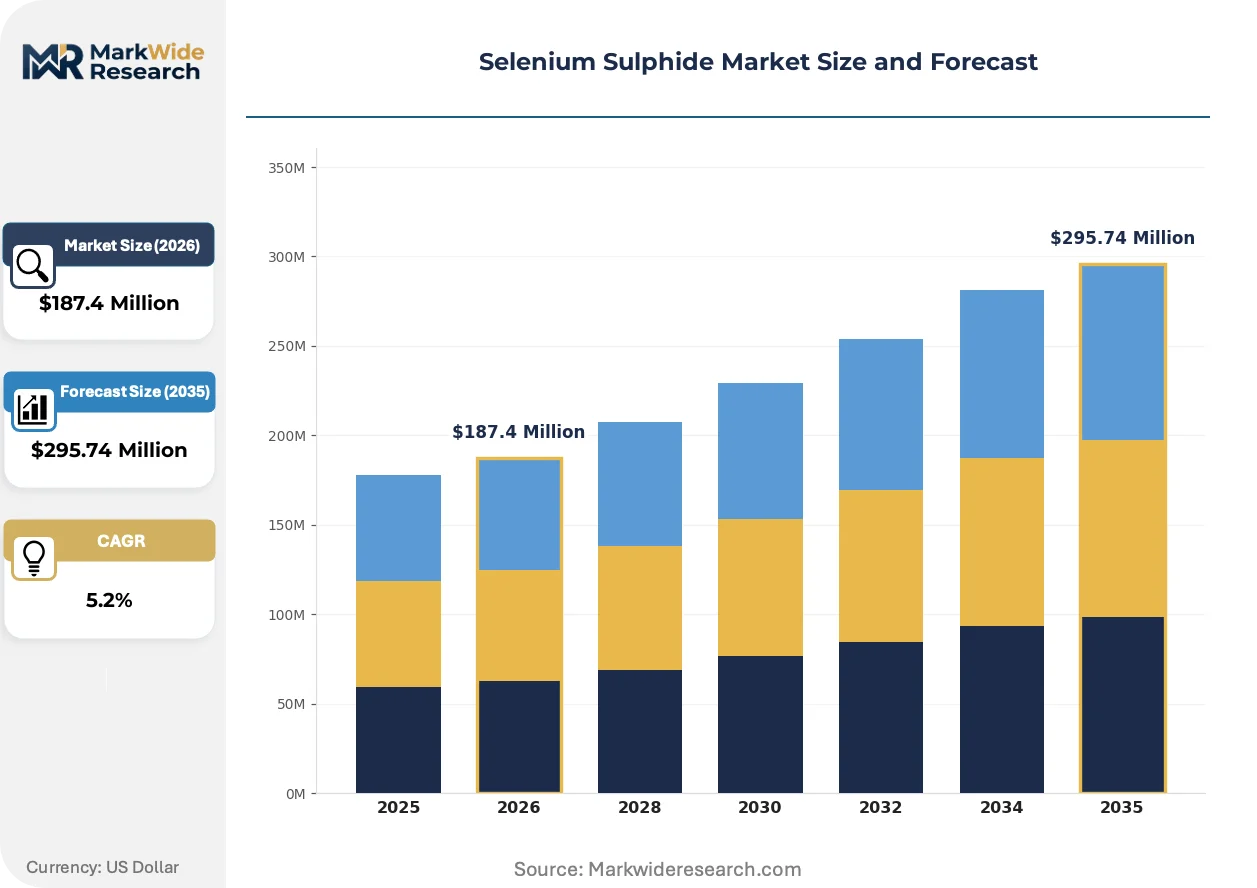
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $295.74 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Suspension, Emulsion, Gel, Liquid Form: Crystalline, Granular, Pelletized, Fine Particle Application: Anti-Dandruff, Antifungal Treatment, Pharmaceutical, Personal Care, Agricultural Fungicide End User: Pharmaceutical Manufacturers, Cosmetic Producers, Crop Protection Companies, Veterinary Suppliers |
| Companies Covered | Wockhardt Ltd, Omkar Specialty Chemicals Ltd, BASF SE, Alfa Aesar, Abcr GmbH, Hubei Xinjing New Material Co., Ltd., MilliporeSigma, GlaxoSmithKline plc, Gujarat Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Selenium Sulphide Market Strategic Shifts & Innovations
Product innovation in the selenium sulphide market centers on resolving the compound's clinical potency with consumer demand for more refined and aesthetically pleasing product formulations. This is driving a shift toward advanced material science and ingredient delivery systems.
Microencapsulation technology provides a method for enclosing selenium sulphide particles within a protective shell. Cosmetic formulators are adopting this technique to improve the stability and sensory profile of anti-dandruff products. This technology is decentralizing development away from strictly pharmaceutical labs toward consumer-focused R&D, enabling brands to create more elegant and marketable formulations.
European Union regulations, particularly REACH, continue to tighten standards for chemical substances used in consumer goods. The framework's emphasis on comprehensive safety data is forcing manufacturers to invest heavily in toxicological testing and supply chain transparency. Cosmetic-grade selenium sulphide is most affected, with suppliers needing to provide robust documentation to maintain market access in Europe.
A distinct behavioral shift shows consumers actively seeking personal care products with clinical or "dermatologist-recommended" credentials. This preference blurs the lines between retail cosmetic aisles and pharmacy channels, favoring brands that can substantiate their efficacy claims. This trend is particularly prominent in North American and Western European markets, amplified by social media and health-conscious consumerism.
Selenium Sulphide Market Segmentation
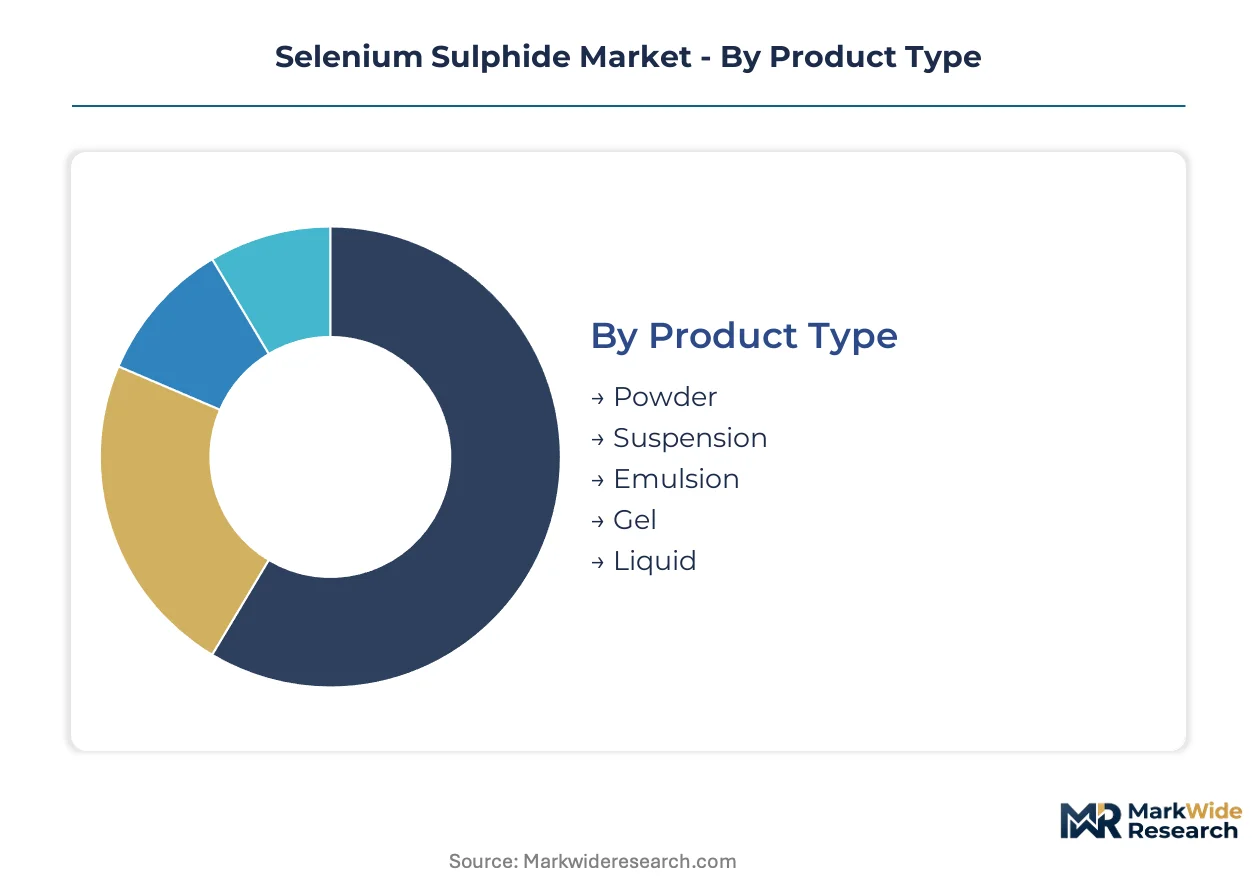
Understanding market segmentation illuminates the diverse product specifications, end-use applications, and customer requirements within the selenium sulphide market. This granular view helps identify key demand drivers and strategic opportunities for manufacturers and suppliers.
Product Type:
Product type segmentation highlights the diverse physical states in which selenium sulphide is delivered to end-users, reflecting varying formulation needs.
- Powder:This fine, solid form of selenium sulphide is extensively used as an active pharmaceutical ingredient. Demand is concentrated in pharmaceutical-grade material due to stringent purity standards for medicated treatments.
- Suspension:Comprising finely dispersed particles in a liquid medium, suspensions are common in topical formulations. This type is a primary driver for anti-dandruff personal care products, enabling easier application and stability.
- Emulsion:Emulsions are stable mixtures of two immiscible liquids, often used for enhanced skin delivery in cosmetic and dermatological products.
- Gel:Gel formulations provide a non-greasy, clear base for topical applications, favored for aesthetic appeal in personal care and some medicated treatments.
- Liquid:Liquid forms offer ease of incorporation into various solutions and formulations, particularly for large-scale industrial or agricultural applications.
Volume sits with Powder; growth tilts toward Suspension.
Form:
The form in which selenium sulphide is supplied often dictates handling and processing requirements for downstream manufacturers, influencing cost and purity.
- Crystalline:Selenium sulphide in crystalline form possesses an ordered atomic structure, essential for pharmaceutical applications requiring high purity and specific dissolution properties. This form is critical for active ingredient consistency.
- Fine Particle:Micro-encapsulated or nano-sized particles offer improved dispersion and stability within complex formulations. This form is gaining traction in advanced cosmetic formulations for enhanced efficacy and aesthetic appeal.
- Granular:Granular forms are easier to handle and less prone to dusting than powders, often preferred for bulk processing and specific industrial uses.
- Pelletized:Pelletized selenium sulphide provides a denser, more uniform product, reducing dust and improving flow characteristics in automated manufacturing processes.
Fine Particle forms are gaining traction for advanced formulations, while Crystalline remains essential for high-purity applications.
Application:
Application segmentation reveals the diverse therapeutic and cosmetic uses driving demand for selenium sulphide across industries.
- Anti-Dandruff:Application in anti-dandruff products remains the primary demand driver for selenium sulphide in personal care. This segment benefits from expanding consumer markets and rising health awareness in populous nations like India and China.
- Pharmaceutical:The pharmaceutical application segment involves its use as an active ingredient in prescription and over-the-counter medications. It treats conditions such as seborrheic dermatitis and tinea versicolor, requiring stringent purity and regulatory compliance.
- Antifungal Treatment:This broad category includes medical and non-medical uses for combating fungal infections on skin and scalp, often overlapping with anti-dandruff and pharmaceutical uses.
- Personal Care:Beyond anti-dandruff, personal care applications include other dermatological and cosmetic formulations aimed at scalp health and skin conditions.
- Agricultural Fungicide:Selenium sulphide finds limited but specialized use as a fungicide in agricultural settings, protecting crops from specific fungal pathogens.
Anti-Dandruff remains the dominant application, with Pharmaceutical uses providing consistent, high-value demand.
End User:
End-user categories reflect distinct procurement behaviors and regulatory compliance needs within the selenium sulphide market.
- Pharmaceutical Manufacturers:These entities produce medicated treatments and require selenium sulphide that meets rigorous quality and purity standards set by health authorities like the FDA and EMA. Their procurement is driven by regulatory compliance and clinical efficacy.
- Cosmetic Producers:Firms formulating personal care products, particularly anti-dandruff shampoos, represent a significant end-user segment. Their procurement is influenced by consumer trends, ingredient safety regulations, and cost-effectiveness for mass-market products.
- Crop Protection Companies:These companies utilize selenium sulphide in formulations designed to protect agricultural crops from fungal diseases, a niche but specialized application.
- Veterinary Suppliers:Veterinary suppliers incorporate selenium sulphide into treatments for fungal skin infections in animals, presenting an opportunity for specialized product development.
Pharmaceutical Manufacturers and Cosmetic Producers represent the largest procurement volumes, while Veterinary Suppliers offer a strategic growth opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in the selenium sulphide market is particularly evident in populous Asian economies, where expanding consumer healthcare and personal care sectors drive significant volume. This growth is paralleled by sustained demand from established markets in North America and Europe, driven by stringent pharmaceutical standards. Multinational cosmetic and pharmaceutical firms are increasingly influencing purchasing patterns, seeking high-purity materials.
India
India's expanding consumer healthcare market and rising disposable incomes fuel demand for anti-dandruff products and medicated skin treatments. The Central Drugs Standard Control Organization (CDSCO) mandates strict quality controls for active pharmaceutical ingredients. Mumbai and Hyderabad serve as key pharmaceutical manufacturing hubs, with significant production for both domestic consumption and export.
China
China represents a substantial growth market, with its large population driving demand for personal care products and dermatological solutions. The National Medical Products Administration (NMPA) sets rigorous standards for pharmaceutical ingredients, influencing market access for suppliers. The Yangtze River Delta region, including Shanghai, is a major center for chemical and pharmaceutical production, attracting significant investment.
United States
The United States market sustains consistent demand for selenium sulphide in both over-the-counter anti-dandruff formulations and prescription dermatological treatments. The US Food and Drug Administration (FDA) governs the use and purity of active ingredients in cosmetic and pharmaceutical products. The Northeast Corridor, encompassing states like New Jersey and Pennsylvania, hosts a concentrated pharmaceutical research and manufacturing base.
Germany
Germany contributes significantly to European demand, particularly for pharmaceutical-grade selenium sulphide used in advanced dermatological applications. Compliance with European Medicines Agency (EMA) guidelines and national regulations ensures high purity standards across the supply chain. The Rhine-Main region, centered around Frankfurt, is a prominent cluster for the chemical and pharmaceutical industries, fostering innovation.
United Kingdom
The United Kingdom's robust consumer healthcare sector and established pharmaceutical industry maintain steady demand for selenium sulphide. The Medicines and Healthcare products Regulatory Agency (MHRA) enforces strict quality and safety standards for medicinal products. London and the Southeast region are focal points for consumer goods companies and pharmaceutical research and development, driving product innovation.
Selenium Sulphide Market Key Industry Players
European chemical producers anchor one tier of the selenium sulphide market; specialized Asian manufacturers hold another. The market structure exhibits a tiered consolidation, with a few large multinational chemical and pharmaceutical firms dominating the high-purity segments. Key strategic archetypes include large-scale chemical manufacturers, specialized pharmaceutical ingredient suppliers, and regional cosmetic formulators. These players primarily engage in capacity expansion and portfolio diversification to address evolving regulatory requirements.
Among global chemical and pharmaceutical entities, BASF SE exemplifies large-scale production and extensive distribution capabilities. GlaxoSmithKline plc represents the multinational consumer healthcare firms integrating selenium sulphide into specialized dermatological products. Omkar Specialty Chemicals Ltd. sits within the specialized chemical producers tier, serving diverse industrial and pharmaceutical clients with specific material requirements.
| Leading Market Players |
|---|
| Wockhardt Ltd |
| Omkar Specialty Chemicals Ltd |
| BASF SE |
| Alfa Aesar |
| Abcr GmbH |
| Hubei Xinjing New Material Co., Ltd. |
| MilliporeSigma |
| GlaxoSmithKline plc |
| Gujarat Organics |
Cost & Logistics Intelligence
Specialized chemical engineering expertise, concentrated in regions like the Yangtze River Delta, influences global pricing tiers. Labor-cost differentials stemming from these focused workforces impact the cost structure for both pharmaceutical and cosmetic-grade selenium sulphide.
Pricing Analysis
The selenium sulphide market exhibits a clear volume-versus-margin split, with high-volume personal care products facing intense price competition. Pricing stratifies across premium, standard, and economy tiers, driven by stringent purity standards for pharmaceutical-grade material and the volume scale for cosmetic producers. Pricing softness reflects competition from alternative antifungal agents in mass-market segments. Cosmetic producers are highly price-sensitive, while pharmaceutical manufacturers prioritize regulatory compliance and consistent quality.
Supply Chain Analysis
Selenium sulphide production relies heavily on the availability and consistent quality of high-purity selenium metal. Geographic supply concentrates among specialized Asian manufacturers and European chemical producers like BASF SE, with raw selenium sourcing often global. Raw material volatility presents a structural risk, creating margin pressure for manufacturers. Distribution runs through direct channels to large multinational cosmetic and pharmaceutical firms, alongside regional distributors for smaller entities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The selenium sulphide market is undergoing a consolidation play, driven by stringent regulatory frameworks like the EU's REACH and FDA guidelines. These rigorous demands for high purity and safety data are forcing weaker, non-compliant players out of the market.
For Market Incumbents: Hedge against raw material volatility by securing long-term supply agreements for high-purity selenium metal. Incumbents like BASF SE must invest in advanced material science, such as microencapsulation technology, to differentiate products and counter alternative ingredients. Reinforce market position through continuous compliance with FDA and EMA purity standards. Expanding capacity for pharmaceutical-grade material in established regions like Germany ensures consistent supply for high-value applications.
For New Entrants and Emerging Players: Begin with specialized applications, such as veterinary formulations for companion animals and livestock, which represent an untapped market segment. Target geographic expansion into Southeast Asian markets like Indonesia and Vietnam, where demand for specialized personal care products is growing. Focus on developing novel delivery systems, including micro-encapsulated suspensions or leave-on lotions, to offer differentiated and higher-value product offerings. This strategy avoids direct competition with established mass-market anti-dandruff products.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking stable, long-term growth driven by persistent dermatological needs. Target specialized pharmaceutical ingredient suppliers, such as Omkar Specialty Chemicals Ltd., or firms demonstrating robust regulatory compliance and advanced formulation capabilities. Prioritize entities with verifiable high-purity selenium supply chains. A critical signal to watch is successful navigation of evolving active ingredient safety regulations across multiple jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increasing production of pharmaceutical-grade selenium sulphide meets rising demand from Wockhardt Ltd. |
| Regulatory Approval Pathway | Securing FDA and EMA certifications for novel formulations ensures market access and product credibility. |
| Product Launch | Introducing micro-encapsulated suspensions enhances user experience for GlaxoSmithKline plc's consumer products. |
| Geographic Expansion | Penetrating nascent markets in Southeast Asia diversifies revenue streams for cosmetic producers. |
| Backward Integration | Gaining upstream control over high-purity selenium metal reduces raw material volatility for BASF SE. |
Research Approach
Independent corroboration across chemical industry reports, regulatory body filings, and trade association publications underwrites the qualitative findings. Primary interviews with chemical plant managers, pharmaceutical R&D executives, and cosmetic formulators provided granular insights. Secondary data sources included FDA filings, EMA submissions, and NMPA standards, validating market dynamics. A robust methodology involved bottom-up data collection from market participants and top-down validation against macroeconomic indicators.
Forecasts were anchored to a comprehensive historical reference period, establishing baseline market performance across the analysis window. Quantitative modeling integrated identified market drivers, restraints, and strategic opportunities. Segmentation dimensions included product type, form, application, end-user, and regional regulatory cluster. Compound Annual Growth Rates were derived from historical trends and projected market shifts, incorporating purity requirements for active ingredients and raw selenium metal price forecasts.
Underlying measurement precision varies by segment; pharmaceutical-grade material carries tighter precision than cosmetic-grade due to rigorous regulatory oversight. Forecasts reflect assumptions regarding raw material price stability and evolving regulatory frameworks. A small set of named triggers, including new alternative ingredients or stricter chemical safety mandates, warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Global Detergents Market
Surfactants
Global Sodium Cocoyl Glutamate Market
Surfactants
Naphthalene Sulfonate Market
Surfactants
Emulsifying Wax Market
Surfactants
Sugar-Based Surfactants Market
Surfactants
Defoamers Market
Surfactants
Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market
Surfactants
Calcium Stearoyl-2 Lactylate Market
Surfactants
Detergent Chemicals Market
Surfactants
Sulfosuccinate Market
Surfactants
Global Biosurfactant Market
Surfactants
Green Surfactants Market
Surfactants
Dioctyl Sulfosuccinates Components Market
Surfactants
Global Surfactants Market
Surfactants
Cetyl Chloride Market
Surfactants
Alkyl Polyglycoside (APG) Market