
 Naphthalene Sulfonate Market | 2026-2036
Naphthalene Sulfonate Market Size, Share, and Industry Trends Forecast 2026-2036
Naphthalene Sulfonate Market Outlook
Project finance for specialty chemical capacity is reconfiguring competitive entry barriers across the naphthalene sulfonate value chain. BASF SE leverages backward integration into naphthalene feedstock to sustain margin stability in European supply. Sika AG anchors its position through geographic dominance in construction-grade admixtures across multiple continents. Himadri Speciality Chemical Ltd competes on manufacturing scale from its eastern India base.
Naphthalene sulfonate denotes a class of anionic surfactants synthesized via sulfonation of naphthalene followed by formaldehyde condensation, typically yielding molecular weights between 500 and 5,000 daltons with sulfonate degrees of 1.0 to 3.5 per naphthalene unit. These compounds function primarily as dispersants and water reducers in cementitious systems, textile dyeing baths, and agrochemical formulations. Powder formulations command the largest volume share due to handling economics in concrete batching operations, while liquid variants represent the fastest-expanding category as ready-mix producers automate dosing systems. Concrete admixtures absorb the dominant share of value across end use industries, with dyes and coatings applications offering higher per-kilogram margins but smaller absolute volumes.
REACH registration requirements in Europe, EPA chemical data reporting in the United States, and BIS certification mandates in India collectively elevate compliance costs for new market entrants while reinforcing incumbent positions. The EU Green Deal's embodied carbon thresholds for construction materials are beginning to redirect specification decisions toward lower-carbon dispersant alternatives. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where product reformulation investments will yield preferential market access.
Market Dynamics
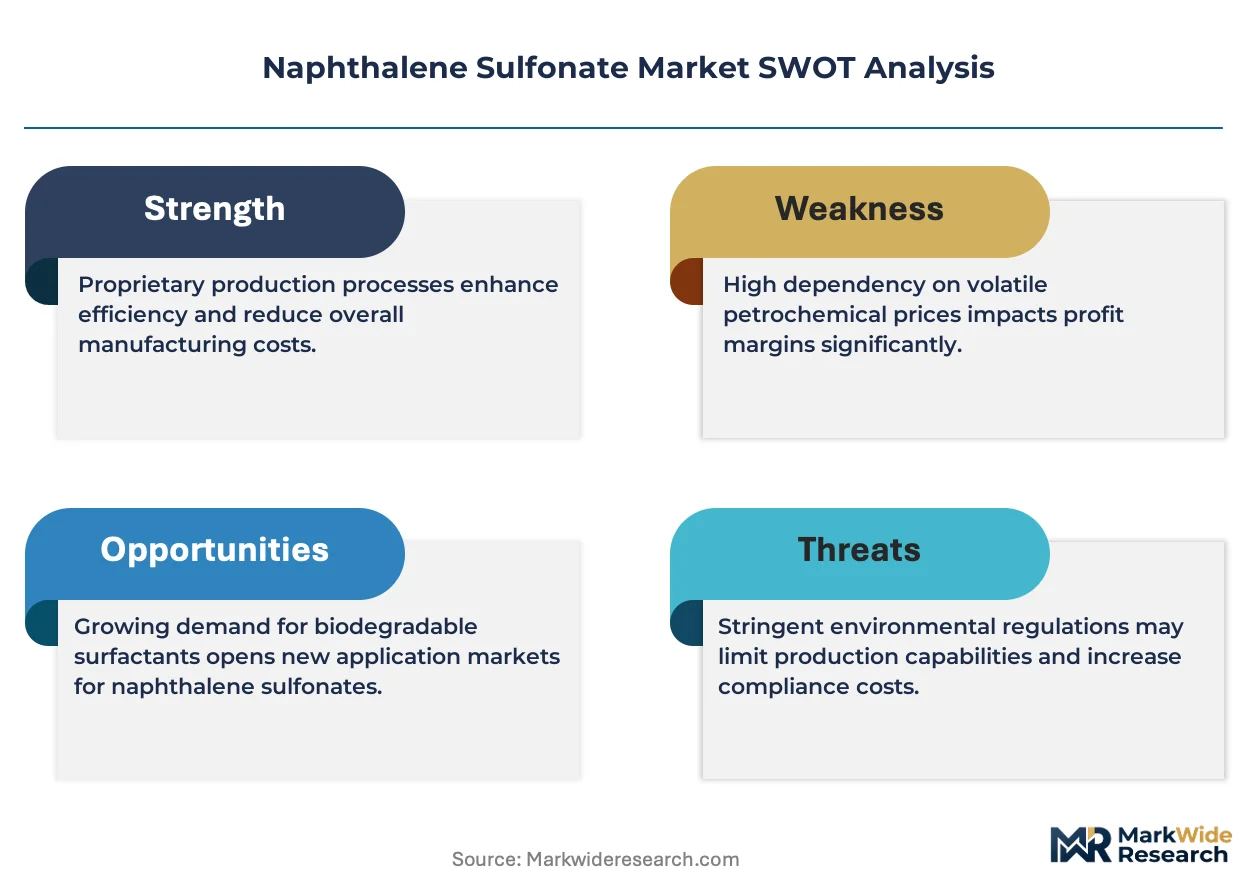
Polycarboxylate ether (PCE) superplasticizers are compressing specification space for naphthalene sulfonate formaldehyde (NSF) in high-performance concrete segments. This substitution pressure is forcing NSF producers to defend volume in mid-tier ready-mix and precast applications where cost sensitivity persists.
Growth Catalysts
- India's western industrial corridor:Infrastructure buildout across Maharashtra and Gujarat is absorbing dispersant volumes for cement grinding aids and concrete admixtures. State-level urban development mandates are accelerating batching plant capacity additions.
- REACH registration consolidation:ECHA's data requirements and substance evaluation protocols have eliminated marginal European suppliers. Surviving registrants capture specification-driven demand from infrastructure contractors facing embodied carbon disclosure rules.
- Agrochemical suspension concentrates:Naphthalene sulfonate dispersants enable stable aqueous suspensions of active ingredients. Formulation chemists in crop protection are specifying these anionic surfactants for compatibility with biological actives.
Market Restraints
- Naphthalene feedstock concentration:Coal tar distillation capacity clusters in China's Shanxi and Shandong provinces. Supply disruptions at coking complexes transmit directly to sulfonation unit economics.
- Polycarboxylate ether displacement:PCE superplasticizers deliver superior water reduction at low dosages. High-rise and infrastructure engineers in premium segments are defaulting to PCE for slump retention beyond two hours.
- EU Green Deal embodied carbon thresholds:Construction material procurement guidelines in the Netherlands and Denmark are beginning to penalize high-carbon admixture categories. NSF carries upstream emissions from coal tar derivation.
Strategic Opportunities
- Indonesia's precast concrete sector:Jakarta-Bandung high-speed rail and new capital city construction are creating admixture demand. Local blending capacity remains underdeveloped relative to project pipelines.
- Textile dyeing bath reformulation:Naphthalene sulfonate dispersants stabilize vat and disperse dyes at high temperatures. Bangladeshi and Vietnamese fabric processors are seeking alternatives to formaldehyde-heavy legacy systems.
- India PLI scheme for specialty chemicals:Production-linked incentives for downstream chemical manufacturing are reducing capital recovery periods. Greenfield sulfonation units in Odisha and Andhra Pradesh qualify for fiscal support.
Industry Challenges
- Sulfonation process control expertise:Formaldehyde condensation chemistry requires precise temperature and molar ratio management. Qualified chemical engineers with continuous sulfonation experience command premium compensation.
- BIS certification timelines:Bureau of Indian Standards testing protocols for concrete admixtures extend 12-18 months. Product approval delays obstruct market entry ahead of construction seasonality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naphthalene Sulfonate Market |
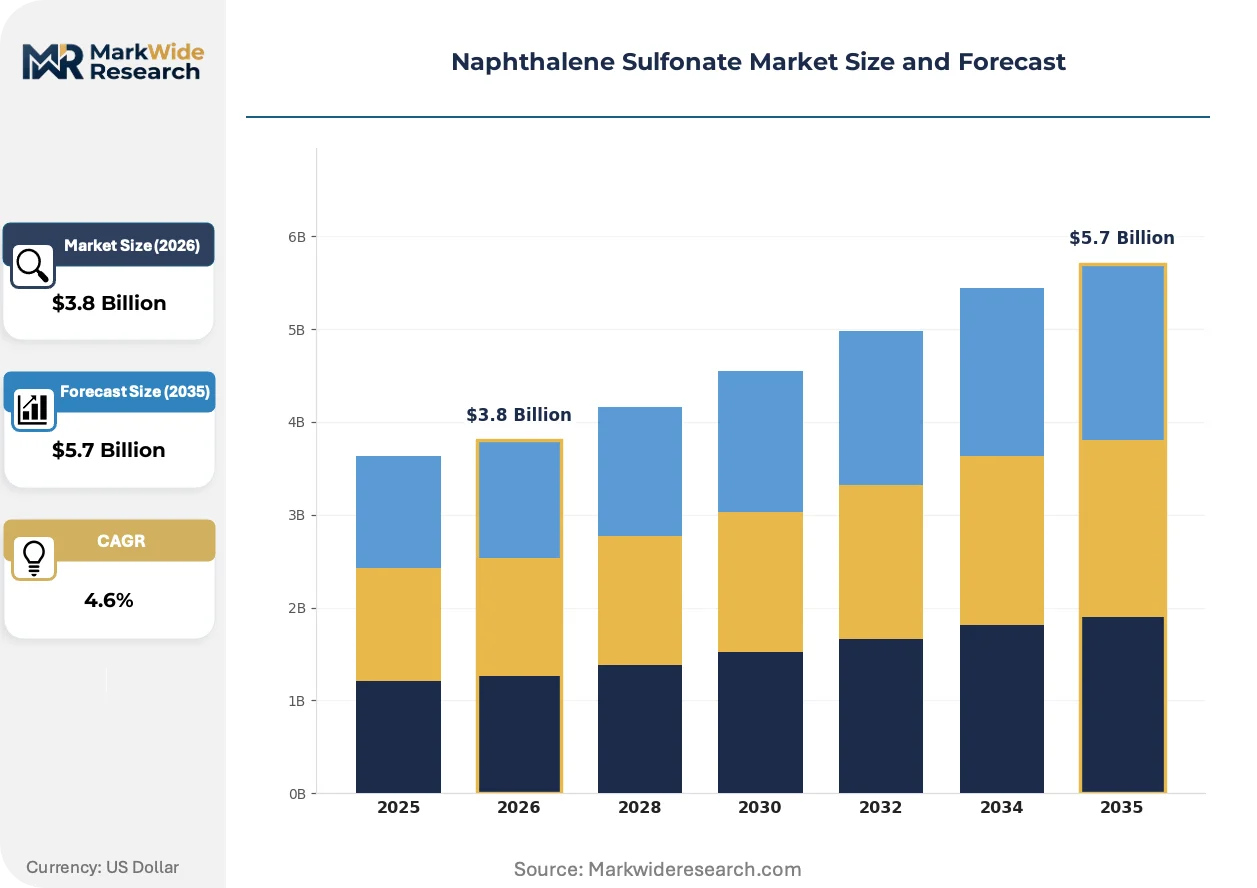
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Paste End Use Industry: Construction, Textiles, Agriculture, Detergents Application: Concrete Admixtures, Dyes, Coatings, Agrochemicals Form: Solid, Aqueous, Slurry, Emulsion |
| Companies Covered | Kao Corporation, GCP Applied Technologies Inc, BASF SE, Sika AG, Mitsui Chemicals Inc, Akzo Nobel N.V., Himadri Speciality Chemical Ltd, Nouryon, Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naphthalene Sulfonate Market Strategic Shifts
Automated dosing systems and real-time rheology monitoring are transforming how concrete producers specify and consume dispersant chemistries. These instrumentation shifts are compressing the acceptable performance variance between admixture batches.
Sensor-integrated batching equipment is digitizing quality assurance workflows across ready-mix operations. Sika and BASF specification engineers are embedding conductivity and viscosity probes directly into truck mixer discharge lines. This instrumentation is digitizing the feedback loop between admixture dosage and slump test results, reducing over-dosage incidents and compressing reliance on manual sampling protocols.
ECHA's revised restriction roadmap for formaldehyde releasers is tightening exposure limit assumptions in industrial chemical categories. The draft opinion targets condensation products including naphthalene sulfonate formaldehyde resins. German and French construction chemical distributors are requesting reformulated low-emission variants to preempt specification exclusion from public procurement tenders.
Ready-mix buyers are consolidating annual admixture contracts around performance-guaranteed service models. Large contractors in China's Pearl River Delta are shifting from per-tonne procurement to cubic-meter-delivered concrete pricing that bundles admixture costs. This bundling is compressing standalone dispersant supplier margins while favoring vertically integrated concrete producers with captive blending capabilities.
Naphthalene Sulfonate Market Segmentation
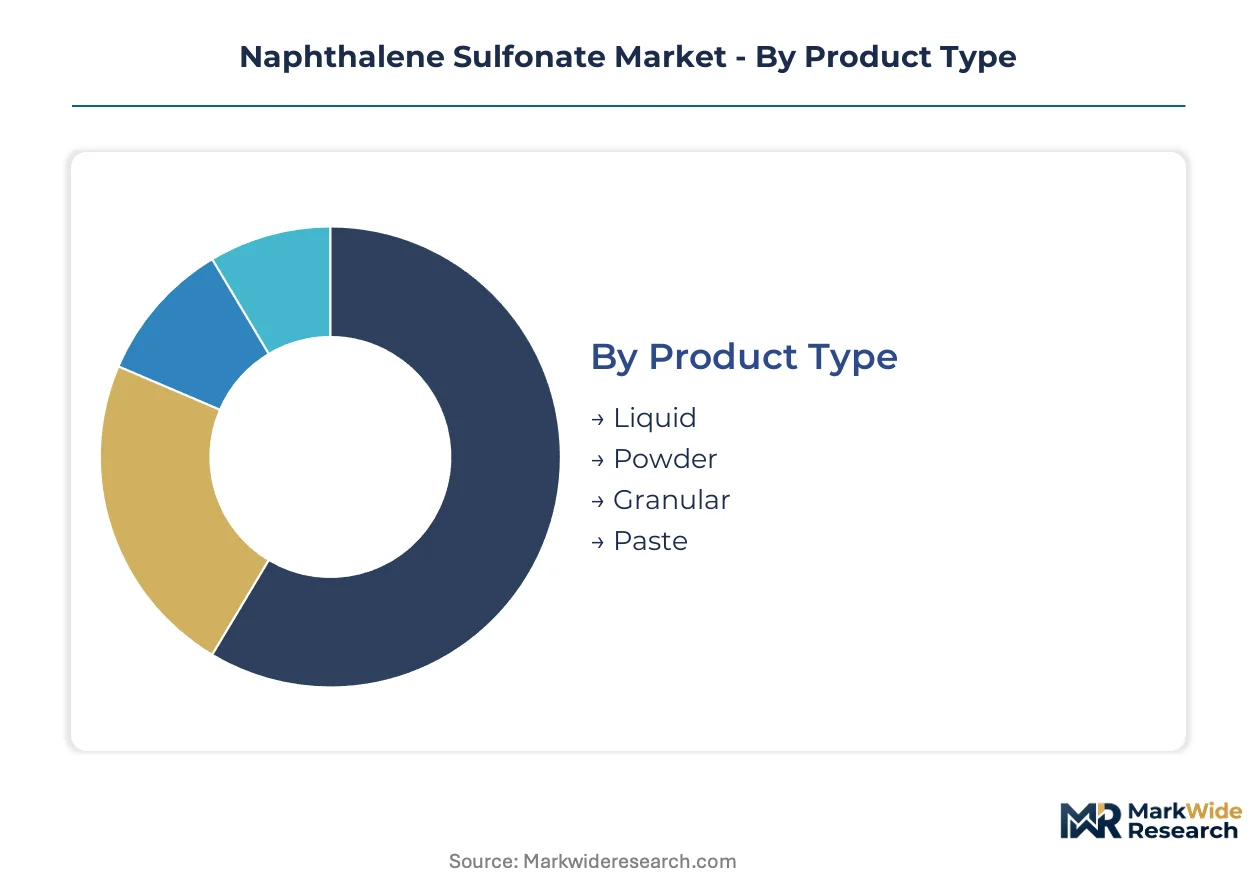
Segmentation in the naphthalene sulfonate market reveals how formulation chemistry and end-use performance requirements drive purchasing decisions. Product form, application method, and industry-specific compliance standards create distinct commercial channels with varying margin profiles.
Product Type:
Use-case spectrum spans automated liquid dosing systems through manual powder handling operations.
- Liquid:Aqueous solutions with 30-45% active content enable precise pump-controlled dosing in ready-mix batching plants. Demand concentrates in China's Pearl River Delta where automated concrete production lines are displacing manual admixture addition. Sika and BASF specification engineers embed conductivity probes directly into truck mixer discharge lines to enable real-time rheology feedback.
- Powder:Spray-dried formulations with 90-95% active content dominate volume economics in emerging market construction. India's western industrial corridor absorbs powder volumes for cement grinding aids where bagged handling suits smaller batching operations. State-level urban development mandates in Maharashtra accelerate batching plant capacity additions.
- Granular:Dust-free agglomerated particles reduce respiratory exposure during textile dyeing bath preparation.
- Paste:High-viscosity concentrates serve niche coating applications requiring extended shelf stability.
The dominant share belongs to Powder, while Liquid is closing the gap fastest as ready-mix automation penetrates developing markets.
End Use Industry:
Cost tier differentiation separates premium infrastructure specifications from commodity textile processing.
- Construction:Concrete admixtures and cement grinding aids absorb the largest absolute volume. REACH registration consolidation has eliminated marginal European suppliers, leaving BASF and surviving registrants to capture specification-driven demand from contractors facing embodied carbon disclosure rules. The EU Green Deal's thresholds are beginning to penalize high-carbon admixture categories.
- Textiles:Vat and disperse dye stabilization at high temperatures commands higher per-kilogram margins. Bangladeshi and Vietnamese fabric processors seek alternatives to formaldehyde-heavy legacy systems, creating reformulation opportunities for naphthalene sulfonate dispersants.
- Agriculture:Suspension concentrate formulations for crop protection rely on anionic surfactant compatibility with biological actives.
- Detergents:Industrial cleaning formulations represent a smaller outlet with price-sensitive procurement.
Construction retains volume leadership, though Textiles offers superior margin density per ton.
Application:
Application maturity varies from established concrete chemistry to emerging agrochemical specifications.
- Concrete Admixtures:Water reducers and dispersants in cementitious systems constitute the foundational demand base. PCE superplasticizers are compressing specification space for NSF in high-performance segments, forcing producers to defend volume in mid-tier ready-mix where cost sensitivity persists.
- Dyes:Textile colorant stabilization requires precise sulfonation degree control for thermal stability. ECHA's revised restriction roadmap for formaldehyde releasers is tightening exposure limit assumptions, prompting German and French distributors to request reformulated low-emission variants.
- Coatings:Pigment dispersants in architectural and industrial finishes.
- Agrochemicals:Active ingredient suspension stability in aqueous concentrates represents the steepest expansion trajectory as biological crop protection formulations proliferate.
Concrete Admixtures anchor the revenue base, while Agrochemicals climbs fastest on biological formulation trends.
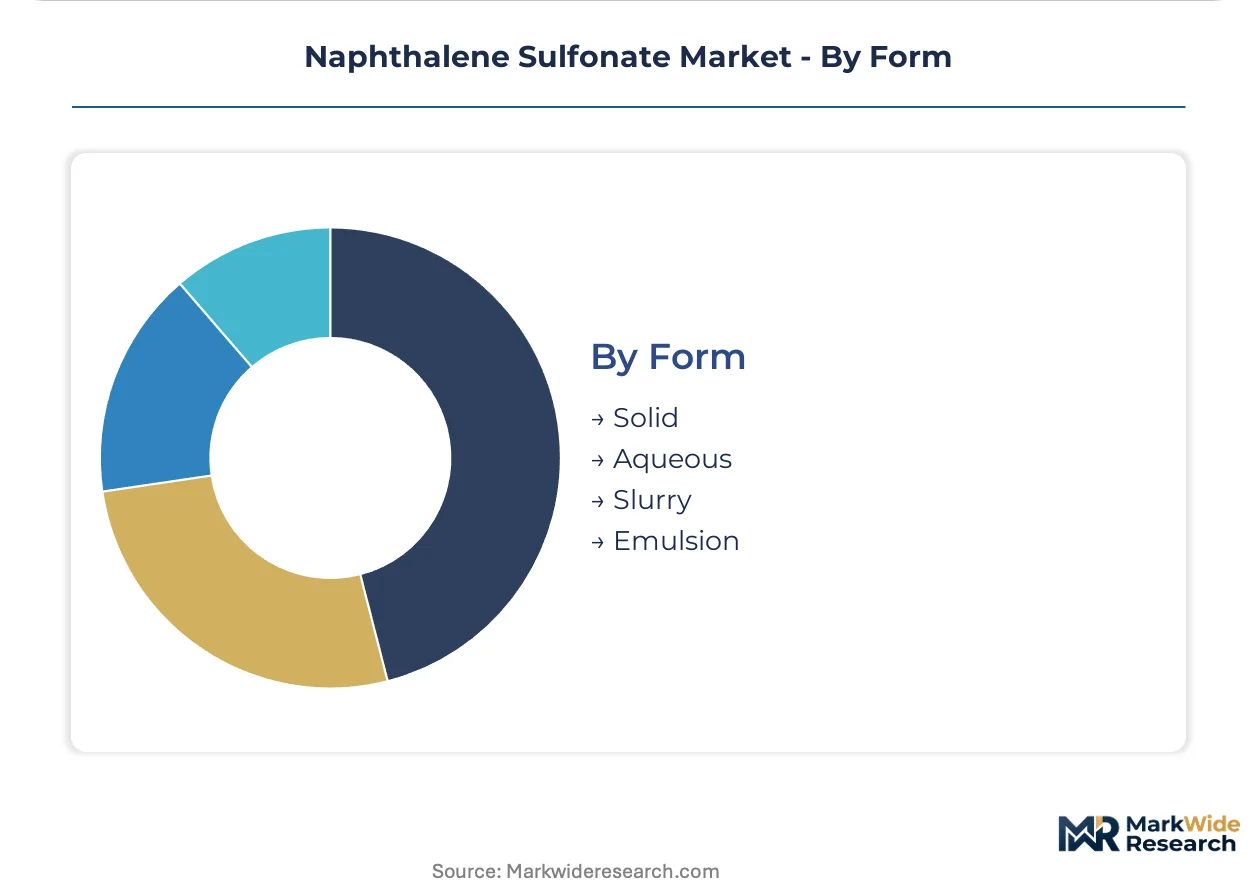
Form:
Supply concentration in solid processing reflects coal tar derivative handling economics.
- Solid:Spray-dried and granular forms dominate shipping efficiency for intercontinental supply chains. Coal tar distillation capacity clusters in China's Shanxi and Shandong provinces, transmitting supply disruptions directly to sulfonation unit economics.
- Aqueous:Ready-to-use liquid solutions eliminate on-site dilution steps for automated dosing systems.
- Slurry:Intermediate processing state for captive consumption in integrated manufacturing.
- Emulsion:Specialized delivery system for hydrophobic active compatibility in coating formulations.
Solid forms command the dominant share, though Aqueous is gaining share fastest on automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers wield pricing power through coal tar derivative concentration in Shanxi and Shandong, while European registrants extract premiums from REACH-compliant specification markets. This asymmetry shapes procurement patterns across construction chemical supply chains.
China
Coastal manufacturing provinces absorb dispersant volumes for automated concrete batching systems. MEE enforcement of dual carbon goals is tightening emissions standards at coking complexes. The Pearl River Delta concentrates ready-mix automation adoption where Sika and BASF specification engineers embed real-time rheology probes.
India
Maharashtra and Gujarat infrastructure buildout drives cement grinding aid procurement for batching plant expansions. BIS certification mandates for concrete admixtures impose 12-18 month approval timelines. The western industrial corridor concentrates state-level urban development mandates accelerating dispersant consumption.
Germany
Construction chemical distributors request low-emission naphthalene sulfonate variants to preempt EU Green Deal procurement exclusions. ECHA's revised restriction roadmap for formaldehyde releasers targets condensation product exposure limits. The Rhine-Ruhr industrial belt anchors BASF's backward integration into naphthalene feedstock for margin stability.
United States
EPA chemical data reporting elevates compliance costs for new sulfonation unit entrants. Infrastructure contractors face embodied carbon disclosure pressures redirecting specification decisions. Texas and California construction corridors concentrate demand for mid-tier ready-mix applications where cost sensitivity persists against PCE displacement.
Indonesia
Jakarta-Bandung high-speed rail and new capital city construction create admixture demand outpacing local blending capacity. The national infrastructure procurement framework favors imported construction chemicals pending domestic sulfonation scale-up. Java-based precast concrete operations rely on dispersed supply chains for dispersant sourcing.
Naphthalene Sulfonate Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with feedstock and formulation chemistry advantages. The vendor base stratifies between multinational construction chemical platforms and regional sulfonation operators. Three archetypes dominate: coal tar-integrated feedstock controllers, specification-engineered admixture platforms, and regional scale manufacturers. Competitive moves concentrate on backward integration into naphthalene supply and geographic expansion through specification engineering partnerships.
Among construction chemical platforms, BASF SE and Sika AG exemplify the integrated system tier, combining admixture formulation with direct contractor specification relationships. Himadri Speciality Chemical Ltd occupies a position within the regional scale archetype, leveraging eastern India manufacturing positioning. These three anchors illustrate how competitive positioning splits between feedstock-integrated multinationals and geography-focused volume producers.
| Leading Market Players |
|---|
| Kao Corporation |
| GCP Applied Technologies Inc |
| BASF SE |
| Sika AG |
| Mitsui Chemicals Inc |
| Akzo Nobel N.V. |
| Himadri Speciality Chemical Ltd |
| Nouryon |
| Solvay S.A. |
| Others |
Value Chain & Pricing Dynamics
Coal tar distillation concentration in China's Shanxi and Shandong provinces creates single-source dependency that widens pricing tier spreads between REACH-compliant European grades and commodity Asian supply while compressing margin buffers for non-integrated blenders. This feedstock chokepoint forces specification engineers to tier procurement strategies around carbon disclosure compliance and automation-readiness rather than unit chemistry alone.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the naphthalene sulfonate market. Price differentiation rests on REACH registration status and automated dosing compatibility, with certified low-emission variants commanding substantial premiums from Dutch and Danish contractors facing embodied carbon thresholds. Pricing pressure stems from polycarboxylate ether displacement in high-performance concrete segments, eroding margins in premium tiers. Ready-mix producers in emerging markets exhibit highest price sensitivity, while specification-engineered infrastructure contractors in Germany and France demonstrate lowest sensitivity due to bundled service contract structures.
Supply Chain Analysis
Extended payment terms from construction chemical distributors now stretch 90-120 days, straining working capital for regional sulfonation operators without captive feedstock. Geographic supply concentration centers on China, India, and Germany, with coal tar derivatives, formaldehyde, and sulfonation catalysts as critical inputs. Single-source vulnerability at Chinese coking complexes transmits directly to European admixture blenders when MEE enforcement triggers production pauses. Distribution runs through construction chemical platforms with direct contractor specification relationships rather than commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-guaranteed service models represent the fastest-expanding revenue layer in naphthalene sulfonate markets, outpacing standalone dispersant sales as ready-mix producers shift toward cubic-meter-delivered concrete pricing that bundles admixture costs with technical support.
For Market Incumbents: Harden specification-lock through embedded conductivity and viscosity probes in automated batching systems, creating switching costs that polycarboxylate ether suppliers cannot easily replicate. Deepen backward integration into naphthalene feedstock to insulate margin stability when coal tar distillation disruptions transmit through Shanxi and Shandong supply nodes. Prioritize low-emission variant development ahead of ECHA's formaldehyde restriction roadmap to preempt procurement exclusion from EU public tenders. For New Entrants and Emerging Players: Mid-tier ready-mix operations in Indonesia's precast concrete sector represent the most penetrable entry point, where Jakarta-Bandung high-speed rail and new capital city construction outpace local blending capacity. Odisha and Andhra Pradesh sulfonation units qualifying under India's PLI scheme offer capital-efficient manufacturing scale for export positioning. Lead with automated dosing system compatibility and 90-day technical support trials to differentiate from commodity powder suppliers. For Investors and Strategic Acquirers: REACH registration consolidation reshapes the acquisition landscape by eliminating marginal European suppliers and concentrating specification-driven demand among surviving registrants with embodied carbon disclosure capabilities. Target regional scale manufacturers with eastern India or coastal China positioning that could anchor backward integration plays. Monitor ECHA substance evaluation protocols and EU Green Deal procurement threshold adjustments as signals for premium tier repricing windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphthalene Feedstock | BASF's Rhine-Ruhr positioning demonstrates margin insulation against coal tar volatility. |
| Low-Emission Variant Development | German and French distributors now specify reformulated grades to preempt tender exclusions. |
| Automated Dosing System Partnerships | Sika's probe-embedded discharge lines create specification lock in China's Pearl River Delta. |
| PLI-Qualified Capacity Expansion | Odisha and Andhra Pradesh greenfield units reduce capital recovery periods for specialty sulfonation. |
| Performance-Guaranteed Service Contracts | Bundled cubic-meter pricing compresses standalone supplier margins while favoring integrated platforms. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the naphthalene sulfonate value chain, including ready-mix plant managers, construction chemical procurement leads, textile dyeing bath formulators, agrochemical R&D directors, and distribution channel partners in Europe and Asia. Secondary validation drew from ECHA registration databases, BIS certification records, SEC filings of listed construction chemical platforms, customs trade data, and EU Green Deal procurement guidelines. Bottom-up volume modeling triangulated against top-down value estimates from identified market participants.
Calibration against historical capacity utilization rates and construction chemical spending patterns shaped the analytical framework across the projection horizon. Segmentation dimensions included product form, end-use industry, application method, and regional regulatory cluster. CAGRs were derived from slope analysis of identified demand drivers and substitution elasticity parameters. Key inputs comprised polycarboxylate ether penetration rates in premium concrete segments and PLI scheme uptake for Indian specialty chemical manufacturing.
Practitioners should monitor ECHA restriction roadmap developments, MEE enforcement intensity at Chinese coking complexes, and BIS certification timeline fluctuations for early signals of forecast deviation. Macroeconomic construction spending cycles, regulatory divergence between jurisdictions, or technological breakthroughs in biological crop protection formulations would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Sodium Methyl Cocoyl Taurate Market
Surfactants
Chlorooctane Market
Surfactants
Surfactant Cleansers and Adjuvants Market
Surfactants
North America Surfactants Market
Surfactants
Microemulsions Market
Surfactants
Bio-Based Surfactants Market
Surfactants
Soap Salts Market
Surfactants
Defoamers Market
Surfactants
Cetanol Market
Surfactants
Amino Silicone Oil Market
Surfactants
Global Sodium Cocoyl Glutamate Market
Surfactants
Sodium Lauroyl Sarcosinate Market
Surfactants
Emulsion Stabilizers Market
Surfactants
Oil-in-Water Anionic Emulsifier Market
Surfactants
Global Detergent Polymers Market
Surfactants
Lauramide DEA Market