
 United Kingdom Lime Market | 2026-2036
United Kingdom Lime Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Lime Market Analytics
Skilled quarry engineering talent is collapsing across Derbyshire and Lincolnshire, constraining kiln modernization timelines and forcing producers to automate or lose throughput. Lhoist Group leverages its captive chalk reserves in the South East to sustain vertical integration from extraction to hydrated lime finishing. Tarmac competes through dense rail-linked distribution nodes that anchor supply security for Thames Valley construction. Singleton Birch specializes in high-calcium quicklime for Sheffield steelworks, occupying a niche that larger commodity players navigate less aggressively.
United Kingdom lime encompasses calcium oxide and calcium hydroxide produced by calcining limestone above nine hundred degrees Celsius, yielding products with ninety-five percent plus CaO content for industrial alkalinity control. Quicklime dominates volume flows through the Humber and Teesside corridors, where steel production and flue gas treatment consume bulk shipments. Hydrated lime captures widening margin pools in water treatment, as Southern Water and Thames Water upgrade pH adjustment systems to meet tightening Environment Agency discharge permits. Soil stabilization applications for Highways England projects represent a mature, price-sensitive segment where Breedon Group and Tarmac battle on logistics cost.
Environment Agency permits under the Environmental Permitting Regulations, HSE Control of Substances Hazardous to Health standards, and British Standards Institution BS EN 459 for building lime collectively shape product certification, site licensing, and end-market access across England, Scotland, and Wales. The UK Emissions Trading Scheme and Carbon Border Adjustment Mechanism preparations are forcing lime burners toward biomass co-firing and electric kiln pilots or facing margin erosion on carbon-intensive production. Stakeholders must monitor whether DEFRA's post-Brexit chemical regime diverges from REACH, as separate registration burdens would fragment supply chains for imported limestone feedstock.
Market Dynamics
The UK lime sector is contending with a structural talent shortage in quarry engineering that is compressing kiln modernization timelines and accelerating automation investments across Derbyshire and Lincolnshire production clusters.
Growth Catalysts
- Industrial Emissions Directive enforcement:The UK Environment Agency's tightening sulfur dioxide limits for steel and power plants are pulling higher-purity quicklime volumes through the Humber corridor.
- Water treatment infrastructure:Southern Water and Thames Water pH adjustment system upgrades to meet stricter discharge permits are expanding hydrated lime offtake.
- Highways England soil stabilization:Road construction specifications for lime-treated subgrade are sustaining bulk demand across the East Midlands and Yorkshire.
Market Restraints
- Natural gas price volatility:Lime burning energy intensity exposes margins to UK wholesale gas market swings, with limited biomass co-firing scale to hedge exposure.
- Feedstock import dependence:High-calcium limestone sourcing concentrates on Irish Sea and Baltic suppliers, creating vulnerability to shipping disruptions and carbon border adjustments.
- Portland cement substitution:Ground granulated blast-furnace slag and fly ash alternatives are capturing soil stabilization and some construction applications on cost.
Strategic Opportunities
- Wales industrial cluster development:Port Talbot steel transition and Celtic Sea offshore wind fabrication could anchor new quicklime demand if carbon capture integration proceeds.
- Electric kiln pilot programs:Grid decarbonization and UK Emissions Trading Scheme cost trajectories are opening capital deployment paths for zero-carbon lime production.
- Scottish water treatment privatization:Scottish Water asset renewal cycles present hydrated lime specification opportunities distinct from England's utility procurement patterns.
Industry Challenges
- Quarry engineering capability gaps:Retiring kiln operators and geotechnical specialists in the Peak District are constraining operational continuity and technology transfer.
- BS EN 459 certification timelines:Building lime product approval delays are extending market access for new hydrated lime grades targeting heritage restoration.
- Carbon accounting complexity:Scope 3 limestone transport emissions and UK-specific DEFRA post-Brexit chemical registration requirements are fragmenting supply chain compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Lime Market |
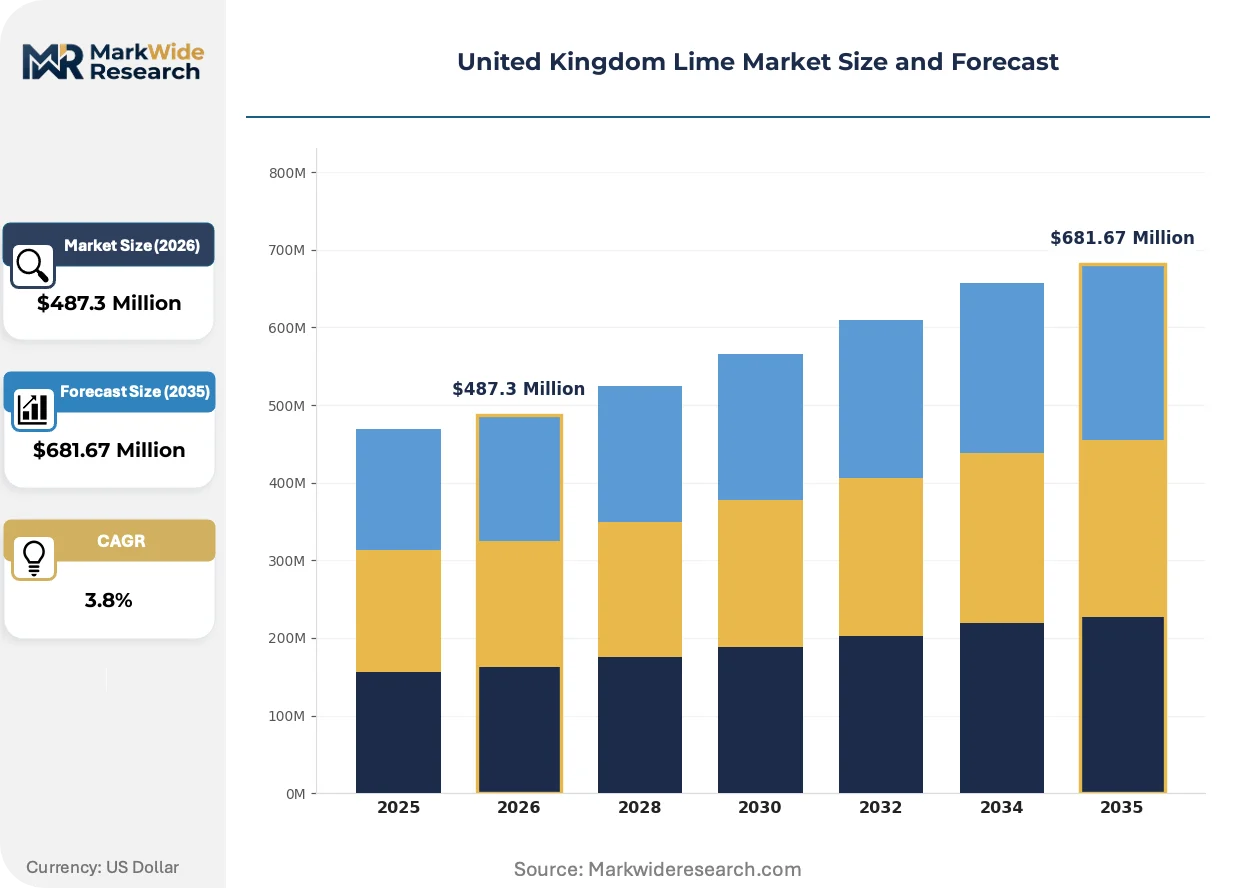
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quicklime, Hydrated Lime, Limestone, Lime Slurry End Use Industry: Construction, Agriculture, Water Treatment, Chemical Manufacturing Application: Soil Stabilization, Flue Gas Treatment, Steel Production, Glass Manufacturing Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Lhoist Group, Tarmac, Carmeuse, Breedon Group, Graymont, Singleton Birch, Cornish Lime, Smiths & Sons Ltd, Imerys, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Lime Market Evolving Landscape
Automation and decarbonization technologies are restructuring production economics across UK lime kilns, while regulatory tightening and buyer consolidation are reshaping procurement relationships.
Electrification of kiln operations is fragmenting the traditional fuel-based production model. Pilot electric calcination installations at demonstration scale are attracting investment from producers seeking UK Emissions Trading Scheme compliance pathways. The technology is fragmenting capital allocation between biomass retrofit and grid-connected electrification across the South East and East Midlands.
DEFRA's divergence from EU REACH chemical registration frameworks is creating parallel compliance burdens for imported limestone feedstock. The industrial consequence is duplicated testing and documentation costs for Irish and Baltic suppliers serving UK kilns. High-calcium quicklime producers dependent on imported stone are responding with accelerated domestic quarry development in Derbyshire and Lincolnshire.
Consolidation among water utilities is compressing supplier panels and extending contract durations. Thames Water and Southern Water procurement teams are consolidating lime supply agreements from multi-vendor spot arrangements toward single-source frameworks with logistics guarantees. The shift is most visible in Southern England, where tanker-fed hydrated lime systems are locking in three to five year supply commitments.
United Kingdom Lime Market Segmentation
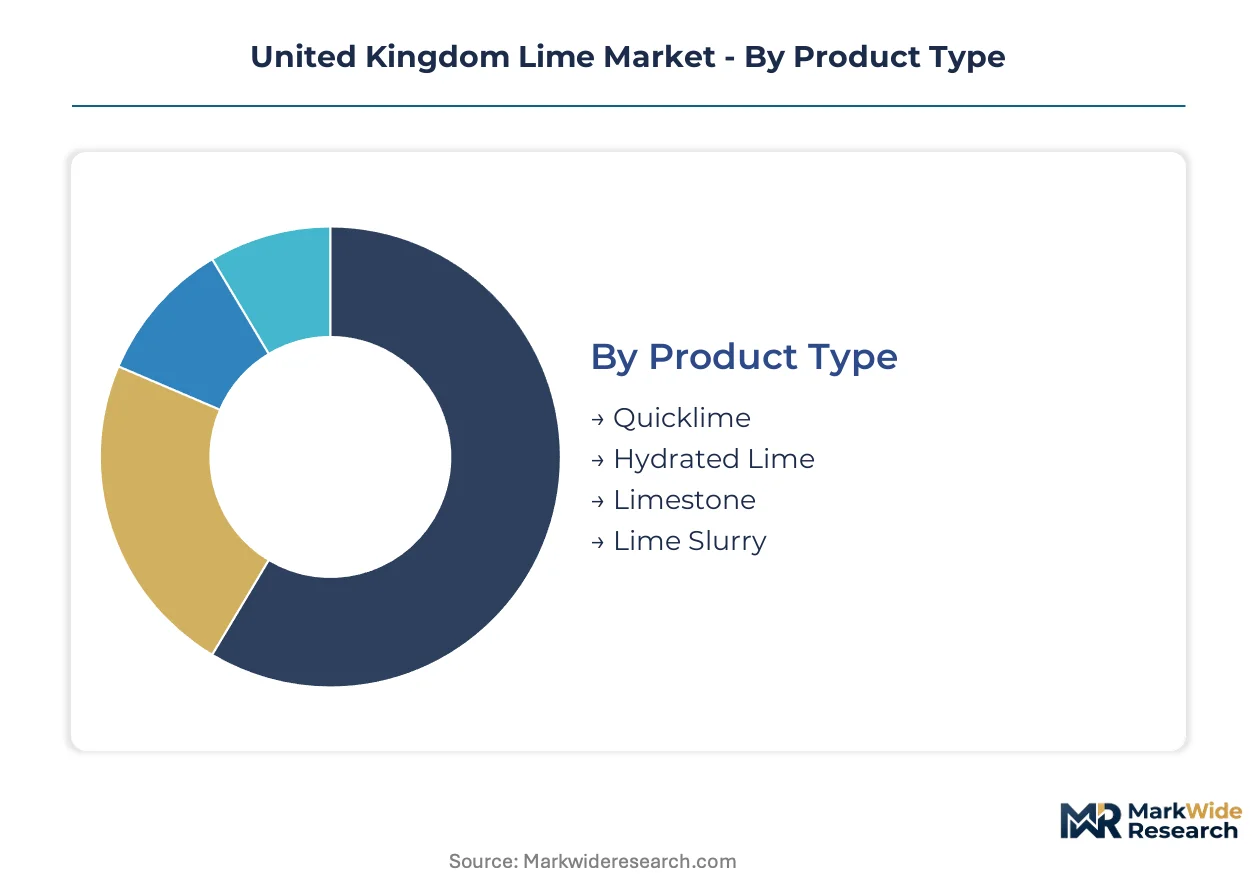
Segmentation in the United Kingdom lime market reveals how substitute materials and regulatory pressures concentrate value in specific product grades while displacing commodity volumes. Understanding these fault lines exposes where producers must defend specification premiums against cementitious alternatives.
Product Type:
Ground granulated blast-furnace slag and fly ash substitution threats fall unevenly across lime product categories, with hydrated lime most insulated by water treatment purity requirements.
- Quicklime:Calcium oxide produced above 900°C with 95%+ CaO content serves steel desulfurization and flue gas treatment across the Humber corridor. The UK Environment Agency's Industrial Emissions Directive enforcement pulls higher-purity volumes through Teesside and Scunthorpe industrial clusters.
- Hydrated Lime:Calcium hydroxide manufactured through controlled quicklime slaking captures widening margin pools in Southern Water and Thames Water pH adjustment systems. Tightening Environment Agency discharge permits lock in specification requirements that slag alternatives cannot meet.
- Limestone:Crushed calcium carbonate feedstock for kiln charging and construction aggregate faces direct competition from recycled concrete aggregate in road building applications.
- Lime Slurry:Pre-slaked aqueous suspensions for automated dosing systems at wastewater plants reduce handling costs but concentrate procurement power among consolidated utilities.
Quicklime retains volume leadership; hydrated lime holds the steepest expansion curve.
End Use Industry:
Cost tier stratification separates premium-specification industrial consumers from price-sensitive agricultural buyers.
- Construction:Highways England soil stabilization specifications sustain bulk demand across the East Midlands and Yorkshire, though Breedon Group and Tarmac compete aggressively on logistics cost in this mature segment.
- Water Treatment:Southern Water and Thames Water asset renewal cycles are consolidating supplier panels toward single-source frameworks with three to five year logistics guarantees in Southern England.
- Agriculture:pH correction for arable soils in Lincolnshire and East Anglia operates on thin margins with limited product differentiation.
- Chemical Manufacturing:Precipitated calcium carbonate and calcium carbide feedstock requirements in Teesside and Runcorn maintain steady offtake for high-calcium quicklime.
Water treatment commands the highest margin tier; construction absorbs the greatest tonnage.
Application:
Application maturity determines where electric kiln pilots and biomass co-firing investments can capture UK Emissions Trading Scheme compliance premiums.
- Flue Gas Treatment:Sulfur dioxide scrubbing at Drax and Ratcliffe-on-Soar power stations plus Port Talbot steelworks drives demand for high-reactivity quicklime with strict particle size distribution.
- Steel Production:Basic oxygen furnace desulfurization and ladle metallurgy at Scunthorpe and Sheffield facilities require consistent CaO content above 95%.
- Soil Stabilization:Lime-treated subgrade for A14 and HS2 earthworks specifications faces substitution pressure from cement and hydraulic binders on cost.
- Glass Manufacturing:Soda-lime silica batch formulations at Saint-Gobain and NSG Group furnaces maintain steady demand for low-iron limestone.
Flue gas treatment anchors decarbonization investment; soil stabilization faces the deepest price compression.
Distribution Channel:
Customer type fragmentation separates bulk industrial procurement from fragmented agricultural and heritage restoration demand.
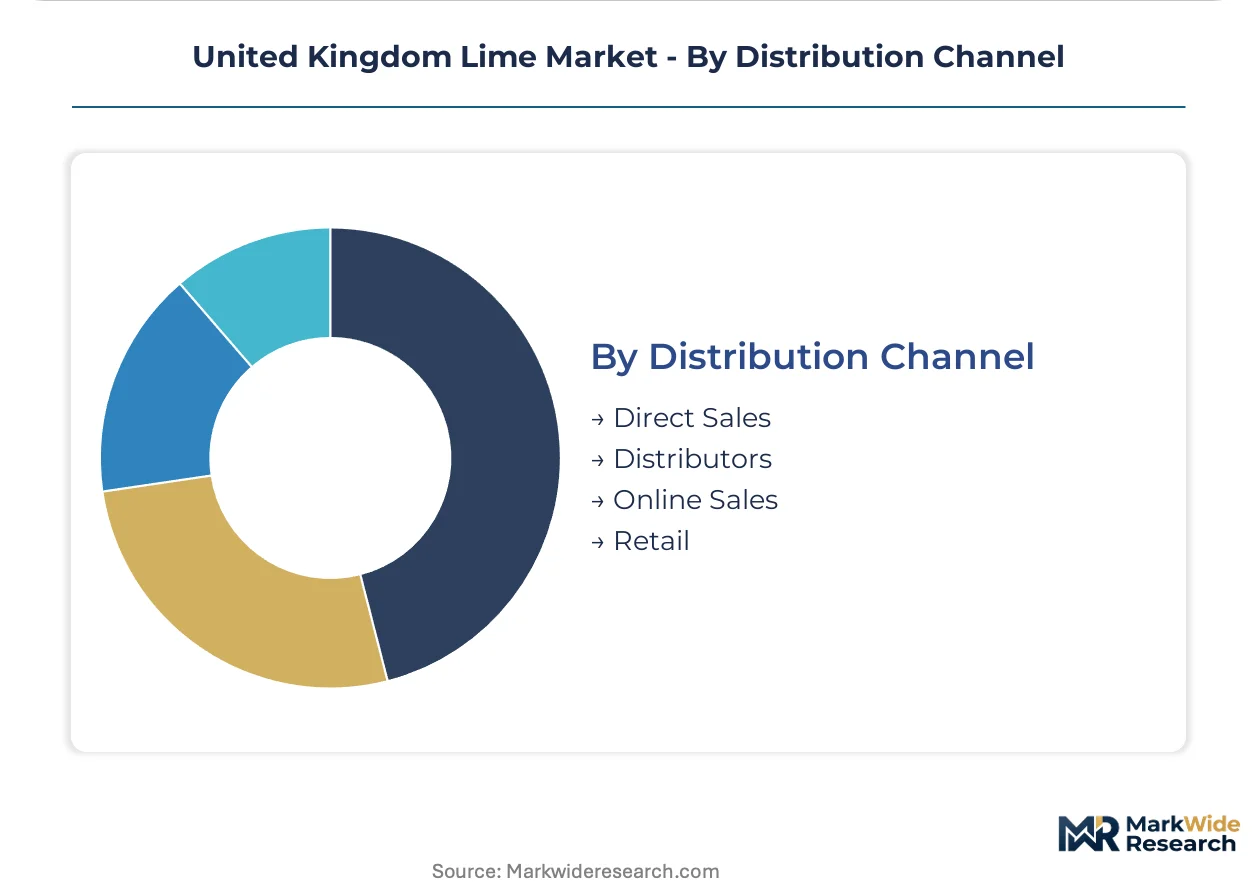
- Direct Sales:Rail-linked bulk deliveries to Humber and Teesside industrial clusters dominate quicklime volume flows, with Tarmac's dense distribution nodes anchoring supply security.
- Distributors:Regional builders merchants and agricultural suppliers handle bagged hydrated lime for construction and farming customers across the Midlands.
- Online Sales:Small-package hydrated lime for heritage restoration and artisan plastering bypasses traditional merchant channels.
- Retail:Garden center and farm shop channels for agricultural lime face margin erosion from consolidated distributor networks.
Direct sales concentrate industrial volume; distributor relationships control construction access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England's East Midlands and Yorkshire consume quicklime for steel desulfurization and flue gas treatment, while Southern England pulls hydrated lime for water treatment upgrades. Scotland and Wales present divergent demand profiles tied to distinct industrial bases and regulatory frameworks.
East Midlands
Steel production at Scunthorpe and power generation at Ratcliffe-on-Soar anchor quicklime offtake for flue gas desulfurization. The UK Environment Agency's Industrial Emissions Directive enforcement tightens sulfur dioxide limits, forcing higher-purity specifications. Derbyshire's historic quarrying infrastructure supports bulk supply chains to the Humber industrial cluster.
Yorkshire
Sheffield steelworks demand high-calcium quicklime for basic oxygen furnace operations and ladle metallurgy. HSE Control of Substances Hazardous to Health standards govern site licensing and worker exposure protocols. The region's rail-linked distribution nodes connect Peak District kilns to Teesside chemical manufacturing facilities.
Southern England
Thames Water and Southern Water drive hydrated lime procurement for pH adjustment system upgrades meeting stricter discharge permits. The UK Emissions Trading Scheme pressures producers toward biomass co-firing or electric kiln pilots. Tanker-fed hydrated lime systems in the Thames Valley are locking in multi-year supply commitments.
Scotland
Scottish Water asset renewal cycles present hydrated lime specification opportunities distinct from England's utility procurement patterns. The country's national environmental regulator enforces discharge standards that favor high-reactivity lime grades. Glasgow and Edinburgh wastewater treatment plants are consolidating supplier panels toward logistics-guaranteed frameworks.
Wales
Port Talbot steel transition and Celtic Sea offshore wind fabrication could anchor new quicklime demand if carbon capture integration proceeds. The UK Environment Agency's Wales division administers Environmental Permitting Regulations for industrial emissions. South Wales industrial clusters are evaluating lime supply security for emerging low-carbon steel pathways.
United Kingdom Lime Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with quarry control and kiln technology separating the tiers. The upper tier commands rail-linked distribution networks and captive limestone reserves. Two archetypes dominate: vertically integrated producers with backward control over extraction, and logistics-optimized distributors with dense node coverage. Competitive moves concentrate on automation investments to offset quarry engineering talent shortages, and on electric kiln pilots to secure UK Emissions Trading Scheme compliance pathways.
Within the integrated producer tier, Lhoist Group and Tarmac occupy positions defined by reserve access and distribution density. Singleton Birch exemplifies the specialist archetype, focusing on high-calcium quicklime for steel applications. These three companies represent the competitive spectrum from commodity scale to specification-grade focus.
| Leading Market Players |
|---|
| Lhoist Group |
| Tarmac |
| Carmeuse |
| Breedon Group |
| Graymont |
| Singleton Birch |
| Cornish Lime |
| Smiths & Sons Ltd |
| Imerys |
| Others |
Value Network & Pricing Analysis
Ground granulated blast-furnace slag displacement in soil stabilization is simultaneously compressing commodity lime pricing in England's East Midlands and redirecting supply chain investment toward higher-margin hydrated lime grades for Southern Water treatment contracts.
Pricing Analysis
Long-term offtake agreements dominate industrial procurement, with Thames Water and Southern Water locking three to five year supply commitments for tanker-fed hydrated lime systems. Price differentiation hinges on CaO purity grade and Environment Agency discharge permit compliance tier, with high-calcium quicklime for steel desulfurization commanding premiums over agricultural grades. Cost compression in construction lime is intensifying because Portland cement and slag alternatives capture subgrade stabilization work on delivered cost. Agricultural buyers in Lincolnshire exhibit the sharpest price sensitivity, while water utilities absorb specification premiums for guaranteed reactivity consistency.
Supply Chain Analysis
Inventory buffers at Humber corridor railheads run thin during peak flue gas treatment seasons, exposing buyers to lead-time volatility when Irish Sea limestone shipments face weather delays. UK lime production draws from Derbyshire, Lincolnshire, and captive South East chalk reserves, with high-calcium stone supplementally sourced from Ireland and Baltic quarries. Single-source vulnerability concentrates in Peak District kiln feedstock, where geotechnical permitting delays constrain alternative quarry development. Distribution runs through rail-linked bulk terminals to industrial clusters, with bagged product flowing via regional builders merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK lime market is positioned for cyclical recovery as steel production restocking and power sector flue gas upgrades drive industrial quicklime offtake through the Humber corridor.
For Market Incumbents: Compound rail-linked distribution density in the East Midlands to defend bulk supply security against emerging Irish import competition. Accelerate electric kiln pilot deployment to capture UK Emissions Trading Scheme compliance premiums before carbon border adjustments erode margins on gas-fired production. Backward integration into captive limestone reserves in Derbyshire hedges feedstock disruption risk from Baltic shipping volatility. For New Entrants and Emerging Players: Lead with Scottish Water asset renewal cycles as the most penetrable utility segment, where procurement patterns diverge from England's consolidated supplier panels. Target heritage restoration hydrated lime as a white-space application, exploiting BS EN 459 certification delays that frustrate incumbent product launches. Position through online direct channels for small-package artisan plastering demand, bypassing merchant margin capture. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed quarry operators in Lincolnshire holding stranded kiln capacity and aging environmental permits. Five-to-ten year viability hinges on successful biomass co-firing retrofits or electric calcination technology transfer from European parent entities. Monitor Port Talbot steel transition timelines as the inflection signal for Welsh quicklime demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Kiln Pilot Deployment | Grid-connected calcination secures UK Emissions Trading Scheme compliance pathways for Derbyshire producers. |
| Captive Limestone Reserve Development | Domestic quarry expansion in Lincolnshire reduces Baltic import dependence and carbon border exposure. |
| Long-term Utility Supply Agreement | Thames Water and Southern Water framework contracts lock in three to five year hydrated lime offtake. |
| Biomass Co-firing Retrofit | Alternative fuel integration hedges natural gas price volatility for Peak District kiln operations. |
| Automation Investment Program | Robotic quarry operations offset collapsing engineering talent availability across Derbyshire. |
Research Methodology
Operator-level perspectives from kiln operations managers, water utility procurement leads, steel plant desulfurization engineers, and quarry geotechnical specialists anchored the qualitative base. These primary insights combined with secondary validation from UK Environment Agency permit databases, British Standards Institution certification records, HSE incident reporting, and UK Emissions Trading Scheme registry filings. Bottom-up volume estimates from individual production site capacities triangulated against top-down industry association aggregates.
Sensitivity analysis tested forecast robustness across natural gas price scenarios, biomass feedstock availability assumptions, and electric kiln technology adoption curves. The analytical framework modeled demand across product type, end-use industry, application, and distribution channel dimensions throughout the forecast period. CAGRs derived from segment-level volume trajectories weighted by purity grade pricing differentials, with steel production cycles and water infrastructure investment programs as key lime-specific demand drivers.
The analysis sits within stated boundaries; outcomes outside sustained Industrial Emissions Directive enforcement or accelerated Port Talbot steel transition timelines would require recalibration. Forecasts reflect documented assumptions regarding energy cost trajectories and regulatory compliance stringency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Asia-Pacific Caustic Soda Market
Bulk Chemicals
Sodium Formate Market
Bulk Chemicals
Sodium Molybdate Market
Bulk Chemicals
Magnesium Acetate Market
Bulk Chemicals
Ammonium Thiosulfate Market
Bulk Chemicals
Global Hexane Market
Bulk Chemicals
Global Butyric Acid Market
Bulk Chemicals
Ethylene and Propylene Market
Bulk Chemicals
Global Linear Alpha Olefins Market
Bulk Chemicals
Global Sodium Chlorate Market
Bulk Chemicals
PAG Base Stock Market
Bulk Chemicals
Aluminum Nitrate Nonahydrate Market
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Global Sodium Borohydride Market