
 Asia Pacific Dry PVC Compound Market | 2026-2036
Asia Pacific Dry PVC Compound Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Dry PVC Compound Market Insights
Chinese petrochemical corridors is rebalancing capacity allocations toward specialty PVC formulations as domestic construction activity moderates. Shin-Etsu Chemical Co., Ltd. leverages its integrated vinyl chloride monomer supply to sustain margin stability across Japanese and Southeast Asian outlets. SCG Chemicals Public Company Limited anchors Thailand's position as a regional export hub for pipe-grade compounds. Xinjiang Zhongtai Chemical Co., Ltd. dominates western China's captive caustic soda and ethylene feedstock position, extending cost advantages into dry blend operations.
Asia Pacific dry PVC compound denotes a pre-mixed formulation of polyvinyl chloride resin with stabilizers, lubricants, fillers, and plasticizers, manufactured to specified Shore hardness and thermal stability parameters for extrusion or injection molding. The material serves primarily as a feedstock for pressure piping, wire insulation, and thermoformed packaging where batch consistency determines processing yields. Flexible PVC formulations command widening specification spreads as medical tubing and automotive interior applications tighten phthalate migration limits. Rigid PVC pipe compounds occupy the deepest volume pool across the application dimension, though cable sheathing grades are pulling fastest growth as grid interconnection projects multiply. Granule form leads procurement preferences among large extrusion houses, while powder blends retain cost traction in smaller Indian and Indonesian processing shops.
BIS certification requirements in India and China's GB/T 8814 standards for window profiles constrain import sourcing and elevate local formulation expertise as a market access barrier. REACH-aligned substance restrictions propagated through ASEAN harmonization protocols are forcing reformulation investments across Thai and Vietnamese compounders. Japan's METI chemical management framework adds disclosure layers for chlorinated material flows, shaping procurement documentation standards for regional exporters. Stakeholders must track how divergent national plasticizer approval lists reshape cross-border product registration strategies and blending plant location decisions.
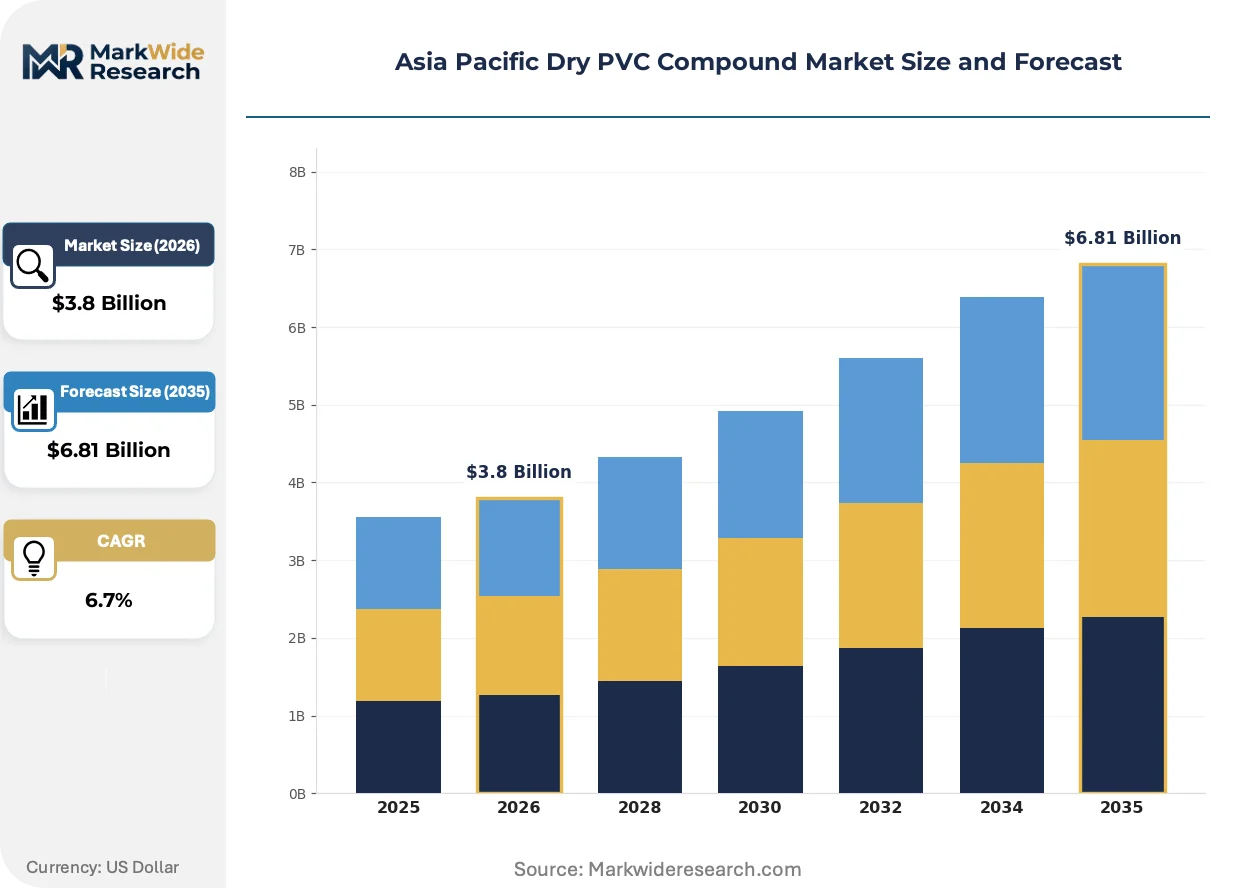
Market Dynamics
China's GB standards on plasticizer content and Vietnam's industrial zone expansions are redirecting formulation demand toward phthalate-free alternatives, compressing legacy compound margins while opening specialty formulation premiums.
Growth Catalysts
- Southeast Asian Infrastructure Programs:Construction sector procurement of rigid PVC pipe compounds is expanding across Thailand, Vietnam, and Indonesia as national water distribution and sanitation networks receive priority funding.
- REACH-Aligned ASEAN Harmonization:Propagated substance restrictions through regional protocols are forcing reformulation investments that favor compounders with advanced technical capabilities.
- Grid Interconnection Projects:Cable sheathing grades are pulling fastest growth as transmission infrastructure multiplies across eastern China's manufacturing corridor and India's power sector.
Market Restraints
- Chlor-Alkali Feedstock Volatility:Caustic soda and ethylene price swings from integrated petrochemical complexes transmit directly into dry blend cost structures.
- Western China Supply Concentration:Xinjiang-based captive feedstock positions dominate regional cost curves, creating geographic dependency for eastern compounders.
- Phthalate Migration Limits:Medical tubing and automotive interior applications face tightening technical barriers that disqualify legacy formulations from premium segments.
Strategic Opportunities
- Indonesian Processing Shop Modernization:Powder blend users in smaller Indonesian facilities represent conversion targets for granule form migration as quality standards tighten.
- Medical Tubing Specification Spreads:Flexible PVC formulations for healthcare applications command widening premiums as migration testing protocols proliferate.
- Japan's METI Chemical Management Framework:Disclosure requirements for chlorinated material flows are elevating documentation capabilities as a competitive differentiator for regional exporters.
Industry Challenges
- Cross-Border Product Registration Complexity:Divergent national plasticizer approval lists between China, India, Thailand, and Vietnam force parallel compliance investments.
- Integrated Chlor-Alkali Technical Labor:Compound blending operations require specialized expertise in thermal stability parameter control that outpaces regional training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Dry PVC Compound Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible PVC, Rigid PVC, Plasticized PVC, High-Temperature PVC End User: Construction, Automotive, Electrical, Packaging Application: Pipes, Sheets, Films, Cables Form: Granules, Powders, Pellets, Blends |
| Companies Covered | TP Polymer Private Limited, NHAT HUY GROUP, AGC Vinythai, Shin-Etsu Chemical Co., Ltd., Prism Masterbatches, Sinochem Holdings Corporation Ltd., Hanwha Solutions, Xinjiang Zhongtai Chemical Co., Ltd., SCG Chemicals Public Company Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Dry PVC Compound Market Trends and Innovations
Formulation chemistry and procurement documentation standards are converging as regulatory disclosure requirements reshape technical service offerings across the Asia Pacific compound value chain.
Calcium-zinc stabilizer systems are unifying heat stability performance across rigid pipe and wire insulation grades while eliminating heavy metal content. Japanese automotive suppliers and Korean cable manufacturers are adopting these systems at accelerated rates to preempt REACH-aligned restrictions. This unifying technology is compressing the traditional segmentation between construction-grade and electrical-grade compound specifications.
China's GB/T 8814 standards for window profiles and India's BIS certification requirements are elevating local formulation expertise as a market access barrier. These frameworks constrain import sourcing and force foreign compounders to establish domestic blending capacity or surrender specification control to licensed partners. Window profile and pressure pipe segments face the steepest compliance timelines as enforcement tightens in eastern China and western India.
Large extrusion houses are consolidating procurement around granule form specifications that guarantee Shore hardness and thermal stability batch consistency. Smaller Indian and Indonesian processing shops retain powder blend preferences for cost traction but face quality audits from export-oriented end-users. This specification divergence is most visible in Maharashtra's cable cluster and Guangdong's pipe extrusion belt, where buyer scale determines form factor access.
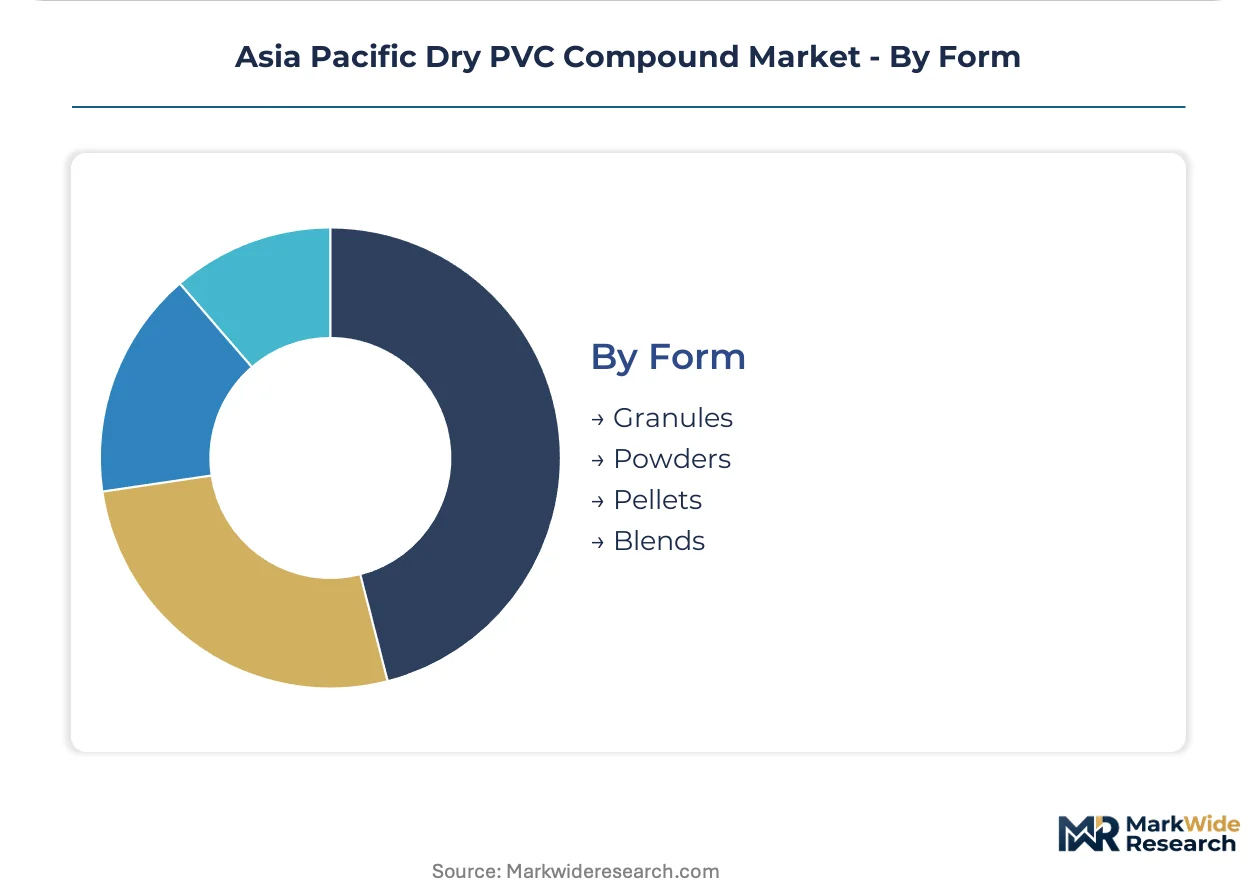
Asia Pacific Dry PVC Compound Market Segmentation
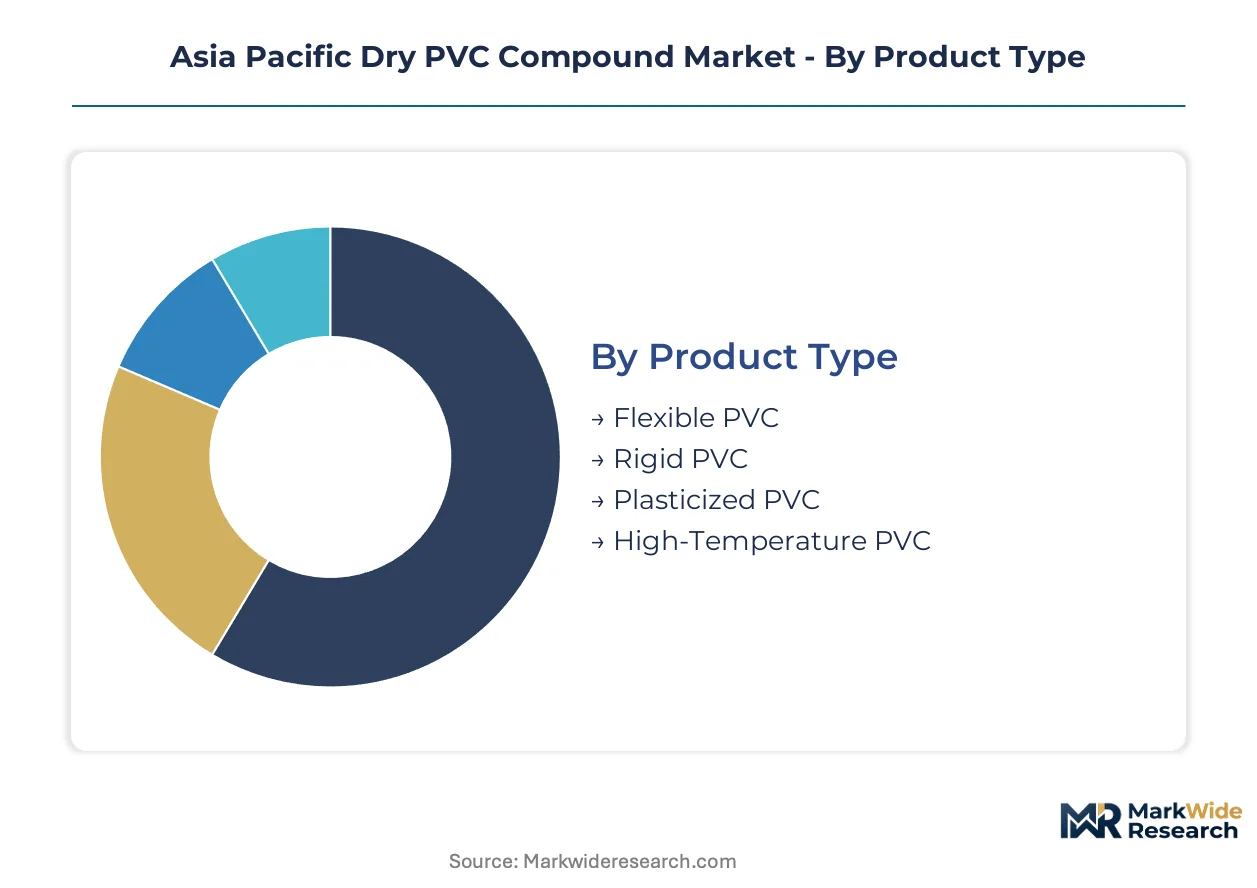
Segmentation in the Asia Pacific dry PVC compound market reflects divergent processing requirements across construction infrastructure, automotive interiors, and electrical insulation. Specification spreads widen as REACH-aligned ASEAN protocols and China's GB standards force reformulation investments that favor compounders with advanced technical capabilities.
Product Type:
Buyers select product type based on Shore hardness requirements and thermal stability parameters for specific extrusion or injection molding processes.
- Flexible PVC:Formulations incorporate higher plasticizer loadings for Shore A hardness ranges, serving medical tubing and automotive interior applications where phthalate migration limits are tightening. Demand concentrates in eastern China's manufacturing corridor as Korean cable manufacturers and Japanese automotive suppliers adopt calcium-zinc stabilizer systems.
- Rigid PVC:Unplasticized formulations deliver high compressive strength for pressure piping and window profiles, manufactured to GB/T 8814 standards in China and BIS certification requirements in India. Construction sector procurement across Thailand, Vietnam, and Indonesia drives volume concentration in this segment.
- Plasticized PVC:Intermediate plasticizer content balances flexibility with structural integrity for general-purpose extrusion.
- High-Temperature PVC:Specialized stabilizer packages extend thermal stability for electrical insulation grades in grid interconnection projects.
Rigid PVC leads on scale; flexible PVC leads on momentum as medical and automotive specifications tighten.
End User:
End-user selection correlates with national infrastructure spending cycles and regulatory enforcement timelines across the region.
- Construction:Rigid pipe compounds dominate procurement for water distribution and sanitation networks receiving priority funding across Southeast Asia. Vietnam's industrial zone expansions and Indonesia's processing shop modernization are redirecting formulation demand toward phthalate-free alternatives.
- Electrical:Cable sheathing grades are climbing the fastest as transmission infrastructure multiplies across eastern China and India's power sector. Maharashtra's cable cluster and Guangdong's pipe extrusion belt illustrate geographic concentration.
- Automotive:Interior trim and under-hood applications face REACH-aligned substance restrictions propagated through ASEAN harmonization protocols.
- Packaging:Thermoformed containers and blister packs utilize calendered sheet compounds with specific clarity and impact requirements.
Construction commands absolute volume; electrical applications gain share fastest on grid investment cycles.
Application:
Application selection determines batch consistency requirements and form factor preferences in procurement decisions.
- Pipes:Pressure-rated formulations for potable water and drainage systems represent the deepest volume pool, with procurement expanding across national water distribution programs in Thailand, Vietnam, and Indonesia.
- Cables:Sheathing and insulation grades for power transmission and telecommunications are expanding most quickly as grid interconnection projects multiply across the region.
- Sheets:Calendered products for construction and packaging applications require precise thickness tolerance control.
- Films:Blown and cast film extrusion for flexible packaging demands high clarity and seal strength specifications.
Pipes anchor volume throughput; cables demonstrate the steepest expansion trajectory on infrastructure electrification.
Form:
Form selection separates large extrusion houses from smaller processing shops on quality assurance capabilities and cost structures.
- Granules:Pre-compounded pellets guarantee Shore hardness and thermal stability batch consistency, preferred by large extrusion houses in Guangdong's pipe extrusion belt and Maharashtra's cable cluster. Japanese automotive suppliers and Korean cable manufacturers specify granule form for quality audit compliance.
- Powders:Dry blend formulations retain cost traction in smaller Indian and Indonesian processing shops, though export-oriented end-users are forcing migration toward granule specifications as quality standards tighten.
- Pellets:Cylindrical extruded form factors optimize feeding characteristics for specific extruder screw designs.
- Blends:Custom-mixed formulations allow compounders to adjust stabilizer and lubricant packages for niche processing requirements.
Granules dominate premium procurement; powders defend position in cost-sensitive smaller shops facing modernization pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's chlor-alkali corridor dwarfs Vietnam's emerging compound capacity, yet both markets face converging pressure from phthalate-free formulation mandates.
China
Construction sector procurement of rigid PVC pipe compounds is moderating as property investment cools, yet grid interconnection projects sustain cable sheathing demand. GB standards on plasticizer content and GB/T 8814 window profile specifications are tightening compliance timelines. Eastern China's chemical manufacturing corridor hosts integrated chlor-alkali complexes feeding compound blending operations, while Xinjiang-based captive feedstock positions dominate western cost curves.
India
Water distribution and sanitation networks are driving rigid pipe compound procurement across national infrastructure programs. BIS certification requirements constrain import sourcing and elevate local formulation expertise as a market access barrier. Maharashtra's cable cluster illustrates geographic concentration where buyer scale determines granule versus powder form preferences.
Thailand
Industrial zone expansions and export-oriented manufacturing are redirecting formulation demand toward phthalate-free alternatives. REACH-aligned substance restrictions propagated through ASEAN harmonization protocols are forcing reformulation investments. Thai compounders leverage regional hub positioning to serve cross-border demand from neighboring Mekong economies.
Vietnam
National water distribution networks and sanitation infrastructure are expanding construction sector procurement of rigid PVC pipe compounds. Industrial zone expansions are attracting compound blending capacity to serve export manufacturing. Northern manufacturing belts near Hanoi and southern hubs around Ho Chi Minh City concentrate demand from foreign-invested processing facilities.
Japan
Automotive interior applications and medical tubing specifications are tightening phthalate migration limits for flexible PVC formulations. METI's chemical management framework adds disclosure layers for chlorinated material flows, shaping procurement documentation standards for regional exporters. Japanese automotive suppliers and Korean cable manufacturers are adopting calcium-zinc stabilizer systems at accelerated rates.
Asia Pacific Dry PVC Compound Market Competitive Landscape
Chinese producers anchor one tier; Japanese and Thai specialists hold differentiated positions on technical specification and regional export access. The vendor base spans state-affiliated petrochemical complexes, integrated chemical conglomerates, and independent compounders. Three archetypes dominate: captive feedstock players with chlor-alkali integration, formulation specialists with certification depth, and regional distributors with blending flexibility. Capacity expansion and strategic partnerships represent the dominant competitive moves as compounders seek to secure plasticizer supply and local formulation licensing.
Among Japanese chemical conglomerates, Shin-Etsu Chemical Co., Ltd. exemplifies the integrated vinyl chloride monomer archetype that sustains margin stability across Southeast Asian outlets. Thai-based SCG Chemicals Public Company Limited occupies a position as a regional export hub for pipe-grade compounds. Xinjiang Zhongtai Chemical Co., Ltd. represents the captive feedstock model dominating western China's cost curves.
| Leading Market Players |
|---|
| TP Polymer Private Limited |
| NHAT HUY GROUP |
| AGC Vinythai |
| Shin-Etsu Chemical Co., Ltd. |
| Prism Masterbatches |
| Sinochem Holdings Corporation Ltd. |
| Hanwha Solutions |
| Xinjiang Zhongtai Chemical Co., Ltd. |
| SCG Chemicals Public Company Limited |
| Others |
Pricing and Supply Chain Analysis
Calcium-zinc stabilizer system adoption across Japanese automotive suppliers and Korean cable manufacturers simultaneously compresses legacy compound margins while concentrating procurement power among technical-capable blenders. This formulation transition rewards compounders with integrated chlor-alkali feedstock positions and phthalate-free certification depth, reshaping competitive economics across the Asia Pacific value chain.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for standard-grade rigid pipe compounds as new blending plants compete for Southeast Asian infrastructure contracts. Three-tier pricing structure across medical-grade, construction-grade, and general-purpose formulations separates compounders by migration testing capabilities and GB/T 8814 certification status. Pricing pressure stems from Xinjiang-based captive feedstock advantages that eastern Chinese compounders cannot match. Small Indonesian processing shops exhibit highest price sensitivity, while Japanese automotive suppliers prioritize batch consistency over unit cost.
Supply Chain Analysis
Freight cost differentials between western China's Xinjiang production belt and eastern manufacturing corridors compound the feedstock advantage of captive chlor-alkali operators. Supply concentrates in China, Thailand, and Vietnam, with India emerging as a demand sink constrained by BIS certification barriers. Raw material flows hinge on ethylene and caustic soda availability from integrated petrochemical complexes. Single-source vulnerability runs through Xinjiang's dominant captive feedstock position. Distribution runs through regional export hubs in Thailand and direct mill supply relationships in eastern China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH-aligned ASEAN harmonization and China's GB standards on plasticizer content are accelerating demand migration toward certified phthalate-free formulations.
For Market Incumbents: Lock in backward integration into vinyl chloride monomer supply or captive chlor-alkali positions to defend margin structures against Xinjiang-based cost competition. Secure BIS licensing in India and GB/T 8814 accreditation in China before enforcement timelines tighten, as these certifications are becoming non-negotiable market access barriers. For New Entrants and Emerging Players: Launch via toll-blending partnerships with established Thai or Vietnamese compounders to bypass capital-intensive chlor-alkali investments. Target medical tubing specification spreads where phthalate migration limits are tightening fastest and incumbent capacity is thinnest. Pursue go-to-market angles through Korean cable manufacturer supply chains seeking ASEAN-based granule form suppliers. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap formulation specialists with multi-country certification portfolios because regulatory fragmentation creates acquisition premiums for compliance-ready assets. Five-to-ten year viability favors compounders with technical service capabilities supporting customer reformulation investments. Monitor GB standards enforcement intensity in eastern China as the inflection indicator for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VCM Supply | Shin-Etsu Chemical's integrated vinyl chloride monomer position sustains margin stability across Southeast Asian outlets. |
| Phthalate-Free Formulation Certification | REACH-aligned ASEAN protocols force reformulation investments that favor compounders with advanced technical capabilities. |
| Regional Hub Capacity Expansion | SCG Chemicals anchors Thailand's position as a regional export hub for pipe-grade compounds serving Mekong economies. |
| Medical-Grade Specification Development | Japanese automotive suppliers and Korean cable manufacturers adopt calcium-zinc stabilizer systems at accelerated rates. |
| Long-Term Supply Agreements with Grid Developers | Cable sheathing grades pull fastest growth as transmission infrastructure multiplies across eastern China's manufacturing corridor. |
Research Methodology
Bottom-up construction and electrical end-use modeling reconciled against top-down chlor-alkali capacity tracking forms the analytical core of this study. Primary interviews with plant managers at integrated petrochemical complexes, procurement leads at Korean cable manufacturers, technical R&D directors at Japanese automotive suppliers, and distribution channel partners across Thailand and Vietnam combined with secondary validation from customs trade data, ACC regional reports, SEC filings of listed chemical conglomerates, and GB standards documentation. Triangulation across these sources ensures demand estimates align with verified supply-side capacity.
Historical trendline analysis of rigid pipe and cable sheathing grade volumes established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type flexibility, end-use industry concentration, form factor preferences, and regional production hub dynamics. CAGRs were derived from slope analysis of verified consumption data against announced capacity additions. Industry-specific forecast inputs included infrastructure spending cycles in Vietnam and Indonesia, plus grid interconnection project pipelines in eastern China and Maharashtra's cable cluster.
Forecast precision tightens around the base case; tail outcomes carry wider variance under chlor-alkali feedstock volatility or accelerated ASEAN harmonization timelines. Forecasts reflect documented assumptions about regulatory enforcement intensity and infrastructure commitment durability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Electronic Batio3 Powder Market
Bulk Chemicals
LAMEA Glacial Acrylic Acid Market
Bulk Chemicals
Naphthalene Market
Bulk Chemicals
Lysine Market
Bulk Chemicals
North America Copper Sulphate Market
Bulk Chemicals
Sodium Tetraborate Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Middle-East and Africa Carbon Black Market
Bulk Chemicals
Glyceryl Triacetate (Triacetin) Market
Bulk Chemicals
N-Heptane Market
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
Isophorone Market
Bulk Chemicals
North America Dimethyl Phosphate Market
Bulk Chemicals
Ethylene Dichloride Market
Bulk Chemicals
Global Capric Acid Market
Bulk Chemicals
Isopentane Market