
 Global Biosurfactant Market | 2026-2036
Global Biosurfactant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biosurfactant Market Foresight
A shift from single-source petrochemical supply toward multi-source microbial fermentation is recalibrating raw material strategies across the value chain. BASF SE leverages its integrated biotechnology platforms to secure consistent glycolipid output at scale. Evonik Industries AG anchors its position through specialized lipopeptide research pipelines. Kaneka Corporation competes via advanced fermentation infrastructure in Asian manufacturing clusters.
Biosurfactants are amphiphilic compounds produced by microorganisms or enzymes, typically exhibiting critical micelle concentrations between 1 and 200 mg/L depending on molecular class and purity grade, and they function primarily to reduce interfacial tension in aqueous systems where synthetic alternatives face toxicity or biodegradability constraints. Glycolipids dominate current commercial output due to established fermentation protocols and broader regulatory acceptance across detergent applications. Lipopeptides represent the fastest-expanding category as pharmaceutical and cosmetics formulators seek high-performance emulsifiers with lower ecotoxicity profiles. Polymer-based biosurfactants command premium positioning in oilfield chemical applications where thermal stability and salinity tolerance justify differentiated pricing.
The EPA's Safer Choice program and the EU REACH framework restrict persistent petrochemical surfactants while the FDA maintains purity standards for food-contact and pharmaceutical-grade bioproducts, collectively steering capital toward compliant fermentation assets. China's NMPA and GB standards for food additive safety create additional compliance layers for exporters targeting processed food applications. Stakeholders must monitor evolving fermentation yield improvements and regulatory reciprocity agreements to optimize capacity placement and certification investments.
Market Dynamics
Fermentation yield improvements are compressing unit economics while REACH restrictions on petrochemical surfactants force simultaneous supply-side substitution and demand-side reformulation across detergent, pharmaceutical, and oilfield chemical value chains.
Growth Catalysts
- EU REACH framework:Persistent petrochemical surfactant restrictions accelerate manufacturer migration toward microbial-derived alternatives in household cleaning formulations.
- Detergent sector procurement:Major formulators in Germany, the United States, and Japan expand long-term glycolipid supply contracts to secure fermentation capacity.
- Fermentation infrastructure:Asian manufacturing clusters invest in scaled bioreactor networks to reduce batch-to-batch variability in lipopeptide output.
Market Restraints
- Feedstock cost volatility:Refined vegetable oil and sugar substrate prices fluctuate with agricultural commodity cycles, squeezing margin predictability for glycolipid producers.
- Supply concentration risk:Commercial-scale lipopeptide fermentation remains concentrated among a limited set of European and Japanese biotechnology platforms.
- Technical limitation:Critical micelle concentration consistency below 10 mg/L remains difficult to achieve at industrial scale for certain polymer-based biosurfactant classes.
Strategic Opportunities
- India processed food sector:FSSAI and BIS alignment on food-contact bioproduct standards creates first-mover positioning for rhamnolipid suppliers targeting emulsifier applications.
- Pharmaceutical emulsifier demand:High-purity lipopeptide grades command premium positioning as FDA maintains stringent purity standards for parenteral drug formulations.
- China dual carbon goals:NMPA and MEE incentives for green chemistry accelerate domestic fermentation capacity buildout for surfactant applications.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA and EMA good manufacturing practice audits for food-contact and therapeutic applications extend commercialization cycles by 18-36 months.
- Fermentation specialist scarcity:Industrial microbiology and downstream processing expertise gaps constrain scale-up velocity across emerging production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biosurfactant Market |
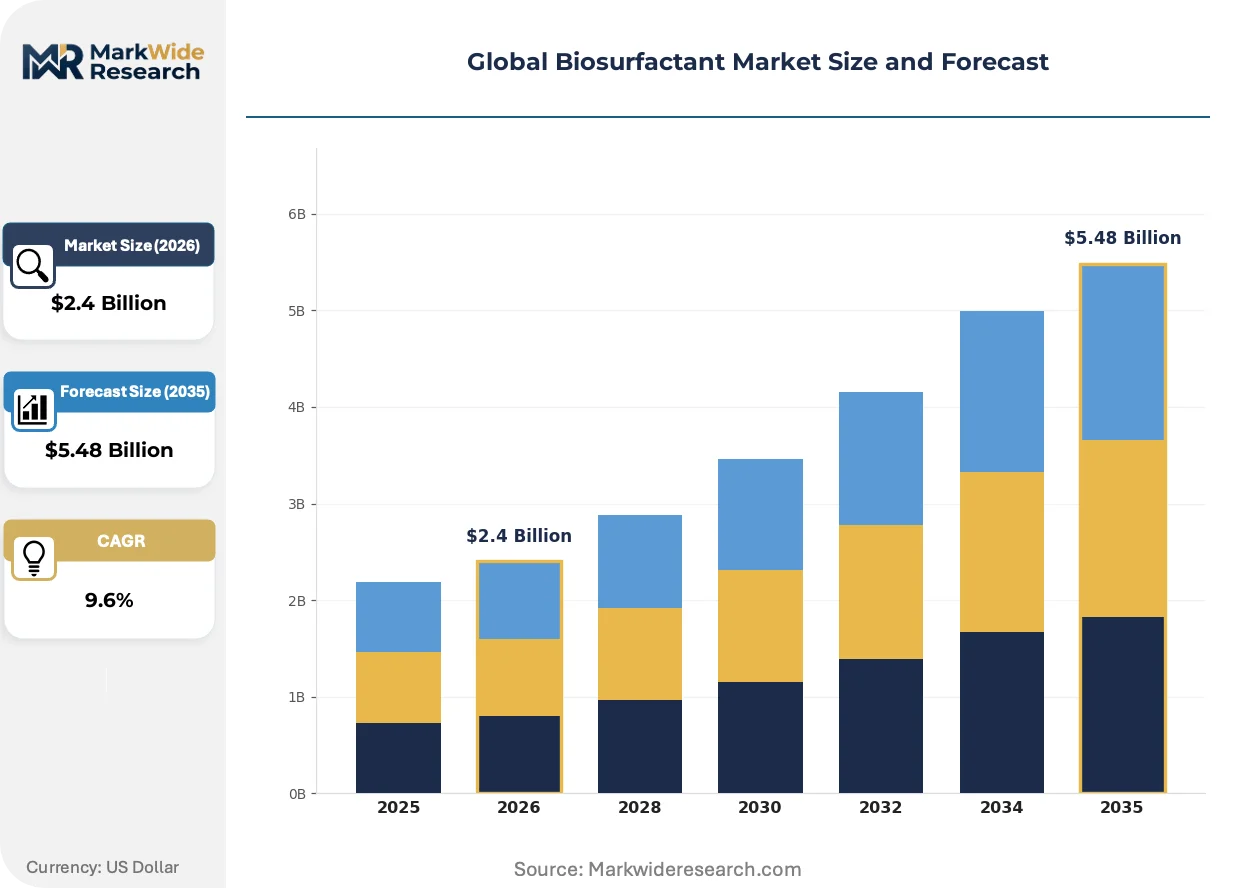
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.48 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glycolipids, Lipopeptides, Phospholipids, Fatty Acids, Polymer-Based Biosurfactants Application: Detergents & Cleaners, Oilfield Chemicals, Food Processing, Pesticides, Pharmaceuticals, Cosmetics Production Technology: Fermentation, Enzymatic Synthesis, Chemical Modification, Microbial Cultivation End User Industry: Personal Care, Agriculture, Food & Beverage Processing, Environmental Management, Chemical Manufacturing |
| Companies Covered | BASF SE, Kaneka Corporation, Evonik Industries AG, GlycoSurf LLC, Saraya Co., Ltd., Stepan Company, Jeneil Biotech, Inc., Croda International Plc, Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biosurfactant Market Shifts & Advancements
Continuous fermentation systems and cell-free enzymatic synthesis routes are compressing capital intensity while regulatory reciprocity negotiations between FDA, EMA, and NMPA reshape certification economics for multinational suppliers.
Cell-free enzymatic biosynthesis is consolidating as the dominant platform for high-value lipopeptide production. Pharmaceutical formulators in Switzerland and Germany adopt this technology to bypass cellular metabolism bottlenecks. The approach is consolidating batch consistency advantages that reduce downstream purification costs by eliminating cell debris separation steps.
REACH authorization requirements for nonylphenol ethoxylates and perfluorinated surfactants tighten through 2027. Industrial cleaning compounders face mandatory reformulation deadlines that accelerate glycolipid qualification programs. German and Dutch detergent manufacturers respond by locking multi-year offtake agreements with fermentation suppliers before capacity constraints materialize.
Specification-driven procurement now dominates surfactant sourcing decisions among institutional buyers. Food processors and cosmetics formulators unbundle technical service from material supply, contracting directly with fermentation specialists rather than traditional chemical distributors. This pattern concentrates most visibly in Japanese and South Korean manufacturing clusters where METI and MFDS certification requirements favor direct supplier relationships for audit traceability.
Global Biosurfactant Market Segmentation
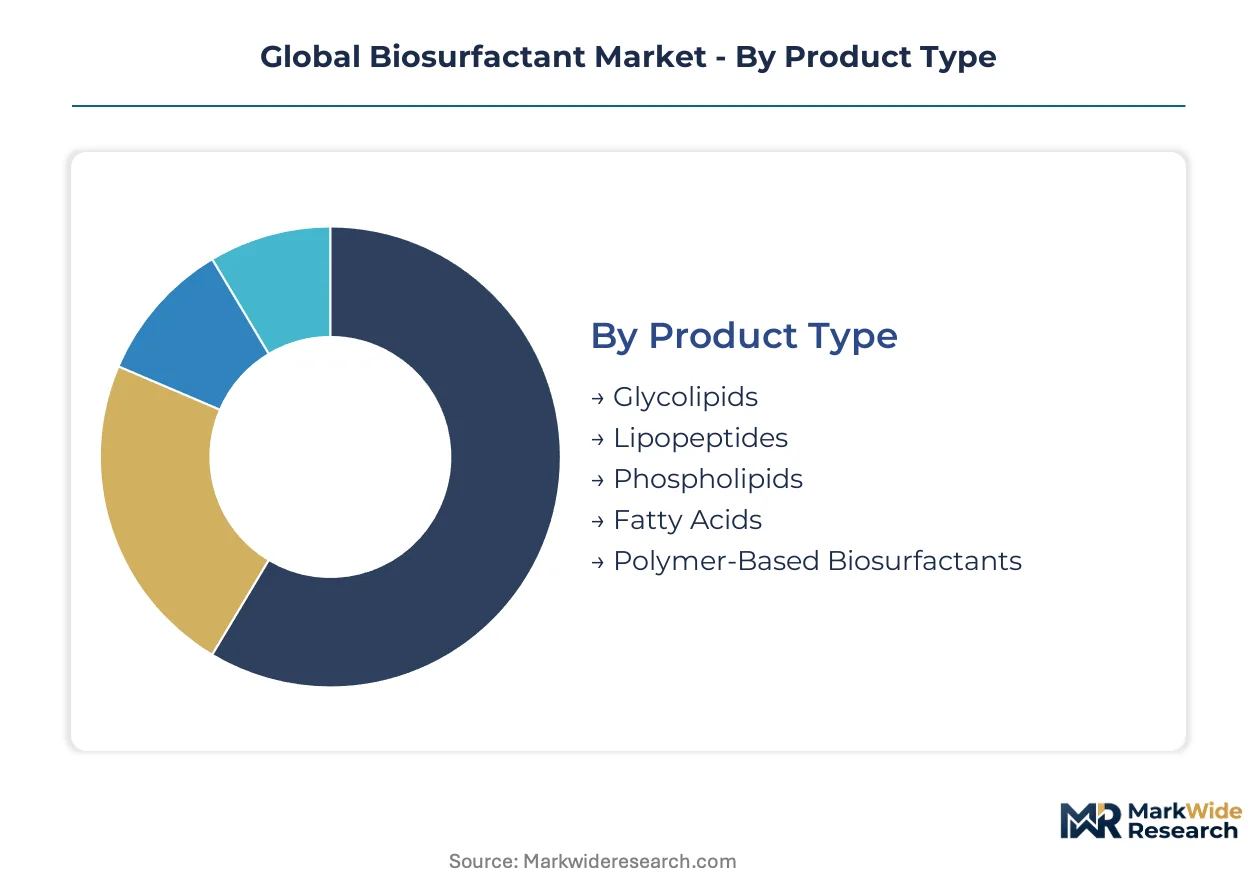
Segmentation in the biosurfactant market reveals how molecular architecture and production technology determine addressable application scope. Technical specifications around critical micelle concentration, thermal stability, and regulatory purity grades create distinct competitive arenas that suppliers must navigate strategically.
Product Type:
Glycolipid rhamnolipids and sophorolipids anchor commercial output through established fermentation protocols, while lipopeptide complexity commands premium positioning in performance-critical formulations.
- Glycolipids:These carbohydrate-fatty acid conjugates exhibit critical micelle concentrations between 10 and 200 mg/L depending on purity grade. Detergent formulators in Germany and the United States lock multi-year offtake agreements with fermentation suppliers to secure consistent sophorolipid volumes for household cleaning applications.
- Lipopeptides:Cyclic peptide-lipid structures deliver superior emulsification at concentrations below 10 mg/L. Pharmaceutical manufacturers in Switzerland and Japan source high-purity surfactin and iturin grades for parenteral drug formulations where FDA and PMDA purity standards apply.
- Phospholipids:Naturally derived membrane lipids function as emulsifiers in food-contact applications subject to EFSA and FDA safety evaluations.
- Fatty Acids:Simple carboxylic acid surfactants serve cost-sensitive industrial cleaning compounds with moderate performance requirements.
- Polymer-Based Biosurfactants:High molecular weight biopolymers withstand extreme salinity and temperature conditions in oilfield chemical applications.
Mature deployment sits with glycolipids in detergent formulations. Newer deployment is concentrated in lipopeptide pharmaceutical emulsifiers.
Application:
End-use requirements around biodegradability mandates, toxicity thresholds, and performance specifications fragment demand across distinct value chains with varying certification burdens.
- Detergents & Cleaners:REACH restrictions on nonylphenol ethoxylates force European formulators toward rhamnolipid alternatives. German and Dutch manufacturers accelerate glycolipid qualification programs ahead of mandatory reformulation deadlines.
- Oilfield Chemicals:Polymer-based biosurfactants justify differentiated pricing through thermal stability above 80°C and salinity tolerance exceeding 100,000 ppm in enhanced oil recovery operations.
- Food Processing:Emulsifier applications require FSSAI, FDA, or EFSA food-contact approvals that extend commercialization timelines by 18 to 36 months for new suppliers.
- Pesticides:Bio-based wetting agents reduce ecotoxicity in agricultural formulations targeting EU and North American regulatory compliance.
- Pharmaceuticals:Parenteral and topical drug delivery demands lipopeptide grades with endotoxin levels below established pharmacopeial limits.
- Cosmetics:Natural positioning drives South Korean and Japanese formulators toward fermentation-derived alternatives in skincare emulsions.
Volume concentration centers on detergents. Steepest expansion trajectory is emerging in pharmaceutical emulsifiers.
Production Technology:
Capital intensity and batch consistency vary substantially across biological and hybrid manufacturing platforms, with cell-free routes gaining traction in high-value segments.
- Fermentation:Scaled bioreactor networks in Asian manufacturing clusters reduce batch-to-batch variability in glycolipid output. Established protocols dominate commercial rhamnolipid and sophorolipid production.
- Enzymatic Synthesis:Cell-free platforms bypass cellular metabolism bottlenecks in lipopeptide manufacturing. Swiss and German pharmaceutical suppliers adopt this approach to eliminate cell debris separation costs and improve batch consistency.
- Chemical Modification:Post-fermentation functionalization extends molecular property ranges for specialized industrial applications.
- Microbial Cultivation:Controlled culture conditions optimize specific biosurfactant yields through strain selection and media engineering.
Commercial scale concentrates in fermentation infrastructure. Technology migration is accelerating toward enzymatic synthesis for premium segments.
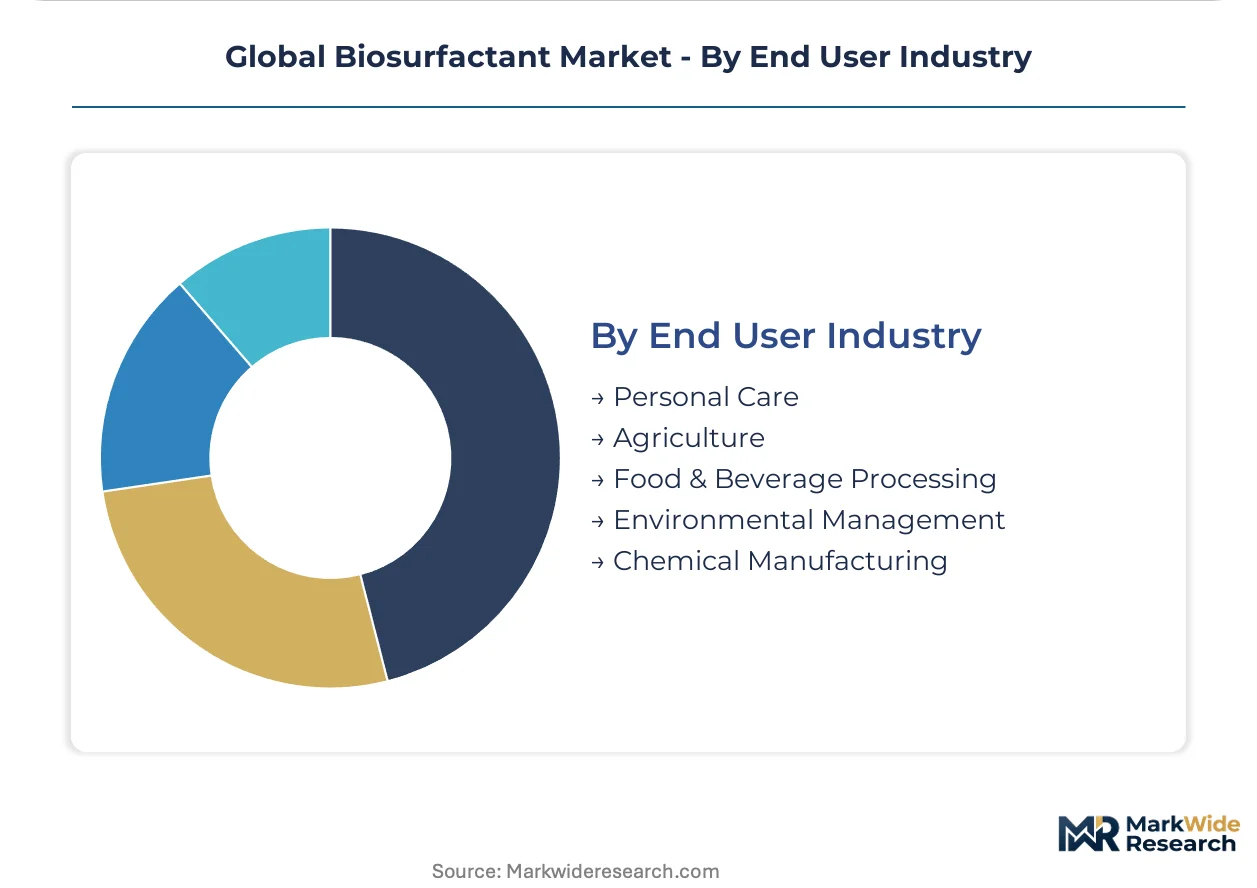
End User Industry:
Procurement sophistication and certification requirements diverge sharply between consumer-facing and industrial applications, reshaping supplier relationship models.
- Personal Care:Cosmetics formulators in Japan and South Korea contract directly with fermentation specialists rather than chemical distributors to satisfy METI and MFDS audit traceability requirements.
- Agriculture:Biopesticide wetting agents face EPA and PMRA ecological toxicity evaluations that favor biodegradable surfactant alternatives.
- Food & Beverage Processing:Emulsifier procurement requires alignment with NMPA, FSSAI, or FDA food additive safety standards for processed food applications.
- Environmental Management:Bioremediation and wastewater treatment applications leverage biosurfactant biodegradability for regulatory compliance in sensitive ecosystems.
- Chemical Manufacturing:Industrial intermediate producers integrate biosurfactants as process aids where synthetic alternatives face REACH authorization restrictions.
Contract sophistication is highest in personal care. Regulatory complexity is expanding fastest in food and beverage processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vegetable oil refining clusters in Germany and Indonesia anchor raw material flows for glycolipid fermentation, while sugar substrate availability in Brazil and corn belt regions of the United States shapes regional production economics.
Germany
Detergent manufacturers in North Rhine-Westphalia expand rhamnolipid procurement as REACH authorization deadlines for nonylphenol ethoxylates approach. The EU Green Deal mandates accelerate green chemistry investments across the Rhine-Ruhr industrial corridor. BASF SE leverages integrated biotechnology platforms in Ludwigshafen to secure consistent sophorolipid output for household cleaning formulations.
United States
EPA Safer Choice program certifications drive institutional cleaning compounders toward microbial-derived surfactants in the Midwest manufacturing belt. Corn substrate abundance in Iowa and Illinois supports competitive fermentation feedstock costs for domestic glycolipid producers. Chicago-area formulators lock multi-year supply contracts ahead of anticipated capacity constraints.
Japan
Cosmetics manufacturers in Osaka and Tokyo prefectures source high-purity lipopeptide grades for skincare emulsions under METI sustainability guidelines. PMDA purity standards for pharmaceutical applications create certification barriers that favor established fermentation specialists. The Kansai region concentrates advanced bioreactor infrastructure for surfactin and iturin production.
China
NMPA food additive safety standards and MEE dual carbon incentives accelerate domestic fermentation capacity buildout in the Yangtze River Delta. Processed food manufacturers in Jiangsu and Zhejiang provinces qualify rhamnolipid emulsifiers for export applications. Shanghai-based biotechnology platforms invest in scaled bioreactor networks to reduce batch-to-batch variability.
India
FSSAI and BIS alignment on food-contact bioproduct standards creates first-mover positioning for rhamnolipid suppliers targeting emulsifier applications in processed foods. Maharashtra and Gujarat industrial clusters attract fermentation infrastructure investment from multinational suppliers. Mumbai-area formulators establish direct supplier relationships to satisfy audit traceability requirements.
Global Biosurfactant Market Competitive Landscape
Capacity expansion dominates the current landscape as fermentation specialists scale bioreactor networks to capture reformulation-driven demand. The vendor base concentrates around integrated chemical conglomerates with biotechnology platforms, specialized fermentation pure-plays, and diversified surfactant manufacturers adding biosurfactant lines. Three archetypes define competitive positioning: integrated biotech-chemical hybrids, dedicated fermentation specialists, and traditional surfactant producers pivoting toward microbial-derived alternatives. Geographic expansion into Asian manufacturing clusters and technology licensing for cell-free enzymatic synthesis represent the dominant competitive moves.
Among integrated biotechnology platforms, BASF SE and Evonik Industries AG exemplify the hybrid archetype combining chemical process expertise with fermentation scale. Kaneka Corporation occupies a position within the dedicated specialist tier, leveraging advanced fermentation infrastructure in Asian manufacturing clusters. Croda International Plc and Solvay S.A. represent traditional surfactant manufacturers diversifying into microbial-derived alternatives through portfolio extension.
| Leading Market Players |
|---|
| BASF SE |
| Kaneka Corporation |
| Evonik Industries AG |
| GlycoSurf LLC |
| Saraya Co., Ltd. |
| Stepan Company |
| Jeneil Biotech, Inc. |
| Croda International Plc |
| Solvay S.A. |
| Others |
Supply & Pricing Matrix
Cell-free enzymatic synthesis routes are compressing capital intensity for lipopeptide manufacturers while simultaneously redistributing supply concentration away from traditional fermentation hubs toward specialized biotechnology platforms in Switzerland and Germany. This production-method transition simultaneously reshapes cost economics through elimination of cell debris separation steps and concentrates pricing power among enzymatic technology licensors.
Pricing Analysis
Technical service unbundling from material supply dominates procurement negotiations, with food processors and cosmetics formulators contracting directly with fermentation specialists rather than chemical distributors. Three-tier pricing structure across pharmaceutical-grade, food-contact, and industrial-grade certification levels creates substantial price differentiation, with FDA and EMA purity standards commanding significant premiums over standard detergent formulations. Cost compression in industrial-grade glycolipids is intensifying because Asian manufacturing clusters are scaling bioreactor networks, while pharmaceutical buyers exhibit the least price sensitivity due to stringent endotoxin requirements.
Supply Chain Analysis
Single-source vulnerability sits with lipopeptide fermentation capacity concentrated among European and Japanese biotechnology platforms, creating exposure to regulatory reciprocity disruptions. Raw material flows draw from vegetable oil refining clusters in Germany and Indonesia alongside sugar substrate availability in Brazil and United States corn belt regions. Feedstock cost volatility presents persistent structural risk as agricultural commodity cycles squeeze margin predictability. Distribution runs through specification-driven procurement channels where institutional buyers prioritize direct supplier relationships for audit traceability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biosurfactant market is navigating a technology-transition phase as cell-free enzymatic synthesis displaces cellular fermentation for high-value pharmaceutical applications. This substitution of enzymatic platforms for traditional bioreactor methods is recalibrating competitive economics across the value chain.
For Market Incumbents: Deepen backward integration into refined vegetable oil and sugar substrate supply chains to buffer margin pressure from agricultural commodity volatility. Secure multi-year offtake agreements with German and Dutch detergent manufacturers ahead of REACH reformulation deadlines. Lock fermentation capacity through dedicated bioreactor networks in Asian manufacturing clusters to defend against enzymatic technology licensors.
For New Entrants and Emerging Players: Capture first-mover positioning in India's processed food emulsifier sector where FSSAI and BIS alignment on food-contact standards creates qualification windows before multinational suppliers establish direct relationships. Target pharmaceutical-grade lipopeptide production through enzymatic synthesis platforms, bypassing cellular metabolism bottlenecks that constrain incumbent scale-up velocity. Pursue technology licensing arrangements with Swiss and German biotechnology specialists rather than greenfield fermentation infrastructure.
For Investors and Strategic Acquirers: Re-rating potential sits with cell-free enzymatic synthesis specialists given FDA and EMA regulatory reciprocity negotiations that favor batch-consistent, high-purity production methods. Long-term viability over the coming decade hinges on certification asset ownership rather than commodity fermentation capacity. Watch for NMPA and MEE alignment on green chemistry incentives as the inflection indicator for China domestic capacity buildout acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive vegetable oil and sugar sourcing insulates margin predictability from agricultural commodity cycles. |
| Cell-Free Enzymatic Technology Licensing | Swiss and German pharmaceutical suppliers eliminate cell debris separation costs through enzymatic platforms. |
| Multi-Year Offtake Agreement Lock | German detergent manufacturers secure fermentation capacity ahead of REACH reformulation deadlines. |
| Pharmaceutical-Grade Certification Investment | FDA and EMA good manufacturing practice audits enable premium positioning in parenteral drug formulations. |
| Asian Bioreactor Network Expansion | Scaled infrastructure in Jiangsu and Zhejiang provinces reduces batch-to-batch variability for export applications. |
Research Methodology
Trade databases, ECHA REACH authorization filings, and FDA food additive safety evaluations formed the secondary backbone of this analysis. Primary interviews with fermentation plant managers, procurement leads at detergent manufacturers, pharmaceutical formulation scientists, and cosmetics R&D directors combined with customs records and SEC filings from integrated chemical conglomerates. Bottom-up volume modeling and top-down value triangulation validated segment-level estimates across molecular classes and application verticals.
Bottom-up modeling anchored projections across the analysis window, with segmentation dimensions spanning molecular architecture, production technology platform, end-use industry, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating REACH restriction timelines, fermentation yield improvement trajectories, and enzymatic synthesis adoption rates. Industry-specific inputs included critical micelle concentration specifications, thermal stability thresholds for oilfield applications, and pharmacopeial purity grade requirements.
The model holds under stable regulatory reciprocity between FDA, EMA, and NMPA; deviation in fermentation yield improvement rates or feedstock cost volatility would shift capacity placement economics. Forecasts reflect assumptions around enzymatic synthesis technology maturation and green chemistry incentive durability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Cocomonoethanolamide (CMEA) Market
Surfactants
Cetanol Market
Surfactants
Superwetting Surfactants Market
Surfactants
Global Calcium Sulfonate Market
Surfactants
Alkylamines Market
Surfactants
MDEA Esterquats Market
Surfactants
Sulfosuccinate Market
Surfactants
Dispersant Market
Surfactants
Bitumen Emulsifier Market
Surfactants
Global Sodium Lauryl Sulfate Market
Surfactants
Oil-in-Water Anionic Emulsifier Market
Surfactants
Global Sodium Cocoyl Glutamate Market
Surfactants
Polysorbate 40 Market
Surfactants
Amino Acid Surfactants Market
Surfactants
Pharmaceutical Surfactants Market
Surfactants
Sugar-Based Surfactants Market