
 Global Sodium Cocoyl Glutamate Market | 2026-2036
Global Sodium Cocoyl Glutamate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sodium Cocoyl Glutamate Market Foresight
ISO 16128 natural origin certification is unwinding competitive access for suppliers lacking verifiable bio-based feedstock chains. Ajinomoto Co. Ltd. leverages its fermentation technology heritage to dominate high-purity grades. BASF SE anchors European supply through backward integration into coconut fatty acid sourcing. Sino Lion specializes in cost-optimized powder grades for Asian detergent producers.
Sodium cocoyl glutamate is an anionic surfactant synthesized from L-glutamic acid and coconut fatty acids, exhibiting a critical micelle concentration near 0.3% and biodegradability exceeding 90% in standard OECD 301 tests. Personal care applications command the deepest margin pools due to premium positioning of sulfate-free cleansers. Powder forms lead volume shipments for industrial cleaners, while liquid concentrates are displacing traditional sulfonates in household formulations.
REACH registration requirements in Europe, EPA Safer Choice criteria in the United States, and China's GB/T 26396 surfactant standards collectively elevate compliance costs for cross-border suppliers. FDA oversight of cosmetic ingredient safety in the US adds a secondary qualification layer distinct from industrial chemical pathways. Stakeholders must monitor regulatory divergence between bio-based content thresholds and biodegradability test protocols as qualification criteria fragment across jurisdictions.
Market Dynamics
ISO 16128 natural origin certification is forcing suppliers to reconstruct feedstock traceability systems, compressing competitive access for producers lacking verifiable bio-based supply chains.
Growth Catalysts
- REACH compliance:European Union chemical registration requirements are accelerating raw material qualification standards for amino acid-derived surfactants entering personal care formulations.
- Sulfate-free cleanser demand:Personal care manufacturers are expanding formulation portfolios with sodium cocoyl glutamate as a milder alternative to traditional sulfates in facial and body cleansers.
- China production clusters:Mature regional manufacturing infrastructure in Jiangsu and Zhejiang provinces is concentrating supply capacity for Asian detergent and cosmetic producers.
Market Restraints
- Coconut fatty acid volatility:Raw material costs fluctuate with Philippine and Indonesian coconut oil harvest cycles, compressing margin predictability for non-integrated producers.
- Fermentation capacity concentration:High-purity grade supply depends on limited fermentation technology holders, creating bottleneck risk for pharmaceutical-grade applications.
- Sulfonate substitution economics:Linear alkylbenzene sulfonates retain cost advantages in mass-market household detergents, limiting penetration in price-sensitive segments.
Strategic Opportunities
- India clean-label acceleration:FSSAI tightening of cosmetic ingredient disclosure requirements is opening formulation-switch opportunities for sulfate-free surfactant suppliers.
- Industrial cleaner concentrates:Liquid concentrate formats are capturing share from traditional powder sulfonates in institutional cleaning applications requiring cold-water solubility.
- EPA Safer Choice alignment:US federal procurement preference for certified safer chemical products is creating qualified supplier status advantages for biodegradable surfactant producers.
Industry Challenges
- Biodegradability test protocol fragmentation:Divergence between OECD 301, GB/T 26396, and EPA 835 test methods forces duplicate certification investments for cross-border suppliers.
- Fermentation scale-up talent scarcity:Limited pool of process engineers capable of optimizing L-glutamic acid yield at industrial bioreactor scale constrains capacity expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sodium Cocoyl Glutamate Market |
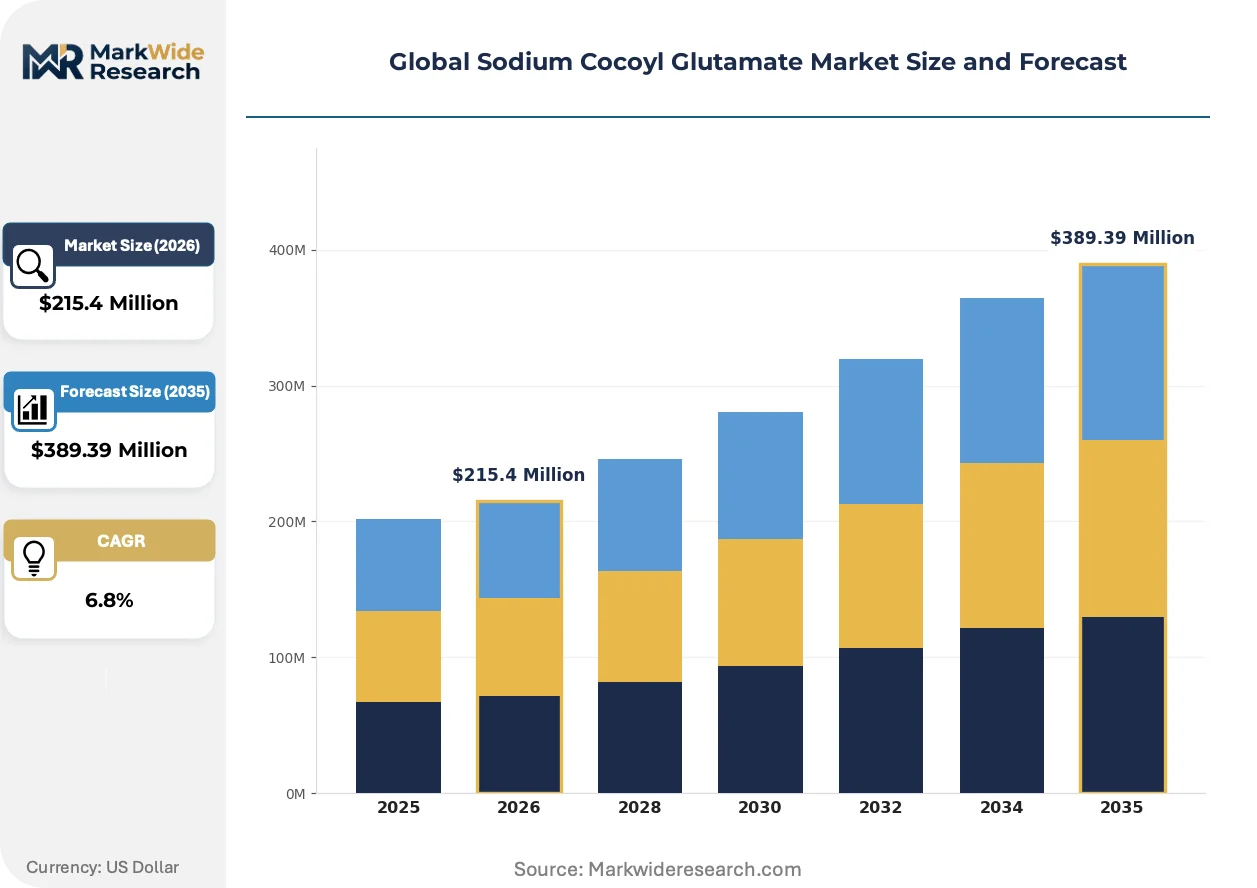
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Powder, Granules, Liquid, Paste Application: Personal Care, Household Cleaners, Industrial Cleaners, Agricultural Products, Textile Processing End User Industry: Cosmetics Manufacturers, Detergent Producers, Agrochemical Companies, Textile Mills Packaging Type: Drums, Bottles, Sacks, Pails |
| Companies Covered | Asahi Kasei, Sino Lion, BASF SE, DeWolf Chemical, Taiwan NJC, Clariant International AG, Schill Seilacher, Changsha Puji, Ajinomoto Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sodium Cocoyl Glutamate Market Shifts & Advancements
Enzymatic esterification processes are reshaping production economics for amino acid surfactants, enabling tighter molecular weight distribution and reduced solvent residues compared to traditional chemical synthesis routes.
Enzyme-catalyzed condensation is displacing acid chloride intermediates in sodium cocoyl glutamate production. Specialty chemical manufacturers in Germany and Japan are retrofitting batch reactors with immobilized lipase systems. The technology is displacing capital-intensive multi-step synthesis routes while eliminating halogenated solvent handling requirements.
China's GB/T 26396 surfactant standards are tightening biodegradability disclosure thresholds for industrial cleaning products. Manufacturers must now submit third-party test data for all surfactant components above 0.1% concentration. Domestic formulators are reformulating legacy alkylphenol ethoxylate systems to maintain product registration compliance.
Direct procurement from fermentation specialists is shortening ingredient supply chains for mid-sized cosmetic brands. Traditional distribution through regional chemical traders is losing share as buyers seek batch-specific origin documentation for natural certification claims. This pattern is most pronounced in French and German markets where ISO 16128 compliance has become a listing requirement for premium retail channels.
Global Sodium Cocoyl Glutamate Market Segmentation
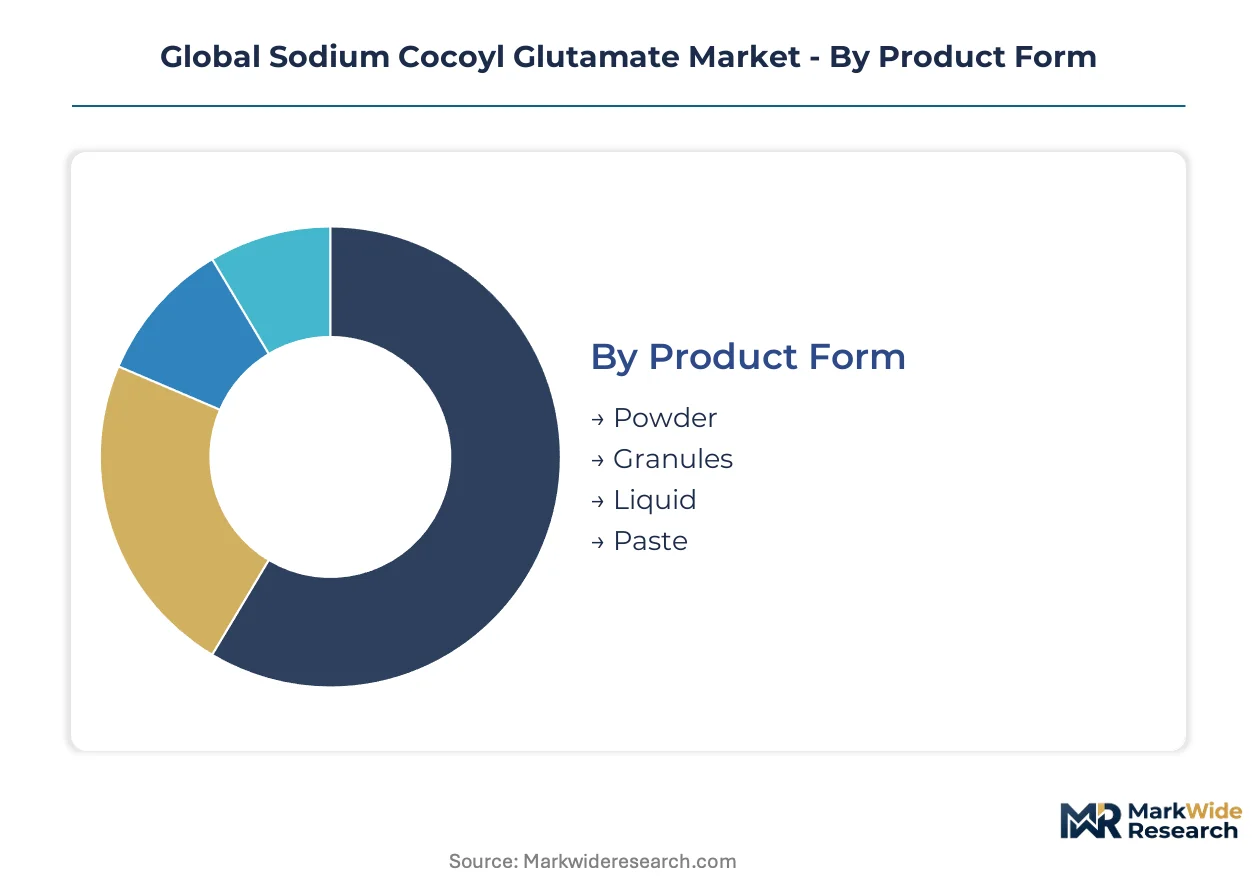
Segmentation in sodium cocoyl glutamate markets reveals how formulation requirements and regulatory thresholds fragment supply chains. ISO 16128 certification mandates and REACH registration tiers create distinct qualification barriers across product forms and end-use categories.
Product Form:
REACH registration complexity and biodegradability test protocol fragmentation differentiate supply economics across physical states. Powder and liquid grades face divergent qualification pathways in cross-border trade.
- Powder:Spray-dried crystalline form with standardized particle size distribution between 80-200 mesh. Industrial detergent producers in China and Japan concentrate procurement here for cold-water solubility requirements and extended shelf stability. Coconut fatty acid cost volatility compresses margin predictability for non-integrated suppliers.
- Liquid:Aqueous concentrates at 30-50% active content, displacing traditional sulfonates in household formulations requiring pump-dispense compatibility. Cosmetics manufacturers in France and Germany source liquid grades for sulfate-free facial cleanser production, driven by ISO 16128 natural origin certification mandates.
- Granules:Agglomerated form for controlled dissolution in institutional laundry systems, favored by European detergent compounders seeking dust-free handling.
- Paste:High-viscosity semisolid for specialized textile processing auxiliaries, limited to Japanese and German specialty chemical distributors serving niche wet-processing applications.
Powder handles the majority of throughput; liquid is the fastest mover on share.
Application:
Margin pools concentrate where premium positioning commands formulation flexibility and where cold-water performance specifications justify amino acid surfactant cost premiums over legacy sulfonates.
- Personal Care:Facial cleansers, body washes, and sulfate-free shampoo formulations requiring mildness profiles and preserved skin barrier function. ECHA REACH compliance and FDA cosmetic ingredient safety oversight create dual qualification layers distinct from industrial chemical pathways.
- Household Cleaners:Liquid dishwashing concentrates and hard surface sprays, capturing share from linear alkylbenzene sulfonates where EPA Safer Choice procurement preferences apply. US federal purchasing guidelines favor biodegradable surfactant producers with certified safer chemical status.
- Industrial Cleaners:Heavy-duty degreasers and metalworking fluids, with China's GB/T 26396 standards tightening biodegradability disclosure thresholds above 0.1% surfactant concentration.
- Agricultural Products:Pesticide emulsifiers and fertilizer coatings, constrained by residue tolerance limits set by national agricultural regulators in Brazil and India.
- Textile Processing:Scouring and dyeing auxiliaries, reformulating away from alkylphenol ethoxylates under EU Green Deal chemical substitution timelines.
Personal Care commands the deepest margin pools; Household Cleaners is expanding most quickly on volume.
End User Industry:
Procurement sophistication varies sharply between beauty brands requiring batch-specific origin documentation and commodity detergent producers optimizing on delivered cost per active unit.
- Cosmetics Manufacturers:Mid-sized French and German brands now source direct from fermentation specialists, bypassing regional chemical traders to secure ISO 16128-compliant documentation chains for premium retail channel listing requirements.
- Detergent Producers:Asian mass-market formulators in Jiangsu and Zhejiang provinces drive powder grade volume, with cost-optimized sourcing from domestic fermentation capacity.
- Agrochemical Companies:Formulation houses serving Brazilian and Indian crop protection markets, navigating residue tolerance variability between national agricultural regulators.
- Textile Mills:Wet-processing operations in Germany and Japan retrofitting legacy systems to eliminate alkylphenol ethoxylates ahead of regulatory deadlines.
Cosmetics Manufacturers concentrate value capture; Detergent Producers dominate physical throughput.
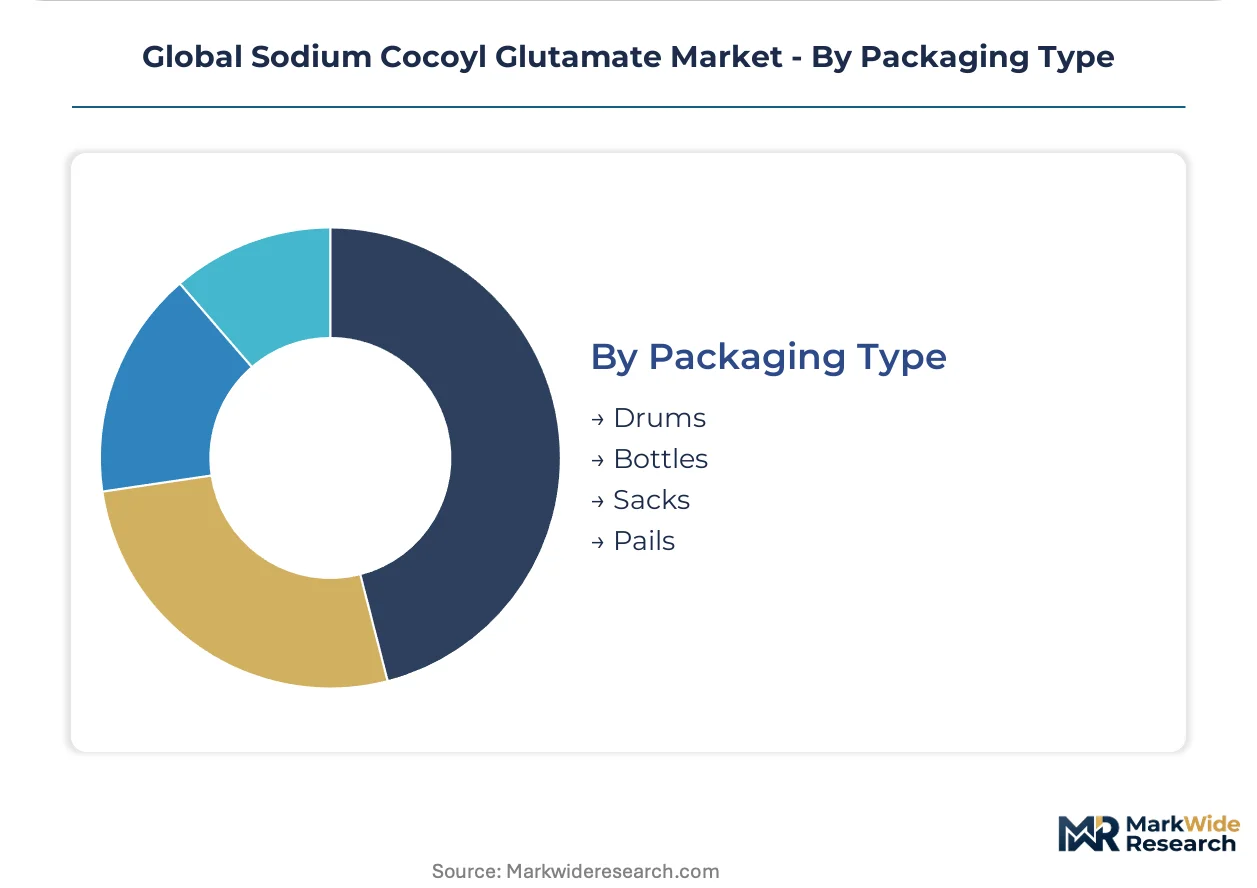
Packaging Type:
Logistics configuration and handling automation requirements segment supply chains between bulk industrial users and formulation houses requiring precise dosing access.
- Drums:Standard 200-liter steel containers for liquid concentrates, serving institutional cleaning contractors and mid-scale detergent compounders with established pumping infrastructure.
- Bottles:1-20 liter polyethylene containers for laboratory sampling and small-batch cosmetics formulation, prevalent in French and German specialty ingredient distribution.
- Sacks:Multi-layer paper or woven polypropylene for powder grades, optimized for pneumatic conveying systems at large-scale detergent production facilities in China.
- Pails:5-25 liter open-head plastic containers for paste grades and high-viscosity liquids, enabling manual scooping access in textile processing and agricultural formulation environments.
Sacks move the greatest powder tonnage; Bottles are climbing the fastest on per-unit value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration requirements in the European Union and EPA Safer Choice criteria in the United States are tightening cross-border qualification standards for amino acid-derived surfactants. Production clusters in Jiangsu and Zhejiang provinces anchor Asian supply capacity, while fermentation technology holders in Japan and Germany concentrate high-purity grade output.
China
Domestic detergent manufacturers in Jiangsu and Zhejiang provinces drive powder grade volume for industrial and household cleaning applications. GB/T 26396 surfactant standards mandate third-party biodegradability test data for all components above 0.1% concentration. Sino Lion and Changsha Puji anchor cost-optimized production for regional formulators seeking cold-water solubility specifications.
Japan
Cosmetic brands in Tokyo and Osaka demand batch-specific origin documentation for ISO 16128 natural certification claims. METI oversees chemical substance management under CSCL frameworks that align with REACH-equivalent safety data requirements. Ajinomoto Co. Ltd. leverages fermentation technology heritage to dominate pharmaceutical-grade and high-purity cosmetic surfactant segments.
Germany
Mid-sized French and German cosmetic brands now source liquid concentrates directly from fermentation specialists, bypassing regional chemical traders. ECHA REACH registration tiers create distinct qualification barriers for personal care versus industrial chemical pathways. BASF SE anchors European supply through backward integration into coconut fatty acid sourcing and backward control over feedstock chains.
United States
EPA Safer Choice procurement preferences in federal purchasing guidelines favor biodegradable surfactant producers with certified safer chemical status. Institutional cleaning contractors in the Midwest and Southeast retrofit formulations to displace traditional sulfonates with liquid concentrate formats. DeWolf Chemical distributes specialty grades for sulfate-free personal care formulations requiring FDA cosmetic ingredient safety compliance.
India
FSSAI tightening of cosmetic ingredient disclosure requirements accelerates formulation-switch opportunities for sulfate-free surfactant suppliers. Detergent producers in Maharashtra and Gujarat evaluate amino acid surfactants for premium household cleaner positioning. Domestic fermentation capacity remains limited, creating import dependence for high-purity grades serving pharmaceutical and cosmetic applications.
Global Sodium Cocoyl Glutamate Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates and specialized fermentation technology holders. Three tiers structure competitive access: global diversified suppliers with captive feedstock control, regional specialists optimizing cost-positioned powder grades, and niche distributors serving formulation houses requiring small-batch certification documentation. Dominant competitive moves include backward integration into coconut fatty acid sourcing and direct procurement relationships that displace traditional chemical trader channels.
Within the fermentation-technology tier, Ajinomoto Co. Ltd. and BASF SE exemplify divergent geographic anchoring strategies for high-purity grade supply. Sino Lion occupies a position representing cost-optimized Asian production for industrial detergent applications. Among specialty chemical distributors, Clariant International AG and Schill Seilacher sit within the European distribution architecture serving mid-sized cosmetic brands with ISO 16128-compliant documentation chains.
| Leading Market Players |
|---|
| Asahi Kasei |
| Sino Lion |
| BASF SE |
| DeWolf Chemical |
| Taiwan NJC |
| Clariant International AG |
| Schill Seilacher |
| Changsha Puji |
| Ajinomoto Co. Ltd. |
| Others |
Supply & Pricing Matrix
ISO 16128 natural origin certification gates both supply qualification and price differentiation simultaneously, forcing suppliers to invest in traceable bio-based feedstock chains while enabling premium positioning for compliant grades in French and German cosmetic channels.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and industrial-grade sodium cocoyl glutamate. Three-tier pricing structure across premium ISO 16128-compliant, standard REACH-registered, and economy non-certified grades reflects divergent qualification investments. Cost compression in economy powder grades is intensifying because Sino Lion and Changsha Puji expand fermentation capacity in Jiangsu province. Mass-market detergent producers in China exhibit highest price sensitivity, while mid-sized French cosmetic brands absorb premiums for batch-specific origin documentation.
Supply Chain Analysis
Coconut fatty acid sourcing from Philippine and Indonesian harvest cycles anchors supply vulnerability for non-integrated producers. Manufacturing concentrates in China, Japan, and Germany, with Ajinomoto and BASF controlling high-purity fermentation technology. Raw material dependencies include L-glutamic acid feedstock, coconut oil derivatives, and enzymatic catalysts for esterification processes. Single-source vulnerability in fermentation capacity creates bottleneck risk for pharmaceutical-grade applications. Distribution runs through direct procurement relationships displacing regional chemical traders, particularly in European cosmetic supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sulfate-free cleanser adoption in personal care represents an early-cycle expansion story, with clean-label requirements accelerating formulation switches across multiple regulatory jurisdictions.
For Market Incumbents: Shield high-purity grade margins by deepening backward integration into coconut fatty acid sourcing and accelerating ISO 16128 certification coverage. Fermentation capacity concentration from Ajinomoto and limited Japanese specialists threatens supply security for pharmaceutical applications. Defensive moves should prioritize captive L-glutamic acid production and direct procurement relationships with mid-sized cosmetic brands seeking documentation chains. For New Entrants and Emerging Players: Anchor in India's FSSAI-driven cosmetic ingredient disclosure tightening, where domestic fermentation capacity scarcity creates import dependence for high-purity grades. White-space targets include liquid concentrate formats for institutional cleaning contractors in the US Midwest and Southeast, plus cold-water soluble powder grades for Maharashtra and Gujarat detergent producers. Go-to-market leverage should emphasize EPA Safer Choice pre-qualification for federal procurement access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic esterification retrofit investments as German and Japanese manufacturers displace acid chloride synthesis routes. Long-term viability favors fermentation technology holders with proven industrial bioreactor scale-up capabilities. Acquisition targets should display captive feedstock control or established origin documentation systems. The signal to watch is GB/T 26396 enforcement tightening in China's industrial cleaning segment, which would accelerate legacy surfactant replacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coconut Fatty Acid Sourcing | BASF SE anchors European supply security through captive Philippine and Indonesian feedstock control. |
| Enzymatic Esterification Retrofit Investment | Immobilized lipase systems in German batch reactors eliminate halogenated solvent handling requirements. |
| ISO 16128 Certification Expansion | Batch-specific origin documentation secures premium retail channel listing requirements in France and Germany. |
| Direct Procurement Relationship Development | Mid-sized cosmetic brands bypass regional chemical traders to secure compliant supply chains. |
| EPA Safer Choice Pre-Qualification | Federal procurement preferences favor certified biodegradable surfactant producers in institutional cleaning. |
Research Methodology
A spread of perspectives from fermentation technology directors, cosmetic formulation chemists, detergent procurement leads, and surfactant distribution channel managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against customs and trade data, Cefic surfactant industry reports, SEC 10-K filings from listed chemical conglomerates, and ECHA REACH registration databases. Bottom-up volume modeling triangulated against top-down market sizing across product forms and end-use segments.
Segmentation dimensions modeled include physical state, application category, end-user industry, and regional production hub concentration. CAGRs were derived from elasticity-adjusted demand projections across the analysis window. Forecast inputs incorporated coconut oil price volatility indices, fermentation capacity expansion timelines, and regulatory compliance cost trajectories for cross-border suppliers.
Decision-makers should treat outputs as directional under sustained sulfate-free formulation adoption and stable coconut harvest yields; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as GB/T 26396 enforcement intensity and EPA Safer Choice procurement scope evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Dioctyl Sulfosuccinates Components Market
Surfactants
Selenium Sulphide Market
Surfactants
Cocamide Monoethanolamine Market
Surfactants
Global Low Foam Surfactants Market
Surfactants
TEA Esterquats Market
Surfactants
Tetradecyl Chloride Market
Surfactants
Cetanol Market
Surfactants
Wetting Agents Market
Surfactants
Soap Salts Market
Surfactants
Global Amphoteric Surfactants Market
Surfactants
Global Detergent Polymers Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Sodium Cumenesulfonate Market
Surfactants
Tetrabutylammonium Bromide Market
Surfactants
Fatty Methyl Ester Sulfonate Market
Surfactants
Global Fluorosurfactants Market