
 Sulfosuccinate Market | 2026-2036
Sulfosuccinate Market Size, Share, and Industry Trends Forecast 2026-2036
Sulfosuccinate Market Analysis
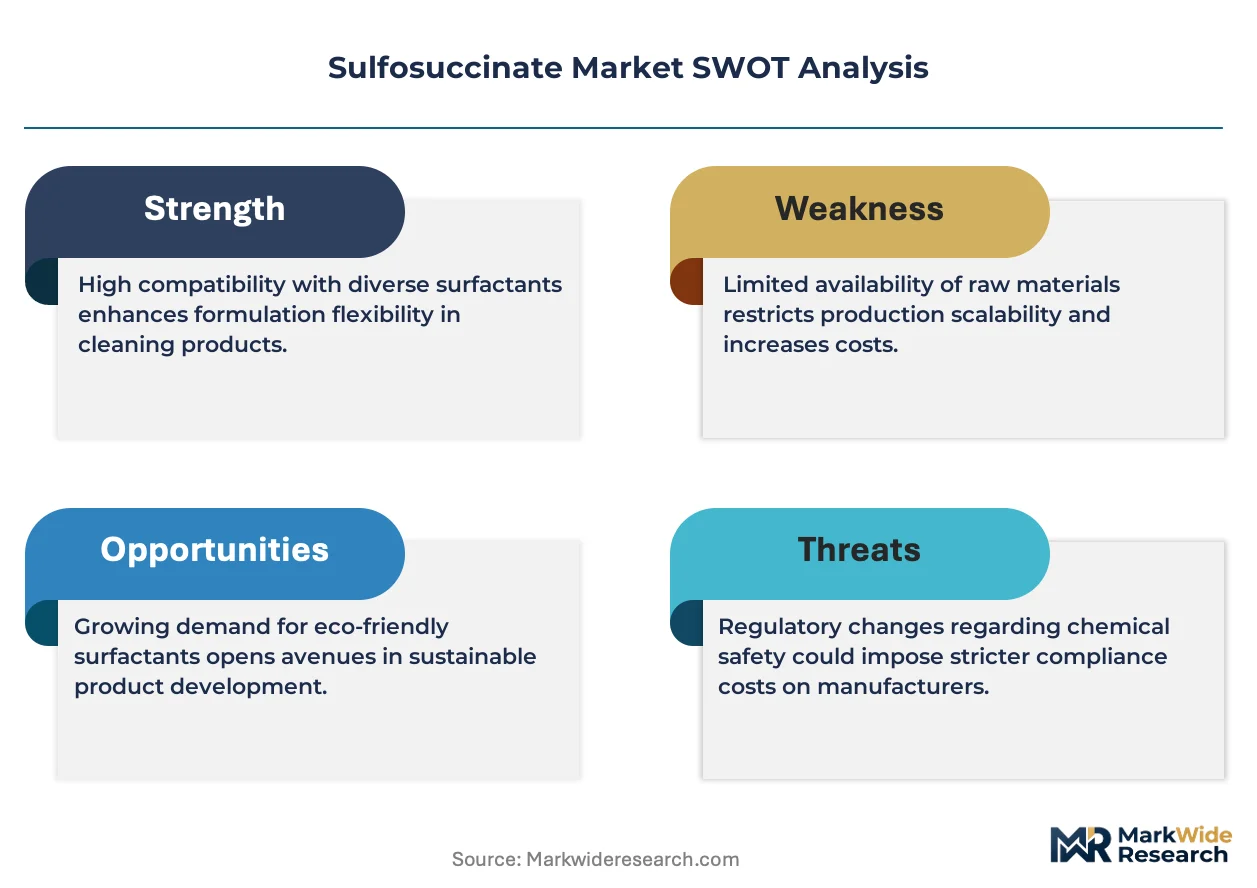
REACH is pivoting the European sulfosuccinate cost-of-entry calculus toward comprehensive substance registration and hazard assessment. BASF SE leverages backward integration into maleic anhydride feedstocks to sustain margin resilience against regulatory compliance costs. Evonik Industries AG anchors its position through specialized esterification technology that navigates tightening purity thresholds. Clariant AG competes via geographic diversification of production assets across multiple regulatory jurisdictions.
Sulfosuccinates are diester salts of sulfosuccinic acid, typically manufactured through esterification of maleic anhydride with fatty alcohols followed by sulfonation and neutralization, yielding anionic surfactants with exceptional mildness and foaming properties valued in sensitive-skin applications. The sodium sulfosuccinate product category dominates volume due to its cost-efficient production profile and broad compatibility across emulsifier and surfactant applications. Personal care end-use absorbs the largest value share as formulators prioritize dermatological safety credentials, while pharmaceutical-grade specifications command premium positioning through tighter impurity controls.
EPA oversight in the United States governs toxic substance reporting under TSCA, while ECHA administers REACH registration obligations across Europe, and China's MEE enforces dual carbon goals that tighten energy intensity benchmarks for esterification processes. These frameworks collectively elevate compliance expenditure but simultaneously filter subscale competitors from market participation. Stakeholders must monitor regulatory divergence between jurisdictions to optimize product registration sequencing and manufacturing location decisions.
Market Dynamics
REACH registration obligations in Europe are restructuring competitive entry costs, forcing manufacturers to absorb comprehensive substance dossier preparation and hazard assessment expenditures that smaller competitors cannot finance.
Growth Catalysts
- Personal care dermatological safety prioritization:Formulators across sensitive-skin applications specify sulfosuccinates for their exceptional mildness profile, creating specification pull through contract manufacturing channels.
- China's MEE dual carbon enforcement:Energy intensity benchmarks for esterification processes are accelerating domestic capacity consolidation toward integrated producers with captive maleic anhydride supply.
- Esterification technology maturation:Continuous sulfonation reactor designs are reducing batch-to-batch purity variation, enabling pharmaceutical-grade certification penetration into higher-margin segments.
Market Restraints
- Maleic anhydride feedstock volatility:Naphtha-linked pricing swings transmit directly into sulfosuccinate cost structures, compressing margin predictability for non-integrated manufacturers.
- European REACH registration cost barriers:Substance dossier preparation and hazard assessment expenditures exceed EUR 100,000 per registration, filtering subscale participants from EU market participation.
- Amphoteric surfactant substitution pressure:Betaine chemistry advances in mild cleansing applications are capturing share in shampoo and body wash formulations where foam quality requirements have relaxed.
Strategic Opportunities
- India's BIS quality mandate expansion:Personal care ingredient standardization is creating first-mover positioning for sulfosuccinate suppliers achieving domestic certification ahead of enforcement deadlines.
- Pharmaceutical excipient grade specification:Tightened impurity thresholds for topical drug delivery systems command 40-60% price premiums over industrial grades with equivalent active content.
- Bio-based fatty alcohol feedstock integration:Palm kernel and coconut oil-derived alcohol supply chain certification is aligning with EU Green Deal sourcing requirements for renewable content claims.
Industry Challenges
- Specialized esterification process engineering scarcity:Operational expertise in continuous sulfonation reactor management concentrates among aging technical workforces in Germany and Japan.
- Pharmaceutical-grade certification timeline compression:GMP audit scheduling backlogs at notified bodies extend qualification cycles by 12-18 months, delaying premium segment entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulfosuccinate Market |
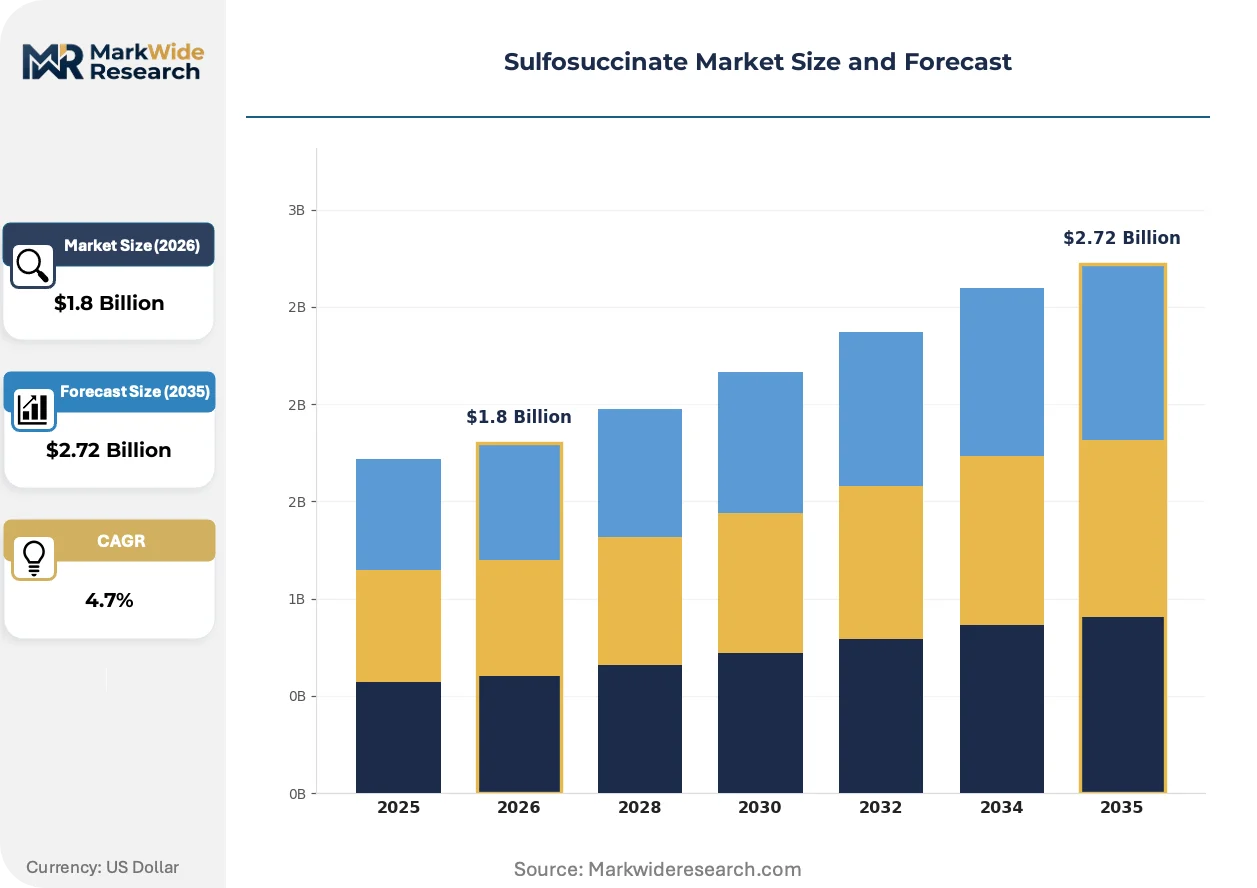
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Sulfosuccinate, Potassium Sulfosuccinate, Calcium Sulfosuccinate, Ammonium Sulfosuccinate End User: Personal Care, Pharmaceuticals, Agrochemicals, Food & Beverages Application: Emulsifier, Surfactant, Stabilizer, Additive Form: Liquid, Powder, Granules, Paste |
| Companies Covered | BASF SE, Evonik Industries AG, Clariant AG, Croda International, Stepan Company, MFG Chemical, Solvay, KAO Corporation, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulfosuccinate Market Emerging Trajectories
Process intensification and regulatory data automation are compressing development cycles while purity threshold escalation is fragmenting product tiers across end-use specifications.
Continuous sulfonation reactor technology is consolidating batch manufacturing into integrated continuous flow systems. Personal care contract manufacturers in South Korea and Germany are adopting these designs to reduce solvent recovery costs and improve lot-to-lot consistency. The technology is consolidating mid-scale batch producers into toll manufacturing relationships with capital-intensive continuous operators.
REACH Article 33 SCIP database obligations are extending substance tracking requirements through downstream article incorporation. Industrial chemical suppliers must now generate and maintain complex supply chain communication dossiers for sulfosuccinate-containing preparations. Personal care formulators importing into the EU are responding by consolidating supplier bases toward REACH-registered producers with established SCIP infrastructure.
Specification-driven procurement is compressing supplier qualification cycles as personal care brand owners unbundle R&D from manufacturing. Contract research organizations in Mumbai and Shanghai are displacing in-house formulation development for mid-tier regional brands. This pattern is most visible in Southeast Asian markets where domestic brand owners lack technical staffing depth for surfactant compatibility screening.
Sulfosuccinate Market Segmentation
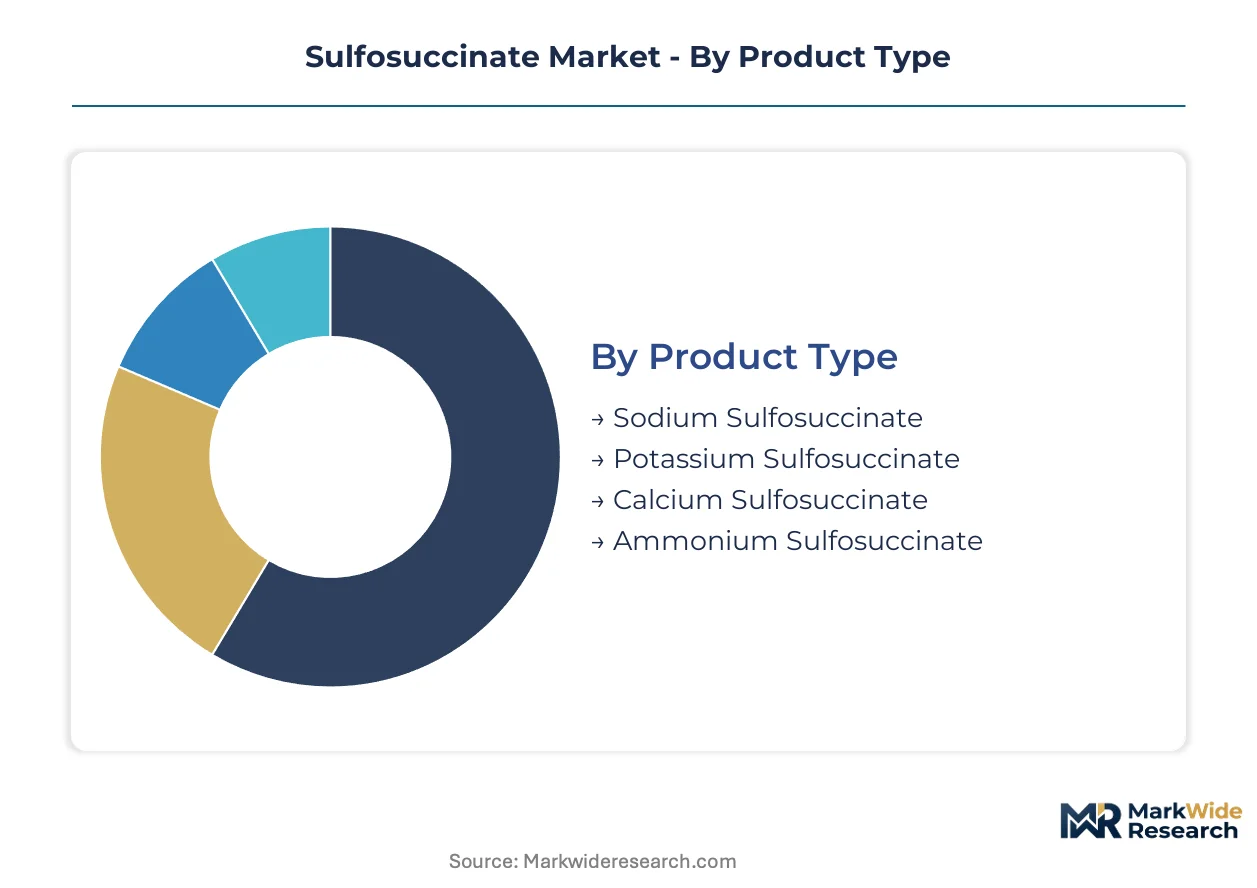
Sulfosuccinate specifications fragment across ionic variants, physical forms, and purity grades that determine end-use eligibility. Formulators select segments based on compatibility matrices with active ingredients, processing equipment constraints, and regional regulatory registration status.
Product Type:
Counterion selection governs solubility profiles and regulatory clearance pathways across pharmaceutical and food-contact applications.
- Sodium Sulfosuccinate:Dominant commercial form manufactured through neutralization with sodium hydroxide, offering broad aqueous solubility and cost-efficient scale production. Personal care formulators in Germany and South Korea specify this grade for shampoo and facial cleanser applications where mildness credentials support dermatological marketing claims.
- Potassium Sulfosuccinate:Produced via potassium hydroxide neutralization, yielding enhanced cold-water solubility and reduced sodium content for electrolyte-sensitive formulations. Pharmaceutical manufacturers in Switzerland and Japan utilize this variant for topical drug delivery systems where cation compatibility with active ingredients is critical.
- Calcium Sulfosuccinate:Calcium salt variant with limited aqueous solubility, primarily specified for oil-phase stabilization in emulsion concentrates.
- Ammonium Sulfosuccinate:Ammonium counterion form offering pH buffering capacity and volatile base characteristics for specialized industrial cleaning formulations.
Sodium sulfosuccinate leads on scale; potassium sulfosuccinate leads on momentum as pharmaceutical-grade demand climbs fastest.
End User:
Customer procurement patterns diverge between specification-intensive regulated sectors and volume-driven consumer goods.
- Personal Care:Largest value-absorbing segment encompassing shampoo, body wash, facial cleanser, and baby care formulations. Formulators specify sulfosuccinates for their exceptional dermatological safety profile and rich foaming characteristics in sensitive-skin positioning. Contract manufacturers in Mumbai and Shanghai consolidate procurement toward REACH-registered suppliers with established SCIP database infrastructure.
- Pharmaceuticals:Premium-tier segment commanding elevated pricing through GMP certification, tightened impurity thresholds, and excipient-grade documentation. Topical drug delivery systems and ophthalmic preparations in Germany and Japan drive qualification cycles that extend 12-18 months due to notified body audit backlogs.
- Agrochemicals:Adjuvant and emulsifier applications for pesticide formulations, where cost efficiency dominates over mildness credentials.
- Food & Beverages:Limited food-contact applications requiring FCC-grade certification and migration testing compliance.
Personal care dominates absolute volume; pharmaceuticals expands most quickly as topical drug delivery complexity increases.
Application:
Functional role selection determines compatibility requirements with co-surfactants, rheology modifiers, and preservation systems.
- Emulsifier:Primary functional deployment leveraging sulfosuccinate amphiphilic structure to stabilize oil-in-water interfaces. Sunscreen and lotion formulators in the United States specify this application for broad-spectrum UV filter compatibility.
- Surfactant:Direct cleansing and foaming applications where mildness differentiates from sulfate-based alternatives. Baby shampoo and sensitive-skin body wash specifications in France and Italy drive this segment's premium positioning.
- Stabilizer:Secondary viscosity and suspension stabilization in complex multi-phase formulations.
- Additive:Minor incorporation as processing aids or dispersion enhancers in industrial chemical manufacturing.
Emulsifier commands the broadest specification base; surfactant gains share fastest as sulfate-free positioning accelerates.
Form:
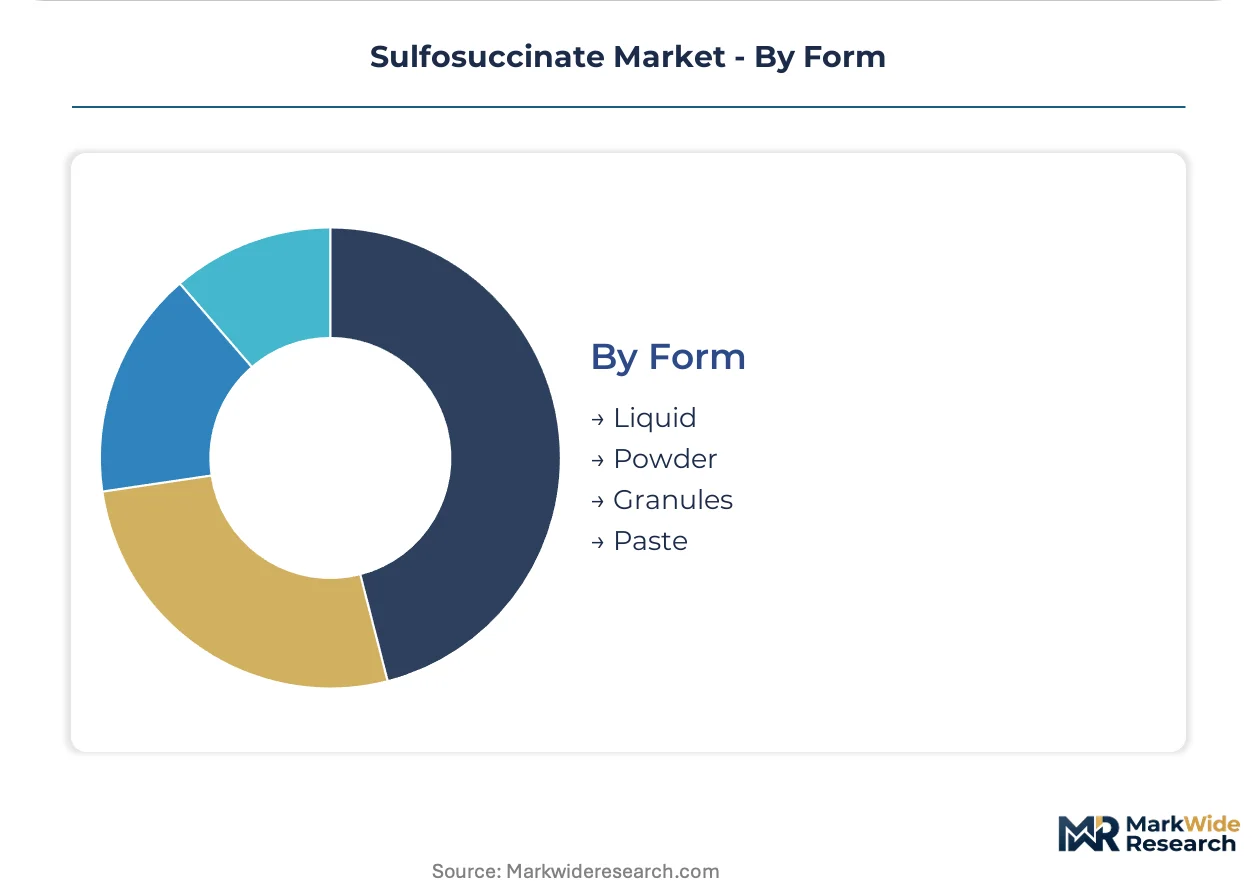
Physical state selection aligns with manufacturing equipment, storage logistics, and dissolution kinetics requirements.
- Liquid:Predominant commercial form offering direct pumpability into continuous manufacturing lines and immediate dissolution kinetics. Personal care contract manufacturers in South Korea and Germany favor liquid sulfosuccinates for reduced handling dust and simplified batch sequencing.
- Powder:Solid-state variant enabling extended shelf stability and reduced shipping costs for long-haul supply chains. Powder specifications concentrate in Indian and Chinese domestic markets where toll manufacturing infrastructure handles dissolution preprocessing.
- Granules:Intermediate particle size for controlled dissolution rate applications in agrochemical emulsion concentrates.
- Paste:High-concentration semisolid form for specialized industrial compounding where viscosity control is critical.
Liquid leads on manufacturing integration; powder leads on logistics efficiency for inland distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical expertise in continuous sulfonation reactor management concentrates in aging workforces across Germany and Japan, anchoring high-purity production capacity in these geographies while emerging manufacturing clusters compete on scale economics.
China
Domestic maleic anhydride production capacity expansion in Jiangsu and Shandong provinces is reducing import dependence for sulfosuccinate feedstocks. MEE dual carbon enforcement tightens energy intensity benchmarks for esterification processes, accelerating consolidation toward integrated producers. The Yangtze River Delta cluster around Shanghai hosts expanding toll manufacturing infrastructure serving personal care contract manufacturers.
Germany
REACH-registered producers leverage established SCIP database infrastructure to capture procurement consolidation among EU personal care formulators. ECHA substance dossier requirements filter subscale competitors from market participation. The North Rhine-Westphalia chemical corridor maintains specialized esterification process engineering capabilities concentrated among legacy technical workforces.
United States
EPA TSCA toxic substance reporting obligations govern sulfosuccinate manufacturing and importation, elevating compliance expenditure for non-domestic suppliers. Personal care contract manufacturers in New Jersey and California specify liquid sulfosuccinate grades for continuous manufacturing integration. The Gulf Coast petrochemical corridor provides naphtha-linked maleic anhydride feedstock access.
India
BIS quality mandate expansion for personal care ingredients is creating certification barriers for unregistered imports. Domestic brand owners in Mumbai and Delhi-NCR outsource formulation development to contract research organizations lacking in-house surfactant screening capabilities. Gujarat's specialty chemical manufacturing belt is developing toll dissolution infrastructure for powder sulfosuccinate preprocessing.
Japan
Pharmaceutical-grade sulfosuccinate demand from topical drug delivery system manufacturers drives GMP certification requirements. METI industrial standards govern chemical manufacturing process documentation. The Kansai region around Osaka maintains concentrated operational expertise in batch-to-batch purity control for excipient-grade specifications.
Sulfosuccinate Market Vendor Landscape
The competitive structure tilts toward integrated petrochemical conglomerates with captive maleic anhydride supply. Three distinct tiers populate the vendor landscape: multinational diversified chemical producers with backward integration into feedstocks, regional specialty surfactant manufacturers with formulation technical service capabilities, and toll processors serving contract manufacturing demand. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing long-term supply agreements with personal care brand owners to defend positioning against substitution pressure from amphoteric surfactants.
Among Germany-based chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated archetype with upstream control over maleic anhydride production. Switzerland-headquartered Clariant AG occupies a position within the specialty tier through geographic diversification of manufacturing assets across multiple regulatory jurisdictions. These three anchors represent contrasting strategic postures: feedstock security versus regulatory agility versus geographic optionality.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Clariant AG |
| Croda International |
| Stepan Company |
| MFG Chemical |
| Solvay |
| KAO Corporation |
| Huntsman Corporation |
| Others |
Supply Flow & Price Mechanics
Specialized esterification process engineers in Germany and Japan anchor high-purity production capacity, widening labor-cost differentials between premium pharmaceutical-grade tiers and standard personal care grades. REACH registration expenditures exceeding EUR 100,000 per substance dossier compress margins for subscale European producers while integrated conglomerates with captive maleic anhydride supply defend pricing power through backward integration into feedstocks.
Pricing Analysis
Bundled technical service and regulatory documentation packages command 40-60% premiums over unbundled commodity grades. Three-tier pricing structure across pharmaceutical excipient, personal care dermatological, and industrial agrochemical grades differentiates by certification intensity and impurity thresholds. Price erosion runs through standard personal care grades as Chinese domestic capacity expansion intensifies volume competition. Contract manufacturers in Mumbai and Shanghai exhibit highest price sensitivity, while Swiss and Japanese pharmaceutical formulators prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-formulator channels handle pharmaceutical-grade demand with GMP audit requirements, while toll manufacturing relationships aggregate personal care volume. Supply concentrates in China, Germany, and the United States, with Jiangsu and Shandong provinces expanding maleic anhydride feedstock self-sufficiency. Maleic anhydride, fatty alcohols, and sulfonating agents constitute critical input dependencies. Single-source vulnerability in pharmaceutical-grade batch-to-batch purity expertise concentrates among aging technical workforces in North Rhine-Westphalia and Osaka-Kansai. Distribution runs through REACH-registered producers with established SCIP database infrastructure for EU-bound shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through pharmaceutical-grade certification penetration, where tightened impurity thresholds command substantial premiums over industrial grades despite equivalent active content.
For Market Incumbents: Lock in long-term supply agreements with personal care brand owners before amphoteric surfactant substitution advances in shampoo and body wash formulations. Deepen backward integration into maleic anhydride production to buffer naphtha-linked feedstock volatility. Secure GMP certification ahead of notified body audit backlogs to capture pharmaceutical excipient tier premiums.
For New Entrants and Emerging Players: Mid-tier Indian personal care brand owners lacking in-house surfactant screening capabilities represent an underserved buyer archetype requiring toll manufacturing partnerships. Target BIS quality mandate compliance ahead of enforcement deadlines to establish first-mover positioning against unregistered imports. Leverage contract research organizations in Mumbai for formulation technical service bundling.
For Investors and Strategic Acquirers: Specialty chemical conglomerates with personal care ingredient portfolios are the most active acquirers in this space, seeking REACH-registered production assets. Five-to-ten year viability hinges on continuous sulfonation reactor technology maturation displacing batch manufacturing. Monitor GMP audit scheduling compression at notified bodies as inflection indicator for pharmaceutical-grade supply tightness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Maleic Anhydride | Captive feedstock supply insulates margin resilience against naphtha price volatility transmitted from Gulf Coast petrochemical corridors. |
| Continuous Sulfonation Reactor Investment | Integrated flow systems reduce solvent recovery costs and improve lot-to-lot consistency for pharmaceutical-grade certification penetration. |
| REACH Registration and SCIP Infrastructure | Substance dossier compliance filters subscale competitors while capturing procurement consolidation among EU personal care formulators. |
| Pharmaceutical-Grade GMP Certification | Tightened impurity thresholds for topical drug delivery systems unlock 40-60% price premiums over industrial grades. |
| Bio-Based Fatty Alcohol Supply Chain Certification | Palm kernel and coconut oil-derived alcohol sourcing aligns with EU Green Deal renewable content claims for premium positioning. |
Methodological Framework
Multiple input streams — technical discussions with plant managers and procurement leads at personal care contract manufacturers, regulatory affairs specialists at ECHA-registered producers, and distribution channel partners — were reconciled against customs and trade data, Cefic sector reports, and SEC 10-K chemical segment disclosures. Bottom-up capacity utilization estimates across Jiangsu, Shandong, and North Rhine-Westphalia production clusters were cross-validated with top-down demand absorption analysis from personal care and pharmaceutical end-use sectors.
Historical volume trajectories were cross-referenced against expert panel assessments of MEE dual carbon enforcement impacts and REACH Article 33 SCIP database implementation timelines. Segmentation modeling spanned counterion variants, purity grades, end-use industries, and regional regulatory clusters. CAGRs were derived from slope consensus across input methodologies. Maleic anhydride feedstock pricing volatility and continuous reactor technology adoption curves served as industry-specific forecast inputs across the projection horizon.
Underlying measurement precision varies by segment; pharmaceutical-grade specifications carry tighter precision than industrial agrochemical grades due to GMP audit documentation availability. Forecasts reflect base assumptions regarding REACH registration cost absorption capacity and MEE energy intensity benchmark enforcement stringency. Periodic stress-testing of base assumptions is recommended against amphoteric surfactant substitution rates and notified body audit scheduling compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Green Surfactants Market
Surfactants
Alkyl Polyglucoside (APG) Surfactant Market
Surfactants
Secondary Alkane Sulfonate Market
Surfactants
Amphoteric Emulsifier Market
Surfactants
Global Methyl Ester Sulfonate Market
Surfactants
Acrylamide Tertiary-Butyl Sulfonic Acid (ATBS) Market
Surfactants
Tetradecyl Chloride Market
Surfactants
Global Amphoteric Surfactants Market
Surfactants
Emulsion Stabilizers Market
Surfactants
Global Sodium Lauryl Sulfate Market
Surfactants
Global Barium Petroleum Sulfonate Market
Surfactants
Cyclotetrasiloxane Market
Surfactants
Soap Salts Market
Surfactants
Global Low Foam Surfactants Market
Surfactants
Cocamidopropyl Betaine Market
Surfactants
Alcohol Ether Sulfates Market