
 Alkyl Polyglycoside (APG) Market | 2026-2036
Alkyl Polyglycoside (APG) Market Size, Share, and Industry Trends Forecast 2026-2036
Alkyl Polyglycoside (APG) Market Outlook
Cosmetic-grade purity specifications are redrawing competitive boundaries in the APG sector. BASF SE leverages integrated glucose and fatty alcohol supply chains to sustain cost leadership in high-specification liquid grades. Clariant AG differentiates through specialized paste formulations for premium personal care accounts. Galaxy Surfactants Ltd anchors South Asian supply with manufacturing scale directed at detergent and industrial cleaning applications.
Alkyl polyglycosides are non-ionic surfactants synthesized from renewable fatty alcohols and glucose via Fischer glycosidation, typically carrying alkyl chain lengths of C8 to C16 and HLB values between 13 and 15 for broad emulsification utility. Their primary commercial purpose centers on replacing petroleum-derived ethoxylates and sulfates in formulations where skin mildness, aquatic biodegradability, and foam stability are co-specified. Liquid APG dominates volume throughput due to compatibility with automated batching systems in household and industrial cleaning, while powder and granule formats command margin premiums in cosmetics and food processing where moisture-free handling and precise dosing are structural requirements. Agricultural application represents the fastest-expanding demand pool as glyphosate adjuvant regulations tighten and biosurfactant drift-control agents gain formulary preference.
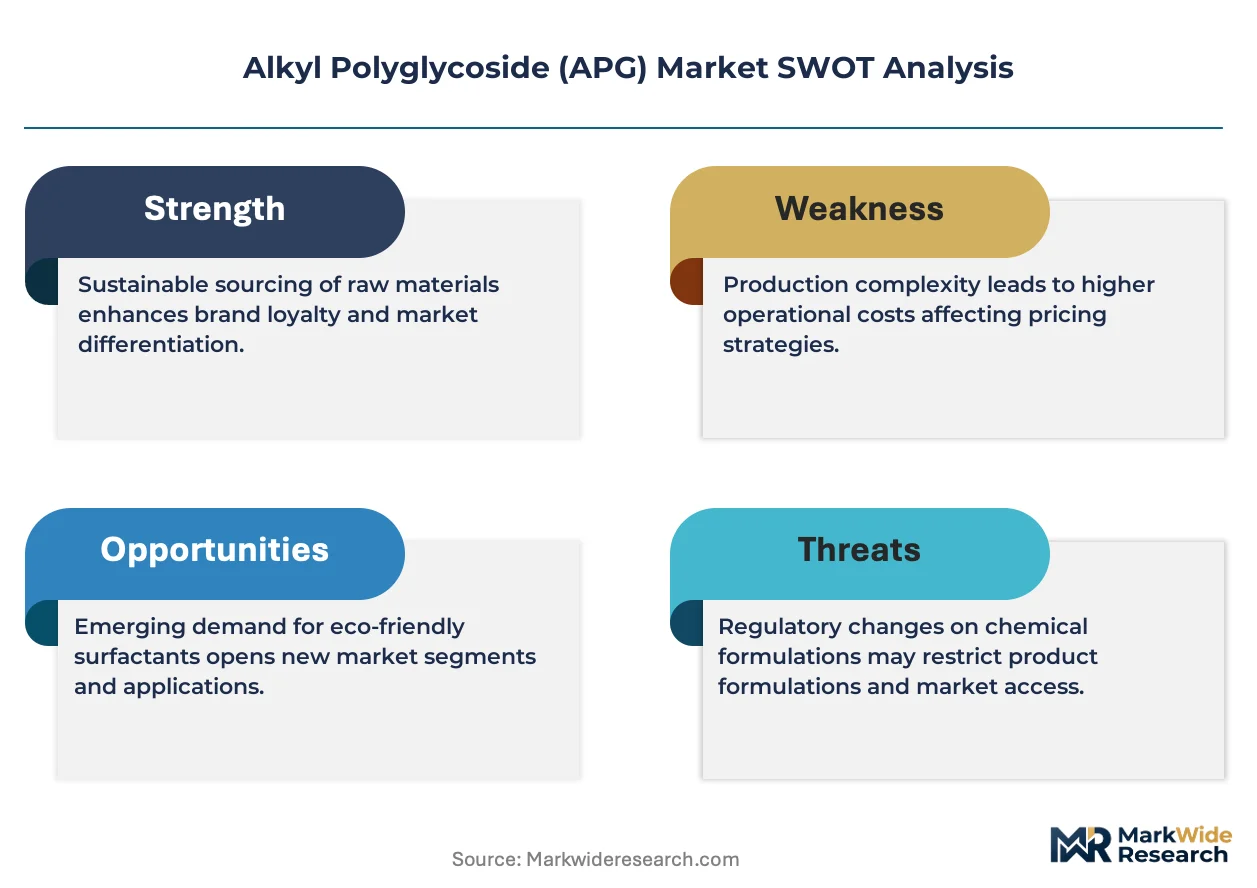
EPA Safer Choice standards and REACH Annex XVII restrictions on nonylphenol ethoxylates are structurally redirecting procurement toward APG-based surfactant systems in North American and European industrial channels. China's GB standards on aquatic toxicity and SAMR labeling requirements for green chemistry claims are similarly elevating APG qualification hurdles for import and domestic formulation. Stakeholders must monitor regulatory divergence between biodegradability testing protocols, as OECD 301B pass criteria in Europe and EPA OPPTS 835.3110 frameworks in the United States create non-harmonized compliance costs that favor suppliers with multi-jurisdictional certification depth.
Market Dynamics
EU REACH Annex XVII restrictions on nonylphenol ethoxylates and EPA Safer Choice mandates are structurally redirecting industrial surfactant procurement toward carbohydrate-based alternatives, compressing reformulation timelines across household and personal care supply chains.
Growth Catalysts
- REACH biodegradability mandates:European manufacturers face binding timelines to eliminate petroleum-derived ethoxylates, accelerating qualification of plant-derived surfactants in industrial cleaning and agrochemical adjuvant applications.
- Personal care formulator rejection of sulfates:Cosmetic brands specify skin-mild, foam-stable alternatives for facial cleansers and baby products, pulling demand toward C8-C14 alkyl chain grades with HLB values between 13 and 15.
- Agricultural drift-control regulations:Glyphosate formulation standards in major producing regions are elevating biosurfactant preference for tank-mix compatibility and aquatic toxicity compliance.
Market Restraints
- Fatty alcohol feedstock volatility:Palm kernel and coconut oil price swings transmit directly to APG production economics, compressing margin visibility for non-integrated compounders.
- Supply concentration in German production clusters:High-purity cosmetic grades depend on concentrated Central European manufacturing assets, creating geographic risk exposure for Asian and North American formulators.
- Technical performance gaps in hard water:APG surfactants exhibit reduced foaming stability above 300 ppm calcium content, limiting penetration in certain industrial cleaning segments where synthetic alternatives maintain functional superiority.
Strategic Opportunities
- Underpenetrated Indian personal care market:Domestic sulfate-free brand expansion creates white space for localized APG production serving mid-tier cosmetic and ayurvedic formulation houses.
- China GB standards on green chemistry labeling:SAMR requirements for biodegradable surfactant claims are elevating import qualification hurdles that favor certified suppliers with multi-jurisdictional testing depth.
- Powder format innovation for food processing:Moisture-free handling requirements in bakery and dairy equipment cleaning open margin-premium positioning currently dominated by legacy phosphate systems.
Industry Challenges
- Fischer glycosidation process engineering talent scarcity:Specialized carbohydrate chemistry expertise concentrates in European and Japanese technical institutes, constraining scale-up velocity for new market entrants.
- Multi-jurisdictional certification timeline compression:Divergent OECD 301B and EPA OPPTS 835.3110 biodegradability testing protocols force redundant study execution, extending product qualification cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkyl Polyglycoside (APG) Market |
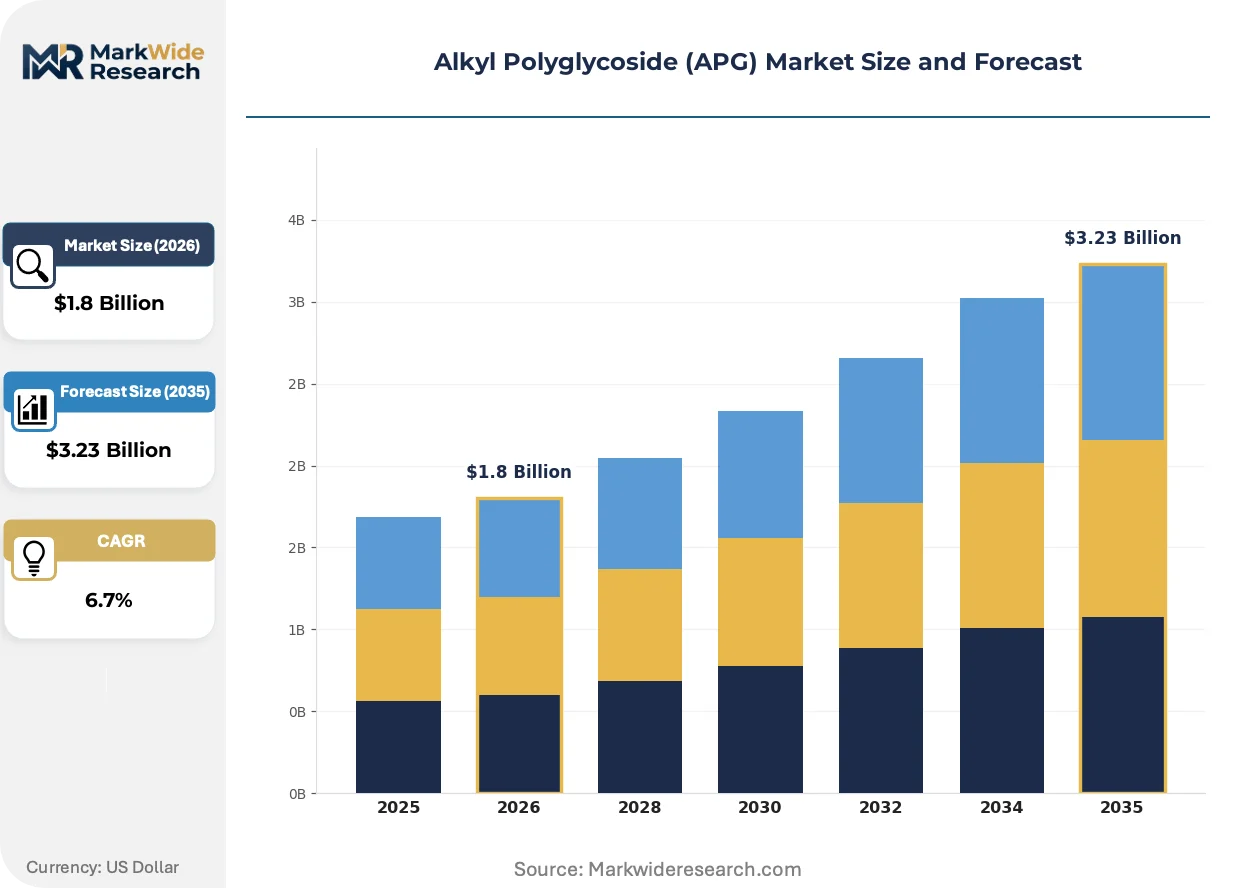
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granule, Paste Application: Household Cleaning, Personal Care, Industrial Cleaning, Agricultural End Use Industry: Cosmetics, Detergents, Food Processing, Textile Formulation Type: Surfactants, Emulsifiers, Solubilizers, Others |
| Companies Covered | BASF SE, Clariant AG, Croda International Plc, Kao Corporation, Galaxy Surfactants Ltd, Dow, SEPPIC, Shanghai Fine Chemical Co., Ltd., Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkyl Polyglycoside (APG) Market Strategic Shifts
Continuous processing technology and enzymatic glycosidation variants are compressing capital intensity and energy consumption in APG manufacturing, while regulatory test method divergence is fragmenting supplier certification strategies across Atlantic and Pacific trade corridors.
Enzymatic glycosidation using immobilized lipase and cellulase biocatalysts is miniaturizing reactor footprints and cutting thermal energy requirements by enabling ambient-temperature synthesis routes. Specialty chemical producers in Japan and South Korea are piloting these systems for cosmetic-grade output. The technology is compressing the minimum efficient scale for viable production, enabling regional hub strategies that reduce freight exposure for liquid surfactant distribution.
EPA Safer Choice standard updates and state-level disclosure requirements in California and New York are forcing reformulation transparency in institutional cleaning contracts. Industrial procurement teams now specify full surfactant composition disclosure, disqualifying complex petroleum-derived ethoxylate blends. North American contract manufacturers are responding by consolidating supplier bases around certified biobased alternatives with third-party validated carbon content claims.
Direct raw material sourcing from glucose refiners and fatty alcohol producers is displacing traditional distributor intermediaries in large-volume household detergent accounts. Procter & Gamble and Unilever procurement teams in Germany and the United States are negotiating multi-year toll manufacturing arrangements that guarantee supply security and price predictability. This channel compression is most visible in C12-C14 liquid grades where annual offtake volumes exceed 5,000 metric tons.
Alkyl Polyglycoside (APG) Market Segmentation
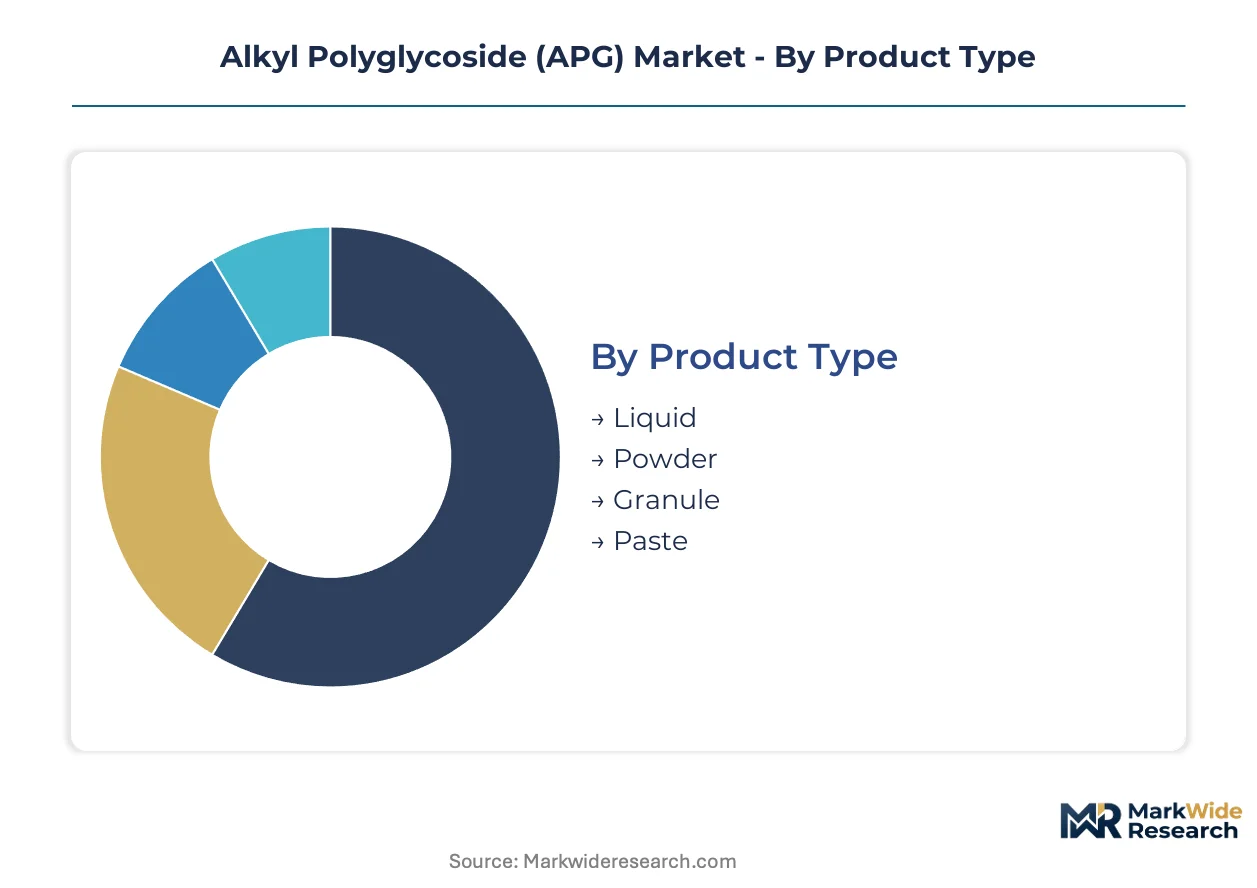
APG market segmentation reveals divergent supply chain configurations across physical formats and end-use specifications. Product type and application splits expose which segments travel as bulk liquid tankers versus specialized powder shipments, reshaping logistics economics and regional sourcing strategies.
Product Type:
Liquid grades dominate export volumes to detergent and industrial cleaning markets, while powder and paste formats serve domestic cosmetic and food processing channels with tighter purity requirements.
- Liquid:C8-C16 alkyl chain solutions with HLB values of 13-15 serve automated batching systems in household and industrial cleaning. Demand concentrates in Germany and the United States where Procter & Gamble and Unilever procurement teams negotiate multi-year toll manufacturing arrangements exceeding 5,000 metric tons annually.
- Powder:Moisture-free granules command margin premiums in cosmetics and food processing where precise dosing and extended shelf stability are mandatory. Bakery and dairy equipment cleaning applications in France and Switzerland favor this format for compatibility with dry-blend sanitation protocols.
- Granule:Intermediate density particles bridge liquid and powder handling requirements in regional detergent compounding operations across India and Brazil.
- Paste:High-viscosity formulations with specialized rheology profiles target premium personal care accounts in Japan and South Korea where sensory texture specifications are stringent.
Liquid holds the largest share; momentum sits with powder as food-grade certification requirements tighten across European processing facilities.
Application:
Cost tier differentiation separates commodity household cleaning from premium personal care and regulated agricultural adjuvant specifications.
- Household Cleaning:Volume throughput concentrates in C12-C14 liquid grades for laundry and hard surface formulations. REACH Annex XVII ethoxylate restrictions in Germany and France are accelerating reformulation timelines across European private label manufacturers.
- Personal Care:Facial cleansers and baby products specify C8-C14 grades with enhanced foam stability and skin mildness profiles. Sulfate-free brand expansion in India creates white space for localized APG production serving mid-tier cosmetic and ayurvedic formulation houses.
- Industrial Cleaning:Hard water compatibility limitations above 300 ppm calcium content constrain penetration in certain metal finishing and precision equipment segments where synthetic alternatives maintain functional superiority.
- Agricultural:Glyphosate adjuvant regulations in the United States and Brazil are elevating biosurfactant preference for tank-mix compatibility and aquatic toxicity compliance under EPA and national environmental agency frameworks.
Household cleaning commands volume leadership; agricultural applications are climbing the fastest as drift-control regulations tighten in major producing regions.
End Use Industry:
Customer type fragmentation separates multinational procurement teams from specialized regional formulators with distinct technical service requirements.
- Cosmetics:Cosmetic-grade purity specifications with residual glucose and fatty alcohol limits below 0.5% serve facial care and baby product lines. ECHA REACH compliance documentation is mandatory for European market access.
- Detergents:Standard-grade liquid APG serves commodity laundry and dish formulations with less stringent color and odor specifications.
- Food Processing:Equipment cleaning applications in dairy and bakery operations require NSF registration and kosher/halal certification for North American and Middle Eastern market access.
- Textile:Scouring and wetting applications in fabric preparation specify APG emulsifiers as alternatives to banned alkylphenol ethoxylates under EU and Chinese GB standards.
Detergents retain the dominant position; cosmetics is gaining share fastest as sulfate-free positioning accelerates across premium personal care brands.
Formulation Type:
Margin structure varies sharply across functional roles, with surfactants capturing volume and emulsifiers extracting premium pricing for technical complexity.
- Surfactants:Primary cleansing and foaming functions in detergent and personal care formulations represent the baseline commercial application with established supply chains.
- Emulsifiers:Oil-water interface stabilization for cosmetic creams and agricultural oil dispersions demands precise HLB matching and batch consistency documentation.
- Solubilizers:Fragrance and active ingredient incorporation into aqueous systems serves niche personal care and pharmaceutical auxiliary applications.
- Others:Wetting agents and dispersants in industrial and agricultural adjuvant formulations complete the functional spectrum.
Surfactants maintain volume dominance; emulsifiers show the steepest expansion trajectory as cosmetic formulation complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity APG production clusters in Germany concentrate supply for European and North American formulators. Asian manufacturing scales serve detergent and industrial cleaning demand across emerging markets. Regional regulatory divergence on biodegradability testing creates compliance friction for multinational suppliers.
Germany
REACH Annex XVII ethoxylate restrictions accelerate reformulation timelines for household and personal care manufacturers. BASF SE and Clariant AG anchor production clusters in Ludwigshafen and Muttenz for cosmetic-grade liquid and paste grades. Procter & Gamble procurement teams negotiate multi-year toll manufacturing arrangements exceeding 5,000 metric tons annually.
United States
EPA Safer Choice mandates redirect institutional cleaning procurement toward certified biobased surfactants with third-party validated carbon content claims. State-level disclosure requirements in California and New York force full surfactant composition transparency in contract specifications. Midwest and Gulf Coast formulators consolidate supplier bases around multi-jurisdictional certified alternatives.
China
GB standards on aquatic toxicity and SAMR labeling requirements for green chemistry claims elevate import qualification hurdles for APG suppliers. Domestic sulfate-free personal care brand expansion creates demand for localized C8-C14 grade production. Yangtze River Delta chemical parks host glucose and fatty alcohol integration projects serving mid-tier cosmetic houses.
India
Underpenetrated personal care markets present white space for localized APG production serving ayurvedic and mid-tier cosmetic formulation houses. BIS standards on biodegradable surfactants are tightening parallel to import substitution policies. Gujarat and Maharashtra industrial corridors attract capacity investments for detergent-grade liquid outputs.
Brazil
Glyphosate adjuvant regulations elevate biosurfactant preference for tank-mix compatibility in agricultural applications. ANVISA oversight of cosmetic ingredient safety creates certification pathways for imported cosmetic-grade materials. São Paulo and Rio Grande do Sul host regional compounding operations for Latin American detergent distribution.
Alkyl Polyglycoside (APG) Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes in the APG sector. Integrated petrochemical giants with captive glucose and fatty alcohol supply chains dominate high-volume liquid grades for detergent applications. Specialized surfactant houses command premium positioning in cosmetic-grade pastes and powders. Competitive dynamics center on backward integration into feedstock supply and multi-jurisdictional certification depth for regulatory compliance.
Within the integrated chemical conglomerate tier, BASF SE and Clariant AG exemplify archetypes combining feedstock control with high-purity process expertise. Croda International Plc occupies a position among specialty surfactant houses focused on premium personal care and pharmaceutical-grade specifications. Galaxy Surfactants Ltd represents the regional scale specialist archetype, anchoring South Asian supply with manufacturing directed at detergent and industrial cleaning volume segments.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Croda International Plc |
| Kao Corporation |
| Galaxy Surfactants Ltd |
| Dow |
| SEPPIC |
| Shanghai Fine Chemical Co., Ltd. |
| Huntsman Corporation |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XVII biodegradability mandates gate both supplier qualification and price tier separation simultaneously, forcing non-certified compounders out of premium channels while rewarding multi-jurisdictional certification depth with margin premiums in cosmetic and agricultural adjuvant segments.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across the European APG market. Three-tier pricing stratifies across cosmetic-grade, industrial-grade, and detergent-grade certification levels, with residual glucose and fatty alcohol limits below 0.5% commanding substantial premiums. Price differentiation rests on HLB precision and multi-jurisdictional OECD 301B plus EPA OPPTS 835.3110 certification depth. Cost compression in standard-grade liquid outputs is intensifying because palm kernel and coconut oil feedstock volatility transmits directly to non-integrated producers. Detergent manufacturers exhibit highest price sensitivity, while cosmetic formulators prioritize batch consistency over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for glucose and fatty alcohol feedstocks. Supply concentrates in Germany, China, and India, with Ludwigshafen and Muttenz anchoring high-purity cosmetic grades while Yangtze River Delta and Gujarat corridors scale detergent-grade outputs. Raw material dependencies draw from palm kernel oil, coconut oil, and glucose refiners. Single-source vulnerability in German high-purity production clusters creates geographic risk exposure for North American and Asian formulators. Distribution runs through toll manufacturing arrangements exceeding 5,000 metric tons annually for liquid grades, while powder formats move through specialized chemical distributors serving cosmetics and food processing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and formulation support services are expanding faster than commodity surfactant sales, creating recurring-revenue layers that attach to long-term supply agreements.
For Market Incumbents: Secure captive glucose and fatty alcohol supply chains through backward integration or multi-year toll arrangements to defend against feedstock volatility. Lock in multi-jurisdictional certification depth across OECD 301B and EPA OPPTS 835.3110 protocols before regulatory timeline compression extends qualification cycles. Capacity addition in India serves sulfate-free personal care brand expansion while reducing freight exposure to South Asian detergent markets. For New Entrants and Emerging Players: Differentiate on enzymatic glycosidation technology for ambient-temperature synthesis routes that compress capital intensity and enable regional hub strategies. Target underpenetrated Indian personal care markets where domestic ayurvedic and mid-tier cosmetic houses lack localized APG supply. Pursue powder format innovation for food processing applications as moisture-free handling requirements tighten across European dairy and bakery equipment cleaning protocols. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across enzymatic glycosidation pilot systems as immobilized biocatalyst technology miniaturizes reactor footprints. Long-term viability over the next decade favors suppliers with integrated feedstock control and certification depth rather than pure-play compounders exposed to margin compression. Acquisition target archetype: regional scale specialists with established toll manufacturing relationships and pending multi-jurisdictional certification completion. Signal to monitor: state-level disclosure requirements in California and New York forcing surfactant composition transparency in institutional cleaning contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | BASF SE and Clariant AG anchor cost leadership through captive glucose and fatty alcohol control. |
| Enzymatic Glycosidation Scale-Up | Japanese and South Korean pilot systems compress minimum efficient scale for regional hub deployment. |
| Multi-Jurisdictional Certification Investment | Dual OECD 301B and EPA OPPTS 835.3110 qualification accelerates product entry into trans-Atlantic procurement channels. |
| Powder Format Capacity Addition | Moisture-free granule production captures margin premiums in European food-grade equipment cleaning segments. |
| Long-Term Toll Manufacturing Arrangement | Procter & Gamble procurement teams negotiate supply security exceeding 5,000 metric tons annually in Germany and the United States. |
Study Parameters
Cross-validation between primary interviews with plant managers, procurement leads at downstream detergent and personal care OEMs, distribution channel partners, and technical R&D directors anchors the qualitative findings. Secondary validation draws from customs and trade data, Cefic sector reports, SEC 10-K filings, and ECHA REACH registration databases. Bottom-up capacity and utilization estimates triangulate against top-down demand modeling across end-use industries.
Sensitivity analysis informs the analytical framework across the projection horizon. Segmentation dimensions modeled include physical format tier, end-use application, alkyl chain length specification, and regional production hub configuration. CAGRs derive from weighted average growth trajectories across household cleaning, personal care, industrial cleaning, and agricultural adjuvant demand pools. Forecast inputs incorporate Fischer glycosidation process economics, fatty alcohol feedstock price indices, and regulatory timeline compression effects.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement and EPA Safer Choice mandate expansion would require recalibration. Forecasts reflect assumptions on enzymatic technology scale-up velocity and palm kernel oil price stabilization. Practitioners should keep alternative scenarios live as GB standards on aquatic toxicity and SAMR labeling requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Polysorbate 40 Market
Surfactants
Global Low Foam Surfactants Market
Surfactants
Dispersant Market
Surfactants
Global Fluorosurfactants Market
Surfactants
Pharmaceutical Surfactants Market
Surfactants
Green Surfactants Market
Surfactants
Alkyl Polyglucoside (APG) Surfactant Market
Surfactants
Sodium Methyl Cocoyl Taurate Market
Surfactants
Global Barium Petroleum Sulfonate Market
Surfactants
Global Thioglycolic Acid Market
Surfactants
Secondary Alkane Sulfonate Market
Surfactants
Soap Salts Market
Surfactants
Global Detergent Polymers Market
Surfactants
Wetting Agents Market
Surfactants
Sodium Naphthalene Sulphonate Formaldehyde Market
Surfactants
Sodium Lauryl Sulphate Market