
 Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market | 2026-2036
Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market Foresight
Waterborne coatings is hardening as the dominant demand vertical, displacing legacy solvent systems in automotive OEM and architectural segments. BASF SE leverages its integrated acrylic acid backbone to sustain cost-advantaged HASE supply across European coating clusters. Dow Chemical Company anchors North American volume through direct partnerships with regional paint manufacturers. Arkema Group differentiates via specialty rheology modifiers for high-shear industrial applications.
Hydrophobically Modified Alkali Swellable Emulsion comprises acrylic copolymer particles with hydrophobic pendant groups that swell upon neutralization to yield pseudoplastic flow control in aqueous systems, typically achieving Brookfield viscosities of 2,000–20,000 cP at low shear. Industrial Grade HASE dominates current volume owing to its penetration in construction chemicals and textile processing, while Cosmetic Grade commands premium pricing in personal care formulations where sensory performance justifies higher unit costs. Pharmaceutical Grade remains nascent, constrained by excipient qualification timelines and pharmacopeial compliance burdens.
EPA VOC regulations under 40 CFR Part 59 and REACH Annex XVII restrictions on hazardous substance content compel coating formulators to validate HASE-based low-VOC architectures, directly expanding addressable demand. ECHA substance evaluation protocols and FDA 21 CFR indirect food contact standards further segment product qualification requirements by end-use jurisdiction. Stakeholders must monitor regulatory divergence between EU Green Deal chemical sustainability targets and emerging state-level disclosure mandates in the United States to anticipate reformulation cycle timing and qualification cost trajectories.
Market Dynamics
Waterborne coating mandates under EPA 40 CFR Part 59 and REACH Annex XVII are compressing solvent-system margins while concentrating HASE procurement among qualified suppliers with validated low-VOC architectures. This regulatory compression is restructuring formulation partnerships across automotive OEM and architectural segments.
Growth Catalysts
- REACH Annex XVII hazardous substance limits:European coating formulators face compulsory reformulation timelines, expanding validated HASE demand for architectural and industrial applications.
- Automotive OEM waterborne transition:Assembly plants in Germany, the United States, and Japan are phasing solvent-borne basecoats, requiring rheology modifiers compatible with high-speed robotic application.
- China construction chemicals scale-up:Domestic paint producers are building captive HASE capacity for cementitious admixtures and waterproofing membranes.
Market Restraints
- Acrylic acid feedstock volatility:Propylene cost swings transmit directly to HASE copolymer economics, compressing margin predictability for non-integrated producers.
- Pharmaceutical Grade qualification timelines:FDA 21 CFR excipient validation and USP-NF certification cycles extend 18-36 months, blocking near-term revenue in high-margin drug delivery applications.
- Cellulosic thickener substitution:Hydroxyethyl cellulose retains cost advantage in mid-shear architectural coatings, limiting HASE penetration in price-sensitive decorative segments.
Strategic Opportunities
- India construction chemicals underpenetration:BIS certification requirements and infrastructure investment under the PLI scheme create first-mover positioning for technical-grade HASE suppliers.
- EU Green Deal chemical sustainability targets:ECHA substance evaluation protocols favor bio-based hydrophobe architectures, rewarding early reformulation investment with preferred supplier status.
- Digital tinting system integration:Point-of-sale color matching in retail paint channels demands pseudoplastic flow control compatible with automated dispensing equipment.
Industry Challenges
- Rheology modifier formulation expertise scarcity:Compound knowledge bridging polymer science and coating application engineering concentrates among senior technologists at established suppliers.
- Multi-jurisdiction compliance synchronization:Divergent EPA, ECHA, and NMPA substance notification requirements force parallel qualification tracks for global coating formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market |
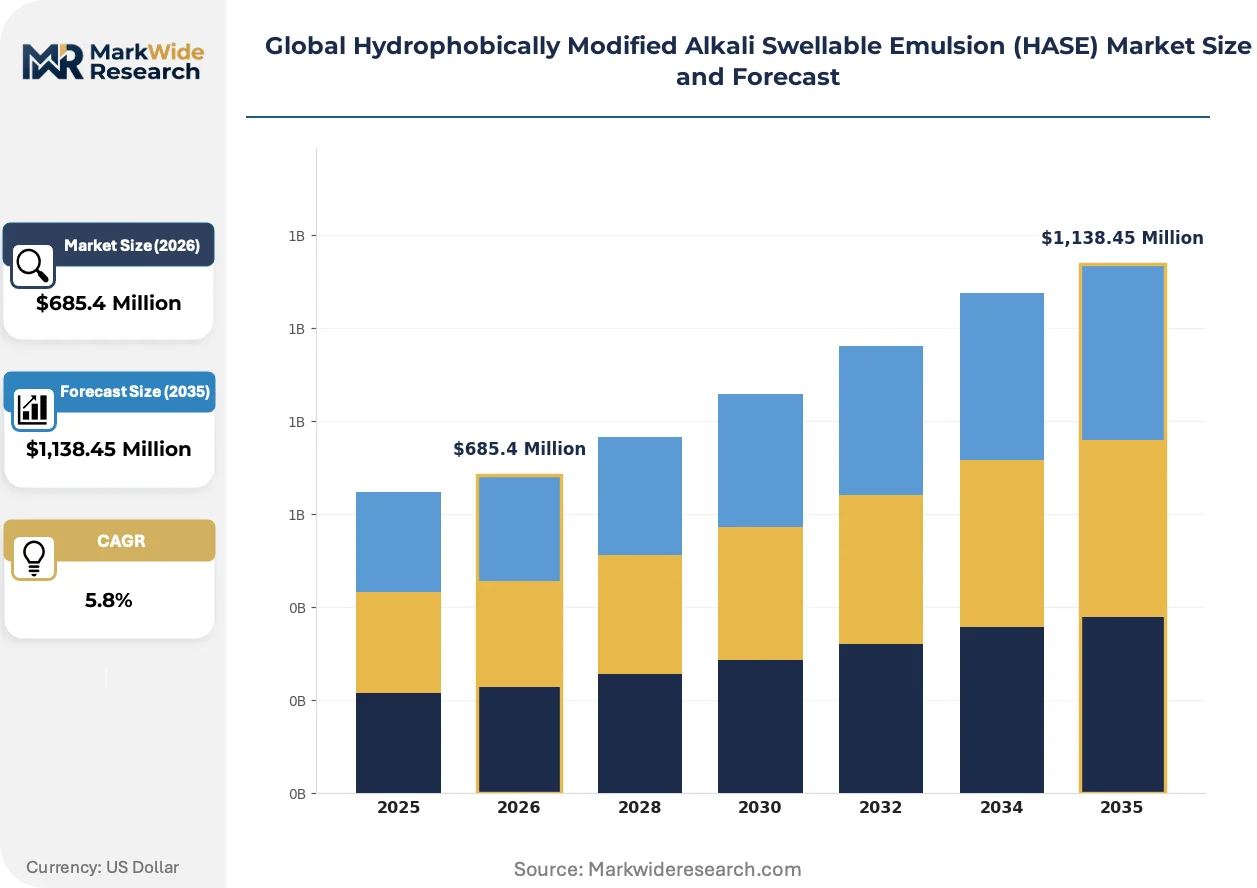
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Grade, Industrial Grade, Pharmaceutical Grade, Agricultural Grade Application: Waterborne Coatings, Adhesives & Sealants, Personal Care, Construction Chemicals, Textile Processing End User Industry: Paint Manufacturers, Personal Care Manufacturers, Construction Services, Textile Processors Packaging Type: Drums, Totes, Bags, Pails, Intermediate Bulk Containers |
| Companies Covered | BASF SE, Dow Chemical Company, Arkema Group, Lubrizol Corporation, Akzo Nobel N.V., Scott Bader Company Ltd., 3V Sigma S.P.A, DuPont, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market Shifts & Advancements
Acid-swellable emulsion technology is fragmenting along performance-tier lines as end-users demand application-specific viscosity profiles rather than universal thickeners. This specialization is compressing commodity margins while opening premium positioning for tailored architectures.
Associative thickener technology with tunable hydrophobe chain length is decentralizing rheology control from centralized additive houses toward integrated coating manufacturers. Automotive OEM labs in Stuttgart, Detroit, and Toyota City are developing captive HASE variants optimized for specific basecoat chemistries. This insourcing trend is compressing merchant supplier volumes in high-specification segments while elevating technical service requirements.
EPA 40 CFR Part 59 Subpart D architectural coating VOC limits are forcing reformulation investments across North American decorative paint producers. The regulation's 100 g/L ceiling for flat coatings and 150 g/L for non-flat systems eliminates legacy solvent-borne thickeners from compliant formulations. California Air Resources Board companion rules extend these constraints, making HASE-based architectures mandatory for shelf distribution in the United States' largest state economy.
Specification-driven procurement is consolidating buyer power among multinational coating formulators with centralized technical approval authority. Regional paint manufacturers in Italy, South Korea, and Brazil now face tier-1 supplier qualification barriers that favor established HASE producers with documented regulatory dossiers. This consolidation is compressing spot-market spot purchases while lengthening contract durations for approved suppliers.
Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market Segmentation
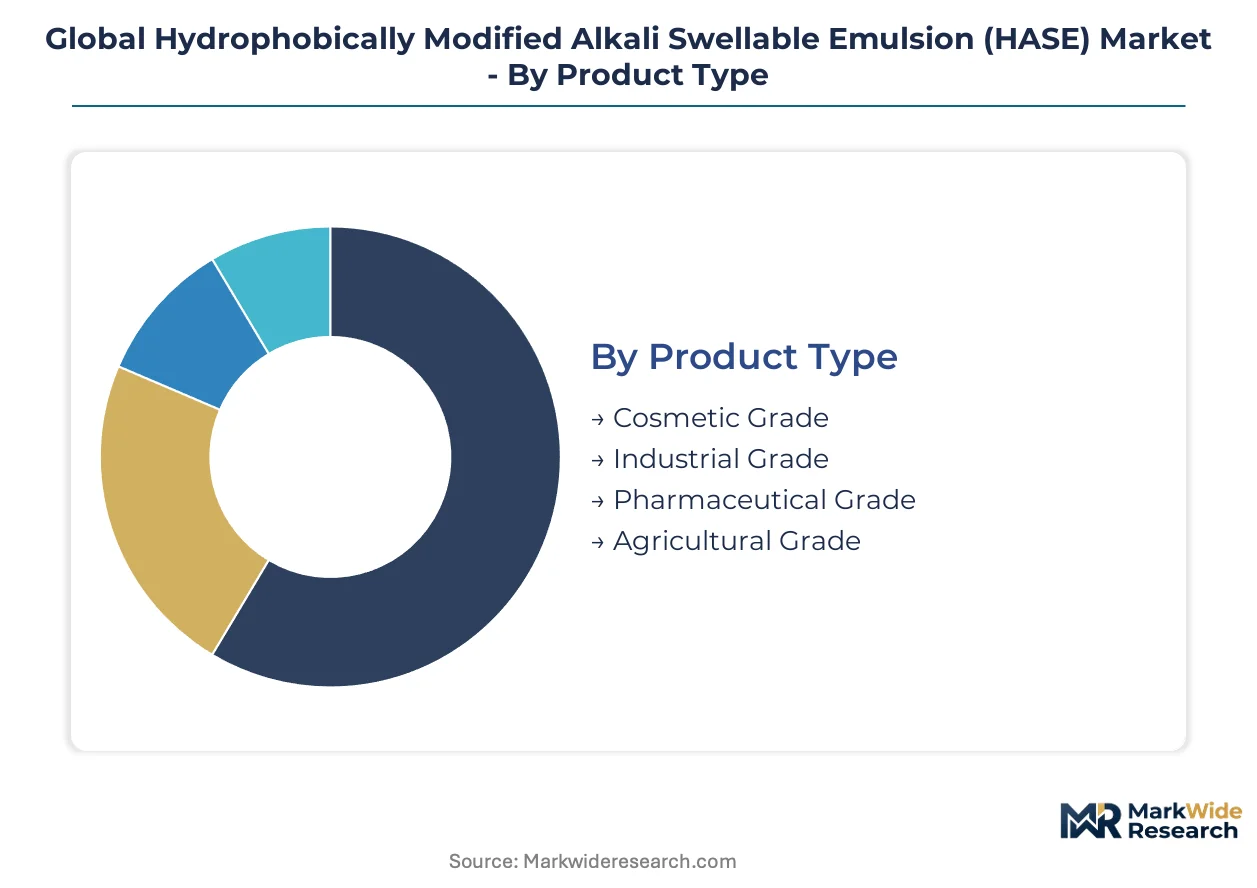
HASE procurement patterns diverge sharply across end-use specifications, with coating formulators prioritizing viscosity stability under shear while personal care buyers emphasize sensory performance and regulatory dossier completeness. Understanding these segment-specific qualification barriers enables suppliers to align technical service investments with margin architecture.
Product Type:
Cost tier separates buyers in this category, with qualification burden and raw material purity driving price stratification across three distinct commercial layers.
- Industrial Grade:Acrylic copolymer emulsions with moderate hydrophobe density serve construction chemicals and textile processing where Brookfield viscosity targets of 5,000–15,000 cP predominate. Demand concentrates in China as domestic cementitious admixture producers scale captive formulation capacity under infrastructure investment programs.
- Cosmetic Grade:Refined hydrophobe architectures with low residual monomer content command premium positioning in personal care formulations, where sensory performance and EU Cosmetics Regulation compliance justify higher unit economics. European and Japanese personal care manufacturers drive specification intensity through ECHA substance evaluation protocols.
- Pharmaceutical Grade:USP-NF excipient validation and FDA 21 CFR compliance constrain supply to qualified polymer houses with documented pharmacopeial dossiers.
- Agricultural Grade:Cost-optimized emulsions for agrochemical suspension concentrates prioritize shear-thinning stability over sensory attributes.
Volume sits with Industrial Grade; growth tilts toward Cosmetic Grade.
Application:
Application maturity determines supplier engagement model, with established coating channels rewarding scale while emerging personal care segments demand technical partnership depth.
- Waterborne Coatings:Dominant demand vertical encompassing architectural paints and automotive basecoats requiring pseudoplastic flow control compatible with high-speed application equipment. EPA 40 CFR Part 59 and REACH Annex XVII VOC mandates are compressing solvent-borne alternatives across Germany, the United States, and Japan.
- Construction Chemicals:Cementitious admixtures and waterproofing membranes utilize HASE for workability retention in pumped concrete and self-leveling underlayments. Chinese infrastructure investment and India's PLI scheme for construction materials are expanding addressable demand.
- Adhesives & Sealants:Pressure-sensitive and construction adhesive formulations employ associative thickening for sag resistance and open-time control.
- Personal Care:Skin care and hair care applications leverage HASE for texture modulation and suspension stability in aqueous systems.
- Textile Processing:Pigment printing pastes and finishing baths utilize viscosity control for uniform substrate coverage.
Revenue concentration favors Waterborne Coatings; Construction Chemicals are expanding most quickly.
End User Industry:
Customer scale and technical capability determine procurement centralization, with multinational formulators consolidating supplier panels while regional processors retain spot-market flexibility.
- Paint Manufacturers:Tier-1 automotive OEM and architectural coating formulators in Stuttgart, Detroit, and Toyota City demand validated low-VOC architectures with documented regulatory dossiers. Specification-driven procurement is lengthening contract durations for approved HASE suppliers.
- Construction Services:Regional cementitious admixture blenders in China and India prioritize cost-competitive technical grades with local technical support.
- Personal Care Manufacturers:European and Japanese cosmetic houses emphasize ECHA and MHLW compliance with sensory performance validation.
- Textile Processors:Dyeing and finishing houses in South Korea and Brazil utilize HASE for process efficiency in pigment printing applications.
Procurement scale aggregates with Paint Manufacturers; qualification intensity peaks with Personal Care Manufacturers.
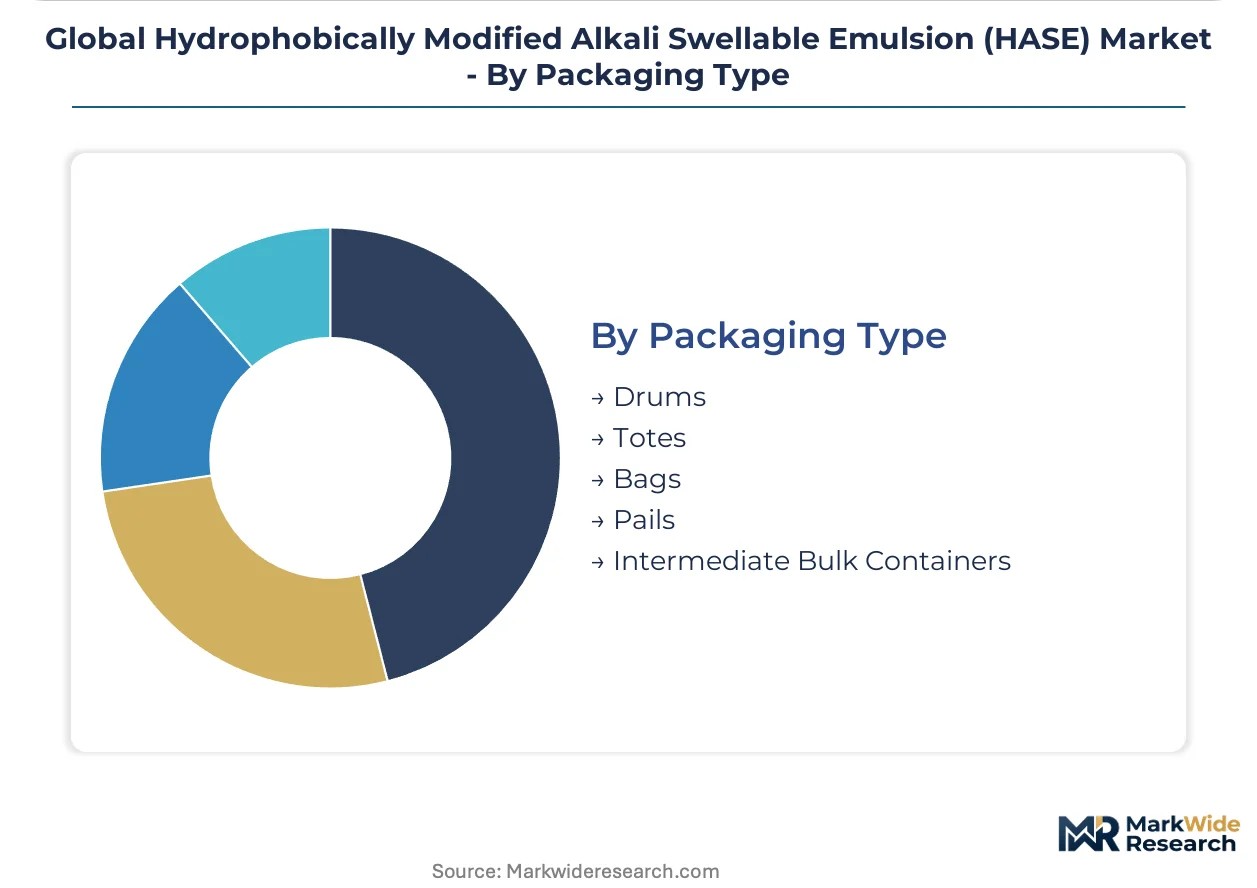
Packaging Type:
Volume scale and logistics infrastructure shape packaging selection, with bulk formats dominating integrated manufacturing while smaller units serve distributed processing networks.
- Drums:Standard 200-liter steel and plastic drums serve mid-volume coating formulators and construction chemical blenders with established material handling infrastructure.
- Totes:Intermediate bulk containers of 1,000-liter capacity reduce packaging waste for high-throughput paint manufacturing facilities.
- Intermediate Bulk Containers:Returnable IBC systems support just-in-time delivery programs for multinational coating clusters with closed-loop logistics.
- Pails:20–25 liter containers address specialty adhesive and sealant compounders with batch-scale formulation requirements.
- Bags:Flexible intermediate bulk bags accommodate powder-grade HASE derivatives for dry-mix construction chemical applications.
Shipment volume concentrates in Drums and Totes; sustainability pressure favors Intermediate Bulk Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones along China's eastern seaboard concentrate HASE manufacturing capacity, with bonded logistics parks in Shanghai and Ningbo offering tariff exemptions on acrylic acid imports. These zones anchor regional supply chains serving coating clusters across Asia-Pacific.
China
Domestic paint producers in Jiangsu and Guangdong provinces are scaling technical-grade HASE capacity for cementitious admixtures and waterproofing membranes. MEE enforcement of dual carbon goals is accelerating waterborne coating transitions in automotive OEM plants. The Yangtze River Delta coating cluster around Shanghai supplies BASF SE and Dow Chemical Company production facilities serving construction chemical blenders.
United States
Automotive assembly plants in Michigan and Ohio are phasing solvent-borne basecoats under EPA 40 CFR Part 59 Subpart D VOC ceilings. The California Air Resources Board extends these constraints to 100 g/L for flat coatings, mandating HASE architectures for shelf distribution. Detroit-area coating formulators are consolidating supplier panels around qualified low-VOC rheology modifier vendors.
Germany
Automotive OEM labs in Stuttgart and Wolfsburg demand pseudoplastic flow control compatible with high-speed robotic application systems. REACH Annex XVII hazardous substance limits compel architectural coating reformulation timelines across Bavaria and North Rhine-Westphalia. ECHA substance evaluation protocols favor suppliers with documented regulatory dossiers for preferred supplier status.
India
Infrastructure investment under the PLI scheme for construction materials is expanding addressable demand for technical-grade HASE in cementitious applications. BIS certification requirements create qualification barriers favoring established suppliers over spot-market entrants. Gujarat and Maharashtra industrial corridors are attracting first-mover positioning from multinational rheology modifier producers.
Japan
Personal care manufacturers in Osaka and Tokyo prefectures emphasize MHLW compliance with sensory performance validation for cosmetic-grade HASE. METI industrial standards guide pharmaceutical-grade excipient qualification timelines extending 18-36 months. The Kanto region's cosmetic houses drive specification intensity through pharmacopeial dossier requirements.
Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market Competitive Landscape
Top-tier vendors anchor integrated petrochemical supply chains, while specialty chemical houses occupy formulation-intensive niches. The market structure stratifies across three tiers: multinational polymer producers with captive acrylic acid supply, regional emulsion specialists with construction chemical focus, and niche players serving personal care qualification requirements. Two dominant competitive moves are reshaping positioning: backward integration into propylene feedstock by integrated producers, and strategic partnerships between coating formulators and qualified HASE suppliers for regulatory dossier sharing.
Within the integrated multinational tier, BASF SE and Dow Chemical Company exemplify scale-driven positioning through petrochemical backbone control. Arkema Group occupies a specialty-focused position emphasizing high-shear industrial applications. These three anchors represent distinct competitive archetypes: feedstock-integrated volume leadership, regional partnership density, and performance-tier premium positioning respectively.
| Leading Market Players |
|---|
| BASF SE |
| Dow Chemical Company |
| Arkema Group |
| Lubrizol Corporation |
| Akzo Nobel N.V. |
| Scott Bader Company Ltd. |
| 3V Sigma S.P.A |
| DuPont |
| Celanese Corporation |
| Others |
Supply & Pricing Matrix
Propylene price index volatility cascades through acrylic acid copolymer economics, compressing margin buffers for non-integrated HASE producers while amplifying pricing power for feedstock-integrated multinationals serving European and North American coating clusters.
Pricing Analysis
Short lead-time premiums separate contract holders from spot purchasers in the HASE procurement landscape. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades reflects qualification burden divergence, with FDA 21 CFR excipient validation justifying substantial premiums. Cost compression in technical-grade segments is intensifying because Chinese domestic producers are scaling captive capacity. Regional construction chemical blenders exhibit highest price sensitivity, while personal care manufacturers prioritize regulatory dossier completeness over unit cost.
Supply Chain Analysis
Returnable intermediate bulk container programs are reshaping logistics economics for multinational coating formulators with closed-loop infrastructure. Manufacturing concentrates in China, Germany, and the United States, with propylene and acrylic acid feedstock drawing from Gulf Coast and Rotterdam petrochemical complexes. Single-source vulnerability runs through concentrated acrylic acid supply from integrated polymer houses. Distribution runs through direct partnerships with tier-1 paint manufacturers and construction chemical blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
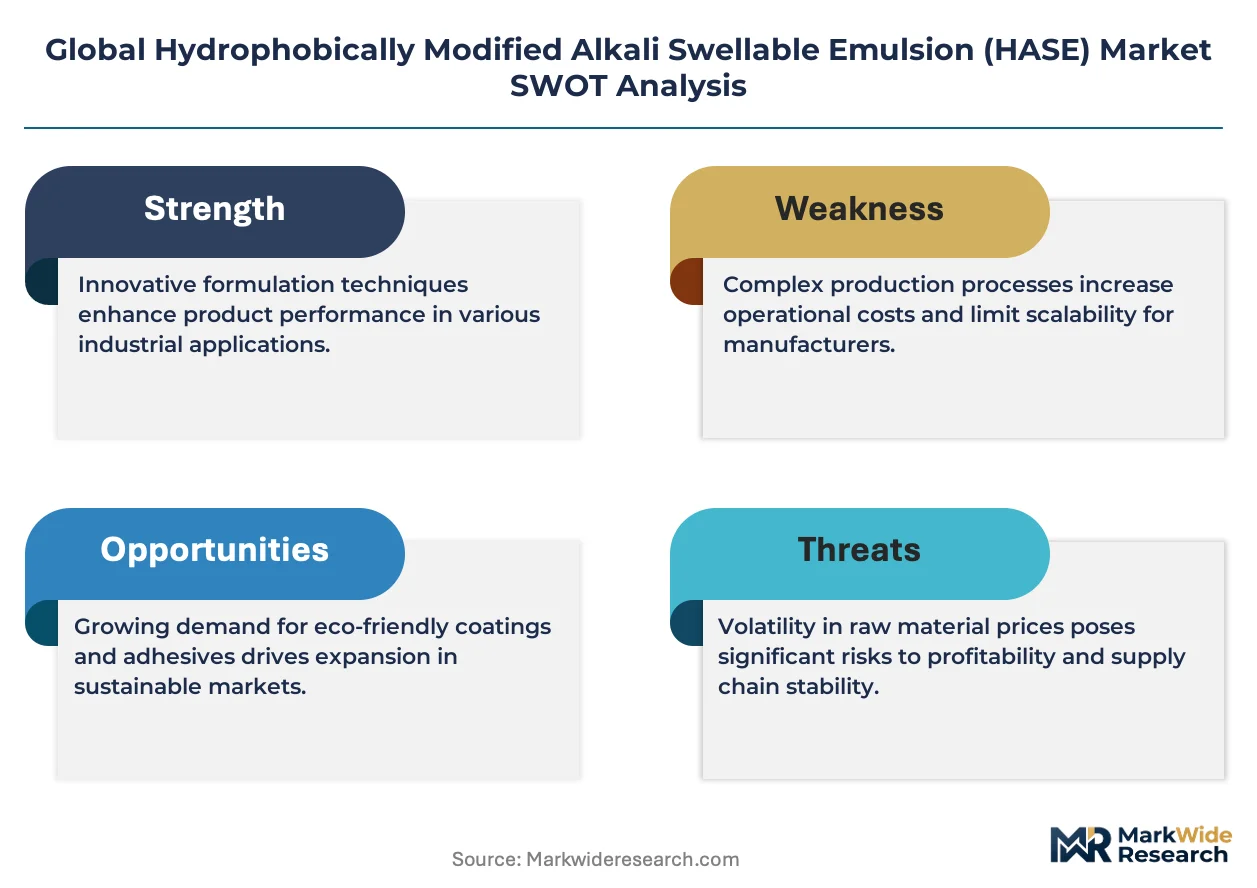
This market reads as a cost-of-compliance story where REACH Annex XVII hazardous substance limits erect regulatory moats favoring established suppliers with validated dossiers over spot-market entrants lacking ECHA substance evaluation documentation.
For Market Incumbents: Extend regulatory dossier advantages into preferred supplier contracts with automotive OEM coating clusters in Stuttgart, Detroit, and Toyota City. Deepen upstream control over propylene feedstock to buffer margin compression from acrylic acid price swings. Cellulosic thickener substitution in mid-shear architectural segments represents the priority defensive perimeter. For New Entrants and Emerging Players: Regional cementitious admixture blenders in Gujarat and Maharashtra industrial corridors offer the most penetrable entry point under India's PLI scheme for construction materials. BIS certification requirements create qualification barriers that favor technical partnership depth over commodity pricing. Digital tinting system integration for retail paint channels provides a differentiated go-to-market vector. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty rheology modifier producers with documented ECHA compliance in European coating clusters. Long-term viability hinges on bio-based hydrophobe architecture positioning aligned with EU Green Deal chemical sustainability targets. Monitor MEE enforcement of dual carbon goals in Chinese automotive OEM plants for demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstock | Captive acrylic acid supply secures margin stability against Gulf Coast petrochemical volatility. |
| Green Manufacturing Transition | Bio-based hydrophobe architectures qualify for preferred supplier status under ECHA evaluation protocols. |
| Long-term Supply Agreement | Multi-year contracts with Stuttgart and Detroit coating clusters lock in volume through VOC mandate cycles. |
| Joint Venture | Local partnerships in Jiangsu and Guangdong provinces accelerate BIS certification for Indian market entry. |
| Capacity Expansion | Technical-grade scale-up in Yangtze River Delta serves cementitious admixture demand from infrastructure programs. |
Research Methodology
Multi-period observation of propylene price benchmarks, REACH Annex XVII compliance timelines, and automotive OEM waterborne coating transitions anchored the trend analysis, supplemented by interviews with technical R&D directors at coating formulators, procurement leads at construction chemical blenders, regulatory affairs specialists, plant managers at emulsion facilities, and distribution channel partners. Secondary validation drew from ECHA substance evaluation protocols, EPA 40 CFR Part 59 filings, customs and trade data, and SEC 10-K disclosures from integrated polymer producers. Bottom-up volume modeling triangulated against top-down demand aggregation across end-use segments.
Input-output matrices mapped acrylic acid feedstock flows through copolymer production to downstream coating and personal care applications across the analysis window. Segmentation dimensions encompassed grade tier, end-use industry, packaging format, and regional production hub. CAGRs derived from regression analysis of historical volume trajectories against regulatory mandate implementation schedules and infrastructure investment cycles. Forecast inputs included automotive OEM waterborne transition timelines and MEE dual carbon enforcement intensity.
Revisions become necessary when propylene price volatility exceeds historical bands, REACH Annex XVII substance restrictions expand unexpectedly, or Chinese domestic HASE capacity scaling accelerates beyond infrastructure demand absorption. Practitioners should monitor ECHA substance evaluation protocol updates and California Air Resources Board rulemaking for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Polyoxyethylene Sorbitan Tristearate Market
Surfactants
Oil-in-Water Anionic Emulsifier Market
Surfactants
Cationic Surfactants Market
Surfactants
Global Surfactants Market
Surfactants
Cyclopentasiloxane Market
Surfactants
Powder Defoamers Market
Surfactants
Sodium Cocoyl Isethionate Market
Surfactants
Global Low Foam Surfactants Market
Surfactants
Emulsifying Wax Market
Surfactants
Zeolite for Detergents Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
Global Thioglycolic Acid Market
Surfactants
Bio-Based Surfactants Market
Surfactants
Dispersant Market
Surfactants
Cetyl Trimethyl Ammonium Chloride Market
Surfactants
Sodium Cumenesulfonate Market