
 Global Detergents Market | 2026-2036
Global Detergents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Detergents Market Foresight
Market Context
Refill-and-concentrate bundling is restructuring buyer choice across the Global Detergents Market, shifting volume from bulky single-use bottles toward compact, lower-carbon-footprint formats. Procter & Gamble leverages its global distribution network to anchor premium concentrate rollouts in North American and European retail channels. Unilever sustains competitive pressure through concentrated liquid formats that reduce plastic intensity per wash load. Henkel AG & Co. KGaA specializes in modular dosing systems that integrate with high-efficiency washing machines.
Technical and Segment Dynamics
Detergents are surface-active formulations comprising surfactants, builders, enzymes, and bleaching agents designed to reduce interfacial tension between water and soils for removal from textiles, hard surfaces, and industrial equipment; anionic and non-ionic surfactants typically constitute 15-40% of finished product weight depending on application intensity. Liquid detergents occupy the dominant revenue position due to superior solubility in cold-water cycles and compatibility with high-efficiency appliances, while bio-enzymatic formulations represent the fastest-expanding technology segment as enzyme stability in alkaline conditions improves manufacturing yields. Industrial cleaning applications command higher per-unit pricing than household segments, though commercial laundries generate the most consistent volume throughput among end-user categories.
Regulatory Environment
EPA Safer Choice standards in the United States, REACH restrictions on phosphates under ECHA oversight in Europe, and Japan's Soap and Detergent Association voluntary guidelines collectively constrain formulation chemistry and mandate biodegradability thresholds for surfactant components. These frameworks elevate compliance costs for imported products while creating preferential market access for manufacturers with established green-chemistry certification pipelines. Stakeholders must monitor pending amendments to EU Detergent Regulation surfactant biodegradability testing protocols, as these technical revisions will determine which existing product lines require reformulation investment.
Market Dynamics
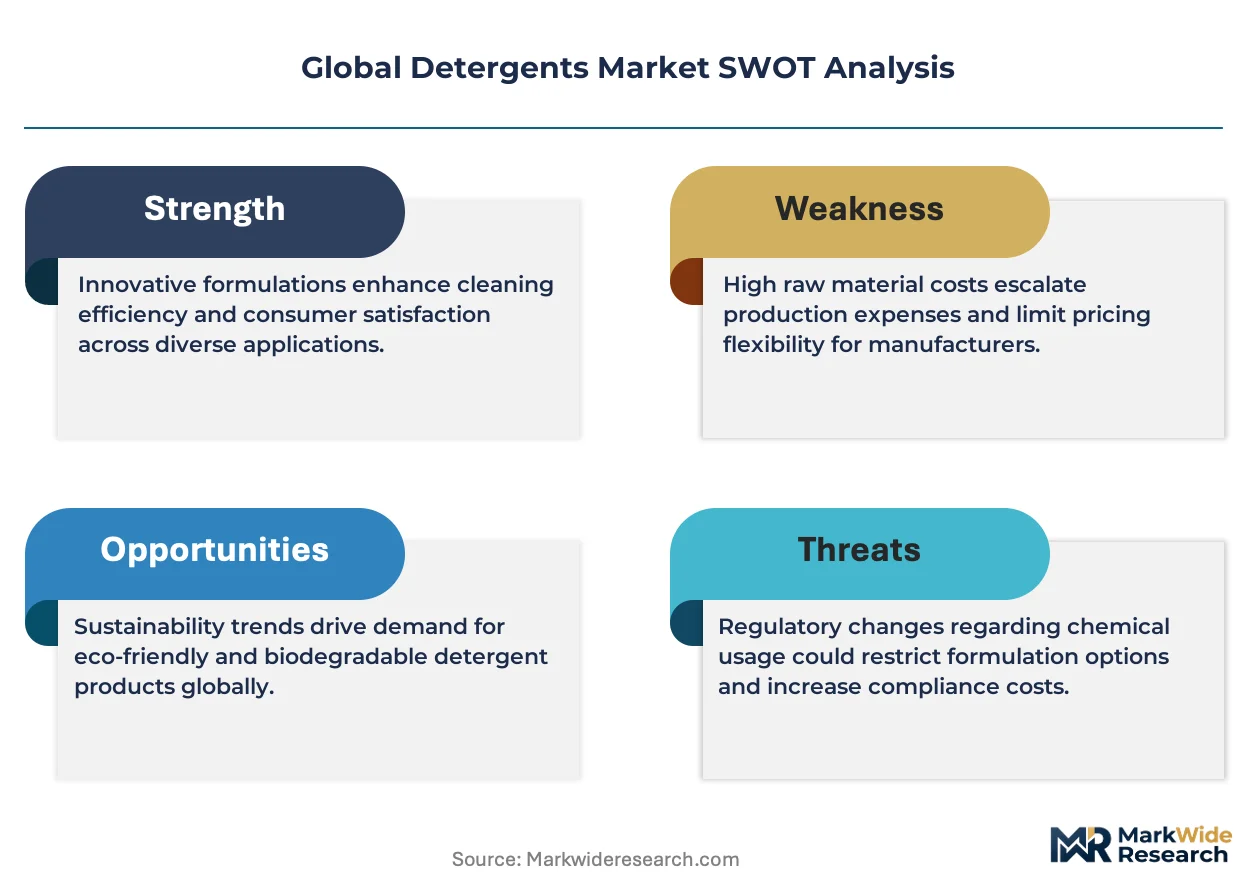
Phosphate-free formulation mandates from Germany, the United States, and Japan are forcing manufacturers to rebuild surfactant chemistry from the ground up, elevating compliance costs while opening preferential access for certified green-chemistry pipelines.
Growth Catalysts
- REACH phosphate restrictions:ECHA oversight in Europe mandates biodegradable surfactant thresholds, accelerating reformulation investment toward enzyme-stabilized alkaline formulations.
- India's urbanization wave:Rising disposable incomes in Mumbai and Delhi expand the consumer base for liquid and pod detergent formats beyond traditional powder dominance.
- Cold-water wash cycles:High-efficiency appliance penetration drives solubility demands that liquid concentrates satisfy more effectively than powder alternatives.
Market Restraints
- Palm oil derivative volatility:Fatty alcohol feedstock costs fluctuate with Southeast Asian plantation yields, compressing margin stability for surfactant manufacturers.
- Single-supplier enzyme concentration:Protease and lipase production clusters in Denmark and the Netherlands create vulnerability to regional logistics disruptions.
- EPA Safer Choice certification timelines:Multi-year biodegradability testing protocols delay product launches and freeze working capital in pending approvals.
Strategic Opportunities
- Refill-and-concentrate bundling:Compact lower-carbon formats gain shelf space in German and French retail channels as retailers enforce plastic-reduction targets.
- Modular dosing systems:Integration partnerships with high-efficiency washing machine manufacturers in Japan and South Korea enable premium pricing capture.
- Bio-enzymatic stability advances:Improved manufacturing yields in alkaline conditions open industrial cleaning applications previously resistant to biological formulations.
Industry Challenges
- Green-chemistry talent scarcity:Formulation chemists with surfactant biodegradability expertise command premium compensation in Germany and the Netherlands, constraining R&D expansion.
- Legacy powder infrastructure stranding:Existing spray-drying towers in mature markets face utilization pressure as demand tilts toward liquid and unit-dose production lines requiring fresh capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Detergents Market |
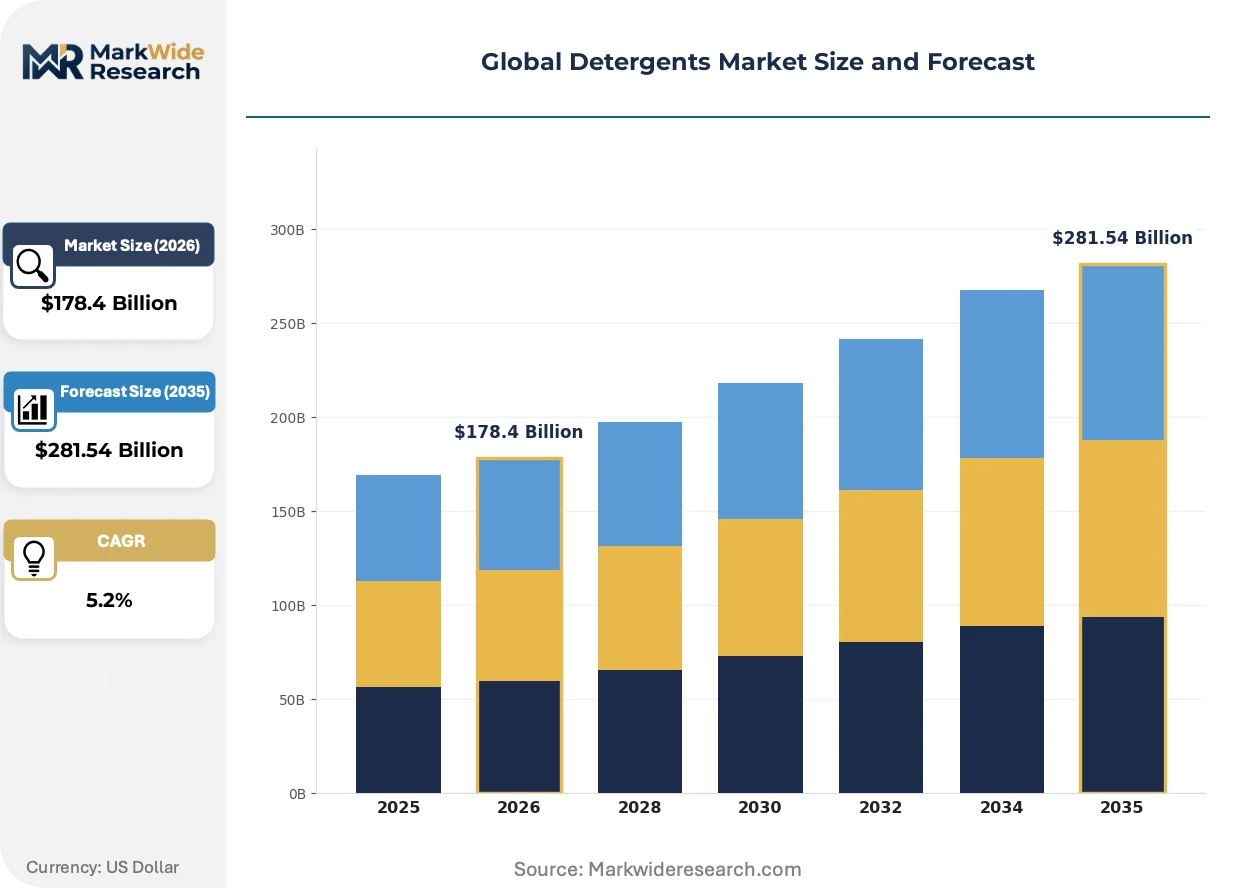
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $281.54 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Bar, Gel, Tablets Application: Household Cleaning, Industrial Cleaning, Institutional Cleaning, Automotive Maintenance Formulation Technology: Bio-Enzymatic, Phosphate-Free, Hypoallergenic, High-Efficiency, Oxygen Bleach End User: Commercial Laundries, Hospitality Services, Healthcare Facilities, Educational Institutions |
| Companies Covered | Procter & Gamble, Unilever, Henkel AG & Co. KGaA, Church & Dwight Co., Inc., Kao Corporation, Reckitt Benckiser Group, BASF SE, Huntsman Corporation, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Detergents Market Shifts & Advancements
Enzyme engineering and cold-water solubility chemistry are converging to redefine performance benchmarks, while regulatory pressure on phosphate content accelerates substitution timelines across formulation laboratories.
Bio-enzymatic detergent technology is overtaking traditional petrochemical surfactant systems in premium household segments. These formulations deploy engineered proteases, amylases, and lipases to break protein, starch, and fat soils at lower temperatures. European and Japanese appliance manufacturers specify enzyme-compatible detergents for their high-efficiency cold-water cycles. This shift is compressing the addressable market for legacy phosphate-heavy builders as retailers delist non-compliant SKUs.
REACH surfactant biodegradability testing protocol amendments are tightening ECHA oversight across European supply chains. Manufacturers must resubmit existing product lines for enhanced aquatic toxicity screening, extending reformulation cycles by 18-24 months. German and French formulators are responding by accelerating in-house green-chemistry certification pipelines to maintain retail distribution access.
Subscription-based concentrate replenishment is disrupting traditional supermarket detergent purchasing in urban United States and United Kingdom markets. Direct-to-consumer channels bundle compact refill cartridges with reusable dosing vessels, capturing higher lifetime value per household. This model concentrates most visibly among millennial buyers in London and New York who prioritize plastic reduction over per-load cost minimization.
Global Detergents Market Segmentation
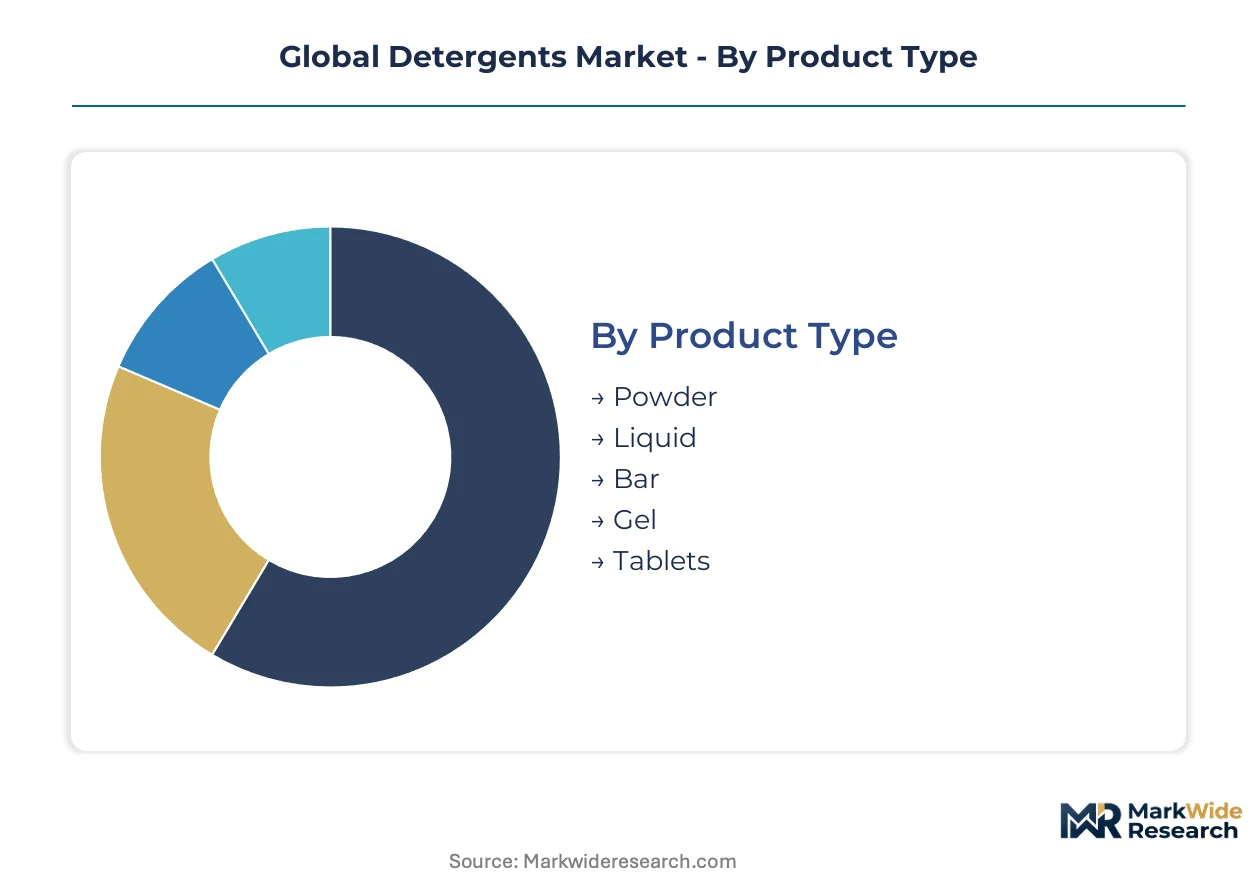
Detergent manufacturers configure production lines around distinct performance specifications and regulatory tolerances that vary sharply across end-use environments. Segmentation discipline separates commodity volume plays from premium formulation investments, directing R&D spend toward enzyme stability and cold-water solubility where appliance compatibility commands price premiums.
Product Type:
Standardization dominates powder and bar formats while liquid, gel, and tablet categories reward customization for regional water hardness and machine interfaces.
- Liquid:Surfactant suspensions in aqueous or non-aqueous bases deliver superior cold-water dissolution and dosing precision through pump or cap mechanisms. Demand concentrates in Germany and Japan where high-efficiency washing machine penetration exceeds thresholds that favor low-temperature cycles.
- Powder:Spray-dried granules incorporating builders, bleaches, and enzymes remain cost-optimized for bulk commercial laundries and price-sensitive households. Volume throughput is highest in India where traditional retail channels and washing practices sustain powder dominance despite liquid encroachment in urban centers.
- Bar:Solid surfactant cakes serve hand-wash applications in rural India and Southeast Asian markets with limited appliance access.
- Gel:Viscous concentrates enable precise dosing control and reduced packaging mass for refill-system compatibility in French and UK retail.
- Tablets:Unit-dose compression formats align with pod-dispensing appliances in Japanese and South Korean households seeking convenience premiums.
Most installed capacity flows through powder production infrastructure. Expansion is steepest in liquid concentrates compatible with subscription refill models.
Application:
Margin structures diverge between high-frequency household consumption and contract-priced industrial accounts with stringent specification compliance.
- Household Cleaning:Laundry and surface care formulations targeting textile and hard-surface soils in residential settings. Cold-water wash adoption in the United States and Japan is compressing powder share as liquid and pod formats capture appliance-upgrade cycles.
- Industrial Cleaning:Heavy-duty degreasers and alkaline cleaners for manufacturing equipment, food processing plants, and metal finishing operations. German automotive and precision engineering clusters generate consistent demand for phosphate-free formulations meeting ECHA discharge standards.
- Institutional Cleaning:Sanitization protocols for schools, government facilities, and public infrastructure requiring documented compliance with EPA Safer Choice or equivalent certification.
- Automotive Maintenance:Specialized surfactants for vehicle wash tunnels, detailing shops, and aerospace component cleaning where foam control and surface compatibility constrain formulation options.
Contract pricing locks in industrial volumes. Household segments yield the steepest margin expansion through concentrate and subscription formats.
Formulation Technology:
Regulatory pressure on aquatic toxicity is accelerating substitution timelines across chemistry pipelines, favoring biological and oxygen-based systems over legacy phosphate builders.
- Bio-Enzymatic:Engineered proteases, amylases, and lipases break protein, starch, and fat soils at reduced temperatures. Stability improvements in alkaline pH conditions are opening industrial applications previously resistant to biological systems.
- Phosphate-Free:Zeolite, citrate, and polycarboxylate builders substitute for banned phosphates under REACH and EPA frameworks. Reformulation costs have stranded legacy product lines while creating preferential access for certified green-chemistry pipelines.
- Hypoallergenic:Fragrance-free, dye-free formulations with reduced enzyme content for sensitive skin segments in German and Japanese markets.
- High-Efficiency:Low-sudsing concentrates calibrated for reduced water volumes in front-loading appliances.
- Oxygen Bleach:Sodium percarbonate and perborate systems for color-safe stain removal in European premium segments.
Phosphate-free platforms carry the heaviest compliance investment burden. Bio-enzymatic systems are climbing the fastest as manufacturing yields improve.
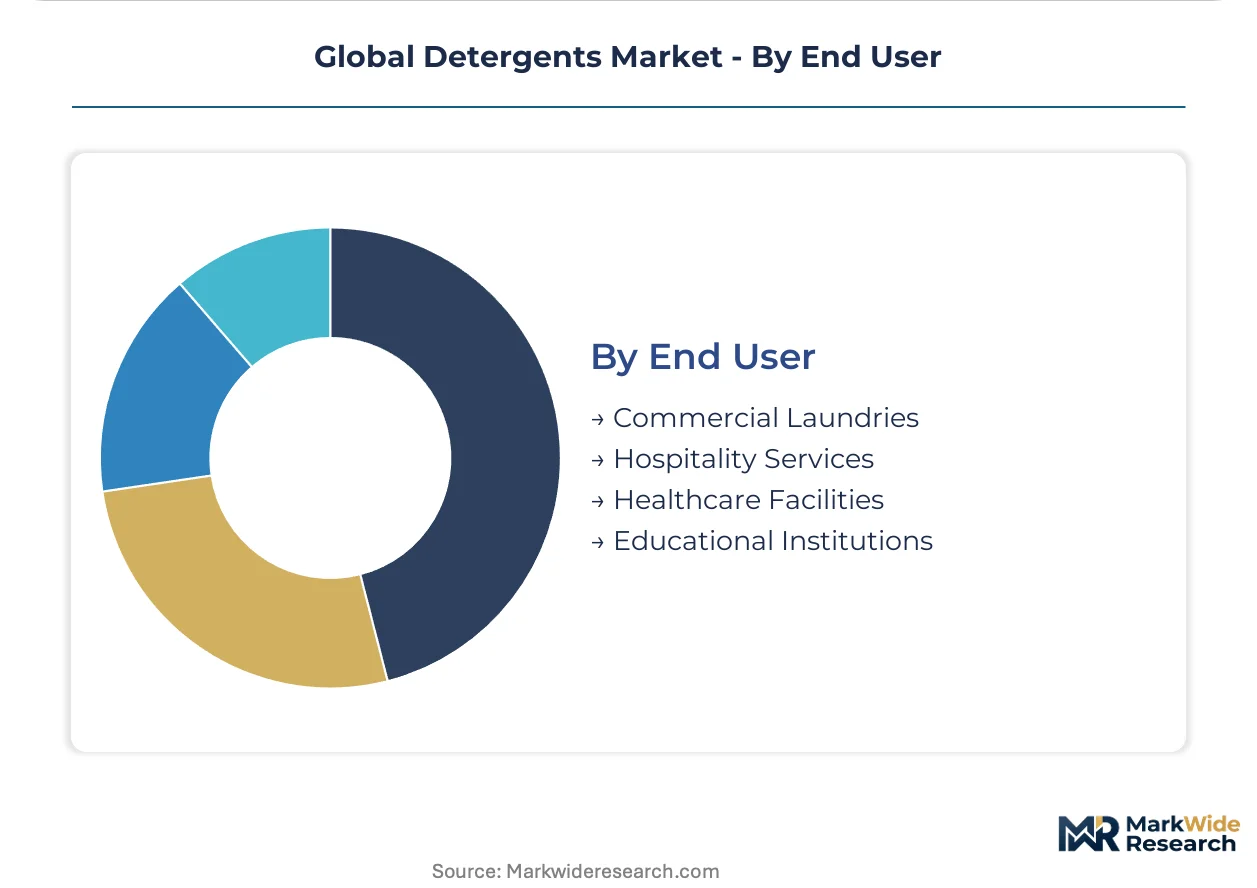
End User:
Procurement authority separates centralized contract buyers from fragmented retail selection, dictating formulation complexity and service bundling requirements.
- Commercial Laundries:Industrial-scale tunnel washers and batch systems in hospitality and healthcare linen services. German and Japanese commercial operators specify enzyme-compatible, phosphate-free formulations to meet discharge permits and textile longevity requirements.
- Hospitality Services:Hotels and restaurants balancing guest-facing fragrance preferences with operational cost controls and sustainability credentials.
- Healthcare Facilities:Infection control protocols demanding documented sporicidal efficacy and compatibility with sterilization equipment.
- Educational Institutions:Budget-constrained procurement through municipal purchasing cooperatives with escalating green-chemistry specifications.
Commercial laundries anchor volume throughput. Healthcare facilities are driving the steepest specification escalation for documented efficacy claims.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern detergent industry traces its industrial origins to Germany in the early twentieth century, where synthetic surfactant chemistry first achieved commercial scale. Today, formulation expertise and regulatory compliance capacity concentrate in distinct national clusters shaped by local water chemistry, appliance standards, and environmental policy frameworks.
Germany
High-efficiency washing machine penetration exceeding thresholds in German households sustains demand for low-temperature liquid concentrates. ECHA oversight of REACH surfactant biodegradability testing mandates reformulation investment cycles of 18-24 months. The Rhine-Ruhr industrial corridor hosts BASF SE and Henkel AG production facilities where phosphate-free builder chemistry originated.
United States
Subscription-based concentrate replenishment models disrupt traditional supermarket purchasing in New York and Los Angeles metropolitan areas. EPA Safer Choice certification timelines delay product launches through multi-year biodegradability protocols. The Midwest manufacturing belt maintains spray-drying infrastructure under utilization pressure as demand tilts toward liquid production lines.
Japan
Pod-dispensing appliance specifications from Tokyo and Osaka manufacturers drive unit-dose tablet format premiums. METI guidelines and Soap and Detergent Association voluntary standards constrain fragrance and dye content for sensitive skin segments. Kao Corporation anchors enzymatic formulation R&D in the Kansai industrial cluster.
India
Rising disposable incomes in Mumbai and Delhi expand the consumer base for liquid and pod formats beyond traditional powder dominance. BIS quality standards and DGFT import regulations elevate compliance costs for multinational entrants. Gujarat and Maharashtra host expanding surfactant manufacturing capacity serving domestic and export markets.
China
Urban household appliance upgrade cycles in Shanghai and Beijing compress powder share as front-loading machine penetration accelerates. MEE discharge standards and dual carbon goals mandate phosphate-free formulation transitions. The Yangtze River Delta concentrates detergent chemical production alongside textile processing clusters.
Global Detergents Market Competitive Landscape
The competitive structure tilts toward multinational consumer goods conglomerates with integrated surfactant supply chains and established green-chemistry certification pipelines. Tiered positioning separates premium concentrate innovators from commodity powder suppliers serving price-sensitive markets. Three archetypes dominate: global brand houses with retail channel control, regional specialists in modular dosing systems, and chemical feedstock suppliers backward-integrated into formulation. Capacity expansion and strategic partnerships with appliance manufacturers constitute the dominant competitive moves.
Among global brand houses, Procter & Gamble and Unilever occupy positions exemplifying premium concentrate rollouts through retail channel anchoring. Henkel AG & Co. KGaA represents the modular dosing specialist archetype with integration partnerships in high-efficiency appliance markets. These three companies illustrate how formulation chemistry expertise, distribution network scale, and regulatory compliance capacity combine to structure competitive advantage in phosphate-free transition environments.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| Henkel AG & Co. KGaA |
| Church & Dwight Co., Inc. |
| Kao Corporation |
| Reckitt Benckiser Group |
| BASF SE |
| Huntsman Corporation |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
EPA Safer Choice certification timelines in the United States force manufacturers to freeze working capital in multi-year biodegradability testing protocols, compelling supply chain reconfiguration toward pre-certified green-chemistry feedstock suppliers and compressing margin structures for non-compliant product lines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates enzyme-stabilized concentrates from legacy powder formulations and bulk commercial grades. Price differentiation hinges on ECHA green-chemistry certification status and cold-water solubility performance tier. Cost compression in economy powder segments is intensifying because palm oil derivative volatility feeds directly into fatty alcohol surfactant costs. Commercial laundries exhibit highest price sensitivity while Japanese pod-format households accept substantial premiums for appliance-compatible dosing precision.
Supply Chain Analysis
Direct-to-retail channels anchor premium concentrate distribution in German and French urban markets while bulk commercial volumes flow through distributor networks serving Indian and Southeast Asian laundry operators. Manufacturing gravity centers on Germany, China, and India where BASF SE, Henkel AG, and domestic Gujarat-based surfactant producers cluster. Feedstock supply draws from Southeast Asian palm oil plantations, Danish protease enzyme facilities, and Chinese zeolite builder production. Single-source enzyme concentration in Denmark and the Netherlands creates acute vulnerability to regional logistics disruptions. Distribution runs through retailer-imposed plastic-reduction compliance gates in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-mandated reformulation costs in Europe and BIS-compliant manufacturing cost advantages in India, where domestic surfactant capacity expansion outpaces regulatory compliance investment cycles.
For Market Incumbents: Anticipate stranded asset risk in legacy spray-drying infrastructure across the United States Midwest and European Rhine-Ruhr corridor as demand tilts toward liquid concentrate production lines. Prioritize backward integration into captive enzyme supply through partnerships with Danish and Dutch biotech specialists. Defend retail shelf access by accelerating EPA Safer Choice and ECHA REACH certification pipelines ahead of protocol amendments tightening aquatic toxicity screening. For New Entrants and Emerging Players: Subscription-oriented millennial households in London and New York represent the most penetrable buyer archetype for direct-to-consumer concentrate replenishment models bypassing traditional supermarket channels. Target modular dosing system partnerships with Japanese and South Korean appliance manufacturers seeking detergent compatibility specifications. Lead with plastic-reduction credentials and cold-water performance guarantees rather than per-load cost minimization. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists commanding green-chemistry certification pipelines in phosphate-free formulation transitions. Long-term viability accrues to manufacturers with demonstrated ECHA compliance capacity and established enzyme stability expertise in alkaline conditions. Monitor REACH surfactant biodegradability testing protocol amendment timelines as the critical inflection signal determining which product lines require capital-intensive reformulation investment.| Strategic Initiative | Industry Significance |
|---|---|
| Green-Chemistry Certification Pipeline Investment | ECHA REACH pre-certification secures preferential retail distribution access in German and French markets ahead of protocol amendments. |
| Backward Integration into Enzyme Supply | Captive protease and lipase production reduces vulnerability to single-source concentration in Denmark and Netherlands clusters. |
| Modular Dosing System Partnerships | Appliance manufacturer integration in Japan and South Korea enables premium pricing capture through specification lock-in. |
| Direct-to-Consumer Refill Channel Launch | Subscription models in London and New York metropolitan areas capture higher lifetime value from plastic-conscious millennial households. |
| Phosphate-Free Formulation Transition | Zeolite and citrate builder substitution meets EPA and ECHA mandates while straining legacy powder production infrastructure. |
Research Methodology
Multiple input streams — structured interviews with detergent formulation chemists and brand managers, trade data reconciliation across customs records, and secondary validation through EPA Safer Choice and ECHA REACH filing databases — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged plant managers at German and Indian surfactant facilities, category buyers at French and UK retail chains, and procurement leads at commercial laundry operators in Japan. Bottom-up volume triangulation from production capacity utilization was cross-checked against top-down consumer expenditure patterns derived from Nielsen retail audit data and national customs statistics.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling demand trajectories by product type, formulation technology, end-user procurement authority, and regional regulatory cluster. Segmentation dimensions included liquid versus powder versus pod format splits, bio-enzymatic versus phosphate-free versus legacy builder chemistry tiers, and household versus industrial versus institutional application environments. CAGRs were derived from appliance penetration curves, cold-water wash adoption rates, and green-chemistry certification pipeline throughput. Key inputs encompassed high-efficiency washing machine shipment data from Japanese and German manufacturers and palm oil derivative price indices tracking Southeast Asian feedstock volatility.
Underlying measurement precision varies by segment; liquid concentrate and bio-enzymatic categories carry tighter precision than legacy powder estimates given more transparent retail scanner data and manufacturer disclosure practices. Forecasts incorporate assumptions regarding REACH protocol amendment implementation timing, EPA certification backlog resolution, and enzyme manufacturing yield improvements in alkaline conditions. Periodic stress-testing of base assumptions is recommended against regulatory delay scenarios and feedstock supply disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Global Sodium Lauryl Ether Sulfate [SLES] Market
Surfactants
Sulfosuccinate Market
Surfactants
Anionic Surfactants Market
Surfactants
Soap Salts Market
Surfactants
Global Calcium Sulfonate Market
Surfactants
Global Saponin Market
Surfactants
North America Surfactants Market
Surfactants
Global Rhamnolipid Market
Surfactants
Polysorbate 40 Market
Surfactants
Global Fluorosurfactants Market
Surfactants
Global Amphoteric Surfactants Market
Surfactants
Global Low Foam Surfactants Market
Surfactants
Trisiloxane Market
Surfactants
Natural Wax Emulsion Market
Surfactants
Asia Pacific Surfactants Market
Surfactants
Chlorooctane Market