
 North America Metal Cleaning Chemicals Market | 2026-2036
North America Metal Cleaning Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Metal Cleaning Chemicals Market Analytics
The EPA Safer Choice standard is rebalancing procurement criteria across metal finishing operations. Dow Inc. leverages its integrated surfactant supply chain to serve automotive OEMs with low-VOC alkaline systems. Stepan Company anchors its position through bio-based feedstock R&D for aqueous cleaner formulations. Evonik Industries differentiates via specialty amine oxide chemistry targeting precision electronics cleaning.
Metal cleaning chemicals comprise formulated blends of surfactants, chelating agents, solvents, and pH modifiers engineered to remove oils, oxides, and particulate contaminants from ferrous and non-ferrous substrates, typically operating at temperatures between 40°C and 80°C depending on substrate sensitivity. These formulations serve critical functions in preparing surfaces for coating, bonding, or final assembly across capital-intensive industries. Alkaline cleaners dominate volume consumption in heavy manufacturing due to compatibility with steel and cost-effective immersion systems. Solvent cleaners retain premium positioning in aerospace and electronics precision cleaning where aqueous methods risk moisture entrapment or corrosion. The liquid formulation segment leads value generation through ready-to-use and concentrated dilutable products optimized for automated spray and ultrasonic systems.
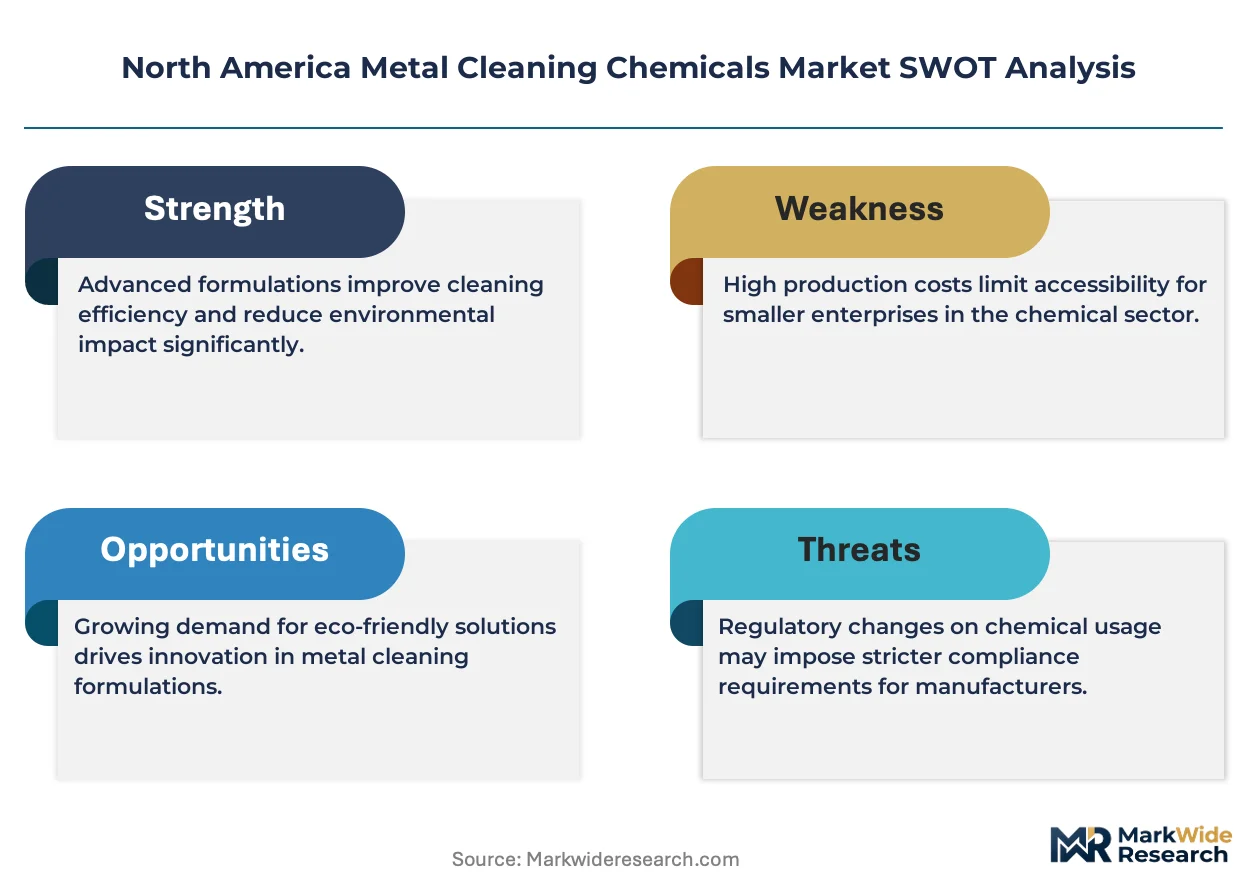
The EPA regulates VOC emissions under 40 CFR Part 59, while OSHA enforces permissible exposure limits for chlorinated and hydrocarbon solvents in metalworking facilities. California's Air Resources Board imposes additional restrictions through its Consumer Products Regulation and SCAQMD Rule 1122, forcing suppliers to reformulate for the state's substantial aerospace and electronics manufacturing base. Canada complements this framework through Health Canada's PMRA oversight of antimicrobial claims and Environment and Climate Change Canada VOC concentration limits. Stakeholders must monitor evolving state-level chemical disclosure requirements and the potential expansion of PFAS restrictions under TSCA Section 5 to anticipate reformulation timelines and raw material substitution strategies.
Market Dynamics
The EPA's Safer Choice program and California's SCAQMD Rule 1122 are forcing simultaneous reformulation across alkaline, solvent, and aqueous cleaner categories, compressing product development timelines while opening procurement channels for compliant suppliers.
Growth Catalysts
- Aerospace solvent-free mandates:United States aerospace OEMs are expanding aqueous and semi-aqueous cleaning protocols for precision components, creating dedicated demand for low-VOC alkaline systems compatible with aluminum and titanium substrates.
- SCAQMD Rule 1122:California's air quality enforcement is accelerating supplier investments in VOC-compliant formulations, with Los Angeles Basin electronics and metal finishing facilities facing compliance deadlines that favor pre-qualified chemical providers.
- Great Lakes manufacturing corridor concentration:Michigan, Ohio, and Illinois automotive stamping and powertrain operations maintain dense demand for immersion-based alkaline cleaners, supporting regional formulation scale and technical service density.
Market Restraints
- Petrochemical feedstock volatility:Surfactant and solvent raw materials derived from ethylene and propylene chains expose formulators to input cost swings that compress margin stability across quarterly planning cycles.
- PFAS regulatory uncertainty:Potential TSCA Section 5 restrictions on fluorinated surfactants used in precision electronics cleaning create reformulation risk for suppliers serving semiconductor and aerospace segments.
- Legacy solvent infrastructure lock-in:Chlorinated hydrocarbon vapor degreasing systems in established metalworking facilities require capital-intensive equipment replacement to transition toward aqueous alternatives.
Strategic Opportunities
- Mexico nearshoring expansion:Automotive and appliance manufacturing growth in Querétaro and Nuevo León is creating demand for localized metal cleaning chemical supply and technical service presence.
- EV battery cell manufacturing:Gigafactory construction across the United States and Canada is generating new demand for precision cleaning of aluminum cell housings and copper current collectors.
- Canada PMRA antimicrobial pathway:Health Canada's regulatory framework for cleaner-sanitizer dual claims offers a differentiated positioning route for suppliers targeting food processing equipment applications.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in chelating agent selection and surfactant synergy optimization for multi-metal compatibility is concentrated among retiring technical staff at established suppliers.
- Equipment-process integration complexity:Aqueous cleaner adoption requires simultaneous optimization of wash chemistry, mechanical action, drying systems, and wastewater handling, extending sales cycles and technical support burdens.
- Cross-border formulation registration:Divergent EPA and Health Canada notification requirements for new chemical substances create timeline friction for suppliers seeking unified North American product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Metal Cleaning Chemicals Market |
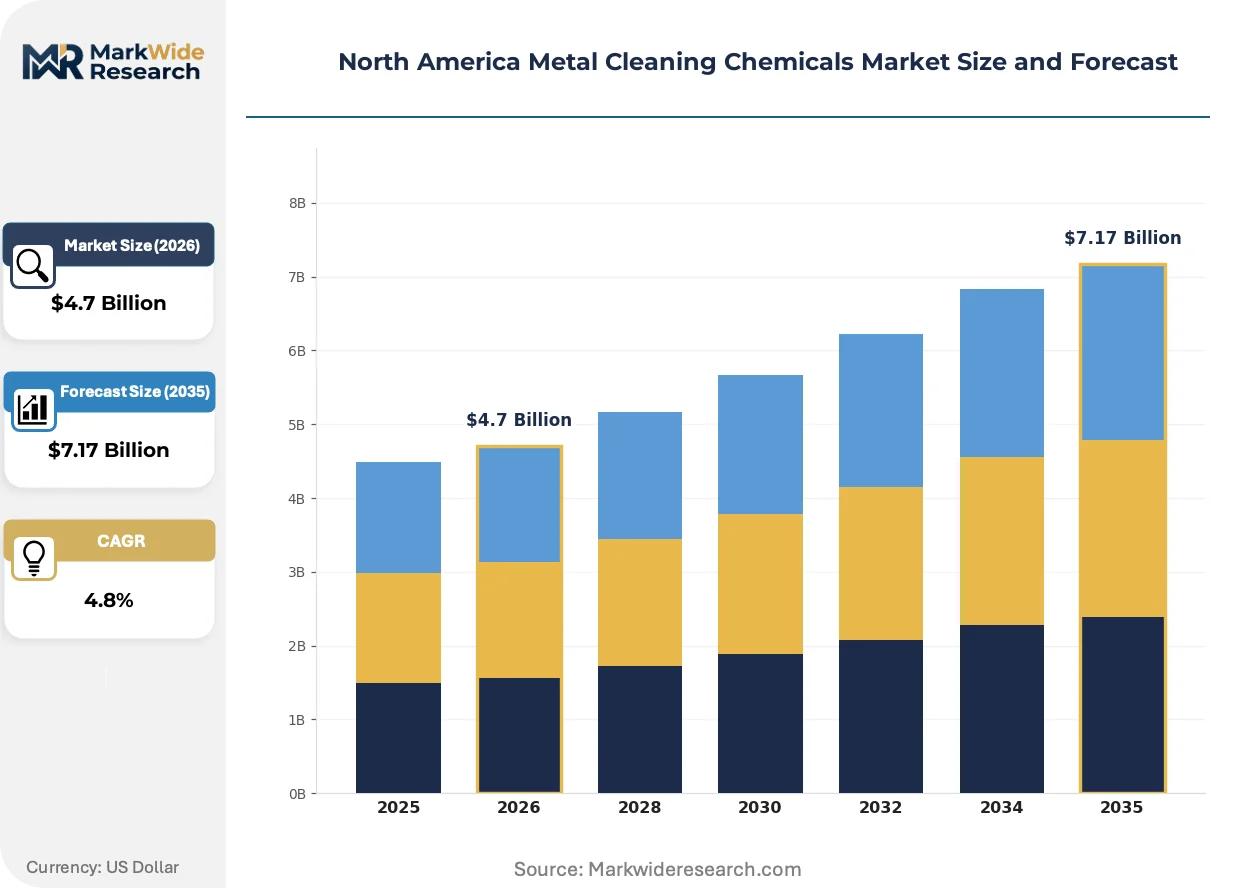
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $7.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline Cleaners, Solvent Cleaners, Acidic Cleaners, Emulsifying Cleaners End User: Aerospace, Automotive, Manufacturing, Electronics Application: Industrial Cleaning, Precision Cleaning, Maintenance Cleaning, Surface Preparation Formulation: Liquid, Powder, Concentrate, Aerosol |
| Companies Covered | Stepan Company, Evonik Industries, Dow Inc., KYZEN Corporation, Chemours Company, BASF SE, Henkel AG & Co. KGaA, Quaker Chemical Corporation, Ecolab Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Metal Cleaning Chemicals Market Evolving Landscape
Reformulation chemistry and automated application systems are converging to redefine performance benchmarks across precision and heavy manufacturing segments, with regulatory compliance now inseparable from technical specification.
Hybrid alkaline-aqueous formulations are unifying the cleaning efficacy of traditional solvent systems with the environmental profile of water-based chemistry. Aerospace tier suppliers in the United States are adopting these systems at accelerated pace for intermediate cleaning operations. This convergence is unifying previously separate product categories into single-solution platforms that reduce inventory complexity and regulatory exposure.
California's Air Resources Board is tightening VOC concentration limits through amendments to Consumer Products Regulation and district-level SCAQMD enforcement. Metal finishing operations across Southern California face reformulation deadlines that favor suppliers with pre-validated low-emission chemistries. Electronics and medical device manufacturers in the Los Angeles Basin are responding by consolidating procurement around compliant formulation portfolios.
Specification-driven procurement is compressing supplier qualification timelines as OEMs centralize chemical approval processes. Tier 1 automotive and aerospace metalworkers are displacing fragmented local sourcing with corporate-approved vendor lists tied to ESG and performance audits. This concentration is most visible across the Great Lakes automotive corridor and Pacific Northwest aerospace cluster.
North America Metal Cleaning Chemicals Market Segmentation
Metal cleaning chemical procurement across North America follows distinct technical specifications tied to substrate sensitivity, regulatory compliance tiers, and equipment integration requirements. Understanding these segment boundaries enables suppliers to align formulation investments with concentrated demand pockets and qualification pathways.
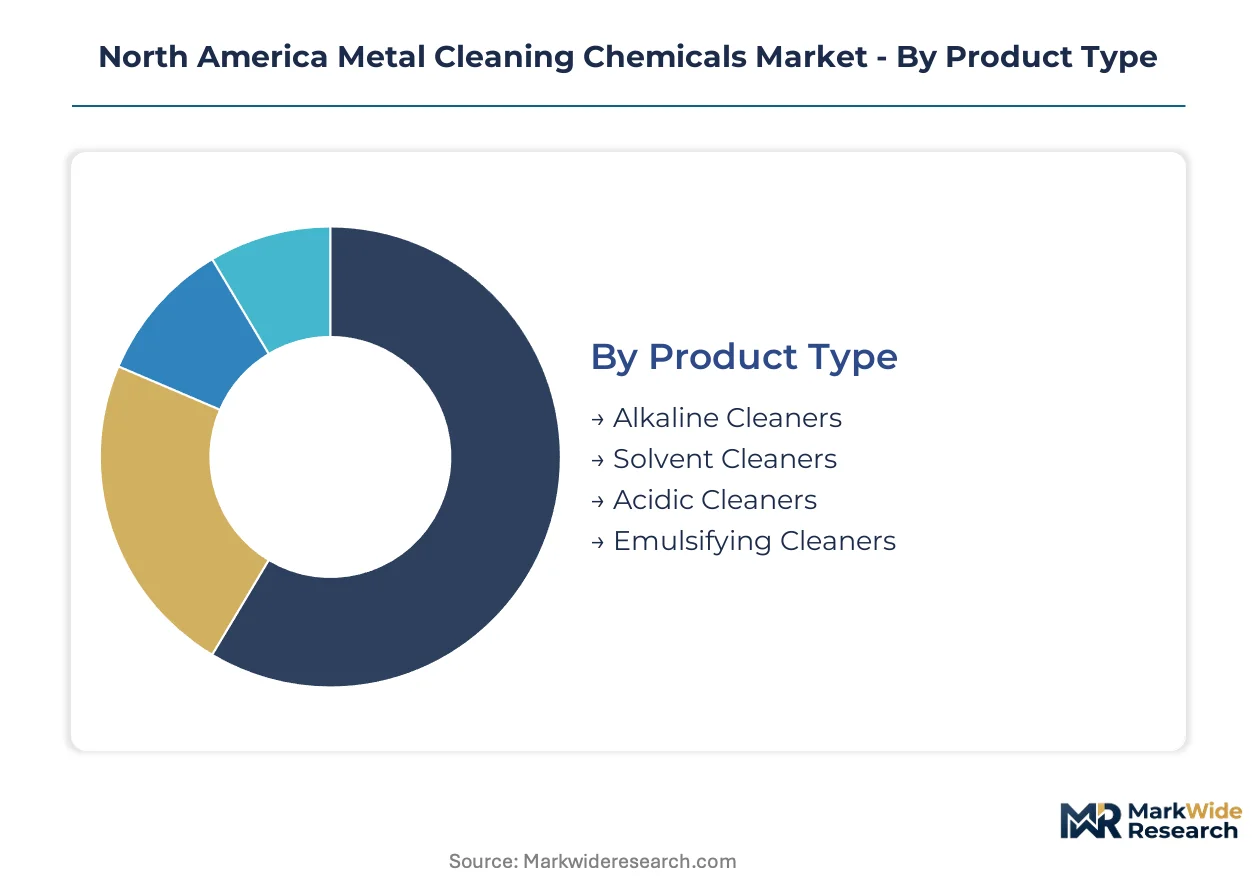
Product Type:
Supply concentration in surfactant manufacturing favors formulators with captive ethylene oxide derivatives and integrated chelating agent production, locking in cost positions for high-volume alkaline systems.
- Alkaline Cleaners:These formulations combine sodium hydroxide, silicates, and surfactant packages to remove heavy oils and particulates from ferrous metals at 50-80°C operating temperatures. Demand concentrates in Michigan and Ohio automotive stamping plants where immersion tanks process steel substrates at scale under EPA wastewater discharge permits.
- Solvent Cleaners:Hydrocarbon and chlorinated formulations deliver rapid drying and residue-free surfaces for precision applications. Aerospace tier suppliers in California face SCAQMD Rule 1122 compliance deadlines that favor low-VOC solvent alternatives or aqueous substitutions for aluminum and titanium component cleaning.
- Acidic Cleaners:Phosphoric and citric acid blends remove oxides and prepare surfaces for coating adhesion.
- Emulsifying Cleaners:Surfactant-rich systems suspend oils in water-based matrices for heavy-duty degreasing.
Today's leader: Alkaline Cleaners. Tomorrow's challenger: Solvent Cleaners.
End User:
Cost tier stratification separates specification-grade aerospace approvals from commodity automotive procurement, with margin structures diverging by qualification intensity and technical service requirements.
- Aerospace:OEM mandates for solvent-free protocols are redirecting specification approvals toward aqueous and semi-aqueous systems compatible with NADCAP accreditation. Boeing and Lockheed Martin supplier networks in Washington and Texas states drive qualification timelines exceeding 18 months for new chemistry introductions.
- Automotive:Powertrain and stamping operations across the Great Lakes corridor consume immersion alkaline cleaners in continuous process tanks. Stellantis and Ford manufacturing sites in Michigan and Ohio specify dilutable concentrates optimized for automated spray systems with integrated oil separation.
- Manufacturing:General metal fabrication and machinery maintenance spans diverse substrate mixes and batch processing economics.
- Electronics:Semiconductor and printed circuit board cleaning demands ultra-low residue formulations with controlled ionic contamination levels.
Aerospace commands premium positioning. Electronics shows steepest expansion trajectory.
Application:
Volume concentration in continuous industrial processes supports regional formulation scale, while precision cleaning applications sustain specialty chemical margins through technical specification barriers.
- Industrial Cleaning:High-throughput immersion and spray operations in automotive and heavy equipment manufacturing consume formulated cleaners in bulk tank systems. Ohio and Indiana metalworking clusters favor dilutable alkaline concentrates with integrated rust inhibition for steel processing lines.
- Precision Cleaning:Critical surface preparation for electronics, medical devices, and aerospace components requires controlled particle and ionic residue specifications. California electronics manufacturers under CARB enforcement are consolidating procurement around validated low-emission aqueous systems.
- Maintenance Cleaning:In-service equipment degreasing and facility upkeep operate on intermittent schedules with portable application methods.
- Surface Preparation:Pre-coating and pre-bonding treatments demand chemistry compatibility with subsequent adhesion processes.
Industrial Cleaning anchors volume. Precision Cleaning climbs fastest.
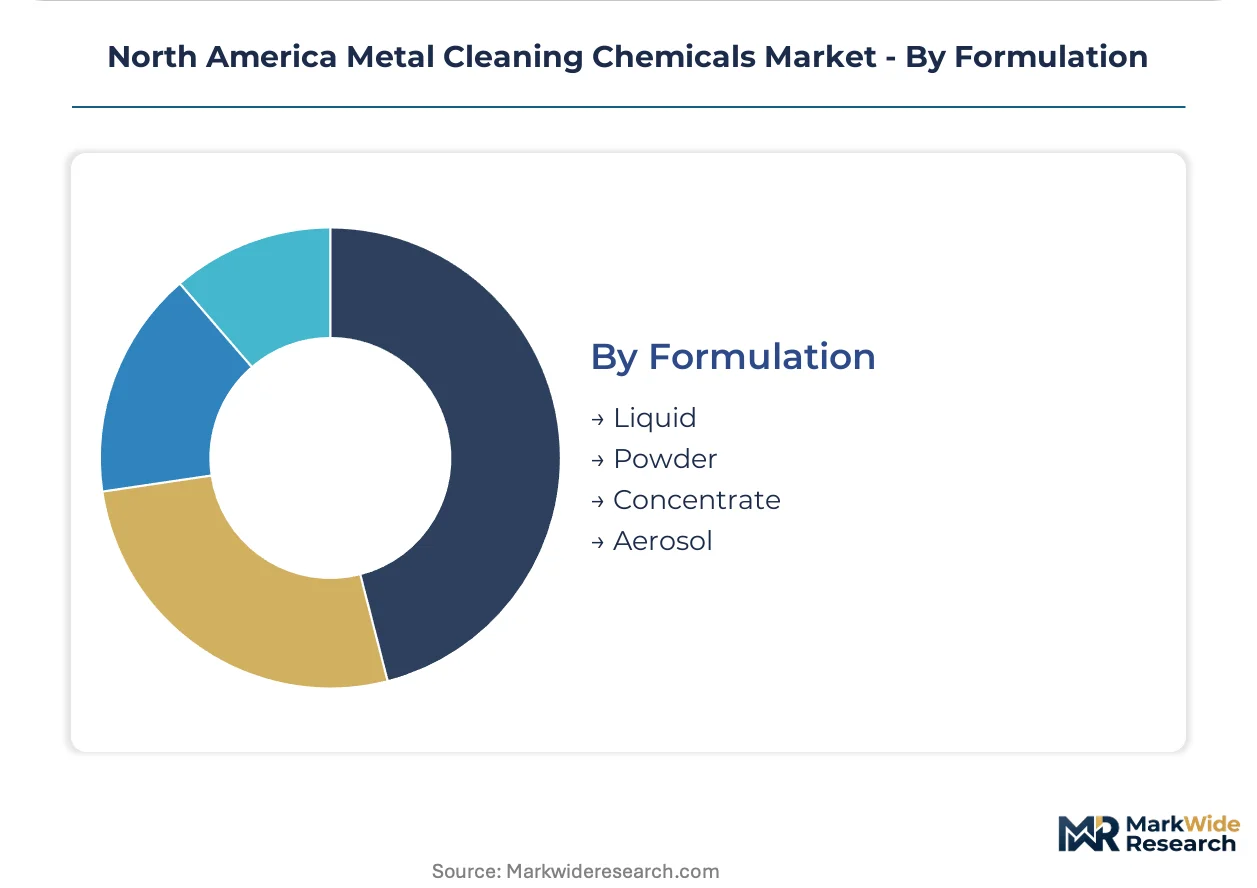
Formulation:
Customer type segmentation separates automated process integrators seeking concentrated feedstocks from maintenance operators prioritizing ready-to-use convenience and storage stability.
- Liquid:Ready-to-use and dilutable solutions dominate automated spray, ultrasonic, and immersion system integrations. Automotive OEMs in Illinois and Wisconsin specify liquid concentrates with controlled foam profiles for high-pressure spray cabinets operating at 60°C.
- Concentrate:High-activity formulations reduce shipping costs and inventory footprint for high-volume consumers with on-site dilution capabilities. Canadian automotive suppliers in Ontario leverage concentrate economics for cross-border supply chain efficiency.
- Powder:Solid alkaline blends offer extended shelf life and reduced packaging waste for remote facility supply.
- Aerosol:Pressurized solvent systems serve spot-cleaning and maintenance applications requiring portability and controlled application.
Liquid formulations dominate value. Concentrate formats gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The metal cleaning chemicals industry traces its North American scale to post-war industrialization in the Great Lakes region, where automotive mass production created concentrated demand for immersion-based alkaline systems that persists in modern stamping and powertrain operations.
United States
Michigan and Ohio automotive clusters consume immersion alkaline cleaners at scale for steel processing lines. The EPA's Safer Choice program and OSHA permissible exposure limits under 40 CFR Part 59 force simultaneous reformulation across solvent and aqueous categories. Boeing and Lockheed Martin supplier networks in Washington and Texas drive 18-month qualification timelines for new aerospace chemistry.
Canada
Ontario automotive suppliers leverage concentrate economics for cross-border supply chain efficiency with US Midwest operations. Health Canada's PMRA oversees antimicrobial claims for cleaner-sanitizer dual formulations targeting food processing equipment. The province maintains dense technical service presence to serve Stellantis and Ford manufacturing sites.
Mexico
Querétaro and Nuevo León automotive and appliance manufacturing growth creates demand for localized metal cleaning chemical supply. Nearshoring expansion accelerates requirements for immersion-based alkaline systems compatible with steel stamping operations. The northern border states concentrate new formulation technical service investments.
California
Los Angeles Basin electronics and medical device manufacturers face SCAQMD Rule 1122 compliance deadlines favoring pre-qualified low-VOC chemical providers. CARB amendments to Consumer Products Regulation tighten VOC concentration limits for precision cleaning applications. The state's aerospace tier suppliers accelerate aqueous and semi-aqueous system adoption for aluminum and titanium components.
Illinois
Chicago-area metalworking clusters specify dilutable alkaline concentrates with controlled foam profiles for automated spray cabinets. The state's position within the Great Lakes corridor supports regional formulation scale for continuous process tank systems. Indiana and Wisconsin automotive OEMs extend procurement networks into Illinois-based technical service operations.
North America Metal Cleaning Chemicals Market Competitive Landscape
Capital-heavy integrated chemical producers compete with asset-light specialty formulators across distinct value chain positions. The market structure concentrates around three to five dominant suppliers with captive surfactant production, while mid-tier players fragment across regional formulation services. Strategic archetypes separate integrated petrochemical giants, bio-based feedstock specialists, and precision electronics chemists. Competitive moves center on M&A for surfactant supply chain control and strategic partnerships for equipment-process integration.
Within the integrated petrochemical tier, Dow Inc. and BASF SE represent scale-driven positions anchored by captive ethylene oxide derivatives and chelating agent production. Stepan Company exemplifies the bio-based formulation specialist archetype through aqueous cleaner R&D investments. These three companies occupy distinct competitive vectors: Dow anchors automotive OEM supply through low-VOC alkaline systems, BASF sits within multi-industrial chemical portfolios with cross-selling capabilities, and Stepan concentrates technical expertise in surfactant synergy optimization for multi-metal compatibility.
| Leading Market Players |
|---|
| Stepan Company |
| Evonik Industries |
| Dow Inc. |
| KYZEN Corporation |
| Chemours Company |
| BASF SE |
| Henkel AG & Co. KGaA |
| Quaker Chemical Corporation |
| Ecolab Inc. |
| Others |
Value Network & Pricing Analysis
Aqueous cleaner adoption across California aerospace and Great Lakes automotive operations is compressing formulation margins while concentrating procurement power among buyers with multi-site tank systems. This technology transition simultaneously elevates surfactant feedstock costs and rewards suppliers with captive ethylene oxide production.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NADCAP-certified aerospace formulations from commodity automotive concentrates and generic maintenance blends. Price differentiation rests on EPA Safer Choice certification and SCAQMD Rule 1122 pre-qualification status. Cost compression in standard-tier alkaline systems is intensifying because automotive OEMs are consolidating vendor lists. Maintenance operators purchasing spot aerosol supplies show highest price sensitivity; aerospace tier suppliers with 18-month qualification timelines demonstrate lowest.
Supply Chain Analysis
Surfactant supply rests on United States Gulf Coast ethylene oxide derivatives, German specialty amine oxide producers, and Canadian bio-based feedstock processors. Formulators draw from petrochemical ethylene chains, phosphoric acid for acidic cleaners, and chelating agent packages. Single-source vulnerability concentrates in fluorinated surfactants facing potential TSCA Section 5 restrictions. Distribution runs through regional formulation facilities serving automotive clusters with tanker-delivered concentrates and technical service support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America metal cleaning chemicals market functions as a stable compounder, with EPA and California regulatory mandates driving steady reformulation demand across automotive and aerospace end uses.
For Market Incumbents: Anchor market position through backward integration into surfactant production and accelerated SCAQMD Rule 1122 pre-qualification investments. Defend against specialty electronics formulators by locking in multi-year supply agreements with Boeing and Lockheed Martin supplier networks. Prioritize technical service density in Michigan and Ohio automotive corridors. For New Entrants and Emerging Players: Capture white space in Mexico nearshoring corridors, specifically Querétaro and Nuevo León automotive stamping operations requiring localized alkaline cleaner supply. Target EV battery cell manufacturing gigafactories across the United States and Canada for precision aluminum and copper cleaning formulations. Lead with equipment-process integration partnerships to bypass incumbent technical service advantages. For Investors and Strategic Acquirers: Roll-up economics work for regional formulation specialists with captive automotive OEM approvals because corporate vendor list consolidation is displacing fragmented local sourcing. Five-to-ten-year viability hinges on regulatory compliance infrastructure rather than commodity scale. Target acquisition archetype: mid-tier formulators with SCAQMD pre-qualified portfolios and dense Great Lakes technical service presence. Watch PFAS restriction announcements under TSCA Section 5 as inflection indicator for fluorinated surfactant substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Production | Captive ethylene oxide supply locks in cost positions for high-volume alkaline systems serving Michigan automotive stamping plants. |
| SCAQMD Rule 1122 Pre-Qualification Investment | Pre-validated low-VOC formulations open procurement channels with Los Angeles Basin electronics manufacturers facing compliance deadlines. |
| Mexico Nearshoring Technical Service Expansion | Localized formulation and service presence captures automotive and appliance manufacturing growth in Querétaro and Nuevo León. |
| EV Battery Cell Manufacturing Partnership | Precision cleaning chemistry for aluminum cell housings and copper current collectors addresses gigafactory construction across the United States and Canada. |
| Health Canada PMRA Dual-Claim Pathway | Cleaner-sanitizer formulations targeting food processing equipment differentiate positioning in Ontario automotive supplier networks. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each jurisdiction triangulated against secondary validation. The report combines interviews with plant managers at automotive stamping operations, procurement leads at aerospace tier suppliers, technical R&D directors at formulation companies, and distribution channel partners serving the Great Lakes corridor. Secondary sources include EPA enforcement records, California Air Resources Board amendments, Health Canada PMRA filings, ACC chemical production data, and SEC 10-K disclosures from publicly traded suppliers. Bottom-up demand modeling from end-use consumption and top-down supply validation from production capacity were cross-referenced.
Rate-of-change decomposition separates volume growth from price and mix effects across the analysis window. Segmentation dimensions include cleaner chemistry type, end-use industry, formulation concentration level, and regional regulatory compliance tier. CAGRs were derived from fitted trend analysis applied to historical consumption patterns and projected regulatory-driven substitution timelines. Industry-specific inputs encompass automotive production forecasts from vehicle registration databases and aerospace OEM specification approval pipelines.
Petrochemical feedstock volatility, PFAS regulatory uncertainty, and aerospace procurement cycle timing are the dominant revision risks to modeled outputs. Forecasts reflect stated policy trajectories and announced OEM mandates. A small set of named triggers—ethylene price spikes, TSCA Section 5 restriction scope, and NADCAP specification changes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
High-Performance Descaling and Deliming Chemicals for HoReCa Equipment Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Efflorescence Remover Market
Cleaning Chemicals
Cement Surface Treatment Chemicals Market
Cleaning Chemicals
Eco-Label Certified Cleaning Chemicals for Professional Users Market
Cleaning Chemicals
Rust Remover Market
Cleaning Chemicals
Kitchen Vent Hood and Duct Cleaning Chemicals Market
Cleaning Chemicals
Industrial Degreaser Market
Cleaning Chemicals
Document Cleaning Powder Market
Cleaning Chemicals
Glass and Metal Cleaner Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Sanitizing Agents Market
Cleaning Chemicals
Commercial Deodorizers Market
Cleaning Chemicals
Cleaning Chemicals for Airports and Transport Hubs Market
Cleaning Chemicals
Surface Cleaning Products Market
Cleaning Chemicals
Electrostatic Liquid Cleaner Market