
 Detergent Chemicals Market | 2026-2036
Detergent Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Detergent Chemicals Market Intelligence
Asia-Pacific capacity expansion is reshaping supply dynamics for detergent chemicals. BASF SE leverages integrated surfactant complexes in Ludwigshafen to sustain cost leadership across European export markets. Evonik Industries AG anchors its position through enzyme technology leadership, while Croda International PLC differentiates via bio-based specialty surfactants for premium household brands.
Detergent chemicals comprise surfactants, enzymes, builders, and solvents formulated to reduce surface tension, emulsify soils, and suspend particulates in aqueous systems for cleaning applications. Anionic surfactants such as linear alkylbenzene sulfonates remain the dominant product type by volume, though enzyme segments command margin pools through concentrated dosing formats. The household end user channel absorbs the largest share of output, while industrial applications in food processing and healthcare textiles represent the fastest-growing demand segment due to hygiene protocol intensification.
REACH registration requirements and the EU Green Deal constrain petrochemical-derived surfactant formulations, while EPA Safer Choice and state-level phosphate bans in the US reshape product compliance thresholds. India's BIS quality standards and PLI scheme for chemical manufacturing create dual pressure on import substitution and export competitiveness. Stakeholders must monitor regulatory divergence between biodegradable mandates in Europe and cost-sensitive performance standards in emerging manufacturing hubs.
Market Dynamics
REACH registration deadlines and EU Green Deal mandates are forcing surfactant manufacturers to reformulate petrochemical-derived chemistries toward biodegradable alternatives, compressing legacy supply chains while enzyme suppliers capture margin from concentrated dosing formats.
Growth Catalysts
- Healthcare hygiene protocols:Industrial laundries in hospital and hospitality sectors are expanding chemical procurement volumes to meet infection control standards. This end-use vertical absorbs specialized surfactant and enzyme formulations at elevated dosing frequencies.
- India PLI scheme:India's production-linked incentive scheme for chemical manufacturing is drawing capacity investments into domestic surfactant complexes. Urbanization and rising household penetration of machine washing accelerate local demand absorption.
- Enzyme technology maturation:Protease and lipase engineering advances enable cold-water efficacy and reduced water consumption. These biocatalysts command premium positioning in concentrated detergent formats.
Market Restraints
- Palm kernel oil price volatility:Fatty alcohol feedstock costs fluctuate with Malaysian and Indonesian plantation yields and biodiesel policy arbitrage. This input concentration exposes margin structures to commodity cycles.
- REACH registration burden:ECHA compliance costs for existing surfactant substances create asymmetric pressure on smaller formulators versus integrated majors with dedicated regulatory affairs functions.
- Phosphate builder substitution:Zeolite and citrate alternatives underperform in hard water regions, creating technical performance gaps that constrain reformulation speed in certain geographies.
Strategic Opportunities
- Industrial food processing:Clean-in-place detergent systems for dairy and beverage equipment represent an underpenetrated application with stringent sanitation mandates. Enzyme-surfactant hybrid formulations address protein and fat soil complexity.
- EU Green Deal tailwind:Carbon border adjustment mechanisms and biodegradable mandates create regulatory preference for bio-based surfactant producers with certified supply chains.
- Direct-to-institutional channels:Industrial laundries and food processors are consolidating procurement through platform intermediaries, bypassing traditional distributor markups.
Industry Challenges
- Biocatalysis talent scarcity:Formulation chemists with enzyme stability and compatibility expertise command premium compensation, constraining R&D expansion at mid-tier producers.
- Legacy equipment incompatibility:Concentrated enzyme detergents require modified dosing systems in industrial laundries, creating retrofit capex friction and adoption delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Detergent Chemicals Market |
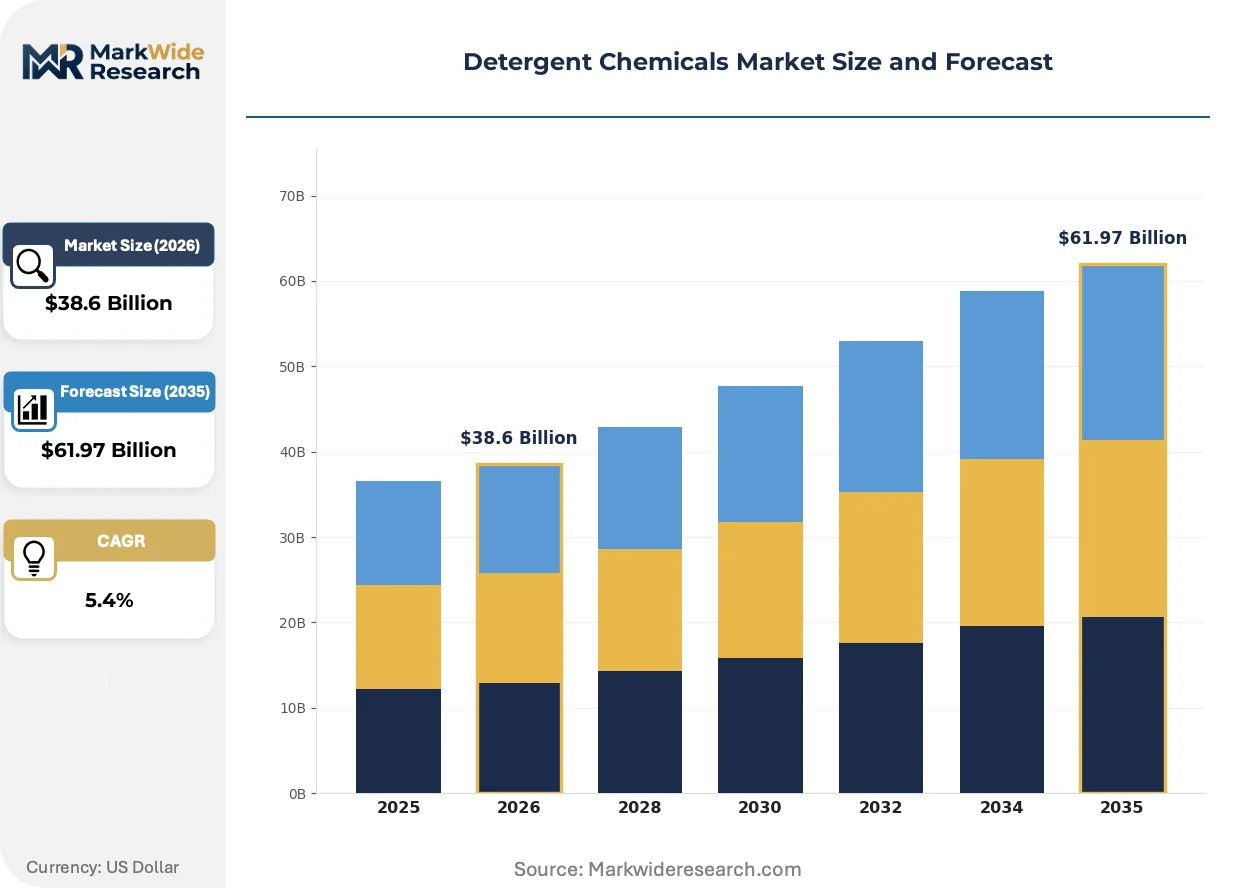
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $61.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Enzymes, Solvents, Builders End User: Household, Industrial, Institutional, Automotive Application: Fabric Cleaning, Dishwashing, Surface Cleaning, Hard Surface Care Distribution Channel: Retail, E-commerce, Direct Sales, Wholesale |
| Companies Covered | BASF SE, Evonik Industries AG, The Dow Chemical Company, Huntsman International LLC, Clariant AG, Croda International PLC, Akzo Nobel N.V., Stepan Company, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Detergent Chemicals Market Strategic Shifts & Innovations
Formulation chemistry is bifurcating between commodity surfactant cost optimization and specialty enzyme-driven performance premiums, with regulatory pressure compressing the viable middle ground.
Enzyme encapsulation technology is collapsing the stability-performance tradeoff that previously constrained protease incorporation in liquid detergents. Industrial laundries in Germany and the Netherlands are adopting cold-water enzyme systems at accelerated replacement cycles. This compression of temperature requirements is enabling energy cost reductions that justify formulation premiums.
REACH authorization timelines for petrochemical surfactants are tightening compliance windows for linear alkylbenzene sulfonate producers. ECHA restrictions on persistent organic pollutants are redirecting R&D expenditure toward bio-based alternatives. Household brand owners in France and Italy are reformulating ahead of regulatory deadlines to secure shelf positioning.
Buyer concentration among retail private-label programs is compressing supplier margins and demanding volume guarantees. Detergent chemical producers are responding with dedicated contract manufacturing arrangements that lock in offtake. This channel evolution is most visible in the UK and Poland where hard discounters command expanding shelf share.
Detergent Chemicals Market Segmentation
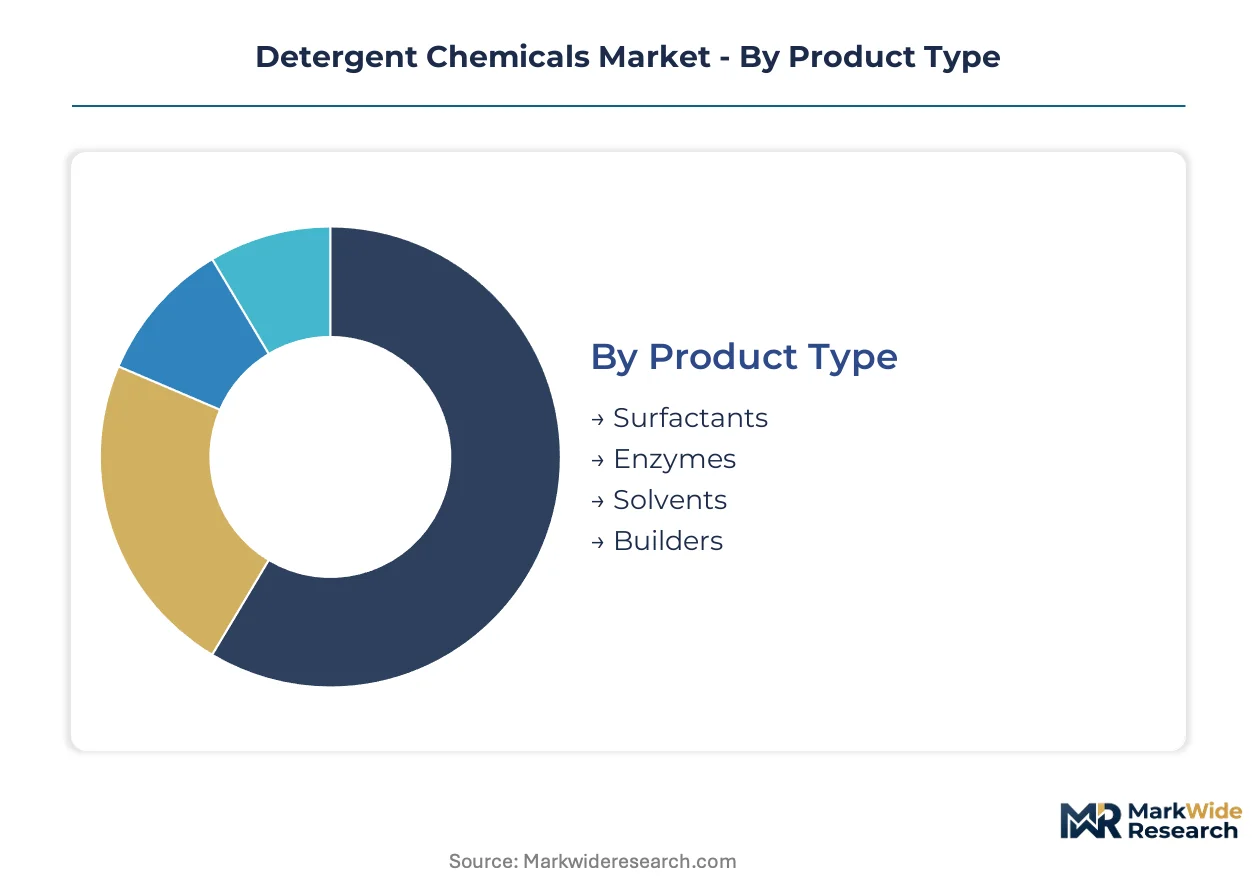
Detergent chemical procurement cycles vary dramatically across product categories and end-use channels. Surfactant volumes turn over rapidly in commodity household applications, while enzyme formulations command longer development timelines and stickier customer relationships. Understanding these velocity differentials shapes inventory positioning and R&D resource allocation.
Product Type:
Surfactants rotate through formulation trials fastest due to substitution elasticity, while enzymes lock in multi-year supply agreements once validated for stability.
- Surfactants:Anionic variants including linear alkylbenzene sulfonates constitute the foundational chemistry for bulk detergent manufacturing. Industrial laundries in Germany and the Netherlands are absorbing elevated volumes as cold-water protocols expand, though REACH registration deadlines compress supplier margins on petrochemical-derived grades.
- Enzymes:Protease and lipase biocatalysts enable concentrated dosing formats with reduced water and temperature requirements. Healthcare textile processors in France represent the steepest expansion trajectory for enzyme-surfactant hybrid systems as infection control standards intensify.
- Solvents:Glycol ethers and alcohols dissolve hydrophobic soils in hard surface applications.
- Builders:Zeolite and citrate alternatives replace phosphate frameworks in regions with hard water constraints.
Surfactants dominate installed base. Enzymes are where expansion concentrates.
End User:
Procurement sophistication stratifies sharply between price-sensitive household buyers and specification-driven institutional purchasers.
- Household:Machine washing penetration in Indian urban centers absorbs the largest surfactant volumes globally. Private-label concentration among UK and Polish hard discounters compresses supplier margins and demands multi-year offtake guarantees.
- Industrial:Food processing clean-in-place systems require enzyme-surfactant hybrids for protein and fat soil removal. Dairy equipment sanitation mandates in the Netherlands are accelerating adoption of specialized formulations.
- Institutional:Hospital and hospitality laundries operate under stringent hygiene protocols with elevated dosing frequencies.
- Automotive:Vehicle wash formulations prioritize foam stability and spot-free rinsing characteristics.
Household commands volume leadership. Industrial applications are climbing the fastest.
Application:
Technical performance requirements diverge between soil suspension chemistry for textiles and hard surface wetting agents.
- Fabric Cleaning:Laundry detergents balance surfactant micelle formation with enzyme protein degradation. Cold-water efficacy standards in Germany are reformulating demand toward protease-heavy concentrates.
- Dishwashing:Manual and automatic formulations require distinct foam profiles and rinse characteristics. Hospitality sector procurement in France concentrates on automatic dishwashing enzymes for water conservation compliance.
- Surface Cleaning:All-purpose sprays and disinfectants target kitchen and bathroom soils.
- Hard Surface Care:Floor and countertop formulations emphasize streak-free drying and material compatibility.
Fabric cleaning anchors revenue. Dishwashing is gaining share fastest.
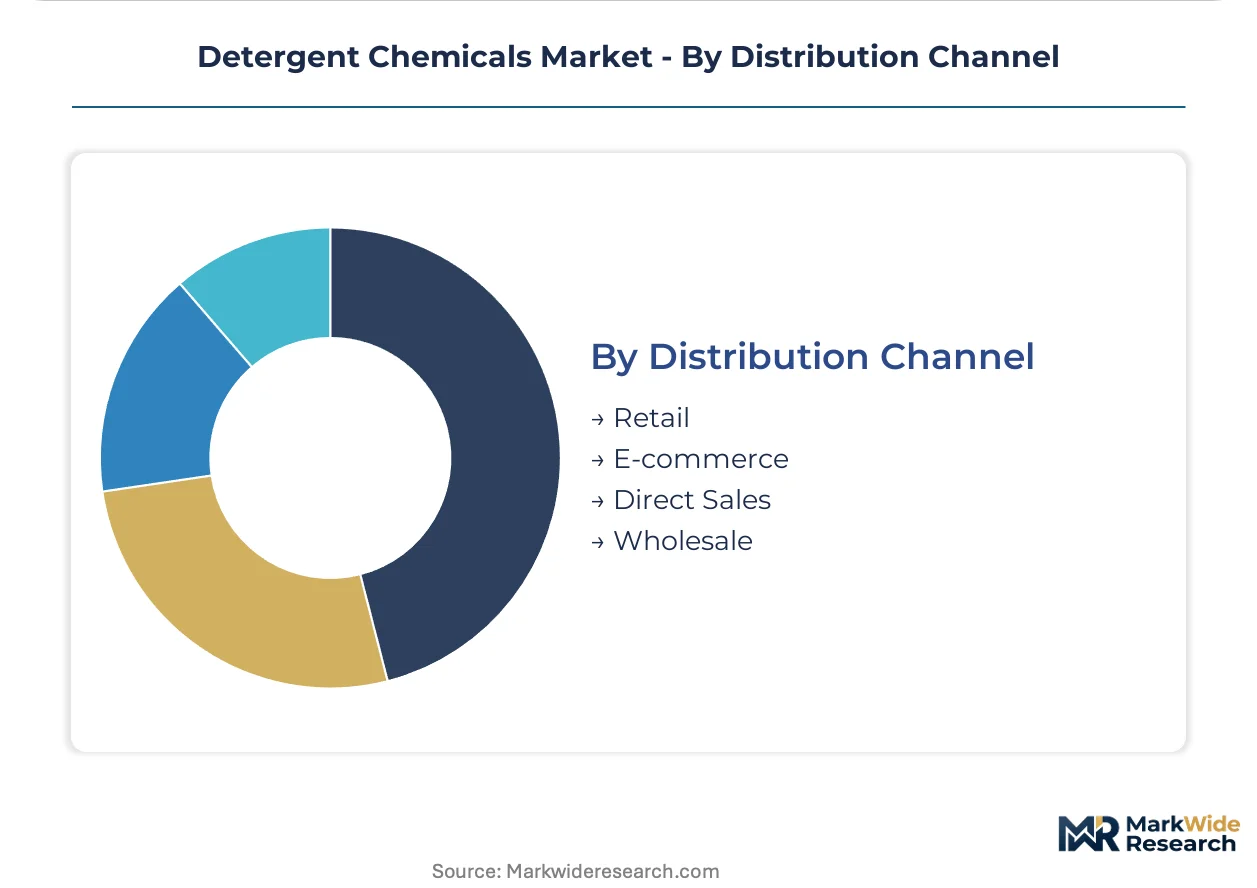
Distribution Channel:
Channel economics separate high-touch specification sales from low-margin volume throughput.
- Retail:Supermarket and hypermarket shelf space determines household brand visibility. Polish hard discounters are consolidating detergent chemical procurement through direct supplier negotiations, bypassing traditional distributor networks.
- E-commerce:Concentrated and subscription-formatted detergents align with direct-to-consumer logistics. Urban Indian households are absorbing rising e-commerce shares as machine washing penetration expands.
- Direct Sales:Industrial laundries and food processors negotiate specification-driven contracts.
- Wholesale:Distributor intermediaries serve fragmented institutional buyers with inventory buffering.
Retail maintains channel dominance. E-commerce is where volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated surfactant complexes cluster in Germany's Rhine corridor and India's western industrial belt, while enzyme technology leadership concentrates in specialized R&D hubs across France and the Netherlands. Regulatory fragmentation between REACH-mandated biodegradability in Europe and cost-sensitive performance standards in emerging manufacturing hubs creates divergent competitive terrain.
United States
Hospital and hospitality laundries in Texas and Florida are expanding chemical procurement volumes to meet CDC infection control protocols. EPA Safer Choice certification and state-level phosphate bans in California and New York reshape product compliance thresholds for surfactant formulators. The Gulf Coast petrochemical corridor sustains legacy anionic surfactant production even as enzyme concentrate adoption accelerates in Great Lakes industrial laundries.
Germany
Cold-water washing protocols in industrial laundries are absorbing elevated volumes of protease-heavy enzyme formulations. ECHA REACH registration deadlines and EU Green Deal mandates compress margins on petrochemical-derived linear alkylbenzene sulfonate grades. The Ludwigshafen chemical complex anchors integrated surfactant manufacturing serving export markets across Central and Eastern Europe.
India
Urban machine washing penetration in Mumbai and Delhi-NCR absorbs the largest surfactant volumes among emerging economies. The PLI scheme for chemical manufacturing draws capacity investments into Gujarat's domestic surfactant complexes. BIS quality standards create dual pressure on import substitution and export competitiveness for formulators targeting Southeast Asian markets.
France
Healthcare textile processors in Lyon and Marseille represent the steepest expansion trajectory for enzyme-surfactant hybrid systems. ANSM sanitation mandates and EU MDR spillover effects intensify infection control standards in hospital laundries. The Paris Basin concentrates premium household brand reformulation activity ahead of REACH authorization timelines.
Netherlands
Dairy equipment clean-in-place systems in Friesland and Noord-Brabant accelerate adoption of specialized enzyme-surfactant formulations. EU F-Gas Regulation and national water conservation compliance reshape automatic dishwashing procurement in hospitality sectors. The Rotterdam-Antwerp chemical cluster facilitates bio-based surfactant feedstock imports for European biodegradable reformulation.
Detergent Chemicals Market Key Industry Players
Integrated petrochemical majors and specialty enzyme houses split the market between commodity surfactant scale and biocatalytic performance premiums. The vendor base stratifies into three tiers: multinational chemical conglomerates with backward-integrated feedstock control, mid-tier regional formulators serving private-label programs, and niche technology licensors focused on encapsulation and stability engineering. Consolidation pressure concentrates among mid-tier players facing REACH registration cost asymmetry, while enzyme specialists capture margin through multi-year supply agreements with healthcare textile processors.
Within the integrated chemical conglomerate tier, BASF SE and Evonik Industries AG anchor opposing strategic positions—BASF exemplifying petrochemical-derived surfactant scale economics, Evonik representing enzyme technology leadership through protease and lipase engineering. Croda International PLC occupies a position bridging bio-based specialty surfactants for premium household brand reformulation. These three entities collectively represent the archetype spectrum from commodity cost leadership through performance-driven biocatalysis to certified sustainable chemistry.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| The Dow Chemical Company |
| Huntsman International LLC |
| Clariant AG |
| Croda International PLC |
| Akzo Nobel N.V. |
| Stepan Company |
| Solvay |
| Others |
Cost & Logistics Intelligence
Ludwigshafen's integrated surfactant complexes anchor European cost structures, with BASF SE's captive ethylene oxide supply conferring margin insulation that smaller formulators cannot replicate. This geographic concentration of backward-integrated capacity translates directly into pricing power across export markets in Central and Eastern Europe.
Pricing Analysis
REACH registration dictates the pricing tier structure across the European detergent chemicals landscape. Three-tier pricing structure across premium, standard, and economy levels separates bio-based specialty surfactants from petrochemical commodity grades and private-label economy formulations. Certification under EU Ecolabel and EPA Safer Choice commands measurable premiums in household channels. Pricing pressure stems from buyer concentration among UK and Polish hard discounters demanding multi-year offtake guarantees. Private-label programs exhibit highest price sensitivity; healthcare textile processors show lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Tariff exposure between Malaysia and Indonesia dominates feedstock risk calculations for fatty alcohol-dependent producers. Supply concentrates in Germany, India, and the Netherlands for surfactant manufacturing, with enzyme production anchored in France and Danish biotechnology clusters. Raw material dependencies rest on palm kernel oil, ethylene oxide, and specialized fermentation media for biocatalyst cultivation. Single-source vulnerability persists in encapsulated enzyme supply chains where stability engineering expertise concentrates among niche technology licensors. Distribution runs through platform intermediaries serving consolidated industrial laundries and food processors, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Detergent chemicals procurement is consolidating through platform intermediaries, creating network-effects dynamics reminiscent of platform economics in industrial distribution. Interoperability between concentrated enzyme dosing systems and legacy laundry equipment represents the critical ecosystem friction determining adoption velocity.
For Market Incumbents: Entrench specification control through multi-year supply agreements with healthcare textile processors in France and Germany. Deepen backward integration into bio-based feedstock certification chains to capture EU Green Deal preference. Counter private-label margin compression by locking in dedicated contract manufacturing arrangements with hard discounters in Poland and the UK. For New Entrants and Emerging Players: Establish a beachhead in clean-in-place systems for dairy equipment in the Netherlands, where ANSM-equivalent sanitation mandates create specification barriers incumbents have underinvested against. Penetrate enzyme-surfactant hybrid formulations for cold-water industrial laundries in Germany, where retrofit capex friction delays incumbent adoption. Pursue direct-to-institutional channel strategies bypassing distributor networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzyme encapsulation specialists with stability engineering IP and validated healthcare supply agreements. Long-term viability over the coming decade rests on biocatalysis capabilities displacing petrochemical surfactant volumes under tightening biodegradability mandates. Acquisition target archetype: niche technology licensors with proprietary encapsulation platforms and sticky relationships with hospital laundry operators. Watch for inflection in cold-water washing protocol adoption rates across German and Dutch industrial laundries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | EU Green Deal and ECHA REACH deadlines favor producers with certified sustainable supply chains. |
| Enzyme Encapsulation Technology Licensing | Stability-performance tradeoff collapse in liquid detergents commands premium positioning in concentrates. |
| Direct-to-Institutional Channel Development | Platform intermediaries serving consolidated laundries bypass distributor markups and capture specification relationships. |
| Capacity Expansion in Gujarat Surfactant Complexes | India's PLI scheme and BIS standards create dual pressure on import substitution and export competitiveness. |
| Long-term Supply Agreements with Healthcare Textile Processors | ANSM and EU MDR spillover effects intensify infection control standards and dosing frequency requirements. |
Research Approach
A spread of perspectives from plant managers at integrated surfactant complexes, procurement leads at industrial laundries, distribution channel partners, and technical R&D directors in enzyme engineering converged on the working assumptions. Primary interview insights combined with secondary validation from customs and trade data, Cefic industry reports, SEC 10-K filings, and BIS quality standard documentation. Bottom-up volume modeling triangulated against top-down market sizing across product categories and end-use channels.
Demand-supply-balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled include surfactant grade tier, end-use industry vertical, enzyme concentration format, and regional production hub clustering. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology substitution curves. Industry-specific forecast inputs incorporated REACH registration timeline impacts and PLI scheme capacity absorption rates.
Sensitivities concentrate around palm kernel oil price volatility, REACH authorization timeline acceleration, and cold-water protocol adoption rates in industrial laundries. Forecasts reflect documented assumptions on regulatory enforcement intensity and biocatalysis technology maturation curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Asia Pacific Surfactants Market
Surfactants
Trisiloxane Market
Surfactants
Micellar Water Market
Surfactants
Global Fluorosurfactants Market
Surfactants
Dioctyl Sulfosuccinates Components Market
Surfactants
Tetrabutylammonium Bromide Market
Surfactants
Benzyl Trimethyl Ammonium Chloride Market
Surfactants
Surfactant Cleansers and Adjuvants Market
Surfactants
Sodium Lauroyl Glycinate Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Glycol Monostearate Market
Surfactants
Natural Surfactants Market
Surfactants
Secondary Alkane Sulfonate Market
Surfactants
Bitumen Emulsifier Market
Surfactants
Cocomonoethanolamide (CMEA) Market
Surfactants
Sodium Lauryl Sulphate Market