
 Green Surfactants Market | 2026-2036
Green Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Green Surfactants Market Outlook
EU Ecolabel certification for detergents and cleaning products is rotating competitive access across Europe, filtering out legacy petrochemical surfactants that fail biodegradability and aquatic toxicity benchmarks. BASF SE leverages its Ludwigshafen integrated site to sustain captive bio-based feedstock streams for alkyl polyglucoside production. Croda International Plc anchors its position through botanical oil fractionation expertise that extends into high-purity non-ionic surfactants for prestige personal care. Evonik Industries AG competes via fermentation-derived rhamnolipid capacity that differentiates its microbial surfactant portfolio from conventional oleochemical routes.
Green surfactants are surface-active compounds derived from renewable biomass or microbial fermentation, typically featuring hydrophilic sugar or amino acid head groups bonded to hydrophobic fatty acid tails, with critical micelle concentrations ranging from 0.01 to 1.0 g/L depending on carbon chain length and head group chemistry. These compounds reduce interfacial tension in aqueous systems to enable detergency, emulsification, and wetting across formulated consumer and industrial products. Non-ionic surfactants from plant-based sources dominate volume due to mature alkyl polyglucoside supply chains and broad pH stability, while microbial anionic variants represent the fastest-expanding margin pool as rhamnolipid and sophorolipid production scales down cost curves. Personal care end users command premium positioning through certification-driven ingredient transparency, whereas industrial cleaning absorbs commoditized liquid formulations where cost parity with petroleum-derived alternatives remains the decisive procurement criterion.
REACH registration requirements and the EU Green Deal's chemical sustainability strategy compel surfactant suppliers to submit full biodegradation and ecotoxicology dossiers, effectively raising fixed compliance costs that favor larger producers with dedicated regulatory affairs teams. The ECHA's ongoing restrictions on per- and polyfluoroalkyl substances further redirect formulation R&D toward bio-based fluorine-free alternatives in specialty cleaning segments. Stakeholders must monitor how the EU's forthcoming criteria for safe-and-sustainable-by-design chemicals will redefine acceptable feedstock provenance and process carbon intensity thresholds before the next regulatory consultation cycle closes.
Market Dynamics
REACH registration dossiers and the EU Green Deal's chemical sustainability strategy are compressing supplier margins while concentrating procurement authority among formulators with dedicated regulatory affairs infrastructure.
Growth Catalysts
- REACH Biodegradability Thresholds:Stricter aquatic toxicity benchmarks under ECHA guidance are filtering legacy petrochemical surfactants from rinse-off cosmetics formulations across Germany and France.
- EU Ecolabel Certification:Personal care brands specify certified surfactants for transparency positioning, creating procurement pull through Germany's Rhine-Ruhr chemical cluster.
- Microbial Fermentation Scaling:Rhamnolipid and sophorolipid production curves are compressing cost differentials against oleochemical routes in industrial cleaning applications.
Market Restraints
- Feedstock Price Volatility:Palm kernel and coconut oil price swings destabilize alkyl polyglucoside cost structures for producers without captive plantation contracts.
- Supply Concentration Risk:Specialty surfactant capacity clusters in Germany's Ludwigshafen site create single-point vulnerability for European formulators.
- Technical Performance Gaps:Microbial anionic surfactants exhibit narrower pH stability windows than non-ionic plant-based alternatives, limiting application breadth.
Strategic Opportunities
- Industrial Cleaning Penetration:Cost parity achievement in bio-based liquid formulations opens volume absorption in Germany's institutional and food-processing sanitation sectors.
- Safe-and-Sustainable-by-Design Criteria:Upcoming EU consultation cycles will redefine acceptable process carbon intensity thresholds, rewarding early feedstock provenance documentation.
- Fluorine-Free Specialty Cleaning:ECHA restrictions on per- and polyfluoroalkyl substances redirect R&D investment toward bio-based alternatives in electronics and aerospace maintenance.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Full ecotoxicology dossier preparation requires specialized toxicologists and environmental chemists in short supply across European chemical clusters.
- Certification Timeline Compression:EU Ecolabel approval cycles lag formulation innovation velocity, delaying product launch windows for premium personal care lines.
- Legacy System Integration:Microbial surfactant feedstocks require fermentation infrastructure incompatible with conventional oleochemical processing trains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Surfactants Market |
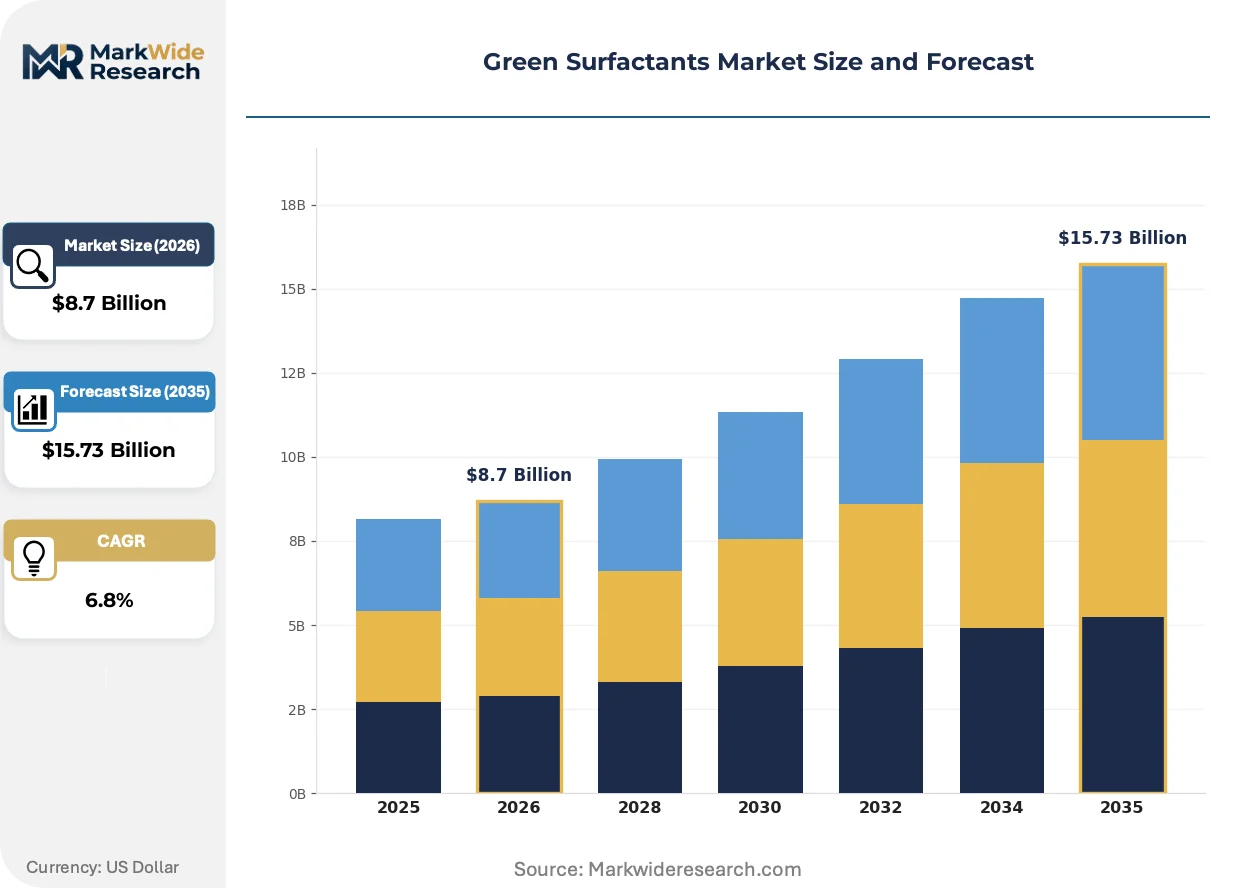
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anionic, Cationic, Non-Ionic, Amphoteric End User: Personal Care, Home Care, Industrial Cleaning, Agriculture Source: Plant-Based, Microbial, Synthetic, Animal-Based Formulation: Liquid, Powder, Granular, Paste |
| Companies Covered | Solvay S.A., Akzo Nobel N.V., BASF SE, Stepan Company, Kao Corporation, Clariant AG, Dow Inc., Evonik Industries AG, Croda International Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Surfactants Market Strategic Shifts
Fermentation-derived biosurfactants and regulatory disclosure requirements are restructuring competitive access while procurement criteria harden around certification transparency.
Continuous fermentation technology for rhamnolipid production is decomposing batch-to-batch variability that previously constrained microbial surfactant adoption. Specialty chemical producers in Germany's Rhine-Ruhr cluster deploy these systems to secure supply contracts with home care compounders seeking feedstock security. The technology is decomposing the historical cost premium that separated microbial routes from plant-based oleochemistry.
ECHA's evolving restrictions on per- and polyfluoroalkyl substances are redirecting formulation portfolios toward bio-based fluorine-free alternatives in precision cleaning segments. The regulation compresses addressable market scope for legacy surfactant suppliers while expanding qualified supplier lists for microbial biosurfactant producers. Electronics manufacturing and aerospace maintenance sectors in Germany and France are accelerating substitution timelines in response.
Ingredient transparency mandates from personal care brands are hardening procurement specifications around EU Ecolabel certification and carbon footprint documentation. Formulators now require full supply chain provenance disclosure from surfactant suppliers, displacing spot-market purchasing with multi-year offtake agreements. This pattern concentrates most visibly in Germany's personal care manufacturing corridor, where rinse-off cosmetics brands specify certified bio-based surfactants for shelf positioning.
Green Surfactants Market Segmentation
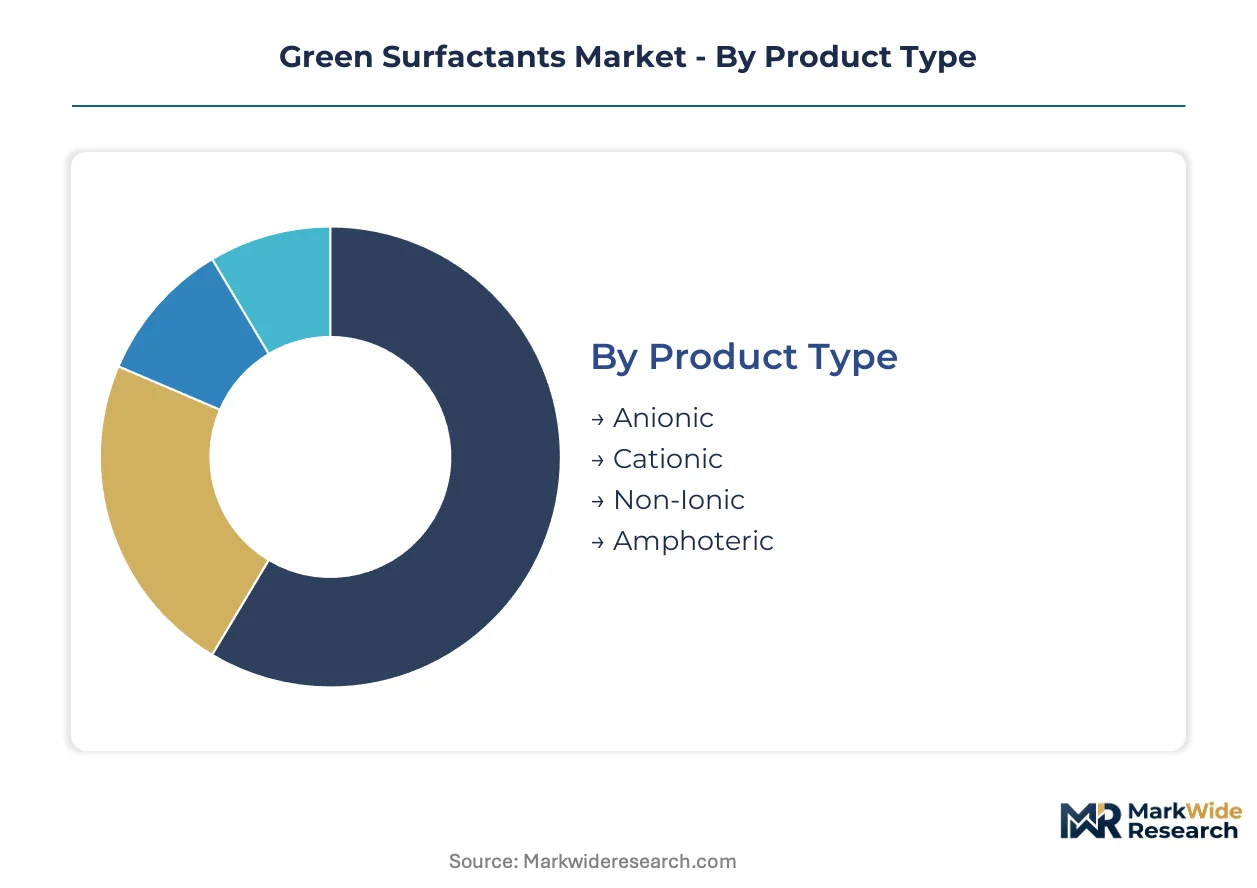
Surfactant procurement channels diverge sharply by segment chemistry and certification requirements. Formulators route plant-based non-ionics through bulk liquid distributors while microbial specialty grades move via direct technical sales relationships.
Product Type:
Channel strategy varies by ionic charge—non-ionics flow through commodity distributors, anionics through technical specialists, cationics via pharmaceutical-grade channels, and amphoterics through personal care ingredient houses.
- Non-Ionic:Alkyl polyglucosides and alkyl glucamides dominate volume through mature supply chains. German home care compounders in the Rhine-Ruhr cluster absorb the majority of EU Ecolabel-certified non-ionic volumes for dishwasher and laundry applications.
- Anionic:Rhamnolipids and sophorolipids from fermentation routes exhibit superior foaming and emulsification. French and German personal care brands specify microbial anionics for rinse-off cosmetics where REACH aquatic toxicity thresholds filter conventional petrochemical alternatives.
- Cationic:Quaternary ammonium compounds from plant oils serve conditioning applications in premium hair care.
- Amphoteric:Betaine derivatives balance mildness with cleansing efficacy in facial cleansers.
Non-ionic surfactants dominate installed base. Anionic microbial variants are where expansion concentrates.
End User:
Margin structure separates these verticals—personal care commands certification premiums, home care operates at cost parity thresholds, industrial cleaning absorbs commodity volumes, agriculture tolerates performance variability for price.
- Personal Care:Rinse-off cosmetics brands in Germany and France specify EU Ecolabel-certified surfactants with full supply chain provenance disclosure. Procurement has shifted from spot-market purchasing to multi-year offtake agreements with documented carbon footprints.
- Home Care:Dishwashing and laundry formulations absorb the largest surfactant volumes across Europe. Germany's institutional sanitation sector is accelerating bio-based liquid adoption as rhamnolipid production achieves cost parity with oleochemical routes.
- Industrial Cleaning:Food-processing and electronics manufacturing sectors require precision cleaning performance.
- Agriculture:Biopesticide formulations and soil wetting agents utilize lower-purity biosurfactant grades.
Home Care commands volume leadership. Personal Care is climbing the fastest on margin expansion.
Source:
Feedstock provenance now determines regulatory access—plant-based routes hold certification advantage, microbial routes gain through REACH compliance, synthetic routes face displacement, animal-based routes confront ethical sourcing scrutiny.
- Plant-Based:Coconut and palm kernel oil fractions supply alkyl polyglucoside production with established fractionation infrastructure. BASF's Ludwigshafen integrated site maintains captive bio-based feedstock streams that insulate against palm kernel price volatility.
- Microbial:Fermentation-derived rhamnolipids and sophorolipids bypass agricultural commodity exposure. Continuous fermentation technology in Germany's Rhine-Ruhr cluster is decomposing batch variability that previously constrained microbial surfactant adoption.
- Synthetic:Petrochemical routes face ECHA biodegradability threshold compression.
- Animal-Based:Tallow derivatives persist in select industrial niches.
Plant-Based sources anchor current supply. Microbial routes are gaining share fastest on regulatory tailwinds.
Formulation:
Physical form dictates logistics economics—liquids suit high-volume automated dosing, powders enable concentrated shipping, granules dissolve for specific applications, pastes deliver viscosity for specialty formats.
- Liquid:Bulk tanker deliveries serve high-throughput home care compounders. Germany's food-processing sanitation sector is standardizing on liquid bio-based formulations where dilution systems reduce handling costs.
- Powder:Spray-dried alkyl polyglucosides enable concentrated laundry detergent tablets. French and German manufacturers specify powder grades for compacted unit-dose products requiring rapid dissolution.
- Granular:Controlled-release formats suit agricultural soil applications.
- Paste:High-viscosity concentrates target manual dishwashing and specialty cleaners.
Liquid formulations dominate throughput economics. Powder formats are where innovation concentrates for concentrated consumer products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH biodegradability mandates and EU Ecolabel procurement specifications are concentrating green surfactant demand across European chemical clusters. National implementation timelines vary, creating differentiated competitive access windows.
Germany
Rhine-Ruhr chemical compounders absorb certified alkyl polyglucoside volumes for dishwasher and laundry formulations. ECHA aquatic toxicity thresholds filter legacy petrochemical surfactants from rinse-off cosmetics. Ludwigshafen integrated sites sustain captive bio-based feedstock streams for non-ionic production.
France
Personal care brands specify EU Ecolabel-certified microbial anionics for transparency positioning. ANSM disclosure requirements harden ingredient provenance documentation for rinse-off products. Paris-region formulators lock multi-year offtake agreements with fermentation-derived surfactant suppliers.
United States
EPA Safer Choice program specifications redirect institutional cleaning procurement toward bio-based liquid formulations. Food-processing sanitation sectors standardize on dilution-system-compatible surfactants. Midwest chemical manufacturing corridors absorb commodity-grade alkyl polyglucoside volumes.
China
Dual carbon goals compress synthetic surfactant capacity expansion permits. NMPA green chemistry guidelines favor fermentation-derived biosurfactants in domestic personal care. Yangtze River Delta home care compounders pilot rhamnolipid integration for export-oriented detergent production.
India
BIS biodegradable detergent standards accelerate oleochemical surfactant substitution in mass-market laundry powders. Maharashtra and Gujarat chemical clusters expand alkyl polyglucoside fractionation capacity. Domestic coconut oil supply chains insulate producers against palm kernel price volatility.
Green Surfactants Market Competitive Environment
Player mix skews toward integrated chemical conglomerates with captive fermentation infrastructure and regulatory affairs scale. Market structure concentrates procurement authority among formulators with dedicated ECHA dossier preparation teams. Strategic archetypes separate into integrated petrochemical diversifiers, specialty oleochemical fractionators, and microbial fermentation specialists. Dominant competitive moves include backward integration into plantation feedstock contracts and technology licensing for continuous fermentation systems.
Among European-based integrated producers, BASF SE and Evonik Industries AG occupy positions reflecting divergent feedstock strategies. BASF anchors the plant-based non-ionic segment through Ludwigshafen site integration. Evonik exemplifies microbial fermentation specialization with rhamnolipid capacity scaling. Croda International Plc represents the botanical oil fractionation archetype extending into high-purity personal care grades. These three structures illustrate how regulatory compliance scale and feedstock provenance documentation are separating viable suppliers from spot-market players.
| Leading Market Players |
|---|
| Solvay S.A. |
| Akzo Nobel N.V. |
| BASF SE |
| Stepan Company |
| Kao Corporation |
| Clariant AG |
| Dow Inc. |
| Evonik Industries AG |
| Croda International Plc |
| Others |
Value Chain & Pricing Dynamics
Rhamnolipid substitution for alkyl polyglucosides in German institutional cleaning contracts is redrawing supply geography toward Rhine-Ruhr fermentation clusters while compressing price premiums that previously separated microbial from plant-based routes. This feedstock pivot simultaneously concentrates procurement leverage among compounders with multi-year offtake agreements and destabilizes spot-market pricing for legacy oleochemical volumes.
Pricing Analysis
Certification tier—EU Ecolabel versus uncertified commodity grades—creates the primary price spread across European procurement channels. Three-tier pricing structure separates premium-certified personal care grades from standard home care formulations and economy industrial cleaning volumes. Price differentiation reflects REACH dossier completion costs and carbon footprint documentation depth. Pricing pressure stems from continuous fermentation technology scaling in Germany, which erodes the cost gap between microbial and plant-based production. Industrial cleaning buyers exhibit highest price sensitivity, while personal care brands absorb premiums for provenance transparency.
Supply Chain Analysis
Inventory cycles for fermentation-derived surfactants run longer than oleochemical alternatives due to batch qualification protocols and ECHA registration lead times. Supply concentrates in Germany, France, and the Netherlands, with Rhine-Ruhr chemical clusters hosting integrated production for both plant-based and microbial routes. Raw material dependencies center on palm kernel oil fractions, coconut oil supplies, and glucose feedstocks for fermentation. Single-source vulnerability exists for EU Ecolabel-certified volumes from Ludwigshafen-integrated sites. Distribution runs through bulk liquid tanker networks for home care compounders and technical ingredient houses for personal care formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a regulatory-entrenchment defensive moat: REACH dossier preparation costs and EU Ecolabel certification timelines create switching costs that lock formulators into qualified supplier relationships and marginalize spot-market competitors.
For Market Incumbents: Secure captive bio-based feedstock streams through plantation contracts or fermentation infrastructure expansion in the Rhine-Ruhr corridor. Defend against emerging microbial specialists by accelerating continuous fermentation capacity additions that match rhamnolipid cost curves. Prioritize regulatory affairs team scaling to compress EU Ecolabel approval cycles for premium personal care lines. For New Entrants and Emerging Players: Differentiate on fermentation-derived specialty grades for electronics and aerospace precision cleaning where ECHA fluorine restrictions displace legacy surfactants. Target France's personal care transparency corridor with documented carbon footprint offerings that bypass established oleochemical supply relationships. Pursue technical partnership routes with home care compounders seeking feedstock security rather than commodity spot-market penetration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed microbial fermentation specialists in Germany possessing rhamnolipid production scale but lacking downstream formulation relationships. Five-to-ten year viability hinges on safe-and-sustainable-by-design criteria adoption velocity. Monitor EU consultation cycle closures as the inflection signal for feedstock provenance documentation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Feedstocks | Captive palm kernel and coconut oil supplies insulate BASF and Croda from commodity price volatility. |
| Continuous Fermentation Scale-Up | Rhine-Ruhr deployment of rhamnolipid production technology decomposes batch variability and cost premiums. |
| EU Ecolabel Certification Acceleration | Compressed approval timelines enable premium personal care positioning before regulatory consultation cycles close. |
| Fluorine-Free Specialty Formulation Development | ECHA PFAS restrictions redirect electronics and aerospace maintenance procurement toward bio-based alternatives. |
| Multi-Year Offtake Agreement Structuring | Provenance disclosure requirements in Germany and France displace spot purchasing with contracted supply security. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with technical R&D directors at specialty surfactant producers, procurement leads at home care compounders, regulatory affairs managers navigating REACH dossier preparation, and channel partners in European ingredient distribution. Secondary validation drew from ECHA registration databases, EU Ecolabel certification records, Cefic chemical industry reports, and customs trade data for bio-based feedstock flows. Bottom-up volume modeling triangulated against top-down market sizing across product type, end-use vertical, and source category dimensions.
Across the analysis window, projections integrated historical capacity utilization trends, fermentation technology cost curve trajectories, and regulatory implementation timelines. Segmentation modeling captured non-ionic versus anionic versus cationic chemistry splits, personal care versus home care versus industrial cleaning end-use concentrations, and plant-based versus microbial versus synthetic source trajectories. CAGRs were derived from regression analysis of certified surfactant procurement volumes and substitution elasticity estimates for petrochemical displacement.
Material uncertainties—feedstock price volatility, regulatory consultation outcomes, and fermentation yield improvements—sit outside the modeled envelope. Forecasts reflect documented assumptions about REACH biodegradability threshold enforcement and EU Ecolabel adoption velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Cationic Surfactants Market
Surfactants
Alkylamines Market
Surfactants
Calcium Stearoyl-2 Lactylate Market
Surfactants
Global Rhamnolipid Market
Surfactants
Non-Ionic Surfactants Market
Surfactants
Asia Pacific Surfactants Market
Surfactants
Zeolite for Detergents Market
Surfactants
Cetyl Trimethyl Ammonium Chloride Market
Surfactants
Coconut Derived Surfactants Market
Surfactants
Fatty Methyl Ester Sulfonate Market
Surfactants
Amino Acid Surfactants Market
Surfactants
Sugar-Based Surfactants Market
Surfactants
MDEA Esterquats Market
Surfactants
Detergent Grade Zeolite Market
Surfactants
Isopropyl Myristate Market
Surfactants
Microemulsions Market