
 Emulsifying Wax Market | 2026-2036
Emulsifying Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Emulsifying Wax Market Analysis
Specialty chemical producers in Germany is decoupling from commodity fatty alcohol supply chains to secure dedicated emulsifying wax streams. BASF SE leverages backward integration into ethoxylation assets to control input costs for synthetic grades. Croda International anchors its position through botanical sourcing networks for natural emulsifying wax variants. Kao Corporation competes in Asia through specialized micro-emulsion technologies for sensitive-skin formulations.
Emulsifying wax denotes a blended surfactant system, typically comprising cetostearyl alcohol combined with ionic or non-ionic emulsifiers such as polysorbate 60 or sodium lauryl sulfate, manufactured through controlled esterification and ethoxylation processes to achieve hydrophilic-lipophilic balance values between 9 and 12 for stable oil-in-water dispersions. Synthetic product types dominate volume flows due to reproducible batch consistency and lower raw material variance, while natural segments command premium positioning as clean-label formulations gain traction in cosmetics and personal care applications. Micro-emulsion grades represent the fastest-expanding category, driven by pharmaceutical demand for transparent, thermodynamically stable topical delivery systems with enhanced bioavailability.
FDA monograph requirements for over-the-counter topical products and REACH registration obligations under ECHA govern emulsifier purity thresholds, surfactant biodegradability, and labeling transparency across cosmetic and pharmaceutical channels. BIS certification in India and GB standards in China add compliance layers for manufacturers targeting multi-jurisdictional distribution. Stakeholders must monitor evolving biocompatibility testing protocols and regional green chemistry mandates to anticipate reformulation costs and qualification timelines.
Market Dynamics
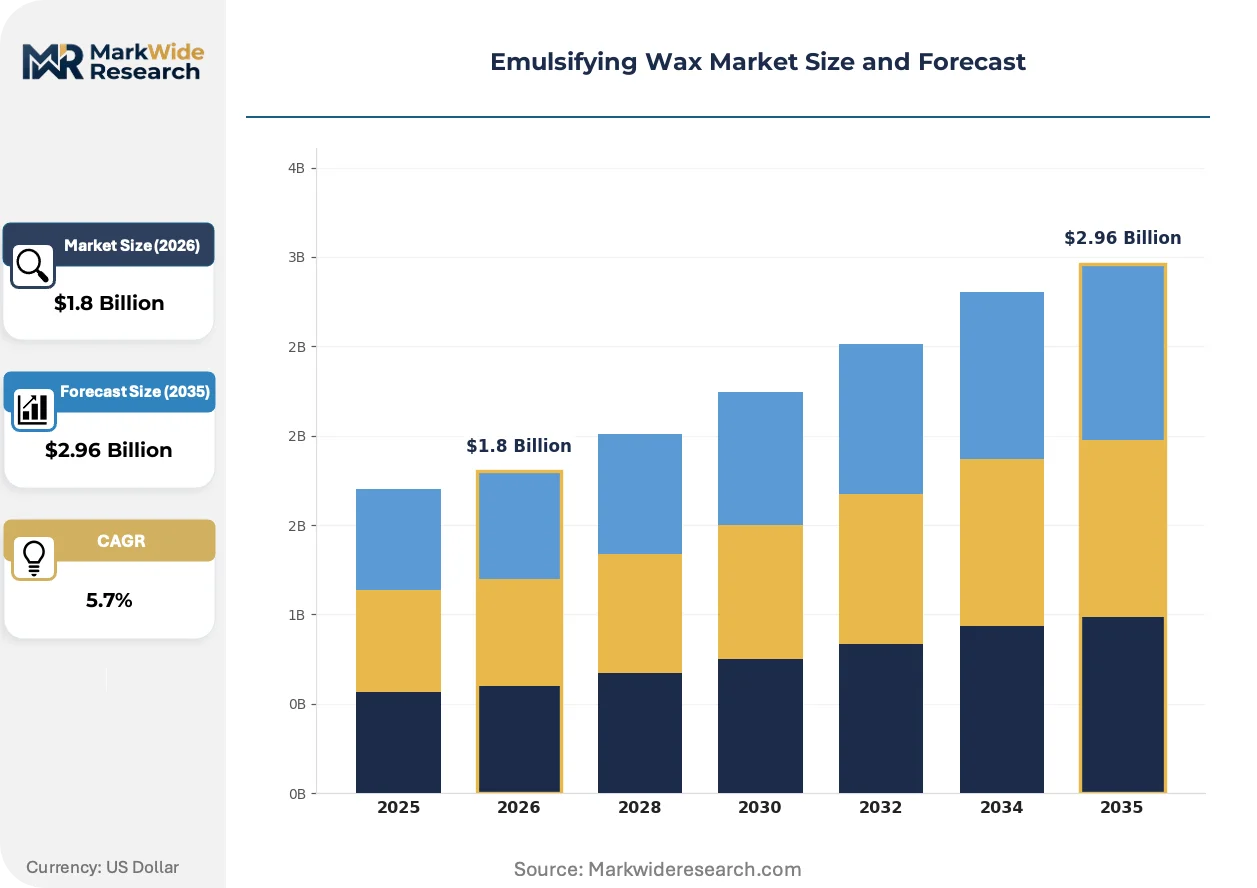
Pharmaceutical formulation labs are driving structural transformation through expanded procurement of emulsifying waxes for topical drug delivery systems, while REACH compliance in Europe and evolving FDA monograph standards simultaneously tighten purity benchmarks across cosmetic and pharmaceutical channels.
Growth Catalysts
- Topical Drug Delivery Expansion:Pharmaceutical labs are scaling emulsifying wax procurement for micro-emulsion systems that enhance bioavailability in dermatological and transdermal therapies.
- REACH Purity Mandates:ECHA registration obligations under REACH are compelling manufacturers to upgrade purification processes, creating qualification barriers that favor established suppliers with compliance infrastructure.
- India Contract Manufacturing Surge:Domestic Indian manufacturers are scaling output for export-oriented personal care brands, concentrating demand growth in Mumbai and Ahmedabad production clusters.
Market Restraints
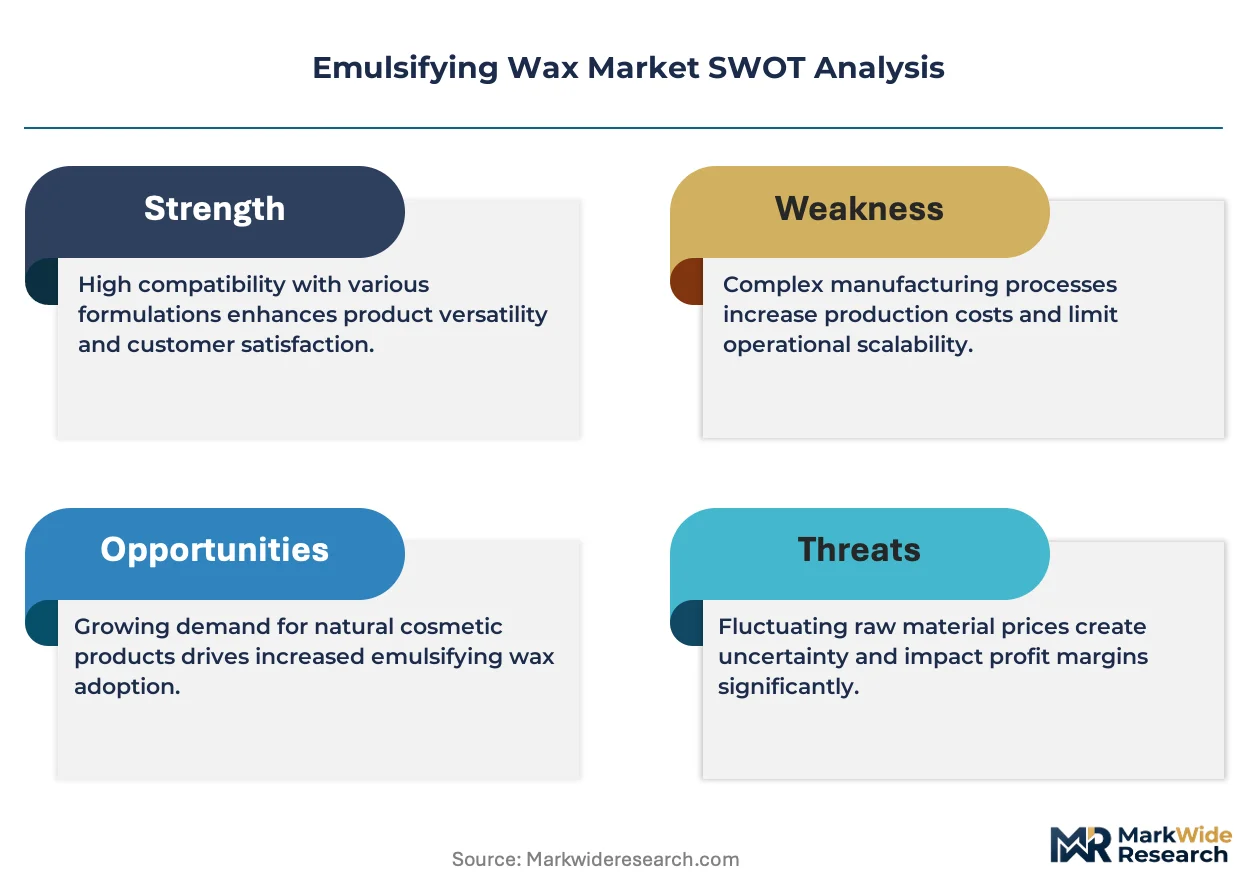
- Cetostearyl Alcohol Price Volatility:Fatty alcohol feedstock costs fluctuate with palm oil and coconut oil commodity cycles, compressing margins for non-integrated producers.
- German Supply Chain Decoupling:Specialty chemical producers in Germany are securing dedicated emulsifying wax streams outside commodity fatty alcohol markets, creating access constraints for smaller buyers.
- Natural Grade Performance Limitations:Botanical-sourced emulsifying waxes exhibit higher batch-to-batch variance in hydrophilic-lipophilic balance values, limiting their adoption in pharmaceutical applications requiring reproducible specifications.
Strategic Opportunities
- Micro-Emulsion Technology Convergence:The intersection of nano-dispersion science and pharmaceutical formulation is opening transparent, thermodynamically stable delivery systems for sensitive-skin therapeutics.
- BIS Certification Arbitrage:India's Bureau of Indian Standards certification requirements for personal care ingredients create first-mover advantages for suppliers qualifying ahead of domestic contract manufacturer procurement waves.
- Clean-Label Premium Positioning:Natural emulsifying wax variants command pricing power as cosmetic formulators reformulate away from synthetic ethoxylated surfactants in North American and European clean-beauty segments.
Industry Challenges
- Multi-Jurisdictional Qualification Timelines:Simultaneous FDA monograph alignment, REACH registration, and BIS certification create extended product launch cycles exceeding eighteen months for new emulsifier grades.
- Ethoxylation Asset Intensity:Backward integration into ethoxylation capacity requires capital deployment for reactor systems and hazardous chemical handling infrastructure that mid-scale producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emulsifying Wax Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Semi-Synthetic, Micro-emulsion Application: Cosmetics, Pharmaceuticals, Food Production, Personal Care End User: Manufacturers, Retailers, Distributors, Direct Consumers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Clariant, Huntsman Corporation, BASF SE, Sasol Limited, Altana AG, Croda International, Evonik Industries, Kao Corporation, Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emulsifying Wax Market Emerging Trajectories
Formulation science and regulatory stringency are converging to reshape emulsifying wax specifications, with micro-emulsion technologies, biocompatibility mandates, and procurement centralization emerging as the dominant vectors of change.
Micro-emulsion-grade emulsifying wax systems is consolidating technical leadership in pharmaceutical applications through transparent, thermodynamically stable oil-in-water dispersions with enhanced drug-loading capacity. Dermatology labs and transdermal patch manufacturers in Germany and Switzerland are adopting these grades at accelerated pace for sensitive-skin therapeutics. This consolidation is compressing demand for conventional macro-emulsion systems in premium pharmaceutical channels while establishing new performance benchmarks that commodity suppliers cannot meet.
REACH registration obligations under ECHA are tightening surfactant biodegradability thresholds and labeling transparency requirements for cosmetic-grade emulsifiers distributed across European channels. The regulation is forcing reformulation cycles among personal care brands sourcing from non-integrated suppliers lacking dedicated compliance infrastructure. Natural emulsifying wax segments face the steepest adaptation costs as botanical sourcing networks must document supply chain traceability to satisfy evolving green chemistry mandates.
Buyer consolidation among contract manufacturers is compressing supplier negotiation cycles and unbundling technical service components from bulk emulsifying wax contracts. Large personal care formulators in India and Southeast Asia are centralizing procurement through dedicated supply agreements with backward-integrated producers, displacing spot-market purchasing. This pattern is most visible in Mumbai and Ahmedabad, where export-oriented manufacturers are qualifying fewer, larger suppliers to streamline multi-jurisdictional compliance documentation.
Emulsifying Wax Market Segmentation
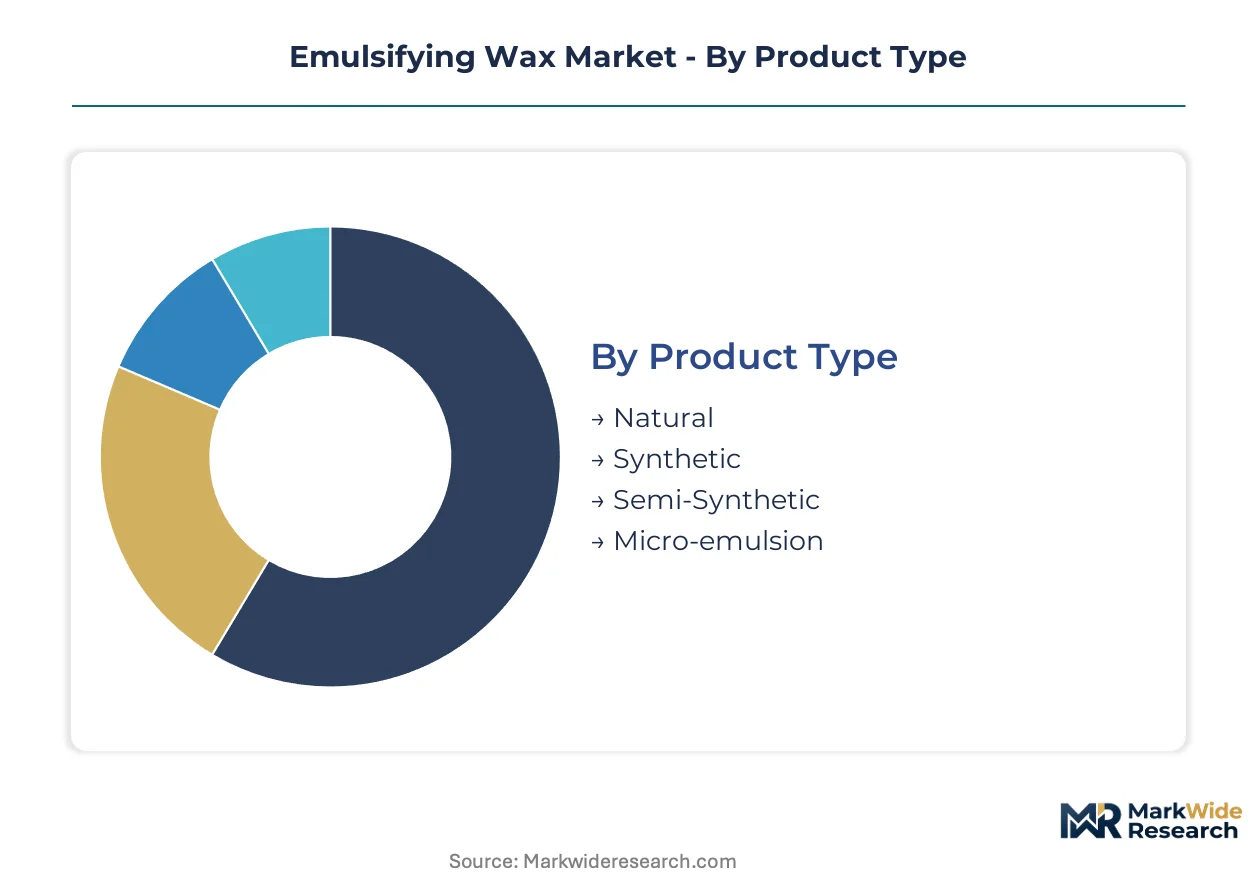
Emulsifying wax procurement patterns diverge sharply across product chemistry and end-use specifications. Pharmaceutical formulators prioritize batch reproducibility while cosmetic brands weight clean-label positioning, creating distinct qualification barriers that reshape supplier economics.
Product Type:
Synthetic grades demand the heaviest capital deployment for ethoxylation reactor systems and hazardous chemical handling infrastructure.
- Natural:Botanical-sourced variants derived from plant waxes and fatty acid esters exhibit higher batch-to-batch variance in hydrophilic-lipophilic balance values. Demand concentrates in North American and European clean-beauty segments where formulators reformulate away from ethoxylated surfactants to capture premium positioning.
- Synthetic:Manufactured through controlled esterification of petrochemical feedstocks, these grades deliver reproducible HLB values between 9 and 12. Pharmaceutical labs in Germany and Switzerland scale procurement for dermatological applications where specification tolerance is tightest.
- Semi-Synthetic:Hybrid formulations blend modified natural fatty alcohols with synthetic emulsifier components, balancing cost stability with partial clean-label appeal.
- Micro-emulsion:Nano-dispersion systems achieve thermodynamic stability with enhanced drug-loading capacity for transparent topical delivery.
Most installed capacity flows through Synthetic. Expansion is steepest in Micro-emulsion.
Application:
Pharmaceutical channels generate the highest margin per kilogram due to extended qualification timelines and documentation burdens.
- Cosmetics:Color cosmetics and skincare formulations utilize emulsifying waxes for texture stabilization and pigment dispersion. Mumbai-based contract manufacturers drive procurement volume for export-oriented brands supplying European retailers.
- Pharmaceuticals:Micro-emulsion systems for transdermal patches and dermatological therapies command technical premiums. FDA monograph alignment and EMA quality documentation create multi-year supplier lock-in effects.
- Food Production:Food-grade emulsifying waxes stabilize confectionery coatings and edible oil dispersions under FSSAI and FDA food additive regulations.
- Personal Care:Hair conditioners and body lotions represent high-volume, specification-flexible demand from mass-market formulators.
Pharmaceutical applications yield the highest unit economics. Personal Care generates the largest absolute tonnage.
End User:
Manufacturer procurement is consolidating toward dedicated supply agreements that bundle technical service with volume commitments.
- Manufacturers:Personal care and pharmaceutical formulators in India and Germany centralize procurement through backward-integrated suppliers to streamline REACH and BIS compliance documentation.
- Retailers:Private-label skincare brands source emulsifying waxes through toll manufacturing arrangements, outsourcing formulation expertise.
- Distributors:Regional chemical distributors serve mid-scale cosmetic formulators with spot-market purchasing and technical advisory services.
- Direct Consumers:Artisan soap makers and small-batch cosmetic producers purchase packaged emulsifying wax blends through specialty ingredient portals.
Manufacturers command the deepest supplier relationships. Direct Consumers represent the most fragmented, price-sensitive tier.
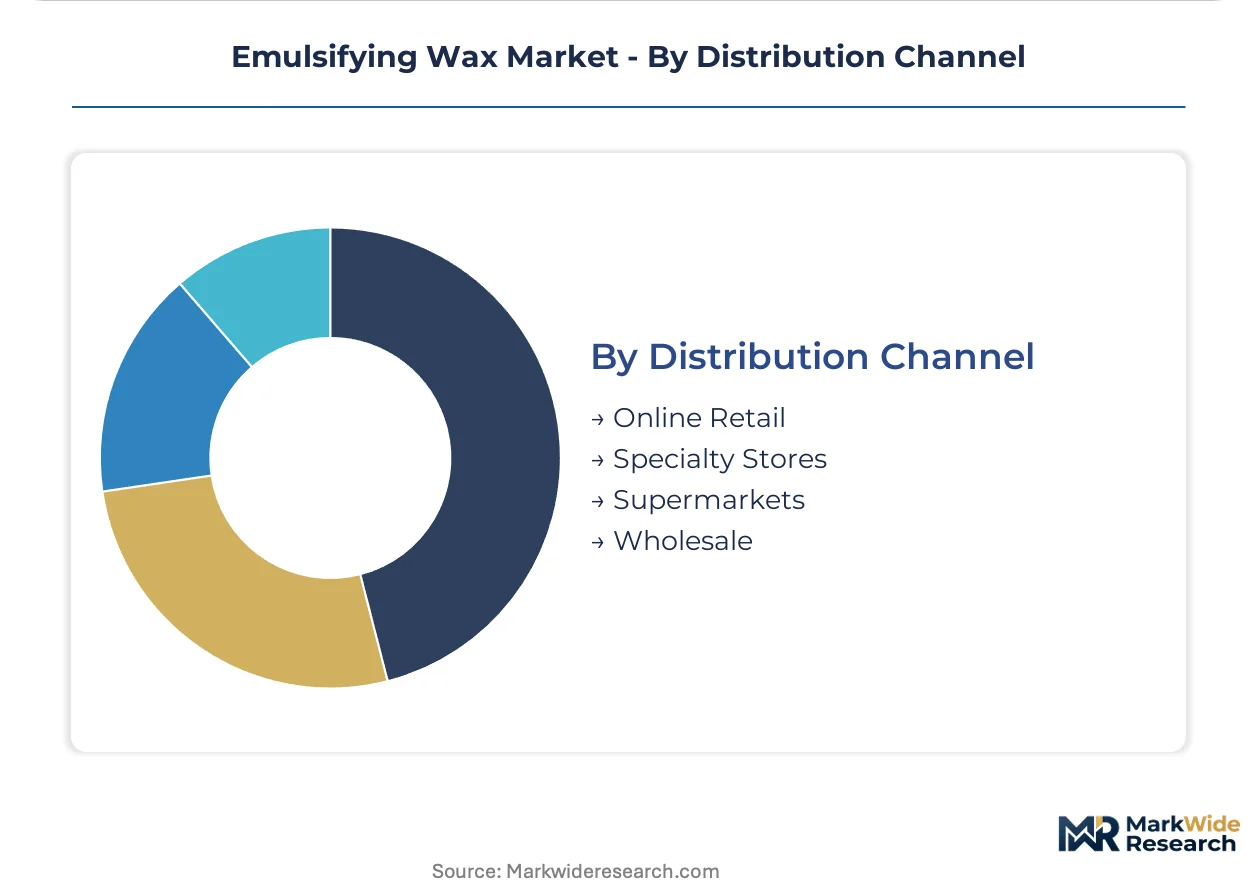
Distribution Channel:
Wholesale channels retain dominance for bulk pharmaceutical and industrial cosmetic procurement.
- Online Retail:Digital platforms serve small-batch formulators and artisan producers with packaged kilogram-scale quantities and technical specification sheets.
- Specialty Stores:Cosmetic ingredient boutiques in Seoul and Tokyo supply independent formulators with natural-grade emulsifying wax variants.
- Supermarkets:Mass-market channels distribute pre-formulated emulsifying wax blends for home cosmetic crafting segments.
- Wholesale:Bulk tanker and drum shipments flow through chemical distributors to pharmaceutical labs and contract manufacturers in Ahmedabad and Mumbai production clusters.
Wholesale channels handle the largest shipment volumes. Online Retail is gaining share fastest among non-industrial buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration toward jurisdictions with streamlined compliance documentation is redrawing supply chain maps. Manufacturers are qualifying dedicated wax streams in lower-cost regulatory environments to serve multi-jurisdictional pharmaceutical and cosmetic channels.
Germany
Specialty chemical producers in the Rhine-Ruhr and Bavarian clusters are decoupling from commodity fatty alcohol markets to secure captive emulsifying wax supply. ECHA REACH registration obligations enforce surfactant biodegradability thresholds that favor integrated producers with in-house purification infrastructure. BASF SE leverages backward integration into ethoxylation assets at Ludwigshafen to control input costs for synthetic pharmaceutical grades.
India
Domestic contract manufacturers in Mumbai and Ahmedabad production clusters are scaling output for export-oriented personal care brands supplying European retailers. BIS certification requirements for cosmetic ingredients create qualification barriers that concentrate procurement among pre-qualified suppliers. CDSCO pharmaceutical regulations align with FDA monograph standards for topical drug delivery systems, enabling dual-market production from Gujarat-based formulation labs.
United States
FDA monograph requirements for over-the-counter topical products govern emulsifier purity thresholds and labeling transparency across cosmetic and pharmaceutical distribution. Dermatology labs in New Jersey and California accelerate procurement of micro-emulsion grades for transdermal patch manufacturing. EPA oversight of ethoxylation process emissions shapes capital deployment decisions for reactor system upgrades.
Switzerland
Swissmedic quality documentation requirements for pharmaceutical excipients create multi-year supplier lock-in effects that favor established emulsifying wax producers. Dermatology research centers in Basel and Geneva adopt transparent thermodynamically stable delivery systems for sensitive-skin therapeutics. Precision formulation standards exceed EU baseline thresholds, compressing demand for commodity-grade supplies.
Japan
METI industrial standards and PMDA pharmaceutical regulations govern emulsifier biocompatibility testing protocols for topical drug applications. Cosmetic formulators in the Kansai region reformulate toward natural emulsifying wax variants to capture clean-label positioning in domestic and Southeast Asian export markets. Osaka-based personal care manufacturers centralize procurement through dedicated supply agreements with backward-integrated regional suppliers.
Emulsifying Wax Market Vendor Landscape
German producers anchor the premium synthetic tier; Japanese and Indian specialists hold positions in natural-grade and contract manufacturing segments. The vendor base separates into three distinct strata: multinational chemical conglomerates with ethoxylation assets, regional botanical sourcing networks, and mid-scale hybrid producers blending modified natural feedstocks. Strategic moves concentrate on securing dedicated supply streams outside commodity markets and accelerating qualification timelines for micro-emulsion pharmaceutical grades.
Within the integrated chemical conglomerate tier, BASF SE and Croda International exemplify divergent sourcing strategies. BASF SE represents backward-integrated producers controlling petrochemical feedstock through captive ethoxylation capacity. Croda International anchors the botanical sourcing archetype through plant-based fatty acid ester networks. Kao Corporation occupies a position bridging specialty surfactant technology with Asia-Pacific formulation science for sensitive-skin applications.
| Leading Market Players |
|---|
| Clariant |
| Huntsman Corporation |
| BASF SE |
| Sasol Limited |
| Altana AG |
| Croda International |
| Evonik Industries |
| Kao Corporation |
| Lubrizol Corporation |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap producers in Gujarat and Maharashtra anchor India's emulsifying wax supply base, deploying patient capital that resists margin compression during cetostearyl alcohol price cycles and sustains pricing discipline through long-term contract manufacturing relationships.
Pricing Analysis
Distributor margin layers separate bulk tanker shipments from packaged kilogram-scale sales to artisan formulators. Three-tier pricing structure across pharmaceutical-grade, cosmetic-certified, and industrial-economy levels reflects FDA monograph alignment costs and REACH registration burdens. Pricing pressure stems from palm oil feedstock volatility squeezing non-integrated compounders. Contract manufacturers in Mumbai exhibit highest price sensitivity; Swiss dermatology labs demonstrate lowest.
Supply Chain Analysis
Skilled chemical process technicians concentrate in Germany's Ludwigshafen corridor and India's Ahmedabad specialty chemical belt. Manufacturing gravity centers on Germany, India, and Japan. Feedstock draws from Malaysian palm oil estates, Philippine coconut plantations, and petrochemical ethylene streams. Single-source vulnerability runs through concentrated ethoxylation reactor capacity. Distribution runs through wholesale chemical distributors serving pharmaceutical labs and cosmetic contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The emulsifying wax market functions as a stable compounder, with pharmaceutical formulation expansion providing steady demand visibility that smooths cyclical feedstock volatility.
For Market Incumbents: Deploy backward integration into ethoxylation assets to capture margin from captive cetostearyl alcohol processing and insulate against commodity price swings. BASF SE's Ludwigshafen model demonstrates how in-house reactor systems neutralize feedstock volatility. Simultaneously, accelerate BIS certification timelines ahead of Indian contract manufacturer procurement waves to lock in multi-year supply agreements before qualification barriers rise. For New Entrants and Emerging Players: Specialty cosmetic ingredient boutiques in Seoul and Tokyo represent underexploited channel partners for natural-grade emulsifying wax variants. White-space concentrates in micro-emulsion pharmaceutical grades where Swissmedic documentation requirements deter commodity suppliers. Target dermatology research centers in Basel and Geneva with transparent thermodynamically stable delivery systems. Go-to-market leverage rests on pre-qualification for REACH registration to bypass eighteen-month incumbent lock-in periods. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Indian producers with BIS certification and CDSCO alignment already secured. Five-to-ten-year viability hinges on pharmaceutical channel penetration rather than cosmetic spot-market exposure. Acquisition archetype: Gujarat-based manufacturers with established export relationships to European personal care brands. Signal to watch: acceleration in Mumbai and Ahmedabad production cluster capacity utilization as contract manufacturers consolidate procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethoxylation Assets | BASF SE's Ludwigshafen captive supply neutralizes palm oil price volatility for pharmaceutical grades. |
| BIS Certification Pre-Qualification | First-mover certification ahead of Indian contract manufacturer waves secures multi-year supply lock-in. |
| Micro-Emulsion Technology Development | Swiss dermatology labs in Basel adopt transparent delivery systems for sensitive-skin therapeutics. |
| Botanical Sourcing Network Expansion | Croda International's plant-based fatty acid ester networks capture clean-label premium in European cosmetics. |
| Long-Term Supply Agreement Structuring | Osaka-based personal care manufacturers centralize procurement through dedicated backward-integrated contracts. |
Methodological Framework
Direct dialogue with pharmaceutical formulation scientists, cosmetic contract manufacturing procurement leads, specialty chemical plant managers, and REACH compliance consultants grounded qualitative findings. Secondary validation drew from ECHA registration databases, FDA monograph filings, BIS certification records, and ACC specialty chemical trade data. Bottom-up volume estimates from individual production facilities triangulated against top-down demand modeling from end-use consumption patterns.
Segment-level outputs across the projection horizon reflect disaggregated modeling by product chemistry, application specification, and regional regulatory cluster. CAGRs derived from weighted average growth assumptions across synthetic, natural, semi-synthetic, and micro-emulsion grade tiers. Forecast inputs incorporated ethoxylation capacity expansion timelines, REACH registration qualification backlogs, and Indian contract manufacturer capacity utilization trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to palm oil commodity cycles, ECHA biodegradability mandate evolution, and FDA monograph reformulation timelines. Material deviation in pharmaceutical lab procurement acceleration or German supply chain decoupling velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Global Demulsifiers Market
Surfactants
Amino Acid Surfactants Market
Surfactants
Dodecanol Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
Asia Pacific Biosurfactants Market
Surfactants
Alcohol Ether Sulfates Market
Surfactants
Calcium Stearoyl-2 Lactylate Market
Surfactants
Bitumen Emulsifier Market
Surfactants
Oil-in-Water Anionic Emulsifier Market
Surfactants
Amino Silicone Oil Market
Surfactants
Soap Salts Market
Surfactants
Sodium Methyl Cocoyl Taurate Market
Surfactants
Global Barium Petroleum Sulfonate Market
Surfactants
Cationic Surfactants Market
Surfactants
Disodium Laureth Sulfosuccinate Market
Surfactants
Chlorooctane Market