
 Cetyl Chloride Market | 2026-2036
Cetyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Cetyl Chloride Market Analytics
Specialty surfactant formulators are reorganizing procurement priorities toward higher-purity cetyl chloride liquid grades for premium personal care applications. Hubei BlueSky New Material leverages integrated chlorination infrastructure to serve domestic emulsifier producers. Vertellus Specialties anchors North American supply through backward integration into fatty alcohol feedstocks. IOL Chemicals and Pharmaceuticals Limited competes on pharmaceutical-grade certification, differentiating from commodity surfactant suppliers.
Cetyl chloride is a long-chain alkyl halide synthesized via chlorination of cetyl alcohol, typically yielding a product with chlorine content between 21-23% and melting points near 12°C, functioning primarily as an intermediate for quaternary ammonium compounds and specialty surfactants. Cetyl chloride liquid dominates volume flows due to easier handling in continuous surfactant manufacturing, while cetyl chloride flakes command margin premiums in pharmaceutical salt formulations where moisture control is critical. The emulsifying agent application leads absolute demand from personal care end users, though conditioning agent applications in hair care are expanding fastest as silicone-free formulations proliferate.
REACH registration requirements in Europe and EPA TSCA Section 5 scrutiny in the United States constrain market access for unregistered import volumes, while China's MEE enforcement of chlorinated byproduct discharge standards elevates compliance costs for Shandong and Jiangsu producers. India's BIS quality certification for food-grade emulsifiers adds a secondary gate for suppliers targeting food processing end users. Stakeholders must monitor feedstock palm kernel oil price volatility and regional chlorination capacity utilization to time procurement and qualification investments.
Market Dynamics
Specialty surfactant formulators are reorganizing procurement priorities toward higher-purity cetyl chloride liquid grades for premium personal care applications. This demand pivot is compressing margins for commodity-grade producers while rewarding integrated chlorination operators with captive fatty alcohol supply.
Growth Catalysts
- REACH registration pathways:European ECHA compliance requirements are filtering out unregistered import volumes, creating protected market access for qualified suppliers with full substance dossiers.
- Silicone-free hair care formulations:Conditioning agent applications are expanding fastest as cosmetic brands reformulate away from silicones, pulling cetyl chloride into quaternary ammonium compound synthesis.
- Jiangsu-Zhejiang chlorination clusters:Concentrated capacity in these coastal provinces enables just-in-time supply to domestic emulsifier producers, reducing logistics costs for downstream personal care manufacturers.
Market Restraints
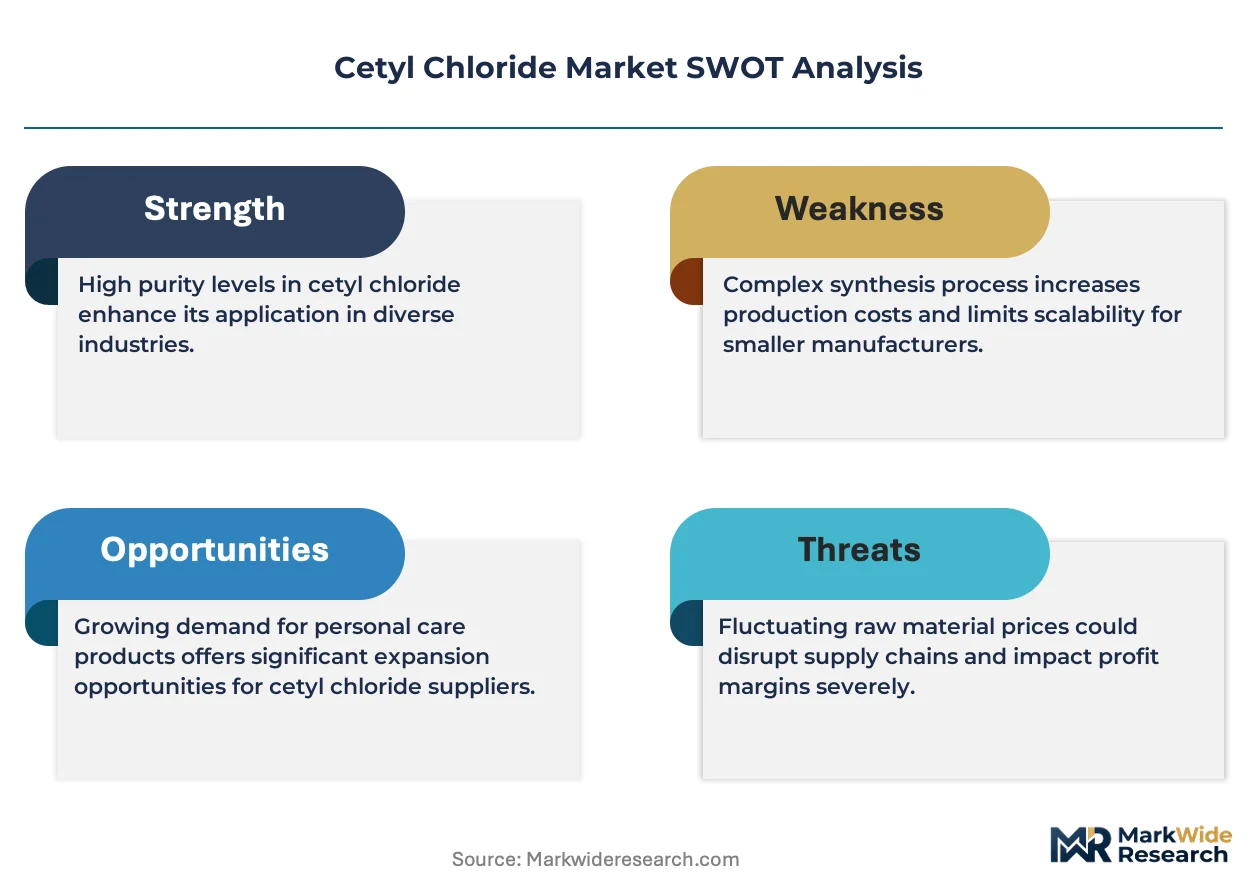
- Palm kernel oil feedstock volatility:Raw material price swings in vegetable oil markets transmit directly to cetyl alcohol costs, compressing chlorination margins without forward-contract hedging.
- Shandong-Jiangsu regulatory enforcement:China's MEE chlorinated byproduct discharge standards are elevating wastewater treatment capital requirements for legacy chlorination assets.
- EPA TSCA Section 5 scrutiny:New chemical notification requirements in the United States constrain market access for unregistered import volumes, lengthening qualification timelines.
Strategic Opportunities
- Pharmaceutical-grade certification:Moisture-critical salt formulations command margin premiums for flake-grade producers with GMP-compliant manufacturing infrastructure.
- India BIS food-grade pathway:Quality certification for food processing emulsifiers opens a secondary demand channel beyond personal care applications.
- Green chemistry mandates:China's evolving environmental compliance frameworks are redirecting supply chain qualification toward producers with closed-loop chlorination processes.
Industry Challenges
- Chlorination process engineering talent:Specialized expertise in continuous alkyl halide synthesis is concentrated among aging technical workforces in legacy chemical manufacturing regions.
- Multi-jurisdiction registration synchronization:Aligning REACH, EPA TSCA, and China MEE compliance timelines strains regulatory affairs capacity at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cetyl Chloride Market |
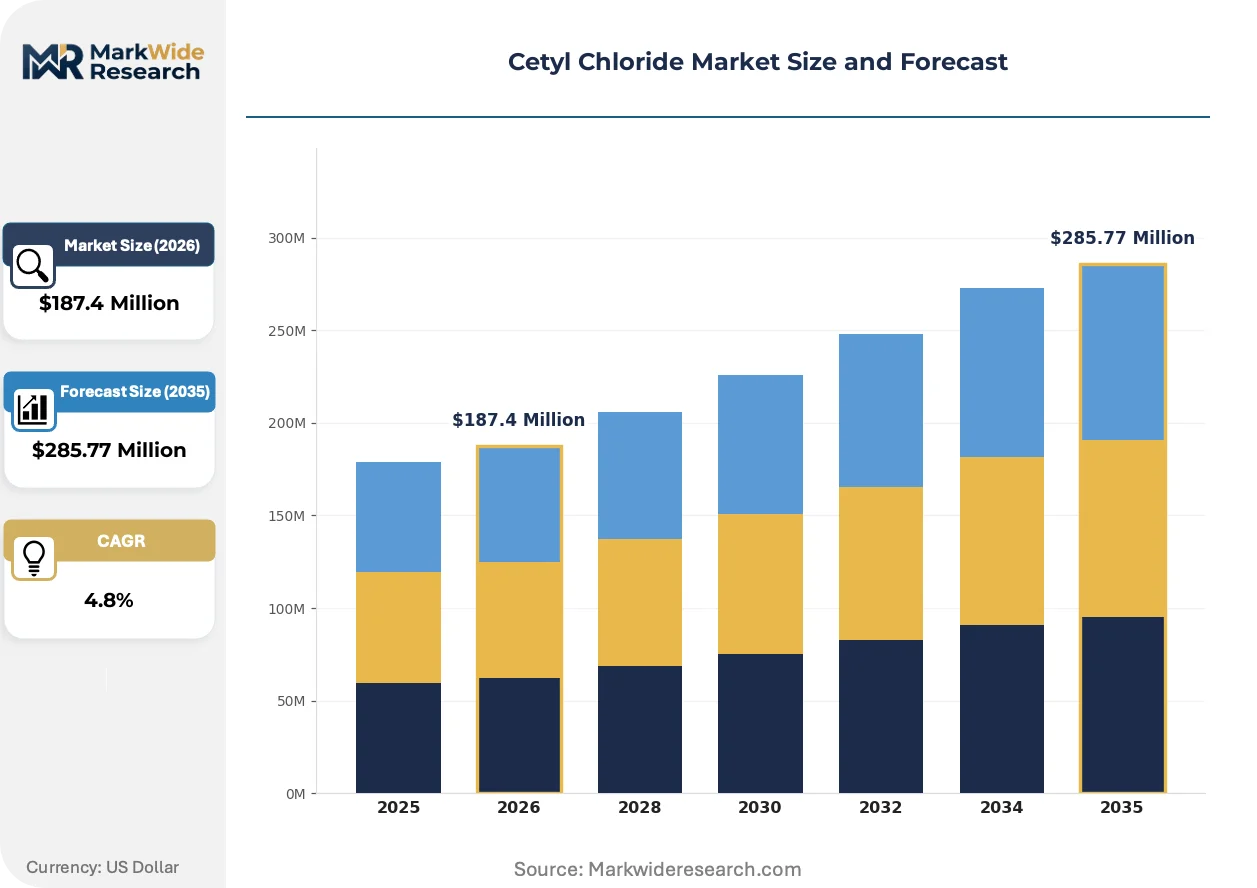
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cetyl Chloride Flakes, Cetyl Chloride Liquid, Cetyl Chloride White Powder, Cetyl Chloride Crystal Application: Emulsifying Agent, Surfactant, Thickeners, Conditioning Agent End User Industry: Personal Care, Pharmaceuticals, Food Processing, Textile Packaging Type: Drum, Bag, Bottle, Pail |
| Companies Covered | Hubei BlueSky New Material INC, Shandong Taihe Technologies Co. Ltd, Aquapharm Chemical Pvt. Ltd, Dongying Huatai Fine Chemical Co. Ltd, Changzhou Zhongyao, Excel Industries Ltd, IOL Chemicals and Pharmaceuticals Limited, Vertellus Specialties, CABB Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cetyl Chloride Market Evolving Landscape
Continuous processing technologies and regulatory qualification frameworks are reshaping competitive positioning in cetyl chloride manufacturing. Producers are investing in integrated chlorination infrastructure to capture margin from specification-grade demand.
Liquid-grade cetyl chloride is bifurcating the market between continuous surfactant manufacturers and batch pharmaceutical processors. Personal care formulators in Europe and North America are consolidating procurement around single-source liquid supply agreements with integrated producers. This technology divide is compressing spot-market volumes while locking in contracted premiums for qualified suppliers with dedicated tank-car logistics.
REACH registration requirements in Europe are tightening substance dossier standards for long-chain alkyl halides. ECHA is demanding enhanced toxicological endpoints for reproductive toxicity and environmental fate, extending registration timelines for new market entrants. Commodity-grade suppliers without existing dossiers are retreating from European personal care channels toward less regulated industrial applications.
Buyer concentration among multinational personal care brands is consolidating procurement around qualified supplier lists with full regulatory coverage. Tier-one formulators in Germany, France, and the United States are demanding auditable chain-of-custody documentation from fatty alcohol through chlorination. This certification-driven preference shift is marginalizing traders and non-integrated producers without backward control over feedstock sourcing.
Cetyl Chloride Market Segmentation
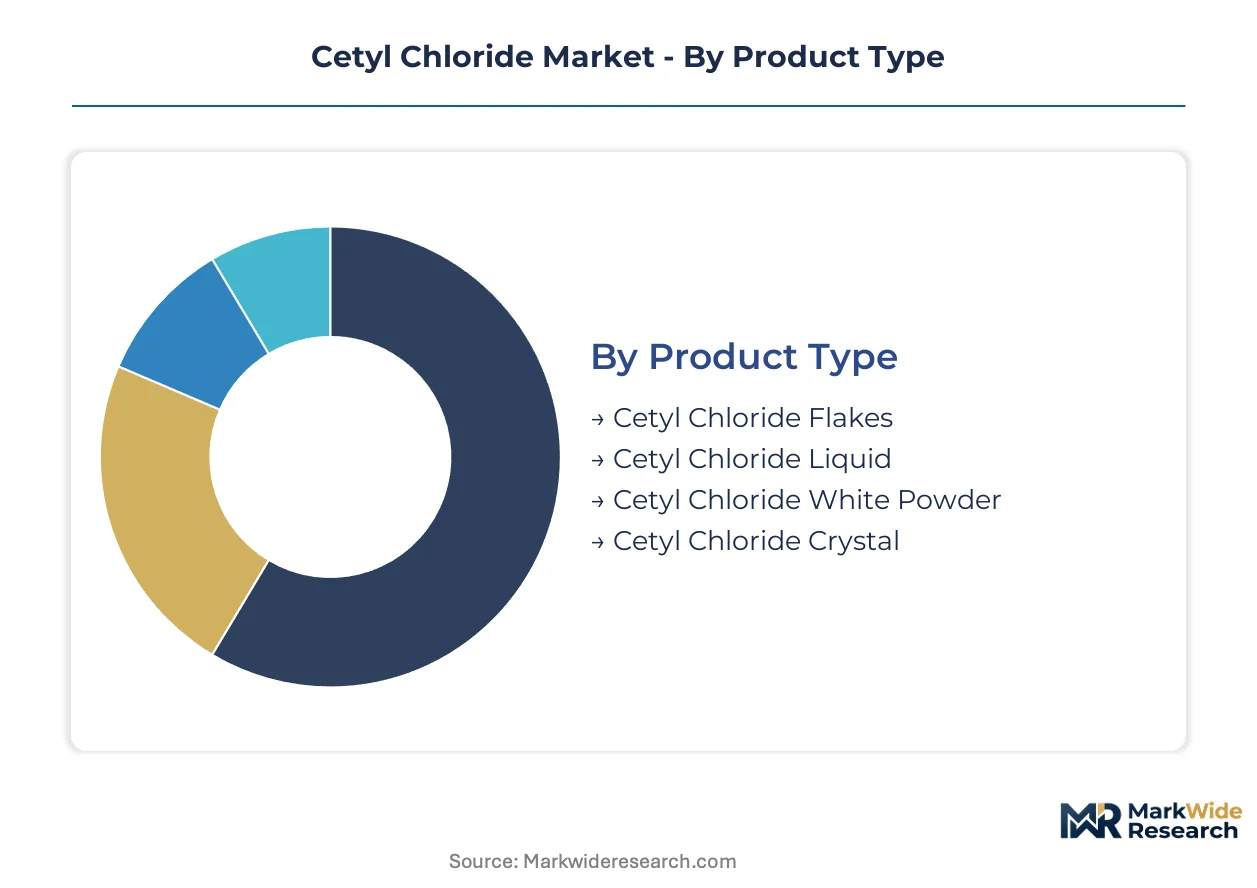
Cetyl chloride specifications diverge sharply across downstream applications, with pharmaceutical-grade flake requirements imposing stricter moisture controls than continuous surfactant manufacturing. Regulatory qualification pathways in Europe and China are segmenting supply chains by purity tier rather than geography alone.
Product Type:
REACH dossier requirements and EPA TSCA notification thresholds split procurement between specification-grade and commodity-grade material flows.
- Cetyl Chloride Liquid:Contains 21-23% chlorine content with melting points near 12°C, enabling pumpable handling in continuous quaternary ammonium synthesis. Personal care formulators in Germany and France are consolidating procurement around single-source liquid supply agreements with integrated chlorination operators.
- Cetyl Chloride Flakes:Solid-phase presentation with controlled moisture specification below 0.5%, critical for pharmaceutical salt formulations where hydroscopic stability determines shelf life. GMP-compliant flake production commands margin premiums from European and North American pharmaceutical contract manufacturers.
- Cetyl Chloride White Powder:Micronized particle distribution serving specialty catalyst and phase-transfer reagent applications in fine chemical synthesis.
- Cetyl Chloride Crystal:Recrystallized grade for analytical standard and reference material applications in regulatory testing laboratories.
Established volume favors liquid grades; emerging adoption favors flake specifications.
Application:
Silicone-free formulation trends are reallocating demand across conditioning and emulsifying functionalities.
- Emulsifying Agent:Primary intermediate for cationic surfactant synthesis in oil-in-water personal care systems. Jiangsu and Zhejiang chlorination clusters supply domestic emulsifier producers with just-in-time liquid delivery.
- Conditioning Agent:Quaternary ammonium compound precursor for silicone-free hair care formulations. Cosmetic brands in France and the United States are reformulating away from silicones, pulling cetyl chloride into conditioning agent synthesis at the steepest expansion trajectory.
- Surfactant:Direct feedstock for industrial cleaning and textile processing applications with lower purity thresholds.
- Thickeners:Secondary application in rheology modification for cream and lotion formulations.
Personal care pull concentrates in emulsifying; hair care reformulation accelerates conditioning.
End User Industry:
Certification requirements stratify supply between regulated pharmaceutical channels and commodity personal care flows.
- Personal Care:Dominant demand channel spanning premium skincare, hair care, and color cosmetic formulations. Multinational brands are demanding auditable chain-of-custody documentation from fatty alcohol through chlorination.
- Pharmaceuticals:GMP manufacturing and API intermediate status impose ICH Q7 compliance on flake-grade suppliers. India's CDSCO and the US FDA inspect active pharmaceutical ingredient facilities, filtering out non-compliant chlorination operators.
- Food Processing:India's BIS quality certification for food-grade emulsifiers adds a secondary qualification gate for suppliers targeting this channel.
- Textile:Industrial softener and antistatic applications with lower regulatory barriers but price-sensitive procurement.
Margin concentration sits with pharmaceutical; volume scale sits with personal care.
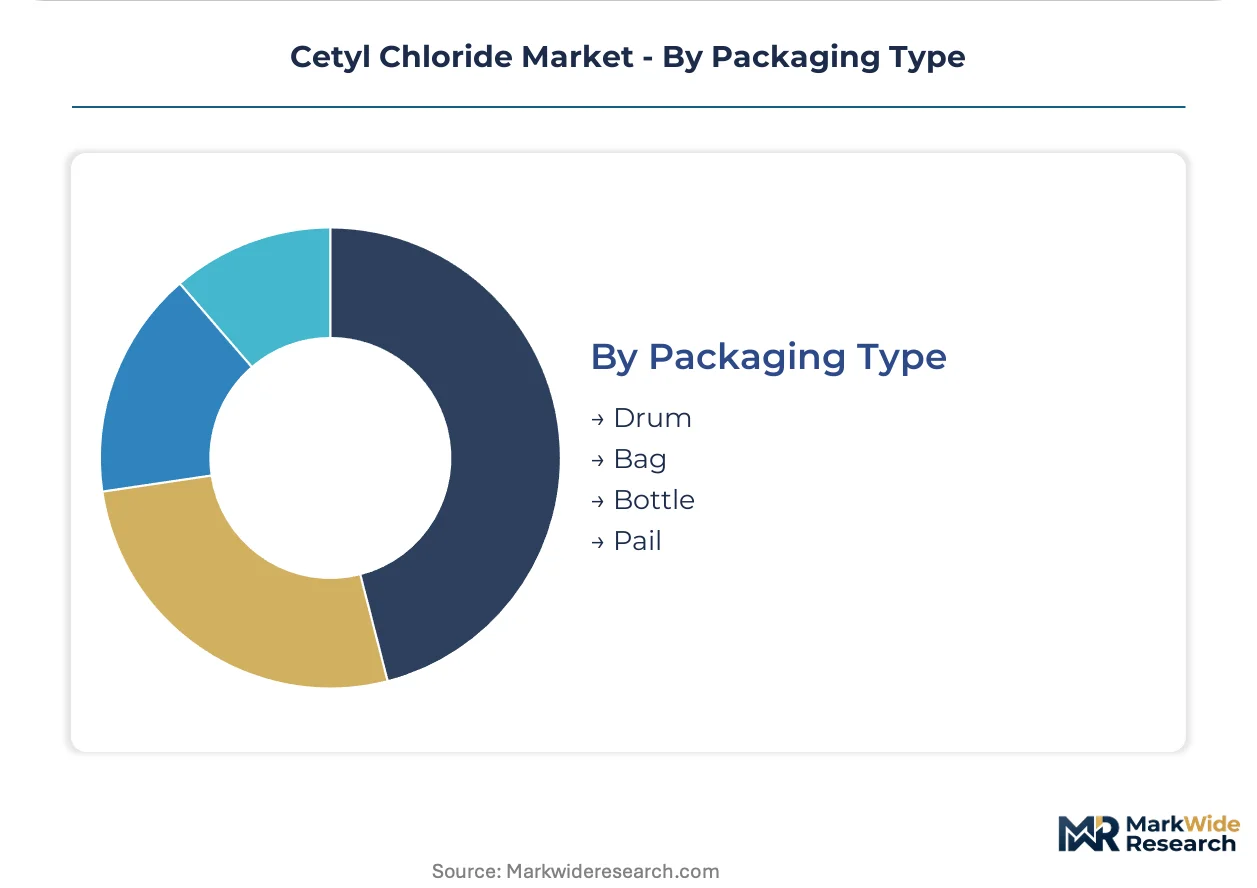
Packaging Type:
Logistics infrastructure and batch size economics determine container selection across manufacturing scales.
- Drum:Standard 200-liter steel drum presentation for liquid grades in continuous manufacturing environments. Tank-car logistics for qualified suppliers reduce per-unit handling costs.
- Bag:Multi-layer laminate bags for flake and powder grades requiring moisture barrier protection during pharmaceutical supply chain transit.
- Bottle:Laboratory-scale packaging for analytical and R&D sampling applications.
- Pail:Intermediate 20-25 liter containers for specialty chemical distributors serving mid-scale formulators.
Industrial scale favors drum logistics; pharmaceutical integrity favors bag protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp pipeline corridor anchors European chlorinated intermediate distribution, while the Yangtze River Delta ports handle the densest cetyl chloride cargo flows globally. Rail links from Shanghai to Nanjing feed chlorination clusters with just-in-time fatty alcohol supply.
China
Jiangsu and Zhejiang chlorination clusters serve domestic emulsifier producers with captive fatty alcohol supply. MEE enforcement of chlorinated byproduct discharge standards elevates wastewater treatment capital requirements for legacy assets in Shandong. The Ningbo-Zhoushan port complex handles bulk cetyl alcohol imports that feed downstream chlorination at Taizhou and Changzhou.
Germany
REACH dossier requirements filter unregistered import volumes from personal care channels, protecting qualified suppliers with full substance dossiers. ECHA demands enhanced toxicological endpoints for reproductive toxicity, extending registration timelines. The BASF Ludwigshafen complex anchors chlorination capacity serving premium surfactant formulators across the Rhine corridor.
United States
EPA TSCA Section 5 scrutiny constrains market access for unregistered import volumes, lengthening qualification timelines for new entrants. Silicone-free hair care formulations from cosmetic brands in New Jersey and California pull cetyl chloride into quaternary ammonium compound synthesis. The Houston Ship Channel handles fatty alcohol imports feeding chlorination assets along the Gulf Coast.
India
BIS quality certification for food-grade emulsifiers adds a secondary qualification gate for suppliers targeting food processing end users. CDSCO inspections of API intermediate facilities filter out non-compliant chlorination operators. Gujarat chlorination clusters in Ankleshwar and Vapi supply domestic pharmaceutical contract manufacturers with flake-grade material.
Cetyl Chloride Market Competitive Landscape
Listed leaders compete with private specialists across regulatory qualification capacity, creating tiered access to premium personal care channels. The vendor base splits between integrated chlorination operators with captive fatty alcohol supply and merchant producers dependent on spot feedstock markets. Three archetypes dominate: backward-integrated chemical conglomerates, pharmaceutical-grade certification specialists, and regional commodity chlorinators. Capacity expansion and REACH dossier completion represent the dominant competitive moves as qualification barriers rise.
Within the integrated chlorination tier, Hubei BlueSky New Material and Shandong Taihe Technologies occupy positions exemplifying captive supply chain control from fatty alcohol through finished alkyl halide. IOL Chemicals and Pharmaceuticals Limited represents the pharmaceutical-grade certification archetype, anchoring the GMP-compliant flake segment where moisture-critical formulations command margin premiums. Vertellus Specialties sits within the North American qualification-leader category, leveraging backward integration into fatty alcohol feedstocks to serve personal care formulators with full regulatory coverage.
| Leading Market Players |
|---|
| Hubei BlueSky New Material INC |
| Shandong Taihe Technologies Co. Ltd |
| Aquapharm Chemical Pvt. Ltd |
| Dongying Huatai Fine Chemical Co. Ltd |
| Changzhou Zhongyao |
| Excel Industries Ltd |
| IOL Chemicals and Pharmaceuticals Limited |
| Vertellus Specialties |
| CABB Chemicals |
| Others |
Value Network & Pricing Analysis
Silicone-free conditioning agents displacing traditional silicone-based formulations are simultaneously redrawing procurement geography toward Jiangsu-Zhejiang chlorination clusters and compressing margin structures for non-integrated commodity suppliers. This substitution cascade rewards backward-integrated producers with captive fatty alcohol supply while penalizing spot-market dependent operators.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade flake premiums from liquid-grade contract baselines. Pricing stratifies across GMP-certified pharmaceutical tiers, REACH-registered European supply, and commodity industrial grades. Cost compression in commodity liquid grades is intensifying because palm kernel oil feedstock volatility transmits directly to cetyl alcohol input costs. Personal care formulators exhibit lowest price sensitivity due to qualification switching costs, while textile industrial buyers drive hardest bargain negotiations.
Supply Chain Analysis
Strait of Malacca transit underwrites palm kernel oil flows from Southeast Asian plantations to Chinese chlorination assets. Supply concentrates in China, India, and Germany as the three dominant manufacturing jurisdictions. Raw material dependencies rest on palm kernel oil derivatives, chlorine gas supply, and specialized chlorination catalysts. Single-source vulnerability runs through Jiangsu province's concentrated chlorination capacity. Distribution runs through drum logistics for liquid grades and multi-layer laminate bags for moisture-critical flake pharmaceutical shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against emerging biosurfactant alternatives that threaten quaternary ammonium compound demand in personal care formulations. Incumbents must navigate this displacement pressure while consolidating regulatory qualification advantages.
For Market Incumbents: Fortify REACH dossier completeness against ECHA's escalating toxicological endpoint demands. Deepen backward integration into fatty alcohol feedstocks to insulate margin from palm kernel oil volatility. Capture conditioning agent volume expansion by locking single-source liquid supply agreements with silicone-free formulation brands before biosurfactant alternatives achieve technical parity.
For New Entrants and Emerging Players: India BIS food-grade certification fast-track opens the most penetrable demand channel beyond saturated personal care procurement lists. Target pharmaceutical contract manufacturers in Gujarat and Maharashtra with GMP-compliant flake production. Enter through toll-manufacturing arrangements with existing chlorination operators to bypass capital-intensive wastewater treatment compliance.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European specialty chemical platforms seeking chlorination capability tuck-ins. Five-to-ten year viability hinges on regulatory qualification moat durability rather than commodity volume scale. Watch ECHA substance dossier revision timelines as the critical inflection signal for competitive repositioning windows.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Completion | ECHA registration unlocks protected European personal care channel access against unregistered imports. |
| Backward Integration into Fatty Alcohol | Captive palm kernel oil supply insulates margin from vegetable oil market volatility. |
| Pharmaceutical-Grade GMP Certification | Moisture-critical flake production commands premium positioning in CDSCO-inspected API facilities. |
| Jiangsu-Zhejiang Capacity Expansion | Coastal chlorination clusters enable just-in-time delivery to domestic emulsifier producers. |
| Closed-Loop Chlorination Process Investment | China MEE compliance redirects supply chain qualification toward wastewater-minimizing operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC chemical company filings, and ECHA registration databases. Plant managers at chlorination facilities, procurement leads at personal care formulators, and distribution channel partners provided operational validation. Bottom-up capacity utilization estimates triangulate against top-down demand modeling from emulsifier and quaternary ammonium compound production volumes.
Segmentation dimensions modeled span product grade tier, end-use industry application, packaging format, and regional production hub across the analysis window. CAGRs derive from slope-intercept fitting of annual volume trajectories. Palm kernel oil price elasticity and chlorination capacity utilization rates serve as industry-specific forecast sensitivity inputs.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity or alternative feedstock cost structures would require recalibration. Practitioners should keep alternative scenarios live as ECHA dossier standards and China MEE discharge regulations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Global Oilfield Surfactants Market
Surfactants
Bio-Based Surfactants Market
Surfactants
Natural Wax Emulsion Market
Surfactants
Cyclopentasiloxane Market
Surfactants
Alkyl Polyglucoside (APG) Surfactant Market
Surfactants
Global Thioglycolic Acid Market
Surfactants
Global Sodium Cocoyl Glutamate Market
Surfactants
Alkylamines Market
Surfactants
Lauramide DEA Market
Surfactants
Trisiloxane Market
Surfactants
Global Barium Petroleum Sulfonate Market
Surfactants
North America Surfactants Market
Surfactants
Cetanol Market
Surfactants
Global Surfactants Market
Surfactants
Sodium Lauroyl Sarcosinate Market
Surfactants
Sulfate Free Body Wash Market