
 Indonesia Flooring Resins Market | 2026-2036
Indonesia Flooring Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Flooring Resins Market Insights
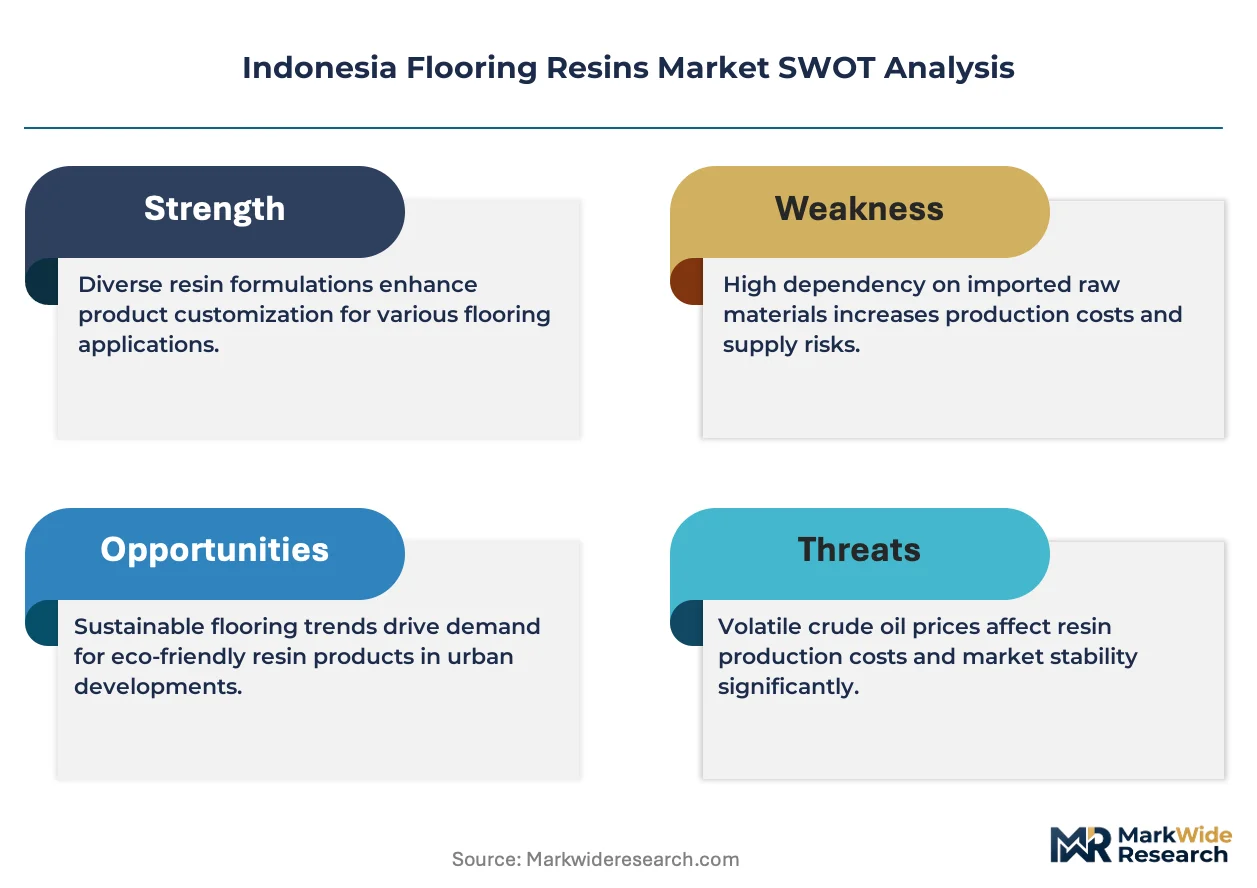
Indonesia's green building certification mandate from the Ministry of Public Works and Public Housing is expanding demand for low-emission flooring resin systems across commercial construction. Sika Indonesia leverages its Swiss parent company's polymer expertise to dominate specification-grade epoxy installations in pharmaceutical and food-processing plants. PT Jotun Indonesia anchors the marine-to-industrial crossover segment with corrosion-resistant polyurethane systems adapted from offshore coatings technology. BASF SE competes through backward integration into aliphatic isocyanate precursors, securing supply continuity for premium polyurethane floor coatings amid raw material volatility.
Indonesia flooring resins comprise synthetic polymer binders—typically two-component thermosetting systems with Shore D hardness ratings of 75–85—formulated for seamless, chemical-resistant surface finishes in high-traffic environments. Epoxy formulations retain the largest volume share due to their cost-performance balance in industrial warehousing and manufacturing floors, though polyurethane is gaining specification in cold-storage and flexural-stress applications where thermal cycling resistance matters. The commercial end-user segment shows the fastest trajectory as Jakarta's retail and hospitality developers specify decorative metallic epoxy and terrazzo-overlay systems for premium aesthetic performance.
BIS-equivalent Indonesian National Standards and Ministry of Industry technical regulations govern VOC content limits and slip-resistance classifications for resin flooring in public buildings. The Ministry of Environment and Forestry's extended producer responsibility frameworks are beginning to shape post-installation waste protocols, particularly for solvent-containing acrylic sealants. Stakeholders must monitor enforcement divergence between national standards and Jakarta's stricter provincial environmental ordinances when configuring product portfolios and compliance documentation for Indonesia's fragmented regulatory landscape.
Market Dynamics
Indonesia's flooring resins sector is being restructured by the Ministry of Public Works and Public Housing's mandatory green building certification, which is compressing specification timelines and elevating low-VOC formulation requirements across commercial construction in Jakarta and Surabaya.
Growth Catalysts
- Green Building Certification Mandate:The Ministry of Public Works and Public Housing's certification requirements are compelling developers to specify low-emission epoxy and polyurethane systems in new commercial projects.
- Java's Manufacturing Corridor Expansion:Industrial facility upgrades across Bekasi, Karawang, and Sidoarjo are generating sustained demand for chemical-resistant flooring in food processing and electronics manufacturing.
- Cold-Storage Infrastructure Buildout:Indonesia's expanding pharmaceutical logistics network is specifying thermal-cycling-resistant polyurethane formulations for warehouse floors subject to temperature extremes.
Market Restraints
- Raw Material Import Dependency:Aliphatic isocyanate and specialty epoxy hardener precursors rely on shipments from Northeast Asian suppliers, exposing formulators to freight cost volatility and currency fluctuation.
- Skilled Applicator Shortage:Proper installation of high-performance resin flooring demands certified contractors, yet Indonesia's training infrastructure for moisture-tolerant substrate preparation remains underdeveloped.
- Cementitious Overlay Substitution:Lower-cost polymer-modified cement screeds are capturing budget-sensitive warehousing projects where chemical resistance requirements are moderate.
Strategic Opportunities
- Sumatra Industrial Zone Penetration:Batam's electronics manufacturing expansion and Medan's palm oil processing cluster remain underserved by specification-grade resin flooring distributors.
- Decorative Metallic Epoxy Segment:Jakarta's retail and hospitality developers are specifying premium aesthetic systems for flagship properties, creating margin expansion potential above commodity industrial grades.
- Extended Producer Responsibility Alignment:The Ministry of Environment and Forestry's emerging waste protocols favor suppliers offering take-back programs for solvent-containing installation byproducts.
Industry Challenges
- Moisture Vapor Transmission Expertise Gap:Tropical humidity conditions in Indonesian substrates demand specialized epoxy primer selection, yet applicator training on calcium chloride testing and breathable membrane specification remains inconsistent.
- Provincial Regulatory Divergence:Jakarta's stricter VOC ordinances create compliance documentation complexity for national distributors serving both the capital and regions operating under baseline national standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Flooring Resins Market |
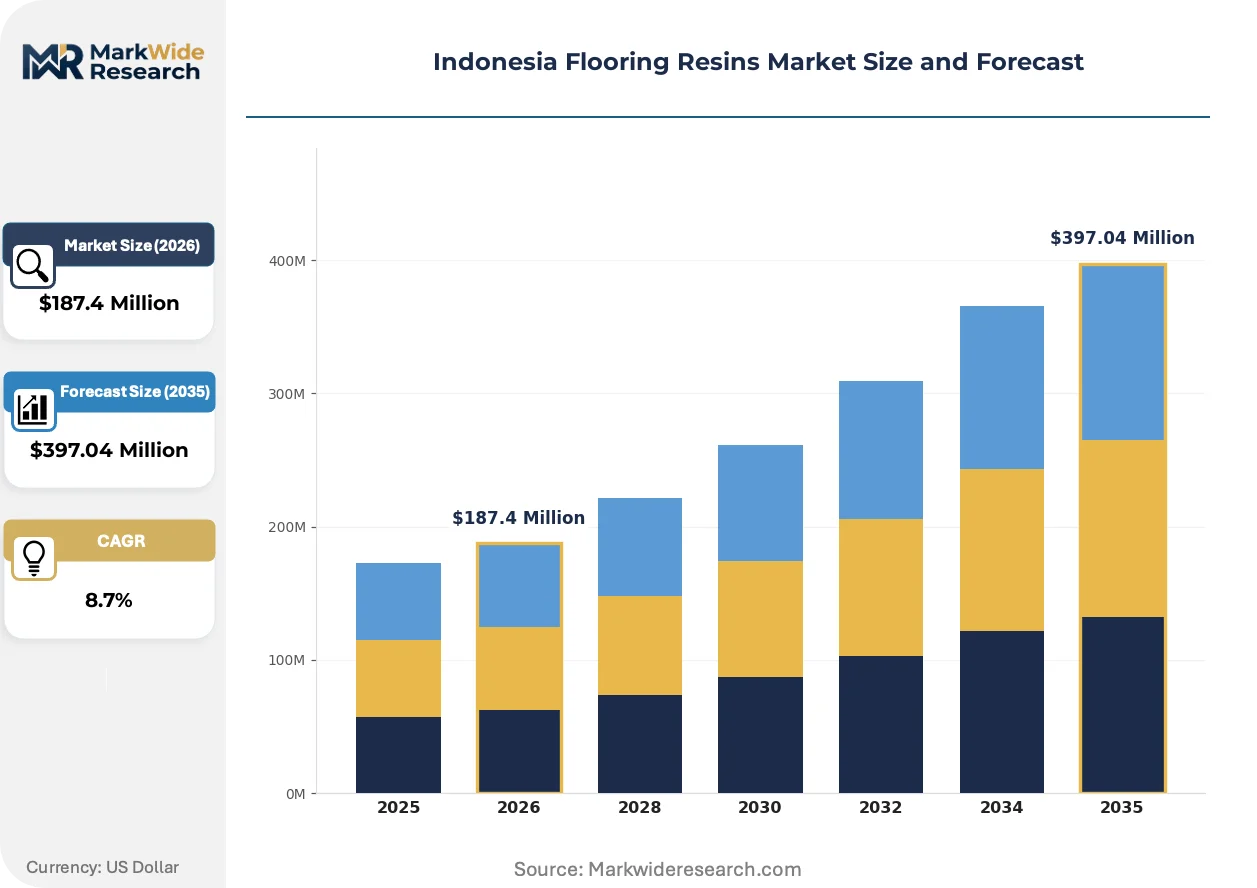
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Polyvinyl Chloride End User: Residential, Commercial, Industrial, Institutional Application: Floor Coatings, Adhesives, Sealants, Surface Treatments Distribution Channel: Direct Sales, Distributors, Online Retail, Contractor Sales |
| Companies Covered | PT Jotun Indonesia, Sika Indonesia, BASF SE, AkzoNobel, PPG Industries, Kansai Paint Indonesia, Nippon Paint Indonesia, RPM International Inc., PT Propan Raya, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Flooring Resins Market Trends and Innovations
Waterborne polyurethane technology and rapid-cure methyl methacrylate systems are compressing installation windows and expanding application seasons in Indonesia's monsoon-affected construction calendar. These advances are redrawing competitive boundaries between commodity epoxy suppliers and specialty performance formulators.
Waterborne aliphatic polyurethane technology is decentralizing the supplier base for premium commercial flooring in Indonesia. Shopping mall developers in Jakarta are specifying these systems for atrium and retail spaces where low odor during application is mandatory. The shift is enabling mid-sized local formulators to compete in segments previously dominated by imports with higher solvent content.
BIS-equivalent Indonesian National Standards for VOC content and slip resistance are tightening enforcement timelines for public building projects. The Ministry of Industry's technical regulations now require third-party certification for resin flooring installed in healthcare and education facilities. Pharmaceutical manufacturing plants in Bekasi are responding by pre-qualifying suppliers with complete SNI documentation packages to avoid specification delays.
Direct procurement relationships between end-users and certified applicators are shortening traditional distribution chains in Indonesia's flooring resins market. Large industrial facility operators in Karawang are bypassing general construction distributors to negotiate volume contracts with Sika- and Jotun-certified installation crews. This channel compression is most pronounced in electronics manufacturing, where warranty terms require applicator traceability back to resin batch records.
Indonesia Flooring Resins Market Segmentation
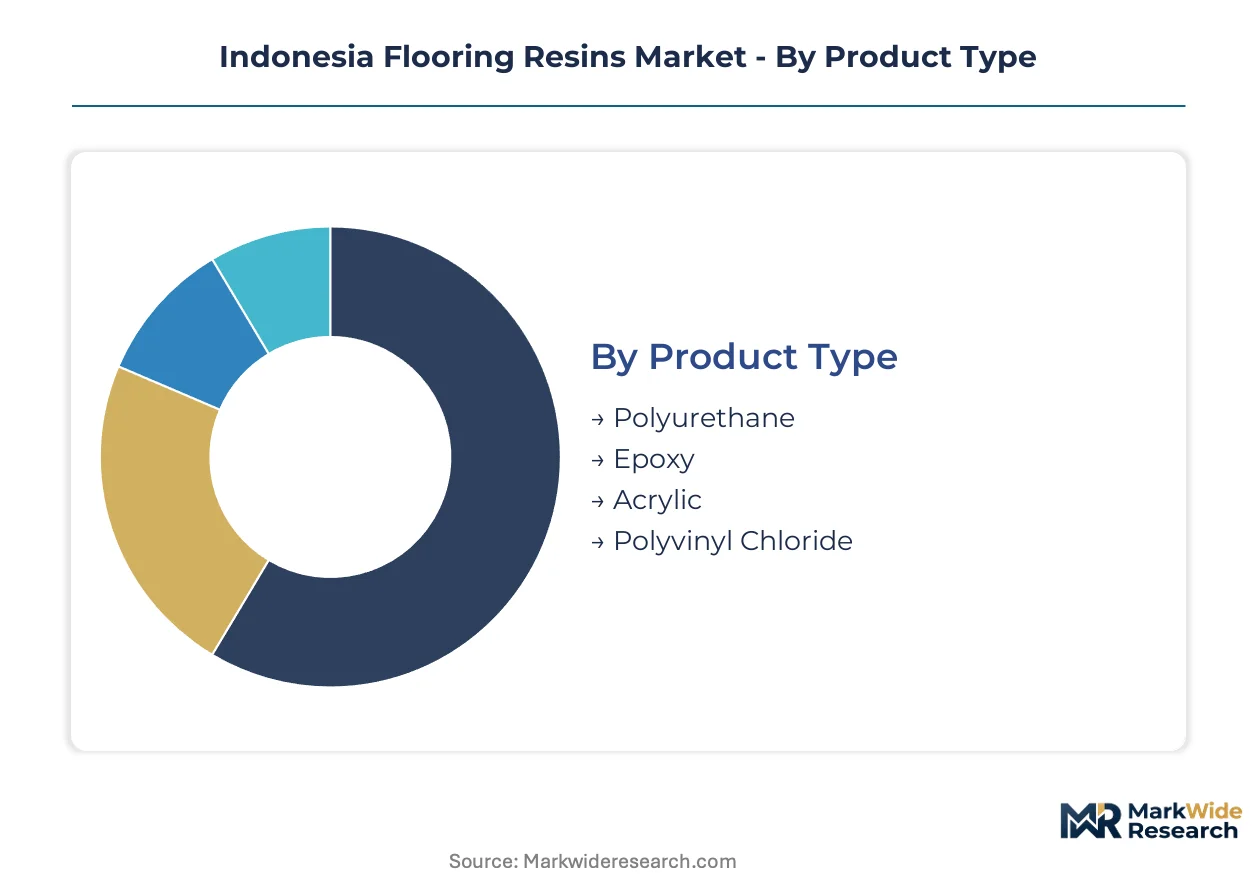
Indonesia's flooring resins market segments along four dimensions that shape procurement patterns and margin structures. Product chemistry determines performance specifications for tropical humidity conditions. End-user categories diverge sharply on certification requirements and price sensitivity.
Product Type:
Buyers in this category differentiate primarily by mechanical performance requirements and installation environment constraints.
- Epoxy:Two-component thermosetting systems formulated with bisphenol-A or bisphenol-F resins deliver Shore D hardness of 75-85 for industrial warehousing. Bekasi's electronics manufacturing plants specify these for chemical resistance in cleanroom environments where solvent exposure occurs.
- Polyurethane:Aliphatic and aromatic isocyanate-cured systems provide superior thermal cycling resistance for cold-storage applications. Jakarta's pharmaceutical logistics warehouses are driving specification of these formulations for floors subject to temperature extremes between -25°C and ambient.
- Acrylic:UV-curable and solvent-borne sealants serve decorative commercial overlays where rapid installation turnaround matters. Retail developers in Surabaya specify these for shopping mall atrium refreshes requiring minimal downtime.
- Polyvinyl Chloride:Plastisol and dry-blend systems target budget-sensitive institutional flooring in education facilities. Provincial healthcare clinics outside Java's industrial corridor utilize these for basic hygiene-compliant surfaces.
Epoxy leads volumes today; polyurethane is gaining share fastest.
End User:
Segmentation here tracks regulatory exposure and project scale, from single-family specifications to national distribution networks.
- Industrial:Food processing plants in Karawang and Sidoarjo require HACCP-compliant seamless flooring with chemical resistance to organic acids and sanitizing agents. Facility upgrades across Java's manufacturing corridor sustain bulk procurement through direct applicator contracts.
- Commercial:Jakarta's retail and hospitality developers specify decorative metallic epoxy and terrazzo-overlay systems for premium aesthetic performance in flagship properties. Green building certification mandates from the Ministry of Public Works and Public Housing are compressing specification timelines for low-VOC formulations.
- Institutional:Healthcare and education facilities face mandatory SNI third-party certification for slip resistance and VOC content. Hospital construction in Surabaya is pre-qualifying suppliers with complete documentation packages to avoid project delays.
- Residential:High-end villa developments in Bali and Lombok specify polyurethane garage floor coatings for UV stability and aesthetic finish. Volume remains constrained by price sensitivity relative to conventional tile or polished concrete alternatives.
Industrial commands the largest revenue pool; commercial shows the steepest expansion trajectory.
Application:
Function determines formulation complexity and margin structure, from commodity coatings to specialized substrate treatments.
- Floor Coatings:Self-leveling and trowel-applied systems constitute the core revenue base, spanning thin-film sealers to heavy-duty slurry broadcast finishes. Manufacturing facility upgrades across Bekasi and Karawang drive specification of 3-5mm nominal thickness systems.
- Adhesives:Reactive polyurethane and epoxy-based bonding agents serve raised access flooring and resilient sheet goods installation. Data center construction in Jakarta is expanding demand for conductive adhesive systems.
- Sealants:Joint fillers and crack repair compounds address substrate movement in tropical conditions. Airport runway and logistics yard maintenance programs specify polysulfide and polyurethane sealants for dynamic crack accommodation.
- Surface Treatments:Penetrating hardeners and anti-slip additives modify existing concrete substrates where full resin overlay is cost-prohibitive. Budget-sensitive warehousing projects in peripheral industrial zones favor these over complete flooring replacement.
Floor coatings dominate absolute volumes; surface treatments are climbing the fastest as refurbishment cycles accelerate.
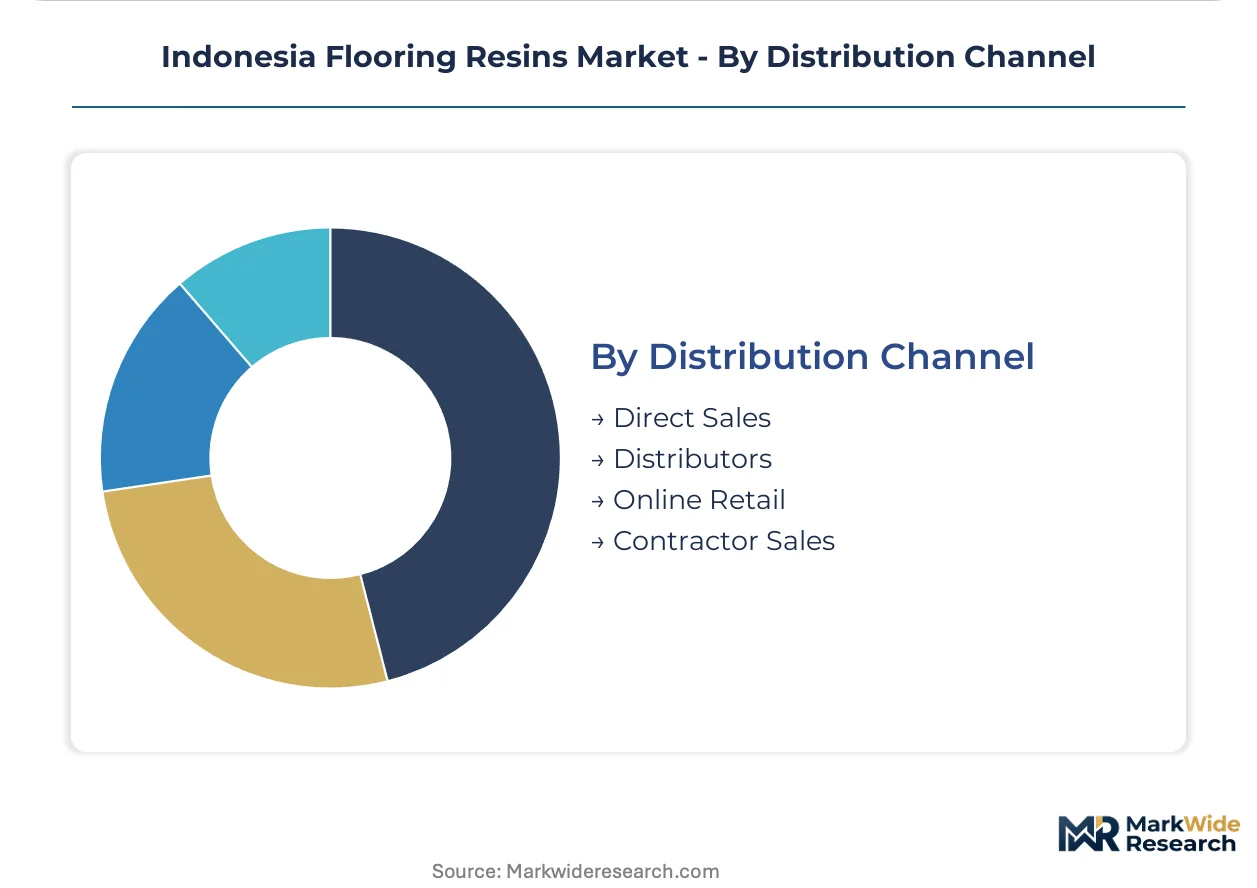
Distribution Channel:
Channel selection reflects project scale, warranty requirements, and the buyer's technical sophistication.
- Direct Sales:Large industrial facility operators in Karawang negotiate volume contracts directly with certified installation crews. Electronics manufacturers require batch traceability from resin production through final application.
- Distributors:General construction supply houses serve mid-tier commercial projects and regional contractors outside major industrial zones. Inventory holding in Surabaya and Medan reduces lead times for specification-grade materials.
- Contractor Sales:Certified applicator networks control specification influence in warranty-sensitive pharmaceutical and food-processing installations. Sika- and Jotun-certified crews in Jakarta command premium positioning through manufacturer-backed guarantees.
- Online Retail:E-commerce platforms capture DIY residential segments and small commercial maintenance quantities. Product selection concentrates on pre-packaged epoxy garage kits and acrylic sealants with simplified application instructions.
Contractor sales capture the highest value per ton; direct sales channels are expanding most quickly as end-users internalize technical procurement functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's certified applicator workforce concentrates in Java's industrial corridor, with Jakarta and Surabaya anchoring technical training infrastructure for moisture-tolerant substrate preparation.
Java
Java dominates national consumption through Bekasi's electronics manufacturing cluster and Karawang's food processing corridor. The Ministry of Public Works and Public Housing's green building certification mandates compress specification timelines for low-VOC epoxy and polyurethane systems in Jakarta's commercial construction. Surabaya's pharmaceutical logistics warehouses are driving specification of thermal-cycling-resistant polyurethane formulations for cold-storage floors.
Sumatra
Sumatra's industrial base is expanding through Batam's electronics manufacturing zone and Medan's palm oil processing cluster. Provincial environmental ordinances in North Sumatra operate under baseline national standards rather than Jakarta's stricter VOC limits. Batam's free trade zone status attracts manufacturing facility upgrades requiring chemical-resistant flooring, though specification-grade resin distributors remain underpenetrated relative to Java.
Sulawesi
Sulawesi's nickel processing corridor is generating demand for heavy-duty industrial flooring in smelter and refinery construction. The Ministry of Industry's technical regulations govern SNI third-party certification requirements for public building projects in Makassar. Kendari's emerging industrial zone is absorbing commodity epoxy systems for warehousing and logistics facilities serving the mining supply chain.
Bali and Nusa Tenggara
Bali's high-end villa developments specify polyurethane garage floor coatings for UV stability and aesthetic finish in premium residential construction. The Ministry of Environment and Forestry's emerging waste protocols are beginning to shape post-installation disposal requirements for solvent-containing sealants. Lombok's tourism infrastructure expansion is creating niche demand for decorative metallic epoxy systems in hospitality properties.
Kalimantan
Kalimantan's coal and palm oil industries require chemical-resistant flooring for processing facilities and bulk storage terminals. National standards for slip resistance and VOC content apply uniformly across East, West, and South Kalimantan provinces. Balikpapan's logistics and energy services cluster is absorbing polymer-modified cement screeds as lower-cost alternatives to full resin systems in budget-sensitive warehousing projects.
Indonesia Flooring Resins Market Competitive Landscape
Capital-heavy producers with captive resin manufacturing compete with asset-light formulators relying on imported precursors and toll blending arrangements. The supplier base fragments across three tiers: multinational chemical conglomerates with backward integration into aliphatic isocyanates, regional coating specialists leveraging marine-to-industrial technology transfer, and local distributors serving price-sensitive refurbishment segments. Two dominant competitive moves are reshaping positioning: direct procurement relationships between end-users and certified applicator networks are compressing traditional distribution channels, and waterborne polyurethane technology adoption is enabling mid-sized local formulators to compete in premium commercial segments previously dominated by solvent-borne imports.
Within the multinational integrated tier, BASF SE anchors positioning through upstream control over specialty chemical precursors. Among Asia-Pacific coating specialists, PT Jotun Indonesia and Nippon Paint Indonesia occupy positions leveraging marine coatings technology adapted for industrial flooring applications. Sika Indonesia represents the specification-grade installation vector, with manufacturer-backed warranty terms requiring certified applicator traceability. These three exemplify divergent strategic archetypes: precursor security, technology crossover, and channel control.
| Leading Market Players |
|---|
| PT Jotun Indonesia |
| Sika Indonesia |
| BASF SE |
| AkzoNobel |
| PPG Industries |
| Kansai Paint Indonesia |
| Nippon Paint Indonesia |
| RPM International Inc. |
| PT Propan Raya |
| Others |
Pricing and Supply Chain Analysis
Backward integration into aliphatic isocyanate precursors anchors BASF SE's supply position and pricing power, while asset-light Indonesian formulators remain exposed to Northeast Asian import volatility and currency fluctuation. This structural divide between integrated multinationals and toll-blending local competitors compresses margins at the commodity epoxy tier while preserving premium pricing for specification-grade polyurethane systems.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates SNI-certified low-VOC formulations from commodity industrial grades and polymer-modified cement screeds. Price differentiation hinges on certification grade and volume scale, with Jakarta's green building mandates compressing premiums for compliant systems. Cost compression in the economy tier is intensifying because cementitious overlays capture budget-sensitive warehousing projects. Small commercial developers exhibit the highest price sensitivity, while pharmaceutical manufacturers in Bekasi prioritize warranty-backed applicator traceability over unit cost.
Supply Chain Analysis
Domestic-content requirements from the Ministry of Industry are reshaping sourcing patterns for public building projects, compelling formulators to qualify local toll-blending partners. Raw material flows draw from China, South Korea, and Japan for epoxy hardeners and specialty isocyanates. Supply chain risk centers on single-source vulnerability for aliphatic isocyanate precursors. Distribution runs through certified applicator networks for warranty-sensitive installations, bypassing traditional construction supply houses in direct procurement trends.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne polyurethane technology adoption is compressing the premium tier and expanding margin capture for mid-sized formulators able to bridge certification requirements with local production. This cost-down driver reshapes competitive positioning across Java's commercial construction corridor.
For Market Incumbents: Deploy applicator certification networks as a defensive moat against emerging local formulators gaining SNI compliance. BASF SE should deepen upstream control over specialty amine hardeners to secure batch traceability for pharmaceutical sector procurement. Sika Indonesia must expand moisture-tolerant substrate training infrastructure to defend specification-grade positioning against Jotun's marine-to-industrial technology crossover. For New Entrants and Emerging Players: The Ministry of Public Works and Public Housing's green building certification in Jakarta opens a window for waterborne polyurethane specialists to capture retail and hospitality specifications previously dominated by solvent-borne imports. Target Surabaya's pharmaceutical logistics corridor for thermal-cycling-resistant formulations. Pursue direct procurement relationships with electronics manufacturers in Karawang requiring documented batch traceability. For Investors and Strategic Acquirers: Roll-up economics work for regional toll-blending specialists because certification documentation gaps create acquisition targets with immediate SNI compliance value. The five-to-ten-year viability window favors platforms consolidating applicator training infrastructure. Monitor enforcement divergence between Jakarta's provincial VOC ordinances and national standards as the inflection signal for portfolio geographic weighting.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Precursors | BASF SE secures supply continuity for premium polyurethane floor coatings amid raw material volatility. |
| Waterborne Technology Transition | Mid-sized Indonesian formulators compete in premium commercial segments previously dominated by imports. |
| Certified Applicator Network Expansion | Sika Indonesia defends specification-grade positioning through manufacturer-backed warranty terms. |
| Direct Procurement Channel Development | Electronics manufacturers in Karawang bypass distributors to negotiate volume contracts with traceability. |
| Extended Producer Responsibility Alignment | Suppliers offering take-back programs for solvent-containing byproducts gain Ministry of Environment preference. |
Research Methodology
Direct dialogue with plant managers at Bekasi electronics facilities, procurement leads at Karawang food processors, distribution channel partners in Surabaya, and technical R&D directors at multinational formulators grounded qualitative findings. Secondary validation drew from Ministry of Industry technical regulations, Indonesian National Standards documentation, customs import records for epoxy precursors, and SEC filings of listed coating manufacturers. Bottom-up and top-down triangulation cross-checked volume estimates against facility upgrade announcements and green building certification timelines.
Bottom-up modeling aggregated individual project specifications across Java's manufacturing corridor, while top-down analysis calibrated against construction sector expenditure patterns. Segmentation dimensions included product chemistry tier, end-use regulatory exposure, application thickness specification, and distribution channel control level. CAGRs were derived from regression analysis of historical certification timelines and projected facility upgrade cycles. Key inputs encompassed Ministry of Public Works green building mandate enforcement schedules and tropical humidity substrate preparation cost curves.
Revisions become necessary when Jakarta's provincial VOC ordinances diverge further from national standards, when Northeast Asian precursor supply experiences sustained disruption, or when cementitious overlay technology advances capture additional specification-grade applications. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Polyethylene Wax Market
Polymers & Resins
Global Alpha Olefins Market
Polymers & Resins
Filled Fluoropolymer Market
Polymers & Resins
Polysulfide Resin Market
Polymers & Resins
Polymer Ingredients Market
Polymers & Resins
India Flooring Resins Market
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Polyphenylene Oxide (PPO) Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Co-Polymer Resin Market