
 Sugar-Based Surfactants Market | 2026-2036
Sugar-Based Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar-Based Surfactants Market Intelligence
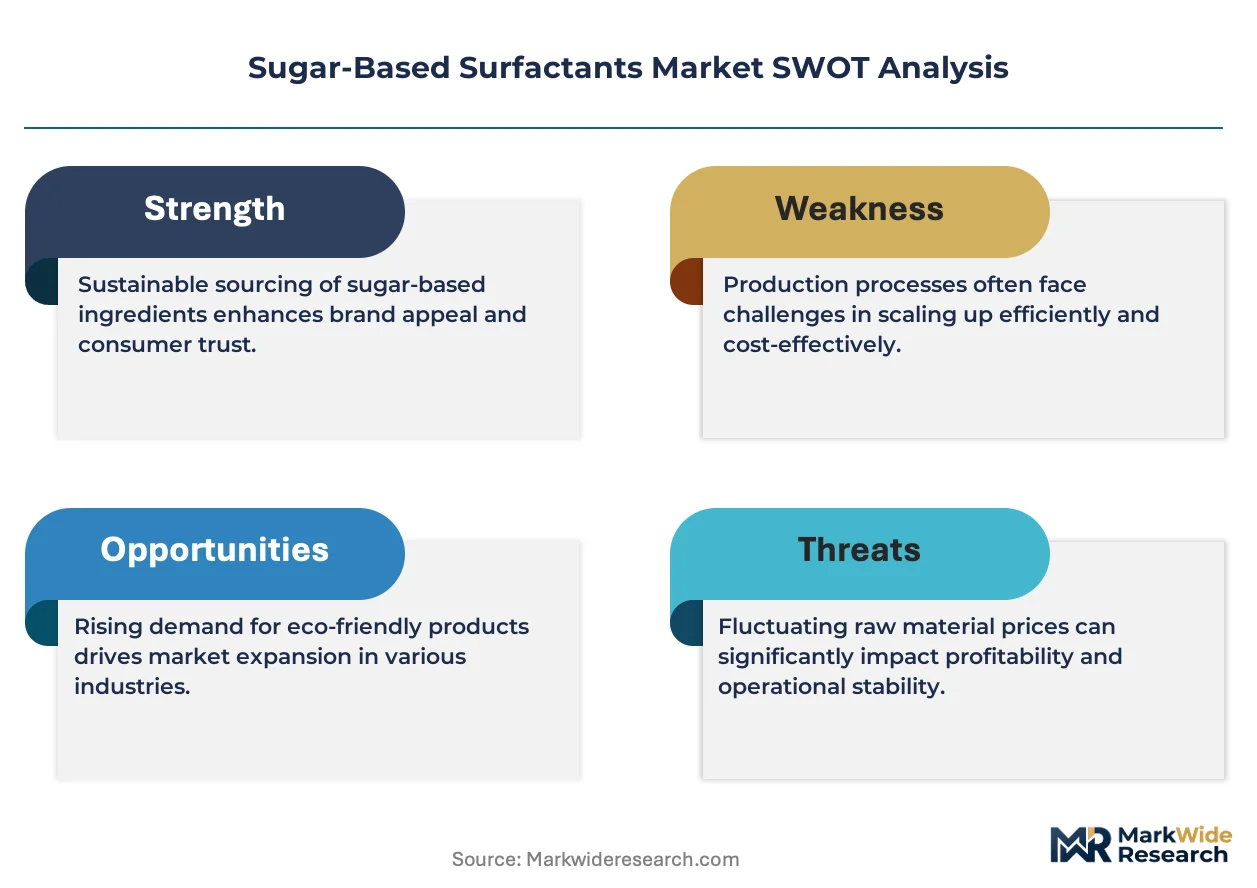
The sugar-based surfactants market is realigning around a widening gap between premium cosmetic-grade alkyl polyglycosides and commodity industrial-grade sucrose esters. BASF SE leverages its Ludwigshafen carbohydrate integration to dominate high-purity cosmetic supply chains. Clariant AG anchors European household cleaning demand through specialized sophorolipid production. Croda International Plc differentiates via food-grade sucrose ester formulations that command tighter specification tolerances.
Sugar-based surfactants are amphiphilic compounds derived from renewable carbohydrate feedstocks such as glucose, sucrose, or rhamnose, typically featuring hydrophilic sugar head groups bonded to hydrophobic alkyl chains through glycosidic or ester linkages, with critical micelle concentrations ranging from 0.01 to 1.0 g/L depending on chain length and degree of polymerization. Alkyl polyglycosides lead product type revenue due to their versatility across personal care and household formulations, while sophorolipids represent the fastest-expanding category driven by microbial fermentation advances that reduce production costs. Cosmetic-grade specifications concentrate margin pools through tighter impurity thresholds and certification requirements that industrial-grade volumes cannot match.
REACH registration requirements and the EU Green Deal framework constrain petrochemical surfactant introductions, directly expanding bio-based quota obligations for European formulators. FDA food additive regulations and EPA Safer Choice labeling in the United States create parallel compliance pathways that favor GRAS-status sucrose esters and alkyl polyglycosides with established toxicological dossiers. Stakeholders must monitor fermentation yield improvements and carbohydrate feedstock price volatility as the primary variables determining which product-grade tier captures incremental volume.
Market Dynamics
REACH restrictions on petrochemical surfactants are forcing European formulators to redirect procurement budgets toward bio-based alternatives, widening the competitive gap between integrated carbohydrate feedstock producers and import-dependent compounders.
Growth Catalysts
- EU Green Deal bio-based quotas:Mandated renewable content thresholds in household cleaning formulations are pulling alkyl polyglycoside volumes into German and French supply chains.
- Sulfate-free personal care claims:Cosmetic formulators are eliminating sodium lauryl sulfate from shampoo and body wash recipes, opening specification slots for mild sugar-based alternatives.
- Microbial fermentation yield improvements:Advances in Candida bombicola strain optimization are compressing sophorolipid production costs and expanding addressable market segments.
Market Restraints
- Carbohydrate feedstock price volatility:Corn and wheat glucose spot markets swing with agricultural commodity cycles, squeezing margin predictability for non-integrated producers.
- Technical performance gaps in hard water:Sugar-based surfactants exhibit reduced foaming stability above 300 ppm calcium concentration, limiting adoption in certain industrial cleaning applications.
- Substitution threat from amino acid surfactants:Glutamate and sarcosinate derivatives are capturing sulfate-free personal care share through superior sensory profiles.
Strategic Opportunities
- EPA Safer Choice labeling acceleration:Federal procurement preference for certified products is opening institutional cleaning channels previously closed to premium bio-based surfactants.
- India PLI scheme for specialty chemicals:Production-linked incentives are attracting fermentation capacity investments targeting export markets.
- Food-grade emulsifier specification tightening:Tighter FDA impurity thresholds for sucrose esters are creating margin pools for producers with pharmaceutical-grade purification assets.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiology and downstream processing expertise concentrates in pharmaceutical clusters, forcing surfactant producers to compete for limited personnel.
- Cosmetic-grade certification timelines:ECOCERT and COSMOS approval cycles extend 18-24 months, delaying revenue recognition for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar-Based Surfactants Market |
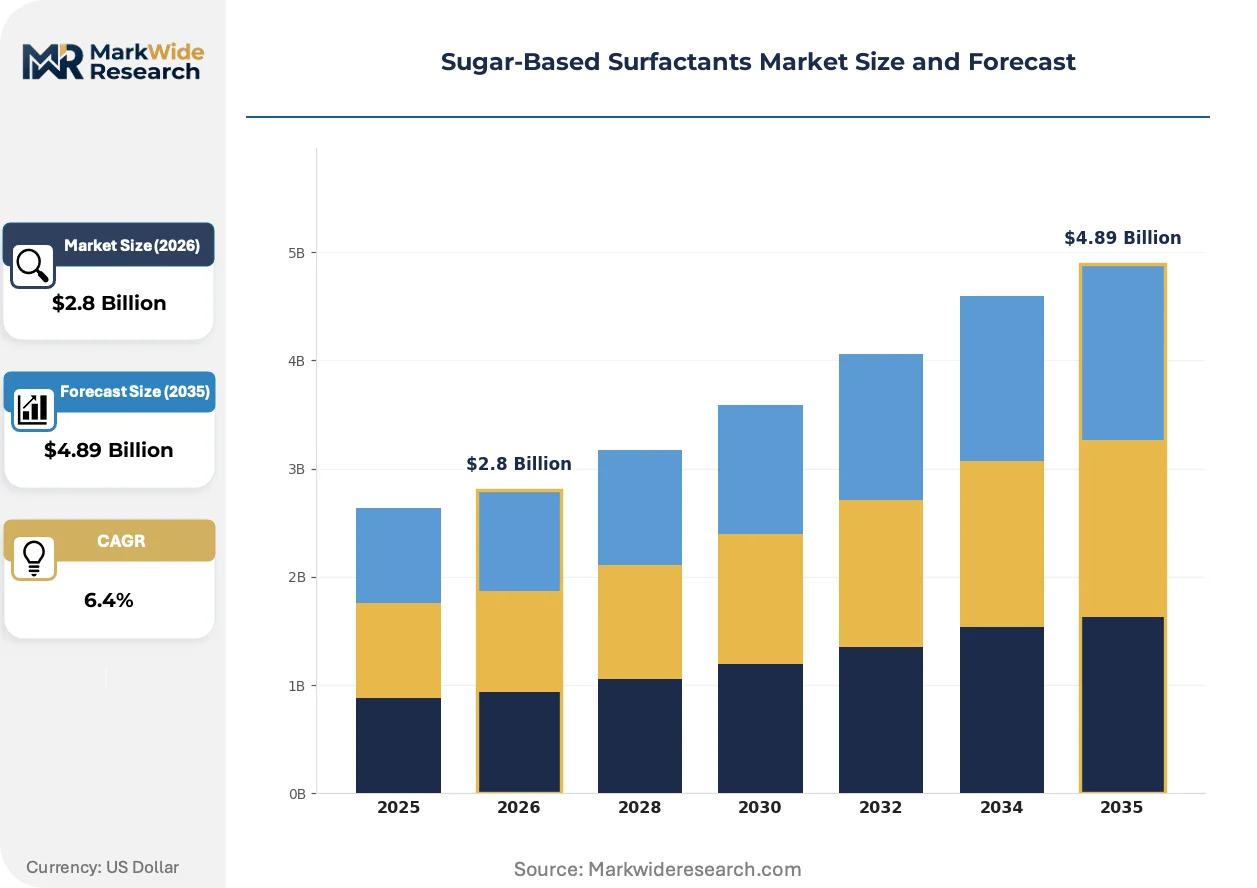
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkyl Polyglycosides, Sucrose Esters, Methyl Glucoside Esters, Sophorolipids End Use Industry: Personal Care, Household Cleaning, Industrial Applications, Food Processing Form: Liquid, Powder, Paste, Gel Grade: Food Grade, Cosmetic Grade, Industrial Grade, Technical Grade |
| Companies Covered | BASF SE, Clariant AG, Stepan Company, Croda International Plc, Solvay S.A., Evonik Industries AG, SEPPIC, Oxiteno S.A., Galaxy Surfactants Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar-Based Surfactants Market Strategic Shifts & Innovations
Continuous processing technology is overtaking batch fermentation in sophorolipid manufacturing, compressing capital intensity and enabling modular capacity expansion that matches demand granularity.
Enzymatic glycosylation is overtaking acid-catalyzed routes for alkyl polyglycoside synthesis, delivering narrower polydispersity indices that satisfy cosmetic-grade specifications without additional purification stages. Personal care formulators in Germany and France are adopting these materials at pace, forcing commodity producers to upgrade or retreat to industrial cleaning applications. The technology is overtaking legacy acid processes in premium supply chains and compressing margin structures for undifferentiated volumes.
REACH authorization requirements for nonylphenol ethoxylates are accelerating substitution timelines across European industrial cleaning. The restriction removes a cost-competitive petrochemical alternative from formulation toolkits, directly expanding alkyl polyglycoside specification opportunities in metalworking fluids and textile processing. Metalworking fluid compounders in Germany are responding fastest, locking in multi-year supply agreements with integrated carbohydrate feedstock producers.
Direct procurement relationships between personal care brands and fermentation operators are disintermediating traditional chemical distributors in premium segments. Specialty surfactant traders are losing share to in-house sourcing teams that negotiate carbohydrate supply and toll manufacturing separately. This pattern is most visible in French cosmetic clusters, where L'Oréal and LVMH have established dedicated bio-surfactant procurement functions.
Sugar-Based Surfactants Market Segmentation
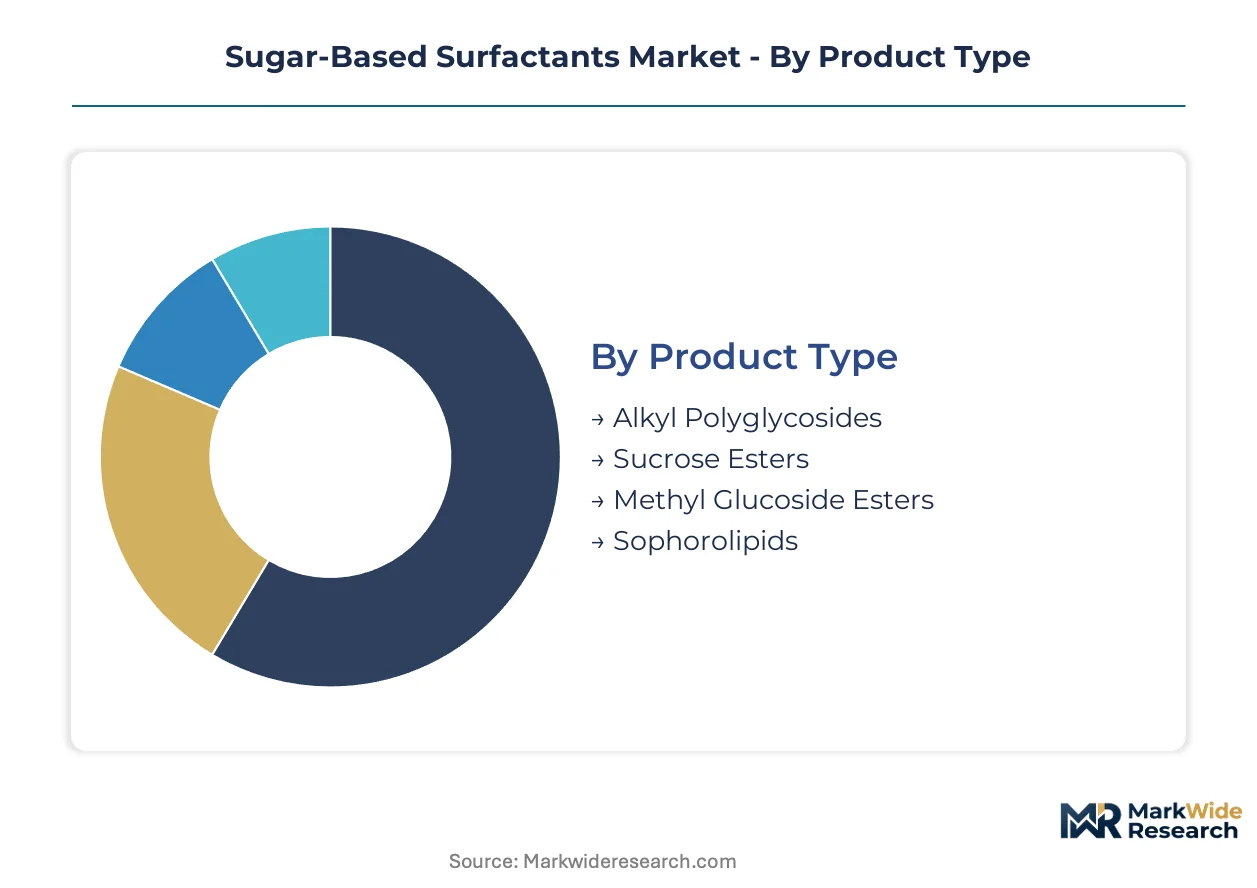
Sugar-based surfactants fragment across four dimensions that determine pricing power and specification rigor. Product chemistry dictates feedstock integration requirements, while end-use grade thresholds separate commodity volumes from premium margin pools.
Product Type:
Upgrade cycles from acid-catalyzed to enzymatic production routes are concentrating investment in segments with the narrowest polydispersity specifications.
- Alkyl Polyglycosides:Glucose-derived amphiphiles with glycosidic linkages to C8-C14 alkyl chains. REACH restrictions on petrochemical alternatives are redirecting German household cleaning procurement toward these materials.
- Sucrose Esters:Fatty acid esters of sucrose with tunable hydrophilic-lipophilic balance. FDA GRAS status locks in food processing demand across North American bakery and confectionery applications.
- Methyl Glucoside Esters:Derived from glucose methylation followed by esterification with C12-C18 acids. Personal care formulators specify these for reduced skin irritation profiles in sensitive-skin segments.
- Sophorolipids:Glycolipid biosurfactants from Candida bombicola fermentation. Microbial yield improvements are compressing production economics and expanding addressable market segments.
Alkyl polyglycosides sit at the top of the volume ranking, with sophorolipids climbing the fastest.
End Use Industry:
Cost tier differentiation separates specification-intensive personal care from price-sensitive industrial applications.
- Personal Care:Shampoo, body wash, and facial cleanser formulations demanding ECOCERT and COSMOS certification compliance. Sulfate-free claim expansion in French and German cosmetic clusters is accelerating alkyl polyglycoside procurement.
- Household Cleaning:Dishwashing liquids, laundry detergents, and surface cleaners. EU Green Deal bio-based quotas mandate renewable content thresholds that pull sophorolipid volumes into German supply chains.
- Industrial Applications:Metalworking fluids, textile processing, and agrochemical formulations. Hard water performance limitations above 300 ppm calcium constrain adoption in certain metalworking segments.
- Food Processing:Emulsifiers for bakery, confectionery, and dairy applications. Tightening FDA impurity thresholds for sucrose esters create margin pools for producers with pharmaceutical-grade purification assets.
Personal care commands the steepest price premiums, while household cleaning delivers the largest absolute volume.
Form:
Application-driven handling requirements determine logistics economics and formulation flexibility.
- Liquid:Ready-to-dilute concentrates preferred by personal care compounders for direct tank addition. German formulators specify aqueous alkyl polyglycoside solutions for continuous processing compatibility.
- Powder:Spray-dried or agglomerated products for solid detergent tablets and dry mix applications. Reduced shipping costs favor powder in transatlantic supply chains.
- Paste:Semi-solid concentrates with higher active matter for specialized industrial formulations. Metalworking fluid compounders specify pastes for controlled dilution protocols.
- Gel:Structured formulations for viscous personal care products. Cosmetic-grade gels require tighter rheological specification tolerances than industrial counterparts.
Liquid forms dominate current procurement volumes, with powder formats gaining share in solid detergent tablet segments.
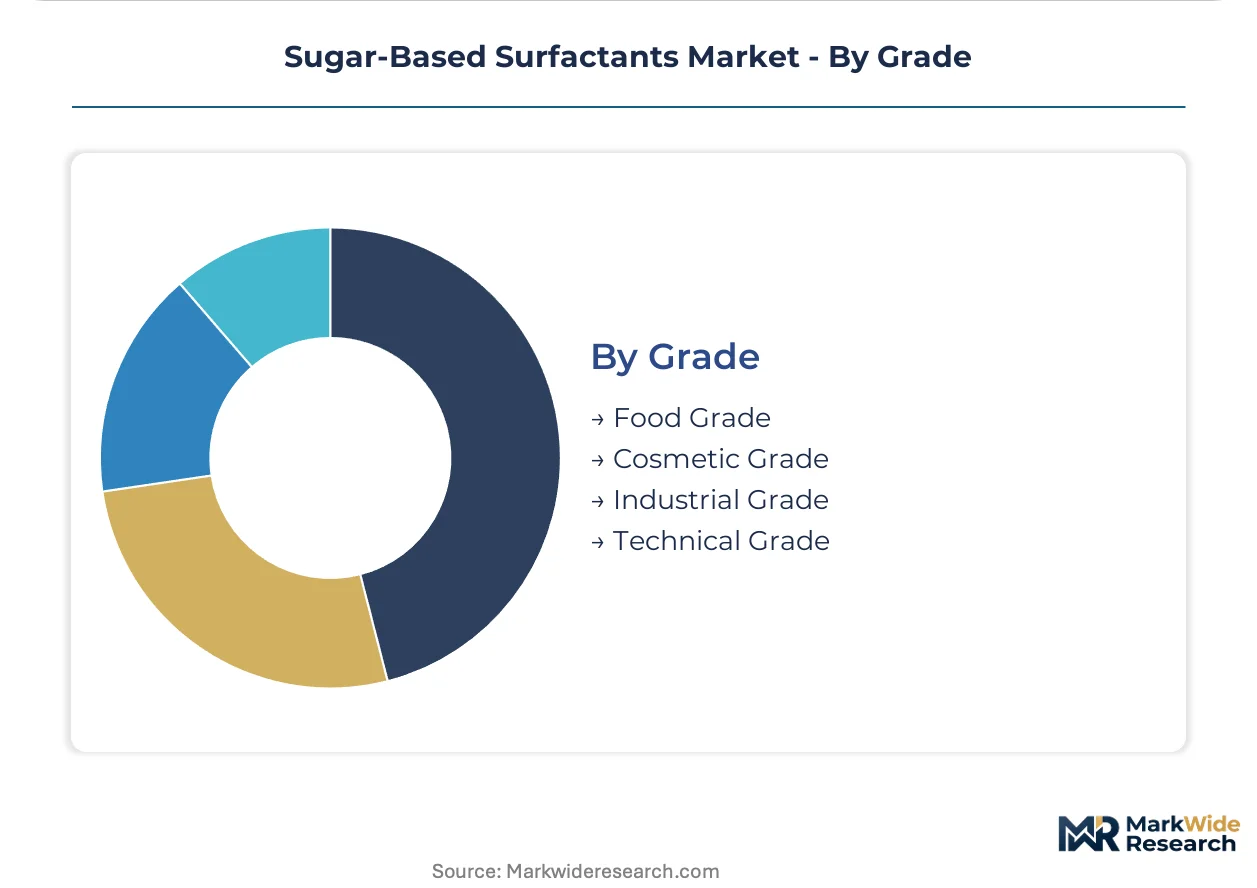
Grade:
Customer type stratification separates pharmaceutical-purity cosmetic grades from commodity industrial specifications.
- Food Grade:Sucrose esters meeting FDA 21 CFR 172.859 and EFSA specifications for direct food contact. Impurity thresholds for residual solvents and heavy metals determine qualification for bakery emulsifier applications.
- Cosmetic Grade:Alkyl polyglycosides and sophorolipids with ECOCERT, COSMOS, or NaTrue certification. Certification timelines extending 18-24 months delay revenue recognition for new product introductions.
- Industrial Grade:Unspecified purity sophorolipids and methyl glucoside esters for metalworking and textile processing. Price volatility in carbohydrate feedstocks squeezes margin predictability for non-integrated producers.
- Technical Grade:Intermediate purity for agrochemical adjuvants and oilfield chemicals. Performance gaps in hard water limit substitution potential for petrochemical alternatives in certain segments.
Cosmetic grade captures the widest margin spreads, with food grade expanding most quickly on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation microbiologists and downstream processing engineers concentrate in pharmaceutical-industrial clusters across Germany, France, and the United States. This talent distribution anchors regional production capabilities and shapes where integrated carbohydrate feedstock facilities locate.
Germany
BASF SE and Evonik Industries AG operate integrated carbohydrate feedstock facilities in Ludwigshafen and Marl respectively. REACH restrictions on petrochemical surfactants redirect procurement budgets toward bio-based alternatives. The Rhine-Neckar chemical cluster concentrates alkyl polyglycoside production capacity for personal care supply chains.
France
L'Oréal and LVMH maintain dedicated bio-surfactant procurement functions in Paris and Clichy. ECOCERT and COSMOS certification timelines extend 18-24 months for cosmetic-grade materials. The Île-de-France cosmetic cluster drives specification-intensive demand for mild sulfate-free alternatives.
United States
EPA Safer Choice labeling creates federal procurement preference for certified bio-based surfactants. FDA GRAS status for sucrose esters locks in food processing demand across bakery and confectionery applications. The New Jersey-Pennsylvania chemical corridor houses fermentation capacity serving institutional cleaning channels.
India
The Production-Linked Incentive scheme attracts fermentation capacity investments targeting export markets. Galaxy Surfactants Ltd. represents domestic manufacturing presence in this segment. Maharashtra and Gujarat industrial zones concentrate specialty chemical infrastructure for downstream processing.
Brazil
Oxiteno S.A. anchors regional alkyl polyglycoside supply for Latin American personal care formulators. Agricultural carbohydrate feedstock availability from sugarcane processing supports cost-competitive production economics. São Paulo state concentrates formulation and distribution infrastructure for household cleaning applications.
Sugar-Based Surfactants Market Key Industry Players
Top-tier vendors anchor integrated carbohydrate feedstock production, while mid-scale compounders rely on toll manufacturing arrangements. The market structure concentrates around producers with captive glucose supply and pharmaceutical-grade purification assets. Strategic archetypes include fermentation-based biosurfactant specialists, petrochemical-diversified bio-based entrants, and regional alkoxylation compounders. Dominant competitive moves encompass backward integration into carbohydrate feedstocks and geographic expansion through toll manufacturing partnerships.
Among European-based integrated producers, BASF SE and Evonik Industries AG exemplify the fermentation-chemical convergence archetype, while Clariant AG occupies a position representing specialized sophorolipid production capabilities. Croda International Plc sits within the food-grade specification tier, reflecting pharmaceutical-grade purification asset deployment. These three entities collectively represent distinct competitive positioning vectors based on feedstock integration depth and end-use certification scope.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Stepan Company |
| Croda International Plc |
| Solvay S.A. |
| Evonik Industries AG |
| SEPPIC |
| Oxiteno S.A. |
| Galaxy Surfactants Ltd. |
| Others |
Cost & Logistics Intelligence
EU Green Deal bio-based procurement mandates are forcing household cleaning formulators to absorb premium pricing for certified alkyl polyglycosides, compelling supply chains to prioritize integrated carbohydrate feedstock producers over import-dependent compounders and compressing margin structures for toll manufacturers.
Pricing Analysis
Bundled certification-and-delivery contracts dominate cosmetic-grade procurement, while unbundled commodity spot trading persists in industrial applications. Three-tier pricing structure across cosmetic, food, and industrial grade levels reflects ECOCERT timeline investments and purification asset intensity. Cost compression in industrial-grade sucrose esters is intensifying because Brazilian sugarcane processors are expanding fermentation capacity. Household cleaning compounders exhibit highest price sensitivity, while French cosmetic brands accept premiums for guaranteed COSMOS compliance.
Supply Chain Analysis
Carbohydrate feedstock supply rests on German glucose refiners, Brazilian sugarcane processors, and Indian corn starch producers. Sophorolipid production draws from Candida bombicola strain banks concentrated in pharmaceutical-industrial clusters. Single-source vulnerability in cosmetic-grade certification expertise creates bottleneck risk for new product introductions. Distribution runs through integrated producers with captive fermentation capacity directly to personal care formulators, bypassing traditional chemical distributors in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by regulatory mandates that permanently shift procurement budgets from petrochemical to bio-based surfactants across European formulation supply chains.
For Market Incumbents: Lock in multi-year carbohydrate supply agreements with Ludwigshafen and Marl integrated producers before fermentation capacity tightens. Secure ECOCERT and COSMOS certification pipelines now to preempt 18-24 month approval delays that amino acid surfactant competitors are exploiting. Backward integration into glucose refining insulates margin predictability against agricultural commodity volatility.
For New Entrants and Emerging Players: Toll manufacturing partnerships with Maharashtra fermentation operators offer the lowest-capital entry path into European household cleaning supply chains. Technical-grade metalworking fluid applications present the most penetrable white space, given hard water performance gaps that incumbent biosurfactants have not resolved. Lead with EPA Safer Choice pre-certification to unlock federal institutional procurement channels.
For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation-based biosurfactant specialists possessing pharmaceutical-grade purification assets and established GRAS dossiers. Five-to-ten-year viability hinges on microbial yield improvements outpacing carbohydrate feedstock cost swings. Watch Candida bombicola strain patent filings as the inflection signal for production economics disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbohydrate Feedstocks | BASF SE's Ludwigshafen glucose refining captures margin pools unreachable by toll-dependent competitors. |
| Long-term Supply Agreement | German metalworking fluid compounders are locking in multi-year alkyl polyglycoside contracts with integrated producers. |
| Green Manufacturing Transition | Continuous processing technology in sophorolipid fermentation compresses capital intensity versus batch methods. |
| Joint Venture | Indian PLI scheme incentives attract fermentation partnerships targeting export-oriented specialty chemical production. |
| Capacity Expansion | French cosmetic clusters demand expanded ECOCERT-certified alkyl polyglycoside output for sulfate-free formulation pipelines. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with fermentation plant managers, personal care procurement leads, household cleaning formulators, and carbohydrate feedstock traders combined with secondary validation from ECHA REACH registration databases, EU Green Deal implementation reports, FDA GRAS notices, and SEC 10-K chemical segment disclosures. Trade flow analysis from customs records triangulates production volume claims against apparent consumption patterns.
Historical trendline analysis of alkyl polyglycoside and sophorolipid price spreads across cosmetic, food, and industrial grade tiers informs projection elasticity assumptions. The forecast framework segments by product chemistry, end-use industry, form, and grade certification scope across the analysis window. CAGRs derive from weighted capacity expansion timelines, regulatory mandate phase-in schedules, and substitution elasticity estimates for sulfate-free personal care formulations.
Revisions become necessary when REACH authorization timelines accelerate, fermentation yield breakthroughs alter production economics, or carbohydrate feedstock price volatility exceeds historical bands. Forecasts reflect documented assumptions about regulatory enforcement consistency and certification body capacity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Tetradecyl Chloride Market
Surfactants
Coconut Derived Surfactants Market
Surfactants
Green Surfactants Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Isopropyl Myristate Market
Surfactants
Global Methyl Soyate Market
Surfactants
Global Sodium Cocoyl Glutamate Market
Surfactants
Emulsion Stabilizers Market
Surfactants
Selenium Sulphide Market
Surfactants
Bitumen Emulsifier Market
Surfactants
Surfactant EOR Market
Surfactants
Global Surfactants Market
Surfactants
Cationic Surfactants Market
Surfactants
Polymer Surfactants Market
Surfactants
Calcium Stearoyl-2 Lactylate Market
Surfactants
Natural Surfactants Market