
 Fungicide Active Ingredients Market | 2026-2036
Fungicide Active Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Fungicide Active Ingredients Market Foresight
Chinese agrochemical intermediates production is pivoting toward higher-purity azole synthesis to serve export markets. BASF SE leverages captive benzene derivatives supply to sustain cost advantages in triazole manufacturing. Syngenta AG anchors its position through integrated seed-to-spray platforms across Latin America. Bayer AG differentiates via digital agronomy bundling with fungicide prescriptions.
Fungicide active ingredients are biologically active chemical compounds formulated to inhibit fungal pathogen development, typically requiring purity thresholds above 95% technical grade for commercial registration. These compounds function by disrupting cell membrane synthesis, mitochondrial respiration, or tubulin polymerization in target phytopathogens. Triazoles occupy the largest volume position due to their systemic mobility and broad-spectrum control across cereal grains. Strobilurins command premium positioning in high-value horticultural plants where resistance management justifies elevated per-hectare expenditure. The suspension concentrate formulation segment is gaining share as drift-reduction mandates favor liquid delivery systems over dustable powders.
The EPA governs residue tolerance establishment and product registration timelines in the United States, while the EU's Farm to Fork Strategy under the European Green Deal mandates 50% pesticide reduction targets that reshape active ingredient portfolios. China's MEE enforces stricter effluent standards on azole and strobilurin intermediate production, raising compliance costs for export-oriented manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions where simultaneous re-registration requirements in multiple markets could strain R&D allocation decisions.
Market Dynamics
Resistance management protocols are compressing product lifecycles across all fungicide chemistries, forcing manufacturers to accelerate molecular diversification while maintaining residue compliance under divergent national standards.
Growth Catalysts
- EU Farm to Fork pesticide reduction mandates:The 50% reduction target under the European Green Deal is redirecting R&D investment toward bio-based formulation platforms and precision application technologies.
- Brazilian soybean expansion:The Cerrado belt's double-cropping intensity generates year-round fungicide demand for Asian soybean rust management.
- California specialty crop intensification:Preventive spray programs in tree nuts and stone fruits are elevating per-hectare active ingredient consumption.
Market Restraints
- Azole intermediate supply concentration:Chinese manufacturers dominate technical-grade azole production, exposing formulators to export license volatility and environmental compliance disruptions.
- Strobilurin resistance proliferation:Pathogen populations in wheat and grape production regions have developed reduced sensitivity, compressing effective spray windows.
- REACH re-registration costs:The EU's substance evaluation process demands multi-year toxicology packages that strain mid-tier active ingredient portfolios.
Strategic Opportunities
- Biological-synthetic hybrid formulations:Convergence of fermentation-derived metabolites with reduced-rate synthetics opens premium positioning in organic-compliant channels.
- India horticulture mechanization:Protected cultivation expansion in Maharashtra and Karnataka creates demand for systemic fungicides with low phytotoxicity profiles.
- Digital agronomy bundling:Prescription algorithms tied to weather stations and disease models enable subscription-based active ingredient delivery.
Industry Challenges
- Formulation chemist scarcity:Expertise in suspension concentrate stability and drift-reduction adjuvant design concentrates among retiring specialists.
- Multi-jurisdiction registration synchronization:Divergent data requirements between EPA, EFSA, and Brazil's ANVISA extend product launch timelines.
- Legacy powder formulation asset stranding:Drift-reduction mandates in California and EU member states devalue dustable powder production capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fungicide Active Ingredients Market |
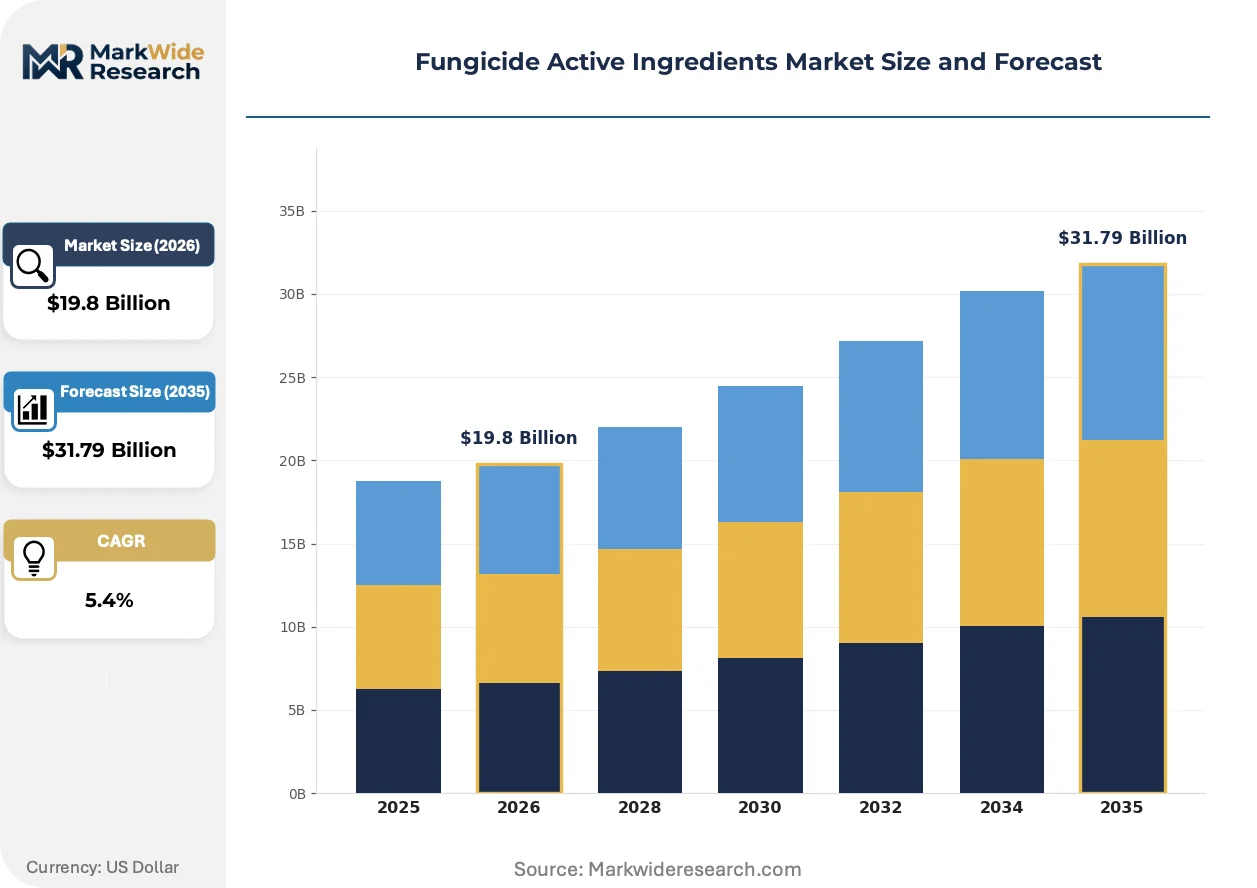
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $31.79 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Active Ingredient Type: Triazoles, Strobilurins, Carbamates, Sulfur Compounds, Anilides Application Crop: Cereal Grains, Horticultural Plants, Pulses, Oilseeds, Fiber Crops Formulation: Wettable Powder, Emulsifiable Concentrate, Dustable Powder, Granules, Suspension Concentrate End User Segment: Contract Farmers, Agrochemical Distributors, Agricultural Cooperatives, Large-Scale Growers |
| Companies Covered | BASF SE, Syngenta AG, Bayer AG, Corteva Agriscience, FMC Corporation, UPL Limited, Sumitomo Chemical Co., Ltd., ADAMA, Nissan Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fungicide Active Ingredients Market Shifts & Advancements
Formulation chemistry is pivoting toward delivery systems that reconcile efficacy with environmental fate constraints, while biological actives gain technical credibility through improved shelf stability and tank-mix compatibility.
Nano-emulsion carrier systems are consolidating market share among high-value horticultural applications. These colloidal delivery platforms improve cuticular penetration in perennial crops. Specialty crop operators in California and Spain are adopting them at accelerated rates, compressing demand for conventional emulsifiable concentrates.
China's MEE effluent enforcement on azole and strobilurin intermediate synthesis is restructuring manufacturing geography. Stricter wastewater standards have shuttered small-scale producers in Jiangsu province. Export-oriented technical-grade suppliers are relocating toward integrated chemical parks with captive treatment infrastructure.
Retail agronomy platforms are unbundling fungicide procurement from bundled crop protection packages. Large soybean and corn growers in Brazil's Mato Grosso state now negotiate active ingredient volumes directly with distributors. This disintermediation compresses channel margins while rewarding manufacturers with direct technical support capabilities.
Fungicide Active Ingredients Market Segmentation
Fungicide active ingredient segmentation reveals divergent regulatory pathways and formulation requirements across chemistries. Manufacturers align R&D portfolios with residue tolerance thresholds that vary by crop category and end-user scale.
Active Ingredient Type:
Triazoles and strobilurins carry the heaviest re-registration burdens under EPA and EFSA protocols, while sulfur compounds face lighter toxicology packages.
- Triazoles:Systemic azole compounds inhibit ergosterol biosynthesis in fungal cell membranes. Demand concentrates in wheat and barley production across the US Great Plains and EU member states, where fusarium head blight management justifies premium pricing despite resistance monitoring requirements.
- Strobilurins:Mitochondrial respiration inhibitors derived from natural fungal metabolites. Grape and pome fruit growers in France, Italy, and California's Central Valley drive consumption, though reduced sensitivity in powdery mildew populations has compressed effective spray windows in Champagne and Napa Valley.
- Carbamates:Broad-spectrum contact fungicides with shorter residual activity.
- Sulfur Compounds:Multi-site inorganic protectants with organic-compliant status in many jurisdictions.
- Anilides:Carboxylic acid amides targeting cellulose synthesis in oomycete pathogens.
Triazoles sits at the top of the volume ranking, with strobilurins climbing the fastest despite resistance constraints.
Application Crop:
Per-hectare fungicide expenditure scales with crop value density, creating tiered pricing structures across commodity and specialty segments.
- Cereal Grains:Wheat, rice, and corn dominate volume consumption due to planted acreage scale. Asian soybean rust pressure in Brazil's Cerrado and septoria leaf blotch cycles in France and Germany sustain preventive spray programs with triazole-strobilurin tank mixes.
- Horticultural Plants:Tree nuts, stone fruits, and vegetables command the highest per-hectare active ingredient expenditure. California almond growers and Spanish citrus operators adopt nano-emulsion formulations to meet residue limits under EPA and EFSA maximum residue levels.
- Pulses:Chickpea and lentil production in India and Canada drives demand for seed treatment formulations.
- Oilseeds:Soybean and canola rust management requires multi-spray programs in Brazil and Argentina.
- Fiber Crops:Cotton root rot control in Texas and Gujarat sustains niche carbamate consumption.
Cereal grains anchor volume demand, with horticultural plants expanding most quickly on value-per-hectare metrics.
Formulation:
Drift-reduction mandates in California and EU member states are restructuring manufacturing asset values across physical form categories.
- Suspension Concentrate:Aqueous dispersions of solid active ingredients with superior tank-mix stability and reduced operator exposure. Brazil's Mato Grosso soybean operators and Spanish olive growers have shifted procurement toward this format as dustable powder restrictions tighten.
- Emulsifiable Concentrate:Oil-based solutions with established manufacturing infrastructure but declining share in high-value horticulture. California's Department of Pesticide Regulation air quality standards have accelerated phase-out timelines for aromatic solvent carriers.
- Wettable Powder:Fine particle suspensions requiring constant agitation.
- Dustable Powder:Dry formulations facing asset stranding from occupational exposure regulations.
- Granules:Controlled-release carriers for soil-borne pathogen management.
Suspension concentrate has captured the leading volume position, with granules gaining share fastest in soil-application niches.
End User Segment:
Procurement scale determines access to technical support and direct manufacturer relationships versus distributor-mediated supply.
- Large-Scale Growers:Operations exceeding 5,000 hectares negotiate active ingredient volumes directly with BASF, Syngenta, and Bayer distributors in Brazil's Mato Grosso and Iowa's corn belt. These buyers bundle digital agronomy subscriptions with fungicide procurement, compressing traditional channel margins.
- Agricultural Cooperatives:Member-owned purchasing organizations aggregate demand across smaller holdings. French cereal cooperatives and US Midwest grain marketing cooperatives leverage volume to secure preferential formulation pricing and shared application equipment pools.
- Contract Farmers:Growers under processor agreements with limited input autonomy.
- Agrochemical Distributors:Regional wholesalers maintaining inventory and technical service relationships.
Large-scale growers command the highest volume share, with agricultural cooperatives expanding their procurement influence fastest through consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is restructuring manufacturing geography as stricter effluent standards in China's Jiangsu province push technical-grade production toward integrated chemical parks, while formulators seek compliance-cost advantages across jurisdictions with divergent environmental enforcement timelines.
United States
California's Central Valley specialty crop operators drive preventive fungicide programs in tree nuts and stone fruits. The EPA governs residue tolerance establishment and product registration timelines, with California's Department of Pesticide Regulation imposing additional air quality standards on aromatic solvent carriers. The Fresno-Modesto corridor concentrates nano-emulsion formulation adoption among almond and pistachio growers.
Brazil
The Cerrado soybean belt generates year-round demand for Asian soybean rust management through double-cropping intensity. ANVISA maintains multi-year toxicology requirements that extend product launch timelines alongside simultaneous EPA and EFSA obligations. Mato Grosso state anchors direct procurement negotiations between large-scale growers and manufacturer distributors.
China
Export-oriented agrochemical intermediate producers pivot toward higher-purity azole synthesis to serve international formulators. The MEE enforces stricter wastewater standards on azole and strobilurin production, shuttering small-scale manufacturers in Jiangsu and relocating capacity toward integrated chemical parks with captive treatment infrastructure. Zhejiang and Shandong provinces concentrate surviving technical-grade suppliers.
Germany
REACH re-registration demands strain mid-tier active ingredient portfolios with multi-year toxicology packages. The EU's Farm to Fork Strategy under the European Green Deal mandates pesticide reduction targets that reshape R&D investment toward bio-based platforms. The Rhine-Main industrial corridor sustains triazole manufacturing through captive benzene derivative supply chains.
India
Protected cultivation expansion in Maharashtra and Karnataka creates demand for systemic fungicides with low phytotoxicity profiles. BIS standards and CDSCO registration requirements govern import and domestic manufacturing compliance. The Pune-Nashik cluster concentrates formulation packaging for horticultural export markets.
Fungicide Active Ingredients Market Competitive Landscape
European producers anchor one tier through integrated seed-to-spray platforms and captive feedstock supply; Chinese intermediate specialists hold cost-position advantages in technical-grade azole synthesis. The vendor base separates into consolidated multinational formulators with direct grower relationships and mid-tier regional blenders dependent on imported actives. Three archetypes dominate: backward-integrated petrochemical players, biological-synthetic hybrid developers, and distributor-anchored local formulators. Capacity relocation and digital agronomy bundling constitute the dominant competitive moves.
Within the backward-integrated tier, BASF SE exemplifies captive supply chain advantages through benzene derivative control, while Syngenta AG occupies a position defined by Latin American platform integration. Bayer AG represents the digital bundling archetype, anchoring prescription algorithm development alongside fungicide portfolios. These three entities collectively illustrate how technical-grade security and direct grower relationships determine competitive positioning.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta AG |
| Bayer AG |
| Corteva Agriscience |
| FMC Corporation |
| UPL Limited |
| Sumitomo Chemical Co., Ltd. |
| ADAMA |
| Nissan Chemical Corporation |
| Others |
Supply & Pricing Matrix
EU Farm to Fork pesticide reduction mandates gate qualified supply and premium-tier pricing access, as formulators achieving bio-based certification command preferential positioning while conventional synthetic producers absorb compliance cost compression. Chinese environmental enforcement on azole intermediate synthesis concentrates technical-grade supply among integrated chemical parks, amplifying pricing power for surviving export-oriented manufacturers.
Pricing Analysis
Distributor margins in Brazil's Mato Grosso and Iowa's corn belt compress as large-scale growers negotiate direct active ingredient volumes with BASF, Syngenta, and Bayer distributors. Three-tier pricing structure across premium nano-emulsion, standard suspension concentrate, and economy wettable powder levels stratifies by formulation complexity and residue compliance tier. Pricing pressure stems from REACH re-registration cost absorption among mid-tier European formulators. Agricultural cooperatives exhibit highest price sensitivity through volume aggregation, while California specialty crop operators show lowest sensitivity due to residue limit compliance premiums.
Supply Chain Analysis
Empty container return programs and formulation packaging refurbishment flows remain underdeveloped across fungicide distribution, creating asset stranding risk for legacy dustable powder production infrastructure. Technical-grade azole synthesis concentrates in China's Zhejiang and Shandong provinces, with strobilurin intermediate production anchored in Jiangsu's surviving integrated chemical parks. Captive benzene derivative supply from BASF's Ludwigshafen complex and fermentation-derived biological actives from specialty suppliers constitute critical input dependencies. Single-source vulnerability pervades Chinese technical-grade export licensing. Distribution runs through regional agrochemical wholesalers maintaining inventory and technical service relationships with grower cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where stricter MEE effluent enforcement in Jiangsu province elevates compliance costs for Chinese technical-grade suppliers while EU Farm to Fork mandates redirect R&D investment toward bio-based platforms at differential cost structures.
For Market Incumbents: Hedge against strobilurin resistance proliferation and Chinese intermediate supply concentration by accelerating biological-synthetic hybrid formulation development and securing captive benzene derivative supply through backward integration into petrochemical feedstocks. Prioritize certification investment for EU bio-based compliance tiers. For New Entrants and Emerging Players: Regional distributors in India's Maharashtra and Karnataka present channel partnership opportunities for protected cultivation systemic fungicide penetration. Target horticultural mechanization segments with low phytotoxicity profile formulations. Pursue direct technical support capabilities to match large-scale grower procurement expectations. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier regional formulators with imported active dependencies because multi-jurisdiction registration synchronization capabilities concentrate among retiring specialists. Five-to-ten year viability hinges on biological-synthetic hybrid platform development. Monitor ANVISA registration timeline compression as inflection indicator for Brazilian market access valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Benzene Derivatives | BASF's captive supply chain sustains cost advantages in triazole manufacturing against import-dependent competitors. |
| Bio-based Formulation Platform Development | EU Farm to Fork mandates redirect R&D investment toward fermentation-derived metabolites with reduced-rate synthetic pairing. |
| Digital Agronomy Subscription Bundling | Bayer's prescription algorithms tied to weather stations enable recurring revenue attachment to fungicide procurement. |
| Integrated Seed-to-Spray Platform Expansion | Syngenta's Latin American anchor captures full-cycle value from genetic trait development through spray application timing. |
| Suspension Concentrate Manufacturing Conversion | Drift-reduction mandates in California and EU member states devalue dustable powder assets while favoring aqueous dispersion capacity. |
Research Methodology
Direct dialogue with agrochemical plant managers, procurement leads at downstream formulators, distribution channel partners, and technical R&D directors grounded qualitative findings in operational reality. Secondary validation drew from EPA registration databases, EFSA substance evaluation records, China MEE effluent compliance disclosures, and customs trade data for azole and strobilurin intermediate flows. Bottom-up active ingredient volume estimates triangulated against top-down formulation market assessments.
Segment-level projections across the analysis window reflect modeled interactions between chemistry type, application crop, physical formulation, and end-user procurement scale. CAGRs derived from regression analysis against planted acreage trends, resistance management protocol adoption curves, and regulatory enforcement intensity indices. Forecast inputs incorporated double-cropping intensity metrics for Brazil's Cerrado and California air quality standard phase-out timelines for aromatic solvent carriers.
Revisions become necessary when ANVISA registration timeline extensions, REACH substance evaluation acceleration, or Chinese export license volatility materialize beyond modeled parameters. Practitioners should monitor MEE enforcement intensity in Jiangsu province and EU bio-based certification uptake rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Elemental Fluorine Market
Chemicals
Deicing Fluid Market
Chemicals
Rocket Propellant Chemicals Market
Chemicals
Fluoroantimonic Acid Market
Chemicals
Aluminum Chemicals Market
Chemicals
Inorganic Chemicals Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Potassium Fluoride Market
Chemicals
3,5-Dinitroaniline Market
Chemicals
Flooring Chemicals Market
Chemicals
Calcium Hydroxide Market
Chemicals
Peracetic Acid Market
Chemicals
South Korea Methanol Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market
Chemicals
Tanning Agents Market