
 Dioctyl Sulfosuccinates Components Market | 2026-2036
Dioctyl Sulfosuccinates Components Market Size, Share, and Industry Trends Forecast 2026-2036
Dioctyl Sulfosuccinates Components Market Analysis
Green chemistry process intensification is reshaping how dioctyl sulfosuccinate derivatives are synthesized and purified across the value chain. BASF SE leverages its integrated alkoxylate technology platforms to maintain cost leadership in high-purity emulsifier grades. Evonik Industries AG anchors its position through specialized hydrogenation capabilities that yield narrow molecular-weight distributions for pharmaceutical customers. Stepan Company differentiates via backward integration into fatty alcohol feedstocks across North American manufacturing assets.
Dioctyl sulfosuccinates are anionic surfactants synthesized through maleic anhydride esterification followed by sulfonation, typically yielding products with critical micelle concentrations below 0.1% w/v and surface tensions near 28 mN/m at 25°C; these properties make them indispensable as wetting agents and emulsifiers in aqueous systems where rapid interfacial activity is required. The surfactant segment commands the largest volume share due to its ubiquity in industrial cleaning and agrochemical formulations, while the solubilizer category is expanding fastest as ophthalmic and injectable drug formulations multiply. Dispersant applications in waterborne coatings are maturing in Western Europe, though margin pools remain attractive for suppliers offering food-contact certified grades.
EPA registration requirements under the Toxic Substances Control Act govern commercial introduction of new sulfosuccinate chemistries in the United States, while REACH dossier obligations in Europe enforce comprehensive hazard communication and substitution principles. FDA food additive regulations and USP-NF monograph standards for pharmaceutical excipients further constrain supplier qualification pathways. Stakeholders must monitor evolving state-level restrictions on per- and polyfluoroalkyl substances, as these may cascade into broader surfactant substitution mandates that reshape competitive positioning in specialty applications.
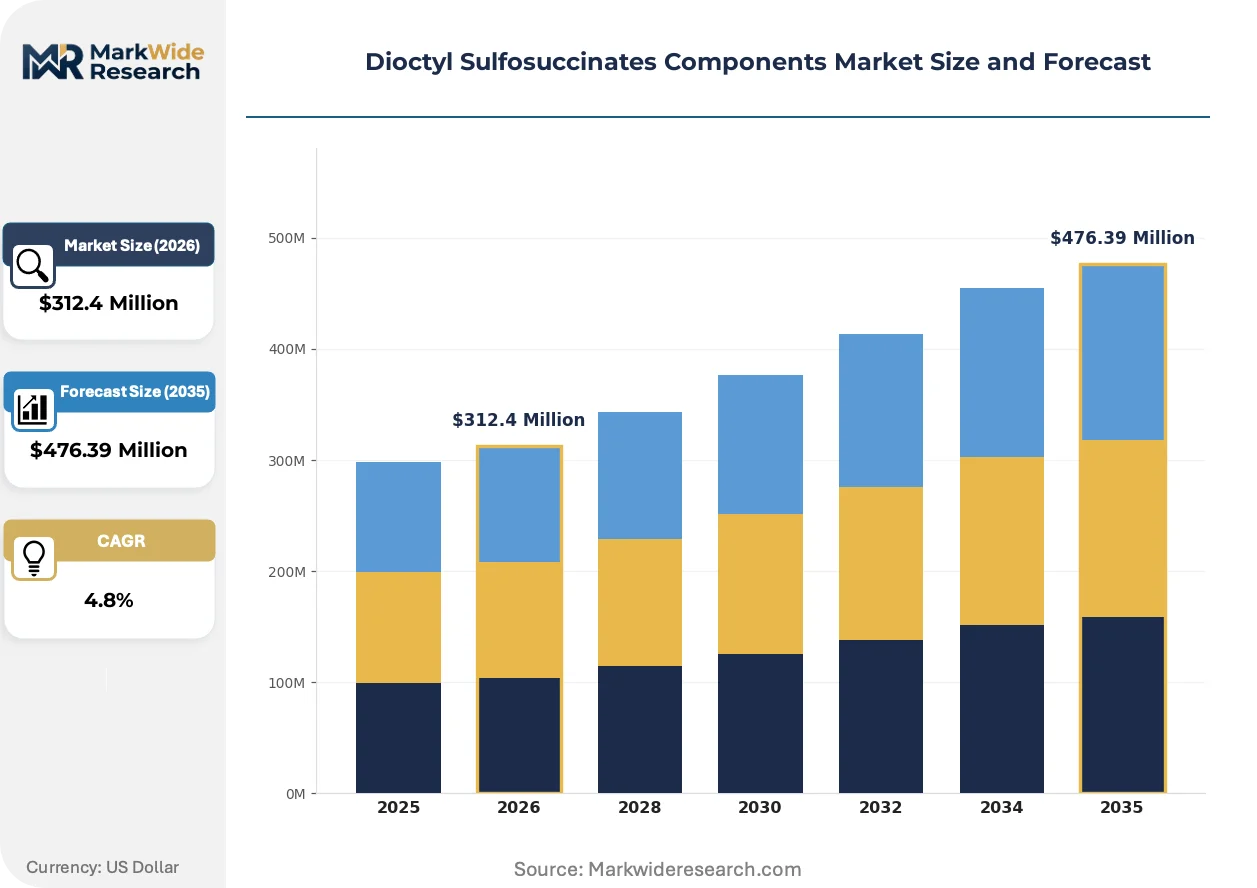
Market Dynamics
Green chemistry mandates are compressing synthetic pathways for dioctyl sulfosuccinates, forcing manufacturers to retire solvent-intensive esterification in favor of enzymatic catalysis and continuous-flow reactor designs that slash solvent recovery costs.
Growth Catalysts
- Ophthalmic formulation expansion:Injectable and eye-drop drug pipelines are multiplying demand for high-purity solubilizer grades that meet USP-NF monograph standards. Formulation developers in Germany and India are qualifying sulfosuccinates for biologic delivery systems.
- REACH substitution principles:ECHA's restriction roadmap on persistent organic pollutants is redirecting procurement away from ethoxylated alkylphenols toward biodegradable anionic alternatives. European agrochemical blenders are reformulating wetting agents to preempt authorization sunset dates.
- Continuous-flow sulfonation:Process intensification technology is cutting reaction times from hours to minutes while improving sulfonation uniformity. Specialty chemical manufacturers in China's Jiangsu province are retrofitting batch plants with microreactor modules.
Market Restraints
- Maleic anhydride price volatility:Feedstock costs swing with refinery operating rates and phthalic anhydride co-production economics. Producers lack long-term hedging instruments for this petrochemical derivative.
- Specialized hydrogenation capacity concentration:Narrow molecular-weight pharmaceutical grades require high-pressure hydrogenation assets concentrated among German and Swiss toll manufacturers. Capacity constraints limit supply elasticity for qualified excipient batches.
- Fluorosurfactant substitution threat:Per- and polyfluoroalkyl substance restrictions are paradoxically slowing sulfosuccinate adoption in some coatings segments where buyers await next-generation fluorine-free alternatives with superior surface tension reduction.
Strategic Opportunities
- Bio-based fatty alcohol feedstocks:Palm kernel and coconut oil-derived C8-C10 alcohols are enabling mass-balance certified grades that command premium positioning in European personal care markets. BASF and Evonik are piloting enzymatic esterification with these renewable inputs.
- Indian pharmaceutical manufacturing corridors:CDSCO's accelerated approval pathways for complex generics are attracting formulation developers to Hyderabad and Ahmedabad clusters. Local sulfosuccinate qualification programs lag, creating first-mover openings for excipient suppliers.
- Waterborne industrial coatings:EPA VOC regulations are compressing solvent-borne system share. Food-contact certified dispersant grades for can coatings represent an underexploited margin pool with qualification barriers that deter commodity competitors.
Industry Challenges
- Multijurisdictional excipient certification:Simultaneous USP-NF, EP, and JP compliance requires redundant stability studies and analytical method validation. Timeline compression for generic drug launches strains supplier documentation bandwidth.
- Legacy batch reactor retrofit costs:Continuous-flow conversion demands capital deployment for corrosion-resistant microreactor arrays and real-time analytical integration. Mid-scale producers face stranded asset risk on undepreciated batch infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dioctyl Sulfosuccinates Components Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Surfactants, Solubilizers, Dispersants Application: Food Additives, Personal Care Products, Pharmaceuticals, Coatings End User: Food Industry, Cosmetics Industry, Chemical Manufacturers, Healthcare Providers Distribution Channel: Direct Sales, Distributors, Online Retail, Specialty Stores |
| Companies Covered | BASF SE, Evonik Industries AG, Stepan Company, Dow Chemical Company, Croda International Plc, Clariant AG, Huntsman Corporation, Eastman Chemical Company, Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dioctyl Sulfosuccinates Components Market Emerging Trajectories
Process analytical technology and enzymatic catalysis are converging to transform sulfosuccinate manufacturing economics, while regulatory substitution mandates and buyer sustainability scorecards are rewiring procurement qualification pathways across pharmaceutical and agrochemical value chains.
Enzymatic esterification using immobilized lipase biocatalysts is migrating from pilot-scale demonstration to commercial production for cosmetic-grade dioctyl sulfosuccinates. German specialty chemical manufacturers are adopting these systems to eliminate sulfuric acid neutralization steps and cut aqueous effluent volumes by sixty percent. The technology is compressing capital intensity for new entrant producers while raising purity thresholds that incumbent solvent-based plants struggle to match without write-offs.
REACH authorization requirements for substances of very high concern are tightening hazard communication obligations across European surfactant supply chains. ECHA's 2024 update to the Candidate List is forcing formulators to document substitution plans for legacy emulsifiers, redirecting technical service resources toward sulfosuccinate compatibility studies. Agrochemical distributors in France and Germany are accelerating reformulation timelines to preempt downstream user liability.
Pharmaceutical excipient buyers are consolidating supplier panels around integrated quality systems that bundle raw material traceability with continuous manufacturing readiness. Large generic drug developers in India are disqualifying toll manufacturers lacking in-house hydrogenation and real-time release testing capabilities. This concentration is visible in CDSCO inspection data showing rising import detention rates for non-compliant surfactant shipments from smaller Chinese producers.
Dioctyl Sulfosuccinates Components Market Segmentation
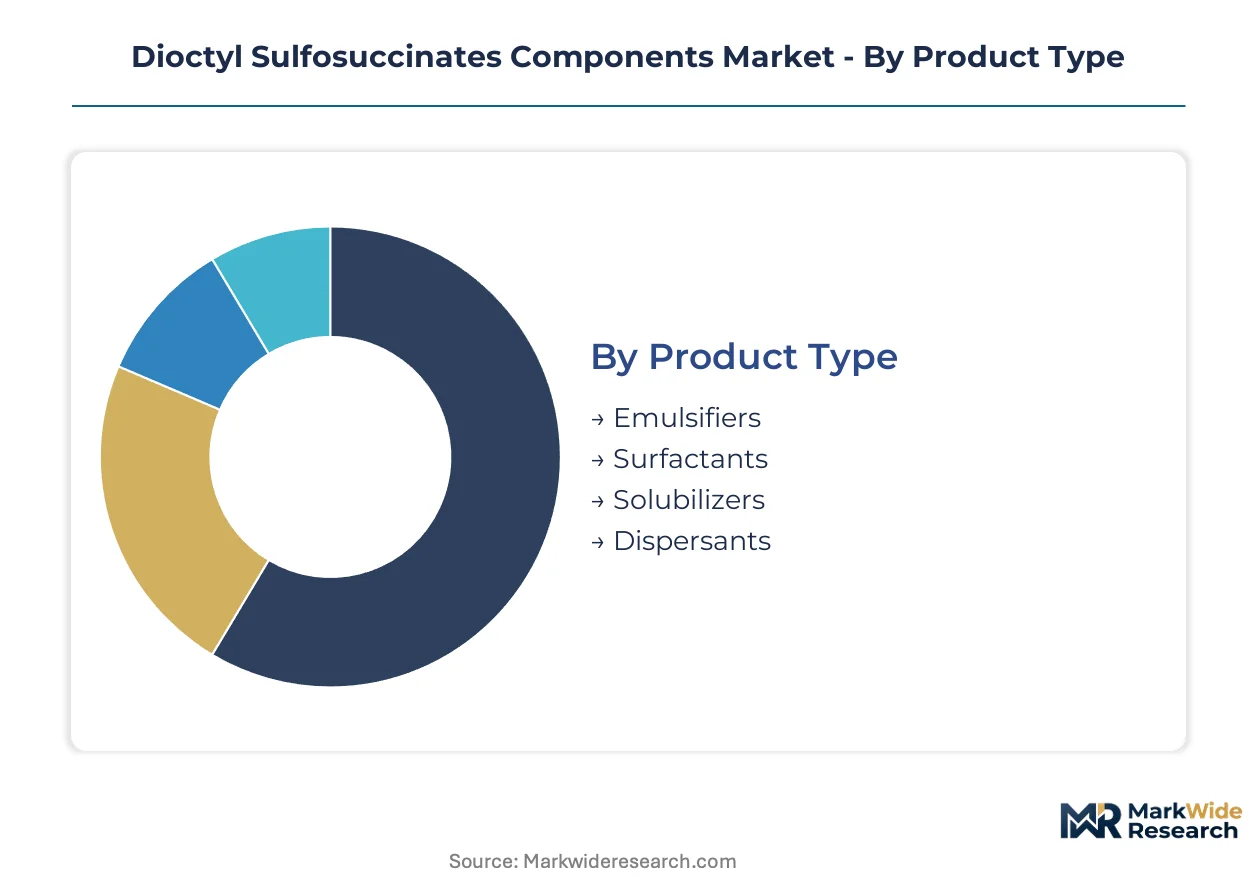
Segmentation in dioctyl sulfosuccinates reveals how functional chemistry dictates procurement pathways across regulated industries. Pharmaceutical and food-contact certifications create tiered qualification barriers that fragment supplier access by end-use.
Product Type:
Mature industrial grades dominate volume, while pharmaceutical-specialized variants command premium positioning through hydrogenation-intensive purification.
- Surfactants:Anionic surface-active agents with critical micelle concentrations below 0.1% w/v serve industrial cleaning and agrochemical wetting applications. Demand concentrates in Germany's specialty chemical manufacturing corridors where REACH substitution principles redirect procurement from ethoxylated alkylphenols. EPA registration requirements under TSCA govern commercial introduction in the United States.
- Solubilizers:High-purity grades meeting USP-NF monograph standards enable ophthalmic and injectable drug formulations. Formulation developers in India and Germany are qualifying these for biologic delivery systems. CDSCO's accelerated approval pathways for complex generics multiply demand from Hyderabad and Ahmedabad clusters.
- Emulsifiers:Stabilize oil-water interfaces in personal care and food systems; mass-balance certified grades from palm kernel and coconut oil feedstocks command premium positioning in European markets.
- Dispersants:Waterborne coatings applications in Western Europe are maturing, though food-contact certified grades for can coatings retain attractive margin pools.
Surfactants handle the majority of throughput; solubilizers are the fastest mover on share.
Application:
Cost tier stratification separates commodity industrial uses from excipient-grade pharmaceutical and food-contact segments requiring redundant stability documentation.
- Pharmaceuticals:Excipient-grade sulfosuccinates for oral, topical, and parenteral dosage forms require simultaneous USP-NF, EP, and JP compliance. Multijurisdictional certification demands redundant analytical method validation that strains supplier documentation bandwidth for generic drug launch timelines.
- Personal Care Products:Cosmetic-grade specifications emphasize mildness and biodegradability profiles for rinse-off and leave-on formulations. European buyers consolidate procurement around sustainability scorecards and green chemistry process certifications.
- Food Additives:FDA food additive regulations and EFSA safety evaluations constrain supplier qualification; enzymatic esterification routes are displacing solvent-based production for cleaner label positioning.
- Coatings:EPA VOC regulations compress solvent-borne system share, redirecting formulation toward waterborne dispersant technologies.
Pharmaceuticals capture the steepest expansion trajectory; coatings volume is flattening as waterborne conversion matures.
End User:
Customer type determines qualification intensity, with healthcare and food sectors imposing the most stringent traceability and continuous manufacturing readiness requirements.
- Chemical Manufacturers:Toll manufacturers and specialty chemical producers supply downstream formulators; backward integration into fatty alcohol feedstocks differentiates competitive positioning.
- Healthcare Providers:Hospital and clinical pharmacy procurement of compounded formulations drives small-volume demand for high-purity excipient grades.
- Cosmetics Industry:Brand owners and contract manufacturers specify biodegradability and renewable content thresholds that redirect supply chain qualification.
- Food Industry:Processors and ingredient blenders prioritize food-contact certification and supply security for emulsifier applications.
Chemical manufacturers absorb the dominant volume share; healthcare providers are expanding most quickly as complex generic pipelines multiply.
Distribution Channel:
Supply concentration in direct relationships with large formulators contrasts with fragmented access through intermediaries for smaller regional buyers.
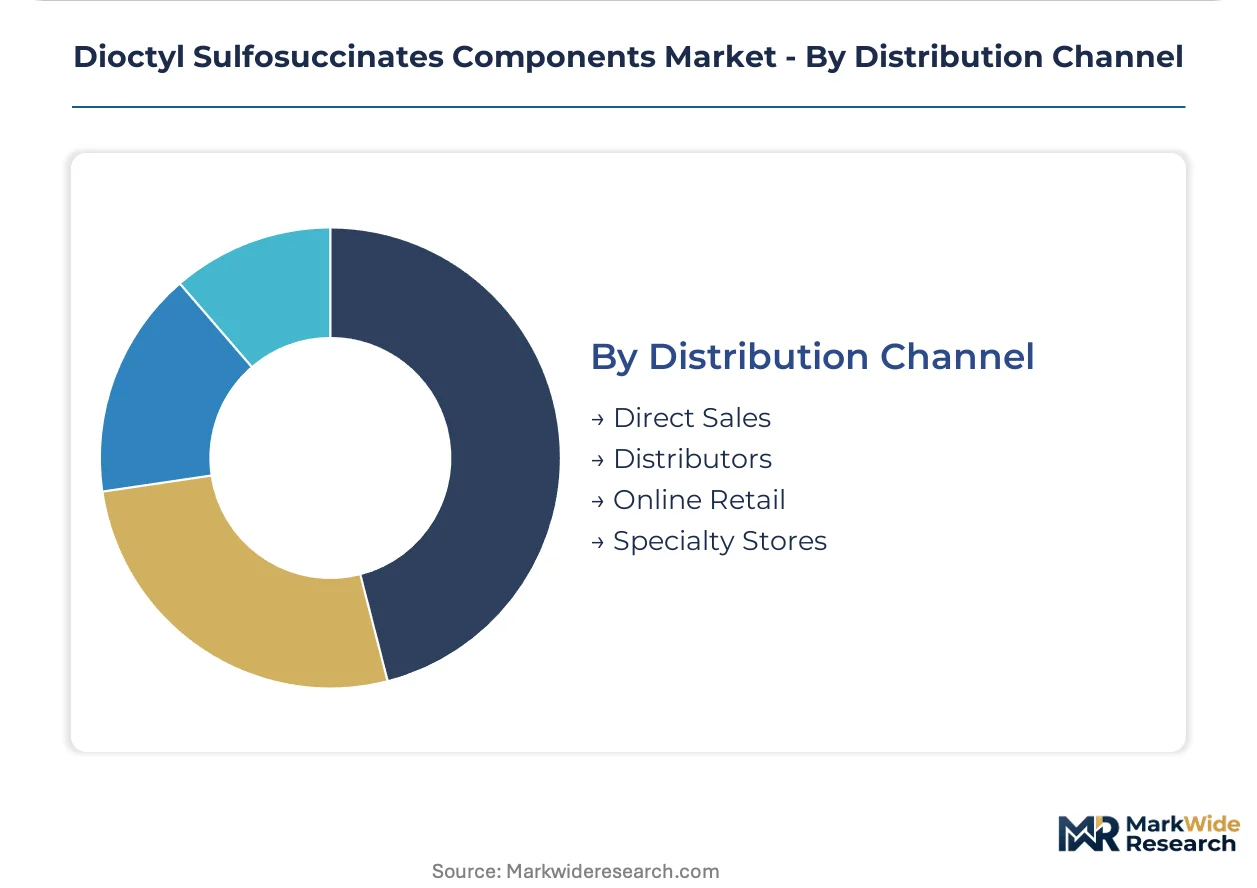
- Direct Sales:Large pharmaceutical and agrochemical formulators negotiate long-term supply agreements with qualified manufacturers. Real-time release testing capabilities and integrated quality systems determine panel inclusion.
- Distributors:Regional chemical distributors serve mid-scale personal care and coatings formulators lacking volume for direct procurement. Inventory positioning in Rotterdam and Singapore hubs supports just-in-time delivery.
- Specialty Stores:Niche suppliers of cosmetic and food-grade ingredients cater to artisanal and small-batch producers.
- Online Retail:E-commerce platforms facilitate sample procurement and small-volume orders for R&D and pilot-scale formulation work.
Direct sales channel manages the bulk of qualified excipient volume; distributors are gaining share fastest among mid-tier personal care formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows for dioctyl sulfosuccinates track specialty chemical manufacturing corridors, with Germany and China running structural surpluses while India remains import-dependent for pharmaceutical-grade material. Regulatory divergence between REACH substitution mandates and FDA monograph standards fragments qualification pathways across jurisdictions.
United States
EPA TSCA registration requirements govern new sulfosuccinate introductions, with formulation developers in New Jersey and North Carolina qualifying high-purity grades for ophthalmic pipelines. FDA food additive regulations constrain supplier pathways for emulsifier applications in processed foods. Houston-Gulf Coast petrochemical corridors anchor maleic anhydride feedstock supply for domestic esterification capacity.
Germany
ECHA's restriction roadmap on persistent organic pollutants redirects agrochemical blenders toward biodegradable anionic surfactants. REACH authorization obligations enforce comprehensive hazard communication across specialty chemical value chains. BASF and Evonik anchor hydrogenation-intensive production in Ludwigshafen and Marl, supplying narrow molecular-weight pharmaceutical grades to European formulators.
China
MIIT industrial chemical standards and evolving environmental compliance compress solvent-intensive batch production in Jiangsu province. NMPA alignment with ICH Q3D guidelines shapes excipient qualification for export-oriented pharmaceutical manufacturers. Yangtze River Delta clusters in Shanghai and Suzhou retrofit microreactor modules for continuous-flow sulfonation to serve domestic coatings demand.
India
CDSCO accelerated approval pathways for complex generics multiply demand from Hyderabad and Ahmedabad pharmaceutical corridors. FSSAI food additive regulations lag excipient-grade qualification, creating import dependence for USP-NF compliant material. Gujarat's specialty chemical belt concentrates toll manufacturing for personal care emulsifiers serving Middle East export markets.
Japan
METI chemical substance management under CSCL aligns with REACH substitution principles for industrial surfactant procurement. PMDA pharmaceutical excipient monographs demand redundant stability documentation that favors established suppliers. Osaka-Kansai chemical manufacturers specialize in cosmetic-grade esterification for Southeast Asian personal care brand owners.
Dioctyl Sulfosuccinates Components Market Vendor Landscape
On the supply side, the industry is consolidating around integrated alkoxylate technology platforms and captive hydrogenation assets that create tiered access barriers. Three strategic archetypes dominate: multinational chemical conglomerates with backward integration into petrochemical feedstocks, mid-scale specialty manufacturers with pharmaceutical qualification expertise, and regional toll producers serving commodity industrial grades. Capacity expansion and enzymatic process licensing represent the dominant competitive vectors as batch reactor retrofit costs strand undepreciated assets.
Among European-headquartered chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated archetype through captive technology platforms and hydrogenation capabilities. Stepan Company anchors North American positioning through fatty alcohol feedstock integration. These three occupy positions that illustrate how geographic concentration of specialized assets shapes competitive access to pharmaceutical and food-contact certification tiers.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Stepan Company |
| Dow Chemical Company |
| Croda International Plc |
| Clariant AG |
| Huntsman Corporation |
| Eastman Chemical Company |
| Solvay S.A. |
| Others |
Supply Flow & Price Mechanics
Jiangsu province's continuous-flow retrofitting wave is concentrating pharmaceutical-grade capacity among toll manufacturers with hydrogenation assets, amplifying pricing power for narrow molecular-weight batches while squeezing commodity surfactant margins.
Pricing Analysis
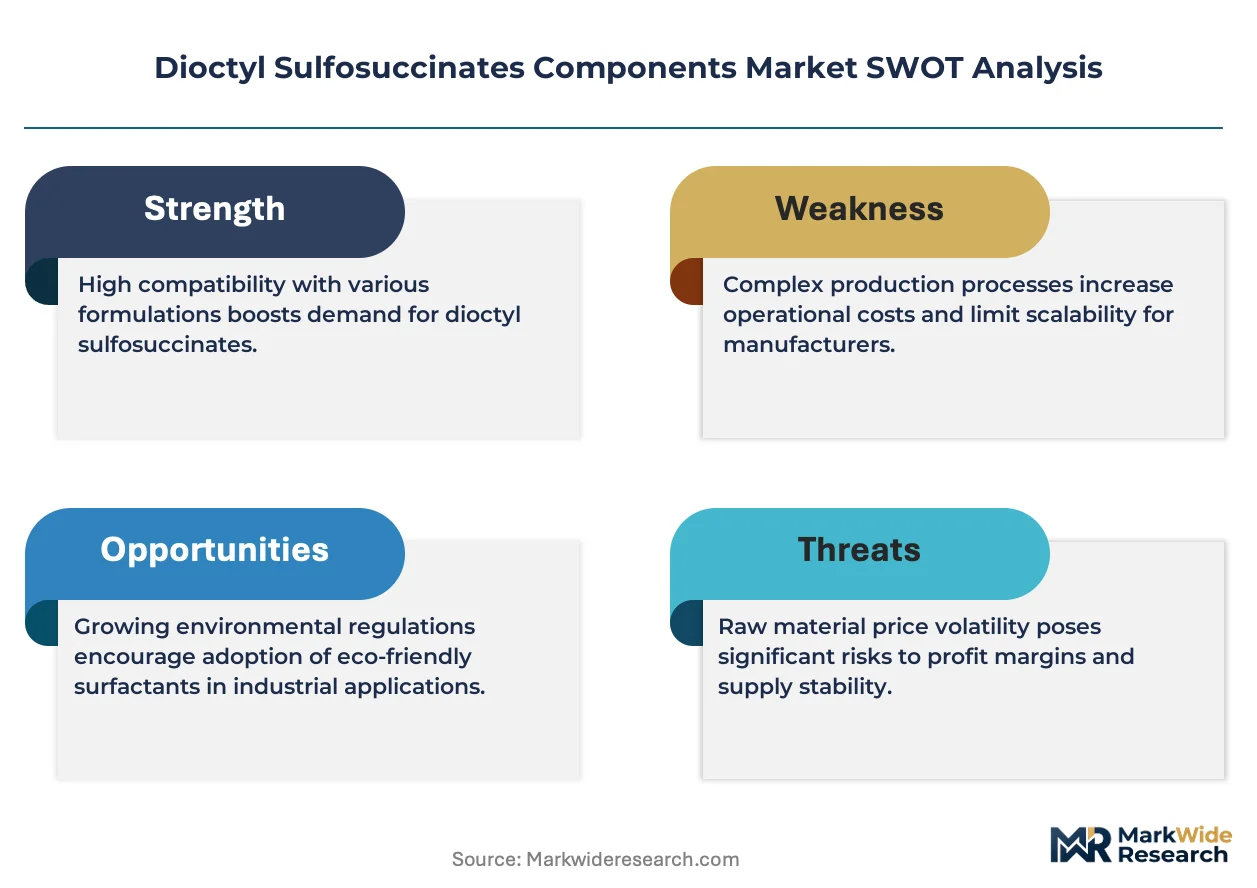
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on USP-NF certification tier and volume scale, with excipient-grade batches commanding multiples over industrial wetting-agent baselines. Cost compression in standard surfactant tiers is intensifying because enzymatic esterification pilots in Germany are collapsing purity premiums that solvent-based incumbents once captured. Agrochemical blenders in France exhibit highest price sensitivity; ophthalmic formulation developers in India show least.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculus for pharmaceutical-grade material. Production gravity centers on Germany, China, and India, with feedstock supply drawing from maleic anhydride corridors in Houston-Gulf Coast and Ludwigshafen. Raw material dependencies rest on C8-C10 fatty alcohols, maleic anhydride, and sulfonation reagents. Distribution runs through Rotterdam and Singapore hub-and-spoke networks serving regional formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern tied to pharmaceutical capital expenditure cycles, with CDSCO's accelerated approval pathways for complex generics now driving the upswing phase.
For Market Incumbents: Insulate excipient-grade margin pools by deepening backward integration into bio-based fatty alcohol feedstocks before enzymatic process patents consolidate. Preempt fluorosurfactant substitution threats in coatings segments by qualifying food-contact certified dispersant grades for can coating applications. Hydrogenation capacity scarcity among Swiss and German toll manufacturers creates defensive moats for qualified batch suppliers. For New Entrants and Emerging Players: Hyderabad and Ahmedabad pharmaceutical corridors present underpenetrated demand for USP-NF compliant sulfosuccinates, with local qualification programs lagging import volumes. Target CDSCO inspection-aligned documentation capabilities as the go-to-market wedge, bundling real-time release testing with raw material traceability to displace detained Chinese shipments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded batch reactor assets in Western Europe. Mid-term viability hinges on enzymatic process licensing revenue streams replacing commodity surfactant volume erosion. Watch for ECHA authorization sunset dates on ethoxylated alkylphenols as inflection signals for sulfosuccinate substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Licensing | Technology transfer agreements collapse capital barriers for new entrants while raising incumbent purity thresholds. |
| Backward Integration into Fatty Alcohols | Palm kernel and coconut oil feedstock control secures mass-balance certification for European personal care procurement. |
| Continuous-Flow Retrofitting | Microreactor modules in Jiangsu province cut sulfonation reaction times from hours to minutes. |
| Multijurisdictional Excipient Certification | Simultaneous USP-NF, EP, and JP compliance opens Hyderabad and Ahmedabad generic drug corridors. |
| Food-Contact Grade Qualification | EPA VOC compliance positions sulfosuccinate dispersants for solvent-borne coating substitution in can coatings. |
Methodological Framework
Desk research of customs trade data, SEC 10-K chemical segment disclosures, and ECHA REACH dossier filings preceded structured interviews with plant managers at specialty chemical manufacturers, procurement leads at agrochemical blenders, technical R&D directors, and distribution channel partners across Rotterdam and Singapore hubs. Bottom-up volume estimates triangulated against top-down value projections derived from feedstock cost structures and certification tier premiums.
Assumptions held maleic anhydride price volatility within historical bands and regulatory substitution timelines per ECHA's published restriction roadmaps. The analytical framework segmented by product grade tier, end-use industry, and regional production hub across the analysis window. CAGRs derived from elasticity-adjusted demand curves for pharmaceutical excipient versus industrial surfactant applications, incorporating hydrogenation capacity utilization rates and enzymatic process adoption curves as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed specialty chemical producers or accelerated ECHA authorization sunsets would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Naphthalene Sulfonate Market
Surfactants
Specialty Surfactants Market
Surfactants
Wax Emulsion Market
Surfactants
Asia Pacific Surfactants Market
Surfactants
Sodium Cocoyl Isethionate Market
Surfactants
Sodium Lauryl Sulphate Market
Surfactants
Dodecanol Market
Surfactants
Alkyl Polyglucoside (APG) Surfactant Market
Surfactants
Bitumen Emulsifier Market
Surfactants
Global Biosurfactant Market
Surfactants
Superwetting Surfactants Market
Surfactants
Global Silicone Surfactants Market
Surfactants
Tetradecyl Chloride Market
Surfactants
Cocamide Monoethanolamine Market
Surfactants
Global Oilfield Surfactants Market
Surfactants
Sodium Naphthalene Sulphonate Formaldehyde Market