
 Global Surfactants Market | 2026-2036
Global Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surfactants Market Outlook
ISO 17025 laboratory accreditation is collapsing as a baseline requirement for surfactant suppliers serving European personal care and household cleaning formulators. BASF SE leverages its integrated ethylene oxide and fatty alcohol backbone to control raw material quality from cracker to finished surfactant. Evonik Industries AG specializes in high-purity quaternary ammonium compounds for industrial disinfection, sustaining premium positioning through cationic technology leadership. Stepan Company anchors North American supply with alkylbenzene sulfonate capacity, competing on scale in the anionic segment for laundry applications.
Surfactants are amphiphilic compounds containing hydrophilic head groups and hydrophobic tail structures that reduce interfacial tension between immiscible phases, typically manufactured through sulfonation, ethoxylation, or enzymatic glycosylation processes depending on target performance. Their primary commercial purpose spans detergency, emulsification, wetting, and foaming across formulated consumer and industrial products. The anionic segment dominates volume in household cleaning applications where cost-efficient foam generation matters, while nonionic surfactants command margin pools in personal care and agrochemical emulsions due to superior mildness and low-temperature performance. Bio-based technology remains the fastest-growing category as brand owners and formulators respond to renewable carbon mandates and consumer preference shifts away from petrochemical derivatives.
REACH registration requirements and the EU Green Deal's biodegradability benchmarks shape product development cycles, forcing reformulation of legacy alkylphenol ethoxylates and branched alkylbenzene derivatives. EPA Safer Choice labeling in the United States and China's GB standards for aquatic toxicity further fragment compliance obligations across supply chains. India's BIS quality certification and FSSAI contact-surface approvals add emerging-market regulatory complexity for multinational suppliers. Stakeholders must monitor feedstock volatility in palm kernel and coconut oil markets while positioning R&D investment toward enzymatic and fermentation-derived surfactant platforms that satisfy tightening multi-jurisdictional environmental standards.
Market Dynamics
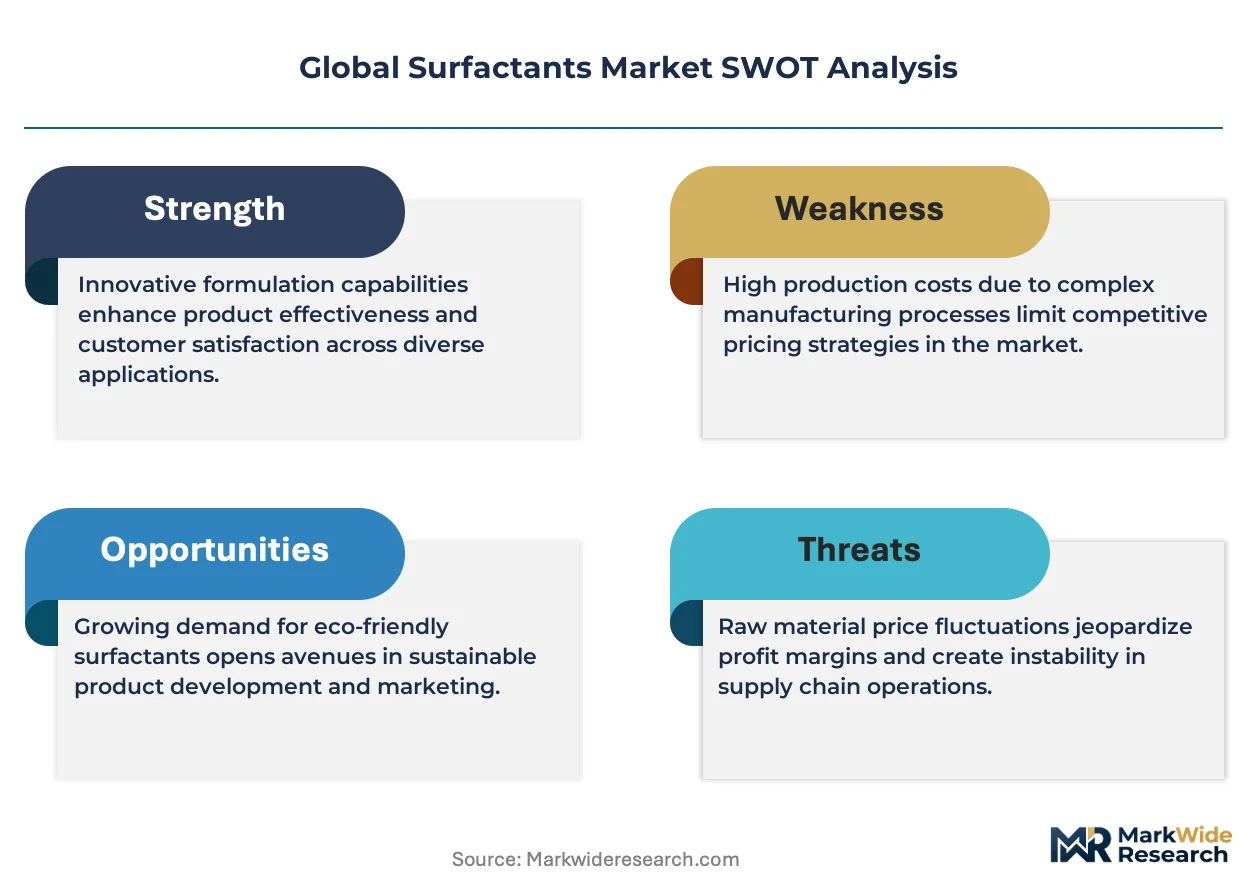
The Global Surfactants Market is undergoing a fundamental restructuring as REACH and the EU Green Deal's biodegradability mandates force formulators to abandon legacy petrochemical feedstocks. This regulatory compression is redirecting capital toward enzymatic production platforms and renewable oleochemical supply chains, reshaping competitive advantage around carbon intensity rather than unit economics alone.
Growth Catalysts
- REACH registration tiers:The EU's escalating data requirements for surfactant dossiers are accelerating phase-out of alkylphenol ethoxylates. Formulators are reformulating with alkyl polyglucosides to maintain market access.
- FMCG rural distribution:India's expanding consumer goods networks are pulling volume demand for anionic laundry surfactants into tier-3 and tier-4 cities.
- Enzymatic glycosylation:Biotechnology platforms using carbohydrate feedstocks are achieving cost parity with ethoxylation for mild personal care applications.
Market Restraints
- Palm kernel oil volatility:Lauryl alcohol price swings tied to Indonesian export duties compress margins for sulfate producers.
- Ethylene oxide supply concentration:US Gulf Coast cracker reliability issues create bottleneck risk for ethoxylate manufacturers.
- Aquatic toxicity testing:China's GB standards for surface water contamination extend product registration timelines by 12-18 months.
Strategic Opportunities
- EPA Safer Choice labeling:The US federal procurement preference creates premium positioning for bio-based anionic surfactants in institutional cleaning contracts.
- Agrochemical emulsion demand:Nonionic surfactants with low-temperature performance are capturing share in precision agriculture formulations.
- India BIS certification gaps:Domestic laboratory capacity shortages create first-mover advantage for accredited multinational suppliers.
Industry Challenges
- ISO 17025 accreditation timelines:European formulators now demand certified analytical support, stretching supplier quality infrastructure.
- Multi-jurisdictional dossier management:Concurrent compliance with REACH, EPA Safer Choice, and China's MEE notification requirements fragments regulatory resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surfactants Market |
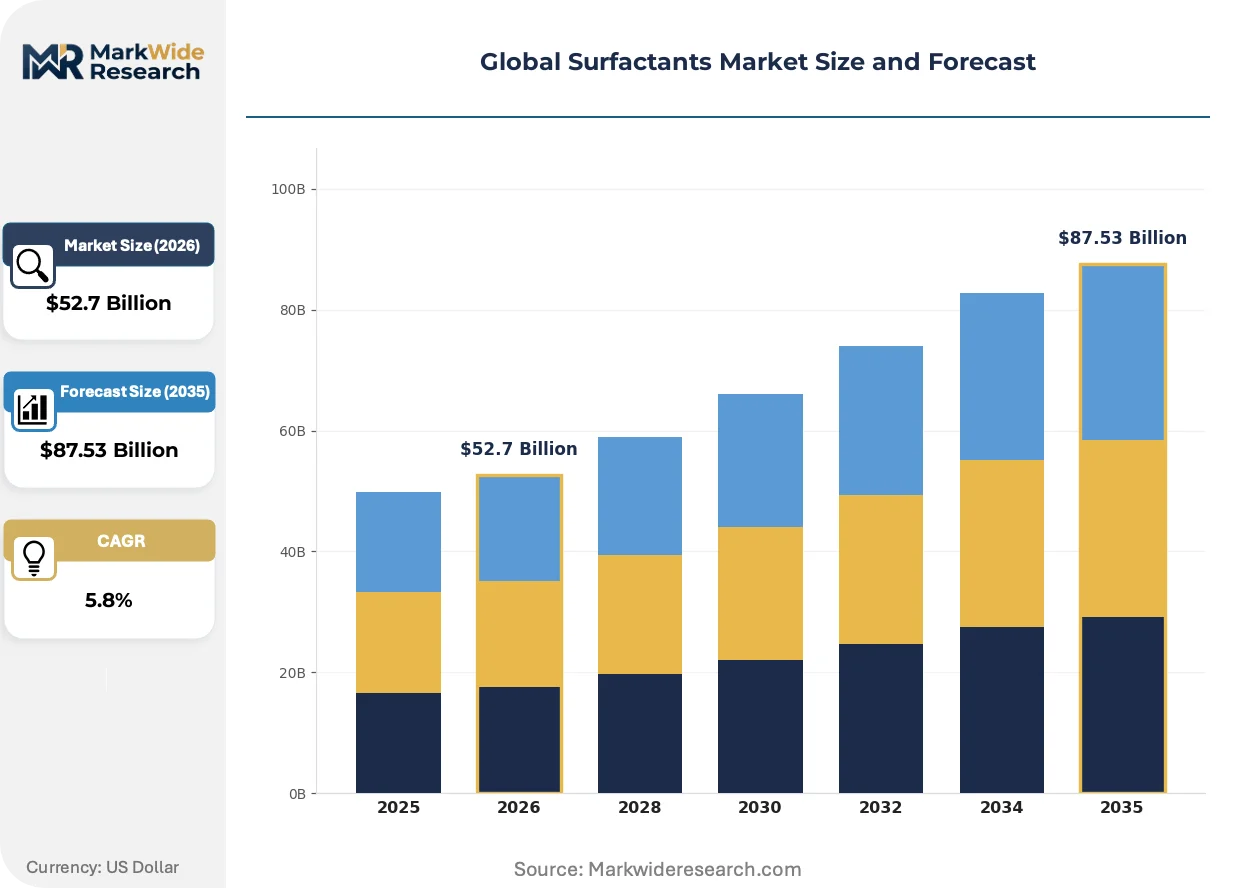
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $87.53 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anionic, Cationic, Nonionic, Amphoteric End Use Industry: Personal Care, Household Cleaning, Oil & Gas, Agriculture Form: Liquid, Powder, Granular, Solid Technology: Bio-based, Synthetic, Surfactant Blends, Others |
| Companies Covered | BASF SE, Evonik Industries AG, Stepan Company, Kao Corporation, Clariant AG, Nouryon, Solvay, Croda International Plc, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surfactants Market Strategic Shifts
Formulation science is pivoting from performance-maximizing chemistries toward compliance-optimized molecular architectures. This shift is compressing development cycles while elevating the strategic value of regulatory intelligence and feedstock traceability systems.
Fermentation-derived rhamnolipid biosurfactants are supplanting synthetic anionics in high-margin personal care segments. L'Oréal and Unilever procurement teams have accelerated qualification timelines for these glycolipid alternatives. The technology is enabling formulators to eliminate ethylene oxide entirely from sensitive skin product lines while maintaining foam stability.
The EU Green Deal's Chemicals Strategy for Sustainability is tightening biodegradability thresholds for surfactants entering European waterways. Industrial laundries and institutional cleaning contractors face reformulation deadlines that invalidate legacy branched alkylbenzene sulfonate inventories. German and Dutch formulators are responding fastest, with pilot-scale alkyl polyglucoside substitution already operational in commercial dishwashing concentrates.
Brand-owner procurement teams are consolidating surfactant supplier panels around cradle-to-gate carbon disclosure capabilities. Tier-1 personal care manufacturers now require Scope 3 emissions data as a mandatory bid qualification criterion. This behavioral shift is most visible in Nordic markets, where Orkla and Essity have implemented supplier scorecards weighting renewable carbon content above historical price-performance metrics.
Global Surfactants Market Segmentation
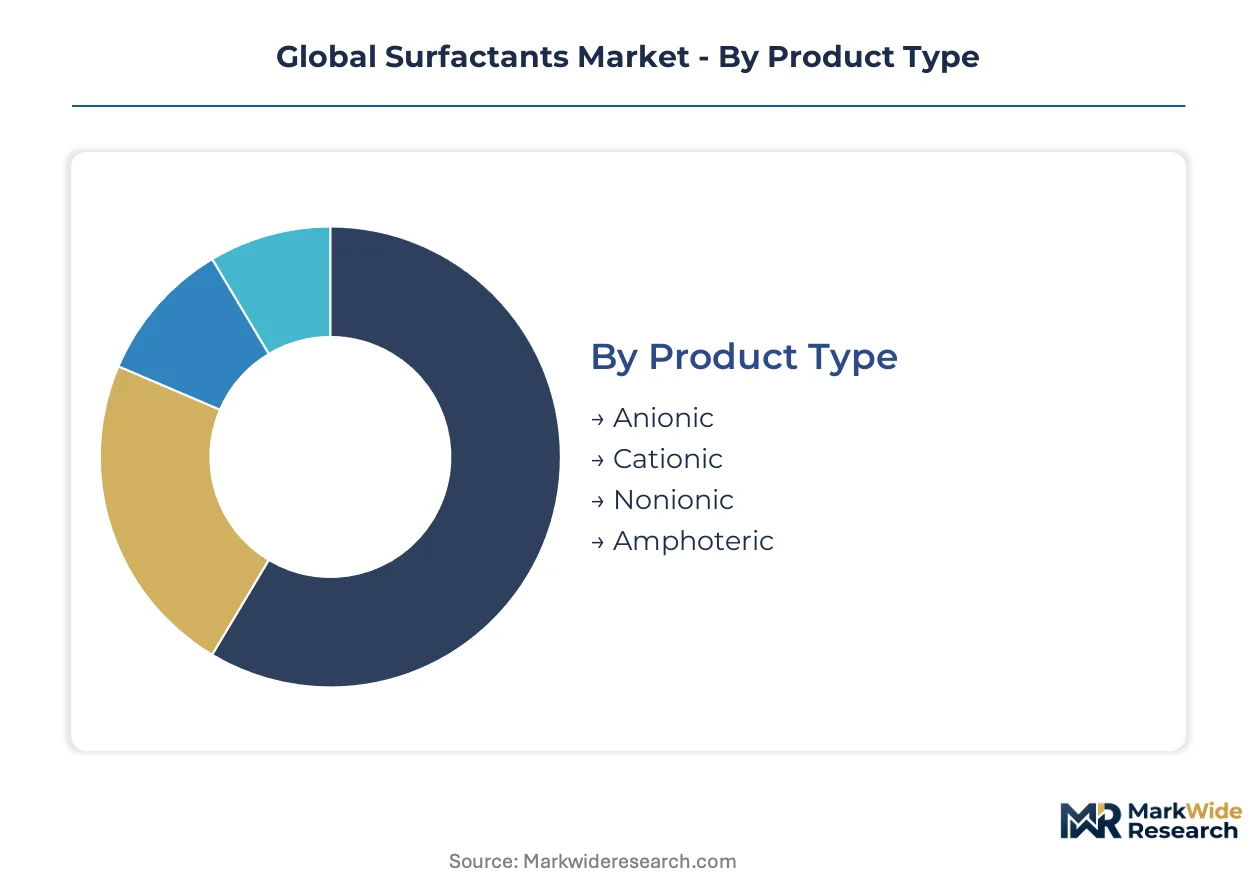
Segmentation reveals how regulatory pressure and feedstock economics concentrate margin pools across distinct molecular architectures. Suppliers must align production assets with the specific compliance burdens and performance premiums governing each category.
Product Type:
Anionic and cationic segments face acute substitution pressure as REACH biodegradability mandates invalidate legacy branched-chain chemistries, while amphoteric compounds capture premium positioning through mildness certification.
- Anionic:Sulfate and sulfonate head groups dominate laundry and dishwashing formulations where foam generation and cost efficiency matter. Demand concentrates in India's tier-3 and tier-4 cities as FMCG distribution penetrates rural markets, though palm kernel oil volatility squeezes lauryl alcohol margins for sulfate producers.
- Nonionic:Ethoxylated fatty alcohols and alkylphenol derivatives serve personal care emulsions and agrochemical formulations with superior low-temperature performance. European formulators are accelerating phase-out of alkylphenol ethoxylates under EU Green Deal timelines, redirecting procurement toward alkyl polyglucoside alternatives.
- Cationic:Quaternary ammonium compounds deliver antimicrobial efficacy for industrial disinfection and fabric softening applications.
- Amphoteric:Amphoacetates and betaines provide pH-responsive mildness for sensitive skin personal care lines, qualifying for Nordic ecolabels.
Anionic surfactants anchor the volume base while amphoteric compounds gain share at the steepest rate.
End Use Industry:
Application-driven cost tiers separate commodity contract cleaners from premium personal care formulations, with regulatory intensity escalating fastest in consumer-facing segments.
- Personal Care:Shampoos, body washes, and facial cleansers demand mildness certification and renewable carbon disclosure. L'Oréal and Unilever procurement teams now require Scope 3 emissions data as mandatory bid qualification, elevating fermentation-derived biosurfactants in supplier evaluations.
- Household Cleaning:Laundry detergents and surface cleaners prioritize unit economics and foam stability over molecular sophistication. India's BIS quality certification gaps create first-mover advantage for accredited multinational suppliers as domestic laboratory capacity remains constrained.
- Oil & Gas:Demulsifiers and corrosion inhibitors tolerate higher toxicity profiles in upstream extraction applications.
- Agriculture:Pesticide emulsions and adjuvants rely on nonionic surfactants for low-temperature field performance.
Household cleaning commands the largest volume position while personal care delivers the highest margin expansion trajectory.
Form:
Physical state determines logistics economics and formulation flexibility, with liquid concentrates capturing share in automated dosing systems.
- Liquid:Pumpable concentrates enable just-in-time manufacturing for contract formulators and automated laundry dosing equipment. German and Dutch institutional cleaning contractors have operationalized pilot-scale alkyl polyglucoside concentrates ahead of EU reformulation deadlines.
- Powder:Spray-dried granules serve emerging markets with limited cold-chain infrastructure and price-sensitive consumers.
- Granular:Free-flowing particles suit automated dishwashing and industrial laundry bulk handling systems.
- Solid:Compressed bars and tablets address zero-waste retail positioning and reduced packaging mandates.
Powder formulations retain volume leadership in developing economies while liquid concentrates climb fastest in premium European and North American channels.
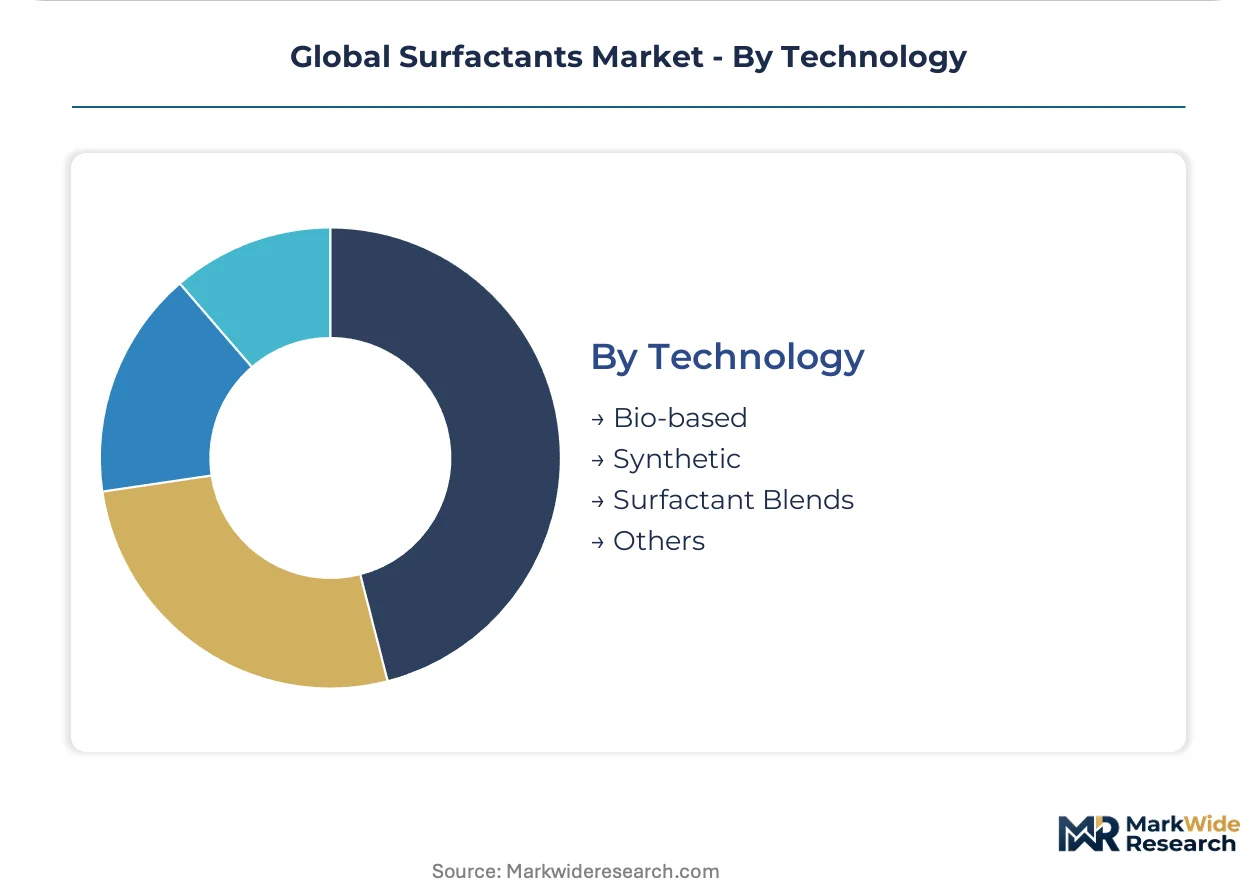
Technology:
Feedstock provenance increasingly stratifies competitive positioning as brand owners implement renewable carbon mandates across supplier scorecards.
- Bio-based:Enzymatic glycosylation and fermentation platforms convert carbohydrate and oleochemical feedstocks into rhamnolipids and alkyl polyglucosides. EPA Safer Choice labeling creates premium positioning for bio-based anionics in US federal procurement contracts.
- Synthetic:Petrochemical ethoxylation and sulfonation retain cost advantage in commodity laundry applications where biodegradability thresholds remain less stringent.
- Surfactant Blends:Co-formulated anionic-nonionic systems optimize performance-cost ratios for specific application requirements.
- Others:Novel architectures including silicone surfactants and fluorinated compounds serve specialty industrial niches.
Synthetic technology maintains the installed production base while bio-based platforms expand most quickly as enzymatic glycosylation achieves cost parity with conventional ethoxylation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulators in India, Germany, the United States, China, and Brazil concentrate procurement decisions that redirect global surfactant trade flows. These five markets generate divergent demand profiles shaped by regulatory stringency, feedstock access, and end-use industry maturity.
India
Rural FMCG distribution networks and tier-3 city expansion drive volume consumption of anionic laundry surfactants. FSSAI contact-surface approvals and BIS quality certification requirements constrain supplier qualification timelines. Gujarat and Maharashtra industrial corridors host the largest concentration of domestic sulfonation capacity serving household cleaning formulators.
Germany
Industrial laundries and institutional cleaning contractors face accelerated EU Green Deal reformulation deadlines for branched alkylbenzene derivatives. REACH registration tiers and ECHA biodegradability benchmarks invalidate legacy petrochemical feedstocks. The Ruhr industrial cluster and North Rhine-Westphalia chemical parks anchor alkyl polyglucoside pilot production for commercial dishwashing concentrates.
United States
EPA Safer Choice labeling creates federal procurement preference for bio-based anionics in institutional cleaning contracts. OSHA workplace exposure standards and state-level aquatic toxicity regulations fragment compliance obligations. Gulf Coast ethylene oxide production concentration generates bottleneck risk for ethoxylate manufacturers serving personal care formulators.
China
GB standards for surface water contamination extend surfactant product registration timelines by 12-18 months, compressing formulation development cycles. MEE notification requirements and dual carbon goals redirect investment toward enzymatic glycosylation platforms. Yangtze River Delta chemical parks concentrate nonionic surfactant capacity for agrochemical emulsion exports.
Brazil
Palm kernel oil import dependence and lauryl alcohol price volatility squeeze margins for sulfate producers serving Latin American household cleaning markets. ANVISA cosmetic ingredient regulations and state-level environmental licensing create multi-layered compliance complexity. São Paulo industrial suburbs host the largest concentration of regional sulfonation capacity for laundry detergent supply.
Global Surfactants Market Competitive Environment
Player mix skews toward integrated petrochemical conglomerates with captive ethylene oxide supply, specialized oleochemical processors with backward integration into tropical oil refining, and biotechnology platforms leveraging fermentation-derived biosurfactant architectures. Strategic archetypes separate around feedstock control depth, regulatory dossier breadth, and carbon disclosure sophistication. Dominant competitive moves include portfolio diversification into alkyl polyglucoside alternatives and geographic expansion into Indian BIS certification gaps.
Among European-based integrated suppliers, BASF SE and Evonik Industries AG exemplify divergent specialization vectors within the same regulatory jurisdiction. BASF SE represents the integrated petrochemical archetype with captive ethylene oxide and fatty alcohol backbone control. Evonik Industries AG occupies a position within the high-purity cationic segment for industrial disinfection applications. Stepan Company anchors North American supply dynamics as a representative of scale-driven anionic production for laundry applications.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Stepan Company |
| Kao Corporation |
| Clariant AG |
| Nouryon |
| Solvay |
| Croda International Plc |
| Dow Inc. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day ethylene oxide inventory cycles at Gulf Coast crackers concentrate pricing power among integrated producers with captive ethylene supply, while spot buyers in alkylbenzene sulfonate chains absorb volatility from Indonesian palm kernel oil export duties. This inventory-lead asymmetry rewards backward integration into fatty alcohol production and punishes merchant sulfonate processors without oleochemical refining assets.
Pricing Analysis
Cost-plus contracts with Malaysian palm kernel oil indexation dominate lauryl sulfate procurement, separating premium-grade amphoterics with Nordic ecolabel certification from standard-tier alkylbenzene sulfonates and economy dishwashing concentrates. Price differentiation rests on REACH dossier completeness and ISO 17025 laboratory accreditation status. Cost compression in standard-tier anionics is intensifying because Indian BIS certification gaps attract low-cost regional sulfonation capacity. Household cleaning formulators in tier-3 Indian cities exhibit highest price sensitivity, while L'Oréal and Unilever procurement teams demonstrate lowest sensitivity due to Scope 3 carbon disclosure mandates.
Supply Chain Analysis
Strait of Malacca transit vulnerability for Southeast Asian oleochemical shipments concentrates supply risk for European ethoxylate manufacturers dependent on lauryl alcohol feedstocks. Manufacturing gravity centers on Germany, India, and China, with Germany anchoring alkyl polyglucoside pilot production, India hosting sulfonation corridors in Gujarat and Maharashtra, and China concentrating nonionic capacity in Yangtze River Delta chemical parks. Raw material flows draw from Indonesian palm kernel plantations, US Gulf Coast ethylene crackers, and Brazilian soybean oil refining. Single-source vulnerability in ethylene oxide supply creates bottleneck exposure for merchant ethoxylators. Distribution runs through bulk liquid tank terminals serving automated laundry dosing systems in institutional cleaning and drum packaging for rural FMCG distribution in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surfactants market functions as a regulatory-entrenchment defensive moat, where REACH registration dossiers and ECHA biodegradability benchmarks create decade-long switching costs that protect incumbents with established compliance infrastructure.
For Market Incumbents: Consolidate alkyl polyglucoside capacity additions in North Rhine-Westphalia chemical parks ahead of EU Green Deal reformulation deadlines. Deepen upstream control over palm kernel oil refining through offtake agreements with Indonesian plantation groups to defend margin position against lauryl alcohol price volatility. Threat: fermentation-derived rhamnolipid biosurfactants from biotechnology platforms.
For New Entrants and Emerging Players: Anchor in India's BIS certification gaps where domestic laboratory capacity shortages delay qualification timelines for multinational suppliers. Target tier-3 and tier-4 city FMCG distribution networks with accredited anionic surfactant supply. Go-to-market angle: EPA Safer Choice pre-certification for US federal procurement eligibility.
For Investors and Strategic Acquirers: Long-term, this sits as a feedstock-control play because carbon disclosure mandates and renewable carbon scoring are elevating oleochemical refining assets above commodity sulfonation capacity. Acquisition target archetype: enzymatic glycosylation platforms with carbohydrate feedstock flexibility. Signal to watch: L'Oréal and Unilever procurement teams accelerating fermentation-derived biosurfactant qualification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Alcohol Production | Captive lauryl alcohol supply insulates BASF and Kao from Indonesian export duty volatility. |
| Enzymatic Glycosylation Platform Investment | Fermentation-derived alkyl polyglucosides satisfy EU Green Deal biodegradability thresholds without ethylene oxide. |
| EPA Safer Choice Pre-Certification | Federal procurement preference unlocks institutional cleaning contracts with premium positioning for bio-based anionics. |
| India BIS Laboratory Accreditation | First-mover qualification in domestic certification gaps captures rural FMCG distribution expansion. |
| Scope 3 Carbon Disclosure Infrastructure | Cradle-to-gate emissions data satisfies Nordic brand-owner procurement scorecards at Orkla and Essity. |
Study Parameters
The analysis maps anionic, nonionic, cationic, and amphoteric surfactant segments, each validated through procurement directors at L'Oréal and Unilever, sulfonation plant managers in Gujarat, and EPA Safer Choice program officers. Primary fieldwork combined with secondary validation against ECHA REACH registration databases, USITC trade flow records, and BIS certification registries. Bottom-up capacity modeling triangulated against top-down FMCG consumption forecasts.
Consistency checks validated volume and value outputs against ACC and Cefic chemical industry benchmarks across the projection horizon. Segmentation dimensions modeled include surfactant class, end-use industry, feedstock technology, and regional regulatory cluster. CAGRs derived from ethoxylate capacity utilization rates and enzymatic glycosylation cost-parity trajectories. Forecast inputs incorporated palm kernel oil price band scenarios and REACH registration tier escalation timelines.
Material uncertainties — feedstock volatility in tropical oleochemical markets, cracker reliability disruptions on the US Gulf Coast, and MEE notification delays in China — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and brand-owner carbon disclosure adoption curves. Practitioners should keep alternative scenarios live as EU Green Deal implementation timelines and Indian BIS laboratory capacity expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Global Low Foam Surfactants Market
Surfactants
Amino Acid Surfactants Market
Surfactants
Global Sodium Lauryl Ether Sulfate [SLES] Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Global Methyl Ester Sulfonate Market
Surfactants
Green Surfactants Market
Surfactants
Lauramide DEA Market
Surfactants
Global Amphoteric Surfactants Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
Oil-in-Water Anionic Emulsifier Market
Surfactants
Amino Silicone Oil Market
Surfactants
Sugar-Based Surfactants Market
Surfactants
Polyoxyethylene Sorbitan Tristearate Market
Surfactants
Emulsifying Wax Market
Surfactants
North America Non-Ionic Surfactants Market
Surfactants
Procream Market