
 Scotch Whisky Market | 2026-2036
Scotch Whisky Market Size, Share, and Industry Trends Forecast 2026-2036
Scotch Whisky Market Intelligence
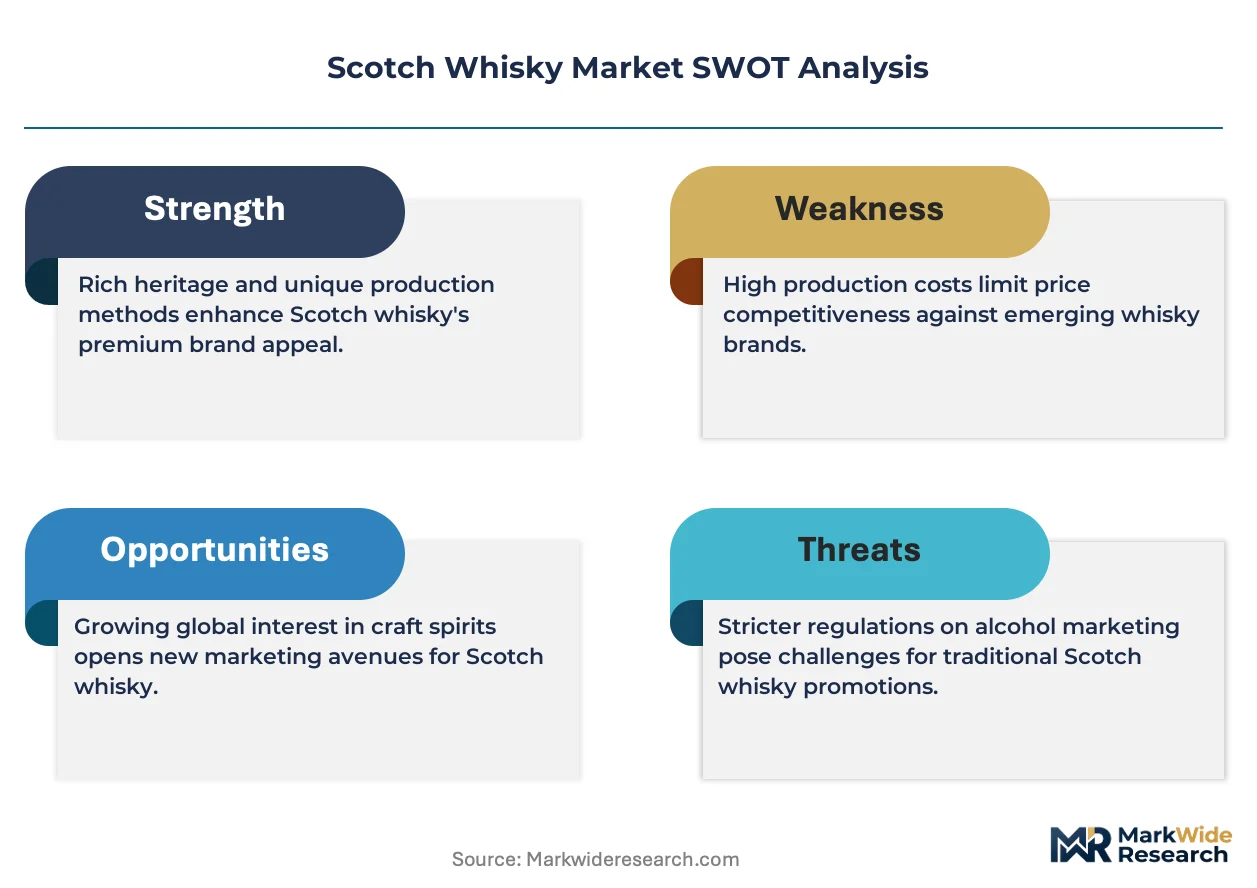
Capital-intensity divergence between large-scale distillers and boutique operators is redrawing competitive boundaries across the category. Diageo leverages its vast warehousing infrastructure and global distribution network to sustain volume leadership in blended Scotch. William Grant & Sons anchors its position through dedicated single malt capacity at Glenfiddich and Balvenie, competing on aged-stock depth that smaller rivals cannot replicate.
Scotch whisky denotes malt or grain whisky distilled and matured in Scotland for a minimum of three years in oak casks, governed by strict geographic and production protocols that preserve its protected status. The spirit serves as a premium beverage for direct consumption, cocktail formulation, and collectible investment across hospitality and retail channels. Single malt commands the deepest margin pools due to constrained production cycles and provenance premiums, while no-age-statement releases attract younger demographics seeking accessible entry points. Blended Scotch dominates total volume through mass-market distribution, though grain whisky is gaining traction as a base for innovative flavor-forward expressions.
The Scotch Whisky Association enforces production standards, while the UK Food Standards Agency monitors labeling compliance and the US Alcohol and Tobacco Tax and Trade Bureau governs import classification and tax stamping. These frameworks shape market access costs, age-statement verification requirements, and export documentation burdens that influence pricing architecture. Stakeholders must track evolving sustainability mandates around glass weight reduction and carbon disclosure, as regulatory pressure on packaging and emissions intensifies scrutiny across the value chain.
Market Dynamics
Maturation stock scarcity is compressing competitive timelines across the Scotch whisky value chain, forcing distillers to choose between volume expansion and aged-statement preservation while warehousing costs escalate in Scotland's Central Belt.
Growth Catalysts
- The Scotch Whisky Regulations 2009:Geographic origin mandates and three-year minimum maturation requirements protect category integrity against counterfeit imports, reinforcing price premiums in the United States and Asian duty-free corridors.
- Single malt cask programs:Direct-to-consumer barrel ownership schemes are bypassing traditional wholesale channels, capturing collector capital from Singapore and London private wealth segments.
- Grain whisky innovation:Distillers are deploying continuous column still modifications to produce lighter, cocktail-forward base spirits that expand mixology applications in New York and Tokyo hospitality venues.
Market Restraints
- Oak cask supply concentration:American white oak cooperage capacity concentrates in Kentucky and Missouri, exposing maturation programs to lumber tariff volatility and extended lead times for first-fill bourbon barrels.
- Three-year statutory minimum:The United Kingdom's maturation floor prevents rapid inventory turnover, locking working capital in unsaleable stock for emerging distillers without legacy warehousing assets.
- Spirits substitution:Japanese whisky and American single malt are capturing shelf space in California and Texas retail, eroding Scotch's historical dominance in premium brown spirits allocation.
Strategic Opportunities
- Climate-adaptive warehousing:Coastal Highland and Island maturation sites are attracting investment for temperature-stressed aging profiles that differentiate flavor signatures from Central Belt production.
- Low-ABV and no-alcohol adjacent:Distillers are deploying spent-grain valorization and flavor extraction technologies to enter the premium mixer category without diluting core equity.
- Digital provenance verification:Blockchain-secured cask registries are emerging as a trust infrastructure for secondary market trading, reducing authentication friction for auction houses in Edinburgh and Hong Kong.
Industry Challenges
- Master distiller succession pipelines:The concentration of nosing and blending expertise among aging specialists in Speyside and Islay creates retention risk as retirement cycles accelerate.
- Legacy system integration:Centuries-old dunnage warehouses lack IoT monitoring infrastructure, complicating real-time cask quality tracking for insurers and export documentation authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scotch Whisky Market |
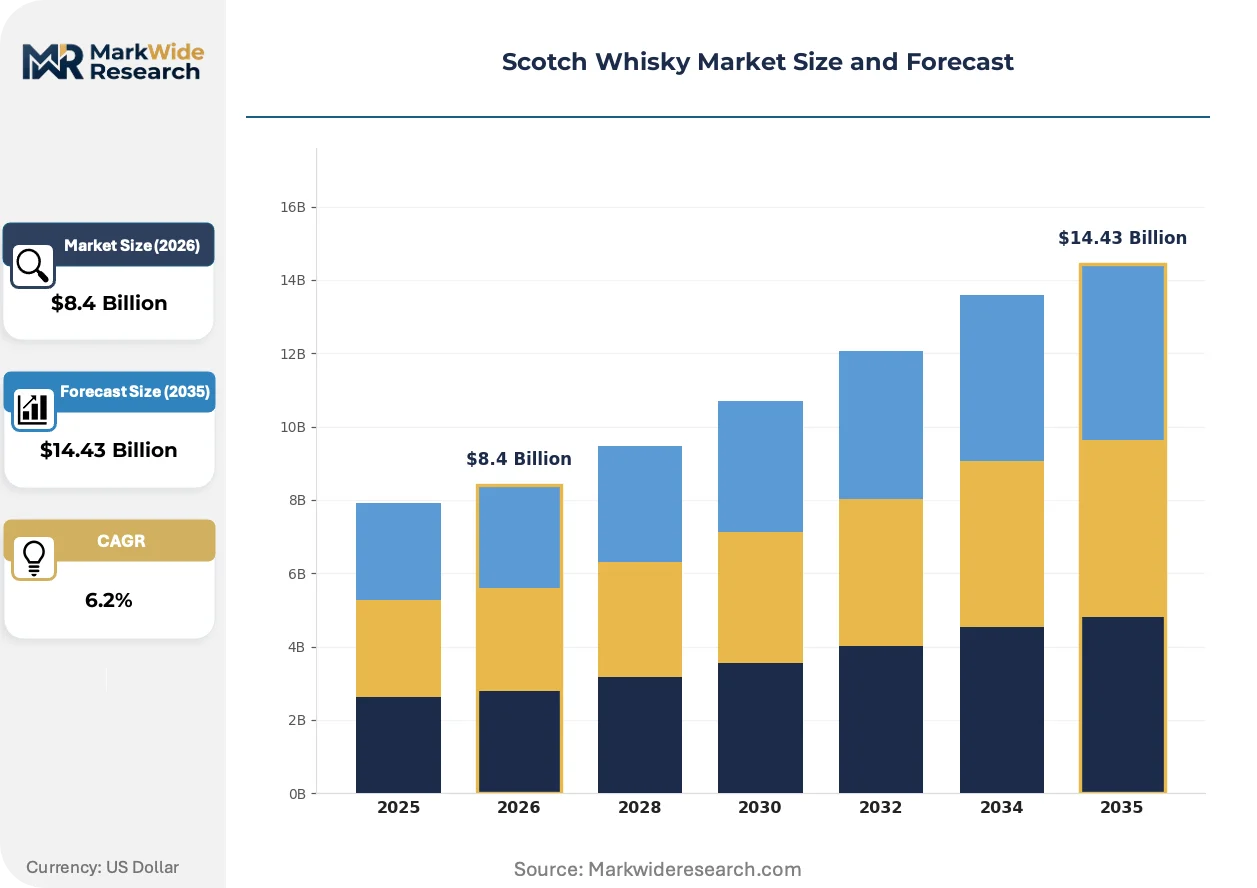
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single Malt, Blended Scotch, Grain Whisky, Cask Strength Age: 12 Years, 18 Years, 21 Years, No Age Statement Packaging Type: Standard Bottle, Gift Box, Miniature, Eco-Friendly Flavor Profile: Smoky, Fruity, Spicy, Floral |
| Companies Covered | William Grant & Sons, La Martiniquaise-Bardinet, Diageo, Whyte & Mackay, Marie Brizard Wine & Spirits, Pernod Ricard, Edrington Group, Ian Macleod Distillers, Bacardi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scotch Whisky Market Strategic Shifts & Innovations
Active cask management technologies and maturation acceleration research are reshaping how distillers balance inventory velocity against heritage claims, while regulatory transparency mandates force disclosure of production methods previously treated as proprietary.
Hyperspectral imaging systems for non-invasive cask monitoring are displacing traditional periodic sampling protocols that required breach and volume loss. Mid-sized distilleries in Campbeltown and the Lowlands are piloting these installations to reduce evaporation uncertainty and optimize racking decisions. The technology is compressing quality-assurance cycles from quarterly to continuous, enabling earlier intervention in at-risk inventory.
The UK Food Standards Agency is mandating enhanced allergen labeling and origin verification for export certification, adding documentation layers to each cask transfer and bottling run. Distillers must now maintain chain-of-custody records spanning grain sourcing through final packaging, with audit trails subject to third-party verification. Smaller operators without dedicated compliance staff are outsourcing these functions to specialized logistics providers, altering cost structures for boutique production.
Collector behavior is rotating from age-statement accumulation toward limited-release scarcity hunting, with buyers prioritizing cask strength and single-cask exclusivity over standardized 12-year or 18-year expressions. Auction volumes in Glasgow and online platforms are shifting toward one-off distillery exclusives and collaborative finishes. This pattern concentrates margin capture with original producers rather than secondary traders, rewarding direct-to-consumer relationship investments.
Scotch Whisky Market Segmentation
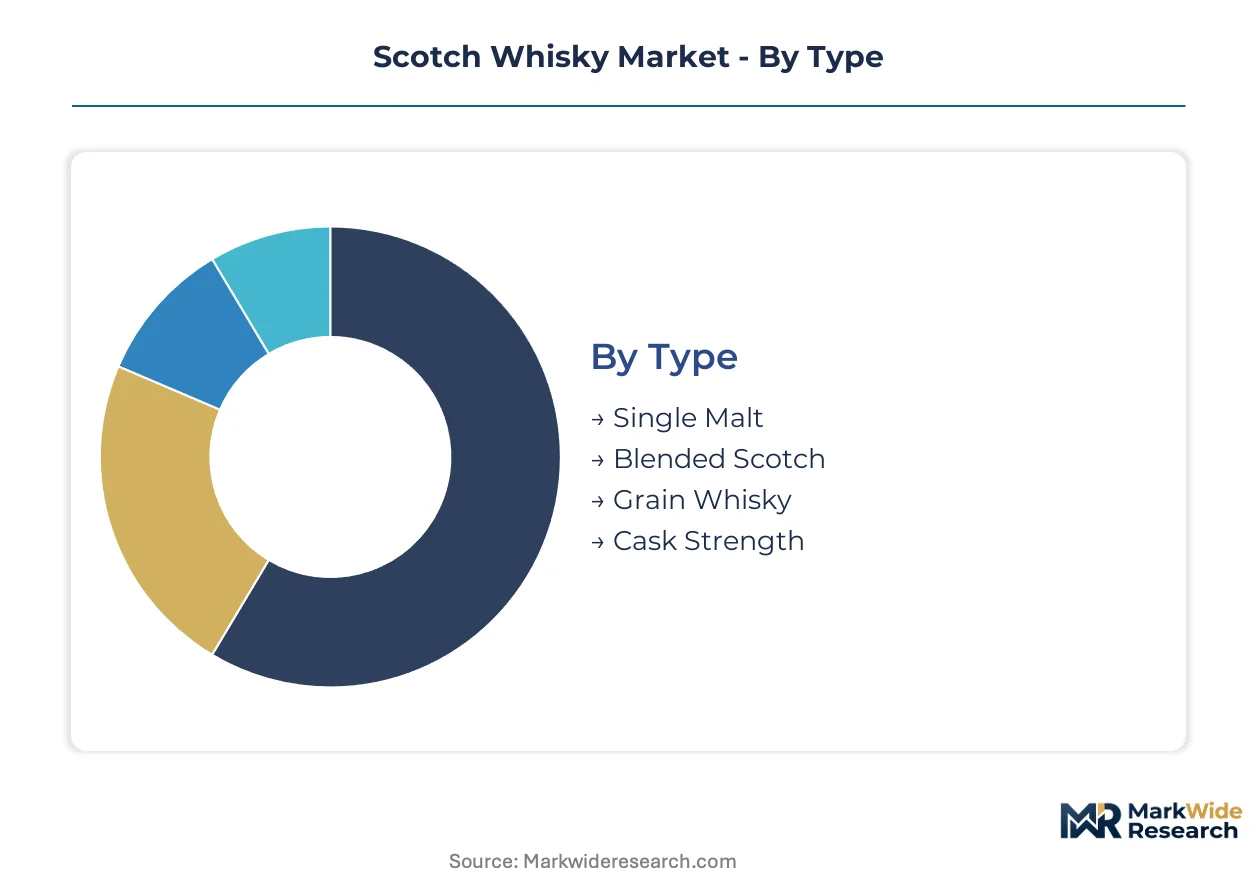
Scotch whisky segmentation reveals distinct margin architectures and channel strategies across type, age, packaging, and flavor dimensions. Each category carries specific regulatory, inventory, and consumer-behavior implications that shape producer resource allocation.
Type:
Channel distribution varies sharply by type, with single malt concentrating in specialist retail and direct-to-consumer platforms while blended Scotch dominates mass-market grocery and duty-free corridors.
- Single Malt:Produced from 100% malted barley at a single distillery, this category commands the deepest price premiums due to constrained pot-still capacity and extended maturation cycles. Demand concentrates in the United States and Singapore, where collectors prioritize aged-statement expressions and distillery-exclusive releases.
- Blended Scotch:Combines malt and grain whiskies from multiple distilleries, enabling volume consistency and accessible price positioning. This segment flows through supermarket chains and airline retail, with Diageo and Pernod Ricard sustaining global distribution dominance through heritage brand equity.
- Grain Whisky:Continuous column still production yields lighter, higher-proof spirit suited for cocktail-forward applications. Bartenders in New York and Tokyo are driving renewed interest as a base for highball and stirred-drink formulations.
- Cask Strength:Bottled without dilution, typically exceeding 50% ABV, appealing to enthusiasts seeking unaltered maturation character. Specialist retailers and auction houses in Edinburgh and Hong Kong handle the majority of volume.
Blended Scotch dominates installed base. Single malt is where expansion concentrates.
Age:
Inventory carrying costs escalate non-linearly with age statement, creating tiered working capital requirements that favor established distillers with legacy warehousing assets.
- 12 Years:The standard entry point for premium positioning, balancing accessibility with provenance credibility. This segment anchors supermarket premium shelves and corporate gifting programs across the United Kingdom and United States.
- 18 Years:Marks the threshold for serious collector attention, with distillers allocating limited stocks to maintain scarcity premiums. Duty-free operators in Heathrow and Changi prioritize these expressions for high-margin retail.
- 21 Years:Ultra-premium positioning reserved for milestone releases and limited editions. Specialist retailers in London and private wealth clients in Asia drive allocation decisions.
- No Age Statement:Flexibility in blending allows distillers to deploy younger stocks creatively, targeting millennials and Gen Z consumers through accessible price points and experimental cask finishes.
12-year expressions dominate installed base. No-age-statement releases are expanding most quickly.
Packaging Type:
Sustainability mandates from UK regulators and retail buyers are reshaping material specifications and cost structures across primary and secondary packaging.
- Standard Bottle:The volume workhorse across all price tiers, with glass weight reduction initiatives responding to carbon disclosure requirements from the Scotch Whisky Association.
- Gift Box:Rigid board and premium finishing elevate perceived value for holiday and corporate purchasing. Asian markets particularly demand elaborate presentation packaging for lunar new year gifting.
- Miniature:5cl and 10cl formats serve airline sampling, hotel minibars, and trial conversion in travel retail. Production complexity limits participation to larger bottling operations.
- Eco-Friendly:Recycled glass, reduced-label designs, and plastic-free closures address ESG reporting requirements from UK supermarkets and export markets.
Standard bottles dominate installed base. Eco-friendly formats are where expansion concentrates.
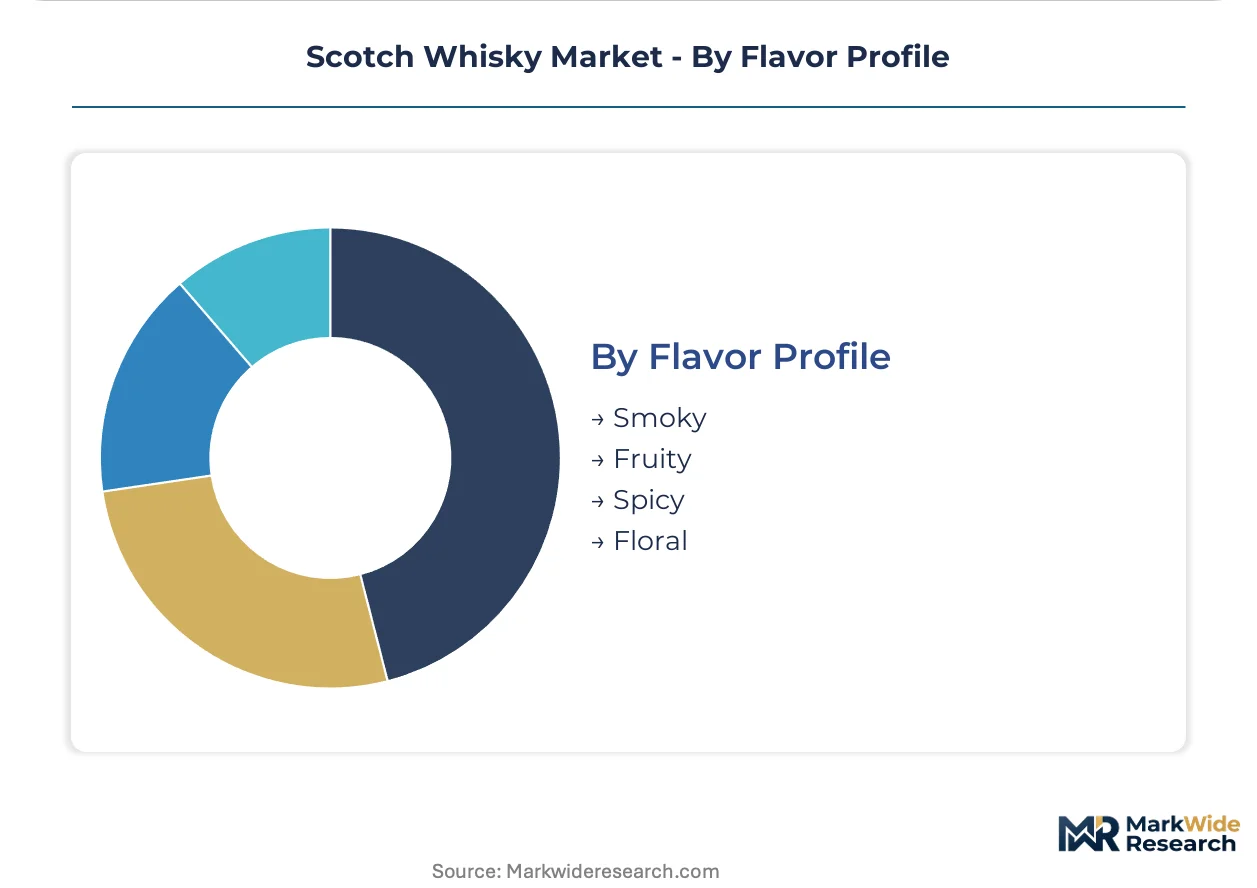
Flavor Profile:
Regional distilling traditions produce distinct organoleptic signatures that guide consumer navigation and mixology application across on-trade and off-trade channels.
- Smoky:Peated malt from Islay distilleries delivers medicinal, maritime phenolic character. Bartenders in London and New York deploy these for bold cocktail formulations that command premium pricing.
- Fruity:Sherry-cask maturation in Speyside yields dried fruit and nut profiles accessible to entry-level consumers. This profile anchors blended Scotch formulations targeting mass-market palates.
- Spicy:Rye-cask finishes and high-rye grain bills introduce cinnamon and pepper notes. Experimental releases from Lowland distillers are gaining traction in craft cocktail bars.
- Floral:Light, grassy character associated with Lowland and some Highland production, suited for highball service and warm-weather consumption. Japanese whisky competition is strongest in this profile space.
Smoky and fruity profiles dominate installed base. Spicy and floral expressions are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets: the United States prioritizes aged-statement single malts for collector portfolios, while Asian markets favor prestige gifting formats and Europe sustains steady blended Scotch volume through supermarket channels.
United States
Private wealth collectors in California and Texas drive allocation priority for 18-year and 21-year expressions, with distributors maintaining waitlists for limited releases. The Alcohol and Tobacco Tax and Trade Bureau governs import classification, age-statement verification, and federal excise tax stamping that shapes pricing architecture. New York City hospitality venues anchor single malt program expansion, deploying cask-strength offerings in premium cocktail formulations.
United Kingdom
Domestic consumption concentrates in supermarket blended Scotch for everyday occasions, while Edinburgh and Glasgow auction houses handle secondary market trading for rare single casks. The Scotch Whisky Regulations 2009 enforce geographic origin, three-year minimum maturation, and labeling standards that protect category integrity. Speyside distilleries cluster around Elgin and Dufftown, where legacy warehousing assets enable extended stock aging that emerging producers cannot replicate.
Japan
Bartenders in Tokyo and Osaka deploy Scotch in highball and stirred-drink formulations, with grain whisky gaining traction as a cocktail-forward base spirit. The National Tax Agency monitors import volumes and tariff classifications, while METI oversees food labeling standards for premium spirits. Osaka's upscale hospitality district sustains dedicated single malt programs that compete directly with domestic Japanese whisky allocations.
Singapore
Duty-free operators at Changi Airport prioritize 18-year expressions for high-margin retail, while private wealth segments participate in direct-to-consumer cask ownership schemes. The country's national food regulator enforces import documentation and origin verification requirements that add compliance layers to each shipment. Raffles Place and Marina Bay hospitality venues anchor Southeast Asia's most concentrated single malt program expansion.
France
Blended Scotch dominates supermarket and hypermarket channels for everyday consumption, while Paris specialist retailers handle limited-release allocations for enthusiast collectors. ANSM monitors labeling compliance for allergen disclosure and origin verification on export-bound shipments. The Île-de-France region concentrates specialist retail and hospitality demand, with bartenders in the Marais district experimenting with grain whisky bases for cocktail innovation.
Scotch Whisky Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with ownership concentration in family-held and publicly traded spirits conglomerates defining competitive boundaries. The upper tier commands global distribution networks and century-old warehousing infrastructure, while mid-sized distillers compete on single malt provenance and limited-release scarcity. Strategic archetypes span volume-integrated multinationals, family-held single malt specialists, and boutique craft operators. Competitive moves concentrate on aged-stock acquisition and direct-to-consumer channel development.
Among family-held specialists, William Grant & Sons and Ian Macleod Distillers occupy positions anchored by dedicated single malt capacity and legacy distillery assets. Diageo represents the integrated multinational archetype, leveraging warehousing scale and global route-to-market infrastructure. These three entities exemplify the tiered structure: independent family ownership against publicly traded volume leadership, each deploying distinct inventory and channel strategies.
| Leading Market Players |
|---|
| William Grant & Sons |
| La Martiniquaise-Bardinet |
| Diageo |
| Whyte & Mackay |
| Marie Brizard Wine & Spirits |
| Pernod Ricard |
| Edrington Group |
| Ian Macleod Distillers |
| Bacardi |
| Others |
Cost & Logistics Intelligence
Legacy warehousing infrastructure in Speyside and Islay creates insurmountable scale economies for aged-stock holders, compressing price floors for emerging distillers while concentrating margin capture among established operators with century-old dunnage assets.
Pricing Analysis
Direct-to-consumer cask ownership programs now drive lifetime value beyond initial bottle sales, with collectors in Singapore and London paying premiums for exclusive barrel access. Three-tier pricing structure across premium, standard, and economy levels separates 21-year single malts from 12-year expressions and no-age-statement releases. Cost compression in grain whisky is intensifying because continuous still operators compete on volume against pot-still malt producers. Corporate gifting programs in Asia show least price sensitivity, while millennial entry-level buyers in the United States demand accessible positioning.
Supply Chain Analysis
Inventory lead times extending beyond the statutory three-year minimum lock working capital in unsaleable stock, favoring distillers with legacy warehousing over new market entrants. American white oak cooperage concentrates in Kentucky and Missouri, while Scottish maturation sites cluster in the Central Belt and coastal Highlands. First-fill bourbon barrels, malted barley from Scottish growers, and glass packaging from European suppliers constitute critical input dependencies. Single-source vulnerability runs through American oak supply given lumber tariff exposure. Distribution runs through specialist retail in Edinburgh and London, duty-free corridors at Heathrow and Changi, and direct-to-consumer platforms for cask programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital provenance infrastructure and cask-registry interoperability are transforming Scotch whisky into a platform economy where blockchain-secured ownership records enable fractional trading and secondary market liquidity previously impossible.
For Market Incumbents: Secure master distiller succession pipelines through structured apprenticeship programs in Speyside and Islay, where nosing expertise concentrates among aging specialists approaching retirement. Defend aged-stock depth by acquiring distressed warehousing assets from emerging distillers unable to carry three-year inventory burdens. Vertical integration into American oak cooperage mitigates tariff exposure on first-fill bourbon barrel supply. For New Entrants and Emerging Players: Lead with climate-adaptive warehousing narratives in coastal Highland and Island sites, where temperature-stressed aging profiles differentiate flavor signatures from Central Belt production. Grain whisky innovation for cocktail-forward applications in New York and Tokyo represents the most penetrable white space. Direct-to-consumer cask ownership schemes bypass wholesale margin compression and capture collector capital from private wealth segments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among distillers with established direct-to-consumer cask programs and digital provenance infrastructure. Five-to-ten-year viability favors operators with dedicated single malt capacity and legacy warehousing assets rather than blended Scotch volume players facing spirits substitution pressure. Watch auction volume shifts from age-statement accumulation toward limited-release scarcity hunting as the inflection indicator for margin migration.| Strategic Initiative | Industry Significance |
|---|---|
| Climate-Adaptive Warehousing Investment | Coastal Highland maturation sites differentiate flavor profiles from Central Belt production for premium positioning. |
| Blockchain Cask Registry Deployment | Edinburgh and Hong Kong auction houses reduce authentication friction through digital provenance verification infrastructure. |
| Grain Whisky Continuous Still Modification | Tokyo and New York bartenders adopt lighter base spirits for highball and stirred-drink formulations. |
| Direct-to-Consumer Cask Ownership Program | Singapore and London private wealth segments bypass traditional wholesale channels for exclusive barrel access. |
| Master Distiller Succession Pipeline | Speyside and Islay retention programs address concentration risk as aging specialists approach retirement cycles. |
Research Approach
A spread of perspectives from master distillers, warehousing operations managers, specialist retail buyers, and auction house specialists converged on the working assumptions driving inventory and pricing dynamics. Primary fieldwork combined structured interviews with distillery leadership and secondary validation through Scotch Whisky Association production statistics, UK Food Standards Agency labeling compliance records, US Alcohol and Tobacco Tax and Trade Bureau import classifications, and customs documentation from Singapore and Japanese regulators. Bottom-up cask-level inventory tracking and top-down category revenue analysis provided triangulation across data sources.
Segmentation dimensions modeled include whisky type, age statement tier, packaging format, flavor profile, and regional consumption pattern across the analysis window. CAGRs were derived from historical volume trajectories and projected demand elasticity by collector segment and hospitality channel. Specific forecast inputs encompass maturation stock scarcity timelines, American white oak supply constraints, and spirits substitution rates from Japanese whisky and American single malt.
Forecasts assume regulatory continuity in the United Kingdom's Scotch Whisky Regulations 2009, the US TTB classification framework, and Japan's National Tax Agency import monitoring; material policy shifts would require re-modeling of age-statement verification requirements and export documentation burdens. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Coffee Beer Market
Alcoholic Beverages
Craft Spirits Market
Alcoholic Beverages
Instant Wine Chillers and Refreshers Market
Alcoholic Beverages
Beer Bottle Market
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market
Alcoholic Beverages
Crystal Malt Market
Alcoholic Beverages
Fruit Brandy Market
Alcoholic Beverages
Asia-Pacific Alcohol E-Commerce Market
Alcoholic Beverages
Wine Destemmer Market
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
South America Wine Market
Alcoholic Beverages
Beer Pasteurization Equipment Market
Alcoholic Beverages
Alcoholic Beverages Market
Alcoholic Beverages
Wine Filtering Machine Market
Alcoholic Beverages
Alcoholic Drinks Market