
 South America Wine Market | 2026-2036
South America Wine Market Size, Share, and Industry Trends Forecast 2026-2036
South America Wine Market Analytics
The South America wine market is restructuring around a sharp divergence between premium estate-bottled offerings and commodity bulk wine, with altitude-designated vineyards and single-varietal labels commanding fundamentally different margin structures than undifferentiated blending stock. Bodega Catena Zapata leverages its high-altitude Mendoza estates to sustain price premiums in export channels. Viña Concha y Toro anchors its portfolio through mass-market consistency while competing in super-premium segments through its Don Melchor label.
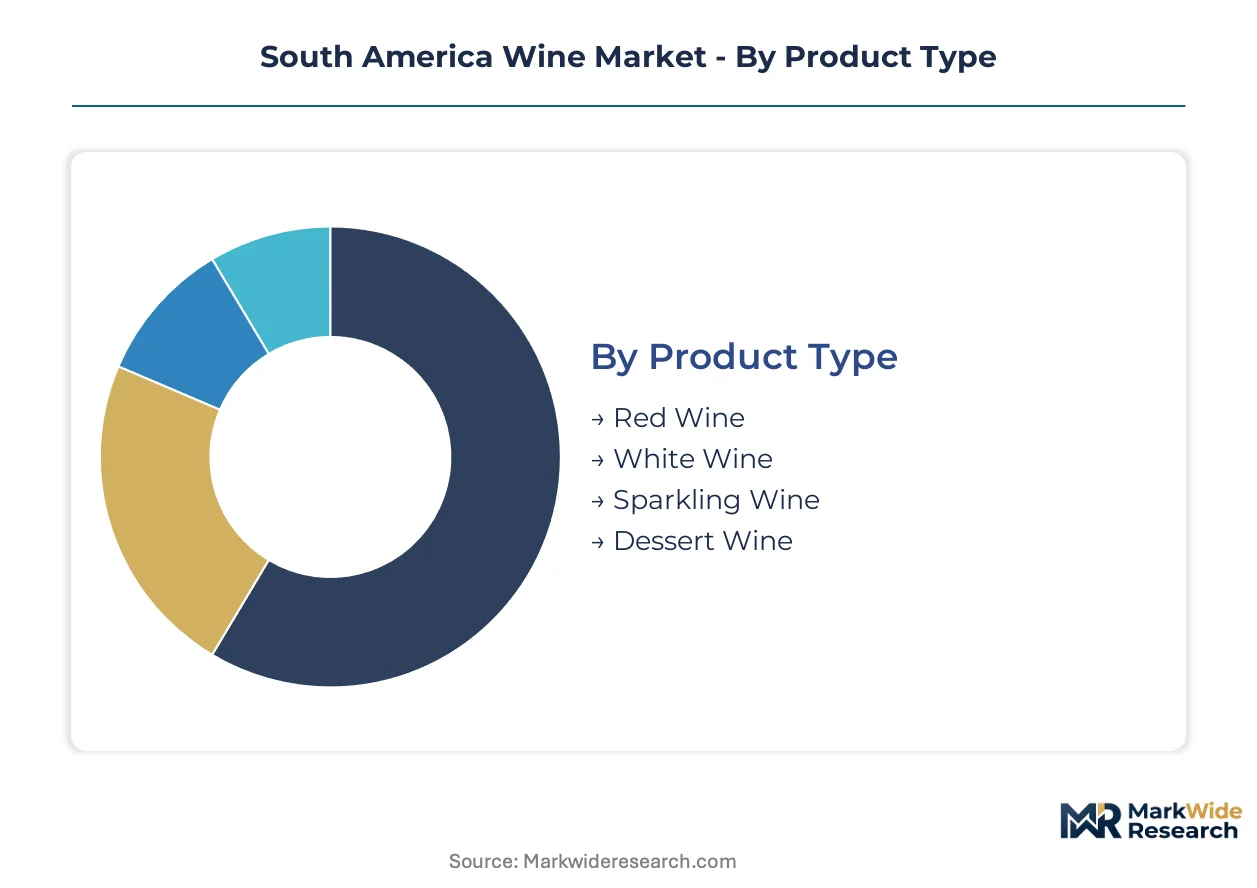
South American wine comprises fermented grape beverages typically bottled at 11-15% alcohol by volume, produced through controlled yeast fermentation of Vitis vinifera varieties followed by aging in stainless steel or oak vessels, serving both gastronomic accompaniment and standalone consumption purposes. Red wine occupies the largest volume share across the region, yet sparkling wine generates disproportionate margin growth as Brazilian and Colombian consumers expand celebratory consumption. The price tier dimension reveals economy and premium segments as mature volume pools, while super-premium and luxury categories concentrate export value and distributor attention.
ANVISA governs additive thresholds and labeling standards in Brazil, while Chile's Ministry of Agriculture enforces denomination-of-origin protocols that shape export market access for Maipo and Colchagua Valley producers. Argentina's Instituto Nacional de Vitivinicultura regulates harvest declarations and geographic indications, directly influencing how Bodega Norton and Grupo Penaflor position regional provenance in international markets. Stakeholders must monitor how evolving Mercosur technical standards harmonize—or fragment—cross-border certification requirements for organic and biodynamic claims.
Market Dynamics
The South America wine market is restructuring around altitude-designated terroir differentiation, with producers in Mendoza's Uco Valley and Chile's Maipo Valley capturing pricing power through single-vineyard bottlings while bulk wine margins compress.
Growth Catalysts
- ANVISA additive disclosure mandates:Brazil's tighter labeling rules are pushing producers toward cleaner formulations, creating first-mover advantages for estates already minimizing sulfur and synthetic inputs.
- Tourism rebound in Buenos Aires and Santiago:Premium hotel and restaurant channels are expanding wine list depth, directly lifting on-premise consumption of super-premium labels.
- Sparkling wine production techniques:Traditional method adoption in Brazilian Serra Gaúcha is displacing charmat-process volume, commanding higher per-bottle yields in domestic and export channels.
Market Restraints
- Glass and cork input volatility:Energy-intensive bottle manufacturing costs fluctuate with natural gas pricing, compressing margins for mid-tier producers unable to pass through increases.
- Water access concentration in Mendoza:Andean snowpack variability restricts irrigation allocation, creating vintage-to-vintage supply uncertainty for high-altitude estates dependent on drip systems.
- Import substitution in neighboring markets:Peruvian and Colombian consumers increasingly access duty-free Chilean bulk wine, eroding Argentina's historical price-positioning in those corridors.
Strategic Opportunities
- Colombia's underpenetrated retail channel:Modern grocery expansion in Bogotá and Medellín creates shelf space for Argentine and Chilean premium labels previously locked out by spirits dominance.
- Organic certification tailwinds:Argentina's Instituto Nacional de Vitivinicultura is streamlining organic conversion timelines, reducing the three-year transition burden for estates pivoting from conventional viticulture.
- E-commerce direct-to-consumer convergence: Subscription platforms and winery-owned digital channels are bypassing traditional distributor markups in Brazilian and Argentine metropolitan markets.
Industry Challenges
- Enologist talent scarcity in emerging regions:Brazil's Serra Gaúcha lacks sufficient trained viticulturists to support quality scaling as sparkling production accelerates.
- Geographic indication compliance timelines:Producers seeking Maipo Valley or Uco Valley designation face multi-year documentation requirements that delay export market entry.
- Oak barrel capex intensity:French and American cooperage costs require substantial upfront investment, straining mid-size estates competing in the super-premium segment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Wine Market |
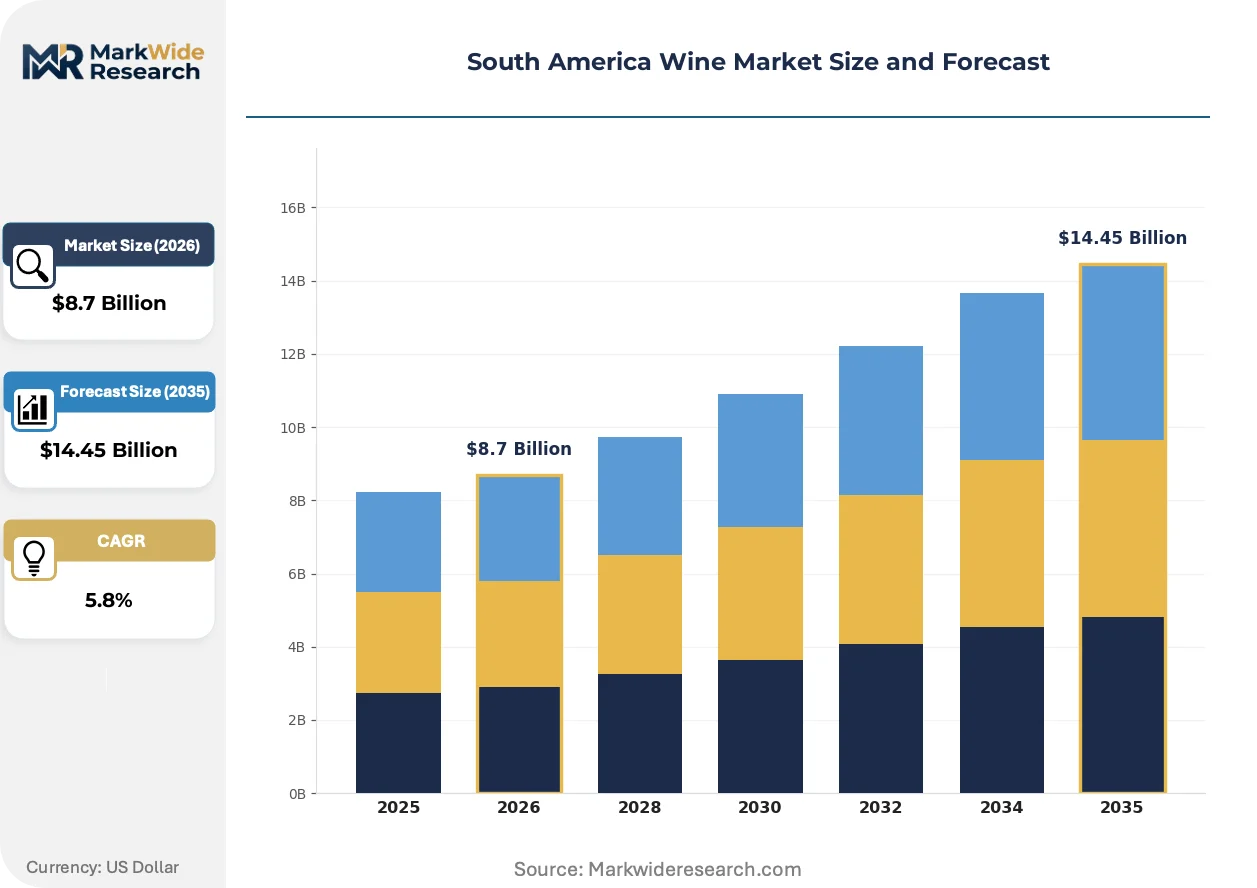
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Wine, White Wine, Sparkling Wine, Dessert Wine End User: Restaurants, Retailers, Distributors, Direct Consumers Packaging Type: Bottles, Tetra Packs, Kegs, Cans Price Tier: Economy, Premium, Super Premium, Luxury |
| Companies Covered | Bodega Catena Zapata, The Miolo Wine Group, Viña Concha y Toro, Bodega Norton, Bodegas Esmeralda, Grupo Penaflor, VSPT Wine Group, Errazuriz Winery, Viña Santa Rita, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Wine Market Evolving Landscape
Precision viticulture and regenerative farming are reshaping how South American estates manage canopy and soil health, with technology adoption fastest among altitude-focused producers seeking differentiation.
Electrical conductivity mapping combined with drone-mounted multispectral imaging is electrifying vineyard management decisions. High-altitude estates in Mendoza's Uco Valley deploy these systems to optimize irrigation block-by-block. The technology compresses the gap between empirical observation and targeted intervention, reducing water use while concentrating fruit quality.
ANVISA's evolving additive threshold standards are forcing reformulation across Brazilian import portfolios. The regulator's 2024 disclosure expansion requires quantitative labeling of stabilizers and fining agents. Premium Argentine exporters are responding by certifying additive-free production lines specifically for the Brazilian market, creating parallel SKUs that command shelf-space premiums.
On-premise buyer concentration is consolidating wine list decision-making in São Paulo and Buenos Aires. Large hospitality groups now centralize beverage procurement, displacing independent sommelier autonomy with data-driven category management. This shift is most visible in Brazilian fine-dining chains, where single-supplier agreements lock out smaller estates lacking volume scale or distributor leverage.
South America Wine Market Segmentation
Wine consumption patterns across South America fragment sharply by occasion, channel, and consumer sophistication. Producers must align portfolio depth with how each segment sources, consumes, and trades up within the category.
Product Type:
Upgrade cycles vary dramatically by color and style, with sparkling wine showing the steepest trade-up velocity as Brazilian and Colombian consumers expand celebratory occasions.
- Red Wine:Malbec-dominant blends from Mendoza's Uco Valley and Maipo Valley Cabernet Sauvignon anchor volume production. Argentine bodegas and Chilean estates compete for shelf space in São Paulo supermarkets and Bogotá retail chains, with altitude designation increasingly required for placement.
- Sparkling Wine:Traditional method production in Brazil's Serra Gaúcha displaces charmat-process volume as ANVISA disclosure rules favor cleaner-label offerings. Brazilian consumers trade up from entry-level Brazilian sparklers to Argentine and Chilean imports during holiday seasons.
- White Wine:Torrontés from Salta and Sauvignon Blanc from Chile's Casablanca Valley serve warm-climate refreshment demand. Coastal vineyard sourcing commands modest premiums in Brazilian coastal cities.
- Dessert Wine:Late-harvest offerings and fortified styles occupy niche gifting occasions in Buenos Aires and Santiago, with minimal export traction.
Volume placements concentrate in Red Wine; the faster expansion belongs to Sparkling Wine.
End User:
Channel concentration shapes margin capture, with hospitality procurement centralization favoring scale suppliers while direct channels reward estate differentiation.
- Restaurants:Premium hotel and independent dining channels in Buenos Aires, Santiago, and São Paulo expand wine list depth as tourism rebounds. Large Brazilian hospitality groups now centralize beverage procurement, locking out smaller estates lacking distributor leverage.
- Direct Consumers:Subscription platforms and winery-owned digital channels bypass traditional markups in Brazilian and Argentine metropolitan markets. E-commerce convergence enables altitude-designated estates to capture full retail margin.
- Retailers:Modern grocery expansion in Bogotá and Medellín creates shelf space for premium labels previously excluded by spirits dominance. Chilean supermarket chains anchor volume through private-label agreements.
- Distributors:Consolidated import portfolios in Brazil face ANVISA reformulation requirements, pushing additive-free SKUs that command shelf-space premiums.
Margin capture concentrates in Direct Consumers; the steepest volume expansion trajectory runs through Restaurants.
Packaging Type:
Format selection tracks consumption occasion and channel economics, with alternative packaging gaining traction where convenience outweighs ritual.
- Bottles:Standard 750ml glass remains mandatory for super-premium and luxury tiers, with Bordeaux and Burgundy shapes signaling provenance in export channels. Energy-intensive manufacturing costs fluctuate with natural gas pricing, compressing mid-tier margins.
- Cans:Single-serve aluminum formats penetrate Brazilian beach and outdoor occasions, displacing entry-level glass for informal consumption. Argentine producers pilot can lines specifically for Brazilian summer markets.
- Tetra Packs:Aseptic cartons dominate economy-tier household consumption in Argentine and Chilean supermarkets, with minimal export relevance.
- Kegs:On-premise draft systems reduce packaging waste for high-volume Brazilian restaurant chains, though wine-specific infrastructure remains limited outside São Paulo.
Standard placements concentrate in Bottles; packaging innovation gains share fastest in Cans.
Price Tier:
Consumer trading patterns stratify the market into distinct margin pools, with super-premium and luxury tiers concentrating export value despite smaller volumes.
- Premium:Single-varietal estate bottlings from Mendoza's Uco Valley and Maipo Valley command consistent placement in modern retail and independent restaurants. Altitude designation and geographic indication compliance increasingly gate access to this tier.
- Super Premium:Single-vineyard expressions and reserve classifications capture distributor attention in export markets, with French oak barrel aging required for competitive positioning. Oak cooperage costs strain mid-size estates competing here.
- Economy:Bulk wine and undifferentiated blending stock face margin compression from Peruvian and Colombian import substitution of duty-free Chilean volume. Private-label agreements dominate supermarket placement.
- Luxury:Icon wines and limited releases serve collector and gifting demand in Buenos Aires and Santiago, with minimal channel overlap with lower tiers.
Unit volume concentrates in Economy; value expansion clusters in Super Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors wine distribution infrastructure across South America, hosting consolidated import portfolios and centralized procurement for Brazilian hospitality chains. Mendoza's Uco Valley and Santiago's Maipo Valley supply the premium and super-premium tiers that flow through this commercial hub.
Argentina
Mendoza's Uco Valley estates command pricing premiums through altitude-designated terroir differentiation, with Bodega Catena Zapata restructuring vineyard investments to capture tourism rebound demand. Argentina's Instituto Nacional de Vitivinicultura regulates harvest declarations and geographic indications, directly influencing how producers position regional provenance in export markets. Buenos Aires hotels and restaurants are expanding wine list depth as international visitor volumes recover.
Brazil
Serra Gaúcha producers displace charmat-process volume with traditional method sparkling techniques, commanding higher per-bottle yields in domestic channels. ANVISA's tighter additive disclosure rules push importers toward cleaner-label formulations, creating first-mover advantages for estates minimizing sulfur inputs. São Paulo's consolidated hospitality procurement now centralizes beverage decisions for large fine-dining chains, locking out smaller estates lacking distributor leverage.
Chile
Maipo Valley Cabernet Sauvignon and Colchagua Valley estates compete for shelf space in regional export corridors, with Viña Concha y Toro anchoring portfolios through mass-market consistency. Chile's Ministry of Agriculture enforces denomination-of-origin protocols that shape export market access for premium producers. Santiago's premium hotel channels are expanding super-premium placements as tourism rebounds.
Colombia
Modern grocery expansion in Bogotá and Medellín creates shelf space for Argentine and Chilean premium labels previously excluded by spirits category dominance. The country's national food safety authority maintains import standards that favor documented geographic indication compliance. Colombian consumers increasingly access duty-free Chilean bulk wine, eroding Argentina's historical price-positioning in this corridor.
Peru
Lima's emerging retail and hospitality channels absorb growing volumes of duty-free Chilean bulk wine, pressuring Argentine export margins in the Andean corridor. Peru's national sanitary authority enforces labeling standards that align with broader regional harmonization efforts. Coastal metropolitan consumption concentrates in informal dining occasions where entry-level pricing dominates purchasing decisions.
South America Wine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across altitude-designation and single-vineyard bottling credentials, with estates in Mendoza's Uco Valley and Chile's Maipo Valley capturing fundamentally different margin structures than undifferentiated bulk wine suppliers. The market structures around three archetypes: altitude-focused estate bottlers, mass-market portfolio anchors, and diversified multi-region groups. Competitive moves concentrate on geographic indication compliance investments and direct-to-consumer channel development.
Within the altitude-focused estate tier, Bodega Catena Zapata exemplifies high-altitude Mendoza positioning, while Viña Concha y Toro anchors mass-market consistency with super-premium segment participation. Grupo Penaflor occupies a diversified multi-region position across Argentine production zones. These three represent distinct strategic postures: terroir-driven premiumization, portfolio breadth with scale efficiency, and regional diversification across multiple valleys.
| Leading Market Players |
|---|
| Bodega Catena Zapata |
| The Miolo Wine Group |
| Viña Concha y Toro |
| Bodega Norton |
| Bodegas Esmeralda |
| Grupo Penaflor |
| VSPT Wine Group |
| Errazuriz Winery |
| Viña Santa Rita |
| Others |
Value Network & Pricing Analysis
French and American oak cooperage flows from European and North American forests through Chilean and Argentine cooperages into super-premium barrel programs, with per-barrel costs stratifying final bottle pricing across Mendoza's Uco Valley and Maipo Valley estates.
Pricing Analysis
Altitude-designated terroir commands value-based pricing anchored to harvest elevation and block-specific yield concentration. Three-tier pricing structure across super-premium, premium, and economy levels separates single-vineyard Malbec from regional blends and undifferentiated bulk wine. Cost compression in economy tiers intensifies as Peruvian and Colombian buyers substitute duty-free Chilean volume for Argentine imports. Distributors in São Paulo exhibit acute price sensitivity for mid-tier placements, while collectors in Buenos Aires absorb luxury tier premiums with minimal elasticity.
Supply Chain Analysis
Glass bottle supply rests on Brazilian and Argentine manufacturing facilities vulnerable to natural gas pricing volatility. Cork bark draws from Portuguese and Spanish forests, while aluminum can feedstock sources from Brazilian smelters. Single-source vulnerability concentrates in Mendoza's drip irrigation infrastructure, where Andean snowpack variability threatens vintage-to-vintage water allocation. Distribution runs through São Paulo's consolidated import portfolios, with centralized procurement for Brazilian hospitality chains displacing fragmented channel access for smaller estates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water access constraints in Mendoza's high-altitude zones prop pricing for altitude-designated estates, creating supply-constrained conditions that favor producers with secured irrigation rights.
For Market Incumbents: Cement geographic indication compliance investments to lock Maipo Valley and Uco Valley designation ahead of multi-year documentation timelines threatening export market entry. Deepen backward integration into oak cooperage through captive barrel programs or long-term French forest contracts, defending margin position against input cost volatility. Channel control through direct-to-consumer platforms in Buenos Aires and São Paulo metropolitan markets reduces distributor markup exposure. For New Entrants and Emerging Players: Drone-mounted multispectral imaging and electrical conductivity mapping offer technology-first differentiation for precision viticulture services targeting mid-size estates lacking in-house agronomy capabilities. White-space concentration sits in Colombia's modern grocery expansion across Bogotá and Medellín, where spirits category dominance previously excluded premium Argentine and Chilean labels. Subscription platform partnerships enable bypass of São Paulo's consolidated distributor infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor altitude-designated estate archetypes in Mendoza's Uco Valley with secured water rights and existing organic certification progress. Long-term viability across the analysis window hinges on terroir differentiation durability against climate variability. Monitor ANVISA disclosure rule evolution as inflection indicator for additive-free SKU premiumization potential in Brazilian import portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Indication Compliance Investment | Maipo Valley and Uco Valley designation unlocks premium channel placement in export corridors. |
| Direct-to-Consumer Platform Launch | Winery-owned digital channels capture full retail margin in São Paulo and Buenos Aires metropolitan zones. |
| Precision Viticulture Technology Adoption | Drone-mounted multispectral imaging reduces water use while concentrating fruit quality in high-altitude blocks. |
| Organic Certification Conversion | Argentina's Instituto Nacional de Vitivinicultura streamlines transition timelines for estates pivoting from conventional viticulture. |
| Traditional Method Sparkling Capacity Buildout | Serra Gaúcha producers displace charmat-process volume to command higher per-bottle yields in Brazilian domestic channels. |
Research Methodology
Independent corroboration across primary interviews with vineyard managers, enologists, export directors, and hospitality procurement leads, combined with secondary validation through Argentina's Instituto Nacional de Vitivinicultura harvest declarations, Chile's Ministry of Agriculture denomination-of-origin protocols, and ANVISA regulatory filings, underwrites the qualitative findings. Bottom-up triangulation across estate-level production data and top-down reconciliation against regional trade flows ensures analytical consistency.
Rate-of-change decomposition across the analysis window isolates volume drivers from pricing dynamics within each segmentation dimension. The analytical framework models product type, price tier, packaging format, and altitude designation as core segmentation variables. CAGRs derive from curve-fitting approaches applied to historical production data and forward-looking channel capacity assessments. Forecast inputs incorporate tourism rebound trajectories in Buenos Aires and Santiago alongside ANVISA regulatory evolution timelines.
Several conditions sit outside the modeled scope, including extreme climate events affecting Andean snowpack, abrupt Mercosur technical standard harmonization failures, and geopolitical disruptions to French oak supply chains. Forecasts reflect documented assumptions about water allocation stability and hospitality procurement centralization velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
Sparkling Red Wine Market
Alcoholic Beverages
Vodka Seltzer Market
Alcoholic Beverages
Mead Beverage Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market
Alcoholic Beverages
Organic Wine Market
Alcoholic Beverages
UAE Alcohol E-Commerce Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Home Brewing Systems Market
Alcoholic Beverages
Global Wine Market
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
Sparkling Wine Market
Alcoholic Beverages
Wine Barrel Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
Wine Cellar Market