
 Wine Destemmer Market | 2026-2036
Wine Destemmer Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Destemmer Market Analytics
Aftermarket service revenue is tilting toward predictive maintenance contracts and refurbishment programs as wineries extend equipment life cycles. Bucher Vaslin leverages its French manufacturing base to sustain strong channel control across European viticulture regions. Zambelli Enotech anchors its position through specialized Italian engineering for mid-scale pneumatic systems. Enoitalia competes aggressively on modular designs that allow wineries to upgrade capacity without full replacement.
A wine destemmer is a mechanical processing unit that separates grape berries from stems through rotating perforated drums or centrifugal beaters, typically operating at throughput rates from 500 kilograms to over 50 tons per hour depending on scale configuration. Its primary commercial purpose is to reduce tannin extraction from green stems while preserving berry integrity for controlled fermentation. Electric destemmers now dominate new installations among medium-scale wineries seeking consistent throughput with minimal labor, while pneumatic separation technology is gaining fastest in premium segments where gentler handling commands measurable quality premiums. Small-scale manual units retain relevance among home winemakers and estate producers with limited harvest volumes.
The EU's CE marking and Machinery Directive shape equipment safety standards and market access across European wine-producing countries, while the US OSHA framework governs worker exposure limits in American crush pad operations. California's Air Resources Board imposes emissions thresholds that push wineries toward electric destemmers over diesel-powered alternatives in Central Valley processing facilities. Stakeholders must monitor how evolving energy efficiency standards in France and Italy reshape total cost-of-ownership calculations for capacity expansion decisions.
Market Dynamics
California's Air Resources Board emissions thresholds are compressing diesel-powered destemmer deployments in Central Valley crush pads, forcing rapid electrification of processing infrastructure across premium and mid-scale winery tiers.
Growth Catalysts
- EU F-Gas Regulation:The regulation accelerates winery transitions toward pneumatic and electric destemming systems that eliminate refrigerant-dependent cooling in processing lines, particularly across French and Italian estate operations.
- Boutique winery expansion:Napa Valley producers are scaling automated destemming capacity to meet premium grape quality standards, driving precision separation equipment demand in high-value viticulture clusters.
- CE marking harmonization:Machinery Directive alignment streamlines equipment safety certification across European wine-producing countries, reducing market access friction for cross-border equipment suppliers.
Market Restraints
- Stainless steel input volatility:Food-grade 304 and 316 stainless price swings compress fabrication margins for drum and beater assembly manufacturers, particularly affecting mid-scale pneumatic system producers.
- German component concentration:Precision bearing and drive motor supply chains cluster in Baden-Württemberg engineering hubs, creating geographic vulnerability for just-in-time destemmer production schedules.
- Manual unit substitution:Small-scale estate producers and home winemakers retain hand-cranked destemming alternatives, capping addressable volume in sub-ton hourly throughput segments.
Strategic Opportunities
- Portuguese modernization wave:Douro Valley and Alentejo cooperatives are upgrading from legacy manual processing, creating first-mover advantage for modular electric destemmer suppliers with localized service networks.
- Predictive maintenance convergence:IoT sensor integration with cloud-based vibration analysis is digitizing aftermarket revenue streams, enabling remote monitoring contracts that extend equipment life cycles.
- US OSHA worker exposure mandates:Stricter crush pad noise and dust regulations are accelerating pneumatic system preference over mechanical beaters in American winery capital planning.
Industry Challenges
- Mechatronics skill scarcity:Winery maintenance teams lack training in servo motor calibration and PLC troubleshooting for automated destemming lines, forcing reliance on OEM service contracts.
- Legacy integration complexity:New electric destemmers must interface with existing must pumps and sorting tables, creating commissioning delays and compatibility engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Destemmer Market |
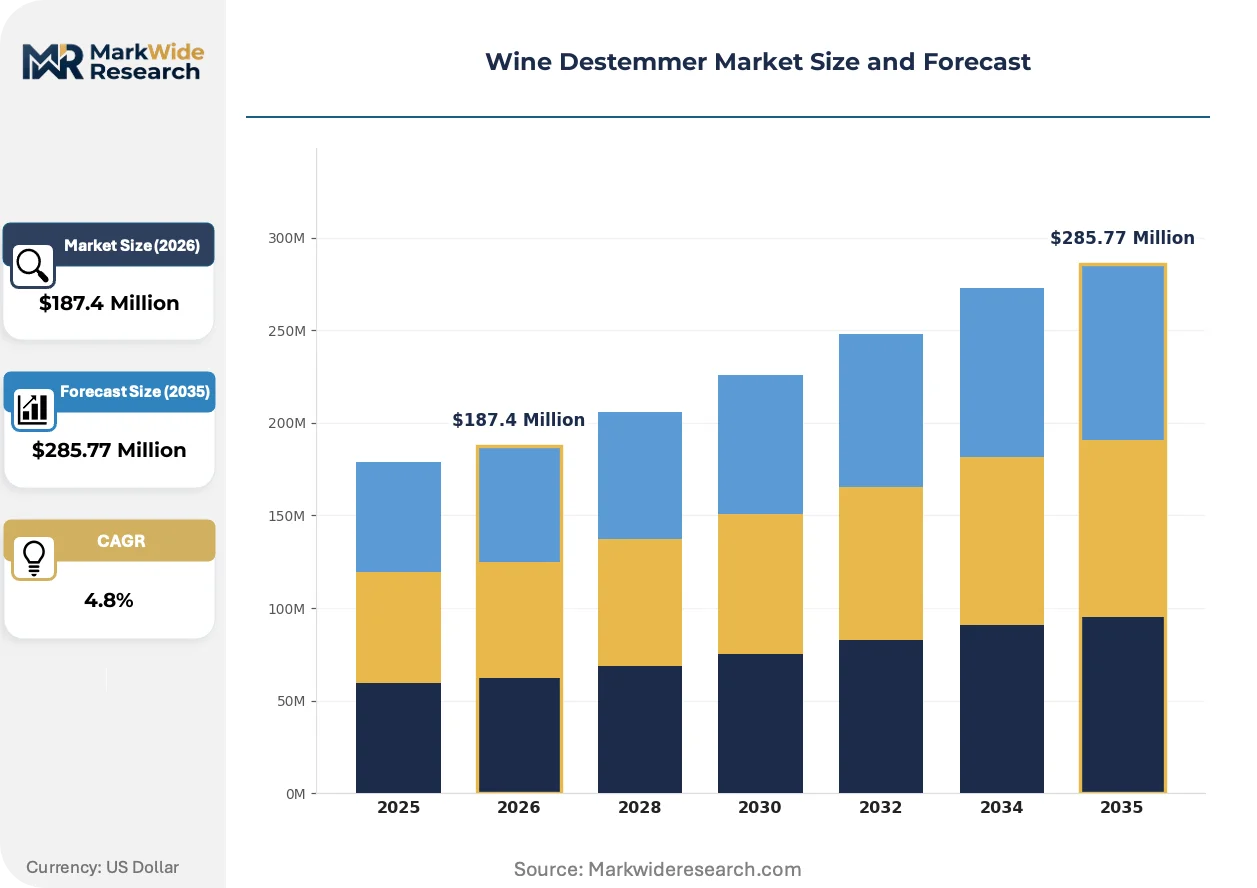
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Destemmers, Pneumatic Destemmers, Electric Destemmers, Motorized Destemmers Technology: Mechanical Separation, Pneumatic Separation, Hydraulic Systems, Vibration Systems End User: Winery, Distillery, Beverage Manufacturer, Home Winemaker Capacity: Small Scale, Medium Scale, Large Scale, Industrial Scale |
| Companies Covered | Bucher Vaslin, Zambelli Enotech, Enoitalia, Criveller Group, Pera-Pellenc, Scharfenberger, Della Toffola, Enoveneta, Mori-Tem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Destemmer Market Evolving Landscape
Winery processing infrastructure is undergoing rapid sensor integration and electrification, with quality control systems and regulatory compliance requirements converging to reshape equipment specification priorities.
Optical grape sorters with integrated destemming modules are digitizing berry selection workflows. Large Bordeaux châteaux and premium Napa estates are deploying these systems at accelerating rates. The technology is digitizing quality assurance protocols by linking real-time defect detection with automated separation adjustments, compressing labor requirements while tightening phenolic consistency.
France's ANSM and environmental regulators are tightening food contact material standards for vineyard processing equipment. Stainless steel surface finish specifications now require enhanced passivation documentation for CE marking renewal. Premium segment producers in Burgundy and Champagne are responding by specifying electropolished drum interiors that exceed baseline regulatory thresholds.
Service contract unbundling is fragmenting traditional equipment procurement. Wineries are separating hardware acquisition from predictive maintenance subscriptions, with mid-scale operators in Italy's Veneto region leading this shift. The change is most visible among cooperatives modernizing multi-vintage equipment fleets without full capital replacement cycles.
Wine Destemmer Market Segmentation
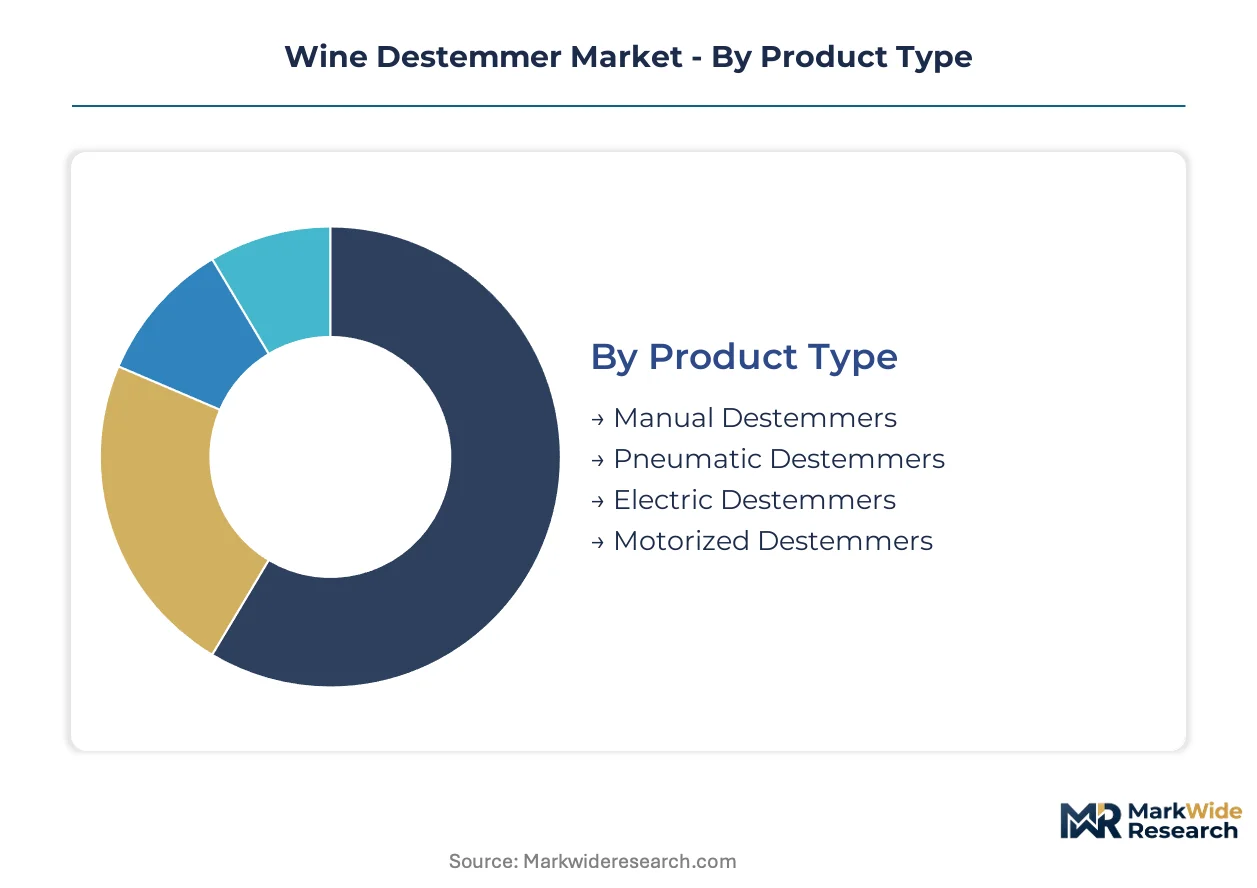
Wine destemmer segmentation reflects the tension between artisanal heritage and precision automation. Equipment specification varies sharply across harvest scale, grape quality tier, and regulatory environment, creating distinct procurement patterns that suppliers must navigate.
Product Type:
Cost tier drives equipment selection more than any other dimension, with capital outlay and operating labor requirements creating sharp stratification across winery budgets.
- Manual Destemmers:Hand-cranked cast iron or aluminum units process 200-500 kilograms hourly through perforated drums with adjustable gap settings. Demand concentrates among home winemakers in Italy's Piedmont and estate producers in Portugal's Douro Valley where harvest volumes stay below five tons. Labor intensity limits scalability.
- Pneumatic Destemmers:Air-jet separation systems eliminate mechanical contact, preserving berry integrity for premium cuvée production. Napa Valley boutique wineries and Bordeaux châteaux prioritize these units despite 40-60% capital premiums, as gentler handling commands measurable price premiums in bottle.
- Electric Destemmers:Three-phase motor drives with variable frequency control dominate mid-scale winery installations across California's Central Valley and France's Languedoc. Consistent throughput with single-operator supervision offsets higher energy costs against labor savings.
- Motorized Destemmers:Diesel or gasoline-powered units serve mobile contract harvesters and estates without grid infrastructure in rural Spain and Greece. CARB emissions thresholds in California are compressing deployments rapidly.
Electric destemmers command the established base. The steepest expansion runs through pneumatic systems.
Technology:
Application requirements determine technology choice, with grape variety skin thickness and desired phenolic extraction driving separation mechanism specification.
- Mechanical Separation:Rotating perforated drums with adjustable beater bars remain the workhorse for robust red varieties. Italian cooperatives in Veneto and Tuscany favor these systems for Amarone and Chianti production where moderate berry damage aids extraction.
- Pneumatic Separation:Controlled air streams lift berries while stems fall through gravity separation. Champagne houses and Burgundy domaines specify these for Pinot Noir and Chardonnay to minimize skin rupture before pressing.
- Hydraulic Systems:Pressurized water-assisted separation serves high-throughput industrial installations in Australia's Riverina and California's San Joaquin Valley. Water recovery and treatment costs constrain adoption in drought-prone regions.
- Vibration Systems:Oscillating mesh screens with frequency-tuned agitation separate berries through inertial differentiation. Emerging deployments in Germany's Pfalz show promise for delicate white grape handling.
Mechanical separation retains volume leadership. Pneumatic technology is gaining share fastest in premium tiers.
End User:
Customer type shapes procurement behavior, with capital access and technical staffing determining automation depth and service contract reliance.
- Winery:Estate and cooperative producers from 50-ton to 50,000-ton annual crush capacity. French châteaux prioritize CE-marked precision equipment with electropolished contact surfaces.
- Distillery:Brandy and eau-de-vie producers in Cognac and Armagnac accept higher stem content for phenolic backbone, specifying less aggressive separation parameters.
- Beverage Manufacturer:Industrial grape juice and concentrate processors in Argentina's Mendoza and Chile's Central Valley demand 20+ ton hourly throughput with automated cleaning cycles.
- Home Winemaker:Enthusiast segment drives manual and small electric unit sales through specialty retailers. Seasonal demand peaks compress inventory planning.
Commercial wineries anchor equipment revenue. Contract distillation services are expanding most quickly in traditional brandy regions.
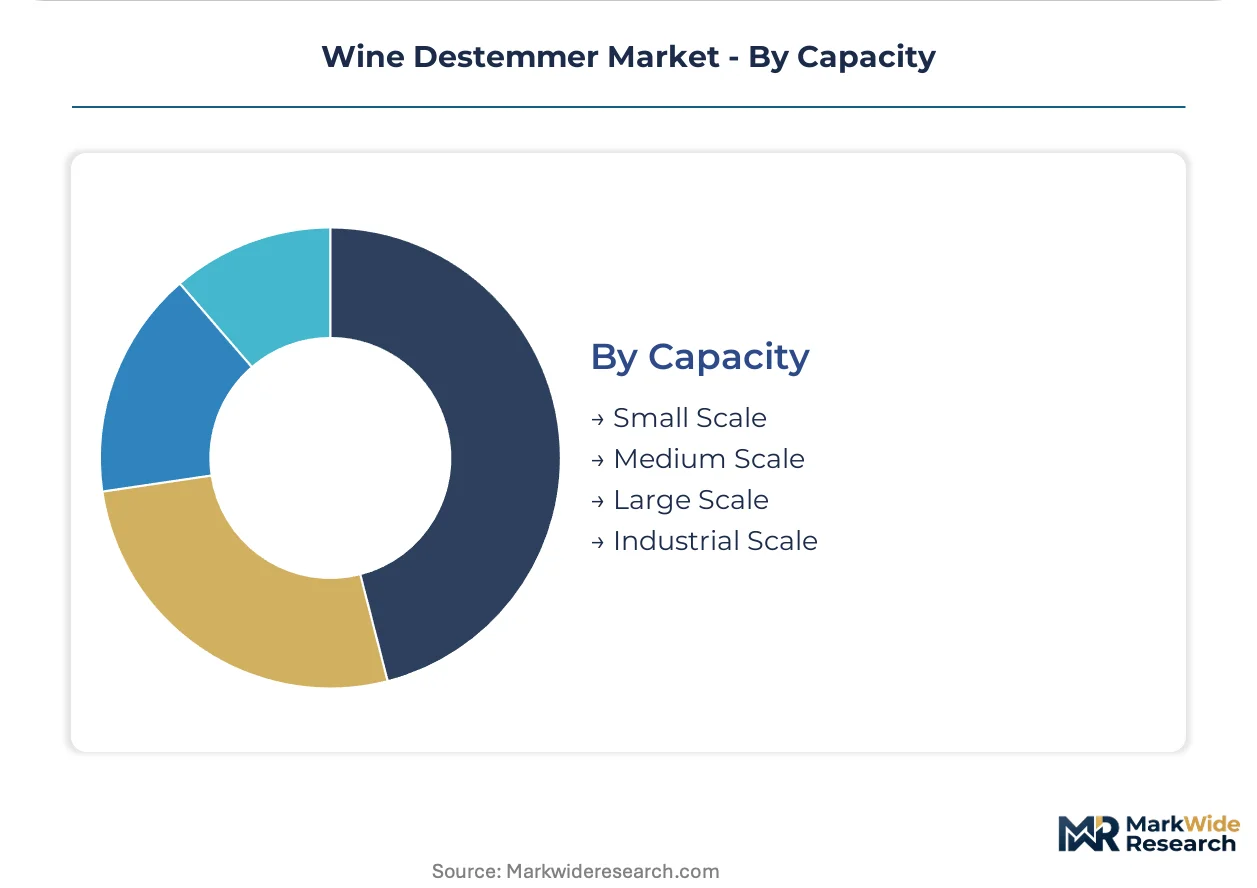
Capacity:
Volume scale determines infrastructure integration complexity, with must pump compatibility and sorting table synchronization creating distinct specification tiers.
- Small Scale:Sub-ton hourly throughput serves estate producers and mobile harvest contractors. Manual or single-phase electric units dominate with minimal foundation requirements.
- Medium Scale:Two to ten tons hourly matches independent wineries in Oregon's Willamette Valley and New York's Finger Lakes. Pneumatic and electric systems with PLC control predominate.
- Large Scale:Ten to fifty tons hourly serves cooperative cellars and regional negociants. Multi-unit parallel configurations with centralized control are standard in France's Bordeaux and Spain's Rioja.
- Industrial Scale:Continuous-feed systems exceeding fifty tons hourly integrate with optical sorting and automated press lines. Limited to major processing hubs in California, Australia, and Argentina.
Medium scale installations represent the revenue core. Industrial scale projects are climbing fastest as consolidation accelerates in New World production zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision component suppliers dominate upstream supply chains for drive motors and bearings, while French and Italian equipment fabricators control downstream assembly. Equipment demand concentrates in established viticulture belts where estate modernization programs and regulatory compliance reshape procurement priorities.
France
ANSM passivation documentation requirements for CE marking renewal are tightening stainless steel surface finish specifications. Bordeaux châteaux and Burgundy domaines are specifying electropolished drum interiors that exceed baseline regulatory thresholds. Champagne houses prioritize pneumatic separation systems to minimize skin rupture before pressing.
Italy
Veneto cooperatives are unbundling service contracts from hardware acquisition, separating predictive maintenance subscriptions from capital purchases. Tuscany and Piedmont estate producers retain manual destemming alternatives for sub-ton harvest volumes. The Machinery Directive shapes safety certification across Italian wine-producing regions.
United States
OSHA crush pad noise and dust regulations are accelerating pneumatic system preference over mechanical beaters in American winery capital planning. California's Air Resources Board emissions thresholds compress diesel-powered deployments in Central Valley processing facilities. Napa Valley boutique wineries scale automated destemming capacity to meet premium grape quality standards.
Spain
Rioja cooperative cellars deploy multi-unit parallel configurations with centralized control for ten to fifty ton hourly throughput. Rural estates in Castile-La Mancha without grid infrastructure retain gasoline-powered mobile units. The country's national environmental regulator is tightening emissions thresholds for processing equipment.
Portugal
Douro Valley and Alentejo cooperatives are upgrading from legacy manual processing, creating first-mover advantage for modular electric destemmer suppliers. Limited harvest volumes in traditional quinta operations sustain demand for small-scale equipment. Localized service networks determine supplier selection in this modernization wave.
Wine Destemmer Market Competitive Landscape
Specialized viticulture equipment fabricators and diversified food processing machinery groups split the market across premium and mid-scale tiers. Italian and French engineering traditions anchor European supply, while component concentration in German industrial clusters creates geographic vulnerability for just-in-time production schedules. Two archetypes predominate: precision pneumatic specialists serving estate châteaux, and modular electric system suppliers targeting cooperative modernization programs. Competitive moves center on predictive maintenance service unbundling and backward integration into stainless steel fabrication.
Among Italian specialists, Bucher Vaslin, Zambelli Enotech, and Enoitalia occupy distinct positions within the equipment hierarchy. Bucher Vaslin exemplifies the French manufacturing archetype with strong channel control across European viticulture regions. Zambelli Enotech sits within the specialized pneumatic tier for mid-scale winery applications. Enoitalia represents the modular design approach that allows capacity upgrades without full equipment replacement. These three anchors illustrate how geographic origin and engineering tradition shape competitive positioning in precision separation equipment.
| Leading Market Players |
|---|
| Bucher Vaslin |
| Zambelli Enotech |
| Enoitalia |
| Criveller Group |
| Pera-Pellenc |
| Scharfenberger |
| Della Toffola |
| Enoveneta |
| Mori-Tem |
| Others |
Value Network & Pricing Analysis
German precision component concentration in Baden-Württemberg engineering hubs determines both three-tier pricing stratification across premium pneumatic, standard electric, and economy manual systems and the geographic vulnerability of just-in-time destemmer production schedules. Stainless steel input volatility from food-grade 304 and 316 suppliers compresses fabrication margins while amplifying price spreads between electropolished premium units and baseline CE-marked alternatives.
Pricing Analysis
The EU's F-Gas Regulation dictates the pricing tier structure by accelerating capital premiums for pneumatic and electric systems that eliminate refrigerant-dependent cooling infrastructure. Pricing stratifies across premium pneumatic, standard electric, and economy manual tiers based on certification grade and after-sales service bundling. Cost compression in mid-scale electric segments is intensifying because stainless steel price swings compress fabrication margins for drum and beater assembly manufacturers. Cooperative wineries in Italy's Veneto region exhibit highest price sensitivity through unbundled service contract procurement, while Bordeaux châteaux accept 40-60% capital premiums for gentler handling systems.
Supply Chain Analysis
Contract manufacturing for precision bearings and drive motors concentrates in German Baden-Württemberg hubs, with final assembly anchored in French and Italian viticulture equipment fabricators. Raw material dependencies center on food-grade 304 and 316 stainless steel from European mills, electropolished surface treatment capacity, and pneumatic valve assemblies from Italian engineering clusters. Single-source vulnerability in servo motor supply chains creates geographic concentration risk for just-in-time production schedules. Distribution runs through specialized viticulture equipment dealers with localized service networks across Napa Valley, Bordeaux, and Veneto cooperative regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wine destemmer market sits at a cyclical recovery phase driven by estate modernization programs across Portuguese and Spanish cooperative tiers, with capital deployment accelerating as harvest volumes stabilize and regulatory compliance deadlines approach.
For Market Incumbents: Build predictive maintenance moats through IoT sensor integration and cloud-based vibration analysis platforms that digitize aftermarket revenue streams. Deepen backward integration into stainless steel fabrication to defend against food-grade 304 and 316 price volatility compressing drum assembly margins. Anchor channel control across European viticulture regions through localized service network density that counters modular competitor upgrade pathways.
For New Entrants and Emerging Players: Build out Portuguese modernization wave positioning in Douro Valley and Alentejo cooperative segments where legacy manual processing creates first-mover advantage for modular electric destemmer suppliers. Target sub-ton hourly throughput gaps in Italy's Piedmont estate producers and home winemaker channels where manual unit substitution caps incumbent addressable volume. Pursue unbundled service contract go-to-market angles that separate predictive maintenance subscriptions from capital purchases.
For Investors and Strategic Acquirers: The market sits at a modernization phase that favors precision pneumatic specialists with electropolished CE-marked certification advantages and established French manufacturing bases. Long-term viability centers on equipment fabricators with backward integration into stainless steel passivation documentation capabilities that exceed ANSM renewal thresholds. Monitor Portuguese cooperative capital deployment rates as the inflection signal indicating acceleration or deceleration of European estate modernization cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | IoT sensor integration with cloud-based vibration analysis digitizes aftermarket revenue for Napa Valley boutique wineries. |
| Backward Integration into Stainless Fabrication | In-house production of food-grade 304 drum assemblies defends margins against commodity price volatility in European mills. |
| Portuguese Service Network Expansion | Localized maintenance capacity in Douro Valley captures cooperative modernization wave ahead of modular competitor entry. |
| CE Marking Electropolish Certification | Enhanced passivation documentation exceeds ANSM renewal thresholds for Bordeaux châteaux premium segment specification. |
| Pneumatic Technology Licensing | Air-jet separation IP partnerships extend gentler handling advantages into mid-scale electric system upgrade pathways. |
Research Methodology
Desk research of customs and trade data, European viticulture machinery association reports, and CE marking directive documentation preceded structured interviews with winery maintenance directors, cooperative procurement managers, OEM equipment sales heads, and aftermarket service technicians. Primary fieldwork across Napa Valley, Bordeaux, Veneto, and Douro Valley processing facilities combined with secondary validation from stainless steel price indices and F-Gas Regulation compliance databases. Bottom-up equipment shipment analysis triangulated against top-down vineyard acreage and harvest volume projections.
Forecast assumptions held fixed the EU F-Gas Regulation compliance timeline and CE marking Machinery Directive enforcement intensity while varying stainless steel input cost trajectories and Portuguese cooperative capital access conditions across the projection horizon. Segmentation modeling incorporated product type, separation technology, end-user category, and hourly capacity tier dimensions. CAGRs derived from vintage-to-vintage equipment replacement cycles and estate modernization program cadences in French and Italian viticulture clusters.
Practitioners should monitor stainless steel commodity price volatility, German precision component lead time extensions, and Portuguese cooperative funding approval rates for early signals of forecast revision. Quarterly review of CE marking renewal application volumes and pneumatic system quotation-to-order conversion ratios is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Dispensing Machine Market
Alcoholic Beverages
Brandy Market
Alcoholic Beverages
East Africa Alcoholic Beverages Market
Alcoholic Beverages
Brewers Spent Grain Market
Alcoholic Beverages
Brewing Enzymes Market
Alcoholic Beverages
Hard Tea Market
Alcoholic Beverages
US Wine Market
Alcoholic Beverages
Organic Beer Market
Alcoholic Beverages
Mezcal Market
Alcoholic Beverages
Rotels Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Whey Based Vodka Market
Alcoholic Beverages
Alcoholic Flavors Market
Alcoholic Beverages
India Gin Market
Alcoholic Beverages
Spirits Miniatures Market
Alcoholic Beverages
Alcohol Enzymes Market