
 Crystal Malt Market | 2026-2036
Crystal Malt Market Size, Share, and Industry Trends Forecast 2026-2036
Crystal Malt Market Outlook
Multi-source procurement among mid-sized brewers is broadening as supply chain resilience becomes a priority. Simpsons Malt leverages its UK heritage and floor-malting expertise to sustain premium positioning in export markets. Weyermann Specialty Malting anchors German brewing tradition with extensive caramel malt specialization. Castle Malting competes through Belgian sourcing networks and small-batch flexibility for craft clients.
Crystal malt denotes kilned barley grain subjected to stewing at controlled moisture levels, typically achieving color ratings from 20 to 120 Lovibond through Maillard reaction caramelization before final drying. This process yields fermentable sugars and distinct toffee-caramel flavor compounds essential for ale body, head retention, and color adjustment in brewing formulations. Light Crystal Malt dominates volume in standard ale formulations where subtle sweetness balances hop bitterness without overwhelming malt character. Dark Crystal Malt and Crystal Malt 120L command margin premiums in imperial stouts, barleywines, and limited seasonal releases where intense color and raisin-plum notes justify higher ingredient costs. Craft Breweries and Large Breweries split procurement patterns, with smaller operators favoring whole grain flexibility while industrial brewers standardize on crushed or extract forms for efficiency.
The FDA oversees grain safety and labeling in the United States under the Food Safety Modernization Act, while the EPA regulates malting facility emissions and wastewater discharge. In Europe, EFSA sets maximum contaminant thresholds for acrylamide and mycotoxins in processed cereals, directly affecting roasting parameters and quality protocols. Brewers and maltsters must monitor evolving sustainability disclosure rules under the EU Green Deal and emerging carbon border adjustments that could reshape transatlantic ingredient trade economics.
Market Dynamics
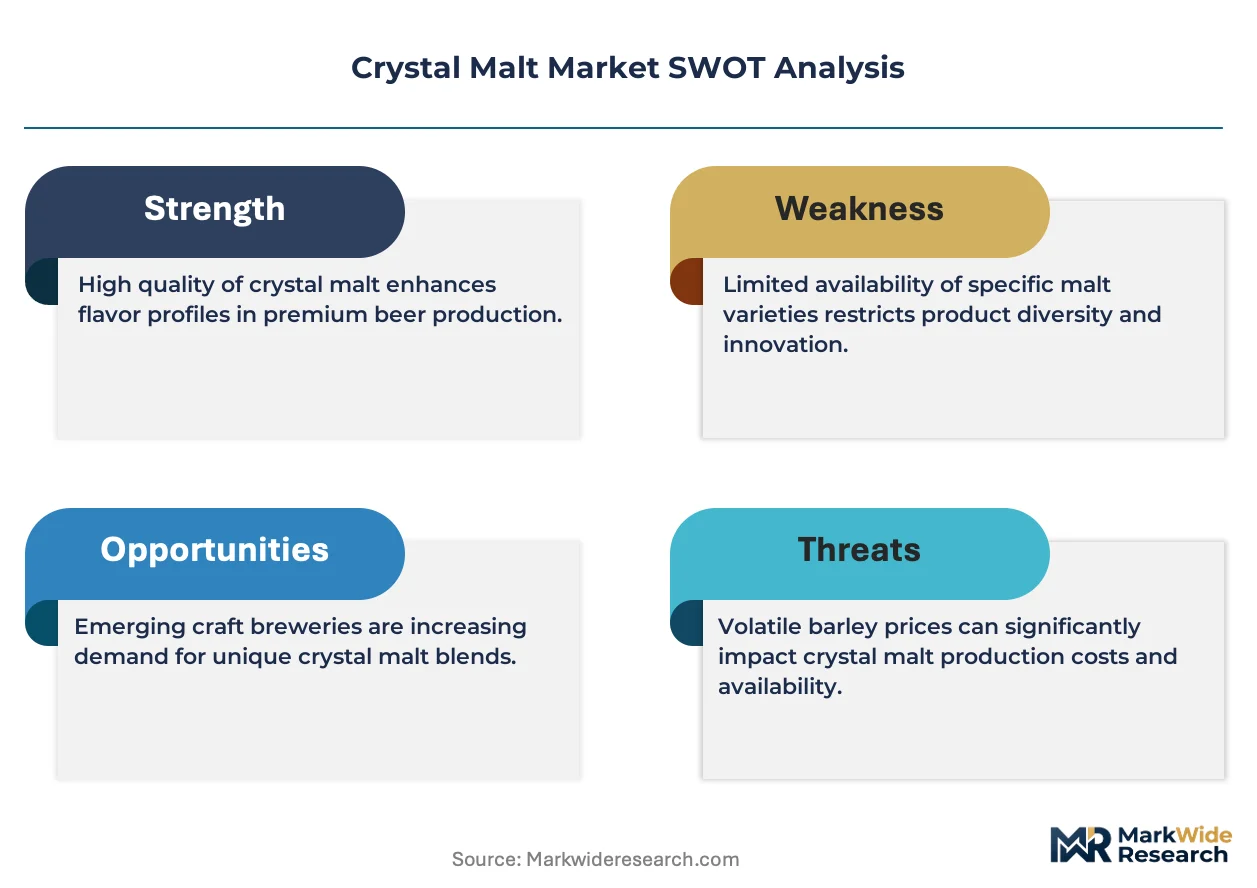
The craft brewing sector's procurement fragmentation is forcing maltsters to rebuild supply chains around smaller batch sizes and sustainability verification, compressing traditional volume-based economics while elevating specialty malt premiums.
Growth Catalysts
- EU Farm to Fork Strategy:Mandatory sustainability disclosure across agricultural inputs is redirecting brewery procurement toward certified maltsters with traceable sourcing, tightening supplier qualification criteria.
- Caramelization process refinement:Advanced stewing-kilning control systems are expanding color consistency ranges, enabling precise flavor matching for experimental ale formulations.
- German export brewery clusters:Bavarian and Franconian brewing traditions anchor specialty malt demand, with Weyermann Specialty Malting and regional competitors feeding transatlantic craft supply chains.
Market Restraints
- Barley price volatility:Feed and food competition for malting-grade barley concentrates cost pressure on smaller craft maltsters lacking forward-contract coverage.
- Acrylamide thresholds:EFSA maximum contaminant limits for roasted cereals constrain roasting parameter flexibility, forcing capital investment in emission and process control upgrades.
- Malt extract substitution:Large industrial brewers standardizing on concentrated extracts reduce whole-grain crystal malt offtake, segmenting procurement volumes by brewery scale.
Strategic Opportunities
- Belgian small-batch craft networks:Castle Malting's sourcing flexibility demonstrates viable positioning for micro-maltsters serving limited-release seasonal formulations.
- Carbon border adjustment preparation:EU Green Deal compliance infrastructure investments now position early movers for advantaged transatlantic trade economics under emerging tariff mechanisms.
- Floor-malting heritage revival:UK and Belgian traditional techniques are capturing premium positioning in export markets seeking differentiated provenance narratives.
Industry Challenges
- Roasting technician scarcity:Maillard reaction control expertise requires years of apprenticeship, constraining capacity expansion at specialty maltsters.
- Multi-jurisdiction compliance layering:Simultaneous FDA Food Safety Modernization Act, EPA wastewater discharge, and EFSA contaminant protocols multiply quality system complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crystal Malt Market |
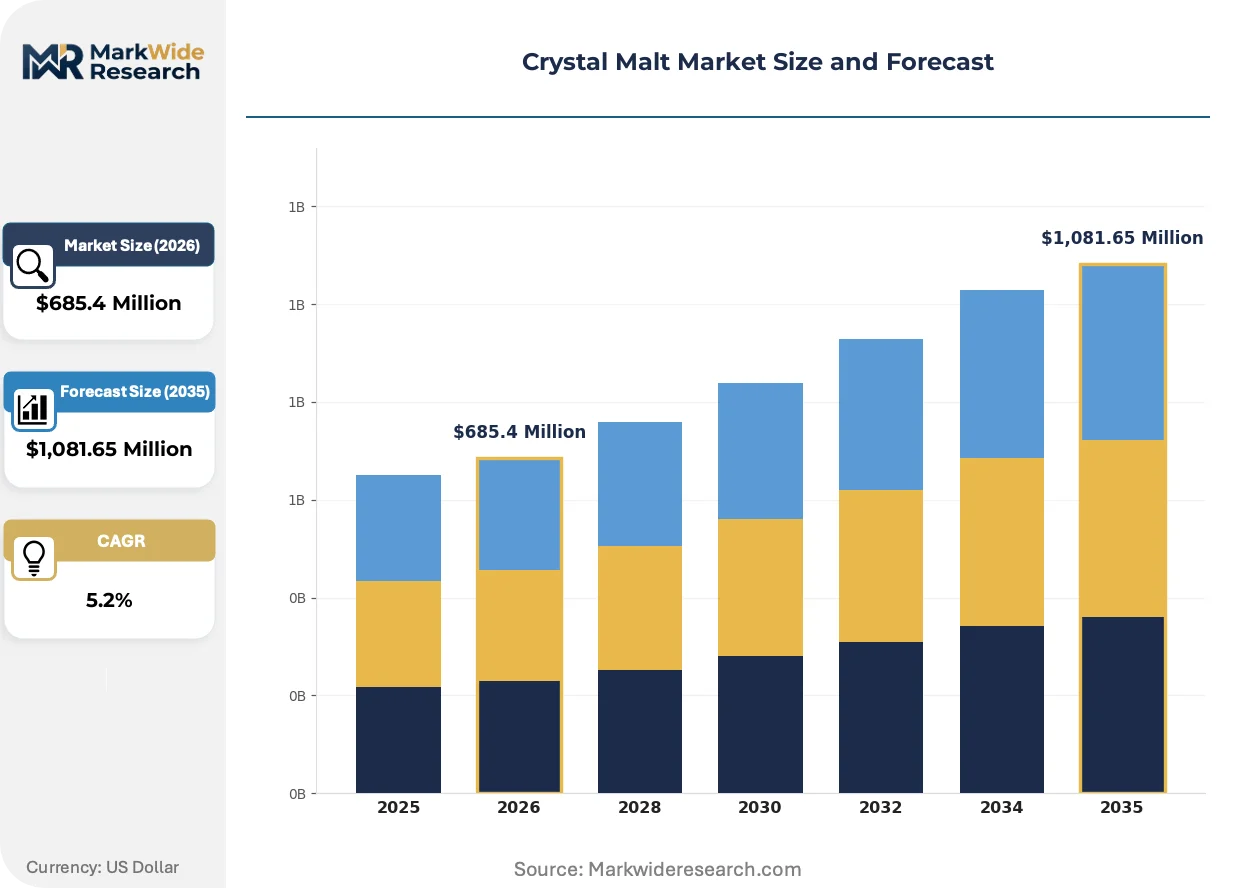
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Crystal Malt, Dark Crystal Malt, Crystal Malt 60L, Crystal Malt 120L Application: Beer Brewing, Distillation, Baking, Flavoring End User: Craft Breweries, Large Breweries, Food Manufacturers, Distillers Form: Whole Grain, Crushed, Powdered, Extract |
| Companies Covered | Cargill, Simpsons Malt, Castle Malting, Briess Malt & Ingredients, Weyermann Specialty Malting, Viking Malt, Bairds Malt, Crisp Malting Group, Great Western Malting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crystal Malt Market Strategic Shifts
Automation in kilning control and sustainability verification protocols are compressing traditional craft production timelines while fragmenting buyer procurement patterns across direct and distributor channels.
Precision moisture and temperature monitoring systems are consolidating quality consistency across small-batch crystal malt production. Mid-sized craft breweries in Germany and the UK are adopting these systems fastest, replacing manual sampling protocols. The technology is consolidating supplier tiers by enabling smaller maltsters to meet industrial-grade specifications without legacy scale.
REACH chemical registration and CSRD sustainability disclosure requirements are tightening supply chain documentation burdens across European malt imports. Maltsters must now maintain substance-level chemical inventories and scope-three emissions tracking. Dark Crystal Malt and premium color-grade categories face the steepest compliance cost escalation, accelerating consolidation toward integrated malting groups with dedicated regulatory staff.
Brewery purchasing departments are fragmenting supplier relationships to reduce concentration risk, splitting annual crystal malt volumes across three to four maltsters rather than single-source contracts. Distributor intermediaries in North America are losing share to direct mill relationships as brewers seek lot-level traceability. This pattern concentrates most visibly in Pacific Northwest craft clusters where sustainability storytelling drives consumer pricing power.
Crystal Malt Market Segmentation
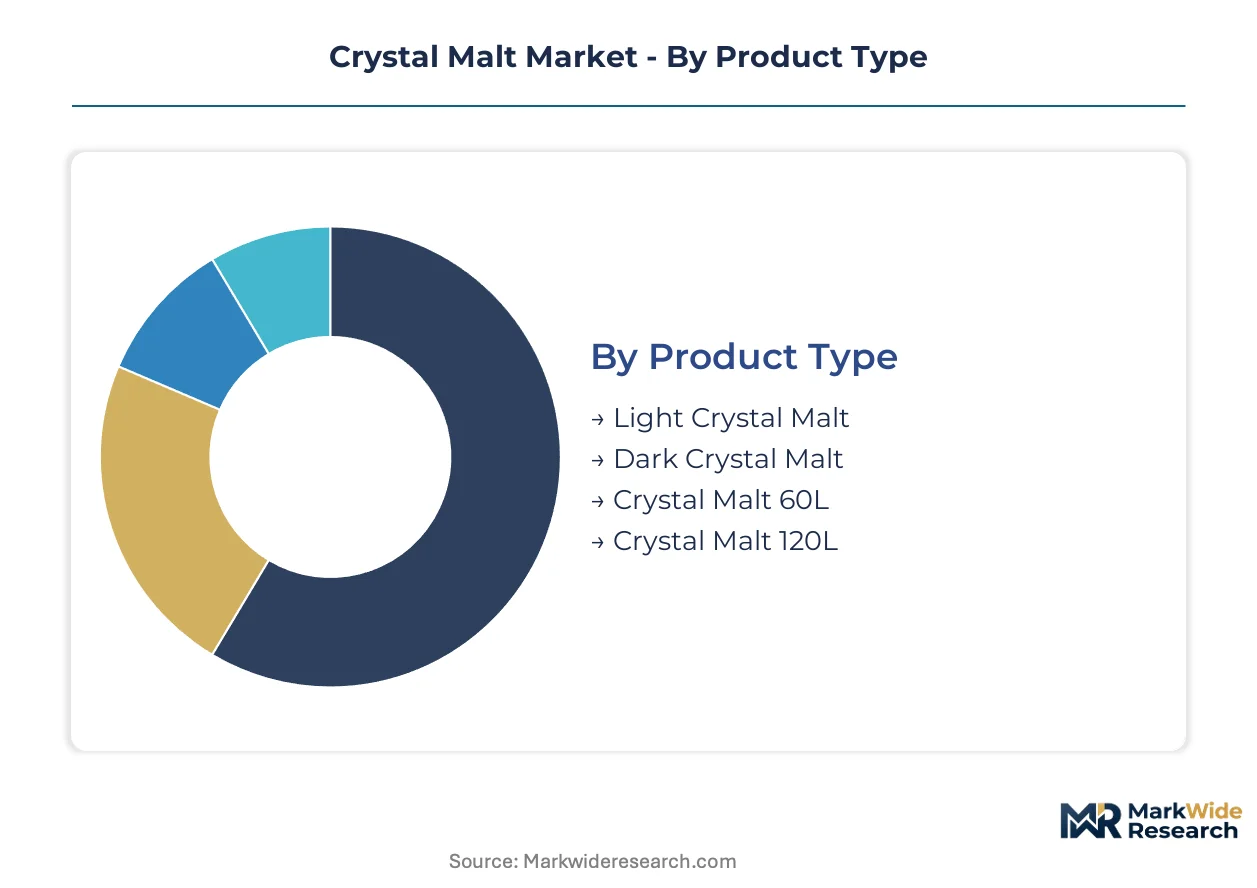
Crystal malt procurement patterns diverge sharply by brewing scale and formulation complexity. Specialty maltsters must align product portfolios with divergent technical specifications across craft experimentation and industrial standardization.
Product Type:
Volume concentrates in standard color grades where economies of scale sustain margin, while premium tiers command pricing power through limited specialty releases.
- Light Crystal Malt:Kilned to 20-40 Lovibond with restrained caramelization preserving enzymatic activity for standard ale formulations. German export breweries and UK cask ale producers anchor procurement volumes, with Weyermann Specialty Malting and Simpsons Malt feeding steady demand for session beer balance.
- Dark Crystal Malt:Achieves 80-120 Lovibond through extended stewing cycles generating pronounced toffee and dried fruit compounds. Imperial stout and barleywine formulations in Pacific Northwest craft clusters concentrate demand, where EFSA acrylamide thresholds constrain roasting flexibility and elevate compliance costs.
- Crystal Malt 60L:Mid-range caramelization suits amber ale and red ale categories requiring color depth without residual sweetness dominance.
- Crystal Malt 120L:Maximum color density serves limited seasonal releases and specialty dark lagers where intense raisin-plum notes justify ingredient premiums.
Mature deployment sits with Light Crystal Malt. Newer deployment is concentrated in Crystal Malt 120L.
Application:
End-use concentration tracks brewing tradition strength versus adjacent market development.
- Beer Brewing:Dominant consumption channel spanning ale body enhancement, head retention improvement, and color standardization across lager and ale families. Bavarian brewing clusters and Belgian abbey traditions sustain volume, while craft experimentation in Oregon and Washington state expands specialty grade offtake.
- Distillation:Caramel malt contributes fermentable sugars and flavor complexity to whiskey and specialty spirit mashes. Scottish and Irish distillers maintain steady procurement, with emerging craft distilleries in Colorado and Kentucky testing small-batch integration.
- Baking:Limited adoption in artisan bread formulations seeking malt sweetness and crust coloration without refined sugar addition.
- Flavoring:Extract and powdered forms serve confectionery and beverage applications requiring clean-label caramel notes.
Established integration sits with Beer Brewing. Expanding integration is concentrated in Distillation.
End User:
Procurement scale and technical requirements fragment supplier relationships across customer tiers.
- Craft Breweries:Smaller batch sizes and formulation flexibility drive whole grain preference and direct mill relationships. Sustainability storytelling requirements in Portland and Seattle markets elevate traceability demands, compressing traditional distributor margins.
- Large Breweries:Standardized formulations and efficiency optimization favor crushed grain or extract forms with contracted volume pricing. Multi-source procurement strategies reduce concentration risk across three to four qualified maltsters.
- Food Manufacturers:Malt extract and powdered forms serve processed food applications with consistent specification requirements.
- Distillers:Specialized mashing protocols and fermentation control demand tailored caramel malt specifications distinct from brewing grades.
Volume leadership sits with Large Breweries. Specification innovation is concentrated in Craft Breweries.
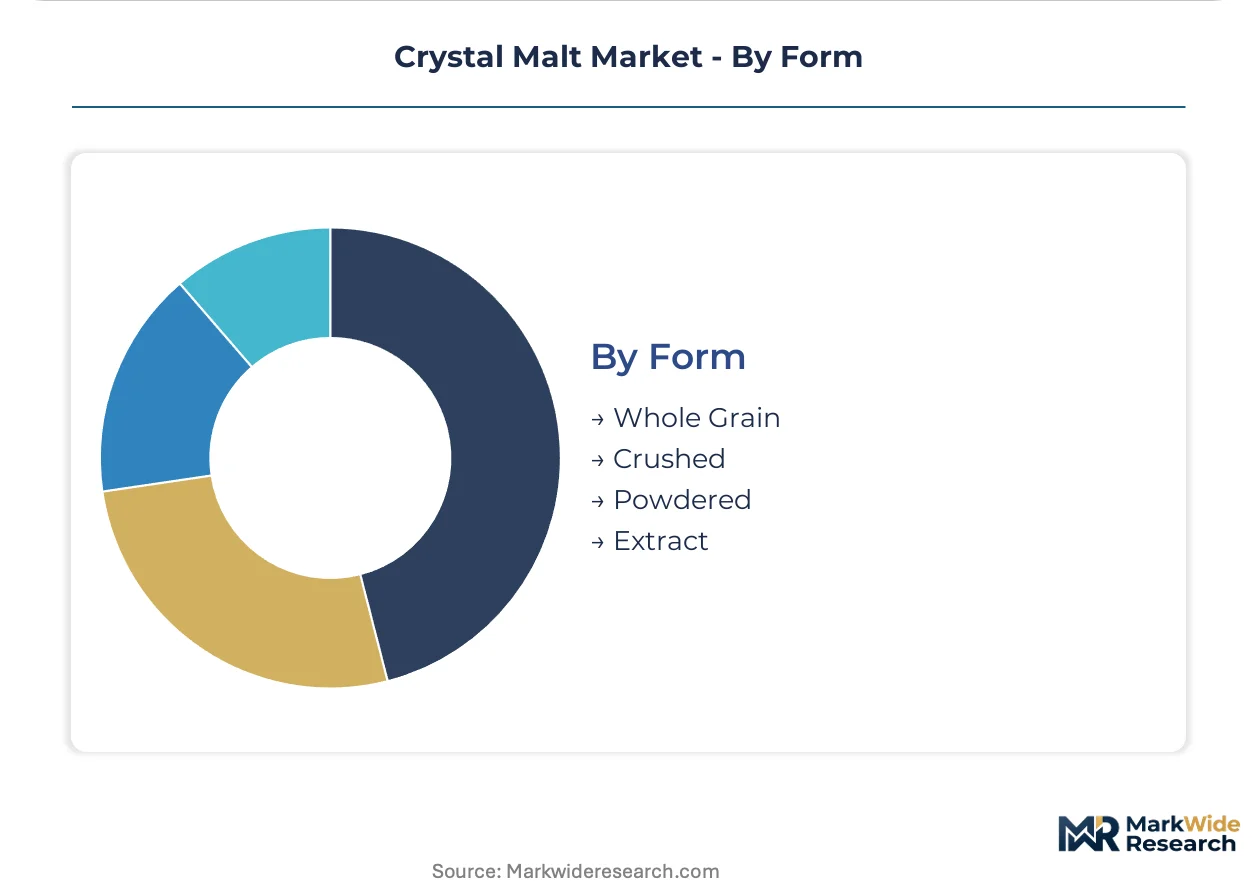
Form:
Processing stage at maltster versus brewery determines supply chain economics and quality control locus.
- Whole Grain:Preserves enzymatic integrity and shelf stability for brewers with in-house milling capability. German and UK craft segments prefer this form for provenance narrative and batch flexibility.
- Crushed:Pre-milled consistency reduces brewery capital investment while accelerating mash conversion. Large brewery procurement standardizes on this form for throughput optimization.
- Powdered:Fine grind enables rapid dissolution in extract production and food manufacturing applications.
- Extract:Concentrated liquid or dry forms eliminate mashing infrastructure requirements for small distilleries and food processors.
Traditional preference sits with Whole Grain. Efficiency-driven conversion is concentrated in Crushed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malting-grade barley cultivation in the North American Great Plains and European breadbaskets anchors crystal malt production geography. Distinct regulatory regimes and brewing traditions fragment procurement patterns across major consuming markets.
Germany
Bavarian brewing clusters sustain premium specialty malt demand through Weyermann Specialty Malting and regional competitors. The EU Green Deal and Farm to Fork Strategy mandate traceable sourcing disclosures that favor established maltsters with integrated supply chains. Franconian craft breweries in Bamberg and Nuremberg anchor experimental caramel malt procurement for export-oriented seasonal releases.
United States
Pacific Northwest craft brewery density in Oregon and Washington drives specialty grade offtake with sustainability storytelling requirements. FDA Food Safety Modernization Act oversight and EPA wastewater discharge rules compress margins for smaller roasters lacking compliance infrastructure. Portland and Seattle purchasing departments fragment supplier relationships across three to four maltsters to reduce concentration risk.
United Kingdom
Scottish and English distillation traditions sustain steady caramel malt procurement for whiskey mashes alongside cask ale brewing heritage. Simpsons Malt leverages floor-malting expertise for premium export positioning under REACH chemical registration and CSRD sustainability disclosure requirements. Burton-upon-Trent and Scottish Highland malting clusters concentrate technical capability for small-batch crystal production.
Belgium
Abbey brewing traditions and craft experimentation sustain demand for flexible small-batch caramel malt specifications. Castle Malting demonstrates viable micro-maltster positioning through sourcing networks serving limited-release seasonal formulations. Flemish brewing clusters around Leuven and Brussels concentrate specialty procurement for experimental ale categories.
Canada
Emerging craft distillery expansion in Alberta and British Columbia tests caramel malt integration for whiskey and specialty spirit mashes. Health Canada grain safety protocols align with FDA frameworks while provincial environmental regulations govern malting facility emissions. Calgary and Vancouver craft clusters drive experimental procurement outside traditional brewing applications.
Crystal Malt Market Competitive Environment
Global majors compete with regional champions across heritage positioning and sustainability verification capabilities. The vendor base organizes around three tiers: integrated agricultural conglomerates with captive barley supply, established specialty maltsters with floor-malting heritage, and flexible micro-maltsters serving craft experimentation. Strategic differentiation concentrates on traceable sourcing infrastructure, roasting technician apprenticeship programs, and multi-jurisdiction compliance system investment.
Within the heritage specialist tier, Weyermann Specialty Malting and Simpsons Malt exemplify premium positioning through traditional production techniques and export market penetration. Castle Malting occupies a position among flexible regional operators serving small-batch craft networks. These three entities represent distinct competitive archetypes: German export-oriented scale, UK floor-malting provenance, and Belgian sourcing agility.
| Leading Market Players |
|---|
| Cargill |
| Simpsons Malt |
| Castle Malting |
| Briess Malt & Ingredients |
| Weyermann Specialty Malting |
| Viking Malt |
| Bairds Malt |
| Crisp Malting Group |
| Great Western Malting |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap maltsters in Germany and the UK anchor pricing discipline through floor-malting heritage premiums, while their supply behavior—small-batch flexibility versus scale economies—directly shapes how buyers negotiate lot-level traceability versus contracted volume discounts.
Pricing Analysis
Warranty-style quality guarantees and unbundled technical support differentiate contract structures across the Crystal Malt Market. Three-tier pricing structure across premium, standard, and economy levels reflects color grade precision, EFSA acrylamide certification tier, and volume scale. Price differentiation stems from floor-malting labor intensity and sustainability disclosure infrastructure. Craft breweries in Portland and Seattle exhibit highest price sensitivity due to distributor bypass pressure, while German export breweries absorb premiums for traceable Bavarian provenance.
Supply Chain Analysis
Ocean freight and overland trucking costs from malting-grade barley cultivation zones in Germany, the United Kingdom, and Belgium concentrate supply economics around proximity to brewing clusters. Production draws from malting-grade barley, specialized roasting kilns, and skilled Maillard reaction technicians. Single-source vulnerability intensifies as multi-jurisdiction FDA, EPA, and EFSA compliance layers disqualify smaller roasters. Distribution runs through direct mill relationships for craft breweries and distributor intermediaries for large industrial brewers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Crystal Malt Market sits in a process-automation transition phase, where precision moisture and temperature monitoring systems displace manual sampling protocols and compress traditional craft production timelines.
For Market Incumbents: Deepen backward integration into captive malting-grade barley supply in Bavaria and Franconia to secure Farm to Fork Strategy traceability compliance. Expand floor-malting technician apprenticeship programs to counter roasting expertise scarcity. Fortify against extract substitution threats by embedding sustainability verification directly into maltster-buyer contracts. For New Entrants and Emerging Players: EU Green Deal carbon border adjustment preparation in Germany opens a window for early compliance infrastructure investment positioning. Target Pacific Northwest craft distillery expansion in Alberta and British Columbia for caramel malt whiskey mash applications. Pursue lot-level traceability storytelling as the primary go-to-market angle against established distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor micro-maltsters with Belgian sourcing flexibility and small-batch craft network relationships in Flemish brewing clusters. Long-term viability hinges on regulatory staff capacity for REACH chemical registration and CSRD sustainability disclosure compliance. Watch EFSA acrylamide threshold enforcement intensity as the inflection signal for roasting capital upgrade requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Kilning Automation | Simpsons Malt and Weyermann Specialty Malting deploy sensor networks to replace manual Maillard reaction control. |
| Sustainability Certification Program | Farm to Fork Strategy compliance infrastructure secures preferential procurement from German export breweries. |
| Floor-Malting Heritage Expansion | UK and Belgian traditional techniques capture premium export positioning through provenance differentiation. |
| Direct Mill Relationship Buildout | Craft breweries in Portland and Seattle bypass distributors to secure lot-level traceability and sustainability storytelling. |
| Carbon Border Adjustment Preparation | Early EU Green Deal compliance investments position maltsters for advantaged transatlantic trade economics. |
Study Parameters
Document review covered malting industry trade publications, EFSA contaminant threshold guidelines, and EU Farm to Fork Strategy implementation documents, complemented by interviews with specialty maltster operations directors, craft brewery purchasing managers, and distillation procurement leads. Secondary validation drew from customs and trade data, brewing industry association reports, and SEC filings from integrated agricultural conglomerates. Bottom-up volume modeling and top-down market sizing triangulated across these inputs.
Output metrics span color grade tiers, brewing scale segments, and geographic production clusters across the analysis window. CAGRs derive from segment-level growth rate blending against macroeconomic baseline assumptions. Industry-specific forecast inputs include craft brewery formation rates in Oregon and Washington, and EFSA acrylamide enforcement trajectory.
The model assumes a particular technology adoption path for precision kilning automation; alternative pathways for manual floor-malting revival would alter the outlook for technician apprenticeship capacity constraints. Forecasts reflect assumptions about EU Green Deal implementation pacing and barley price volatility patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Edible Alcohol Market
Alcoholic Beverages
UK Tequila Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Australia and New Zealand Tequila Market
Alcoholic Beverages
Sparkling Red Wine Market
Alcoholic Beverages
Global Bars and Nightclubs Market
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market
Alcoholic Beverages
Cannabis Drinks Market
Alcoholic Beverages
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market
Alcoholic Beverages
Sparkling Wine Market
Alcoholic Beverages
Barrel Liner Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Fermented Beverages Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Industrial Alcohol Market