
 Floral Tea Market | 2026-2036
Floral Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Floral Tea Market Analytics
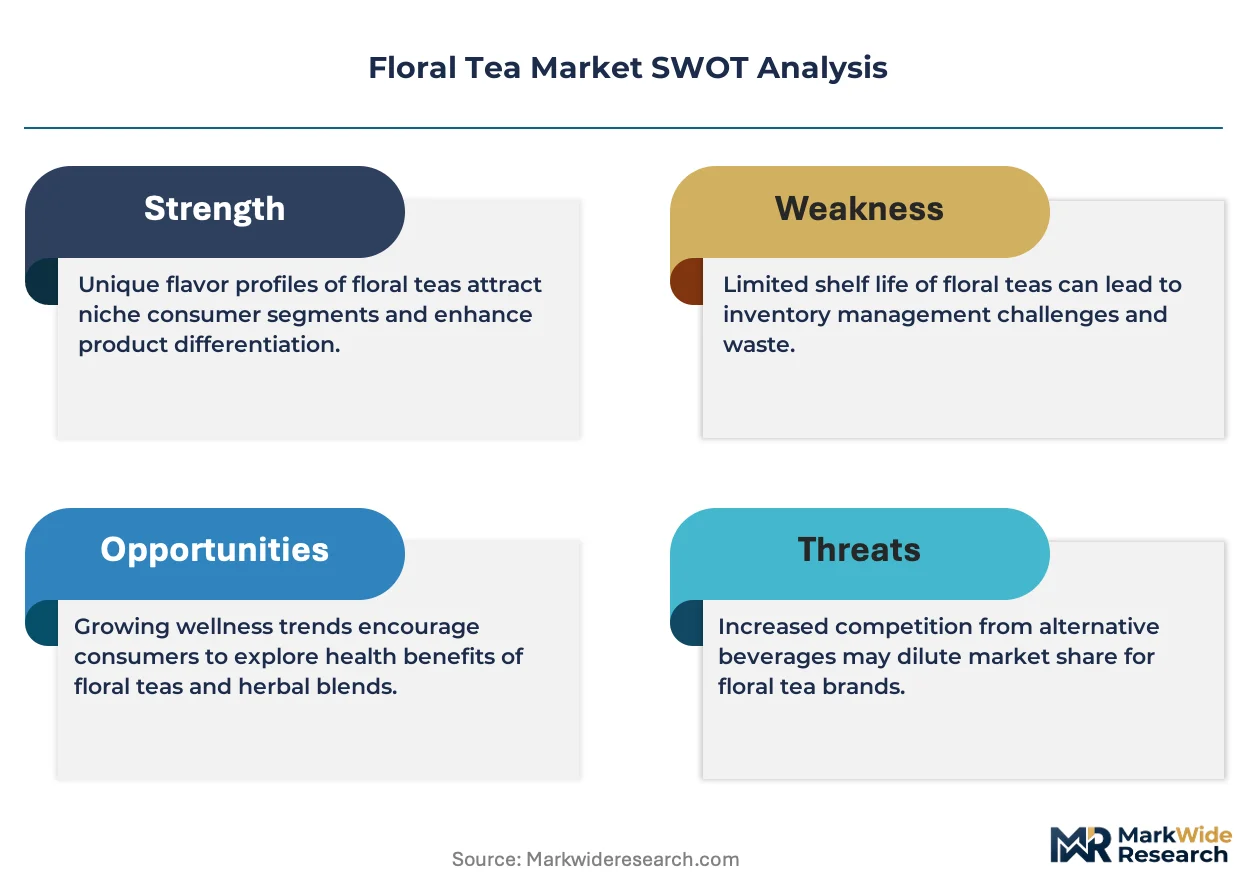
Consolidation among boutique hotel chains and wellness retreat operators is restructuring procurement patterns for premium floral tea. Twinings leverages its century-old blending expertise to sustain contract relationships with European hospitality groups. Harney & Sons anchors its position through direct-to-consumer subscription channels that bypass traditional retail markups. Tazo Tea Company competes by controlling shelf placement in North American grocery multiples with dedicated floral tea planograms.
Floral tea comprises dried flower petals, buds, and calyxes steeped in hot water to extract volatile oils, polyphenols, and anthocyanins, with brewing temperatures typically ranging from 85°C to 100°C depending on botanical species. The primary commercial purpose centers on delivering caffeine-free functional beverages positioned for relaxation, digestive support, and antioxidant intake. Hibiscus dominates volume among product types due to its vivid color and tart flavor profile that blends across sweet and citrusy flavor categories. Pyramid bags capture margin concentration in packaging type as consumers accept price premiums for whole-flower visibility and expanded infusion space. Wellness centers represent the fastest-growing end user segment as spas integrate branded floral tea rituals into service menus.
The FDA governs botanical ingredient labeling under dietary supplement and food additive frameworks, while the EU Green Deal and EFSA novel food assessments constrain new flower introductions into European formulations. China's SAMR enforces GB standards for pesticide residues in dried botanicals exported as tea ingredients, directly shaping supplier qualification requirements for jasmine and chrysanthemum sourcing. India's FSSAI mandates stringent heavy metal testing for imported floral materials, adding compliance layers for chamomile entering through Mumbai and Chennai ports. Stakeholders must monitor evolving botanical novel food rulings across jurisdictions to secure uninterrupted market access for emerging flower varieties.
Market Dynamics
Specialty cafés and wellness retreat operators now consolidate procurement through long-term contracts, compressing spot-market liquidity for premium hibiscus and chamomile grades while elevating supplier qualification barriers.
Growth Catalysts
- EU Green Deal implementation:The EU's updated botanical food supplement directives tighten ingredient sourcing rules, forcing suppliers to upgrade traceability systems and creating first-mover advantages for compliant processors.
- Wellness center channel expansion:Spas in Germany, China, and the United States integrate branded floral tea rituals into service menus, converting beverage costs into premium experience pricing.
- Pyramid bag technology:Whole-flower visibility packaging captures consumer willingness to pay premiums for expanded infusion space and aesthetic presentation.
Market Restraints
- Input cost volatility:Egyptian and Sudanese hibiscus harvest fluctuations transmit directly to blenders through concentrated Nile Delta supply.
- Regulatory friction:EFSA novel food assessments constrain new flower introductions into European formulations, extending time-to-market for emerging botanicals.
- Substitution threat:Functional bottled beverages and adaptogenic coffee alternatives capture convenience-seeking consumers in commuter channels.
Strategic Opportunities
- Underpenetrated wellness tourism:Boutique hotel chains in Portugal and Costa Rica lack established floral tea programs, creating white space for turnkey ritual partnerships.
- Direct-to-consumer channel innovation:Subscription models bypass traditional retail markups and capture recurring revenue with predictable inventory planning.
- Technology convergence:Blockchain traceability combined with cold-chain logistics enables premium positioning for temperature-sensitive whole-flower products.
Industry Challenges
- Certification timeline compression:India's FSSAI heavy metal testing mandates for Mumbai and Chennai port entries extend supplier onboarding cycles.
- Skill gap in botanical grading:Experienced calyx inspectors for hibiscus color and moisture assessment remain scarce relative to expanding procurement volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floral Tea Market |
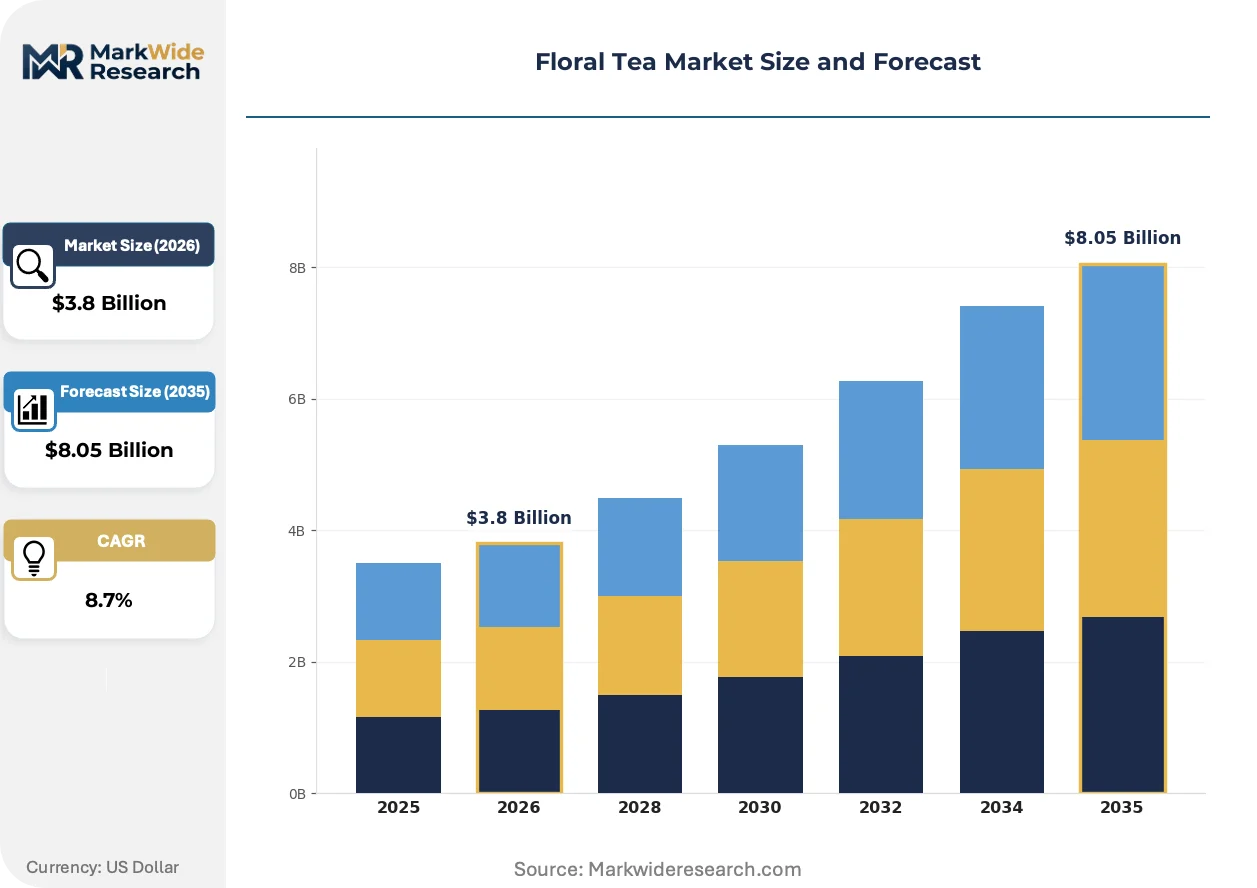
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hibiscus, Chamomile, Lavender, Jasmine Packaging Type: Loose Leaf, Tea Bags, Pyramid Bags, Bulk End User: Retail Consumers, Cafés, Restaurants, Wellness Centers Flavor Profile: Sweet, Floral, Citrusy, Herbal |
| Companies Covered | Twinings, Harney & Sons, Tazo Tea Company, The Republic of Tea, Celestial Seasonings, Bigelow Tea Company, Dilmah, Ahmad Tea, Yogi Tea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floral Tea Market Evolving Landscape
Functional positioning now dominates product development as caffeine-free alternatives displace conventional black tea in afternoon consumption occasions, with brewing ritual and visual aesthetics becoming core differentiators.
Cold-brew floral extraction technology is decentralizing production economics by enabling smaller-batch processing without capital-intensive drying infrastructure. Regional blenders in second-tier Chinese cities adopt these systems to serve local wellness chains. The technology compresses minimum viable scale requirements and fragments supply concentration.
China's SAMR enforcement of GB pesticide residue standards for exported jasmine and chrysanthemum is restructuring supplier qualification protocols. Exporters must maintain dual certification tracks for domestic and international markets. German importers now require third-party laboratory verification beyond official certificates.
Wellness centers now specify branded house blends rather than accepting generic white-label products, reversing prior procurement standardization. This behavior compresses supplier margins while elevating formulation partnerships. The shift is most visible in United States coastal metropolitan markets where spa differentiation intensifies.
Floral Tea Market Segmentation
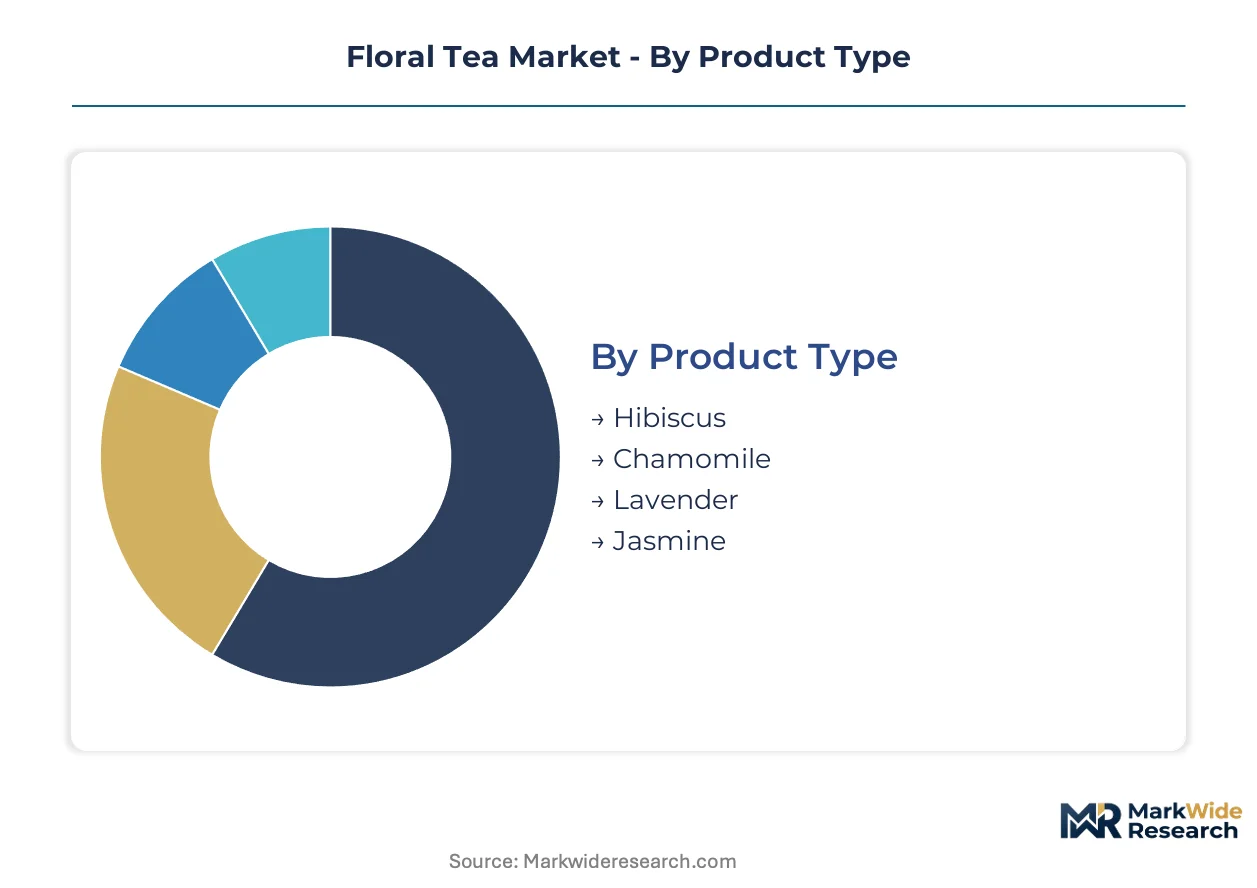
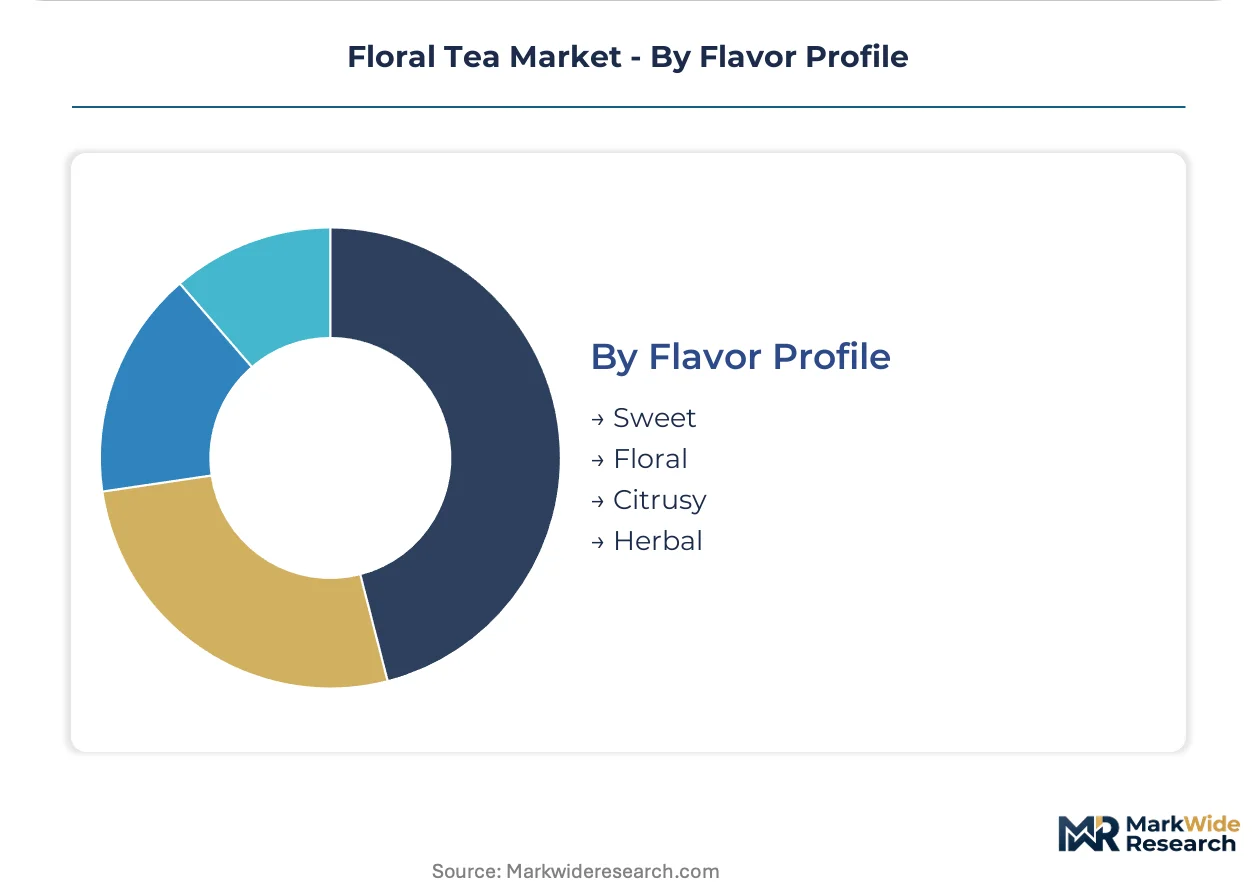
Floral tea segmentation tracks how brewing rituals, visual aesthetics, and functional claims reshape procurement priorities across hospitality and wellness channels. Each dimension reveals distinct margin structures and supplier qualification thresholds.
Product Type:
Upgrade cycles in this category follow shifting antioxidant research and color stability requirements rather than equipment obsolescence.
- Hibiscus:Dried calyxes yield vivid crimson infusions rich in anthocyanins and organic acids. German wellness centers and United States coastal spas now specify Sudanese and Egyptian grades with certified color values above 1.5 absorbance units, tightening supplier pools.
- Chamomile:Matricaria recutita flowers deliver apigenin and bisabolol compounds associated with relaxation positioning. Boutique hotel chains in Portugal and Costa Rica source Roman chamomile for premium ritual menus, diverging from commodity German chamomile.
- Lavender:Lavandula angustifolia buds contribute linalool volatility requiring nitrogen-flushed packaging for shelf stability.
- Jasmine:Scenting green tea bases with Jasminum sambac flowers remains concentrated in Fujian province, with SAMR pesticide residue enforcement restructuring export qualification.
Hibiscus sits at the top of the volume ranking, with chamomile climbing the fastest as wellness center procurement consolidates.
Packaging Type:
Cost tier differentiation separates commodity bulk from experience-driven formats that command shelf placement premiums.
- Pyramid Bags:Nylon mesh structures provide expanded infusion space and whole-flower visibility. United States specialty cafés accept 40-60% price premiums over flat bags for Instagram-compatible brewing aesthetics and faster extraction kinetics.
- Loose Leaf:Unprocessed whole flowers target connoisseur segments with precise temperature control and steeping rituals. German direct-to-consumer subscriptions emphasize origin-labeled loose formats for home brewing authenticity.
- Tea Bags:Standard rectangular paper envelopes dominate grocery multiples through Tazo and Twinings shelf placement contracts.
- Bulk:Foodservice sacks serve restaurant iced tea programs and wellness center back-of-house operations with minimal packaging overhead.
Pyramid bags capture the steepest margin expansion trajectory, while bulk maintains volume leadership in foodservice procurement.
End User:
Customer type fragmentation creates diverging specification requirements between ritual-driven hospitality and convenience-oriented retail.
- Wellness Centers:Spas in Germany, China, and United States metropolitan markets now reject generic white-label products in favor of branded house blends with documented polyphenol content. This behavior elevates formulation partnerships while compressing supplier margins through exclusivity demands.
- Cafés:Specialty coffee chains and independent operators source hibiscus and chamomile for caffeine-free afternoon menu extensions, with brewing equipment compatibility driving format selection.
- Retail Consumers:Supermarket and e-commerce purchasers prioritize convenience and price transparency over origin documentation.
- Restaurants:Full-service and fast-casual operators emphasize consistent color and flavor for iced tea programs with high turnover velocity.
Wellness centers are gaining share fastest, with retail consumers remaining the volume anchor.
Flavor Profile:
Maturity gradients separate established herbal positioning from emerging citrusy blends that attract younger demographics.
- Citrusy:Hibiscus-lemon and bergamot-jasmine combinations target afternoon consumption occasions displacing conventional black tea. Chinese second-tier city blenders deploy cold-extraction technology to preserve volatile citrus notes without heat degradation.
- Floral:Rose, elderflower, and orange blossom positioning dominates premium gifting segments in European pharmacy channels.
- Sweet:Monk fruit and stevia-sweetened blends serve diabetic-conscious and reduced-sugar positioning in United States mass retail.
- Herbal:Traditional single-botanical chamomile and lavender maintains baseline volume through pharmacy and grocery distribution.
Herbal formulations retain volume leadership, with citrusy profiles expanding most quickly through café channel adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Experienced tea blenders and botanical sourcing specialists concentrate in traditional trading hubs and emerging wellness corridors, anchoring regional procurement networks and quality certification systems.
United States
Specialty café chains and coastal wellness retreats in California and New York drive hibiscus and chamomile procurement. FDA dietary supplement labeling frameworks govern botanical ingredient claims, creating compliance thresholds for functional positioning. Miami and Los Angeles spa operators now specify branded house blends with documented polyphenol content, elevating supplier partnership requirements.
Germany
Wellness center chains and pharmacy retail channels anchor European demand for relaxation-positioned floral infusions. EFSA novel food assessments constrain new flower introductions, extending time-to-market for emerging botanicals. Hamburg and Berlin direct-to-consumer subscription services emphasize origin-labeled loose formats, bypassing traditional retail markups through recurring revenue models.
China
Jasmine scenting operations and chrysanthemum processing clusters concentrate in Fujian province and Guangdong province. SAMR enforcement of GB pesticide residue standards restructures supplier qualification for export markets. Second-tier city blenders in Chengdu and Hangzhou deploy cold-extraction technology to serve local wellness chains with smaller-batch capabilities.
India
Import-dependent blenders source chamomile through Mumbai and Chennai ports for domestic wellness and hospitality channels. FSSAI heavy metal testing mandates extend supplier onboarding cycles and elevate laboratory verification requirements. Kerala and Karnataka boutique hotel operators increasingly specify Roman chamomile for premium ritual menus, diverging from commodity German grades.
United Kingdom
Heritage blending houses and specialty retail channels sustain demand for pyramid bag formats with whole-flower visibility. REACH compliance and botanical traceability requirements shape sourcing relationships with Nile Delta hibiscus suppliers. London hospitality groups consolidate procurement through century-old contract relationships, compressing spot-market liquidity for premium grades.
Floral Tea Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered positioning vectors. Twinings leverages century-old blending expertise to sustain hospitality contracts, while Harney & Sons anchors direct-to-consumer channels. Tazo Tea Company controls grocery shelf placement through dedicated planograms. The vendor base fragments across premium gifting, mass retail, and foodservice supply tiers. Dominant competitive moves include subscription model expansion and blockchain traceability partnerships.
Within the heritage blending tier, Twinings and Harney & Sons represent archetypal positioning strategies. Twinings exemplifies contract-based hospitality anchoring through European boutique hotel chains. Harney & Sons occupies a direct-to-consumer specialist position with subscription-driven inventory planning. Tazo Tea Company sits within the grocery retail control archetype, leveraging shelf placement dominance in North American multiples.
| Leading Market Players |
|---|
| Twinings |
| Harney & Sons |
| Tazo Tea Company |
| The Republic of Tea |
| Celestial Seasonings |
| Bigelow Tea Company |
| Dilmah |
| Ahmad Tea |
| Yogi Tea |
| Others |
Value Network & Pricing Analysis
Wellness center chains in Germany and United States coastal markets now consolidate procurement through annual contracts, compressing spot-market premiums for Egyptian hibiscus while elevating subscription-based pricing for branded house blends with documented polyphenol content.
Pricing Analysis
Service bundling separates ritual-experience pricing from commodity ingredient costs. Pyramid bag formats command 40-60% premiums over flat bags through Instagram-compatible aesthetics and faster extraction kinetics. Price differentiation rests on color-grade certification and nitrogen-flushed packaging for volatile preservation. Cost compression in bulk foodservice tiers is intensifying as Egyptian harvest volatility transmits directly to blenders. Retail consumers exhibit highest price sensitivity, while wellness centers accept premiums for exclusivity and origin documentation.
Supply Chain Analysis
Regional distribution centers in Hamburg, Dubai, and Singapore anchor hub-and-spoke patterns for temperature-sensitive whole-flower products. Raw material sourcing draws from Egyptian and Sudanese hibiscus calyxes, Fujian jasmine scenting operations, and German chamomile processing clusters. Single-source vulnerability concentrates in Nile Delta hibiscus harvests exposed to climate fluctuation. Downstream distribution runs through direct-to-consumer subscription channels and hospitality contract networks, bypassing traditional retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in floral tea hinges on cold-extraction technology adoption that compresses minimum viable scale requirements while enabling premium positioning for volatile-preservation capabilities.
For Market Incumbents: Deepen backward integration into Egyptian and Sudanese calyx sourcing to secure color-grade certification above 1.5 absorbance units. Invest in blockchain traceability partnerships to defend against emerging cold-extraction specialists in Chinese second-tier cities. Prioritize nitrogen-flushed packaging capacity to serve wellness center exclusivity demands. For New Entrants and Emerging Players: Begin with turnkey ritual partnerships for boutique hotel chains in Portugal and Costa Rica that lack established floral tea programs. Target United States coastal spa operators seeking branded house blends with polyphenol documentation. Deploy direct-to-consumer subscription models to bypass retail shelf placement barriers controlled by incumbents. For Investors and Strategic Acquirers: Wellness hospitality groups are the most active acquirer in this space, seeking formulation capabilities to differentiate spa experience pricing. Long-term viability favors processors with dual certification tracks for China's SAMR GB standards and EU EFSA novel food pathways. Monitor EFSA botanical novel food ruling velocity as inflection indicator for emerging flower variety market access.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Extraction Technology Deployment | Second-tier Chinese blenders in Chengdu and Hangzhou adopt decentralized processing without capital-intensive drying infrastructure. |
| Blockchain Traceability Partnership | German importers now require third-party laboratory verification beyond official SAMR certificates for jasmine sourcing. |
| Direct-to-Consumer Subscription Launch | Harney & Sons anchors recurring revenue models that bypass traditional retail markups through inventory planning predictability. |
| Branded House Blend Formulation | United States coastal spas reject generic white-label products, elevating supplier partnership requirements while compressing margins. |
| Nitrogen-Flushed Packaging Scale-Up | Lavender processors invest in shelf-stability technology to preserve linalool volatility for premium gifting segments. |
Research Methodology
Multiple input streams — procurement directors at German wellness center chains, blending specialists at Fujian jasmine scenting operations, and category buyers at United States specialty café groups — were reconciled against customs records for dried botanical trade flows, EFSA novel food assessment databases, and FSSAI heavy metal testing protocols. Bottom-up volume modeling across product type, packaging format, and end-user channels was cross-validated with top-down expenditure estimates from hospitality procurement surveys.
Historical trade volume patterns were cross-referenced against panel input from Egyptian hibiscus exporters and Sudanese calyx inspectors to derive expansion rates across the projection horizon. Segmentation dimensions modeled include botanical species, packaging technology tier, distribution channel archetype, and regional regulatory cluster. CAGRs were computed from reconciled baseline estimates and stakeholder-informed adoption curves for cold-extraction systems and subscription channel penetration.
Several conditions sit outside the modeled scope, including unforeseen EFSA novel food rulings for emerging flower varieties and extreme climate events disrupting Nile Delta harvest cycles. Forecasts reflect documented assumptions regarding wellness tourism recovery trajectories and SAMR enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Tea Pitchers Market
Tea
Smart Tea Set Market
Tea
Plant Based New Tea Drink Market
Tea
New Style Tea Drink Market
Tea
Matcha Market
Tea
Bottled Tea Market
Tea
Tea Essence Market
Tea
Global Tea Extract Market
Tea
Nitro Tea Market
Tea
Pu-Erh Tea Market
Tea
Green Tea Market
Tea
Europe Green Tea Market
Tea
Probiotic Tea Market
Tea
Asia-Pacific Green Tea Market
Tea
Europe Ready-To-Drink Tea Market
Tea
Tea Polyphenols Market