
 Beer Pasteurization Equipment Market | 2026-2036
Beer Pasteurization Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Pasteurization Equipment Market Outlook
Craft brewing's share of equipment procurement is rebalancing as contract brewers scale pasteurization investments for distributed brands. GEA Group leverages its thermal engineering heritage across European brewery installations. Alfa Laval anchors flash pasteurization systems for mid-size facilities seeking energy recovery. Krones AG dominates turnkey bottling lines with integrated tunnel pasteurization modules.
Beer pasteurization equipment encompasses heat exchange systems that raise packaged or unpackaged beer to precise temperatures, typically holding at 60-70°C for defined intervals to eliminate spoilage organisms while preserving flavor stability. Continuous pasteurizers achieve higher throughput with lower thermal degradation than batch configurations, making them standard for lager production lines. Flash pasteurization systems command premium positioning among ale producers prioritizing sensory preservation, while tunnel pasteurizers occupy the volume tier serving mainstream lager bottling operations across large beverage producers.
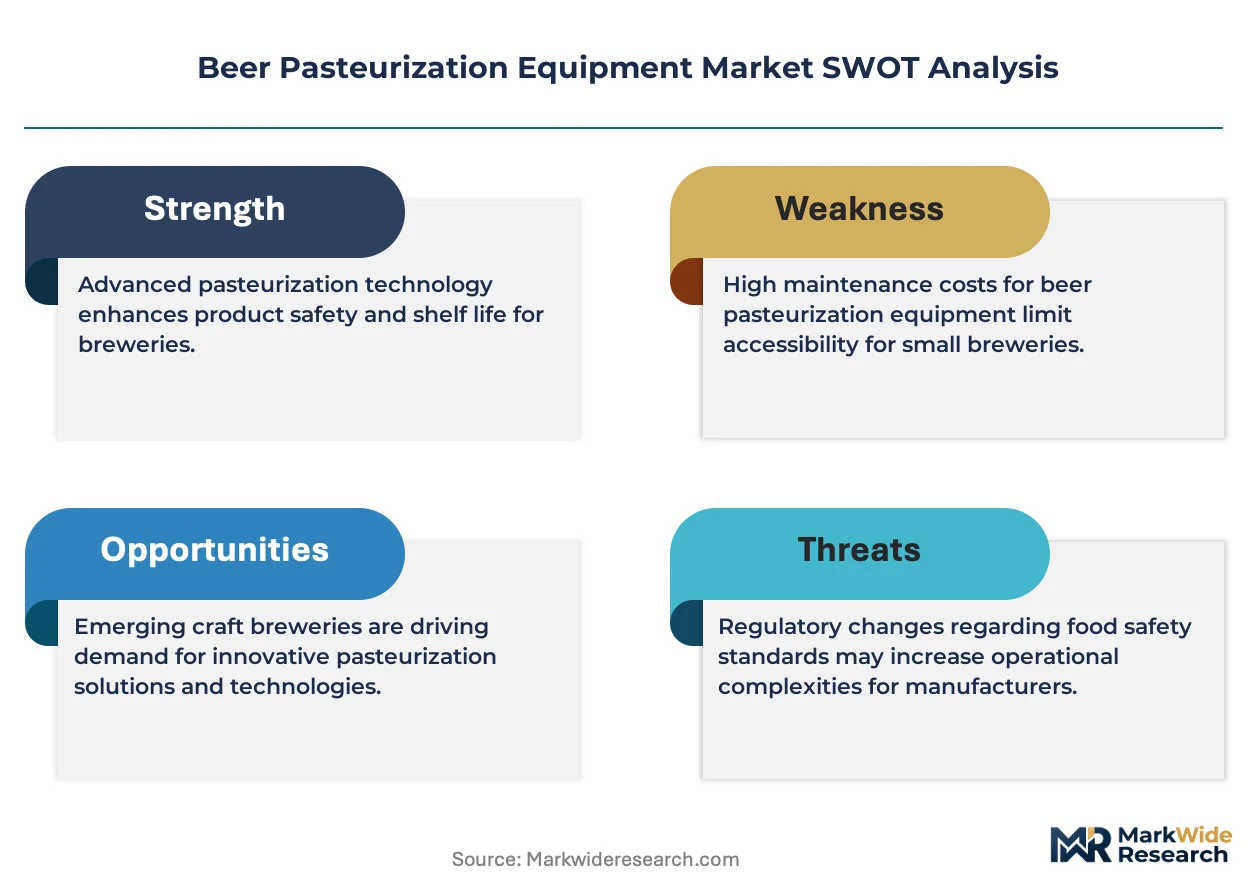
Germany's KBA enforces machinery safety standards affecting pasteurizer construction, while the EU F-Gas Regulation constrains refrigerant choices in cooling-integrated systems. The EU Green Deal's energy efficiency benchmarks push breweries toward heat-recovery pasteurization designs. Stakeholders must weigh cold pasteurization alternatives against thermal system upgrades as regulatory thresholds tighten and utility costs reshape operating economics.
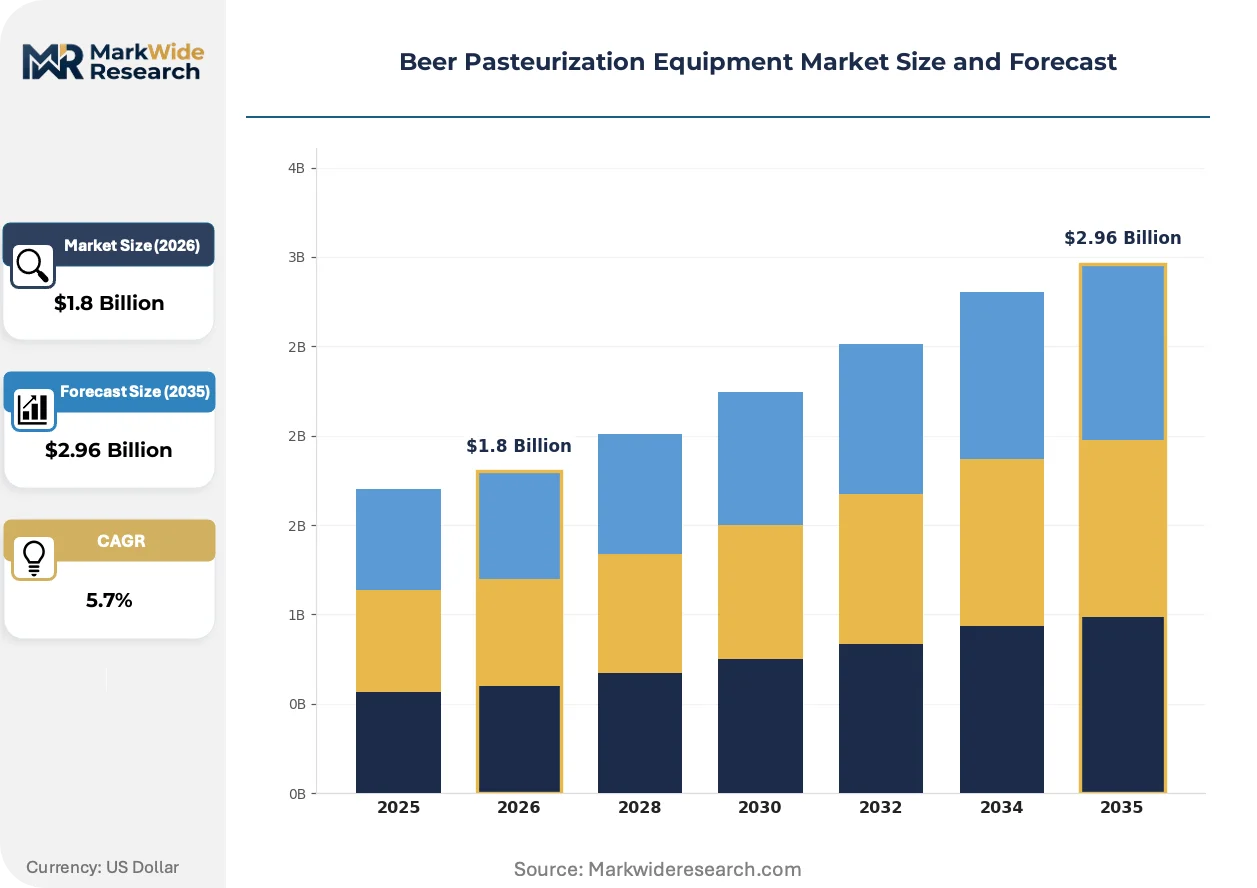
Market Dynamics
Energy recovery mandates from the EU Green Deal are forcing breweries to retire legacy pasteurizers and adopt heat-recovery tunnel systems, compressing replacement cycles from fifteen to eight years.
Growth Catalysts
- Craft brewery consolidation:Contract brewers in Germany and Belgium are pooling capital for shared pasteurization facilities, spreading fixed costs across distributed brand portfolios.
- F-Gas Regulation:The EU's phasedown of hydrofluorocarbon refrigerants is accelerating upgrades to ammonia-based cooling-integrated pasteurizers with superior thermal efficiency.
- Flash pasteurization:Ale producers seeking sensory differentiation are prioritizing continuous flow systems that minimize thermal degradation compared to tunnel configurations.
Market Restraints
- Stainless steel price volatility:Heat exchanger fabrication depends on nickel-alloy grades whose commodity swings compress equipment margins unpredictably.
- German supplier concentration:Tunnel pasteurizer component sourcing clusters around Bavarian metalworking clusters, creating vulnerability to regional labor disruptions.
- Cold pasteurization substitution:Membrane filtration and UV systems are capturing niche applications where thermal processing risks flavor compromise.
Strategic Opportunities
- Eastern European craft expansion:Polish and Czech microbreweries lack pasteurization capacity, creating first-mover advantage for modular flash system providers.
- Heat pump integration:Pasteurizers are converging with industrial heat pumps to satisfy EU Green Deal efficiency benchmarks while qualifying for national retrofit subsidies.
- Service unbundling:Predictive maintenance contracts and remote thermal monitoring are opening recurring revenue streams separate from equipment sales.
Industry Challenges
- Thermal engineering talent scarcity:Breweries struggle to hire technicians capable of calibrating continuous pasteurizer temperature profiles across variable batch sizes.
- Legacy system integration:Retrofitting heat-recovery modules into existing tunnel lines requires custom piping fabrication that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Pasteurization Equipment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Pasteurizers, Continuous Pasteurizers, Tunnel Pasteurizers, Plate Pasteurizers Technology: Thermal Pasteurization, Flash Pasteurization, Cold Pasteurization, Microwave Pasteurization End User: Brewery, Beverage Producer, Contract Brewer, Importer Application: Ale, Lager, Stout, Specialty Beers |
| Companies Covered | Krones AG, GEA Group, Alfa Laval, SPX FLOW, KHS GmbH, JBT Corporation, Paul Mueller Company, Ziemann Holvrieka, Feldmeier Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Pasteurization Equipment Market Strategic Shifts
Pasteurization technology is bifurcating between energy-intensive volume systems for mainstream lagers and precision thermal tools for craft sensory preservation, with digital controls bridging both paths.
Plate heat exchangers with laser-welded cassettes are converging with variable-speed pumps to enable real-time temperature modulation during continuous pasteurization. Mid-size Belgian and Dutch ale breweries are adopting these configurations within two-year capital cycles. The technology is converging with brewery management software to automate hold-time compliance and generate audit trails for EFSA food safety documentation.
The EU F-Gas Regulation's refrigerant phase-down is mandating ammonia or CO2 secondary cooling circuits in new pasteurizer installations. Equipment fabricators in Germany must redesign condenser architectures to accommodate these working fluids. Large beverage producers with pan-European bottling networks are consolidating procurement specifications to ensure cross-border spare parts compatibility under the new thermal standards.
Brewery procurement departments are unbundling pasteurizer purchases from turnkey bottling line contracts, issuing separate RFPs for thermal modules. This fragmentation favors specialized heat exchange vendors over integrated line suppliers. The shift is most pronounced in Germany's Mittelstand brewery sector, where technical teams demand direct specification control over pasteurization parameters independent of conveyor system vendors.
Beer Pasteurization Equipment Market Segmentation
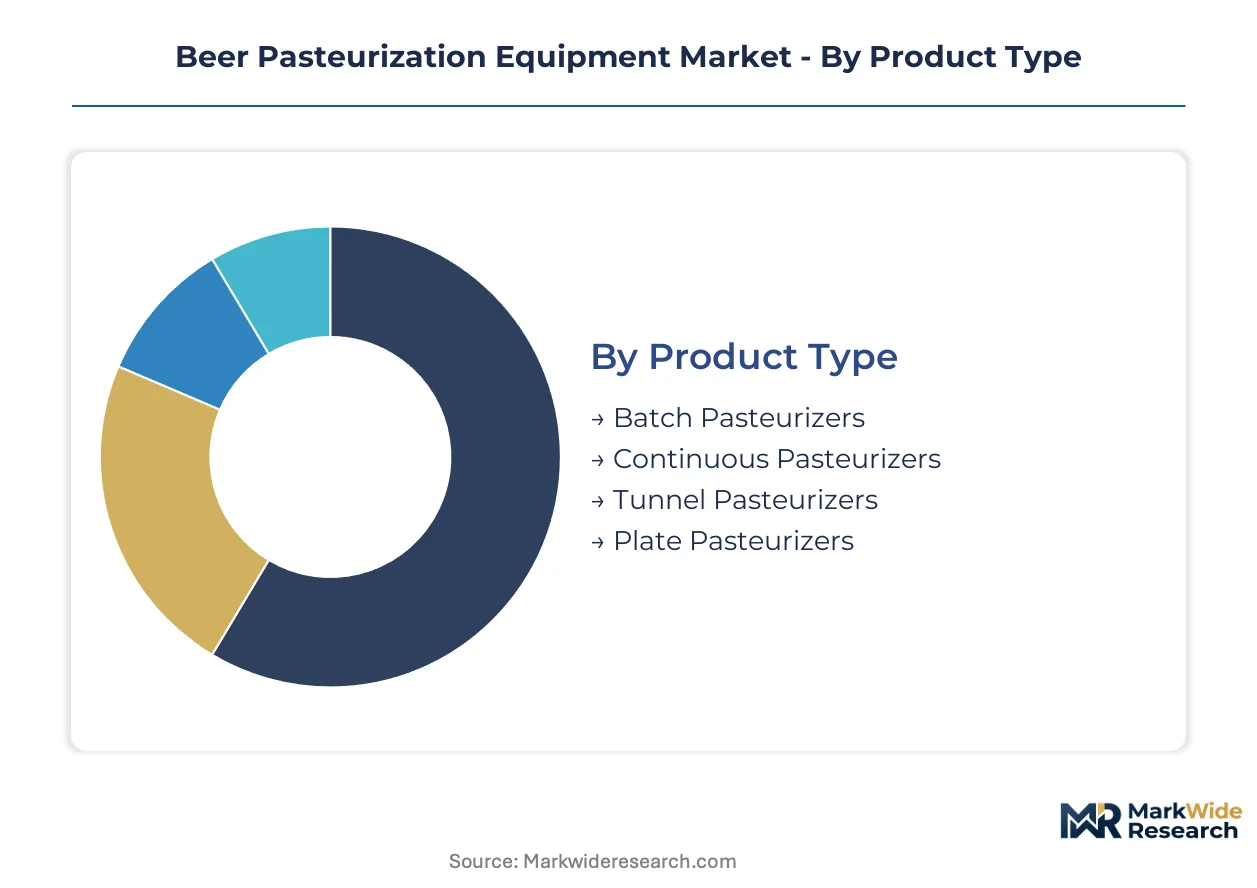
Equipment segmentation in beer pasteurization reflects divergent thermal strategies between mass-market lager operations and craft ale producers. Technology choices cascade into facility layout, energy recovery potential, and regulatory compliance pathways across brewery scales.
Product Type:
Standalone pasteurizers dominate craft installations while embedded tunnel systems anchor integrated bottling lines at large beverage producers.
- Batch Pasteurizers:Chamber-style units process packaged bottles or cans through timed heating and cooling cycles. Demand clusters at Belgian contract brewers serving distributed craft brands where flexibility outweighs throughput requirements. Energy recovery retrofit compatibility remains limited compared to continuous alternatives.
- Continuous Pasteurizers:Plate heat exchanger systems move unpackaged beer through controlled temperature zones without interruption. German Mittelstand breweries favor these configurations for lager production lines requiring EFSA-compliant hold-time documentation. Heat pump integration potential satisfies EU Green Deal efficiency benchmarks.
- Tunnel Pasteurizers:Conveyor-integrated spray systems treat sealed containers moving through graduated temperature baths. Large beverage producers specify these for high-volume lager bottling operations.
- Plate Pasteurizers:Compact heat exchange units suit microbreweries with space-constrained production floors. Polish craft breweries adopt these for modular capacity expansion.
Volume placements concentrate in Tunnel Pasteurizers; the faster expansion belongs to Continuous Pasteurizers.
Technology:
Cost tier stratification separates premium precision systems from standardized thermal processing infrastructure.
- Thermal Pasteurization:Conventional heating systems using steam or hot water as thermal media represent the baseline technology category. Established lager producers across Bavaria deploy these for predictable spoilage organism elimination.
- Flash Pasteurization:Ultra-rapid heat exchange achieves pasteurization temperatures for seconds rather than minutes, preserving volatile aromatic compounds. Dutch ale specialists prioritize these systems for sensory-critical specialty releases where thermal degradation risks brand differentiation. Equipment premiums reflect precision engineering requirements.
- Cold Pasteurization:Membrane filtration and UV treatment eliminate thermal exposure entirely. Czech microbreweries experimenting with unpasteurized positioning adopt these for niche export markets.
- Microwave Pasteurization:Electromagnetic heating enables rapid volumetric temperature rise with reduced thermal lag. Experimental deployments at German research breweries test integration feasibility.
Capital deployment concentrates in Thermal Pasteurization; steepest expansion trajectory belongs to Flash Pasteurization.
End User:
Customer type determines procurement sophistication and service contract attachment rates.
- Brewery:Owner-operated production facilities span multinational lager conglomerates to single-site craft producers. German family-owned breweries represent the core equipment replacement cycle as EU F-Gas Regulation deadlines approach.
- Beverage Producer:Diversified drinks companies operate beer as one category among bottled water, soft drinks, and alcoholic alternatives. These buyers consolidate pasteurizer specifications across pan-European bottling networks to ensure spare parts interoperability.
- Contract Brewer:Third-party production facilities manufacture beer for brand owners without owned brewing capacity. Belgian and Dutch contract operators are pooling capital for shared pasteurization infrastructure.
- Importer:Distribution-focused entities requiring pasteurization for quality assurance of inbound beer shipments. These users favor compact batch systems for warehouse integration.
Procurement volume concentrates in Brewery; Contract Brewer is climbing the fastest as brand-asset-light models proliferate.
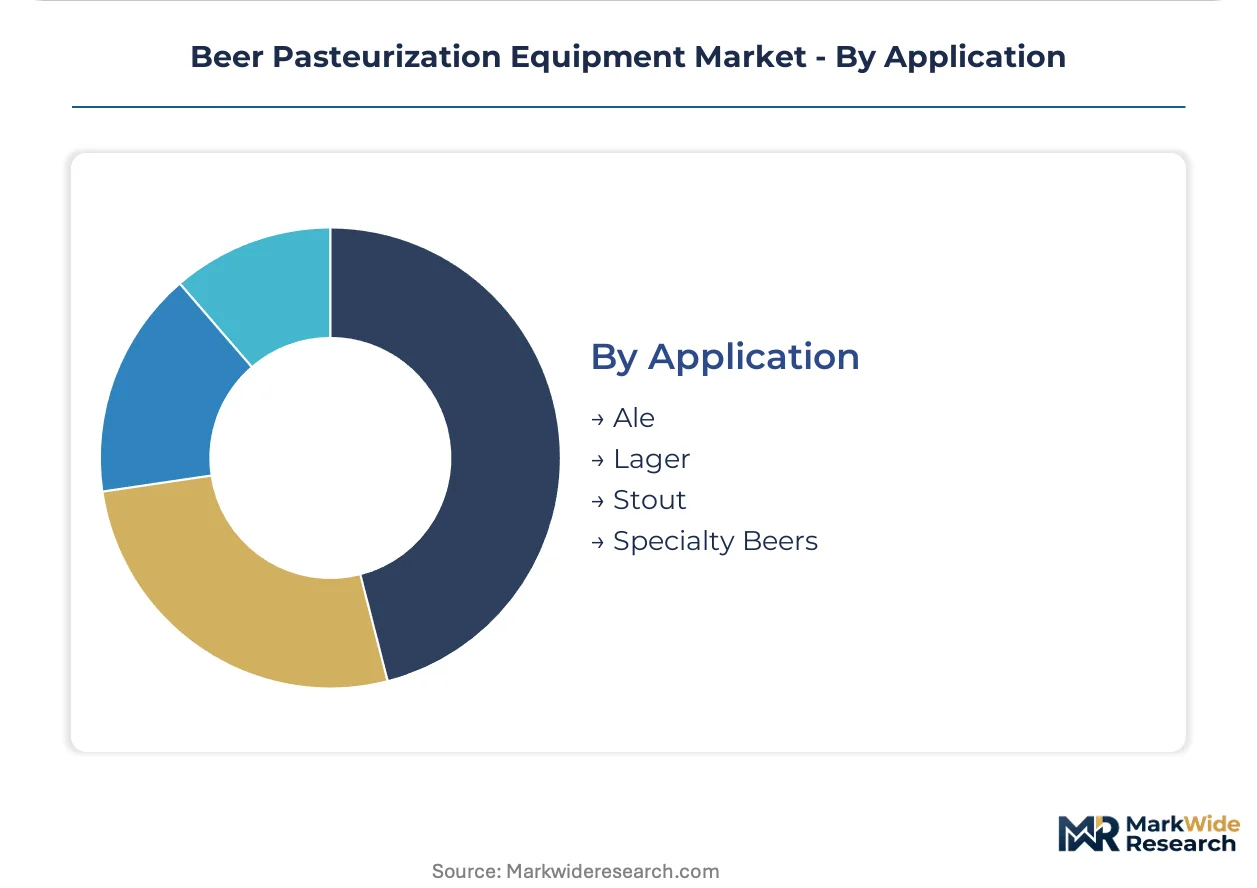
Application:
Beer style determines pasteurization intensity requirements and thermal sensitivity thresholds.
- Ale:Top-fermented beers with complex ester profiles demand minimal thermal exposure to preserve sensory character. Flash pasteurization adoption concentrates at UK and Belgian ale specialists.
- Lager:Bottom-fermented styles tolerate higher thermal loads without flavor degradation. Tunnel pasteurizer installations dominate this category across German and Czech production bases.
- Stout:Dark roasted malt beers present viscosity challenges for heat exchange efficiency. Irish and UK producers specify modified plate configurations.
- Specialty Beers:Barrel-aged, sour, or adjunct-enhanced styles with non-standard microbiological profiles. Pasteurization decisions vary by stability requirements and distribution radius.
Equipment base concentrates in Lager; Specialty Beers are gaining share fastest as craft portfolio diversification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Mittelstand brewery belt operates as the primary tax-advantaged zone for equipment investment, with EU cohesion funds channeling modernization grants into Bavarian and Baden-Württemberg production clusters.
Germany
Bavarian family breweries and North Rhine-Westphalian beverage conglomerates drive tunnel pasteurizer replacement cycles. The EU F-Gas Regulation forces ammonia-based cooling retrofits by 2027. Munich's metalworking corridor supplies heat exchanger components to Mittelstand fabricators upgrading for EFSA compliance.
Belgium
Contract brewers in Flanders and Wallonia pool capital for shared flash pasteurization facilities serving distributed craft brands. REACH chemical safety protocols constrain heat transfer fluid selections. Antwerp's port logistics cluster enables just-in-time stainless steel delivery for modular equipment assembly.
Netherlands
Ale specialists in South Holland prioritize continuous flow systems for sensory preservation in specialty releases. The EU Green Deal's energy efficiency benchmarks mandate heat pump integration. Eindhoven's thermal engineering hub supports digital control system development for precision pasteurization.
Czech Republic
Plzeň and Prague microbreweries lack pasteurization capacity for export market expansion. National food safety regulators align with EFSA thermal processing standards. The Bohemian brewing corridor attracts modular plate pasteurizer vendors targeting first-mover craft installations.
Poland
Warsaw and Kraków craft breweries adopt compact heat exchange units for space-constrained production floors. EU structural funds subsidize energy recovery equipment for regional beverage producers. Silesian manufacturing zones fabricate standardized tunnel components for Eastern European distribution networks.
Beer Pasteurization Equipment Market Competitive Environment
Top-tier vendors anchor integrated bottling line supply, while specialized heat exchange fabricators occupy mid-market positions serving unbundled procurement trends. The vendor base stratifies across three tiers: turnkey system integrators, modular thermal specialists, and regional component suppliers. Strategic archetypes include engineering heritage conglomerates, precision thermal technology developers, and craft-focused niche configurators. Competitive moves concentrate on heat-recovery technology licensing and predictive maintenance service unbundling.
Among German engineering conglomerates, Krones AG and GEA Group represent the integrated system tier, anchoring turnkey installations across European beverage networks. Alfa Laval exemplifies the precision thermal specialist archetype, with flash pasteurization positioning aligned to craft sensory requirements. These three occupy positions reflecting divergent strategic bets: scale-driven line integration versus modular precision engineering versus heat exchange component specialization.
| Leading Market Players |
|---|
| Krones AG |
| GEA Group |
| Alfa Laval |
| SPX FLOW |
| KHS GmbH |
| JBT Corporation |
| Paul Mueller Company |
| Ziemann Holvrieka |
| Feldmeier Equipment |
| Others |
Value Chain & Pricing Dynamics
Flash pasteurization's precision engineering requirements are compressing equipment margins while concentrating procurement power among specialized thermal fabricators in Germany and the Netherlands. Heat-recovery system mandates from the EU Green Deal simultaneously elevate upfront capital requirements and reshape supplier qualification criteria across the European brewing corridor.
Pricing Analysis
Lead-time premiums command substantial markups in flash pasteurization systems where Belgian and Dutch ale specialists require sub-six-month delivery for seasonal release scheduling. Contract-based long-term procurement dominates tunnel pasteurizer transactions as large beverage producers consolidate specifications across pan-European bottling networks. Price differentiation rests on certification tier and after-sales service bundling, with EFSA-compliant documentation packages carrying material premiums. Stainless steel commodity volatility is intensifying cost compression in standard thermal configurations, while craft breweries demonstrate highest price sensitivity against multinational lager producers with captive maintenance infrastructure.
Supply Chain Analysis
Regional distribution centers in Bavaria and Baden-Württemberg anchor hub-and-spoke patterns for heat exchanger components serving Mittelstand fabricators. Manufacturing concentration clusters in Germany, Belgium, and Poland, with Munich's metalworking corridor supplying laser-welded plate cassettes and Silesian zones fabricating standardized tunnel modules. Nickel-alloy grades and ammonia-based cooling circuits constitute critical input dependencies. Single-source vulnerability in Bavarian precision machining creates exposure to regional labor disruptions. Distribution runs through brewery management software integrators who bundle thermal modules with digital control packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The beer pasteurization equipment market is accelerating into a vertical-integration race where control over heat-recovery technology licensing and predictive maintenance software determines margin capture. Players are pursuing downstream service unbundling to escape equipment commoditization.
For Market Incumbents: Deepen captive supply relationships with Bavarian metalworking clusters to secure heat exchanger component allocation during nickel-alloy price spikes. Incumbents must consolidate predictive maintenance platforms before specialized thermal vendors capture recurring revenue streams from craft brewery installations. Cold pasteurization substitution in Czech microbreweries threatens thermal system replacement cycles, requiring accelerated heat pump integration roadmaps to defend positioning against membrane filtration alternatives.
For New Entrants and Emerging Players: The premium-to-economy tier gap in continuous pasteurizers offers white-space entry for modular plate configurations targeting Polish and Czech craft breweries with space-constrained production floors. First-mover positioning in Eastern European contract brewing infrastructure represents the most penetrable geography, with shared flash pasteurization facilities spreading fixed costs across distributed brand portfolios. Go-to-market execution should anchor on brewery management software partnerships that embed thermal control modules within digital transformation roadmaps.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated bottling line suppliers seeking thermal engineering capabilities. Long-term viability across the projection horizon favors precision thermal specialists with ammonia-compatible cooling architectures and EFSA compliance documentation expertise. Acquisition targets should demonstrate installed base density in Germany's Mittelstand brewery belt with attachable predictive maintenance contracts. The signal to watch is EU F-Gas Regulation enforcement intensity accelerating replacement cycle compression from fifteen to eight years.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Integration | EU Green Deal compliance unlocks national retrofit subsidies for Bavarian brewery upgrades. |
| Predictive Maintenance Unbundling | Remote thermal monitoring contracts generate recurring revenue separate from equipment sales cycles. |
| Ammonia Cooling Retrofit | F-Gas Regulation deadlines force cooling architecture redesigns across German installations. |
| Flash System Modularization | Compact configurations penetrate Polish craft breweries lacking pasteurization capacity for export expansion. |
| Software Platform Integration | Brewery management system partnerships embed pasteurization controls within digital audit trail automation. |
Study Parameters
Independent corroboration across equipment procurement directors, thermal engineering specialists, and regulatory compliance officers underwrites the qualitative findings in this study. Primary interviews with brewery operations managers, contract brewing facility owners, and aftermarket service heads were validated against secondary sources including EFSA thermal processing guidelines, EU F-Gas Regulation implementation documents, and KBA machinery safety standards. Customs records for stainless steel alloy imports and trade association capacity surveys provided demand-side triangulation. Bottom-up equipment shipment data and top-down beverage production volume analysis were reconciled to establish market sizing boundaries.
Rate-of-change decomposition across the analysis window separates volume effects from mix shifts and price evolution in pasteurization technology categories. The analytical framework models segmentation dimensions including equipment type, thermal technology tier, end-user archetype, and beer style application, with geographic regulatory clusters capturing EU Green Deal implementation variance. CAGRs were derived from installed base replacement cycles and craft brewery formation rates, with heat-recovery adoption curves and F-Gas compliance deadlines as industry-specific forecast inputs.
Inputs from primary fieldwork and regulatory filing databases were available through the study window; gaps in real-time stainless steel commodity pricing and contract brewer capital commitment timelines introduce uncertainty bands around equipment procurement forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
West Africa Alcoholic Beverages Market
Alcoholic Beverages
Roasted Malt Market
Alcoholic Beverages
Beer Cans Market
Alcoholic Beverages
Germany Alcohol E-Commerce Market
Alcoholic Beverages
Asia-Pacific Kegs Market
Alcoholic Beverages
Home Brewing Systems Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
United States Spirits Market
Alcoholic Beverages
Puncheon Barrel Market
Alcoholic Beverages
Commercial Beer Tap System Market
Alcoholic Beverages
Beer Line Cleaning Kit Market
Alcoholic Beverages
Luzhou-Flavor Liquor Market
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
American Oak Barrels Market
Alcoholic Beverages
Low-Alcohol Beer Market