
 Coffee Beer Market | 2026-2036
Coffee Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Beer Market Analytics
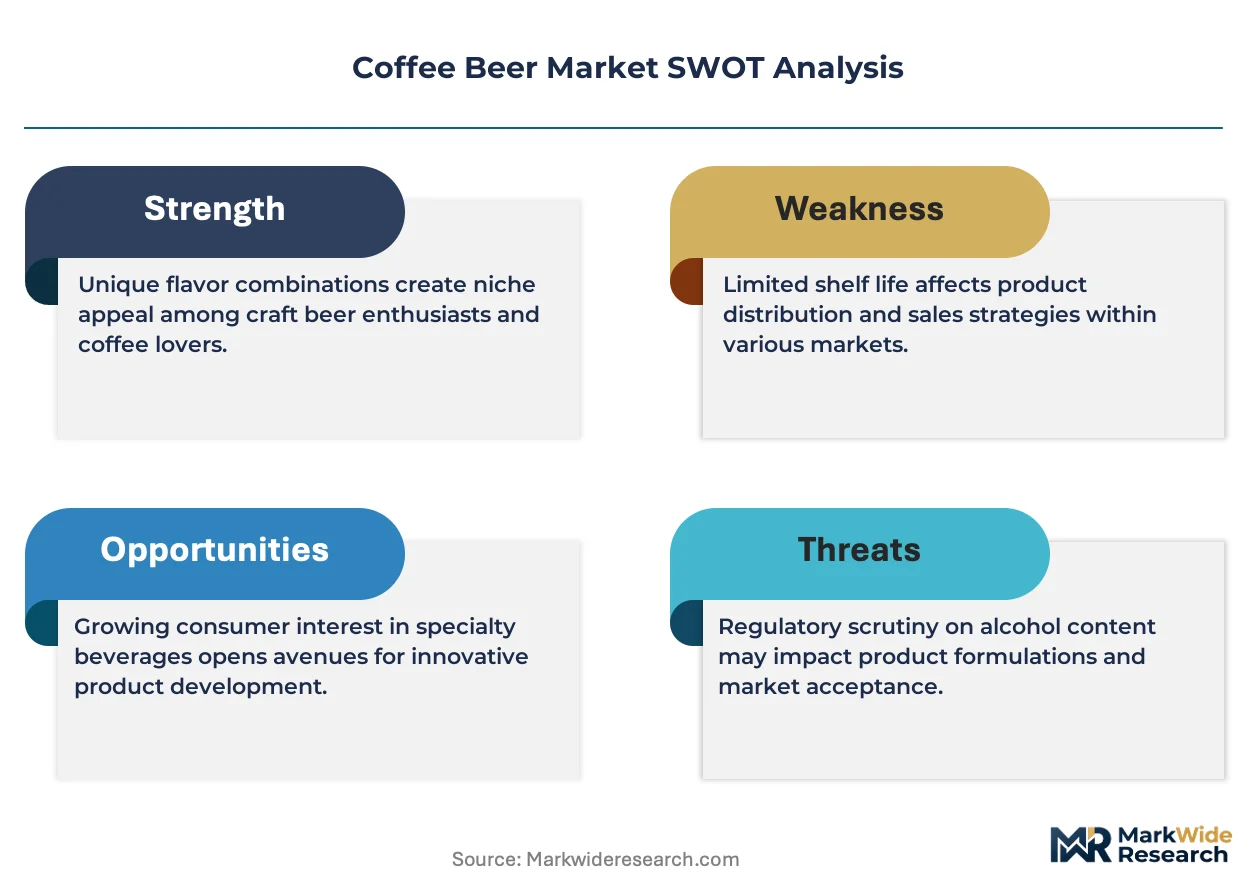
Craft brewery taprooms is recalibrating the channel mix for coffee beer, pulling volume away from conventional off-premise retail as on-site experiential consumption rebounds. Anheuser-Busch InBev leverages its vast distribution infrastructure to secure shelf placement for coffee-infused variants in mainstream retail. Stone Brewing differentiates through aggressive R&D intensity in barrel-aged coffee stout programs. Sierra Nevada Brewing Co. anchors its position with sustained investment in sustainable sourcing partnerships for coffee bean procurement.
Coffee beer denotes an alcoholic beverage produced through fermentation of malted grains with integrated coffee components, typically achieving alcohol by volume of 4% to 12% depending on base style and brewing approach. The primary commercial purpose centers on capturing crossover consumers seeking roasted, bitter flavor complexity beyond traditional hop profiles. Stout and porter styles dominate volume due to inherent compatibility with dark roast coffee characteristics, while nitro brewing methods command premium positioning through enhanced mouthfeel differentiation. Cold brew infusion techniques represent the fastest-growing preparation category as producers pursue smoother extraction profiles and reduced astringency.
The U.S. Alcohol and Tobacco Tax and Trade Bureau governs formula approval for coffee beer products, creating compliance thresholds that favor established brewers with regulatory affairs capacity. The FDA's Generally Recognized as Safe determinations for caffeine additives influence formulation ceilings and labeling obligations across interstate commerce. The European Food Safety Authority evaluates novel ingredient combinations under EU food law, affecting import eligibility for U.S.-produced coffee beer entering continental markets. Stakeholders must monitor evolving caffeine disclosure mandates and state-level distribution restrictions that could reshape channel economics.
Market Dynamics
Cold brew infusion techniques are compressing production cycles while nitro brewing methods command premium positioning through mouthfeel differentiation. These technical advances intersect with tightening caffeine disclosure mandates from the U.S. FDA and EFSA, forcing formulation recalibration across export portfolios.
Growth Catalysts
- Third-wave coffee culture:Specialty roasters in Germany and the Pacific Northwest are driving ingredient co-development with craft breweries. This collaboration expands the addressable consumer base beyond traditional beer drinkers.
- Barrel-aging infrastructure:Expanded oak cask programs enable extended maturation protocols that integrate coffee extraction with spirit character. The technique supports price architecture in the super-premium tier.
- EFSA novel ingredient pathways:Streamlined evaluation procedures for coffee-derived additives reduce time-to-market for European distribution. Brewers leverage this regulatory clarity to scale cross-border formulations.
Market Restraints
- Arabica price volatility:Climate-induced harvest variability in Colombia and Ethiopia transmits directly to input cost structures. Smaller craft operators lack hedging capacity against commodity swings.
- TTB formula approval timelines:The U.S. Alcohol and Tobacco Tax and Trade Bureau's review queues create 90-180 day delays for new product introductions. This friction favors established brewers with dedicated regulatory affairs staff.
- Non-alcoholic coffee alternatives:Sophisticated cold brew and nitro coffee products without alcohol capture similar flavor-seeking occasions. These substitutes erode trial rates among health-conscious demographics.
Strategic Opportunities
- Japan's craft beer liberalization:METI licensing reforms opened the domestic market to small-batch imports. Japanese consumers demonstrate high willingness-to-pay for barrel-aged variants with origin-specific coffee provenance.
- Direct-to-consumer subscription channels:Brewery-owned membership programs bypass three-tier distribution economics. These platforms capture full margin while building recurring revenue predictability.
- CSRD supply chain disclosure:The EU Corporate Sustainability Reporting Directive creates competitive advantage for brewers with verified sustainable sourcing. Early compliance positions brands for institutional procurement channels.
Industry Challenges
- Cold chain integrity:Nitro coffee beer requires maintained refrigeration through last-mile delivery. Distributor capability gaps in secondary markets limit geographic expansion.
- Cross-functional formulation expertise:Brewing teams lack coffee roasting knowledge, while coffee partners misunderstand alcohol fermentation constraints. Joint training programs remain underdeveloped.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Beer Market |
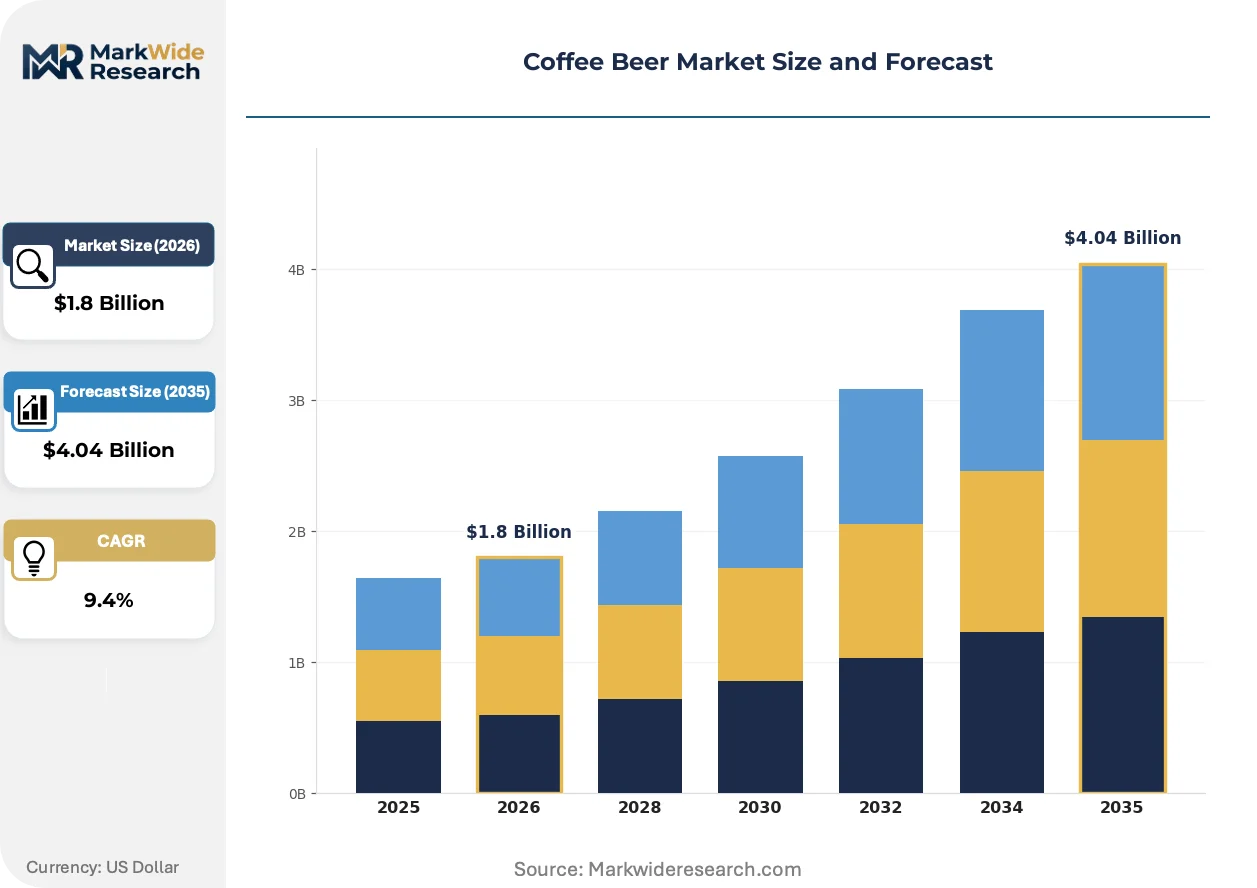
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stout, Porter, Lager, Ale Flavor Profile: Nutty, Chocolate, Dry, Sweet Brewing Method: Cold Brew, Hot Brew, Nitro, Infusion Packaging Type: Can, Bottle, Keg, Draft |
| Companies Covered | Anheuser-Busch InBev, Carlsberg Group, Heineken N.V., Diageo, Samuel Adams, Erdinger Brewery, Stone Brewing, Sierra Nevada Brewing Co., Lagunitas Brewing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Beer Market Evolving Landscape
Hybrid beverage development is compressing traditional category boundaries as technical capabilities from adjacent industries migrate into brewing operations. These shifts are restructuring competitive advantage around extraction science and sensory engineering rather than conventional hop procurement.
Anaerobic coffee processing methods are converging with controlled fermentation environments in brewing facilities. Craft producers in Copenhagen and Melbourne are adopting wine-industry techniques for managing microbial activity during coffee integration. This convergence is enabling flavor profiles previously unattainable through standard hot-extraction protocols, compressing the innovation cycle from concept to commercial release.
The FDA's updated Generally Recognized as Safe determinations for caffeine additives are tightening formulation ceilings across interstate commerce. Brewers must now document caffeine source concentration and total additive load in pre-market submissions. Small-batch producers without dedicated compliance infrastructure face disproportionate administrative burden, accelerating consolidation pressure in the craft segment.
Experiential taproom consumption is displacing conventional off-premise retail as the primary discovery channel. Brewery visitors seek education on coffee origin and roasting integration alongside tasting protocols. This behavioral pivot concentrates demand generation in urban clusters with established craft beer tourism infrastructure, particularly Portland, Berlin, and Melbourne.
Coffee Beer Market Segmentation
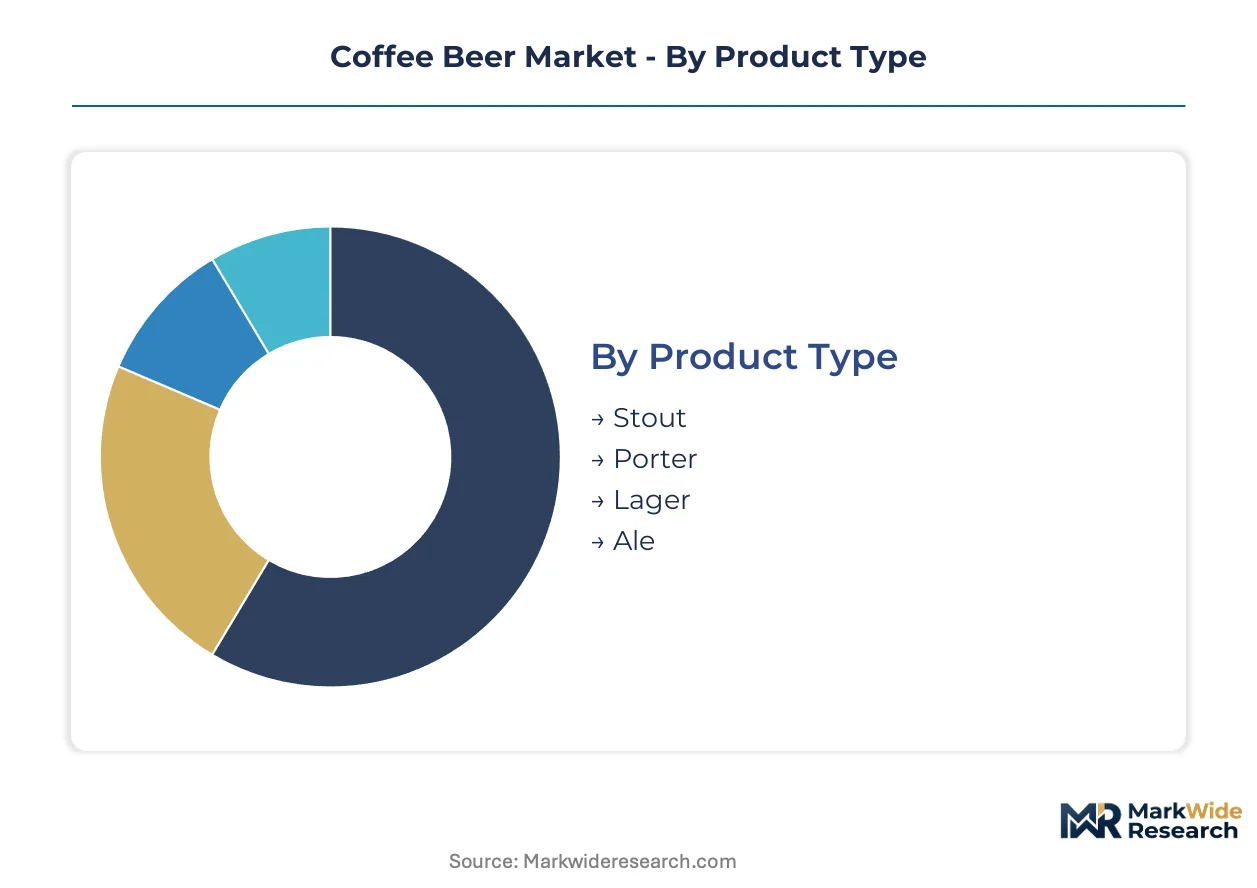
Coffee beer segmentation reveals how technical choices in base style, extraction method, and packaging format determine margin capture and distribution feasibility. Producers calibrate these dimensions against regulatory constraints and channel economics.
Product Type:
Integration depth varies sharply: stout and porter embed coffee as a core flavor architecture, while lager and ale treat it as an additive layer.
- Stout:Dark roasted malts provide inherent compatibility with coffee's bitter, roasted profile. German craft breweries anchor volume here, leveraging Reinheitsgebot heritage for credibility in specialty stout production.
- Porter:Slightly lighter body than stout permits more nuanced coffee expression without overwhelming malt character. Pacific Northwest taprooms concentrate demand for porter-coffee hybrids, driven by third-wave roasting partnerships.
- Lager:Clean fermentation profile demands precise coffee dosing to avoid clashing with delicate malt bills. Japanese import channels show selective interest in lager-based formats.
- Ale:Fruity ester production from ale yeast creates formulation challenges with coffee acids. Limited commercial traction outside experimental small-batch programs.
Stout leads volumes today; lager is gaining share fastest as producers seek lighter entry points for crossover consumers.
Flavor Profile:
Cost tier stratification emerges: nutty and chocolate profiles command premium positioning through ingredient complexity, while dry and sweet variants target accessibility.
- Nutty:Hazelnut and almond notes require specialty coffee varietals from Brazil and Guatemala. Barrel-aging programs in Copenhagen integrate nutty profiles with oak-derived vanillin for super-premium tier placement.
- Chocolate:Cacao-like coffee characteristics align with dessert occasion positioning. Melbourne craft producers concentrate R&D here, exploiting anaerobic processing methods for enhanced chocolate expression.
- Dry:Minimal residual sugar emphasizes coffee's natural acidity and tannic structure. Draft-dominant distribution in Berlin taprooms favors this profile for sessionability.
- Sweet:Lactose or maltodextrin additions balance bitterness for entry-level consumers. Can formats in U.S. mainstream retail show volume concentration.
Chocolate leads volumes today; nutty is climbing the fastest as origin-specific provenance commands price premiums.
Brewing Method:
Application logic separates on-premise experiential formats from scalable packaged production.
- Cold Brew:Extended cold-water extraction yields smoother, less astringent coffee integration. Portland craft breweries pioneered this technique; EFSA novel ingredient pathways now accelerate European adoption.
- Nitro:Nitrogen injection creates cascading pour aesthetics and creamy mouthfeel. Taproom-dominant format with limited retail scalability due to cold chain requirements.
- Hot Brew:Traditional hot-extraction permits faster production cycles but risks over-extraction and astringency. Standard for mass-market stout variants.
- Infusion:Post-fermentation coffee addition preserves volatile aromatics. Labor-intensive method concentrated in small-batch premium tiers.
Cold brew leads volumes today; nitro is expanding most quickly through experiential consumption recovery.
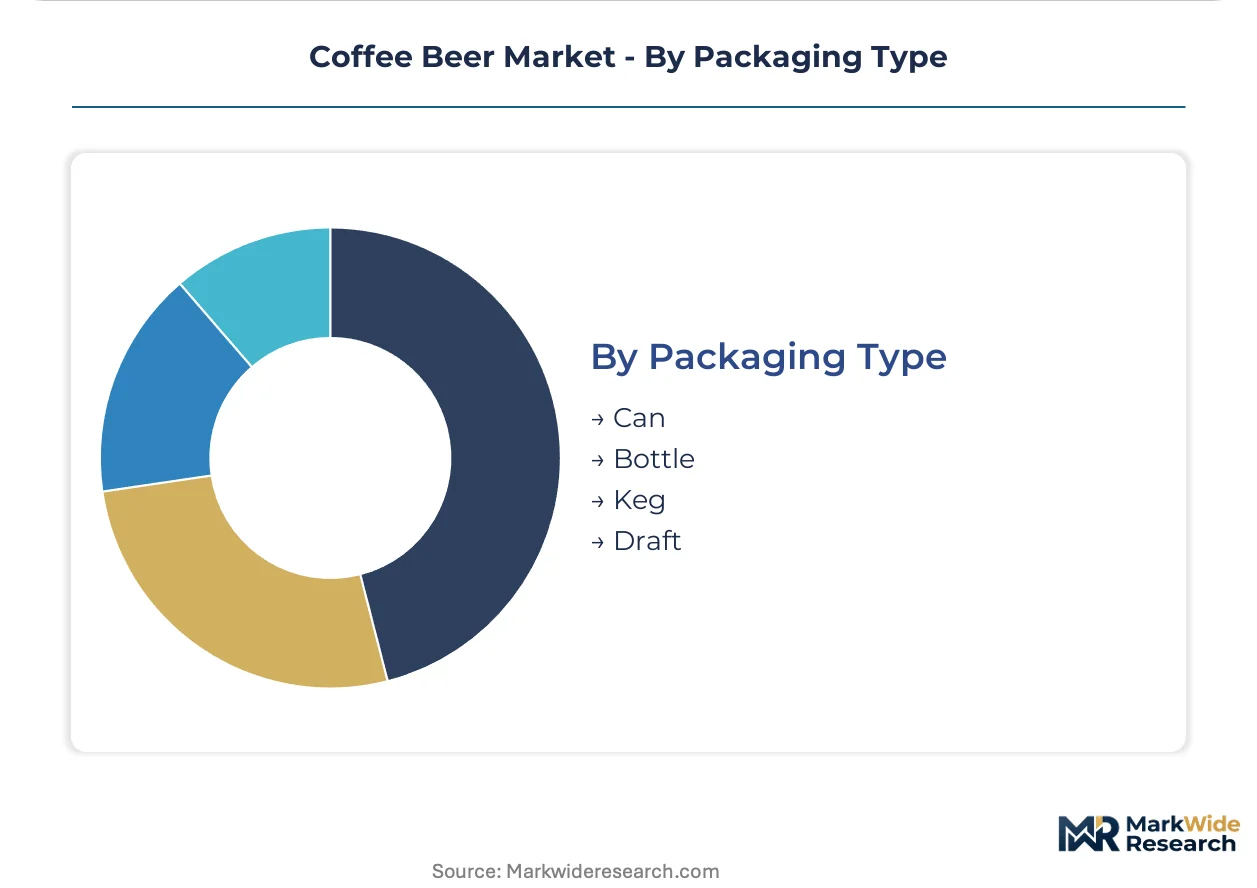
Packaging Type:
Customer type determines format: on-premise discovery versus off-premise repeat purchase.
- Can:Light-weight, opaque aluminum protects against light degradation and supports outdoor occasion targeting. U.S. craft breweries favor cans for distribution economics.
- Bottle:Premium perception and label real estate for origin storytelling. German and Belgian producers maintain bottle traditions for export positioning.
- Keg:On-premise volume driver with highest margin capture per liter. Concentrated in urban taproom clusters.
- Draft:Nitro-dispense systems require specialized infrastructure; limited to established craft beer bars with trained staff.
Can leads volumes today; keg is gaining share fastest as taproom experiential consumption rebounds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as brewers migrate toward jurisdictions with streamlined formula approval pathways. Cost-of-compliance gaps between the U.S. TTB's 90-180 day review queues and EFSA's novel ingredient fast-tracks are concentrating new product development in European pilot facilities.
United States
Third-wave coffee culture in Portland and Seattle drives ingredient co-development between specialty roasters and craft breweries. The TTB's caffeine disclosure mandates create compliance thresholds that favor established operators with dedicated regulatory affairs staff. California's barrel-aging infrastructure anchors super-premium tier production in San Diego and Los Angeles metro clusters.
Germany
Traditional brewing heritage intersects with third-wave coffee culture in Berlin and Munich taprooms. EFSA novel ingredient pathways provide regulatory clarity for cross-border formulations entering continental markets. Bavarian craft producers leverage Reinheitsgebot credibility to anchor specialty stout volume leadership.
Japan
METI licensing reforms opened the domestic market to small-batch coffee beer imports. Japanese consumers demonstrate high willingness-to-pay for barrel-aged variants with origin-specific coffee provenance. Tokyo and Osaka craft beer bars concentrate experiential consumption demand.
Australia
Melbourne craft producers pioneer anaerobic coffee processing convergence with controlled fermentation environments. The country's food standards code governs caffeine additive thresholds for interstate distribution. Sydney and Brisbane taprooms drive nitro brewing format adoption through on-premise experiential positioning.
United Kingdom
London's specialty coffee shop chains expand coffee beer offerings as hybrid beverage interest rises. The Food Standards Agency evaluates novel ingredient combinations under retained EU food law frameworks. Manchester and Bristol brewery clusters concentrate cold brew infusion technique development.
Coffee Beer Market Competitive Landscape
Portfolio diversification dominates the current landscape as multinational brewers acquire craft labels to capture hybrid beverage growth. The market exhibits tiered structure with multinational conglomerates controlling mainstream retail distribution, mid-scale craft operators anchoring regional taproom networks, and micro-breweries specializing in experimental barrel-aged programs. Three archetypes prevail: scale-driven portfolio builders, terroir-focused craft specialists, and vertically integrated taproom operators. Capacity expansion in nitro dispensing infrastructure and strategic partnerships with specialty coffee roasters represent the dominant competitive moves.
Among multinational portfolio builders, Anheuser-Busch InBev and Heineken N.V. exemplify scale-driven market presence through vast distribution infrastructure. Stone Brewing and Sierra Nevada Brewing Co. occupy positions within the craft specialist tier, representing terroir-focused production archetypes with sustained investment in sustainable sourcing partnerships.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Carlsberg Group |
| Heineken N.V. |
| Diageo |
| Samuel Adams |
| Erdinger Brewery |
| Stone Brewing |
| Sierra Nevada Brewing Co. |
| Lagunitas Brewing Company |
| Others |
Value Network & Pricing Analysis
Arabica coffee futures on the Intercontinental Exchange cascade through coffee beer supply chains, compressing margins for craft brewers while concentrating pricing power with multinational operators capable of long-term bean procurement contracts and hedging instruments.
Pricing Analysis
Distributor margin layers absorb 25-35 percent of ex-brewery value, with three-tier pricing structure across premium, standard, and economy levels separating barrel-aged small-batch releases from nitro taproom exclusives and mass-market canned stouts. Price differentiation hinges on origin-specific coffee provenance and TTB formula approval status, with certified organic or fair-trade bean sourcing commanding shelf-space premiums. Cost compression in the economy tier is intensifying because Arabica price volatility transmits directly to input structures, while health-conscious demographics show highest price sensitivity and super-premium barrel-aged collectors demonstrate lowest.
Supply Chain Analysis
Workforce availability constraints in Portland, Melbourne, and Copenhagen brewing clusters limit expansion of anaerobic processing and cold brew infusion capacity, forcing producers to locate pilot facilities near specialty coffee roasting talent pools. Supply concentrates in Germany for Reinheitsgebot-compliant stout production, the United States for TTB-approved cross-state distribution, and Japan for METI-licensed import channels. Raw material dependencies include Colombian and Ethiopian Arabica beans, American white oak for barrel-aging, and nitrogen gas systems for nitro dispensing. Single-source vulnerability in Ethiopian coffee harvests threatens formulation consistency. Distribution runs through three-tier systems in the United States and direct-to-taproom models in Germany and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coffee beer represents a margin-expansion story as cold brew infusion techniques compress production cycles while barrel-aging programs capture super-premium pricing tiers previously occupied by spirit categories.
For Market Incumbents: Extend barrel-aging infrastructure investments to defend against emerging non-alcoholic nitro coffee substitutes eroding trial rates. Lock in multi-year Arabica supply contracts with Ethiopian and Colombian cooperatives to hedge climate-induced price volatility. Prioritize dedicated regulatory affairs capacity to navigate TTB formula approval queues that disadvantage smaller competitors. For New Entrants and Emerging Players: The price-point gap between premium barrel-aged variants and economy-tier canned stouts offers white-space entry through mid-tier cold brew lager formats targeting Japanese import channels. Japan's craft beer liberalization under METI reforms presents the most penetrable geography. Launch through direct-to-consumer subscription channels to bypass three-tier distribution economics and capture full margin. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated taproom operators possessing in-house cold brew capacity and origin-story coffee partnerships. Long-term viability frames around CSRD supply chain disclosure compliance positioning brands for institutional procurement. Watch EFSA novel ingredient pathway expansion as the inflection signal for European market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Barrel-Aging Infrastructure Expansion | Extended oak cask programs integrate coffee extraction with spirit character for super-premium tier placement. |
| Cold Brew Infusion Scale-Up | Portland and Melbourne facilities pioneer smoother extraction profiles that reduce astringency and accelerate production cycles. |
| Direct-to-Consumer Subscription Launch | Brewery-owned membership programs bypass three-tier distribution economics and build recurring revenue predictability. |
| Sustainable Sourcing Certification | CSRD-compliant supply chain disclosure positions brands for European institutional procurement channels. |
| Nitro Dispensing System Deployment | Taproom-dominant nitrogen injection creates cascading pour aesthetics that command experiential consumption premiums. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with craft brewery head brewers, specialty coffee roaster sourcing directors, TTB regulatory affairs consultants, and three-tier distribution executives with secondary validation against FDA GRAS determinations, TTB formula approval databases, EFSA novel ingredient registers, and customs import records for coffee beer trade flows. Bottom-up volume builds from taproom and retail channel audits triangulated against top-down market sizing from alcoholic beverage consumption datasets.
Comparable historical reference periods anchored the projection horizon to pre-pandemic experiential consumption baselines and post-liberalization import growth trajectories in Japan. The analytical framework modeled segmentation dimensions including base beer style, coffee extraction method, packaging format, and regional regulatory cluster. CAGRs derived from trend-line extrapolation of cold brew adoption curves and nitro dispensing infrastructure rollouts, with Arabica price elasticity and TTB approval queue lengths as industry-specific forecast inputs.
Caveats apply where Arabica harvest variability, TTB regulatory backlog extensions, or EFSA ingredient reclassification could materially shift the outlook. Forecasts reflect assumptions around sustained third-wave coffee culture penetration and craft beer tourism recovery. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Airport Duty-Free Liquor Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Beer Cans Market
Alcoholic Beverages
Winetainer Market
Alcoholic Beverages
Japan Beer Market
Alcoholic Beverages
Pressurized Wine Filter System Market
Alcoholic Beverages
Gin Market
Alcoholic Beverages
Wine Cellar Market
Alcoholic Beverages
Home Brewing Systems Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market
Alcoholic Beverages
Rhum Agricole Market
Alcoholic Beverages
Wine Filling Machine Market
Alcoholic Beverages
Organic Beer Market
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
Pisco Market
Alcoholic Beverages
Vodka Market