
 Alcoholic Drinks Market | 2026-2036
Alcoholic Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Alcoholic Drinks Market Intelligence
Expertise from master distillers and brewers is rotating from large-scale industrial production toward artisanal and craft formulations, unlocking premium value segments. This shift challenges established players while creating new market niches. Diageo plc leverages its extensive portfolio of heritage brands to command premium pricing in the spirits category. In contrast, Constellation Brands specializes in the high-growth premium beer segment in the US market, while Anheuser-Busch InBev sustains a dominant position through its global scale and distribution network.
Alcoholic drinks are beverages containing ethanol, produced via the fermentation of sugar from sources like grains and fruits. Processes such as distillation are used to increase ethanol concentration for spirits, while aging imparts distinct flavor characteristics. The spirits product type currently offers the highest margin potential, contrasting with the high-volume, lower-margin beer segment. Analysis of consumer age groups reveals that Millennials and Gen Z are propelling demand for innovative flavor profiles and convenience formats, distinct from traditional consumption patterns.
Market access and product standards are heavily shaped by national and regional regulations. In the United States, the FDA enforces strict labeling and advertising rules, while the European Union's geographical indication laws protect regional specialties like Scotch whisky and Champagne. In China, the SAMR governs import requirements and food safety standards. Navigating these diverse and evolving regulatory frameworks remains a critical competency for brand owners seeking to expand their geographic footprint.
Market Dynamics
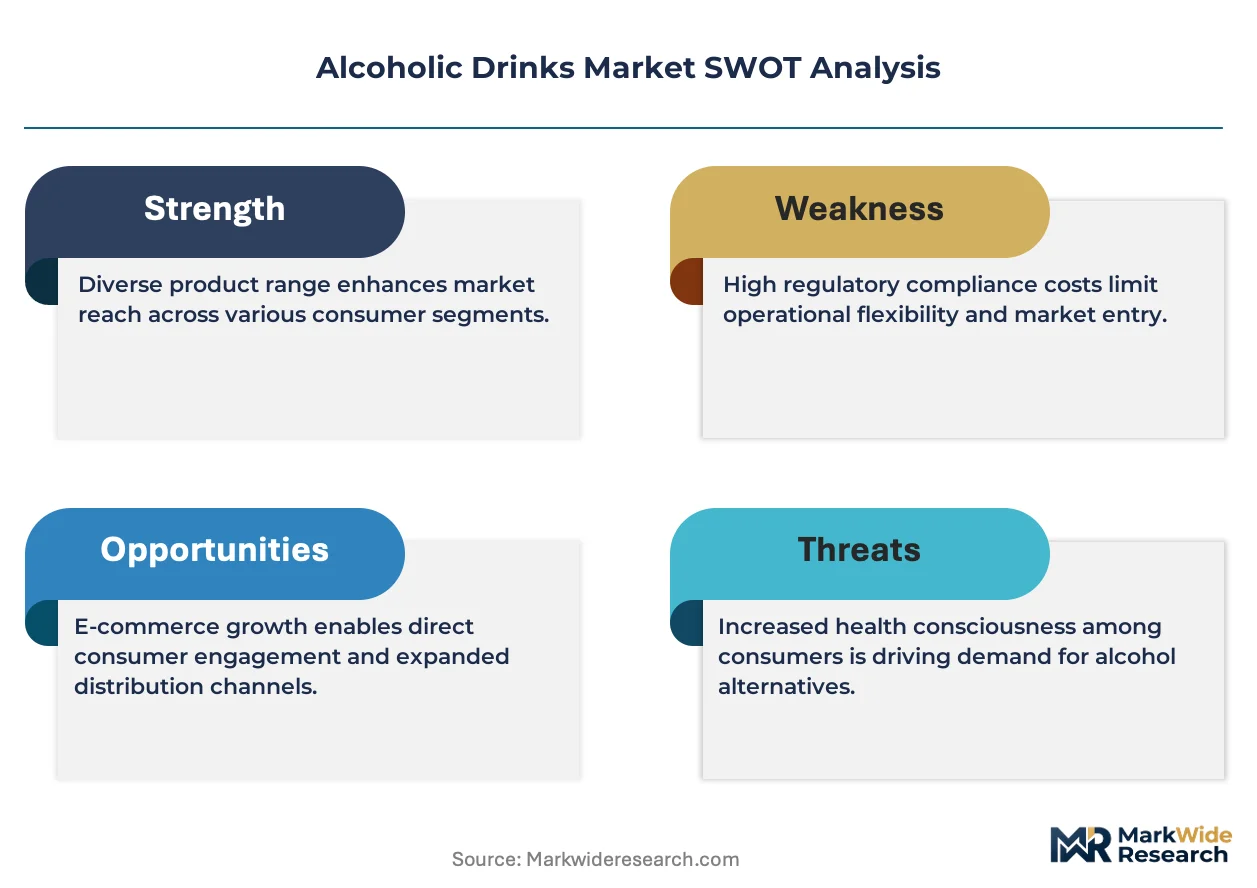
The convergence of health-conscious consumerism and demand for novel experiences defines the market landscape. This creates tension between the growth of low-alcohol alternatives and the premiumization of traditional spirits and cocktails.
Growth Catalysts
- Premiumization in Emerging Markets:A growing middle class in India and Southeast Asia is trading up to premium spirits, driving value growth for heritage and craft brands.
- Rise of Ready-to-Drink (RTD) Products:RTD cocktails cater to consumer demand for convenience and novel flavors, expanding consumption occasions beyond traditional settings.
- E-commerce and DTC Sales:Regulatory shifts allowing online sales create direct channels, enabling data collection and bypassing three-tier distribution systems in select markets.
Market Restraints
- Heightened Regulatory Scrutiny:Governments are increasing excise taxes and imposing stricter marketing controls, which dampen demand and increase compliance burdens for producers.
- Agricultural Input Volatility:Climate change creates price and supply instability for key raw materials like barley and agave, directly impacting production costs.
- Growth of Low/No-Alcohol Segment:The "sober curious" movement drives consumer adoption of non-alcoholic alternatives, creating a direct substitution threat to traditional categories.
Strategic Opportunities
- Functional Beverage Innovation:Incorporating botanicals and other wellness-associated ingredients into alcoholic beverages presents an opportunity to appeal to health-conscious consumers.
- Expansion into African Markets:Rising disposable incomes in countries like Nigeria and Kenya offer significant white-space growth for established international brands.
- AI-Powered Personalization:Using AI to analyze consumer data enables targeted new products and personalized marketing, fostering loyalty in a fragmented market.
Industry Challenges
- Aged Spirits Inventory Risk:The long maturation for spirits like whisky ties up significant capital and requires accurate long-range demand forecasting, creating substantial financial risk.
- Complex Global Compliance:Adhering to a patchwork of national labeling regulations, such as EU nutrition rules and US TTB standards, is a costly and complex operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcoholic Drinks Market |
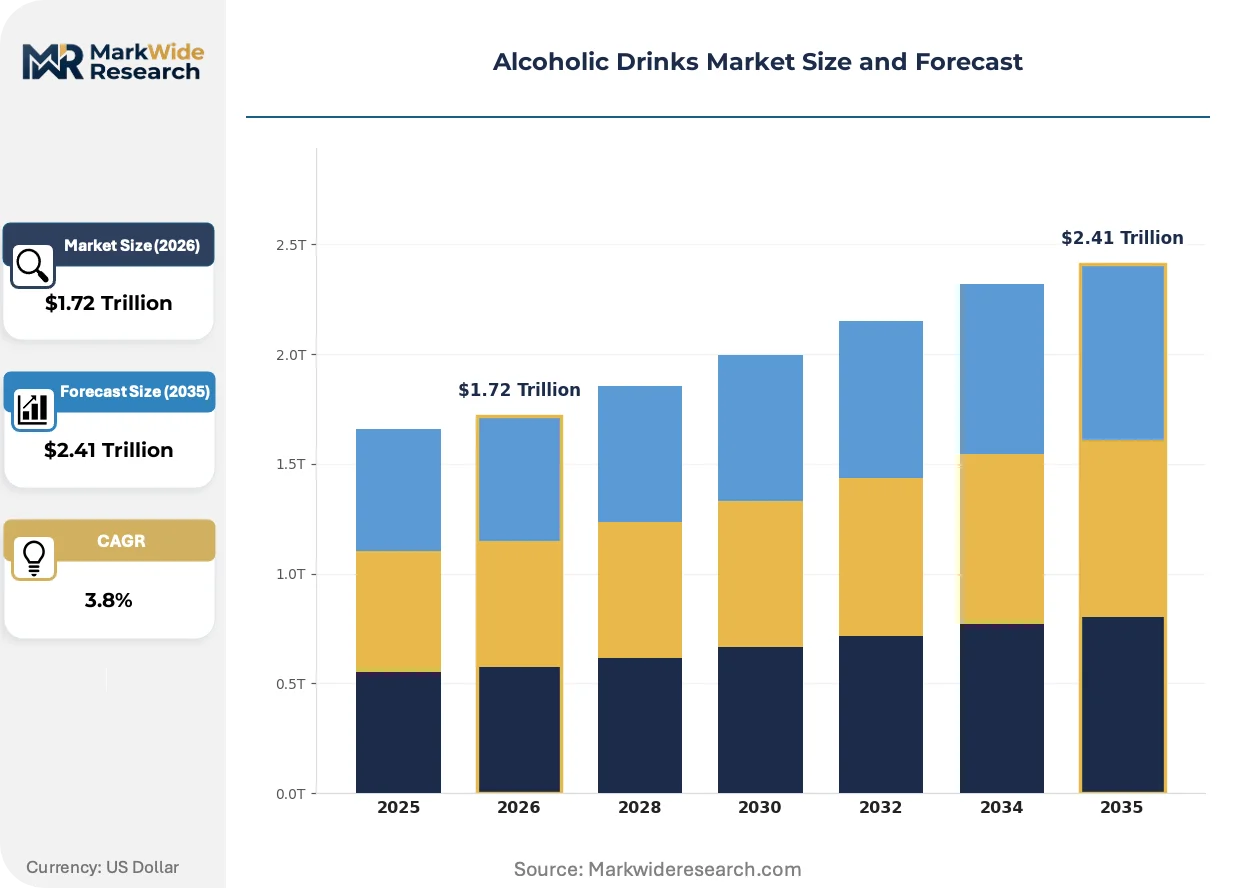
| Market Size in 2026 | $1.72 Trillion |
| Market Size in 2035 | $2.41 Trillion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Cider Distribution Channel: Supermarkets, Liquor Stores, Online Retailers, Bars Consumer Age Group: Millennials, Generation X, Baby Boomers, Gen Z Flavor Profile: Citrus, Spicy, Sweet, Bitter |
| Companies Covered | Heineken N.V., Constellation Brands, Diageo plc, Asahi Group Holdings, Brown-Forman Corporation, Pernod Ricard S.A., LVMH Moët Hennessy, E & J Gallo Winery, Anheuser-Busch InBev, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcoholic Drinks Market Strategic Shifts & Innovations
Product innovation is moving beyond simple flavor extensions to fundamentally rethink format, function, and alcohol content. This shift responds directly to a new generation of consumers whose purchasing decisions are guided by values like health, sustainability, and authenticity.
Advanced distillation technology, including vacuum and reverse osmosis systems, allows for the removal of ethanol from fermented liquids without stripping flavor. Producers of non-alcoholic spirits and wines are rapidly adopting these methods to create more authentic alternatives. This technology is bifurcating the market, creating a distinct, premium-priced non-alcoholic segment that coexists with traditional alcoholic beverages.
The European Union's updated Common Agricultural Policy mandates that wine and aromatized wine products must display ingredient and nutrition information. This regulation forces producers to either overhaul physical labels or implement digital solutions like QR codes. Small to mid-sized wineries are most impacted, facing disproportionate costs and logistical hurdles to achieve compliance across their portfolios.
Consumer purchasing behavior is pivoting from brand loyalty toward discovery and experience, especially in on-premise settings. This change disrupts the traditional volume-driven model of major brands, opening space for craft spirits and local beers with compelling origin stories. The trend is most pronounced in major metropolitan areas in North America and Western Europe.
Alcoholic Drinks Market Segmentation
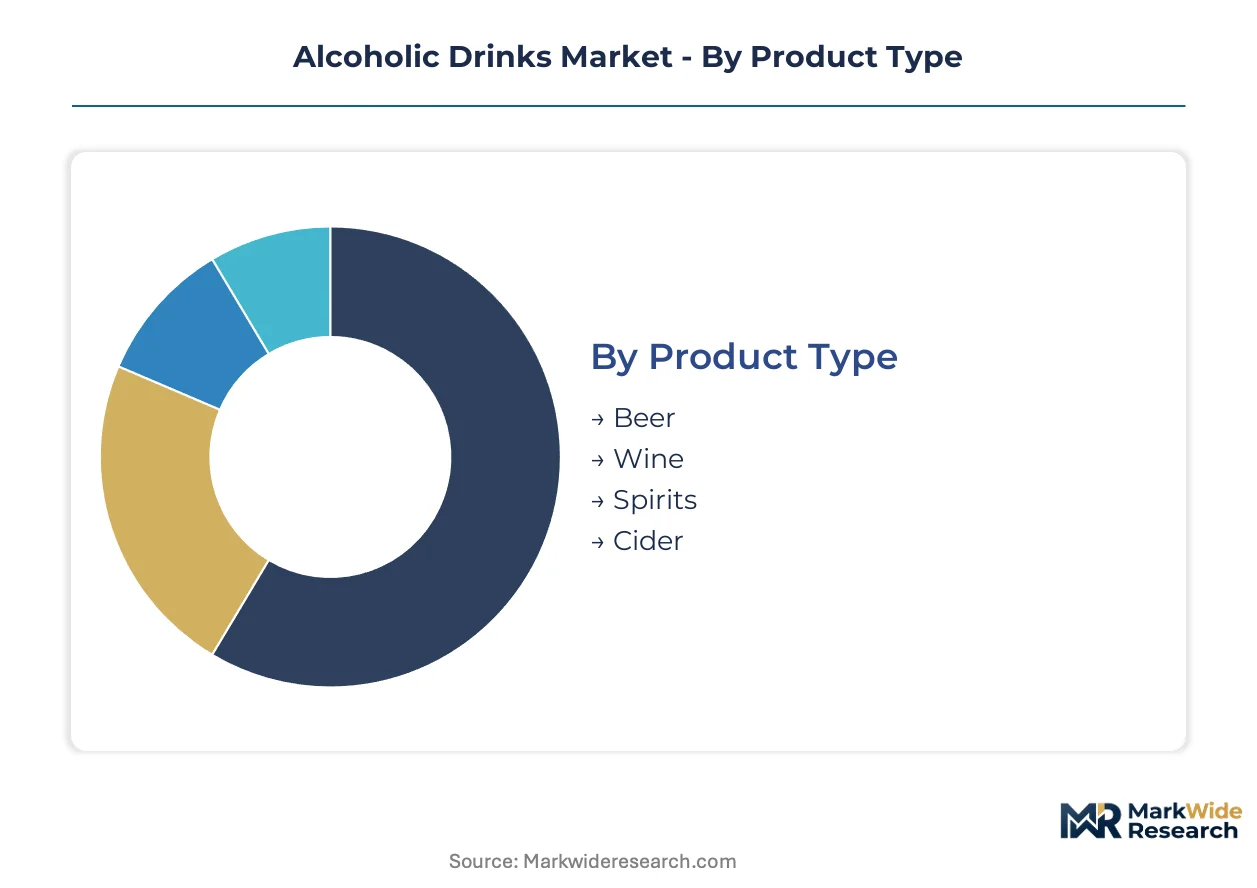
Market segmentation provides a structured view of the alcoholic drinks industry, highlighting distinct consumer preferences and operational dynamics. Understanding these divisions allows brand owners to tailor product development and marketing strategies effectively. This granular analysis is essential for identifying growth pockets and mitigating competitive pressures across diverse categories.
Product Type:
Segments within product type face varying substitution pressures from non-alcoholic alternatives and cross-category consumer shifts. Each category carries distinct production complexities and consumer appeal, influencing market positioning.
- Spirits:High-proof alcoholic beverages produced via distillation, such as whisky, vodka, and gin. Demand for premium spirits is concentrating in India, driven by an expanding middle class and evolving consumer tastes.
- Beer:Fermented beverages primarily made from malted barley, hops, water, and yeast, offering diverse styles from lagers to stouts. Consumer preferences in North America increasingly favor craft beer varieties and innovative flavor profiles.
- Wine:Fermented grape juice, encompassing red, white, rosé, and sparkling varieties. European markets maintain strong traditional consumption patterns for wine.
- Cider:Fermented apple juice, often lower in alcohol content than other categories. Younger demographics in Western Europe are increasingly adopting cider as a refreshing alternative.
Beer anchors the volume base while Cider gains share at the steepest rate.
Distribution Channel:
The effectiveness of distribution channels is increasingly shaped by consumer demand for convenience and personalized access. Channels differentiate by their ability to offer immediate consumption versus at-home purchasing options.
- Online Retailers:E-commerce platforms enabling direct-to-consumer sales, often bypassing traditional three-tier systems in select markets. Regulatory shifts in the United States and parts of Europe are enabling expanded online sales.
- Supermarkets:Large retail stores offering a broad selection of alcoholic beverages alongside groceries, providing high volume and accessibility. These outlets serve as primary purchasing points for household consumption across developed economies.
- Liquor Stores:Specialized retail establishments focusing exclusively on alcoholic beverages, offering expert advice and curated selections.
- Bars:On-premise establishments providing immediate consumption experiences, crucial for brand discovery and social interaction.
Online Retailers are expanding reach, while Supermarkets sustain everyday purchasing.
Consumer Age Group:
Consumer age groups exhibit distinct purchasing behaviors, with younger cohorts driving innovation in flavor and format. Each generation approaches alcoholic beverage consumption with unique values and expectations.
- Gen Z:Consumers born from the late 1990s to early 2010s, characterized by a preference for low/no-alcohol options and novel, Instagrammable experiences. This demographic in North America and Western Europe is influencing the growth of RTD cocktails.
- Millennials:Individuals born between the early 1980s and mid-1990s, seeking premiumization, authenticity, and craft formulations. This group in major metropolitan areas drives demand for unique craft spirits and local beers.
- Generation X:Consumers born from the mid-1960s to early 1980s, often loyal to established brands and traditional categories.
- Baby Boomers:Individuals born between the mid-1940s and mid-1960s, maintaining consistent consumption patterns for classic spirits and wines.
Gen Z consumers are driving demand for novel experiences, while Millennials continue to seek out premium and authentic options.
Flavor Profile:
Flavor profiles are diversifying to meet evolving consumer palates and product innovation strategies. The choice of flavor directly impacts product appeal and market penetration across various beverage types.
- Sweet:Characterized by sugary notes, including fruit-forward, caramel, or vanilla flavors, appealing to a broad consumer base. This profile dominates the RTD and flavored spirit segments in many global markets.
- Spicy:Featuring notes of chili, ginger, or other warming spices, often integrated into innovative cocktails and spirits. Younger consumers in North America are exploring spicy flavor infusions for unique experiences.
- Citrus:Incorporating lemon, lime, orange, or grapefruit notes, providing a refreshing and often tangy taste.
- Bitter:Defined by sharp, pungent, or herbal undertones, commonly found in aperitifs, certain beers, and complex cocktails.
Sweet profiles maintain broad appeal, while Spicy notes are gaining traction through innovative product development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Food and Drug Administration (FDA) sets critical standards for alcoholic beverage production and labeling, influencing market access across North America. Regional dynamics within the global alcoholic drinks market vary significantly, driven by diverse cultural preferences and evolving regulatory landscapes. These factors shape consumption patterns and product innovation worldwide.
United States
United States consumers are increasingly driving demand for innovative ready-to-drink cocktails and craft beer varieties. The Alcohol and Tobacco Tax and Trade Bureau (TTB) enforces strict labeling and advertising rules nationwide. Major craft brewing hubs like Portland, Oregon, exemplify this innovation, fostering local brand loyalty.
India
India's expanding middle class fuels substantial demand for premium spirits and imported wines. The Food Safety and Standards Authority of India (FSSAI) governs product quality and labeling requirements. Urban centers such as Mumbai and Delhi serve as key consumption points, showcasing evolving consumer tastes.
Germany
German consumers maintain strong traditional consumption patterns for beer, alongside a growing interest in local craft spirits. European Union geographical indication laws protect regional specialties, including specific German beers and wines. Bavaria, a major beer-producing region, continues to be a hub for brewing heritage.
China
China exhibits robust demand for traditional Baijiu and premium imported alcoholic beverages. The State Administration for Market Regulation (SAMR) oversees import requirements and food safety standards. Shanghai's metropolitan area represents a significant market for both domestic and international brands.
Brazil
Brazilian consumers show strong preferences for local Cachaça and international beer brands, alongside rising interest in premium spirits. The National Health Surveillance Agency (ANVISA) regulates the production and commercialization of alcoholic drinks. The São Paulo state region is a major production and consumption center for various beverage types.
Alcoholic Drinks Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the global alcoholic drinks market structure. This market features global conglomerates focusing on extensive portfolio diversification, alongside regional specialists catering to localized preferences. Archetypes include large-scale industrial producers and agile craft formulators. Strategic partnerships and targeted geographic expansion are common competitive moves among these players, alongside significant investment in M&A activities to consolidate market share.
At the scale-driven end, Diageo plc represents a global conglomerate with a vast portfolio of heritage brands across spirits categories, anchoring premium pricing. Constellation Brands occupies a strong position within the high-growth premium beer segment in the United States, alongside its significant wine and spirits offerings. Anheuser-Busch InBev exemplifies a dominant player through its global scale and extensive distribution network, sustaining a leading position across multiple continents. These companies collectively demonstrate the market's tiered structure, where established brand equity and broad market reach are critical for maintaining competitive advantage, often leveraging historical market penetration.
| Leading Market Players |
|---|
| Heineken N.V. |
| Constellation Brands |
| Diageo plc |
| Asahi Group Holdings |
| Brown-Forman Corporation |
| Pernod Ricard S.A. |
| LVMH Moët Hennessy |
| E & J Gallo Winery |
| Anheuser-Busch InBev |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for key agricultural inputs like barley and agave secure raw material access and stabilize production costs within the alcoholic drinks market. These contracts provide essential price visibility for producers, influencing final product pricing strategies.
Pricing Analysis
Geographic price spreads for alcoholic beverages vary significantly, reflecting local excise taxes and consumer purchasing power across regions. The dominant pricing structure is a tiered premium-mid-economy differentiation, driven by brand equity and product quality. Production cost volatility, particularly for aged spirits, creates upward pricing pressure. Gen Z consumers exhibit higher price sensitivity for traditional categories, while Millennials prioritize premium options and unique experiences.
Supply Chain Analysis
Inbound logistics costs, particularly for cross-border shipments of bottled products, impact regional pricing and availability. The global supply chain for alcoholic drinks sources key inputs from regions like France for grapes, Scotland for malted barley, and Mexico for agave. Agricultural input volatility, driven by climate change, represents a significant structural risk. Distribution runs through a hybrid model combining large-scale supermarkets, specialized liquor stores, and expanding online retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alcoholic drinks market is experiencing an early-cycle expansion, driven by the increasing penetration of ready-to-drink cocktails among younger demographics. This presents distinct strategic imperatives for various market participants.
For Market Incumbents:Compound existing portfolio strength by investing in advanced distillation technologies for non-alcoholic alternatives to mitigate the "sober curious" movement threat. Deepen channel control through strategic partnerships with e-commerce platforms to counter new entrant agility. Leverage heritage brands for premiumization in emerging markets like India. This approach helps defend against product substitution and market fragmentation.
For New Entrants and Emerging Players:EU geographical indication certification fast-track offers a route to premium positioning for craft spirits in Western Europe. Target innovative flavor profiles in the ready-to-drink cocktail segment, particularly appealing to Gen Z consumers in North America. The most penetrable segment remains functional beverages incorporating botanicals. A direct-to-consumer online sales model provides a strong go-to-market angle.
For Investors and Strategic Acquirers:Capital is best deployed toward agile craft formulators with strong brand narratives and established e-commerce capabilities. The long-term viability of this market over the next decade remains strong, driven by evolving consumer preferences for premium and novel products. Target acquisition profiles include companies specializing in low/no-alcohol innovation. The signal to watch is sustained growth in the functional beverage segment.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand into African Markets | Rising disposable incomes in Nigeria and Kenya create white-space growth for established international brands. |
| AI-Powered Personalization | Using AI to analyze consumer data enables targeted new products and personalized marketing strategies. |
| Functional Beverage Innovation | Incorporating botanicals appeals to health-conscious consumers, diversifying the alcoholic drinks market. |
| Direct-to-Consumer (DTC) Channel Development | Bypassing traditional three-tier distribution systems enables data collection and market access in select regions. |
| Advanced Distillation Technology Adoption | Vacuum and reverse osmosis systems create authentic non-alcoholic alternatives, bifurcating the market. |
Research Approach
Initial hypotheses were tested against primary input from master distillers, brand managers, and regulatory affairs leads, and refined through iterative feedback. This involved combining qualitative interviews with robust secondary validation from sources like FSSAI reports, EU geographical indication databases, and TTB filings. Bottom-up data aggregation and top-down market sizing ensured comprehensive market understanding.
Variance decomposition identified key drivers impacting market trajectory across the analysis window, including shifts in consumer age group preferences. The analytical framework modeled segmentation by product type, distribution channel, flavor profile, and regional regulatory environment. Compound annual growth rates were derived from historical data trends and projected future demand. Key forecast inputs included raw material price projections and excise tax changes.
Underlying assumptions cover stable geopolitical conditions and predictable regulatory evolution, with deviation risk concentrated in unforeseen excise tax hikes or extreme climate events impacting agricultural yields. Forecasts reflect these assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Herbal Distillates Market
Alcoholic Beverages
North America Spirits Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
Tequila Market
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market
Alcoholic Beverages
Wine Barrel Market
Alcoholic Beverages
Roasted Malt Market
Alcoholic Beverages
Middle East and Africa Kegs Market
Alcoholic Beverages
Beer Filter System Market
Alcoholic Beverages
Portable Keg System Market
Alcoholic Beverages
Beer Line Cleaning Kit Market
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
South America Craft Beer Market
Alcoholic Beverages
Asia-Pacific Alcohol E-Commerce Market
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
Irish Whiskey Market