
 Instant Wine Chillers and Refreshers Market | 2026-2036
Instant Wine Chillers and Refreshers Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Wine Chillers and Refreshers Market Foresight
Modular accessory bundles pairing electric chillers with reusable ice inserts is repositioning buyer choice away from standalone units. Rapid Ice Coolers leverages its specialization in manual chilling systems to anchor the budget hospitality segment. LG Electronics competes through integrated smart-kitchen ecosystems that extend connectivity into wine storage. Viski differentiates via design-forward stainless steel aesthetics that occupy premium gifting channels.
Instant wine chillers and refreshers comprise thermoelectric or passive cooling devices engineered to reduce wine temperature from ambient to serving range within minutes, typically employing Peltier modules or gel-based thermal mass with wattage ratings between 25 and 90 watts for commercial electric units. Electric chillers dominate the product type landscape due to their speed advantage in restaurant settings, while manual chillers and reusable ice inserts capture margin pools in outdoor events and travel applications where power access constrains equipment choice. Stainless steel and silicone materials command structural attention as durability requirements intensify in winery and restaurant end-use environments.
The U.S. Department of Energy and California Energy Commission appliance efficiency frameworks shape electric chiller design specifications, compressing allowable standby power and forcing redesigns of thermoelectric module drivers. FDA food-contact material regulations and EU REACH compliance for silicone and plastic components govern material selection in export-bound production. Stakeholders must monitor evolving state-level energy codes and hospitality sustainability certifications that increasingly influence procurement decisions in premium foodservice accounts.
Market Dynamics
Thermoelectric module miniaturization is compressing chiller footprints while forcing supply chain reconfiguration around specialized semiconductor foundries. The U.S. Department of Energy's standby power limits are mandating driver circuit redesigns across all electric unit portfolios.
Growth Catalysts
- California Energy Commission Title 20:Appliance efficiency thresholds are accelerating Peltier module innovation cycles and disqualifying legacy resistive heating designs from hospitality procurement.
- Vineyard tasting room densification:Napa and Sonoma corridor operators are deploying portable chillers to extend outdoor service seasons without permanent infrastructure investment.
- Silicone thermal mass engineering:Reusable gel insert formulations are capturing outdoor event demand segments where grid access remains unreliable.
Market Restraints
- Bismuth telluride supply concentration:Thermoelectric material sourcing clusters in Chinese refining operations create input vulnerability for Peltier module assemblers.
- Passive cooling substitution:Ice bucket protocols in budget hospitality accounts limit electric chiller penetration at price points below commercial-grade thresholds.
- FDA food-contact compliance timelines:Silicone formulation certifications extend product development cycles by eight to fourteen months for export-bound manufacturers.
Strategic Opportunities
- Texas Hill Country hospitality expansion:Fredericksburg and Austin corridor winery development is outpacing permanent cooling infrastructure installation.
- Smart-kitchen ecosystem integration:API-enabled chillers are converging with restaurant management platforms to enable automated inventory-temperature synchronization.
- Modular accessory bundling:Electric base units paired with manual backup inserts are opening dual-use purchase occasions previously split across separate supplier relationships.
Industry Challenges
- Thermoelectric engineering talent scarcity:Peltier module design expertise concentrates in aerospace and medical device sectors, constraining hiring pipelines for appliance manufacturers.
- Legacy POS integration complexity:Tabletop service equipment requires API development for reservation and inventory systems that lack standardized connectivity protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Wine Chillers and Refreshers Market |
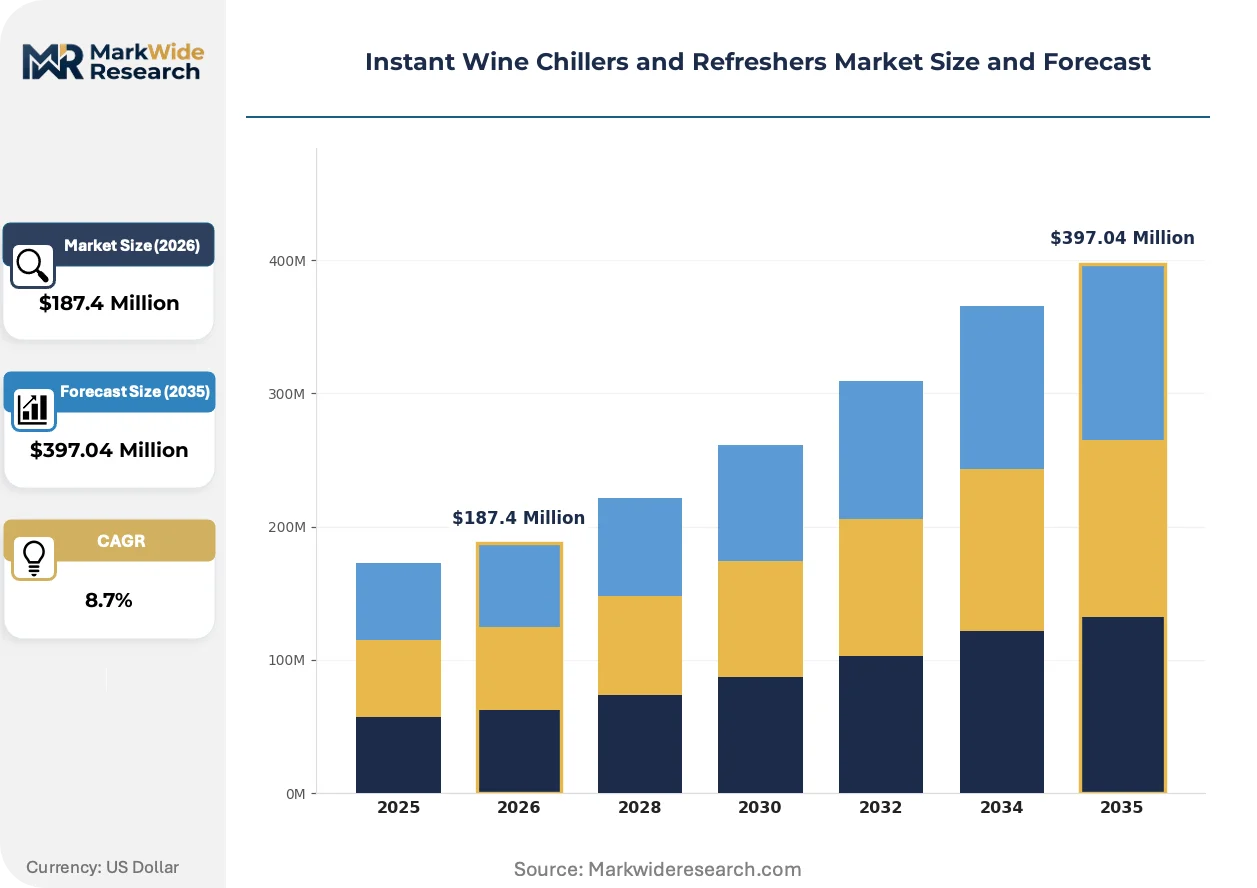
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Chillers, Manual Chillers, Accessories, Reusable Ice Inserts End User: Home Users, Restaurants, Wineries, Events Material: Plastic, Stainless Steel, Glass, Silicone Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Rapid Ice Coolers, LG Electronics, Viski, Bosch, Samsung Electronics, Vinglacé, Haier, Whirlpool Corporation, Vochill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Wine Chillers and Refreshers Market Shifts & Advancements
Solid-state cooling architectures are displacing compressor-based alternatives across premium hospitality segments. Three converging developments are restructuring competitive positioning and procurement patterns.
Peltier-based thermoelectric arrays are decentralizing temperature control from centralized cellar systems to individual service points. Upscale restaurant operators in Manhattan and Chicago are deploying tabletop units to eliminate server transit time to remote wine storage. This distributed architecture is compressing floorplan requirements and enabling revenue recovery from previously unservable square footage.
The U.S. Department of Energy's amended standby power standards are forcing semiconductor driver redesigns across electric chiller portfolios. Manufacturers must achieve sub-one-watt idle consumption without sacrificing cooling recovery speed. California-based assemblers are responding with burst-mode power management firmware that thermally cycles Peltier modules rather than maintaining continuous operation.
Procurement patterns among hospitality groups are consolidating supplier relationships around bundled beverage service equipment. Multi-unit restaurant operators are negotiating enterprise agreements covering chillers, glassware, and preservation systems through single vendor contracts. This concentration is most visible in Florida's resort corridor, where property management companies are standardizing tabletop service specifications across portfolio properties.
Instant Wine Chillers and Refreshers Market Segmentation
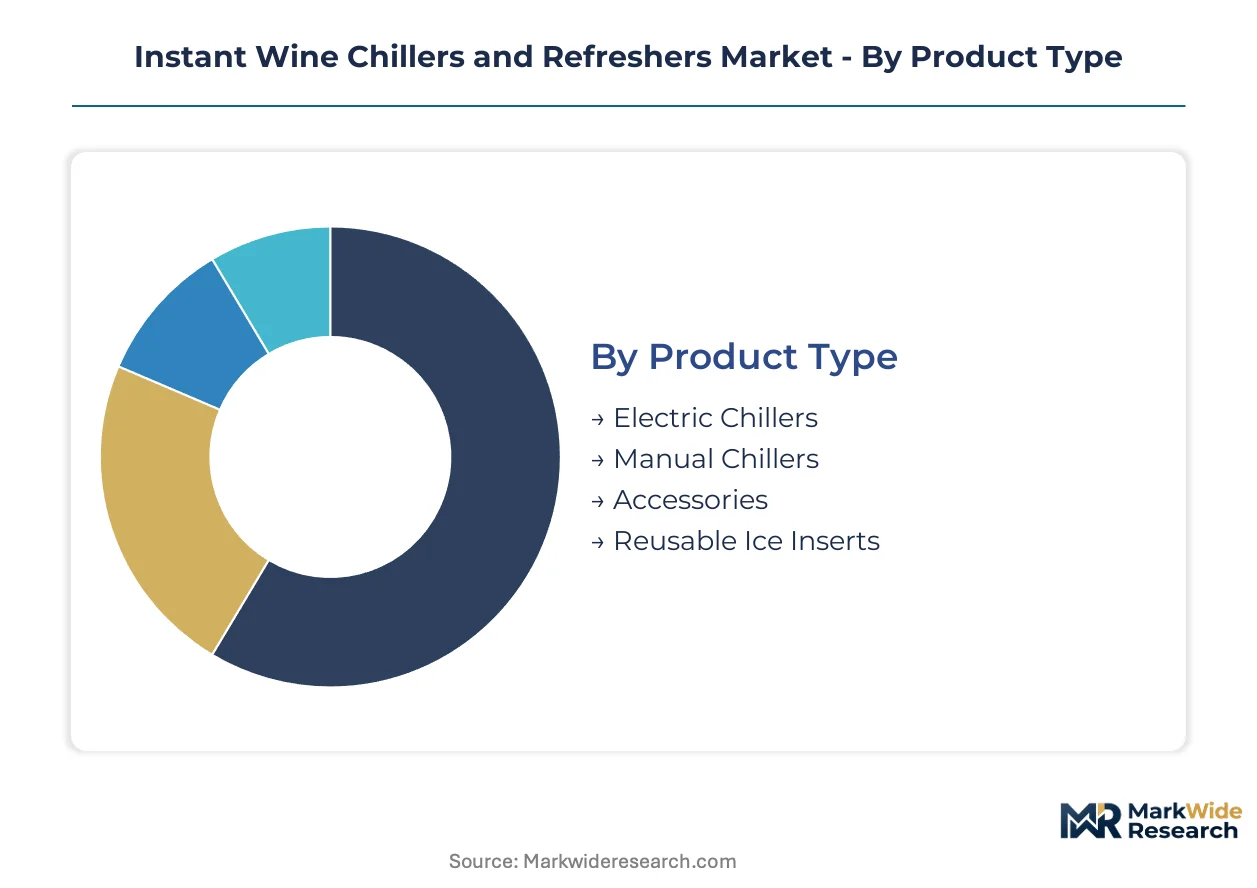
Segmentation in the instant wine chillers and refreshers market reflects divergent performance requirements across hospitality environments versus residential settings. Material specifications and power access constraints fragment procurement patterns, forcing suppliers to maintain parallel product architectures.
Product Type:
Standardization dominates high-volume electric units, while manual systems accommodate customization for branded hospitality programs.
- Electric Chillers:Thermoelectric Peltier modules rated 25-90 watts deliver sub-ten-minute cooling cycles. Napa Valley tasting rooms deploy these units to extend outdoor seating seasons without permanent infrastructure investment.
- Manual Chillers:Passive gel-based thermal mass systems require no electrical input. Rapid Ice Coolers anchors budget hospitality procurement with specialized manual chilling expertise for outdoor events and travel applications.
- Accessories:Modular bundling components including power adapters and carrying cases support hybrid deployment models.
- Reusable Ice Inserts:Silicone-encased gel formulations enable backup cooling redundancy. Texas Hill Country winery operators pair these with electric bases for grid-independent service continuity.
Leading the category by volume: Electric Chillers. Growing fastest: Reusable Ice Inserts.
End User:
Volume concentration tilts toward commercial accounts, though margin profiles favor premium residential purchasers.
- Restaurants:Manhattan and Chicago upscale operators deploy tabletop units to eliminate server transit time to remote wine storage, recovering revenue from previously unservable floor space.
- Wineries:California's wine country hospitality corridor prioritizes guest experience upgrades through portable chilling infrastructure.
- Home Users:Smart-kitchen ecosystem integration drives premium residential demand.
- Events:Outdoor catering procurement concentrates on manual and hybrid systems where grid access remains unreliable.
Commercial hospitality aggregates the largest revenue pool. Residential smart-kitchen integration shows steepest expansion trajectory.
Material:
Durability specifications intensify in winery and restaurant environments, elevating metal content in commercial-grade units.
- Stainless Steel:Viski occupies premium gifting channels through design-forward aesthetics. FDA food-contact compliance and corrosion resistance satisfy winery sanitation protocols.
- Silicone:Thermal mass engineering for reusable inserts captures outdoor event segments. EU REACH compliance extends product development cycles for export-bound manufacturers.
- Plastic:Cost-driven residential and budget hospitality procurement.
- Glass:Aesthetic-focused presentation applications with limited thermal performance.
Stainless Steel commands premium positioning. Silicone formulations are climbing the fastest on outdoor event demand.
Distribution Channel:
Enterprise procurement consolidation among multi-unit restaurant operators compresses direct sales margins while expanding contract values.
- Direct Sales:Florida's resort corridor property management companies standardize tabletop specifications across portfolio properties through single-vendor enterprise agreements.
- Specialty Stores:Premium gifting and design-forward product placement.
- Online Retail:Residential market access with smart-kitchen ecosystem bundling.
- Supermarkets:Mass-market penetration for entry-level electric and manual units.
Direct Sales leads commercial volume. Online Retail expands most quickly on smart-home convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in East Asian electronics corridors while consumption tilts toward North American and European hospitality markets. Supply chains route thermoelectric modules through Chinese semiconductor foundries before final assembly in Mexico and Vietnam for US-bound distribution. Regulatory divergence across efficiency standards and food-contact protocols fragments product specifications by destination market.
United States
Upscale restaurant operators in Manhattan and Chicago deploy tabletop chillers to compress server transit time and recover revenue from remote floor sections. The Department of Energy's standby power limits mandate sub-one-watt idle consumption, forcing burst-mode firmware redesigns. California's Napa and Sonoma corridor tasting rooms prioritize portable chilling infrastructure to extend outdoor service seasons without permanent construction.
Germany
Precision engineering traditions sustain demand for thermoelectric systems in Michelin-starred dining establishments across Bavaria and Baden-Württemberg. ECHA REACH compliance for silicone thermal mass materials extends certification timelines for import-bound suppliers. The Stuttgart industrial cluster hosts specialized Peltier module assemblers serving premium appliance OEMs with sub-50-watt specifications.
China
Domestic winery development in Ningxia and Shandong provinces generates procurement for electric chilling systems in tasting room construction. MIIT appliance efficiency labeling requirements compress allowable power consumption bands for thermoelectric devices. The Yangtze River Delta manufacturing belt concentrates bismuth telluride refining and Peltier module fabrication for global supply.
France
Champagne house hospitality programs in Reims and Épernay anchor demand for design-forward chilling equipment in heritage tasting environments. ANSM food-contact material regulations govern silicone insert formulations for export-compliant production. The Île-de-France region aggregates procurement decision-making for multinational hospitality groups operating across European portfolios.
Australia
Barossa Valley and Yarra Valley winery operators prioritize outdoor service flexibility amid seasonal tourism fluctuations. The country's national energy efficiency regulator maintains standby power thresholds that align with California Title 20 specifications, enabling product platform standardization. Melbourne and Sydney hospitality groups consolidate supplier relationships around bundled beverage service equipment procurement.
Instant Wine Chillers and Refreshers Market Competitive Landscape
The competitive structure tilts toward diversified appliance conglomerates with thermoelectric engineering capabilities. Market concentration remains moderate, with electronics specialists and hospitality-focused fabricators occupying distinct tier positions. Three archetypes dominate: diversified home appliance conglomerates leveraging smart-kitchen ecosystems, specialized thermal equipment manufacturers with Peltier module expertise, and design-forward lifestyle brands targeting premium gifting channels. Capacity expansion and strategic partnerships represent the dominant competitive moves, with suppliers securing semiconductor foundry allocation and hospitality distributor exclusivity.
Within the diversified conglomerate tier, LG Electronics and Samsung Electronics exemplify scale-driven positioning through integrated smart-home platforms. Bosch occupies a precision-engineering archetype rooted in German industrial traditions. Specialized hospitality fabricators include Rapid Ice Coolers, which anchors budget segment procurement with manual chilling expertise, and Viski, which represents design-forward stainless steel aesthetics in premium gifting channels. Vinglacé and Vochill exemplify lifestyle-brand positioning targeting outdoor and travel applications.
| Leading Market Players |
|---|
| Rapid Ice Coolers |
| LG Electronics |
| Viski |
| Bosch |
| Samsung Electronics |
| Vinglacé |
| Haier |
| Whirlpool Corporation |
| Vochill |
| Others |
Supply & Pricing Matrix
Multi-unit restaurant operator consolidation in Florida's resort corridor and California's wine country tilts procurement toward enterprise contract structures that compress unit margins while expanding lifetime contract values. This buyer concentration rewards suppliers with hospitality distributor exclusivity and modular bundling capabilities.
Pricing Analysis
Cost-down pressure on commercial-grade electric chillers accelerates because bismuth telluride supply constraints and DOE standby power compliance investments squeeze assembler margins. Pricing stratifies across premium stainless steel hospitality units, mid-tier thermoelectric restaurant systems, and economy manual chiller tiers. Brand premium and FDA food-contact certification tier separate Viski's gifting-channel positioning from Rapid Ice Coolers' budget hospitality penetration. Event catering procurement shows highest price sensitivity; Michelin-starred restaurant accounts demonstrate lowest.
Supply Chain Analysis
Dual-sourcing mandates from U.S. hospitality groups force Peltier module assemblers to qualify secondary semiconductor foundries beyond Yangtze River Delta primary suppliers. Manufacturing concentrates in China for bismuth telluride refining and module fabrication, Mexico for U.S.-bound final assembly, and Vietnam for secondary electronics integration. Raw material dependencies span bismuth telluride thermoelectric substrates, silicone thermal mass formulations, and stainless steel food-grade enclosures. Single-source vulnerability in Chinese refining operations creates input disruption exposure. Distribution runs through hospitality equipment distributors and direct enterprise sales to property management companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The U.S. Department of Energy's standby power standards and California Energy Commission Title 20 thresholds erect compliance moats that disadvantage non-compliant imports while rewarding domestic engineering investment. This cost-of-compliance dynamic favors incumbent assemblers with firmware development capabilities.
For Market Incumbents: Anticipate passive cooling substitution in budget hospitality accounts by accelerating modular accessory bundling that pairs electric bases with manual backup inserts. Secure captive supply of bismuth telluride through long-term offtake agreements with Chinese refiners to defend against input price volatility. Prioritize API development for restaurant management platform integration to lock in enterprise procurement relationships. For New Entrants and Emerging Players: Capture Texas Hill Country winery development outpacing permanent cooling infrastructure installation, where portable thermoelectric demand exceeds established supplier coverage. Target outdoor event catering procurement with silicone thermal mass systems requiring no electrical input. Pursue design-forward stainless steel aesthetics to penetrate premium gifting channels where Viski holds dominant positioning. For Investors and Strategic Acquirers: The window for entry favors specialized Peltier module assemblers with hospitality sector focus and existing FDA compliance pathways. Long-term viability hinges on smart-kitchen ecosystem integration capabilities and enterprise contract scale. Watch API-enabled inventory-temperature synchronization adoption rates as inflection indicator for platform consolidation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Foundry Allocation | Secures bismuth telluride module supply from Yangtze River Delta fabrication capacity. |
| API Development for Restaurant Platforms | Enables automated inventory-temperature synchronization with Toast and Oracle MICROS systems. |
| Modular Accessory Bundling | Captures dual-use purchase occasions across electric and manual cooling applications. |
| Enterprise Hospitality Contracts | Locks in multi-year procurement from Florida resort property management companies. |
| Firmware Redesign for DOE Compliance | Achieves sub-one-watt standby consumption through burst-mode Peltier thermal cycling. |
Research Methodology
Multi-period observation of thermoelectric module shipment volumes, hospitality construction permits, and energy efficiency certification timelines anchored the trend analysis, supplemented by interviews with restaurant equipment procurement directors, winery tasting room operators, Peltier module design engineers, and hospitality distributor sales executives. Secondary validation drew from U.S. Department of Energy appliance standards filings, California Energy Commission Title 20 compliance databases, FDA food-contact material registrations, and SEC 10-K disclosures from diversified appliance manufacturers. Bottom-up unit shipment modeling triangulated against top-down hospitality capital expenditure estimates.
Input-output matrix framing structured the forecast framework across product type, material specification, end-user vertical, and distribution channel dimensions throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market value expansion. Industry-specific inputs included Peltier module wattage efficiency curves, vineyard tasting room development pipelines, and smart-kitchen platform API adoption trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to bismuth telluride supply disruption, state-level energy code divergence, and hospitality sustainability certification evolution. Deviation in Chinese semiconductor export restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Electrolyte Beer Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
Stemware Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Flavored Whiskey Market
Alcoholic Beverages
Commercial Wine Dispenser Market
Alcoholic Beverages
Luzhou-Flavor Liquor Market
Alcoholic Beverages
Japan Beer Market
Alcoholic Beverages
Alcohol Enzymes Market
Alcoholic Beverages
India Gin Market
Alcoholic Beverages
Wine Filling Machine Market
Alcoholic Beverages
Rose Wine Market
Alcoholic Beverages
Spirits Market
Alcoholic Beverages
Cognac Brandy Market
Alcoholic Beverages
Middle East and Africa Kegs Market
Alcoholic Beverages
Ethanol Market