
 Medicinal Herbs Market | 2026-2036
Medicinal Herbs Market Size, Share, and Industry Trends Forecast 2026-2036
Medicinal Herbs Market Outlook
Modular single-herb and blended-format capsules is expanding choice for home users and wellness centers. Schwabe Group leverages its phytopharmaceutical heritage to dominate standardized extract production in Europe. Himalaya Global Holdings anchors its position through backward integration into cultivation across the Indian subcontinent. Bionorica SE specializes in clinical-grade herbal combinations for respiratory applications.
Medicinal herbs comprise dried, processed, or extracted plant materials containing bioactive alkaloids, flavonoids, or terpenoids used for therapeutic or preventive health outcomes, typically standardized to marker compound concentrations of 0.3–5% by dry weight. Their primary commercial purpose spans pharmaceutical APIs, dietary supplement formulations, and cosmetic active ingredients. Extracts command premium positioning due to dosage precision and regulatory compliance burdens, while teas retain volume leadership among home users across Asian markets. Pharmaceutical applications attract the most stringent certification requirements, whereas cosmetics represents the fastest-growing margin pool as clean-label actives displace synthetic alternatives.
FDA botanical drug guidance, EMA herbal monographs, and CDSCO Ayurvedic drug standards collectively shape formulation requirements, clinical evidence thresholds, and import-export protocols across major supply corridors. WHO traditional medicine strategy and ISO 17025 testing protocols further harmonize quality benchmarks for cross-border trade. Stakeholders must monitor evolving pharmacovigilance mandates and adapt traceability systems to maintain market access as regulatory divergence between herbal and conventional pharmaceutical pathways intensifies.
Market Dynamics
Standardization pressure from EMA herbal monographs and FDA botanical drug guidance is compressing formulation timelines while elevating quality thresholds for cross-border trade.
Growth Catalysts
- EMA Quality Frameworks:Harmonized monographs for valerian root and St. John's wort extracts accelerate batch approval cycles for German and Swiss phytopharmaceutical exporters.
- Ayurvedic Export Demand:CDSCO-registered ashwagandha and turmeric formulations gain shelf space in North American wellness retail chains.
- Clean-Label Cosmetic Actives:Synthetic paraben displacement by berberine and centella extracts drives contract manufacturing volumes for French and Korean skincare formulators.
Market Restraints
- Wild-Harvest Supply Volatility:Himalayan cordyceps and rhodiola populations face extraction quotas from China's NMPA and Tibet Autonomous Region forestry bureaus.
- Pharmacovigilance Cost Burden:EudraVigilance reporting requirements for serious adverse events add 12-18 month compliance overhead for multi-herb preparations.
- Synthetic API Substitution:Semisynthetic artemisinin from Sanofi and Huvepharma compresses pricing power for botanical Artemisia annua extract producers.
Strategic Opportunities
- Sub-Saharan Cultivation Expansion:Madagascar and Kenya pilot farms for devil's claw and pelargonium sidoides reduce European dependency on Namibian wild collection.
- Digital Therapeutic Pairing:Prescription herbal apps integrating with telemedicine platforms unlock reimbursement pathways in German statutory health insurance.
- Carbon-Negative Extraction:Supercritical CO2 processing powered by geothermal energy in Iceland commands premium positioning for Nordic bilberry and angelica extracts.
Industry Challenges
- Analytical Chemist Scarcity:HPLC and UPLC-MS method development for marker compound quantification outpaces university training pipelines in India and Eastern Europe.
- Seed-to-Shelf Traceability Integration:Blockchain verification systems require 18-24 month ERP overhauls for mid-sized cooperatives in Indonesia and Vietnam.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medicinal Herbs Market |
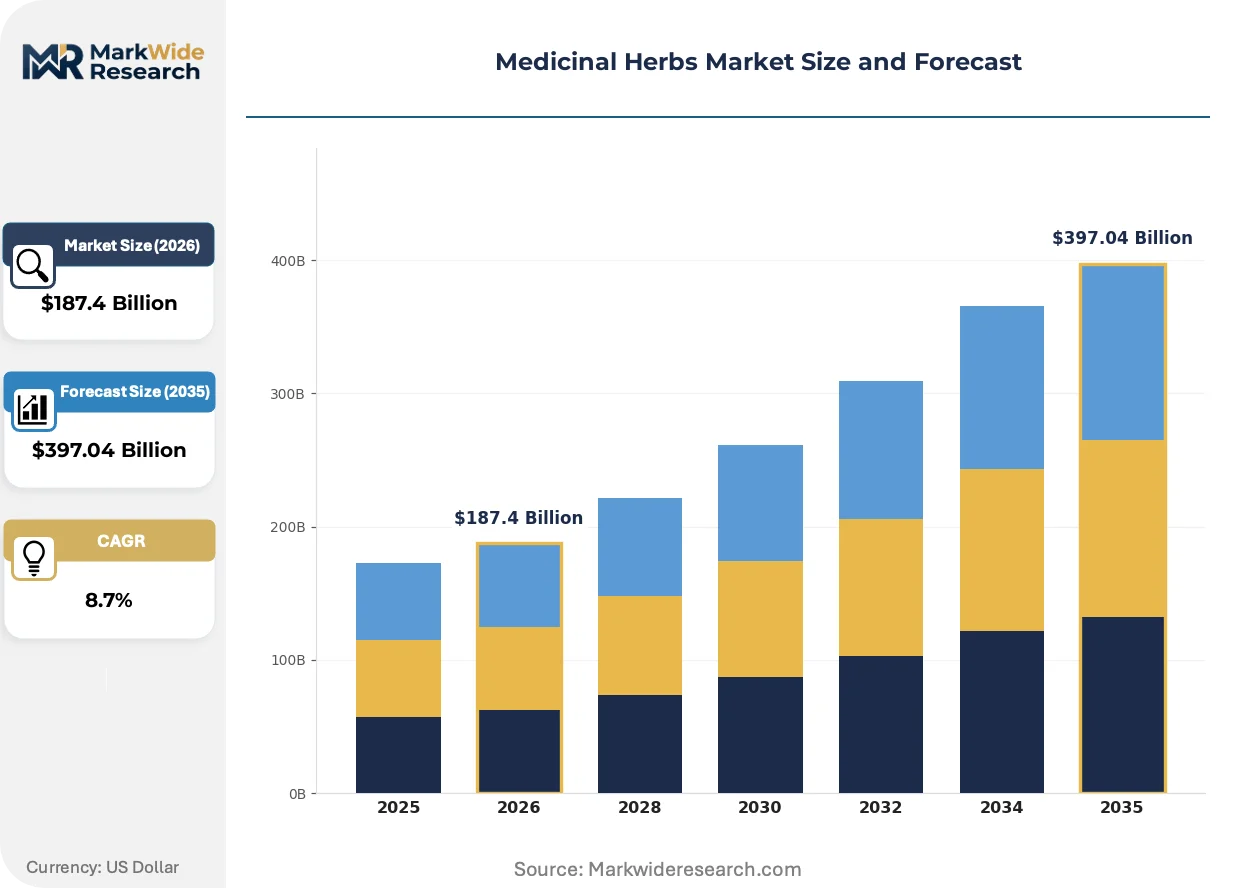
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Dried Herbs, Extracts, Teas Application: Pharmaceuticals, Dietary Supplements, Cosmetics, Traditional Medicine End User: Hospitals, Home Users, Wellness Centers, Research Institutions Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Schwabe Group, Himalaya Global Holdings, Bionorica SE, Herbalife International of America, Inc., Glanbia PLC, Dabur Ltd., Blackmores Limited, Gaia Herbs, Patanjali Ayurved Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medicinal Herbs Market Strategic Shifts
DNA barcoding and metabolomic fingerprinting are collapsing identity verification timelines while opening new patentable formulation spaces.
Metabolomic profiling platforms are rewriting quality assurance protocols by replacing chromatographic spot tests with full-spectrum chemical signatures. Contract laboratories in Singapore and Rotterdam deploy these systems for identity confirmation of powdered raw materials. The compression of release testing from weeks to days is enabling just-in-time manufacturing for seasonal respiratory formulations.
REACH botanicals registration deadlines are forcing European importers to consolidate supplier bases and pre-register novel extraction solvents. The industrial consequence is a 40% reduction in approved solvent options for polar compound extraction. German and Italian manufacturers are responding by retrofitting facilities for pressurized ethanol and water-only processing lines.
Wellness subscription models are displacing traditional pharmacy and health food store purchasing for chronic-condition herbal regimens. Direct-to-consumer brands bypass wholesale markups while capturing adherence data for formulation refinement. This channel shift concentrates in US and UK metropolitan markets where telehealth prescribing integrates with automated refill logistics.
Medicinal Herbs Market Segmentation
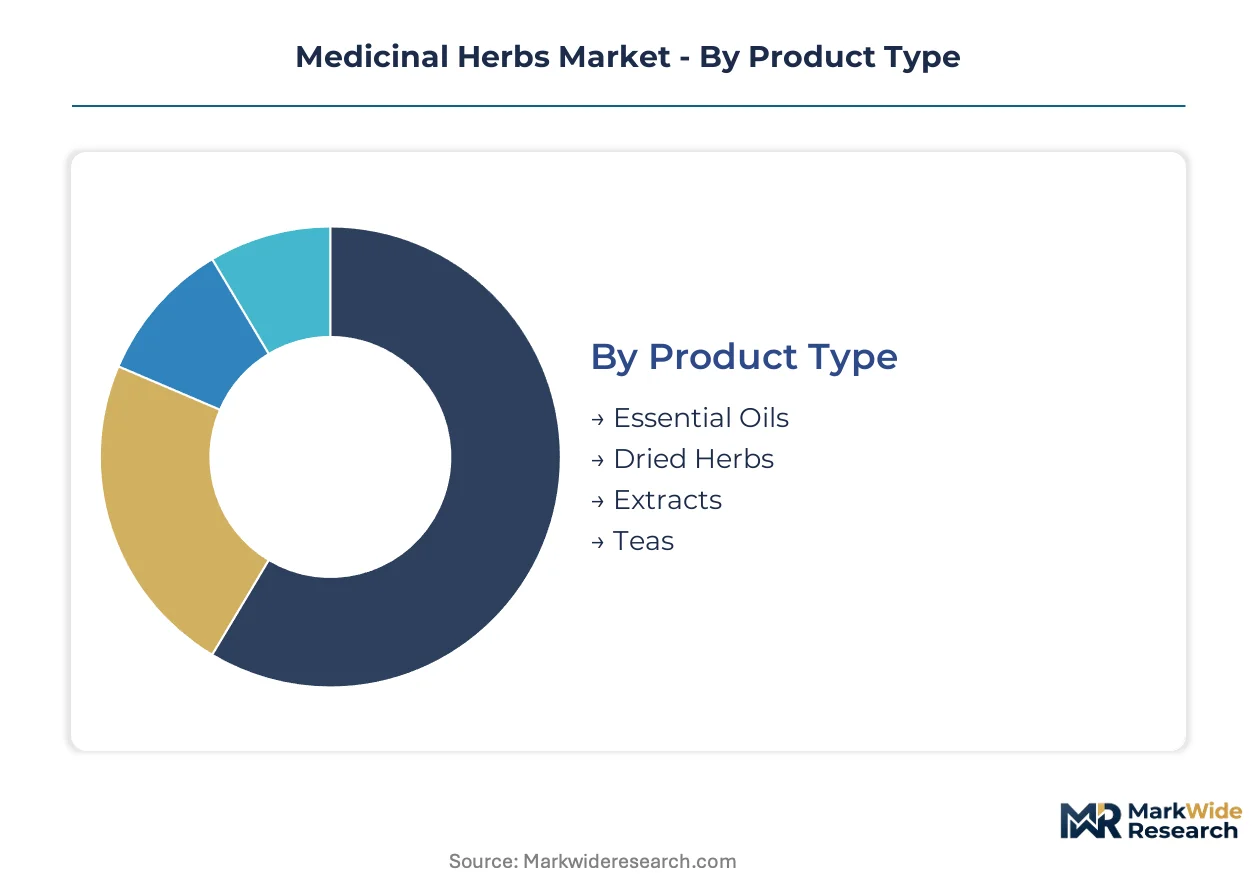
Segmentation in medicinal herbs reflects divergent regulatory burdens, formulation complexity, and channel economics across therapeutic and wellness applications. Product form determines quality certification pathways, while end-user context shapes dosage precision requirements and purchasing frequency.
Product Type:
Standardization technology separates commodity-grade from clinical-grade positioning, with extraction method and marker compound verification defining margin architecture.
- Extracts:Concentrated preparations standardized to 0.3–5% marker compounds by dry weight, requiring HPLC verification and EMA monograph compliance. German phytopharmaceutical manufacturers and CDSCO-registered Ayurvedic exporters dominate procurement, driven by pharmaceutical API demand and dosage precision requirements in clinical settings.
- Essential Oils:Steam-distilled or cold-pressed volatile fractions containing terpenoids and phenylpropanoids at therapeutic concentrations. French and Bulgarian lavender oil, plus Indian sandalwood distillates, supply cosmetic formulators seeking clean-label fragrance and antimicrobial actives.
- Dried Herbs:Whole or cut plant material air-dried to 10–12% moisture content, retaining cellular structure for decoction or infusion. Traditional medicine practitioners across South Asia and home users in East Asian markets sustain procurement volumes.
- Teas:Single-herb or blended loose-leaf and bagged preparations targeting preventive wellness consumption. Chinese and Japanese green tea extracts, plus South Asian tulsi and ginger blends, anchor retail shelf space.
Extracts lead on scale; essential oils lead on momentum.
Application:
Regulatory pathway intensity creates three distinct commercial zones with divergent evidence requirements and pricing power.
- Pharmaceuticals:Botanical drug submissions under FDA guidance or EMA herbal monographs demand multi-phase clinical evidence and pharmacovigilance systems. German Schwabe Group and Swiss phytopharmaceutical specialists concentrate manufacturing for prescription and OTC distribution.
- Cosmetics:Active ingredient incorporation into skincare and haircare formulations, displacing synthetic parabens and retinoids. Korean and French formulators drive contract manufacturing demand for centella and berberine extracts.
- Dietary Supplements:Capsule, tablet, and powder formats for wellness maintenance without disease claims. North American direct-to-consumer brands and European pharmacy chains capture recurring revenue through subscription models.
- Traditional Medicine:Ayurvedic, TCM, and Unani formulations following classical preparation methods. CDSCO-registered manufacturing facilities across India and NMPA-licensed producers in China serve domestic and diaspora populations.
Pharmaceuticals command premium pricing; cosmetics climbs fastest.
End User:
Purchasing authority and clinical oversight requirements segment demand by compliance burden and order frequency.
- Hospitals:Inpatient and outpatient departments prescribing standardized extracts for evidence-supported indications. German statutory health insurance reimbursement for herbal prescriptions sustains procurement volumes.
- Home Users:Self-directed consumers purchasing through retail and direct-to-consumer channels for preventive regimens. US and UK metropolitan markets show highest subscription adherence rates.
- Wellness Centers:Spas, Ayurvedic clinics, and integrative medicine practices dispensing customized formulations. Practitioner consultation fees support premium pricing for personalized protocols.
- Research Institutions:Universities and contract research organizations sourcing authenticated reference materials for clinical trials and pharmacological studies. ISO 17025-certified suppliers mandatory for publication-grade validation.
Home users dominate volume; hospitals retain pricing power.
Distribution Channel:
Channel selection determines margin capture, traceability investment, and customer data access for formulation refinement.
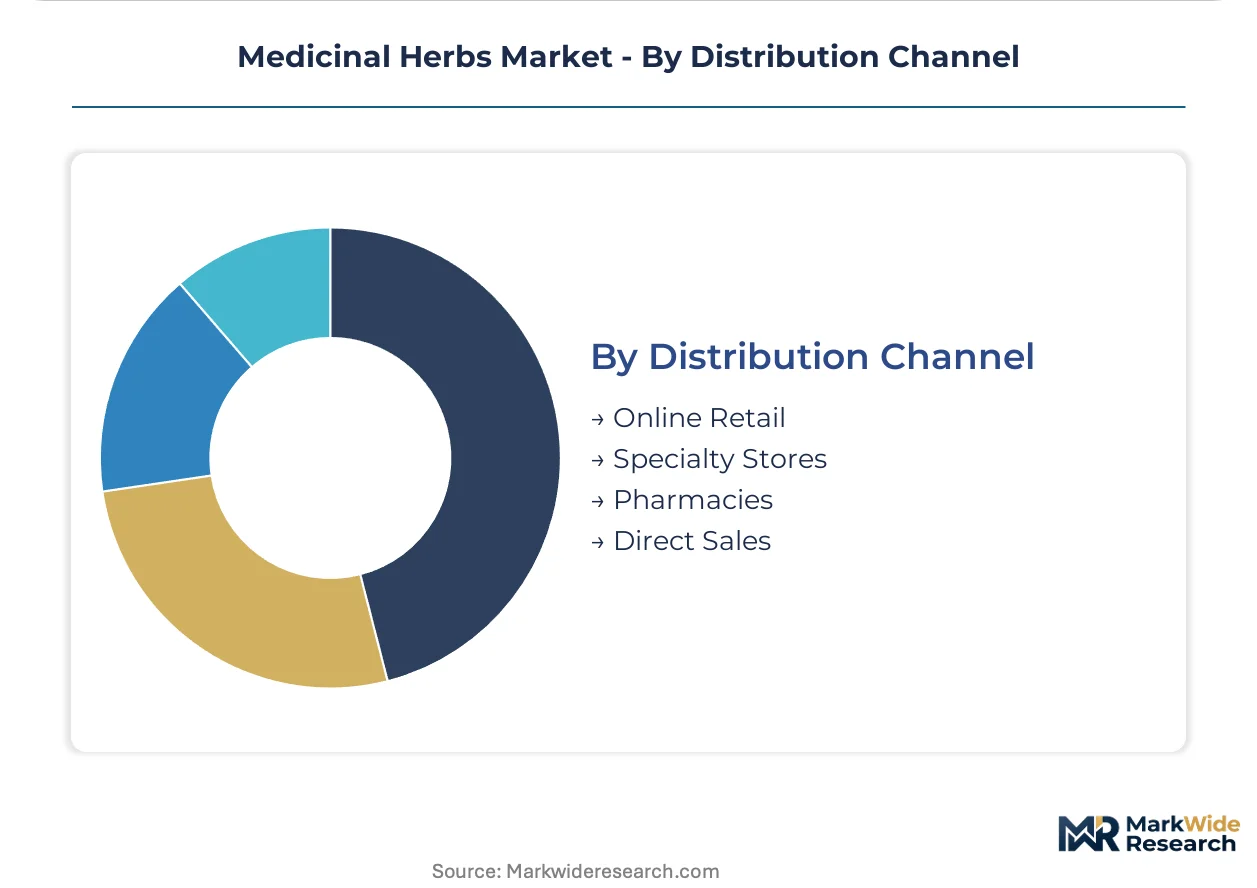
- Pharmacies:Brick-and-mortar and online pharmacy chains with licensed pharmacist oversight, required for prescription botanical drugs in Germany and Switzerland. Cold-chain logistics for liquid extracts elevate operational costs.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators bypassing wholesale markups. Subscription algorithms optimize refill timing based on adherence data from US and UK metropolitan users.
- Specialty Stores:Health food retailers and Ayurvedic dispensaries offering curated selections and practitioner consultation. Physical inspection of dried herb quality sustains foot traffic.
- Direct Sales:Practitioner networks and multi-level marketing organizations distributing through personal relationships. Commission structures align incentives with customer education investment.
Pharmacies anchor regulatory compliance; online retail expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Traditional medicine systems rooted in ancient pharmacopeias have shaped modern commercial infrastructure across multiple continents. Germany's phytopharmaceutical heritage and India's Ayurvedic industrial base established template production models now replicated elsewhere. Contemporary demand concentrates where regulatory frameworks accommodate botanical drug pathways alongside conventional pharmaceuticals.
Germany
Phytopharmaceutical prescriptions covered by statutory health insurance sustain manufacturing scale for standardized valerian and St. John's wort preparations. EMA herbal monographs originating from German regulatory leadership accelerate batch approvals for Schwabe Group and domestic competitors. Bavarian and Baden-Württemberg production clusters concentrate extraction and formulation capacity for European export markets.
India
Domestic Ayurvedic consumption and diaspora demand across North America and Europe drive cultivation-to-formulation integration by major holding companies. CDSCO registration requirements for classical and proprietary Ayurvedic medicines standardize quality verification for turmeric and ashwagandha exports. Maharashtra and Gujarat processing hubs coordinate with Karnataka and Madhya Pradesh contract farming networks for raw material security.
United States
FDA botanical drug guidance creates a dual pathway for prescription development alongside DSHEA-regulated dietary supplements. Direct-to-consumer subscription models concentrate in metropolitan markets where telehealth prescribing integrates with automated refill logistics. Utah and North Carolina manufacturing clusters serve domestic contract manufacturing demand for capsule and tablet formulations.
China
NMPA licensing of traditional Chinese medicine materials maintains domestic supply security while restricting wild-harvested species like cordyceps through extraction quotas. Sichuan and Yunnan cultivation bases scale domesticated alternatives to threatened Himalayan populations. Yangtze River Delta processing centers convert raw materials into granule and extract formats for hospital and retail distribution.
Switzerland
Swissmedic oversight of herbal medicinal products anchors premium positioning for Alpine botanical extracts including gentian and edelweiss. Geothermal-powered supercritical CO2 processing in Icelandic satellite facilities commands carbon-negative certification for Nordic bilberry and angelica derivatives. Basel-region pharmaceutical heritage informs phytopharmaceutical R&D investment by specialized manufacturers.
Medicinal Herbs Market Competitive Environment
Premium-margin players sit above commodity-margin players across standardization and certification intensity. The market structures into three tiers: multinational phytopharmaceutical conglomerates with integrated cultivation networks, mid-scale Ayurvedic and TCM specialists with regional brand recognition, and contract manufacturers serving private-label demand. Consolidation pressure favors acquisition of CDSCO-registered facilities by Western buyers seeking Ayurvedic export capacity. Competitive moves center on backward integration into cultivation and geographic expansion through regulatory harmonization.
Within the multinational phytopharmaceutical tier, Schwabe Group represents European standardization leadership while Himalaya Global Holdings anchors South Asian vertical integration. Bionorica SE occupies a specialized position in clinical-grade respiratory combinations. These three entities exemplify divergent strategic pathways: German monograph compliance, Indian cultivation-to-retail control, and indication-specific therapeutic positioning.
| Leading Market Players |
|---|
| Schwabe Group |
| Himalaya Global Holdings |
| Bionorica SE |
| Herbalife International of America, Inc. |
| Glanbia PLC |
| Dabur Ltd. |
| Blackmores Limited |
| Gaia Herbs |
| Patanjali Ayurved Ltd. |
| Others |
Value Chain & Pricing Dynamics
Wild-harvest cordyceps quotas from China's NMPA cascade through extraction costs to premium-tier botanical extracts, compressing margins for European phytopharmaceutical manufacturers while elevating pricing power for certified cultivators in Sichuan and Yunnan.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EMA-monograph extracts from dietary supplement grades and commodity dried herbs. Price differentiation rests on HPLC verification costs and CDSCO registration status. Pricing pressure stems from semisynthetic artemisinin substitution eroding botanical Artemisia annua extract premiums. Home users in direct-to-consumer channels exhibit highest price sensitivity; hospital procurement committees demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for European and Asian markets. Cultivation concentrates in India, China, and Madagascar for turmeric, ashwagandha, and devil's claw respectively. Processing draws from ethanol solvents, supercritical CO2 equipment, and HPLC verification services. Single-source vulnerability runs through Himalayan wild-harvest species subject to extraction quotas. Distribution runs through pharmacy chains, direct-to-consumer platforms, and specialty Ayurvedic dispensaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in medicinal herbs rests on carbon-negative extraction premiums and subscription-model adherence data reducing customer acquisition costs.
For Market Incumbents: To counter synthetic API substitution in antimalarial and respiratory categories, Schwabe Group and Himalaya Global Holdings should deepen backward integration into certified cultivation networks in Karnataka and Madhya Pradesh. EMA pharmacovigilance compliance investment creates switching costs for hospital procurement committees. For New Entrants and Emerging Players: Subscription-fatigued wellness consumers in UK and US metropolitan markets represent the most penetrable buyer archetype. White-space targets include personalized Ayurvedic protocols paired with telehealth platforms, and carbon-negative Nordic bilberry extracts for French and Korean cosmetic formulators. Direct-to-consumer launch with adherence-tracking apps bypasses pharmacy wholesale markups. For Investors and Strategic Acquirers: Roll-up economics work for CDSCO-registered Ayurvedic manufacturers because regulatory compliance creates scarcity value for Western buyers seeking export capacity. Five-to-ten year viability hinges on traceability technology adoption rates. Acquisition target archetype: mid-scale facilities with ISO 17025 certification and established contract farming networks. Signal to watch: German statutory health insurance reimbursement expansions for herbal prescriptions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Cultivation | Karnataka contract farming networks secure turmeric and ashwagandha supply for CDSCO-registered exporters. |
| Carbon-Negative Extraction Certification | Geothermal-powered supercritical CO2 processing in Iceland commands premium positioning for Nordic botanicals. |
| Digital Therapeutic Platform Integration | Prescription herbal apps paired with German statutory health insurance unlock reimbursement pathways. |
| Blockchain Traceability Implementation | Seed-to-shelf verification systems satisfy EudraVigilance pharmacovigilance requirements for multi-herb preparations. |
| Direct-to-Consumer Subscription Launch | Automated refill logistics capture adherence data for formulation refinement in US and UK metropolitan markets. |
Study Parameters
Coverage spans Germany, India, China, and the United States, with primary inputs from each. Cultivation directors at contract farming networks, extraction facility managers, CDSCO regulatory affairs leads, and pharmacy procurement managers contributed structured interviews. Secondary validation drew from EMA herbal monographs, FDA botanical drug guidance filings, CDSCO Ayurvedic drug registration databases, and ISO 17025 laboratory certification records. Bottom-up volume estimates from cultivation acreage and extraction capacity triangulated against top-down pharmaceutical API demand projections.
Rate-of-change decomposition across the analysis window separates volume growth from pricing dynamics and mix shifts. Segmentation dimensions modeled include product form, application, end user, and distribution channel. CAGRs were derived from regression analysis against historical regulatory approval timelines and cultivation yield trends. Industry-specific forecast inputs incorporated wild-harvest quota enforcement intensity and EudraVigilance reporting compliance adoption curves.
Inputs from CDSCO registration databases and EMA herbal monograph revision schedules were available through the study window; gaps in proprietary cultivation yield data from Tibetan Autonomous Region cooperatives introduce uncertainty bands around cordyceps supply projections. Forecasts reflect documented assumptions regarding regulatory harmonization pace and synthetic substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Space Food Market
Specialty Foods
Super Foods Market
Specialty Foods
Therapeutic Dog Food Market
Specialty Foods
Acacia Honey Market
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
North America Alcohol-Infused Ice Cream Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Global Diet Food and Beverages Market
Specialty Foods
Malaysia Manuka Honey Market
Specialty Foods
Global Pine Pollen Market
Specialty Foods
Low Calorie Diet Meal Plan Market
Specialty Foods
Hot Pot Market
Specialty Foods
Manuka Honey Market
Specialty Foods
Cannabis-Infused Burger Market
Specialty Foods
Chamomile Market
Specialty Foods
Low-Fat Low-Calorie Desserts Market