
 Alcoholic Beverages Market | 2026-2036
Alcoholic Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Alcoholic Beverages Market Intelligence
The rise of ready-to-drink cocktails and variety packs is expanding consumer choice beyond traditional single-beverage formats. Anheuser-Busch InBev leverages its vast distribution network to introduce these new product configurations across global markets. Diageo differentiates its market position through a strong portfolio of premium spirits. Meanwhile, Heineken competes by innovating within its core beer segment and expanding into adjacent categories.
Alcoholic beverages are liquids containing ethanol, produced through the fermentation of grains, fruits, or other sugar sources, and sometimes followed by distillation. Their primary commercial purpose is for recreational consumption, with products categorized by alcohol by volume (ABV) and production method. The beer segment remains the largest by volume, but spirits and ready-to-drink cocktails show significant value growth. Sales through online retail channels are gaining share from traditional on-trade establishments like bars and restaurants.
Regulations from bodies like the US FDA, the European Union's directives on labeling, and China's GB standards govern production and marketing. These frameworks mandate strict controls on advertising, health warnings, and ingredient transparency, shaping product formulation. Navigating the divergent rules on digital marketing and e-commerce sales for alcohol is a critical challenge for brand owners seeking international expansion.
Market Dynamics
The alcoholic beverages market is being fundamentally altered by the fragmentation of consumer demand, moving away from monolithic brand loyalty towards occasion-based consumption. This shift fuels rapid product innovation in formats like ready-to-drink cocktails and variety packs, challenging traditional category boundaries.
Growth Catalysts
- Premiumization in Emerging Economies:Rising disposable incomes in countries like India and Brazil are fueling consumer appetite for premium and super-premium spirits, shifting consumption patterns from local spirits to globally recognized brands.
- Ready-to-Drink (RTD) Innovation:The development of sophisticated, high-quality RTD cocktails and hard seltzers appeals to consumer demand for convenience and variety, creating a significant new revenue stream outside of traditional beer and wine.
- E-commerce Channel Expansion:The growth of online retail platforms and direct-to-consumer (DTC) models provides brands with new routes to market, bypassing traditional distribution and enabling personalized marketing to niche consumer segments.
Market Restraints
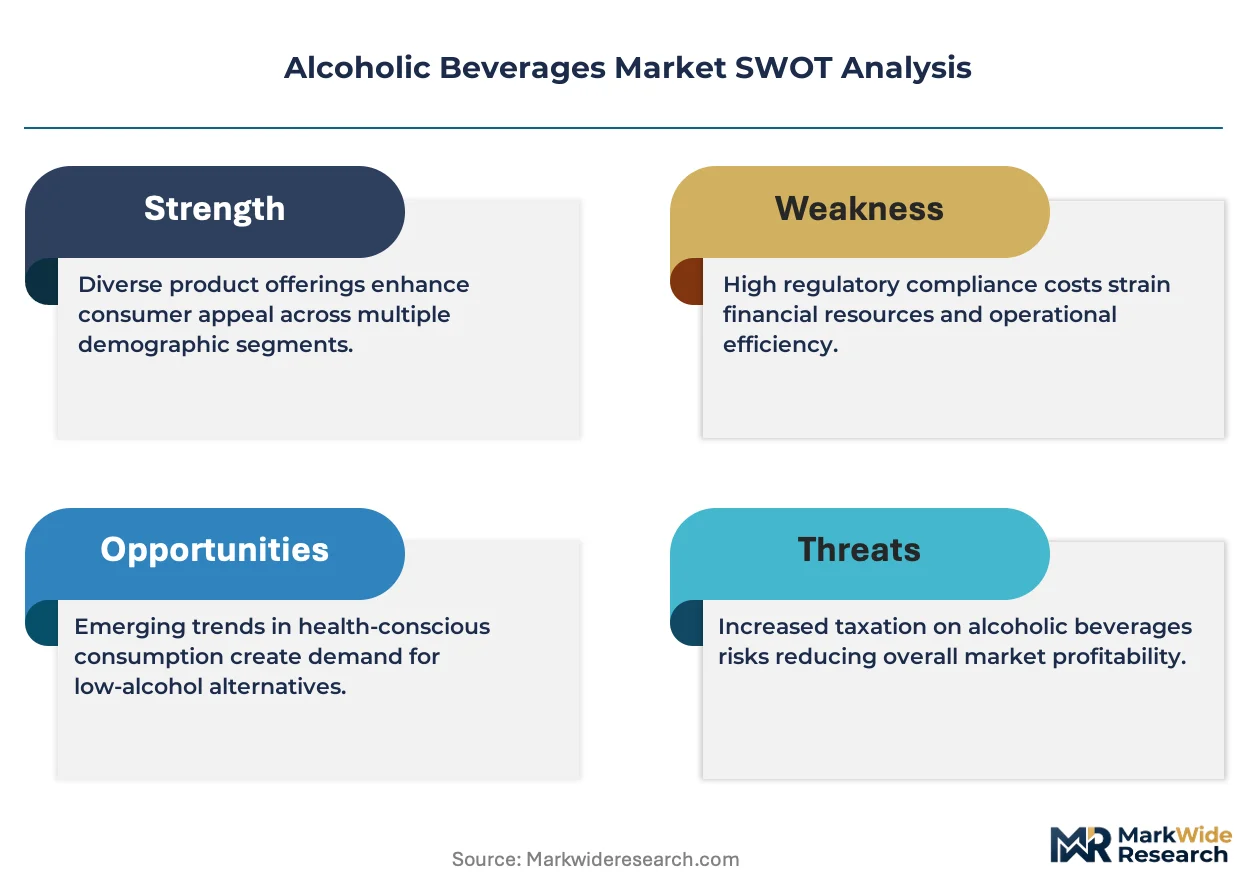
- Divergent Marketing Regulations:A complex web of national and local rules governing alcohol advertising, particularly on digital and social media platforms, creates significant compliance burdens and restricts brand messaging in key markets.
- Agricultural Input Volatility:The production of alcohol depends on agricultural commodities like barley, grapes, and agave, whose prices and availability are subject to climate change, weather events, and geopolitical trade disputes.
- Public Health Scrutiny:Heightened focus on alcohol-related health risks leads to stricter government policies, including higher taxation, mandatory health warnings, and campaigns promoting moderation or abstinence, which can dampen overall consumption volume.
Strategic Opportunities
- No- and Low-Alcohol Segments:Investing in the development of sophisticated non-alcoholic spirits, wines, and beers caters to a growing demographic of health-conscious consumers seeking to moderate their alcohol intake without sacrificing social rituals.
- Sustainable Packaging:Adopting lightweight glass, recycled aluminum, and paper-based bottle formats offers a path to meet regulatory mandates like the EU Green Deal and appeal to environmentally conscious consumers.
- Geographic White Space:Entering underpenetrated markets in parts of Southeast Asia and Africa with tailored product portfolios and localized marketing presents a long-term growth frontier beyond mature North American and European markets.
Industry Challenges
- Supply Chain Complexity:The explosion in product SKUs from flavor variations and format diversification creates significant logistical challenges in forecasting, inventory management, and distribution, straining existing supply chain capabilities.
- Digital Commerce Compliance:Navigating the patchwork of regulations for online age verification, interstate shipping, and digital taxation for alcohol sales is a critical operational hurdle for brands scaling their e-commerce presence.
- Brand Architecture Management:Established beer and spirits producers face the challenge of extending their brand equity into new categories like seltzers or RTDs without diluting their core premium identity or creating internal channel conflict.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcoholic Beverages Market |
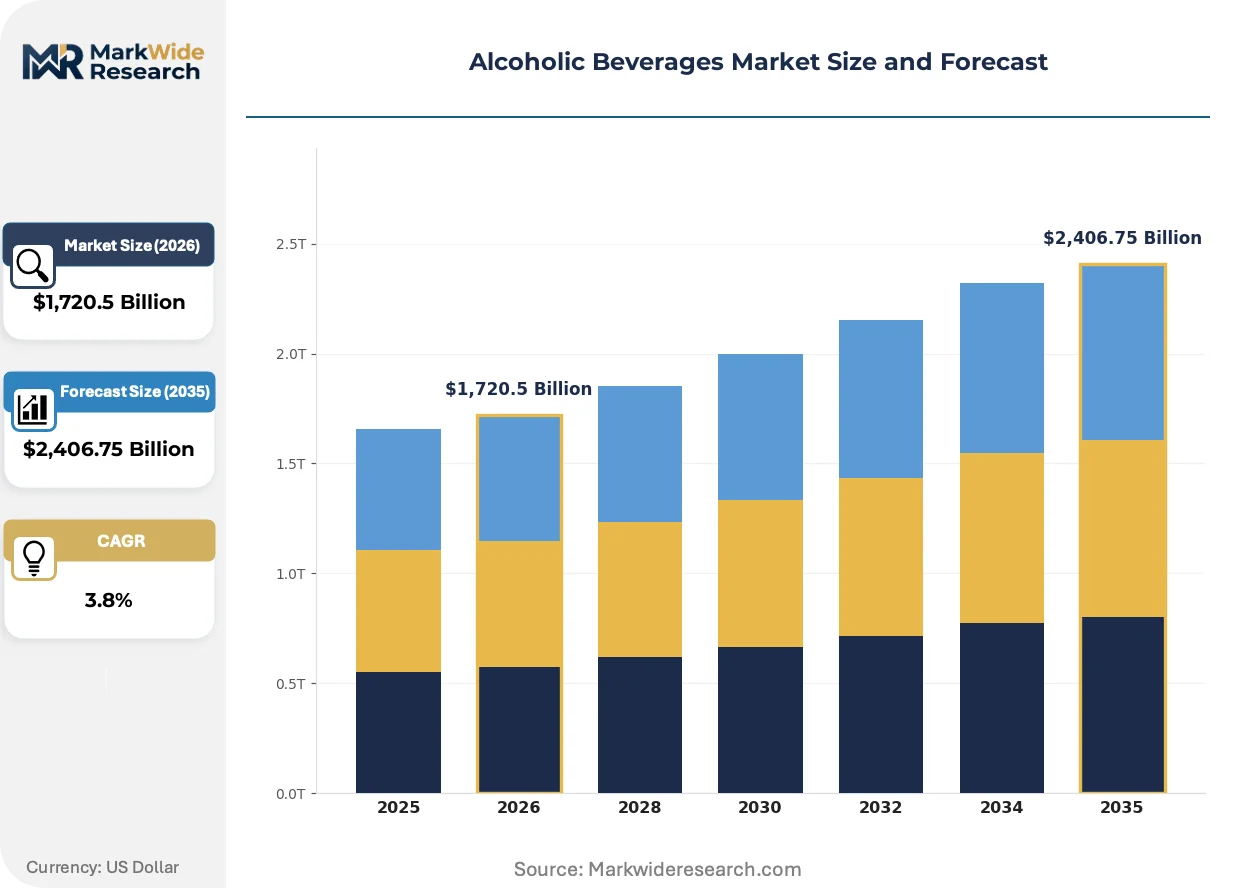
| Market Size in 2026 | $1,720.5 Billion |
| Market Size in 2035 | $2,406.75 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Beverage Type: Beer, Wine, Spirits, Cider, Ready-to-Drink Cocktails Packaging Format: Bottle, Can, Keg, Tetra Pak, Bag-in-Box Distribution Channel: On-Trade, Off-Trade, Online Retail, Convenience Stores, Supermarkets Consumer Age Group: Legal Drinking Age, Young Adults, Middle-Aged, Seniors |
| Companies Covered | Pernod Ricard, Carlsberg, Anheuser-Busch InBev, Molson Coors, E&J Gallo Winery, Diageo, Constellation Brands, Brown-Forman, Heineken, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcoholic Beverages Market Strategic Shifts & Innovations
The convergence of convenience, wellness, and digital accessibility is redefining consumption occasions and product development. This evolution pressures brands to innovate beyond their core categories and embrace new technologies in both formulation and packaging to stay relevant with a more discerning consumer base.
Advanced fermentation and flavor science allows for the creation of sophisticated no- and low-alcohol beverages. Health-conscious consumers and younger demographics are rapidly adopting these alternatives that closely mimic the taste and mouthfeel of traditional alcoholic drinks. The pursuit of authentic flavor profiles in this segment is overtaking older, less effective de-alcoholization techniques, establishing a new premium tier within the non-alcoholic space.
Regulations focused on environmental sustainability are directly influencing product design and material selection. The EU Green Deal, with its stringent targets for packaging waste reduction, is compelling producers to invest in lightweight glass, recycled aluminum, and alternative formats like bag-in-box. The wine and spirits segments, historically reliant on heavy, single-use glass bottles, are the most affected and are now actively exploring innovative packaging to ensure market access.
A behavioral shift toward at-home entertainment and cocktail culture is altering where and how consumers purchase alcohol. This trend favors online retailers and direct-to-consumer (DTC) channels, which offer wider selection and delivery convenience, disrupting the dominance of on-trade establishments like bars and restaurants for certain occasions. This pattern is most pronounced in North American and European markets, where consumers increasingly buy premium ingredients and kits for home-based social events.
Alcoholic Beverages Market Segmentation
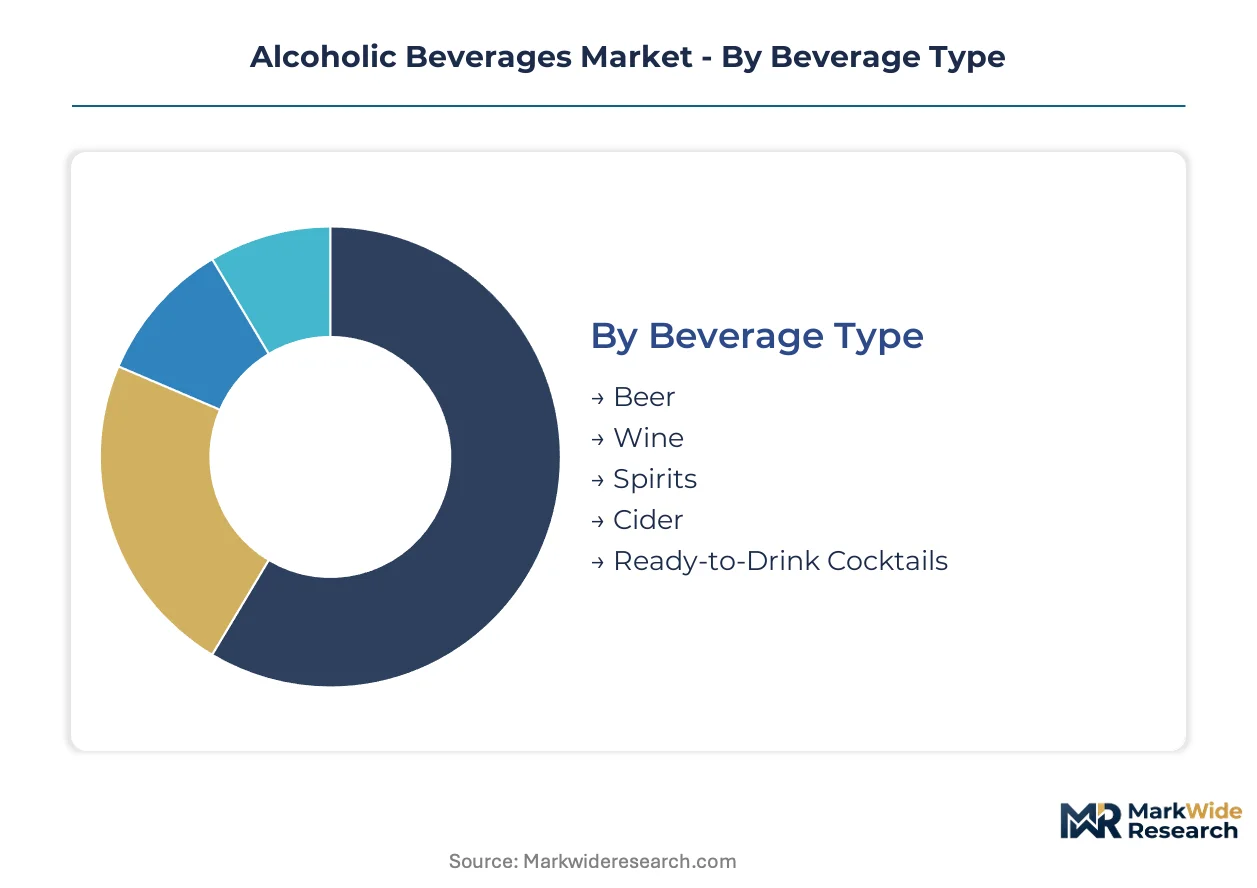
The Alcoholic Beverages Market is segmented to reflect the diverse preferences and consumption behaviors of consumers across various product types and purchasing channels. Understanding these distinct segments allows producers to tailor product innovation, marketing strategies, and distribution networks effectively. Market dynamics are shaped by evolving consumer lifestyles and regulatory environments.
Beverage Type:
Consumer preferences for taste, occasion, and alcohol content primarily drive purchasing decisions within the beverage type segment.
- Ready-to-Drink Cocktails:These pre-mixed beverages offer convenience and variety, often featuring spirits, wine, or malt bases. Demand concentrates among young adult consumers in North American and European markets seeking sophisticated, easy-to-consume options.
- Spirits:This category encompasses distilled alcoholic beverages like whiskey, vodka, gin, and rum, typically having higher alcohol by volume. Consumption shifts towards premium spirits in emerging economies like India and Brazil, driven by rising disposable incomes.
- Beer:Produced by fermenting cereal grains, beer remains the largest segment by volume, offering a wide range from light lagers to craft ales.
- Wine:Made from fermented grapes, this category includes still, sparkling, and fortified varieties, primarily consumed in European and North American markets.
- Cider:An alcoholic beverage from fermented apple juice, cider offers a gluten-free alternative, gaining traction in specific European markets.
Beer leads on volume scale; Ready-to-Drink Cocktails leads on value momentum.
Packaging Format:
Environmental concerns and consumer convenience are key considerations influencing the choice of packaging format for alcoholic beverages.
- Can:Aluminum cans offer lightweight, recyclable, and portable solutions, favored for ready-to-drink cocktails, beers, and hard seltzers. The EU Green Deal drives innovation in recycled aluminum for this format.
- Bottle:Glass bottles remain a traditional choice for wines, spirits, and premium beers, offering perceived quality and shelf stability. Producers invest in lightweight glass designs to meet sustainability regulations.
- Keg:Large-format containers designed for draught systems, primarily used in on-trade establishments for beer distribution.
- Tetra Pak:Multi-layered carton packaging provides a lightweight option for wine and some RTD beverages, reducing breakage risk.
- Bag-in-Box:This format consists of a flexible bag inside a cardboard box, commonly used for larger volumes of wine, extending freshness.
Sustainability mandates and consumer portability needs are redefining packaging priorities across all beverage types.
Distribution Channel:
The customer's desire for convenience and access dictates the preferred distribution channel for purchasing alcoholic beverages.
- Online Retail:E-commerce platforms and direct-to-consumer models provide extensive product selection and home delivery. This channel gains significant share from traditional establishments, driven by at-home consumption trends in North America and Europe.
- On-Trade:This channel includes bars, restaurants, and clubs where alcoholic beverages are consumed on-premise. It remains vital for premium spirits and social occasions, despite shifts towards at-home entertainment.
- Off-Trade:This segment includes retail outlets where beverages are purchased for off-premise consumption, encompassing supermarkets and liquor stores.
- Convenience Stores:Smaller retail formats offering quick access to a limited selection of alcoholic beverages, catering to immediate consumption needs.
- Supermarkets:Large retail chains providing a broad assortment of alcoholic beverages alongside groceries, appealing to regular household purchasing.
Online platforms are rapidly gaining market share, challenging traditional brick-and-mortar dominance.
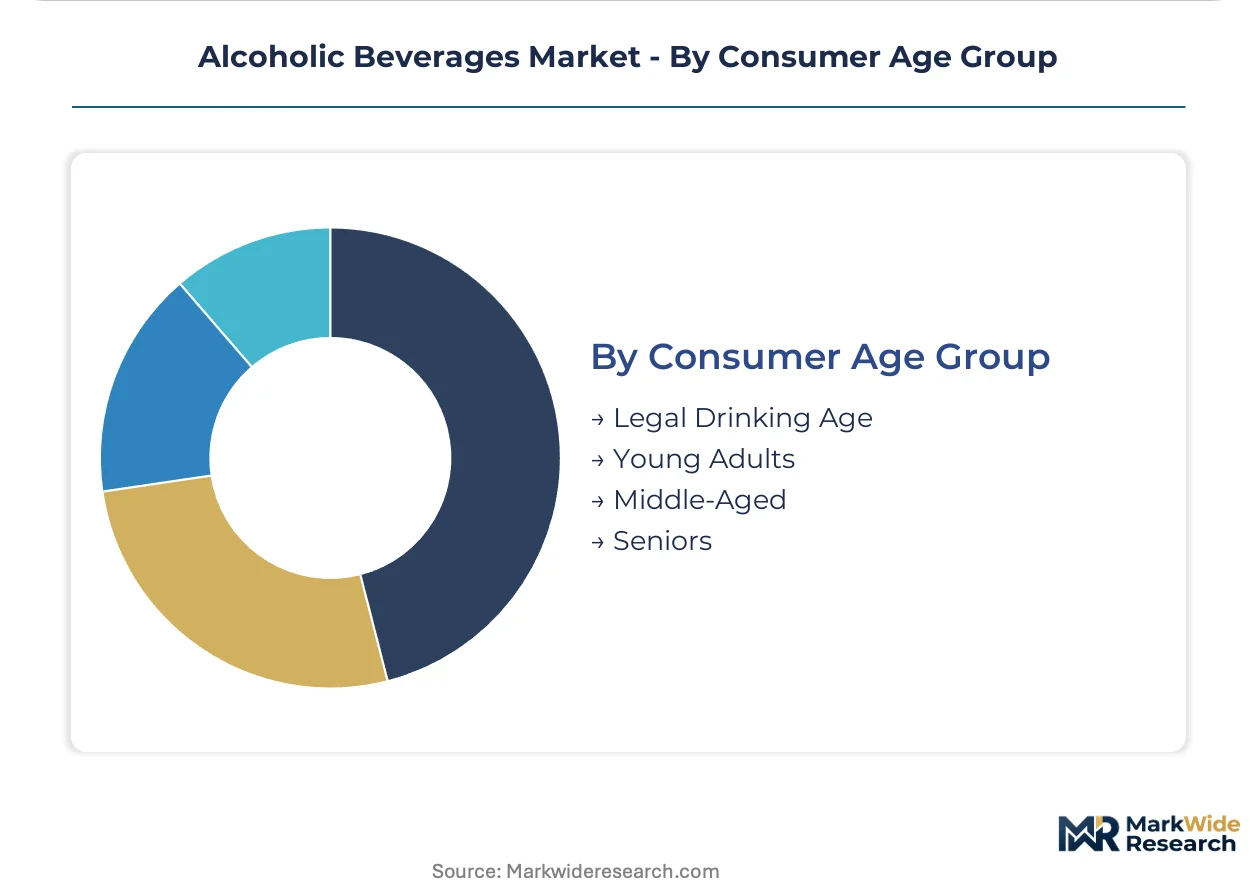
Consumer Age Group:
Distinct consumption patterns and lifestyle choices define the alcoholic beverage preferences across different consumer age groups.
- Young Adults:This demographic, typically aged 21-35, shows strong demand for ready-to-drink cocktails, hard seltzers, and no- and low-alcohol alternatives. Their purchasing decisions are influenced by social media trends and a preference for convenience and variety.
- Legal Drinking Age:This foundational group represents all individuals permitted to legally purchase and consume alcohol within their respective jurisdictions. This segment forms the base for all market activity.
- Middle-Aged:Consumers in this group often exhibit loyalty to established brands and premium spirits, frequently consuming wine and craft beer.
- Seniors:This demographic typically maintains traditional consumption habits, showing a preference for classic wines, beers, and spirits, often in moderate quantities.
Brands must tailor product innovation and marketing to resonate with the evolving preferences of younger demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The alcoholic beverages market traces its origins to ancient civilizations, with fermentation techniques developing across diverse cultures globally. Traditional brewing and distillation methods scaled significantly with industrialization, establishing foundational production hubs. Today, market evolution reflects a blend of heritage and modern consumer shifts.
United States
Demand for ready-to-drink cocktails and premium spirits drives innovation across American markets. The US FDA regulates product safety and labeling, influencing formulation and marketing practices for new product categories. Craft breweries and distilleries cluster in states like California and Oregon, fostering diverse product offerings that cater to local preferences.
Germany
European consumers prioritize no- and low-alcohol beer alternatives, influencing German brewers and product development. The EU Green Deal mandates sustainable packaging, pushing producers towards recycled materials and lighter glass bottles. Bavaria remains a central hub for traditional beer production and new beverage development, particularly in the non-alcoholic segment.
India
Rising disposable incomes in India fuel premiumization trends, particularly for imported spirits and high-end wines. The country's FSSAI sets standards for food and beverage safety, impacting local and international brands seeking market entry. Major metropolises like Mumbai and Delhi see concentrated consumption of premium alcoholic products and expanding e-commerce channels.
Brazil
Consumer appetite for convenience products like RTD cocktails is expanding rapidly in urban centers across Brazil. ANVISA oversees health and sanitation regulations for alcoholic beverages, ensuring product quality and ingredient transparency. São Paulo serves as a key distribution and innovation center for new beverage formats, adapting to evolving local tastes.
Japan
Established brands and innovative craft spirits cater to discerning Japanese tastes for quality and craftsmanship. METI guidelines influence packaging and recycling initiatives within the beverage industry, promoting environmental stewardship. Tokyo's vibrant nightlife drives demand for diverse and high-quality alcoholic selections, including premium sake and whiskies.
Alcoholic Beverages Market Key Industry Players
Premium-margin players sit above commodity-margin players across the alcoholic beverage market's value chain, creating distinct competitive tiers. The landscape presents a complex structure, with established global conglomerates operating alongside numerous regional craft producers and niche specialists. Strategic archetypes include portfolio diversifiers leveraging extensive distribution, core segment innovators focusing on product quality, and emerging market specialists adapting to local tastes. Companies primarily engage in geographic expansion and brand portfolio diversification to maintain market position and capture new consumer segments.
On the premium-tier vector, Diageo exemplifies a focus on high-value spirits brands, leveraging its global reach and brand equity to target affluent consumers. Anheuser-Busch InBev anchors the market's scale-driven beer segment, continuously innovating within its core offerings and expanding into adjacent categories like hard seltzers. Heineken occupies a position as a core beer innovator, expanding into adjacent categories and emphasizing sustainable production practices. These global entities navigate complex regulatory environments and evolving consumer preferences through diversified product offerings and extensive distribution networks across various regions.
| Leading Market Players |
|---|
| Pernod Ricard |
| Carlsberg |
| Anheuser-Busch InBev |
| Molson Coors |
| E&J Gallo Winery |
| Diageo |
| Constellation Brands |
| Brown-Forman |
| Heineken |
Cost & Logistics Intelligence
The EU Green Deal, specifically its packaging waste mandates, gates qualified supply of sustainable materials and influences premium-tier pricing access for environmentally conscious brands. This regulatory pressure forces producers to re-evaluate traditional material sourcing and manufacturing processes. These shifts directly impact cost structures across the value chain.
Pricing Analysis
Tiered pricing across premium, standard, and economy levels characterizes the alcoholic beverages market. Brand premium and the quality grade of ingredients drive significant price differentiation. Pricing softness reflects intense competition in the mainstream beer segment. Young adult consumers show less price sensitivity for innovative ready-to-drink cocktails, while traditional beer consumers remain highly sensitive to price fluctuations.
Supply Chain Analysis
Agricultural input supply draws from diverse global regions, with barley originating from Europe and North America, and agave from Mexico. Grapes for wine production concentrate in Europe and the Americas. The production of alcohol depends on commodities like sugar, barley, and agave. Agricultural input volatility, influenced by climate change and geopolitics, presents a structural supply chain risk. Distribution runs through a hybrid model, combining traditional on-trade and off-trade channels with expanding online retail platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage play, as the cost of raw material sourcing and production differs significantly between established European markets and emerging economies like India.
For Market Incumbents:
Acquire specialized craft producers to broaden brand portfolios and reach niche consumer segments. Expand ready-to-drink cocktail production capacity to counter consumer fragmentation. Leverage extensive distribution networks to introduce no- and low-alcohol alternatives across global markets. Invest in digital marketing compliance expertise to navigate divergent national regulations, mitigating a significant threat.
For New Entrants and Emerging Players:
Health-conscious consumers represent an underserved buyer archetype, seeking sophisticated non-alcoholic spirits and beers. Target underpenetrated Southeast Asian and African markets with localized product portfolios. Focus on direct-to-consumer e-commerce channels for personalized marketing and efficient market entry. Develop unique flavor profiles and sustainable packaging to differentiate offerings within the competitive landscape.
For Investors and Strategic Acquirers:
Roll-up economics work for regional craft producers because market fragmentation allows for consolidation of niche brands with strong local followings. Long-term viability rests on sustained premiumization trends and the growth of convenience formats. Target innovative ready-to-drink brands or distilleries with unique intellectual property and strong e-commerce penetration. A shift in digital marketing regulation enabling broader online advertising warrants ongoing watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Brand Extension into No- and Low-Alcohol | Expands consumer base by catering to health-conscious preferences and moderation trends. |
| Direct-to-Consumer Launch for RTDs | Bypasses traditional distribution, enabling personalized marketing and increased margin capture. |
| Premium Tier Introduction in Emerging Markets | Captures rising disposable incomes and aspirational consumption in key growth regions. |
| Distribution Channel Expansion via E-commerce | Increases market reach and convenience for consumers, adapting to evolving purchasing behaviors. |
| Green Manufacturing Transition for Packaging | Addresses regulatory mandates and consumer demand for sustainability, enhancing brand reputation. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a comprehensive market view. Primary interviews engaged brand managers, procurement leads, regulatory affairs specialists, and e-commerce platform managers across major markets. Secondary validation drew from FSSAI standards, EU Green Deal reports, ANVISA regulations, and company financial filings, triangulating bottom-up and top-down data.
Segment-weighting approaches informed the analytical framework for market sizing and forecasting. This framework modeled beverage type, packaging format, distribution channel, consumer age group, and regional regulatory environments. Compound annual growth rates were derived from historical data and expert consensus, incorporating disposable income growth and raw material price forecasts across the projection horizon.
Underlying measurement precision varies by segment; established beer and wine categories carry tighter precision than others. Forecasts reflect assumptions regarding evolving consumer preferences and regulatory shifts. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
South America Alcoholic Beverages Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Chocolate Liqueur Market
Alcoholic Beverages
India Tequila Market
Alcoholic Beverages
Home Beer Brewing Machine Market
Alcoholic Beverages
Brewing Supplies Market
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
Sparkling Wine Market
Alcoholic Beverages
US Wine Cooler Market
Alcoholic Beverages
Europe Wine Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Wine Glass Market
Alcoholic Beverages
Mexico Tequila Market
Alcoholic Beverages
Portable Keg System Market
Alcoholic Beverages
Pinot Noir Market
Alcoholic Beverages
Tanzania Spirits Market