
 Asia-Pacific Alcoholic Beverage Market | 2026-2036
Asia-Pacific Alcoholic Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Alcoholic Beverage Market Outlook
E-commerce and direct-to-consumer platforms is reconfiguring how alcoholic beverages reach buyers across Asia-Pacific. Pernod Ricard leverages its digital cellar door initiatives to capture premium wine and spirits buyers in Australia and Japan. Anheuser-Busch InBev anchors its position through extensive brewery networks and wholesale partnerships that dominate Southeast Asian beer distribution. Suntory Holdings differentiates via specialized whisky portfolios that command shelf space in high-end off-trade channels.
Asia-Pacific alcoholic beverages encompass fermented and distilled products typically containing ethanol concentrations from four percent to over forty percent by volume, produced through brewing, fermentation, or distillation processes for recreational and social consumption. Beer retains the largest volume footprint across the region, though spirits generate disproportionate margin concentration in China and India. Wine competes for occasion-based drinking among young adults in metropolitan Australia and Japan. Cider occupies niche positioning in seasonal markets with limited geographic penetration outside Australasia.
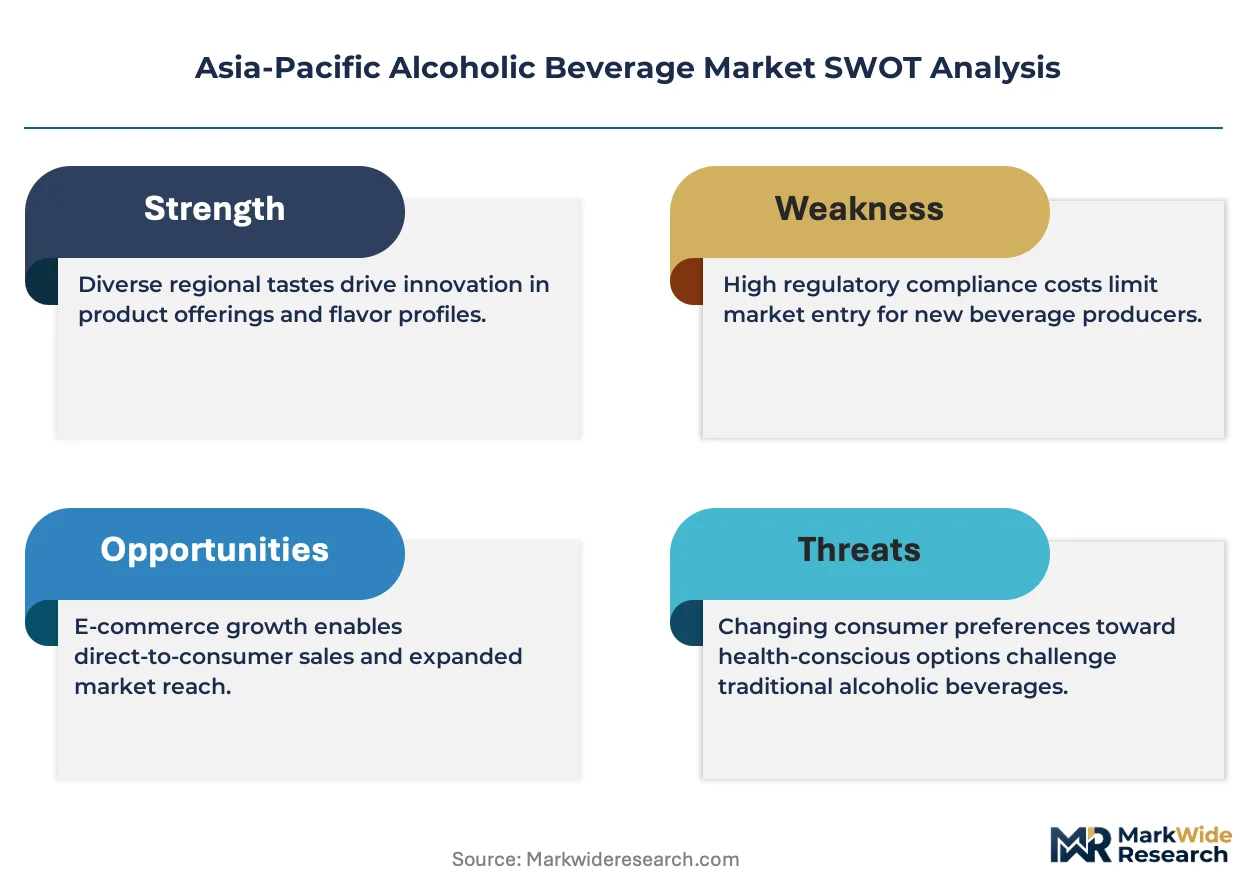
FSSAI in India enforces strict labeling and advertising standards that constrain how brands target young adults, while Australia's ABAC and state liquor licensing boards shape on-trade operating hours and promotional activities. China's SAMR monitors food safety and anti-counterfeiting measures that protect premium spirits brands from illicit production. Stakeholders must track evolving e-commerce regulations and excise tax structures as governments balance revenue generation with public health objectives across diverse national frameworks.
Market Dynamics
E-commerce penetration and direct-to-consumer platforms are restructuring distribution economics across Asia-Pacific alcoholic beverages, compressing traditional wholesale margins while opening premium access channels previously gated by on-trade gatekeepers.
Growth Catalysts
- India's FSSAI labeling mandates:Standardized disclosure requirements are accelerating formalization of the spirits sector, pushing unorganized producers toward compliance and creating shelf space for certified brands in modern retail.
- Tokyo-Sydney craft venue concentration:Premium on-trade expansion in these metropolitan clusters is elevating consumer willingness-to-pay for small-batch spirits and single-origin wines.
- China's tier-one urbanization:Concentrated affluence in Beijing, Shanghai, and Shenzhen is concentrating demand for imported spirits and aged whisky portfolios.
Market Restraints
- Malt and grain input volatility:Barley and corn price swings squeeze distiller margins, particularly for whisky producers dependent on imported feedstock.
- Australia's state liquor licensing fragmentation:Inconsistent operating-hour regulations across New South Wales, Victoria, and Queensland create compliance overhead for national on-trade operators.
- Illicit spirits substitution:Counterfeit production in unregulated facilities erodes tax-compliant volume in Southeast Asian markets.
Strategic Opportunities
- India's metropolitan corridors:Underpenetrated premium beer and wine segments in Bangalore, Mumbai, and Delhi present whitespace for imported portfolio expansion.
- SAMR anti-counterfeiting enforcement:China's strengthened food safety monitoring creates competitive shelter for authentic premium spirits brands.
- Direct-to-consumer platform convergence:Integration of subscription models with licensed delivery networks is unlocking recurring revenue streams in Japan and Australia.
Industry Challenges
- Master distiller talent scarcity:Shortage of qualified blending and aging specialists constrains craft spirits scaling in emerging production bases.
- Cross-border excise compliance complexity:Divergent tax structures across ASEAN member states fragment regional supply chain planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Alcoholic Beverage Market |
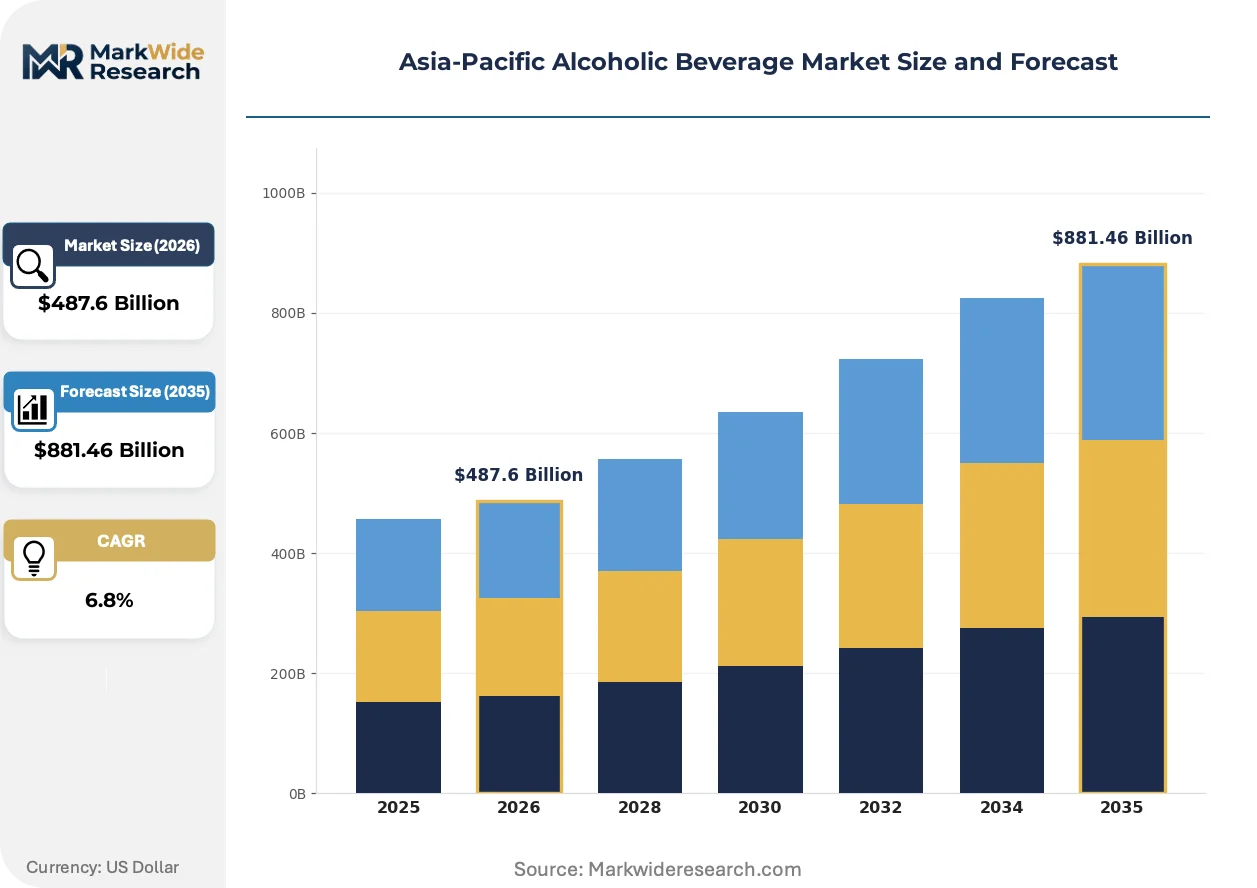
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Cider Distribution Channel: On-trade, Off-trade, E-commerce, Supermarkets Customer Type: Adults, Young Adults, Middle-aged, Seniors Packaging Type: Bottles, Cans, Kegs, Tetra Packs |
| Companies Covered | Kirin Holdings, Pernod Ricard, Anheuser-Busch InBev, Heineken Holding NV, Diageo, China Resources Beer, Suntory Holdings, Asahi Group Holdings, Tsingtao Brewery, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Alcoholic Beverage Market Strategic Shifts
Digital infrastructure is compressing the path from producer to consumer across Asia-Pacific alcoholic beverages, enabling precision targeting while destabilizing legacy wholesale hierarchies that have governed distribution for decades.
Blockchain-based provenance verification is virtualizing supply chain transparency for premium spirits. High-net-worth collectors in Singapore and Hong Kong are adopting tokenized ownership records for rare whisky casks. This technology is virtualizing the authentication layer that previously required physical inspection and paper documentation.
Australia's ABAC code revisions are tightening promotional restrictions across broadcast and digital channels. Brewers and distillers must now pre-clear social media campaigns, adding compliance latency to marketing calendars. Spirits brands targeting young adult demographics are reallocating budgets toward experiential on-trade activations less constrained by advertising prohibitions.
Subscription-based curation services are displacing conventional retail discovery for wine and craft spirits. Urban professionals in Tokyo and Melbourne are prioritizing algorithm-matched selections over supermarket aisle browsing. Japan's metropolitan markets exhibit the highest penetration of these recurring-purchase models, with off-trade channels responding through dedicated subscription fulfillment infrastructure.
Asia-Pacific Alcoholic Beverage Market Segmentation
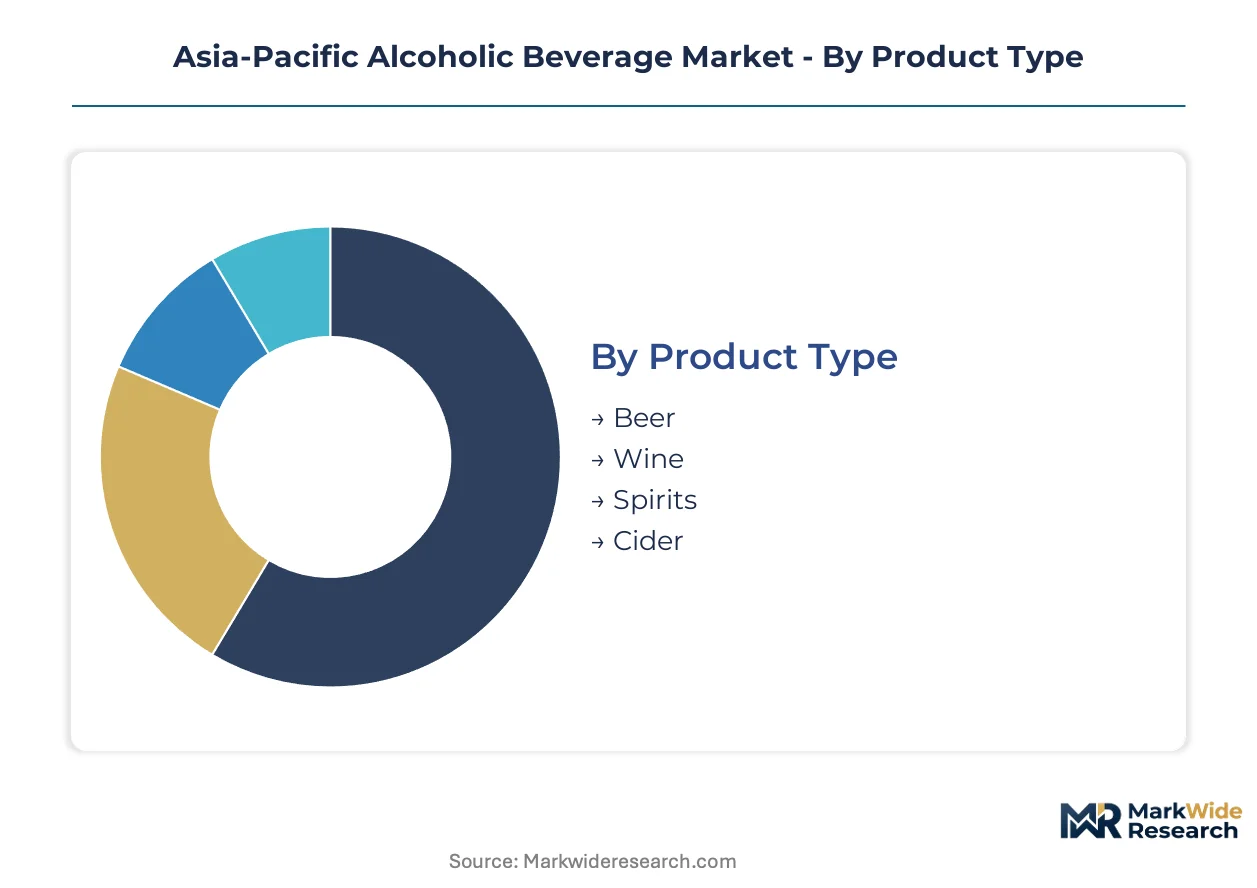
Asia-Pacific alcoholic beverage segmentation reveals distinct margin profiles across product categories, with distribution channel bifurcation separating volume-driven mass markets from premium experience-based consumption. Understanding these segment boundaries enables precise resource allocation across divergent consumer occasions and regulatory environments.
Product Type:
Mature beer markets in Australia and Japan contrast with emerging spirits sophistication in China and India, creating divergent investment horizons across the maturity spectrum.
- Beer:Fermented malt beverages typically range from four to six percent ABV, with lager variants dominating Southeast Asian consumption. Volume concentrates in Vietnam, Thailand, and Philippines through on-trade venues, though premium craft positioning is gaining traction in Sydney and Melbourne microbrewery clusters.
- Spirits:Distilled ethanol products spanning whisky, vodka, rum, and baijiu command disproportionate margin concentration relative to volume share. China's tier-one cities generate concentrated demand for imported aged whisky, while India's metropolitan corridors drive premium rum and vodka adoption among affluent young professionals.
- Wine:Fermented grape products compete for occasion-based drinking in metropolitan Australia and Japan, with red varietals dominating winter consumption patterns.
- Cider:Apple and pear-based fermented beverages occupy seasonal niche positioning with limited geographic penetration outside Australasia.
Beer handles the majority of throughput; spirits is the fastest mover on share.
Distribution Channel:
Cost tier separation distinguishes premium experience channels from efficiency-driven retail, with e-commerce emerging as a hybrid price-accessibility layer.
- On-trade:Licensed venues including bars, restaurants, and hotels generate premium pricing through experience bundling. Tokyo, Singapore, and Sydney craft venue expansion is elevating consumer willingness-to-pay for small-batch spirits and single-origin wines in these metropolitan clusters.
- Off-trade:Licensed retail stores and dedicated liquor outlets serve stock-up occasions and gift purchasing. Australia's state liquor licensing fragmentation creates compliance overhead for national operators seeking consistent operating-hour frameworks across New South Wales, Victoria, and Queensland.
- E-commerce:Direct-to-consumer platforms and licensed delivery services compress traditional wholesale margins while opening premium access channels.
- Supermarkets:Mass retail chains dominate standardized beer and value wine volume through promotional pricing and aisle visibility.
Off-trade maintains volume leadership; e-commerce is climbing the fastest on penetration metrics.
Customer Type:
Application-based consumption patterns separate social occasion drinking from solitary relaxation and ceremonial gifting behaviors.
- Adults:Broad demographic encompassing legal drinking-age population across all consumption occasions. Regulatory frameworks including India's FSSAI labeling mandates and Australia's ABAC code shape how brands target this expansive segment.
- Young Adults:Consumers aged 18-30 drive trial adoption and brand switching, with social media discovery replacing traditional advertising channels. Spirits brands targeting this demographic are reallocating budgets toward experiential on-trade activations less constrained by advertising prohibitions.
- Middle-aged:Established earners prioritize quality consistency and brand heritage over experimentation, concentrating spending in premium whisky and wine categories.
- Seniors:Health-conscious older consumers moderate volume while maintaining loyalty to traditional categories and trusted domestic labels.
Adults represents the broadest addressable base; young adults shows the steepest expansion trajectory for premium portfolio entry.
Packaging Type:
Volume-to-margin tradeoffs differentiate single-serve convenience from bulk efficiency, with sustainability pressures reshaping material selection.
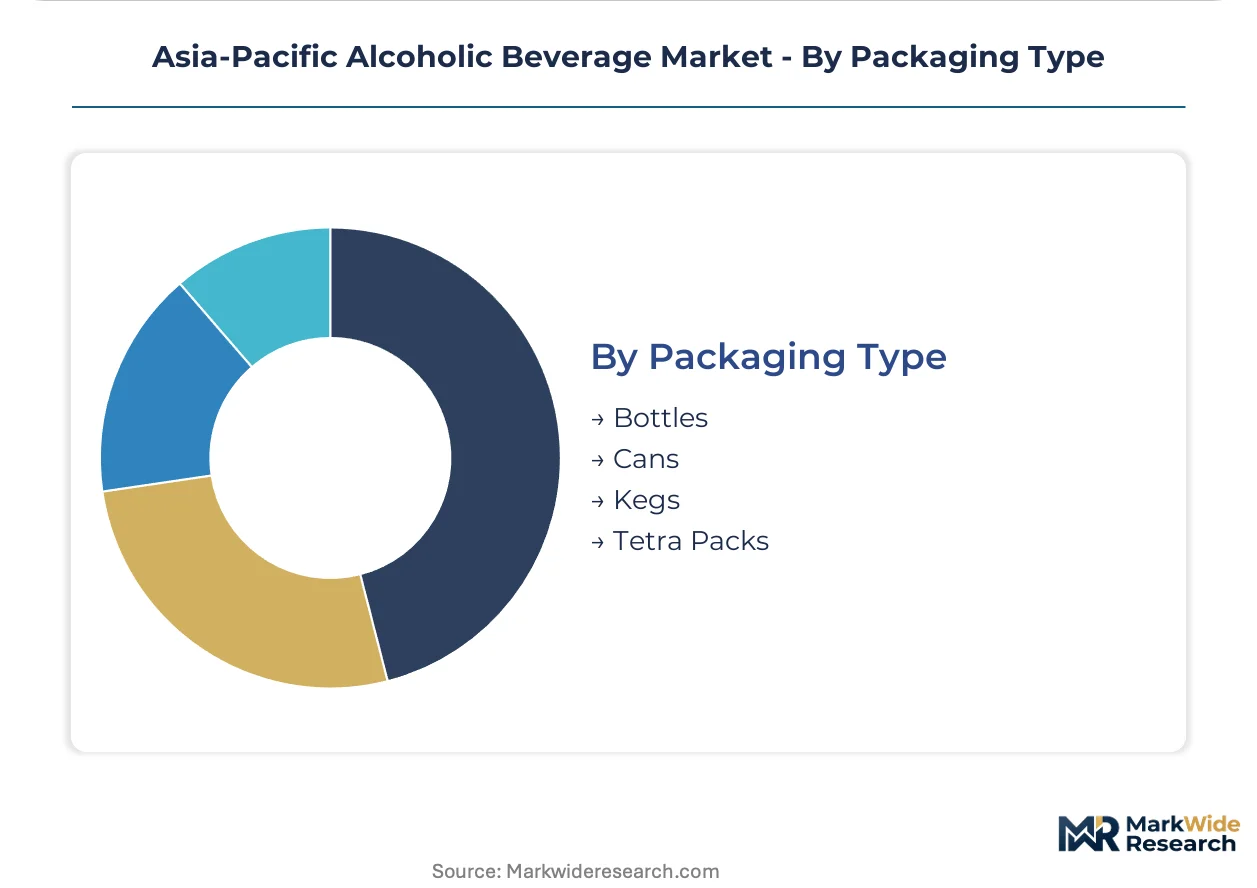
- Bottles:Glass containers dominate wine and premium spirits presentation, with weight and fragility offset by perceived quality signaling. China's SAMR anti-counterfeiting enforcement strengthens authentication layers for bottle-format premium spirits.
- Cans:Aluminum formats capture beer and ready-to-drink cocktail growth through portability and recycling efficiency. Japanese and Australian markets exhibit highest can penetration among Asia-Pacific economies.
- Kegs:Stainless steel returnable containers serve on-trade draft beer distribution with significant logistics complexity.
- Tetra Packs:Aseptic carton formats occupy niche positioning for value wine in price-sensitive Southeast Asian markets.
Bottles command the value share; cans is gaining share fastest on sustainability and convenience alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR in China anchors the regulatory framework for Asia-Pacific alcoholic beverages, with tier-one urbanization and anti-counterfeiting enforcement reshaping demand concentration across the region's largest market.
China
Beijing, Shanghai, and Shenzhen concentrate affluence for imported spirits and aged whisky portfolios. SAMR monitors food safety and anti-counterfeiting measures that protect premium brands from illicit production. Yangtze River Delta and Pearl River Delta clusters generate disproportionate margin concentration for baijiu and imported spirits distribution.
India
Bangalore, Mumbai, and Delhi metropolitan corridors drive premium rum and vodka adoption among affluent young professionals. FSSAI enforces strict labeling and advertising standards that constrain how brands target young adults. Maharashtra and Karnataka states present whitespace for imported beer and wine portfolio expansion through modern retail formalization.
Japan
Tokyo and Osaka metropolitan markets exhibit highest penetration of subscription-based curation services for wine and craft spirits. METI frameworks shape beverage alcohol distribution licensing and e-commerce compliance requirements. Kanto and Kansai clusters anchor Suntory Holdings' specialized whisky portfolios in high-end off-trade channels.
Australia
Sydney and Melbourne microbrewery clusters elevate consumer willingness-to-pay for craft beer and small-batch spirits. ABAC and state liquor licensing boards shape on-trade operating hours and promotional activities across New South Wales, Victoria, and Queensland. Pacific Northwest wine regions compete for occasion-based drinking among metropolitan young adults.
South Korea
Seoul Capital Area concentrates soju premiumization and imported spirits trial among middle-aged earners. MFDS regulates food safety and labeling standards for alcoholic beverage manufacturing and import. Busan-Ulsan industrial corridor supports packaging material supply chains for canned beer and ready-to-drink formats.
Asia-Pacific Alcoholic Beverage Market Competitive Environment
Global spirits conglomerates and Asia-Pacific brewery networks split the market across divergent margin structures. Consolidation concentrates in premium spirits and mass beer, while craft segments fragment across metropolitan micro-producers. Three archetypes dominate: multinational portfolio holders, regional brewing champions, and specialized distilling houses. Competitive moves center on direct-to-consumer platform integration and licensed delivery network partnerships.
Within the multinational tier, Pernod Ricard and Diageo exemplify premium spirits archetypes leveraging digital cellar door initiatives. Suntory Holdings occupies a specialized position in Japanese whisky portfolios commanding shelf space in high-end channels. Anheuser-Busch InBev anchors mass beer distribution through extensive brewery networks across Southeast Asia.
| Leading Market Players |
|---|
| Kirin Holdings |
| Pernod Ricard |
| Anheuser-Busch InBev |
| Heineken Holding NV |
| Diageo |
| China Resources Beer |
| Suntory Holdings |
| Asahi Group Holdings |
| Tsingtao Brewery |
| Others |
Value Chain & Pricing Dynamics
Barley and corn input volatility determines both pricing tier spreads and supply chain shape across Asia-Pacific alcoholic beverages, compressing distiller margins on imported feedstock while forcing premium producers toward long-term agricultural contracts and geographic sourcing diversification.
Pricing Analysis
Configured-to-order pricing for single-cask whisky and small-batch gin commands substantial premiums over standard portfolio releases. Three-tier pricing structure across premium, standard, and economy levels separates aged Japanese whisky from blended domestic spirits from mass-market beer. Cost compression in economy beer is intensifying because aluminum can and malt procurement expenses are rising faster than brand pricing power permits. Young adults in India's metropolitan corridors exhibit highest price sensitivity, while collectors in Singapore and Hong Kong demonstrate lowest elasticity for authenticated rare spirits.
Supply Chain Analysis
Contract manufacturing concentration among specialized bottling facilities in Thailand and Vietnam holds capacity for international brands seeking ASEAN market access. Raw material sourcing draws from Australian barley, Canadian grain, and French oak for cooperage, creating multi-continental dependency chains. Single-source vulnerability concentrates in Japanese malt whisky production where domestic distillery capacity constraints limit scaling. Distribution runs through layered wholesaler networks in Southeast Asia, though direct-to-consumer platforms are displacing traditional tiers in Japan and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific alcoholic beverages constitute a high-growth disruption as SAMR anti-counterfeiting enforcement and blockchain provenance verification simultaneously elevate authentic brand premiums and collapse illicit substitution economics.
For Market Incumbents: Build regulatory compliance moats through FSSAI certification investment and ABAC pre-clearance infrastructure that emerging competitors cannot replicate quickly. Deepen backward integration into Australian barley and French oak cooperage to secure input cost predictability against commodity swings. Anchor capacity addition in Vietnam and Thailand bottling corridors to capture ASEAN volume growth while defending margin position against tariff-exposed import alternatives. For New Entrants and Emerging Players: Build out direct-to-consumer subscription platforms in Tokyo and Melbourne where algorithm-matched curation services are displacing conventional retail discovery. Target India's metropolitan corridors for premium rum and vodka entry, exploiting whitespace from formalizing modern retail and FSSAI-compliant shelf space expansion. Deploy experiential on-trade activation as the primary go-to-market angle to circumvent Australia's ABAC advertising restrictions on digital channels. For Investors and Strategic Acquirers: The market sits at a premiumization phase that favors specialized distilling houses with authenticated provenance and scarce aging inventory. Long-term viability across the analysis window hinges on ownership of maturing stock and licensed distillery assets rather than brand marketing alone. Acquisition target archetype encompasses craft producers with 8-15 year aged inventory and established export licensing into China. Monitor SAMR enforcement intensity and FSSAI labeling mandate expansion as inflection indicators for competitive shelter duration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Pernod Ricard's digital cellar door initiatives capture premium buyers in Australia and Japan through subscription curation. |
| Anti-Counterfeiting Technology Deployment | Blockchain provenance verification protects Suntory Holdings' rare whisky portfolios from illicit substitution in Hong Kong collector markets. |
| Regulatory Compliance Infrastructure | FSSAI certification investment creates shelf access barriers for unorganized spirits producers in India's modern retail channels. |
| Metropolitan On-Trade Expansion | Craft venue concentration in Tokyo and Sydney elevates consumer willingness-to-pay for small-batch spirits and single-origin wines. |
| Agricultural Contract Securement | Long-term barley and grain procurement agreements insulate Anheuser-Busch InBev's Southeast Asian brewery networks from input volatility. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of trade customs data, excise tax filings, and regulatory gazettes across Asia-Pacific jurisdictions. Primary interviews engaged master distillers, regional brand managers, modern retail category buyers, and state liquor licensing officials in China, India, Japan, and Australia. Secondary validation drew from SAMR food safety bulletins, FSSAI compliance directories, ABAC adjudication records, and METI distribution licensing frameworks. Bottom-up volume modeling triangulated against top-down macroeconomic consumption proxies.
Forecast inputs span product type segmentation by ABV tier and occasion, distribution channel evolution across on-trade formalization and e-commerce penetration, and customer type migration from mass-market beer toward premium spirits and wine. Modeled dimensions include geographic regulatory cluster, packaging material sustainability profile, and urbanization density tier. CAGRs were derived from elasticity-adjusted per-capita consumption trajectories and demographic cohort analysis. Industry-specific inputs encompass excise tax regime stability and anti-counterfeiting enforcement intensity across the projection horizon.
Stress conditions across barley price bands, tariff rate fluctuations, and licensing regime shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding urban affluence concentration and regulatory compliance cost trajectories. Illicit spirits substitution rates and cross-border e-commerce policy reversals represent specific risk factors that could revise projections. Quarterly review of SAMR enforcement actions and FSSAI mandate expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
RTD Cocktails Market
Alcoholic Beverages
Specialty Beer Market
Alcoholic Beverages
Spirits Miniatures Market
Alcoholic Beverages
Home Brew Boiler Market
Alcoholic Beverages
Beer Kegs Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Nitro Cocktails Market
Alcoholic Beverages
Global Beer Market
Alcoholic Beverages
Global Premium Alcoholic Beverage Market
Alcoholic Beverages
Chocolate Liqueur Market
Alcoholic Beverages
Chocolate Beer Market
Alcoholic Beverages
Cognac Market
Alcoholic Beverages
Organic Wine Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Gluten-Free Beer Market