
 Asia-Pacific Alcohol E-Commerce Market | 2026-2036
Asia-Pacific Alcohol E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Alcohol E-Commerce Market Insights
Premium craft and small-batch spirit tiers is rotating toward the center of Asia-Pacific Alcohol E-Commerce strategy as consumers trade up from mass-label substitutes. Suntory Holdings Limited leverages its Japanese whisky heritage to command digital shelf space across Southeast Asian e-tailers. Kweichow Moutai Co., Ltd. anchors its scarcity-driven pricing through controlled direct-to-consumer releases on proprietary platforms. Alibaba Group dominates last-mile logistics and payment infrastructure, enabling alcohol fulfillment where third-party delivery networks remain restricted.
Asia-Pacific Alcohol E-Commerce encompasses the digital sale, fulfillment, and regulatory-compliant delivery of fermented and distilled beverages through online channels, requiring temperature-controlled logistics, age-verification protocols, and excise tax integration at checkout. Spirits and ready-to-drink categories capture disproportionate margin pools as producers bypass traditional wholesale markups through direct-to-consumer channels. E-tailers and social commerce platforms lead volume throughput, while aggregators compete on discovery algorithms and bundled pricing across beer and wine selections.
China's SAMR enforces food safety and advertising restrictions on alcohol promotions across live-stream platforms, while Australia's state regulators mandate digital age-gating and delivery signature requirements. Japan's National Tax Agency modernizes liquor licensing to accommodate subscription and same-day delivery models. Stakeholders must monitor evolving excise harmonization between ASEAN markets and platform liability frameworks governing cross-border alcohol shipments.
Market Dynamics
Live-stream commerce is compressing purchase cycles across Asia-Pacific alcohol e-commerce, merging discovery with instant checkout through influencer-hosted sessions that bypass traditional retail intermediaries entirely.
Growth Catalysts
- Mobile-first wallet penetration:Super-app payment ecosystems in China and Southeast Asia embed alcohol purchases within social feeds, collapsing friction between content consumption and transaction completion.
- SAMR live-stream advertising protocols:China's tightened food safety enforcement on alcohol promotions paradoxically legitimizes compliant platforms, concentrating advertiser spend toward verified channels with built-in age-gating infrastructure.
- Same-day cold-chain fulfillment:Temperature-controlled last-mile networks in Shanghai, Tokyo, and Sydney enable perishable craft beer and natural wine segments previously excluded from digital channels.
Market Restraints
- State-level digital ID fragmentation:Australia's patchwork of age-verification requirements across New South Wales, Victoria, and Queensland forces redundant compliance infrastructure for cross-border sellers.
- Excise harmonization gaps:ASEAN's unaligned liquor taxation creates arbitrage complexity that deters regional platform expansion beyond domestic markets.
- Glass bottle weight economics:Spirits' packaging density inflates last-mile costs relative to lightweight substitutes, compressing margins on sub-premium price tiers.
Strategic Opportunities
- Subscription licensing modernization:Japan's National Tax Agency revised liquor codes explicitly accommodate recurring delivery models, opening recurring revenue architectures previously restricted to beer.
- Tier-two city live-stream penetration:Chengdu and Hangzhou exhibit lower platform saturation than Beijing or Shanghai, offering first-mover advantages in influencer partnership costs.
- Blockchain provenance verification:Distributed ledger integration with Kweichow Moutai's controlled release systems addresses counterfeiting anxiety that suppresses high-value digital transactions.
Industry Challenges
- Cross-border excise reconciliation:Platform operators must integrate real-time tax calculation engines that vary by destination prefecture or state, requiring sustained engineering investment.
- Cold-chain talent scarcity:Specialist logistics managers capable of coordinating temperature-sensitive alcohol fulfillment remain concentrated in legacy beverage distributors rather than pure-play e-tailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Alcohol E-Commerce Market |
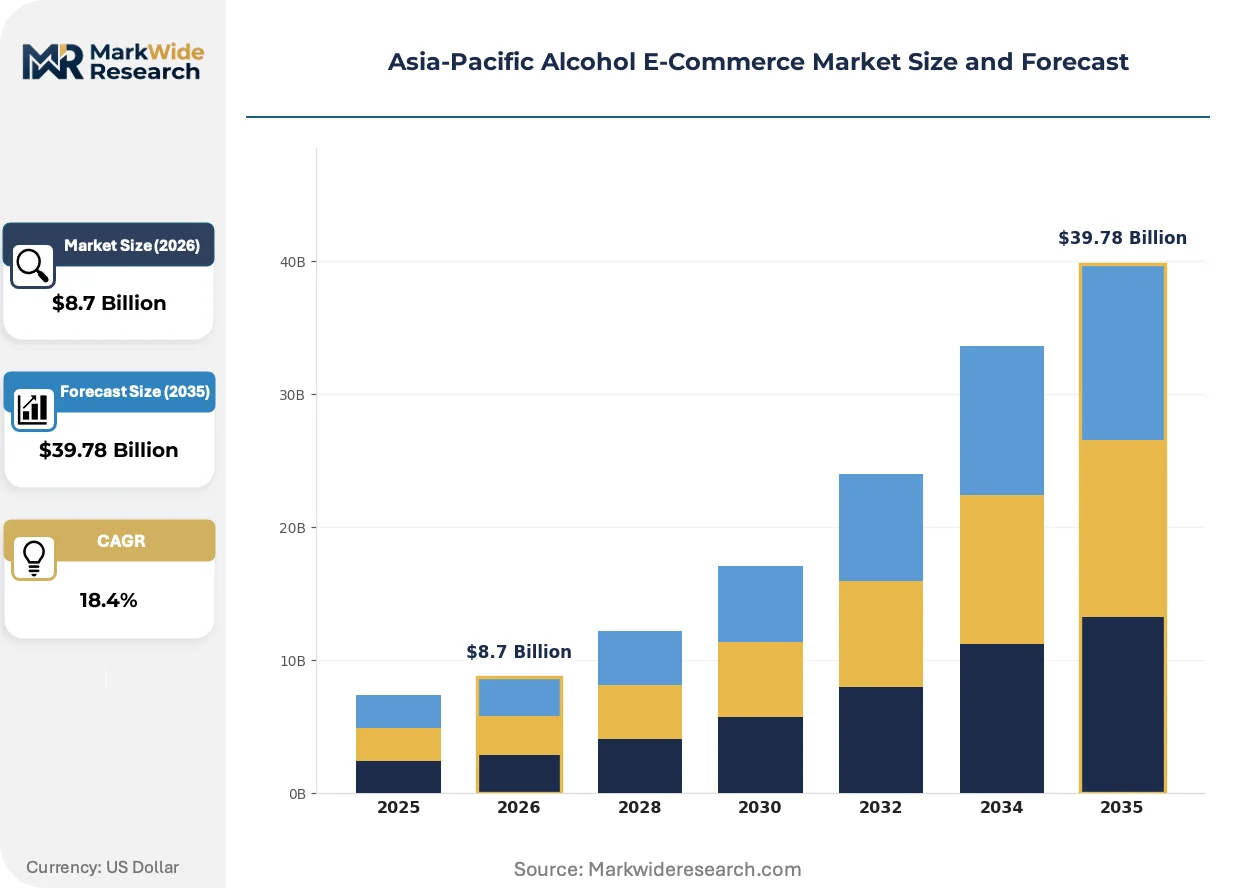
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Ready-to-Drink Customer Type: Individual Consumers, Restaurants, Retailers, Wholesalers Distribution Channel: Direct-to-Consumer, E-Tailers, Aggregators, Social Commerce Price Tier: Premium, Mid-Range, Economy, Discounts |
| Companies Covered | Suntory Holdings Limited, Wuliangye Yibin Co., Ltd., Diageo PLC, Kirin Holdings Company Limited, Thai Beverage PLC, Pernod Ricard SA, Kweichow Moutai Co., Ltd., Alibaba Group, Asahi Group Holdings Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Alcohol E-Commerce Market Trends and Innovations
Algorithmic discovery engines are displacing brand loyalty as the primary purchase determinant, with recommendation systems trained on consumption occasion rather than product category reshaping how consumers encounter unfamiliar labels.
AI-powered visual search is fragmenting traditional category navigation. Image recognition systems allow shoppers to photograph bottles in physical venues and locate identical or similar inventory across competing e-tailers instantly. Young urban professionals in Seoul and Singapore adopt this behavior at accelerating frequency, collapsing the distinction between offline discovery and online fulfillment. The technology is fragmenting platform moats built on exclusive supplier relationships, as visual matching erodes catalog differentiation.
Japan's liquor tax enforcement modernization is compressing licensing timelines for digital-native entrants. The National Tax Agency's streamlined application portal reduces approval periods from months to weeks for subscription and same-day delivery operators. Small-batch distilleries in Hokkaido and Okinawa leverage this regulatory tailwind to bypass wholesale distribution entirely, establishing direct relationships with metropolitan consumers previously inaccessible without distributor representation.
Occasion-based bundling is displacing single-bottle purchases as the dominant transaction format. Platforms now assemble curated selections around specific consumption contexts — hot pot dinners, rooftop gatherings, business gifting — rather than grape varietal or spirit type. This behavioral shift concentrates margin capture in Shanghai and Mumbai, where time-constrained professionals prioritize convenience over individual label research. The model rewards inventory breadth over depth, favoring aggregators with multi-category fulfillment capabilities.
Asia-Pacific Alcohol E-Commerce Market Segmentation
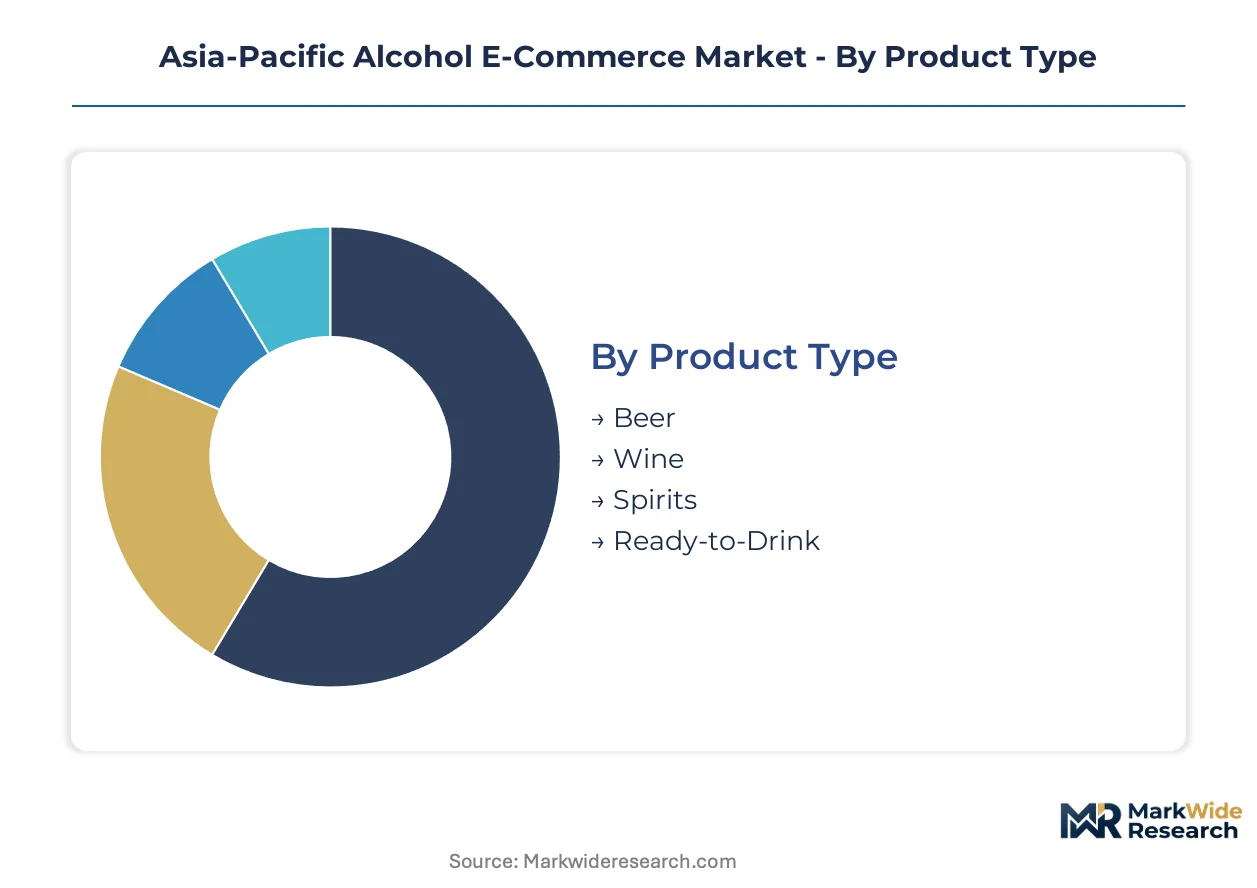
Asia-Pacific Alcohol E-Commerce Market segmentation reveals how regulatory frameworks, logistics constraints, and payment infrastructure reshape competitive positioning across product categories and channel architectures. Distinct compliance requirements for spirits versus beer, combined with varying age-verification protocols by customer type, create asymmetric growth corridors that favor certain segment combinations over others.
Product Type:
SAMR's tightened live-stream advertising protocols and Japan's National Tax Agency licensing modernization create divergent compliance burdens across alcoholic beverage categories, directly influencing platform assortment strategies and margin structures.
- Spirits:High-proof distilled beverages including whisky, vodka, and baijiu face stringent cross-border excise reconciliation requirements. Demand concentrates in China's tier-one cities where Kweichow Moutai's controlled direct-to-consumer releases anchor scarcity-driven digital pricing, though glass bottle weight economics compress margins on sub-premium tiers.
- Beer:Fermented malt beverages benefit from established cold-chain infrastructure and subscription licensing modernization in Japan. Same-day fulfillment networks in Shanghai and Tokyo enable perishable craft segments previously excluded from digital channels, with temperature-controlled logistics now standard for metropolitan delivery.
- Wine:Grape-based fermented products spanning still, sparkling, and fortified styles encounter fragmented state-level digital ID requirements in Australia that complicate cross-border seller expansion.
- Ready-to-Drink:Pre-mixed cocktails and alcoholic seltzers leverage lightweight packaging economics and occasion-based bundling formats popular among time-constrained professionals in Mumbai and Seoul.
Established volume favors Beer; emerging adoption favors Ready-to-Drink.
Customer Type:
Procurement patterns diverge sharply between individual and commercial buyers, with B2B segments requiring integration with food safety licensing and wholesale tax documentation that pure-play e-tailers struggle to automate.
- Individual Consumers:End-users purchasing for personal consumption dominate mobile-first wallet penetration metrics across Southeast Asian super-apps. Live-stream commerce compresses purchase cycles through influencer-hosted sessions, with algorithmic discovery engines displacing brand loyalty as the primary purchase determinant in Seoul and Singapore.
- Restaurants:On-premise establishments sourcing inventory through digital channels require invoice-compliant documentation for liquor licensing renewal. Japan's streamlined National Tax Agency portal reduces approval friction for subscription models, enabling recurring delivery architectures previously restricted to beer.
- Retailers:Brick-and-mortar shops replenishing stock through e-commerce platforms face excise harmonization gaps across ASEAN markets that deter regional platform expansion.
- Wholesalers:Traditional distributors adopting digital procurement tools concentrate in legacy beverage supply chains rather than pure-play e-tailer ecosystems, creating talent scarcity in cold-chain coordination.
Transaction velocity concentrates with Individual Consumers; margin expansion favors Restaurants.
Distribution Channel:
Channel economics reflect varying degrees of captive supply control, with direct models capturing wholesale markup bypass while aggregator platforms compete on discovery algorithms and bundled pricing breadth.
- Direct-to-Consumer:Producer-controlled platforms enabling proprietary fulfillment and customer data capture. Suntory Holdings leverages this architecture across Southeast Asian markets to command digital shelf space through Japanese whisky heritage positioning.
- E-Tailers:Dedicated online retailers with multi-category fulfillment capabilities dominate last-mile logistics where third-party networks face restrictions. Alibaba Group's payment infrastructure enables alcohol completion in compliance-heavy jurisdictions.
- Aggregators:Platform businesses assembling inventory from multiple suppliers compete on visual search integration and occasion-based curation, with AI-powered image recognition fragmenting traditional catalog moats.
- Social Commerce:Embedded purchasing within social feeds and live-stream sessions collapses friction between content consumption and transaction completion, particularly in metro China and India.
Logistics scale advantages E-Tailers; engagement intensity favors Social Commerce.
Price Tier:
Pricing stratification across premium, mid-range, and economy levels reflects authentication anxiety and provenance verification demands that suppress high-value digital transactions without blockchain integration.
- Premium:Ultra-price tiers including aged spirits and limited releases. Blockchain distributed ledger integration with controlled release systems addresses counterfeiting concerns that otherwise constrain transaction values.
- Mid-Range:Standard-label positioning for established brands with regional recognition. This tier captures volume in tier-two Chinese cities like Chengdu and Hangzhou where platform saturation remains lower than Beijing or Shanghai.
- Economy:Mass-market labels competing on price accessibility with compressed margins from glass bottle weight economics and last-mile cost inflation.
- Discounts:Promotional pricing and clearance inventory requiring careful excise tax integration at checkout to maintain regulatory compliance across fragmented state-level frameworks.
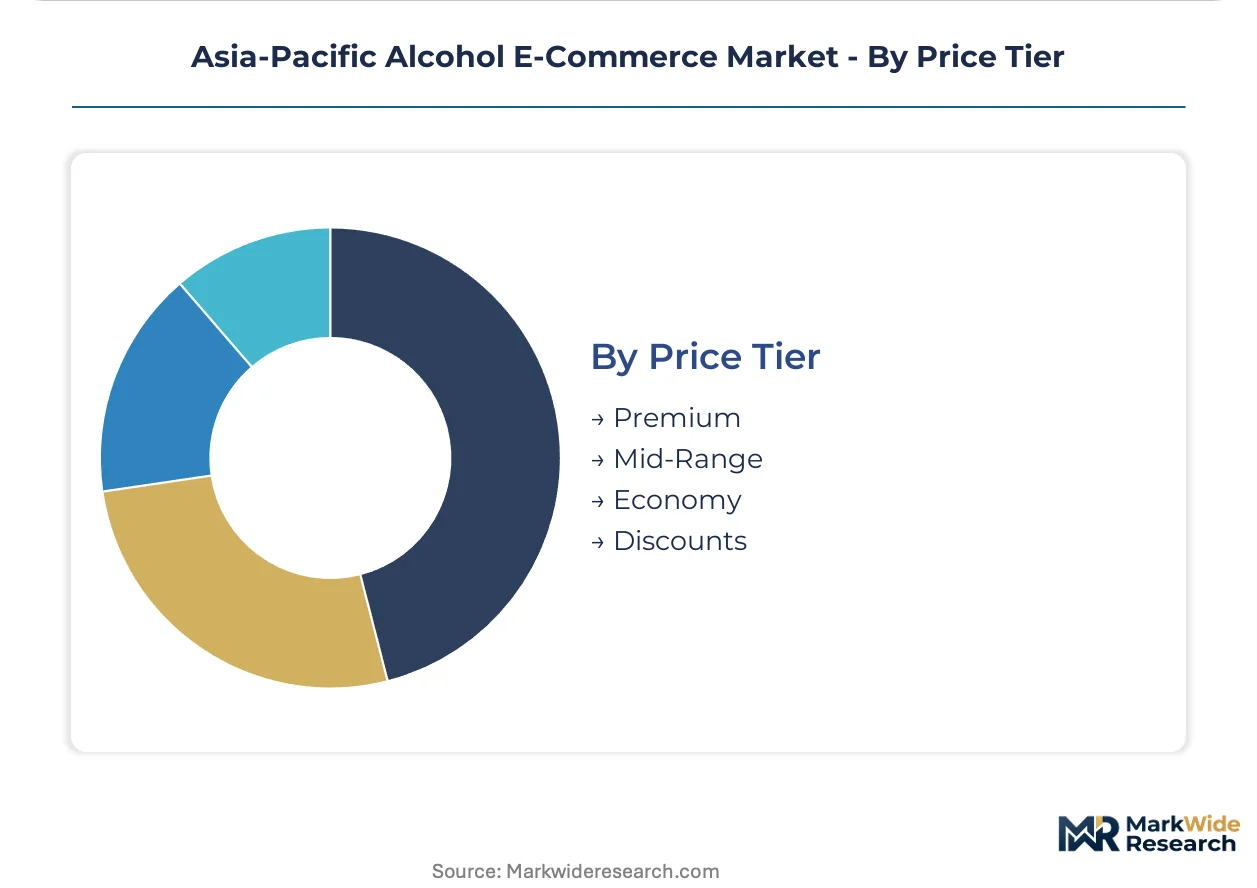
Margin capture concentrates in Premium; volume throughput favors Mid-Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border spirits flows from Japan to Southeast Asian e-tailers intensify as Tokyo-based distilleries exploit streamlined National Tax Agency licensing. Australian craft producers simultaneously target Chinese tier-one cities through controlled-release direct-to-consumer platforms.
China
Live-stream commerce in Shanghai and Beijing compresses purchase cycles through influencer-hosted sessions that merge discovery with instant checkout. SAMR's tightened food safety enforcement on alcohol promotions legitimizes compliant platforms, concentrating advertiser spend toward verified channels with built-in age-gating infrastructure. Chengdu and Hangzhou exhibit lower platform saturation, offering first-mover advantages in influencer partnership costs for spirits and baijiu releases.
Japan
Subscription licensing modernization from the National Tax Agency explicitly accommodates recurring delivery models, opening revenue architectures previously restricted to beer. Small-batch distilleries in Hokkaido and Okinawa bypass wholesale distribution entirely, establishing direct relationships with metropolitan consumers previously inaccessible without distributor representation. Same-day cold-chain fulfillment networks in Tokyo enable perishable craft segments previously excluded from digital channels.
Australia
State-level digital ID fragmentation across New South Wales, Victoria, and Queensland forces redundant compliance infrastructure for cross-border sellers targeting Sydney and Melbourne. TGA-aligned food safety protocols intersect with liquor licensing renewal requirements for restaurants sourcing inventory through digital channels. Natural wine producers leverage temperature-controlled last-mile networks to reach time-constrained professionals prioritizing convenience over individual label research.
India
Young urban professionals in Mumbai and Delhi drive online spirits purchases through mobile-first super-app payment ecosystems that embed alcohol transactions within social feeds. State-level excise variations complicate interstate platform expansion, concentrating demand in Maharashtra and Karnataka where regulatory harmonization has advanced. Occasion-based bundling around hot pot dinners and business gifting formats captures margin from time-constrained metropolitan consumers.
South Korea
AI-powered visual search adoption in Seoul fragments traditional category navigation, allowing shoppers to photograph bottles in physical venues and locate inventory across competing e-tailers instantly. MFDS-aligned food safety enforcement shapes platform compliance investments for soju and whisky imports. The technology collapses the distinction between offline discovery and online fulfillment, eroding catalog moats built on exclusive supplier relationships.
Asia-Pacific Alcohol E-Commerce Market Competitive Landscape
Listed leaders compete with private specialists across logistics scale and heritage brand positioning. The market structure concentrates around three tiers: integrated beverage conglomerates with captive distribution, pure-play e-tailers commanding last-mile infrastructure, and platform aggregators competing on discovery algorithms. Strategic moves center on cold-chain capacity expansion in metropolitan clusters and direct-to-consumer licensing acquisitions that bypass traditional wholesale markups.
Within the heritage spirits archetype, Suntory Holdings Limited and Kweichow Moutai Co., Ltd. occupy positions defined by scarcity-driven pricing and controlled release systems. Among platform operators, Alibaba Group anchors logistics and payment infrastructure enabling alcohol fulfillment in compliance-heavy jurisdictions. These three entities exemplify divergent competitive vectors: Japanese whisky heritage positioning, Chinese baijiu scarcity architecture, and integrated e-commerce infrastructure scale.
| Leading Market Players |
|---|
| Suntory Holdings Limited |
| Wuliangye Yibin Co., Ltd. |
| Diageo PLC |
| Kirin Holdings Company Limited |
| Thai Beverage PLC |
| Pernod Ricard SA |
| Kweichow Moutai Co., Ltd. |
| Alibaba Group |
| Asahi Group Holdings Ltd |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between tier-one e-tailers and Japanese whisky producers lock in both supply access and price visibility, insulating premium inventory from spot-market volatility while compressing margin flexibility for mid-range entrants.
Pricing Analysis
Legacy cold-chain infrastructure commands premium pricing over emerging temperature-controlled networks, with established Shanghai and Tokyo fulfillment operators extracting rent from craft producers lacking captive logistics. Three-tier pricing structure across premium, standard, and economy levels stratifies around authentication technology adoption, as blockchain-enabled provenance verification justifies ultra-price positioning for limited baijiu releases. Cost compression in sub-premium spirits intensifies because glass bottle weight economics inflate last-mile delivery expenses disproportionately. Individual consumers in tier-two Chinese cities exhibit highest price sensitivity, while corporate gifting segments in Mumbai and Seoul absorb premium markups with minimal elasticity.
Supply Chain Analysis
Strategic stockpiling of aged inventory dominates spirits producer behavior, whereas just-in-time replenishment governs perishable craft beer and natural wine segments dependent on same-day cold-chain fulfillment. Manufacturing concentration clusters in Japan for whisky, China for baijiu and packaging materials, and Australia for natural wine production. Raw material dependencies encompass malted barley from Australia and Canada, glass bottle supply from Chinese foundries, and oak barrel imports from American and French cooperages. Single-source vulnerability runs through proprietary temperature-controlled last-mile networks in metropolitan China, where third-party logistics restrictions limit fulfillment alternatives. Distribution runs through platform-controlled e-tailer ecosystems rather than open wholesale markets, concentrating gatekeeper power with Alibaba Group and regional super-app operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment moat, where SAMR compliance infrastructure and Japan's National Tax Agency licensing requirements create switching costs that platform incumbents exploit against unverified competitors.
For Market Incumbents: Fortify cold-chain capacity in Chengdu and Hangzhou before competitor saturation erodes first-mover logistics advantages. Deepen backward integration into temperature-controlled warehousing to defend against emerging aggregator platforms poaching craft distillery relationships through superior discovery algorithms. Prioritize blockchain provenance certification investment to maintain premium pricing power as visual search technology fragments traditional catalog differentiation.
For New Entrants and Emerging Players: Anchor in tier-two Chinese live-stream commerce penetration, where influencer partnership costs remain below Beijing and Shanghai levels while audience engagement metrics climb. Target subscription licensing modernization in Japan's National Tax Agency framework, where recurring delivery architectures for spirits remain underdeveloped relative to beer. Deploy AI-powered visual search integration as primary go-to-market angle to circumvent established platform catalog moats.
For Investors and Strategic Acquirers: Regional cold-chain specialists with compliant age-verification infrastructure represent the most defensible acquisition archetype, as regulatory fragmentation across Australian states and ASEAN markets concentrates scarce operational capabilities. Long-term viability hinges on platform consolidation enabling cross-border excise harmonization at scale. Monitor SAMR enforcement intensity against non-compliant live-stream channels as inflection indicator for legitimate platform valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Capacity Expansion | Temperature-controlled warehousing in Chengdu and Hangzhou captures tier-two demand before competitor saturation. |
| Blockchain Provenance Integration | Distributed ledger authentication addresses counterfeiting anxiety suppressing high-value digital transactions in China. |
| Subscription Licensing Acquisition | Japan's National Tax Agency modernization enables recurring revenue architectures previously restricted to beer categories. |
| Visual Search Platform Development | AI-powered image recognition fragments catalog moats by collapsing offline discovery into online fulfillment. |
| Direct-to-Consumer Channel Launch | Producer-controlled platforms bypass wholesale markups and capture customer data in Southeast Asian markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with platform operations directors, cold-chain logistics managers, regulatory compliance officers at e-tailers, and live-stream commerce influencers; alongside secondary validation through SAMR enforcement bulletins, Japan National Tax Agency licensing records, Australian state-level digital ID regulatory filings, and ASEAN customs trade databases. Bottom-up triangulation across individual market sizing and top-down cross-checks against regional e-commerce penetration metrics ensured consistency.
Across the analysis window, the forecasting framework modeled volume and value trajectories across product type, customer segment, distribution channel architecture, and price tier stratification. CAGRs were derived from regression analysis against mobile wallet penetration curves and live-stream commerce adoption rates. Forecast inputs incorporated cold-chain infrastructure buildout timelines and regulatory harmonization probability assessments between ASEAN markets.
Decision-makers should treat outputs as directional under assumptions of continued SAMR enforcement consistency and stable Japan licensing modernization; material deviation would warrant model refresh. Forecasts embed assumptions regarding temperature-controlled logistics capacity expansion and influencer marketing cost trajectories in tier-two Chinese cities. Revision becomes warranted when cross-border excise reconciliation complexity crosses thresholds that deter regional platform expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Alcohol Enzymes Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Tanzania Spirits Market
Alcoholic Beverages
Vodka Market
Alcoholic Beverages
Japan Beer Market
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
Port Wine Market
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Draught Beer Market
Alcoholic Beverages
Saffron Beer Market
Alcoholic Beverages
Cannabis Beverages Market
Alcoholic Beverages
N-Hexyl Alcohol Market
Alcoholic Beverages
Grain Alcohol Market
Alcoholic Beverages
Alcoholic Flavors Market