
 RTD Cocktail Shots Market | 2026-2036
RTD Cocktail Shots Market Size, Share, and Industry Trends Forecast 2026-2036
RTD Cocktail Shots Market Analytics
The capital-intensity divergence between large-scale distillers and craft entrants is redrawing competitive boundaries in RTD cocktail shots. Diageo plc leverages its captive spirits supply and global distribution infrastructure to sustain margin advantages across multiple price tiers. Brown-Forman anchors its position through concentrated whiskey-based shot portfolios that dominate American convenience channels. Bacardi Limited competes via rum-forward formulations and tropical flavor specialization that extends its Caribbean heritage positioning.
RTD cocktail shots are pre-mixed, single-serve alcoholic beverages typically containing distilled spirits combined with flavoring agents, sweeteners, and diluents, packaged in volumes ranging from 50 mL to 200 mL with alcohol by content between 10% and 25%. These products serve commercial and social consumption occasions requiring portability, consistent quality, and minimal preparation. The flavored segment leads volume due to broader demographic appeal and repeat purchase frequency, while the premium tier captures disproportionate margin pools through super-premium spirit bases and limited-batch positioning. Pouch packaging is gaining fastest among younger customer segments for its lightweight logistics and festival-friendly format, though glass bottles retain structural importance in bars and gift-oriented channels.
The FDA governs ingredient disclosure and allergen labeling for RTD alcoholic beverages, while the Alcohol and Tobacco Tax and Trade Bureau enforces formula approvals, tax classifications, and interstate commerce restrictions that shape product development timelines. State-level three-tier distribution laws fragment market access and compel brand owners to navigate wholesaler relationships differently across jurisdictions. Stakeholders must monitor evolving low-alcohol taxation frameworks and on-premise licensing reforms that could reallocate volume between retail and hospitality channels.
Market Dynamics
The FDA's updated labeling requirements for alcoholic beverages are compressing formulation timelines while simultaneously opening premium positioning opportunities for brands that achieve early compliance certification.
Growth Catalysts
- On-Premise Licensing Reforms:Municipalities in California, Texas, and New York are streamlining outdoor consumption permits, expanding festival and street-vending channels for portable formats.
- Pouch Packaging Technology:Lightweight polymer barriers with oxygen-scavenging layers extend shelf stability without refrigeration, enabling direct-to-consumer shipping economics.
- Flavor Chemistry Advances:Natural extraction methods from botanical suppliers in Florida and Oregon reduce artificial additive dependence, aligning with clean-label preferences among urban millennials.
Market Restraints
- Glass Supply Concentration:Domestic bottle manufacturing clusters in Ohio and Pennsylvania face capacity constraints from energy cost volatility, squeezing margins for heritage-format brands.
- Three-Tier Distribution Laws:State-level wholesaler mandates in jurisdictions like Utah and Oklahoma fragment market access and inflate logistics costs for out-of-state entrants.
- Spirits Input Cost Volatility:Bourbon and tequila agave pricing swings from climate-pressured harvests in Kentucky and Jalisco destabilize cost structures for whiskey-forward and agave-based portfolios.
Strategic Opportunities
- Underpenetrated Convenience Channels:Independent gas station networks across the Mountain West lack dedicated RTD cold-box infrastructure, creating first-mover shelf space for pouch-format entrants.
- Low-Alcohol Taxation Frameworks:Proposed ABV-tiered excise structures in state legislatures would reclassify sub-15% products into beer-tax brackets, improving retail price competitiveness.
- Direct-to-Consumer Platforms:E-commerce fulfillment partnerships with temperature-controlled logistics providers bypass three-tier constraints for subscription and gift-box segments.
Industry Challenges
- Formula Approval Timelines:The Alcohol and Tobacco Tax and Trade Bureau's multi-month review queues delay seasonal and limited-batch launches, compressing revenue windows.
- Flavor Stability Expertise Gap:Shortage of beverage chemists with distilled spirits matrix experience forces reliance on external formulation labs, diluting proprietary knowledge capture.
- Cold-Chain Integration Complexity:Legacy distributors lack refrigerated last-mile capacity for premium chilled formats, requiring parallel logistics investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RTD Cocktail Shots Market |
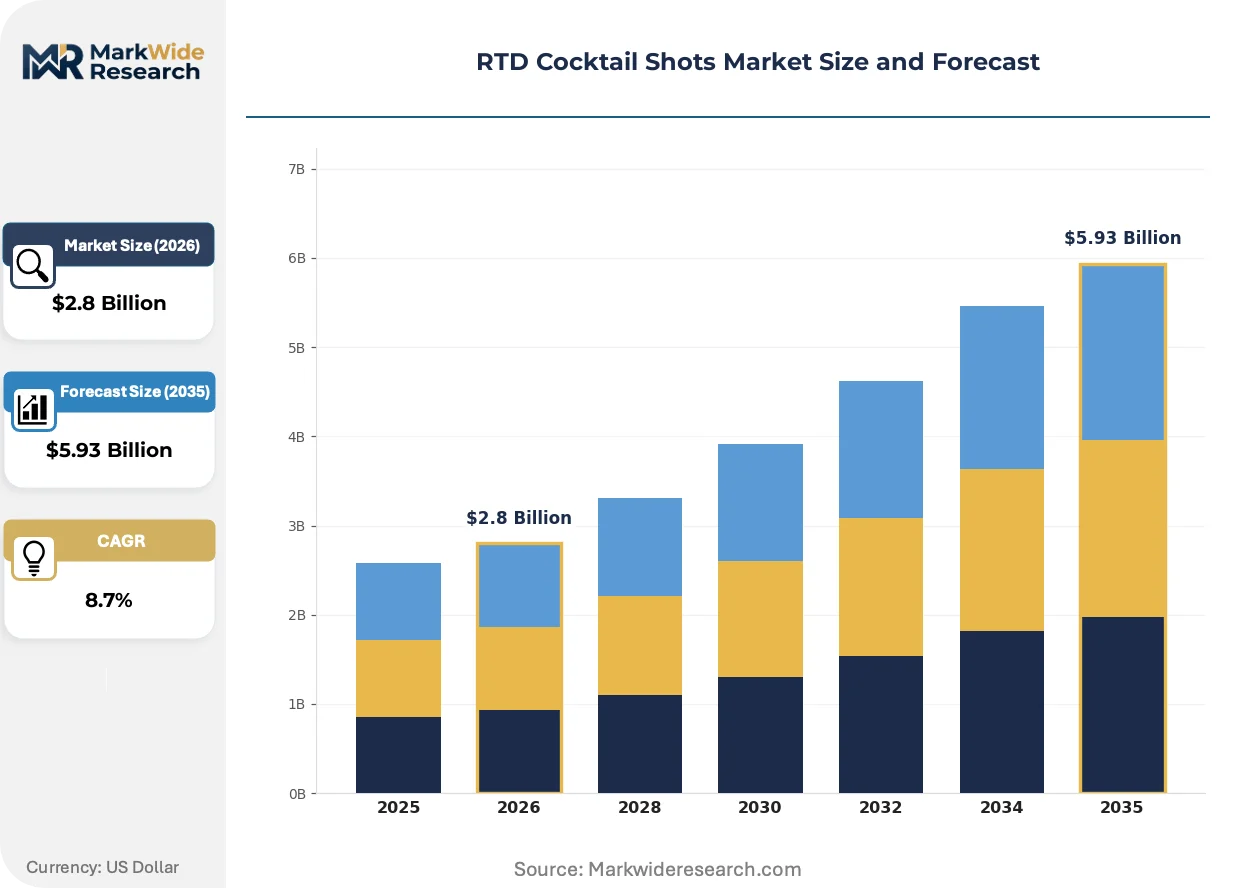
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored, Classic, Premium, Low-Calorie Packaging Type: Glass Bottles, Cans, Pouches, Tetra Packs Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Bars Customer Type: Millennials, Gen Z, Professionals, Party-goers |
| Companies Covered | Diageo plc, Bacardi Limited, Brown-Forman, Anheuser-Busch InBev, Pernod Ricard, Constellation Brands, Suntory Holdings Limited, Asahi Group Holdings, Beam Suntory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RTD Cocktail Shots Market Evolving Landscape
Active packaging technologies and regulatory transparency mandates are reconfiguring how RTD cocktail shots achieve shelf differentiation and consumer trust.
Pouch packaging with multi-layer barrier films is bifurcating the convenience channel. Festival organizers and outdoor venue operators in Austin and Miami are adopting these formats for reduced waste-handling costs. The technology is bifurcating volume between lightweight logistics winners and glass-dependent premium positioning.
The FDA's updated allergen disclosure requirements are forcing reformulation of flavor bases containing milk derivatives and tree nut extracts. Manufacturers must resubmit formulas for TTB approval, extending development cycles by four to six months. Smaller craft distillers in Portland and Nashville are responding by simplifying ingredient lists to accelerate compliance.
Young urban professionals are compressing purchase cycles through mobile-first discovery platforms. Instagram and TikTok-native brands bypass traditional retail gatekeepers via influencer-curated tasting kits. This pattern concentrates in metropolitan clusters across Los Angeles, Brooklyn, and Chicago where on-premise experimentation drives retail trial.
RTD Cocktail Shots Market Segmentation
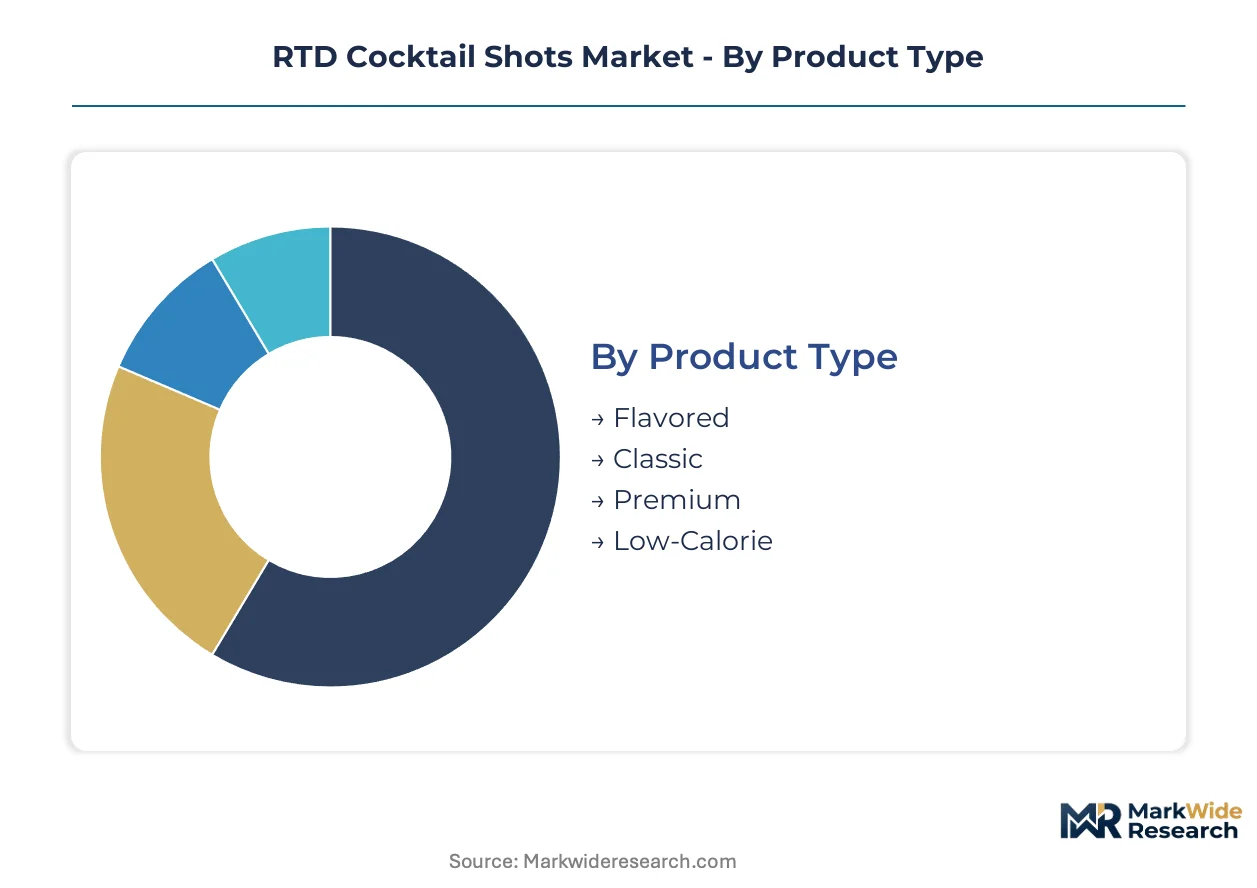
Segmentation in RTD cocktail shots determines formulation complexity, cold-chain requirements, and channel economics. Each dimension carries distinct regulatory burdens and margin profiles that reshape competitive positioning across price tiers and consumption occasions.
Product Type:
FDA labeling thresholds for allergen disclosure and calorie claims fragment development timelines across this dimension, with natural flavor classifications requiring separate TTB formula approvals.
- Flavored:These SKUs incorporate fruit extracts, botanical infusions, and artificial flavoring systems to mask spirits harshness. Demand concentrates in metropolitan clusters across California and Texas where festival culture and outdoor venue consumption drive repeat purchase frequency. The TTB's extended review queues for non-standard formulas compress seasonal launch windows.
- Premium:Super-premium spirit bases and limited-batch positioning command disproportionate margin pools. Urban professionals in New York and Chicago sustain this tier through gift-box and on-premise trial channels where provenance storytelling justifies price elevation.
- Classic:Traditional cocktail formulations—martini, margarita, old fashioned—appeal to heritage-seeking demographics with minimal flavor adulteration.
- Low-Calorie:Sub-100 calorie positioning targets health-conscious millennials through sugar-alternative formulations that require stability testing under FDA guidance.
Flavored handles the majority of throughput; Premium is the fastest mover on share.
Packaging Type:
Logistics cost per unit and temperature sensitivity requirements divide manufacturer capabilities, with lightweight formats enabling direct-to-consumer economics that glass-dependent competitors cannot match.
- Pouches:Multi-layer polymer barriers with oxygen-scavenging layers extend shelf stability without refrigeration. Festival organizers in Austin and Miami adopt these formats for reduced waste-handling costs and festival-friendly portability.
- Glass Bottles:Structural importance persists in bars and gift-oriented channels where premium perception requires heft and transparency. Ohio and Pennsylvania manufacturing clusters face capacity constraints from energy cost volatility.
- Cans:Aluminum sourcing from domestic smelters supports mainstream retail placement with established recycling infrastructure.
- Tetra Packs:Aseptic carton technology remains marginal in alcoholic beverages due to TTB labeling surface area requirements and consumer skepticism.
Glass bottles anchor current volume; pouches are climbing the fastest on adoption curves.
Distribution Channel:
Three-tier compliance burdens and cold-chain investments determine which channels attract capital, with online retail requiring parallel logistics infrastructure that bypasses wholesaler mandates.
- Online Retail:Temperature-controlled fulfillment partnerships enable subscription and gift-box segments that circumvent state-level wholesaler fragmentation. Brooklyn and Los Angeles concentrate demand through influencer-curated tasting kits.
- Convenience Stores:Independent gas station networks across the Mountain West lack dedicated RTD cold-box infrastructure, creating first-mover shelf space for pouch-format entrants with ambient-stable formulations.
- Supermarkets:Chain buyers demand slotting fees and promotional calendars that favor established distillers with trade marketing budgets.
- Bars:On-premise licensing reforms in California, Texas, and New York streamline outdoor consumption permits, expanding festival and street-vending channels.
Supermarkets process the highest absolute volume; online retail shows the steepest expansion trajectory.
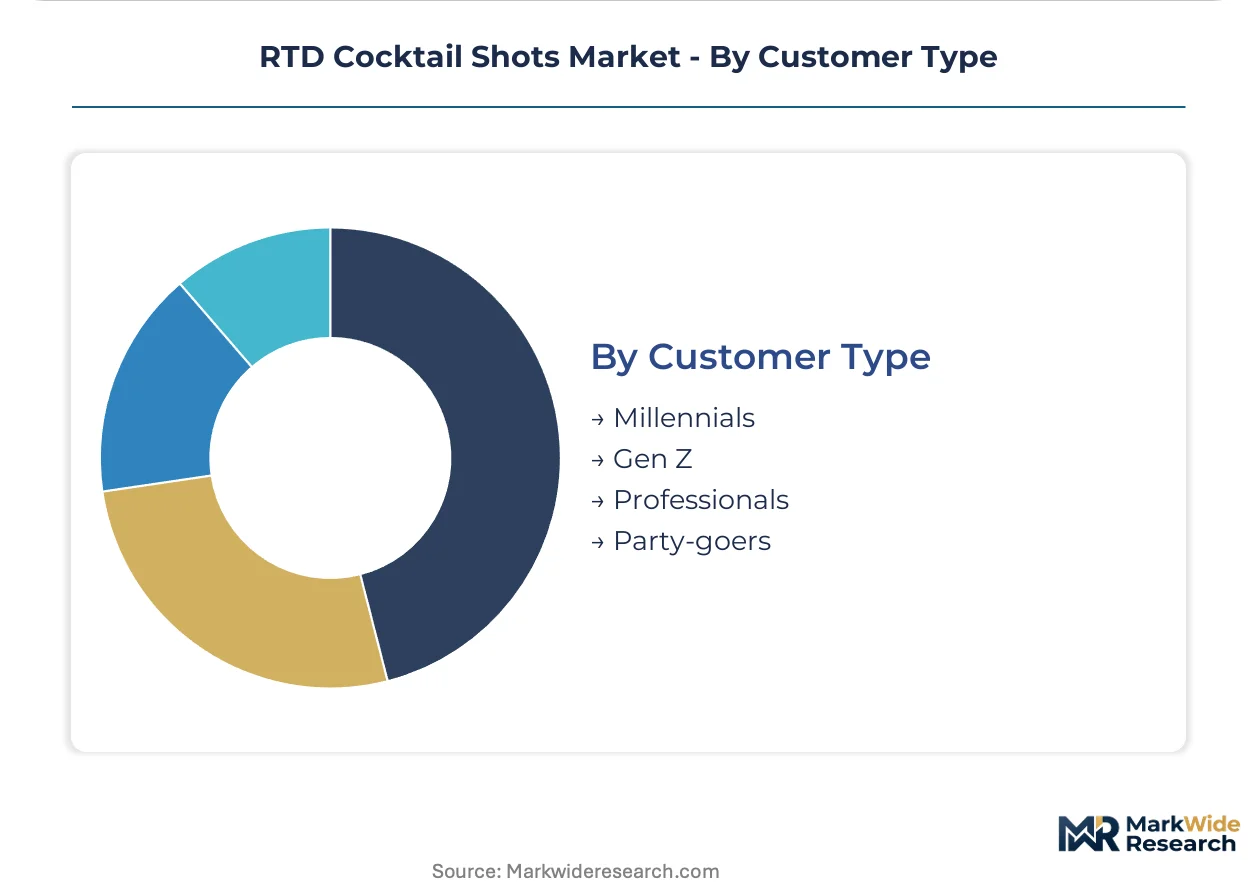
Customer Type:
Mobile-first discovery patterns and occasion-based consumption fragment marketing spend, with platform-native brands bypassing traditional retail gatekeepers through algorithmic targeting.
- Gen Z:TikTok-native discovery compresses purchase cycles toward impulse trial. Chicago and Brooklyn clusters demonstrate highest engagement with limited-batch drops and influencer collaborations.
- Millennials:Clean-label preferences and clean-ingredient sourcing drive reformulation toward natural extraction methods from botanical suppliers in Florida and Oregon.
- Professionals:Time-constrained urban workers prioritize portability and consistent quality for after-work and travel occasions.
- Party-goers:Bulk purchase and sharing formats dominate this occasion-driven segment with price sensitivity elevated versus individual consumption.
Millennials sustain the largest installed base; Gen Z is gaining share fastest on platform-driven trial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States outstrips Canadian and Mexican markets by 40-60% per equivalent volume unit. Metropolitan clusters in California, Texas, and New York concentrate demand for premium and flavored formulations. Regulatory fragmentation across state-level three-tier distribution laws creates arbitrage opportunities for direct-to-consumer entrants.
United States
Festival culture in Austin and Miami drives pouch-format adoption for outdoor venues. The TTB enforces formula approval timelines that compress seasonal launch windows by four to six months. California's cluster of botanical extraction suppliers in Sonoma and Napa supports clean-label reformulation for millennial preferences.
Germany
Beer-tax bracket advantages for sub-15% ABV products incentivize low-alcohol RTD development. The BfR (Federal Institute for Risk Assessment) governs additive safety assessments that extend reformulation cycles. Berlin's craft distiller ecosystem experiments with natural flavor stability under REACH chemical registration requirements.
United Kingdom
Urban professionals in London and Manchester sustain premium-tier gift-box demand through subscription channels. HMRC's excise duty structures favor lower-ABV products in retail price positioning. Scotland's spirits heritage clusters in Glasgow and Edinburgh supply super-premium whiskey bases for limited-batch portfolios.
Japan
Convenience store density in Tokyo and Osaka supports single-serve chilled format penetration. The National Tax Agency maintains strict label disclosure standards for allergen and calorie claims. Suntory's captive distribution infrastructure in Kansai demonstrates vertical integration advantages for route-to-market efficiency.
Australia
Outdoor consumption culture in Sydney and Brisbane accelerates pouch-format trial among younger demographics. FSANZ (Food Standards Australia New Zealand) mandates alcohol content disclosure that exceeds FDA stringency. Victoria's packaging innovation hubs in Melbourne develop oxygen-scavenging barrier films for ambient-stable logistics.
RTD Cocktail Shots Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the RTD cocktail shots landscape. Large-scale distillers with captive spirits supply and global distribution infrastructure sustain margin advantages through economies of scope. Craft entrants compete via flavor specialization and limited-batch positioning that commands premium pricing. Strategic moves concentrate on portfolio diversification across ABV tiers and packaging format innovation to capture festival and direct-to-consumer channels.
Within the heritage spirits conglomerate tier, Diageo plc and Brown-Forman occupy positions anchored by whiskey-forward portfolios and American convenience channel dominance. Bacardi Limited represents the tropical flavor specialization archetype, extending Caribbean rum heritage into pouch-format festival positioning. These three companies exemplify how captive supply chains and established wholesaler relationships defend against direct-to-consumer disruption.
| Leading Market Players |
|---|
| Diageo plc |
| Bacardi Limited |
| Brown-Forman |
| Anheuser-Busch InBev |
| Pernod Ricard |
| Constellation Brands |
| Suntory Holdings Limited |
| Asahi Group Holdings |
| Beam Suntory |
| Others |
Value Network & Pricing Analysis
Pouch packaging substitution for glass bottles is redrawing procurement geography and compressing logistics cost differentials between ambient-stable and refrigerated formats. This material shift simultaneously opens direct-to-consumer shipping economics for lightweight entrants while stranding glass-dependent producers in legacy three-tier distribution constraints.
Pricing Analysis
The customization-premium spread separates configured-to-order subscription boxes from standard retail SKUs by 40-60% per equivalent volume unit. Three-tier pricing structure across premium, standard, and economy levels reflects spirit base provenance, packaging format, and channel control intensity. Pricing pressure stems from spirits input cost volatility in agave and bourbon supply regions. Party-goers exhibit highest price sensitivity; gift-box purchasers in metropolitan clusters show lowest elasticity.
Supply Chain Analysis
Mexico and Kentucky anchor agave and bourbon spirit base production for RTD cocktail shots. Domestic manufacturing draws from Ohio and Pennsylvania glass clusters, Florida and Oregon botanical suppliers, and polymer barrier film producers in Victoria. Single-source vulnerability concentrates in TTB formula approval bottlenecks that delay seasonal launches. Distribution runs through state-mandated wholesaler tiers with parallel cold-chain investments for premium chilled formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against hard seltzer and cannabis beverage alternatives that threaten spirits-based consumption occasions. Incumbents must navigate share erosion from low-alcohol substitutes while capturing premium migration toward provenance-forward formats.
For Market Incumbents: Fortify captive spirits supply through backward integration into agave and bourbon production regions. Secure exclusive wholesaler relationships in California, Texas, and New York before licensing reforms accelerate channel fragmentation. Invest in pouch packaging capacity to match festival and direct-to-consumer demand trajectories. For New Entrants and Emerging Players: Differentiate on clean-label botanical sourcing from Sonoma and Napa extraction clusters. Target independent gas station networks across the Mountain West with ambient-stable pouch formats. Deploy influencer-curated tasting kits via temperature-controlled e-commerce fulfillment to bypass three-tier constraints. For Investors and Strategic Acquirers: Secondary-cycle assets sit with craft distillers in Portland and Nashville holding TTB-approved formulas but lacking distribution scale. Long-term viability hinges on portfolio diversification across ABV tiers and packaging formats. Watch for state-level low-alcohol taxation framework passage as volume reallocation signal.| Strategic Initiative | Industry Significance |
|---|---|
| Pouch Packaging Scale-Up | Oxygen-scavenging barrier films enable ambient-stable logistics for festival channels. |
| Clean-Label Reformulation | Natural extraction methods from Florida and Oregon suppliers accelerate FDA compliance. |
| Direct-to-Consumer Platform Launch | Temperature-controlled fulfillment partnerships bypass three-tier distribution fragmentation. |
| Spirits Base Backward Integration | Captive agave and bourbon supply hedges climate-pressured harvest volatility in Jalisco and Kentucky. |
| Subscription Box Premium Tier | Limited-batch positioning with provenance storytelling captures gift-oriented urban professional demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with brand managers, category buyers at convenience chains, TTB regulatory affairs specialists, and botanical extraction suppliers. Secondary validation drew from FDA labeling guidance documents, TTB formula approval databases, customs import records for spirits bases, and state-level licensing reform filings. Bottom-up volume triangulation against top-down value estimates anchored segmentation-level precision.
Across the analysis window, the forecasting framework modeled product type, packaging format, distribution channel, and customer type dimensions with alcohol-by-volume tier as an industry-specific stratifier. CAGRs were derived from slope analysis of segment-level growth trajectories calibrated against spirits input cost indices and channel penetration curves. Forecast inputs incorporated TTB approval timeline distributions and pouch packaging adoption elasticity parameters.
Material uncertainties — regulatory delays in formula approvals, climate-driven agave harvest disruptions, and state-level taxation framework reversals — sit outside the modeled envelope. Forecasts reflect documented assumptions about wholesaler relationship stability and cold-chain infrastructure investment continuity. Recalibration cycles align with material shifts in FDA labeling enforcement intensity and low-alcohol excise reclassification legislation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Cabernet Sauvignon Market
Alcoholic Beverages
US Wine Cooler Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
Middle East and Africa Kegs Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
Malt Beverages Market
Alcoholic Beverages
Decanter Market
Alcoholic Beverages
Dark Spirits Market
Alcoholic Beverages
Wine Glass Market
Alcoholic Beverages
South America Wine Market
Alcoholic Beverages
Beer Dispensing Machine Market
Alcoholic Beverages
Asia Pacific Beer Market
Alcoholic Beverages
Global Wine Coolers Market